
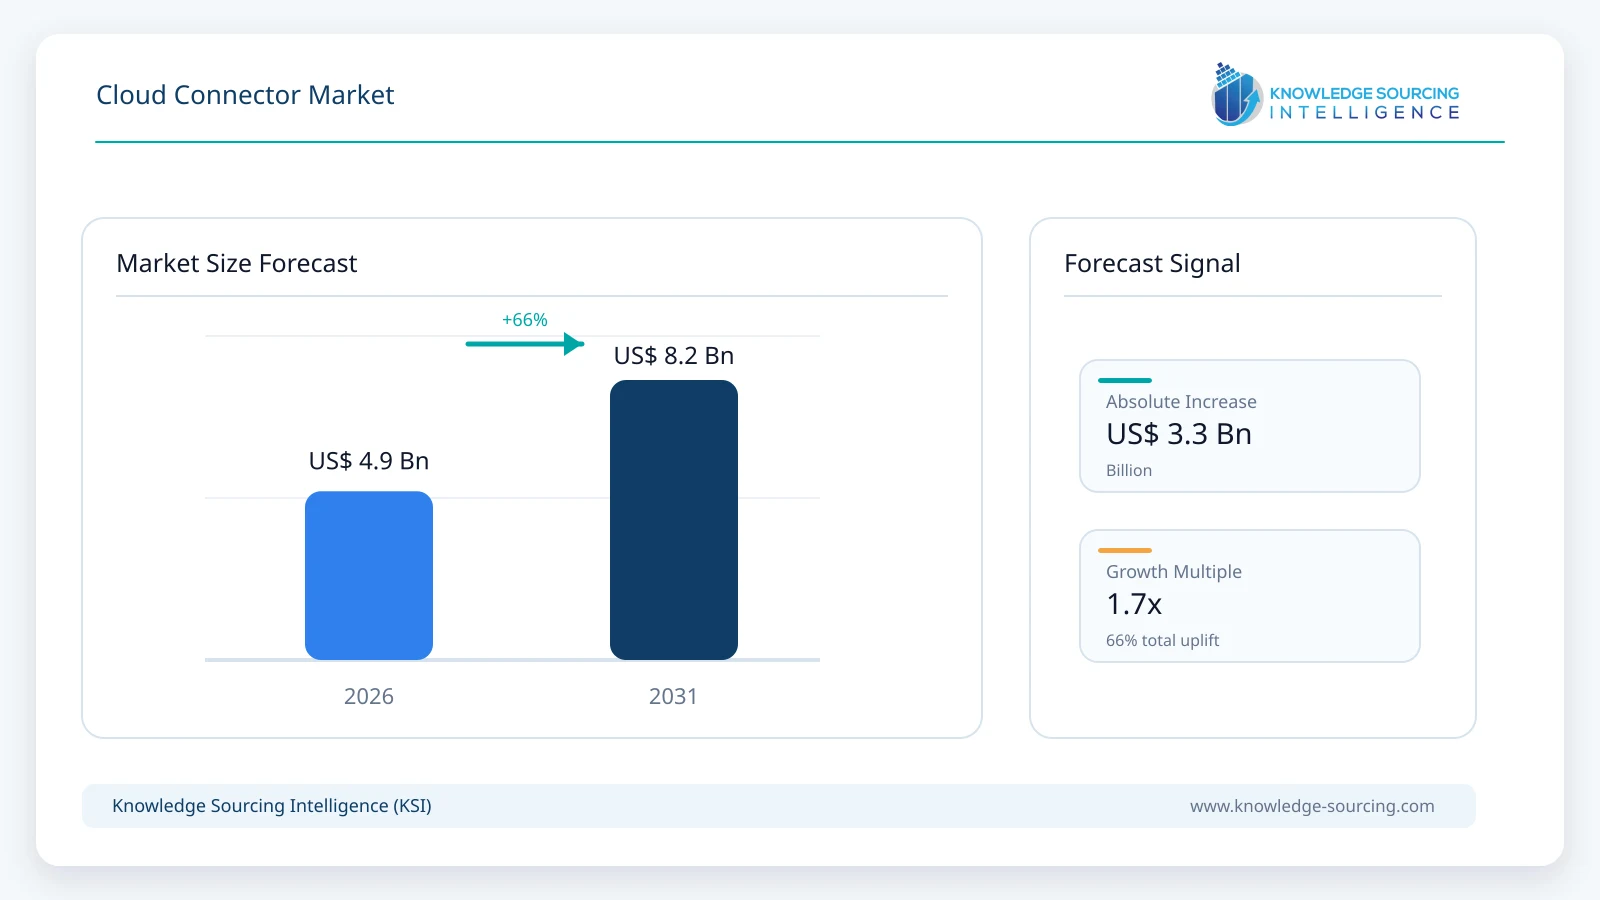
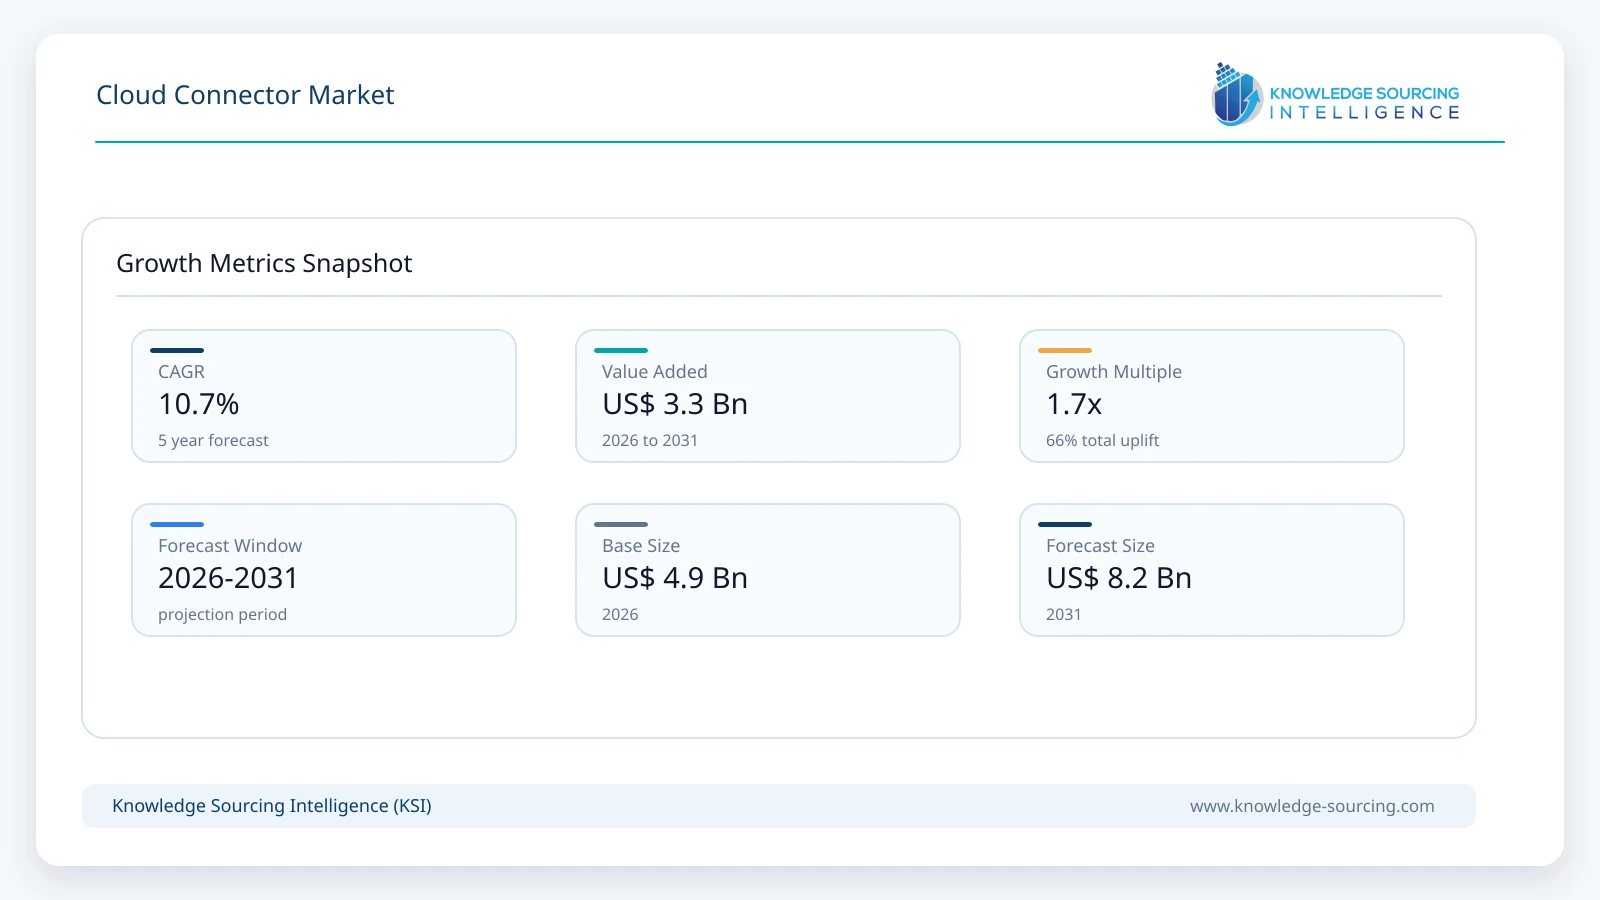
The Cloud Connector Market is forecast to grow at a CAGR of 10.7%, reaching USD 8.18 billion in 2031 from USD 4.93 billion in 2026.
Highlights:
- 1Enterprises are increasingly deploying cloud connectors to streamline data exchange across diverse applications and platforms.
- 2Organizations are integrating cloud connectors to improve interoperability between on-premises infrastructure and cloud environments.
- 3Businesses are automating workflows through cloud connectors to reduce manual data transfers and operational complexity.
- 4IT teams are strengthening cloud connectivity by integrating secure connectors with hybrid and multi-cloud architectures.
Market Overview
The cloud connector market is developing as organizations connect cloud applications, databases, enterprise software, on-premises infrastructure, and external digital services. Cloud connectors are software components, managed services, application programming interfaces (APIs), or hardware-enabled solutions that facilitate communication and data exchange between otherwise separate systems. Depending on their functionality, they can support application integration, data ingestion, workflow automation, federated queries, identity management, and private connectivity between cloud environments.
Cloud connectors help organizations reduce integration complexity, improve data accessibility, and coordinate processes across different technology environments. Their applications range from transferring operational data into analytics platforms to enabling business applications to exchange customer records and connecting enterprise networks to cloud infrastructure. However, cloud connectors are not a single standardized product category. The market encompasses different technical solutions, and the report's market definition should distinguish software and data connectors from network connectivity services and specialized Internet of Things (IoT) gateways to avoid double counting.
The growth outlook is supported by enterprise cloud adoption, distributed data environments, application modernization, and the increasing need to make organizational information accessible to analytics and artificial intelligence (AI) systems. Organizations are also seeking managed integration capabilities that reduce the effort required to develop, maintain, and secure custom interfaces. These factors create opportunities for cloud connector providers serving enterprises across information technology, financial services, government, retail, manufacturing, healthcare, and other industries.
According to Eurostat's February 2026 release, 52.7% of European Union enterprises used paid cloud computing services in 2025, an increase of 7.4 percentage points compared with 2023. Cloud usage included email, office software, file storage, security applications, and enterprise database hosting. Although these figures measure cloud adoption rather than connector purchases, they demonstrate the expanding digital infrastructure within which integration solutions operate.
Cloud Connector Market Drivers
Workflow Automation and AI Integration
Workflow automation is an important application area because businesses increasingly need to coordinate information and actions across customer relationship management (CRM), enterprise resource planning (ERP), finance, human resources, customer support, and analytics systems. Cloud connectors allow these applications to exchange data and initiate predefined tasks without requiring employees to transfer information manually between platforms. This can reduce repetitive work, improve process consistency, and support faster responses to operational events.
The development of AI assistants and autonomous software agents is extending these requirements. AI applications often need controlled access to enterprise records, business applications, databases, and external services. Connectors can provide the interfaces through which these systems retrieve information or execute permitted actions. Their effectiveness depends on data quality, authentication, authorization, API reliability, and appropriate monitoring rather than connectivity alone.
On April 28, 2026, AWS announced additional built-in action connectors for Amazon Quick, including integrations with Google Workspace, Zoom, Airtable, and other applications. AWS stated that these integrations support managed authentication and allow users to perform supported actions across connected services. This development illustrates how connector functionality is extending beyond basic data transfer into business workflows and AI-assisted productivity.
For organizations, these capabilities can support automated reporting, customer-service processes, project coordination, and document management. Nevertheless, broader integration increases the importance of restricting connector permissions to the minimum required for each task. Enterprises must evaluate which systems a connector can access, what information it can modify, and whether its activities can be audited. Consequently, workflow automation creates opportunities for providers that combine integration flexibility with reliable governance and security controls.
Expansion of Cloud Ecosystems and Multicloud Connectivity
Major cloud providers offer extensive ecosystems of computing, storage, analytics, database, security, and application services. Enterprises frequently combine these services with legacy systems, third-party applications, and privately hosted workloads. Cloud connectors help bridge these environments by standardizing data access, simplifying configuration, and reducing the need to maintain separate custom integrations for every system combination.
Multicloud connectivity is particularly relevant when organizations distribute workloads across different cloud providers to meet performance, resilience, regulatory, or technology requirements. Connecting these environments can involve network routing, private links, identity federation, data movement, and application-level integration. Although these functions are related, network interconnection products and software data connectors should be measured as distinct categories unless the report explicitly includes both.
On April 14, 2026, AWS announced the general availability of AWS Interconnect – multicloud, with Google Cloud as its first launch partner. The service enables private connectivity between participating cloud environments. AWS subsequently announced general availability with Oracle Cloud Infrastructure on July 29, 2026, expanding available multicloud connectivity options. These announcements demonstrate continued investment in managed cloud interconnection, although they do not establish the size or growth rate of the overall cloud connector market.
As cloud ecosystems expand, businesses can benefit from reduced integration effort and improved interoperability. However, differences in service architecture, identity systems, network configurations, API specifications, and pricing models can still create implementation challenges. Providers that simplify cross-platform configuration, document their interfaces clearly, and support consistent operational monitoring may be better positioned to address enterprise requirements.
Data Integration and Analytics Requirements
Organizations generate information across transactional databases, enterprise applications, websites, operational systems, and external data services. When these sources remain isolated, employees and analytics platforms may have incomplete information for reporting, forecasting, and decision-making. Cloud connectors can facilitate data ingestion, synchronization, and federated access, helping businesses combine information without necessarily building a separate custom integration for every source.
Demand is also influenced by the need to support data pipelines that remain adaptable as organizations introduce new applications or change their technology infrastructure. Managed connectors can reduce the maintenance burden associated with custom libraries, API changes, and infrastructure configuration. Their practical value depends on the number of supported sources, data freshness, transformation capabilities, error handling, performance, and compatibility with the customer's existing architecture.
On February 5, 2026, AWS announced a native REST API connector for AWS Glue. The capability enables customers to integrate data from REST-enabled sources into extract, transform, and load (ETL) jobs without developing and maintaining specialized connector libraries in supported scenarios. AWS described the feature as an extension of AWS Glue's existing connectivity to numerous external data sources through native and additional connector options.
On July 29, 2026, AWS further announced virtual private cloud (VPC) connectivity, filter pushdown, and partition support for the AWS Glue REST API connector. These enhancements address private-source access, unnecessary data transfer, and parallel processing requirements. Such product developments demonstrate how connector capabilities are evolving to address security, efficiency, and scale in enterprise data integration.
Government statistics provide additional context for this opportunity. Eurostat's Digitalisation in Europe 2026 publication reported that 33.02% of EU enterprises performed data analytics using their own employees in 2025. The share was higher among large enterprises than among smaller businesses. These figures are not connector-specific, but they indicate the relevance of data access and integration infrastructure to enterprise analytics activities.
Cloud Connector Market Opportunities
Security, Compliance, and Controlled Access
Cloud connectors can create additional access paths between enterprise applications, cloud platforms, databases, and external services. These connections introduce risks if credentials are exposed, permissions are excessive, APIs are misconfigured, or data is transmitted without suitable protection. Security considerations therefore influence vendor selection, implementation design, and the long-term cost of operating cloud integration environments.
Organizations may require encrypted communications, strong authentication, role-based access controls, secrets management, logging, audit trails, network restrictions, and monitoring of unusual activity. Connectors operating in regulated environments may also need to support data residency, retention, privacy, and sector-specific compliance requirements. Enterprises should verify the controls offered by individual products rather than assuming that every connector automatically provides the same security capabilities.
The National Institute of Standards and Technology (NIST) published Special Publication 1800-35, Implementing a Zero Trust Architecture, in June 2025. The guidance demonstrates approaches for implementing zero-trust architecture across distributed enterprise resources, including on-premises and multiple cloud environments. Its principles are relevant to connector deployments because access should be explicitly authorized and continuously evaluated rather than trusted solely because a system is inside a network boundary.
These requirements can increase demand for connectors that integrate with enterprise identity management, provide granular permissions, support private endpoints, and generate usable security logs. At the same time, security reviews can lengthen deployment cycles and increase implementation costs. Smaller organizations may also lack the resources needed to evaluate complex integration risks. Vendors that offer clear documentation, manageable configuration, and transparent security practices can help address these barriers.
Cloud Connector Market Restraints
Implementation Complexity and Interoperability Limitations
Despite the benefits of integration, connecting multiple cloud platforms and enterprise applications can require significant configuration, testing, and ongoing maintenance. APIs may change, authentication methods may be updated, and source systems may impose rate limits or restrict access to specific data. Organizations can experience failed synchronization, inconsistent records, delayed data transfers, or service disruptions when integrations are not properly managed.
Vendor Lock-In and Operating Costs
Vendor dependence is another concern. A connector built around proprietary interfaces or platform-specific data models may make migration more difficult if an organization changes providers. Subscription charges, data transfer costs, connector licensing, and support fees can also increase the total cost of ownership. Open standards, portable integration logic, documented APIs, and appropriate exit planning can help mitigate these risks.
Security and Compliance Barriers
Security and compliance requirements may constrain adoption in organizations handling sensitive financial, healthcare, personal, or government information. Businesses must assess where data is processed, which parties can access it, how credentials are stored, and whether integration logs satisfy audit requirements. These considerations may be particularly important when connectors enable AI agents to retrieve records or perform actions across multiple applications.
Cloud Connector Market Challenges
Another restraint is the difficulty of comparing products across the broad cloud connector category. A network interconnection service, a database connector, a SaaS workflow integration, and an IoT gateway may have different customers, pricing structures, and performance metrics. Market analysis that combines these offerings without clearly defined inclusion criteria risks producing misleading market shares and growth estimates. A consistent product taxonomy and transparent market-sizing methodology are therefore essential.
Regional Analysis
North America
North America benefits from an established enterprise technology ecosystem, substantial cloud infrastructure investment, and the presence of major cloud platforms and software providers. Businesses across financial services, retail, healthcare, manufacturing, and professional services use interconnected applications to manage customer information, transactions, analytics, and operations. These environments create demand for data connectors, workflow integration, and secure links between enterprise infrastructure and cloud services.
The United States is an important market within the region because of its concentration of technology vendors, cloud service providers, and large enterprise customers. Canada also offers opportunities as public and private organizations modernize applications and improve data accessibility. Mexico may benefit from digital transformation across manufacturing, logistics, financial services, and cross-border business operations. However, regional dominance should be established through comparable market revenue or deployment data, rather than inferred solely from the presence of major vendors.
Europe
Europe represents an important market for integration solutions because enterprises increasingly rely on paid cloud services and connected digital applications. Eurostat's 2025 data show variation in cloud adoption across EU countries, with Finland, Italy, and Malta among the countries reporting the highest shares of enterprises using paid cloud services. Differences in adoption, organizational size, data governance requirements, and legacy infrastructure create varying requirements for connector functionality and implementation support.
Asia Pacific
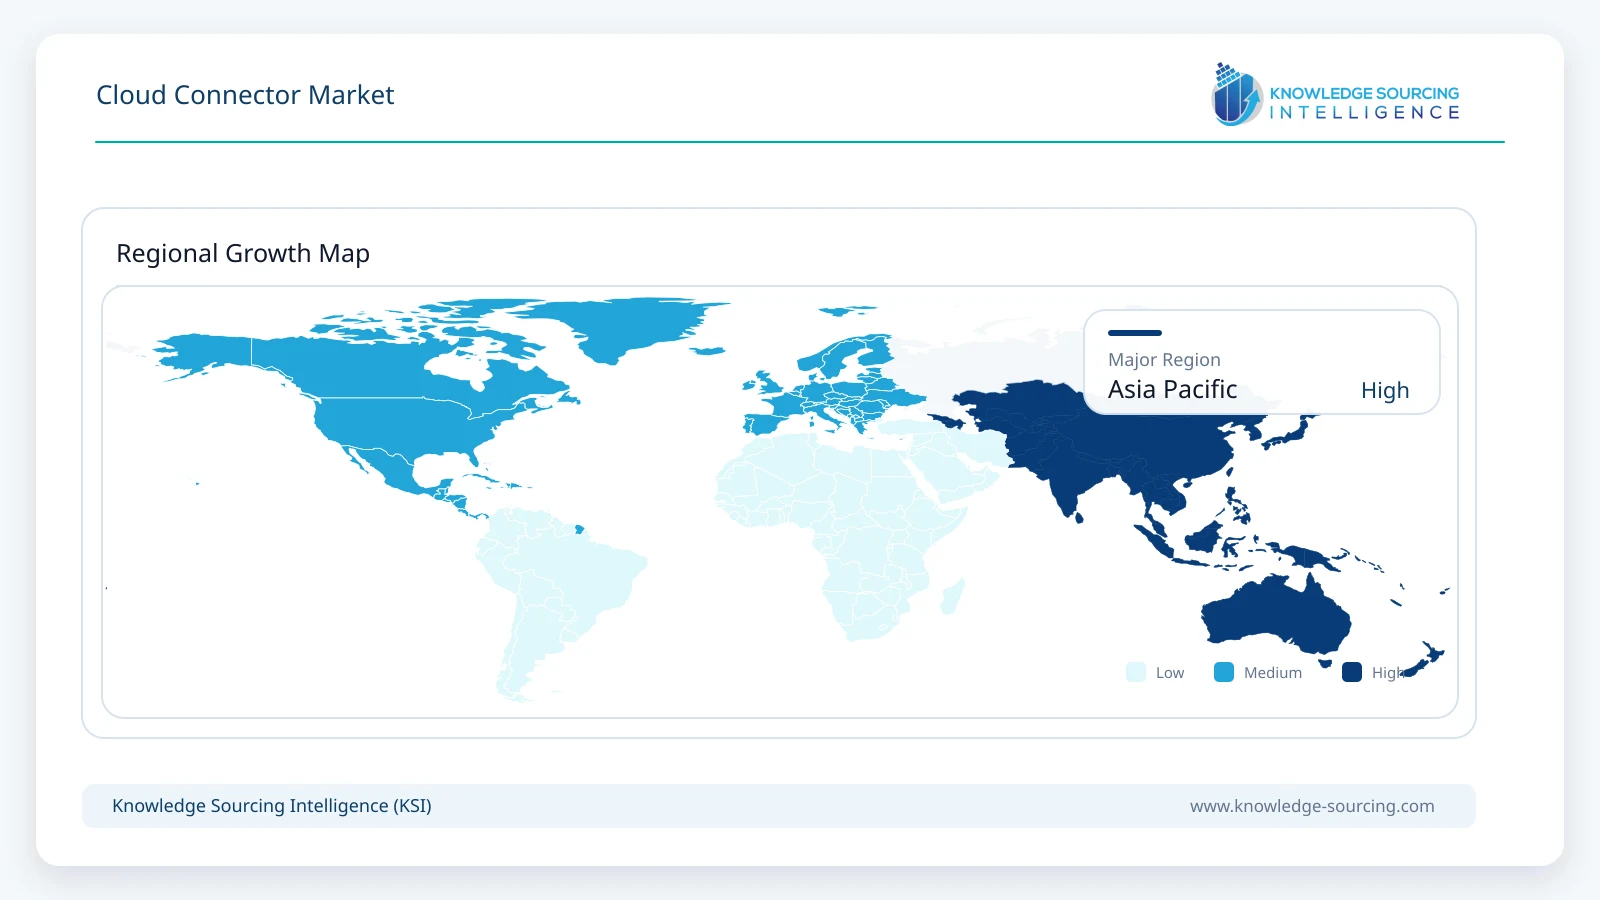
Asia Pacific offers opportunities as organizations expand digital services, modernize enterprise systems, and invest in cloud-based analytics. China, Japan, South Korea, India, and Australia have different technology ecosystems and regulatory environments, requiring vendors to adapt product availability, deployment models, and support arrangements. South America and the Middle East and Africa also provide opportunities as businesses digitize workflows and adopt cloud applications, although market development varies by country, sector, and infrastructure maturity.
Segmentation Analysis
By Operating System
Operating-system compatibility can be important for connectors installed on enterprise servers, endpoints, integration runtimes, and on-premises infrastructure. Windows-based environments may require connectors that work with established enterprise applications and administrative tools. Linux compatibility can be relevant for server-side integration, containerized workloads, and data-processing environments. macOS support may matter for particular desktop applications and developer workflows, but its importance should be assessed against actual product requirements and the market definition.
Not every cloud connector is installed directly on an operating system. Many connectors are delivered as managed cloud services, SaaS integrations, APIs, or browser-based application connections. Therefore, the Windows, Linux, and macOS segmentation should be retained only if the report can measure operating-system-specific demand consistently. Otherwise, connector type, integration function, or delivery model may provide a more meaningful basis for market analysis.
By Deployment
Deployment requirements differ across organizations. Public-cloud connectors can support scalable integration with cloud-hosted applications and data services. Private-cloud implementations may be selected where organizations require greater control over infrastructure, access, or data handling. Hybrid environments combine cloud services with on-premises systems and can require connectors capable of operating across network boundaries. Other deployment approaches may apply to specialized hardware or edge-based integrations.
The selection of a deployment model depends on latency, availability, data sensitivity, connectivity, integration complexity, and operating costs. Hybrid deployments can create opportunities for connectors that support both legacy and modern systems, but they may also require more complex monitoring and configuration. Market segmentation should distinguish deployment architecture from connection type and avoid counting a single connector repeatedly across overlapping categories.
Cloud Connector Market Key Developments
September 2, 2026: AWS announced new Amazon Quick connector controls and Model Context Protocol (MCP) synchronization support. The update enables connector owners and administrators to manage individual tools, configure permission requirements, and keep integrations synchronized as external MCP servers change. The announcement highlights growing emphasis on controlled access and maintainable integrations for AI-assisted business workflows.
August 7, 2026: Google Cloud outlined new BigQuery Data Transfer Service capabilities for managed data ingestion, including additions and enhancements to its connector ecosystem. The update focused on simplifying data movement from external sources into BigQuery and reducing the maintenance associated with data pipelines.
July 29, 2026: AWS expanded its Glue REST API connector with VPC support, filter pushdown, and partition support. The enhancements enable private-source connectivity, more selective data retrieval, and parallel processing of larger datasets. These capabilities address security and performance requirements in enterprise data integration.
July 29, 2026: AWS announced general availability of AWS Interconnect – multicloud with Oracle Cloud Infrastructure. The service enables customers to establish managed private connectivity between AWS and OCI in supported environments, expanding available options for interconnecting cloud workloads.
April 28, 2026: Amazon Quick introduced 13 additional built-in action connectors, including integrations with Google Workspace, Zoom, Airtable, and other applications. AWS stated that the connectors support managed authentication, allowing users to access connected services and execute supported actions through the Amazon Quick environment.
April 14, 2026: AWS announced general availability of AWS Interconnect – multicloud, with Google Cloud as its first launch partner. The service provides managed private connections between participating cloud providers, addressing the complexity of configuring and operating multicloud network links.
February 5, 2026: AWS introduced a native REST API connector for AWS Glue, allowing data engineers to connect REST-enabled sources to ETL jobs without the same need for specialized connector libraries in supported scenarios. The capability expands integration options for proprietary and emerging platforms while reducing connector maintenance overhead.
Cloud Connector Market Company Profiles and Products
Cisco
Cisco provides cloud and networking products that support communication between enterprise infrastructure and cloud services. Its collaboration portfolio includes integration capabilities linking supported meeting-management deployments with Webex cloud services. These capabilities can assist organizations with centralized administration, monitoring, and connectivity across supported environments. The specific product name, availability, and supported architecture should be verified against current Cisco documentation before describing a particular Cisco Meeting Server Cloud Connector as an actively marketed standalone offering.
Hewlett Packard Enterprise
HPE offers cloud and networking solutions for enterprise infrastructure, including products within its HPE Aruba Networking portfolio. Cloud-managed networking and secure access capabilities can help organizations connect distributed users, applications, and infrastructure. The original HPE Multi-Cloud Connector description should not automatically be treated as a current standalone product specification; its present availability, functionality, and relationship to HPE GreenLake should be confirmed against the relevant official product documentation.
Citrix Systems, Inc. (Cloud Software Group)
Citrix provides enterprise application delivery, virtualization, and secure access capabilities within the Cloud Software Group corporate structure. These offerings can be relevant to cloud access and hybrid enterprise environments, but the company should not be characterized as a provider of every type of data connector. Its inclusion should be supported by specific products that satisfy the report's definition of a cloud connector.
Disruptive Technologies
Disruptive Technologies offers IoT sensing solutions that transmit sensor data to cloud-based services through supported gateway and connectivity arrangements. These products are relevant where the report includes hardware-enabled IoT cloud connectivity. However, they should be distinguished from software-only enterprise data connectors because their functionality, deployment model, customer requirements, and revenue structure may differ substantially.
Alpha Serve
Alpha Serve has developed data integration applications that connect business platforms with analytics and reporting environments. These integrations can help organizations access information from operational systems for analysis and reporting. Its corporate attribution should be updated in accordance with its relationship with Tempo, and only products that remain available and relevant to the defined cloud connector market should be included in the company profile.
Lexmark
Lexmark’s cloud document integration capabilities allow supported printers and multifunction devices to connect with selected cloud file services for printing and scanning workflows. This functionality supports cloud-based document management by simplifying access to digital files, streamlining document processing, and enabling users to print or scan documents directly through compatible cloud services. Key considerations include supported devices, compatible cloud platforms, and current product availability.
Cloud Connector Market Outlook
The cloud connector market is positioned to benefit from the continued integration of enterprise applications, data platforms, and distributed cloud infrastructure. Demand is likely to be shaped by the growth of managed data ingestion, cross-application automation, AI-enabled workflows, and multicloud interoperability. Security, interoperability, and lifecycle management will remain important selection criteria as organizations seek to connect more systems without creating unnecessary operational complexity.
Data connectors and workflow integrations may be particularly relevant to enterprises consolidating information for analytics and AI applications, while network connectors and gateways address separate connectivity requirements. Public, private, and hybrid cloud deployments can each create opportunities, depending on organizational infrastructure and compliance needs. Operating-system segmentation should be retained only where comparable data support it.
Cloud Connector Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 4.93 billion |
| Total Market Size in 2031 | USD 8.18 billion |
| Forecast Unit | Billion |
| Growth Rate | 10.7% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Operating System, Deployment, End-User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Operating System
Windows
Linux
macOS
Other Operating Systems
By Deployment
Public Cloud
Private Cloud
Hybrid Cloud
Other Deployment Models
By End User
IT and Telecommunications
Government and Defense
Banking, Financial Services, and Insurance (BFSI)
Retail and E-commerce
Healthcare and Life Sciences
Manufacturing and Industrial
Energy and Utilities
Transportation and Logistics
Others
By Geography
North America
United States
Canada
Mexico
Others
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Spain
Others
Middle East and Africa
Saudi Arabia
United Arab Emirates
South Africa
Others
Asia Pacific
China
Japan
South Korea
India
Australia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency and Units
1.6. Assumptions
1.7. Base Year, Historical Period, and Forecast Period
2. RESEARCH METHODOLOGY
2.1. Research Data and Sources
2.2. Primary Research
2.3. Secondary Research
2.4. Market Size Estimation and Forecasting
2.5. Data Validation and Triangulation
2.6. Methodological Assumptions and Limitations
3. EXECUTIVE SUMMARY
3.1. Research Highlights
3.2. Key Market Findings
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Market Opportunities
4.4. Porter's Five Forces Analysis
4.4.1. Bargaining Power of Suppliers
4.4.2. Bargaining Power of Buyers
4.4.3. Threat of New Entrants
4.4.4. Threat of Substitutes
4.4.5. Competitive Rivalry in the Industry
4.5. Industry Value Chain Analysis
5. CLOUD CONNECTOR MARKET ANALYSIS BY OPERATING SYSTEM
5.1. Introduction
5.2. Windows
5.3. Linux
5.4. macOS
5.5. Other Operating Systems
6. CLOUD CONNECTOR MARKET ANALYSIS BY DEPLOYMENT
6.1. Introduction
6.2. Public Cloud
6.3. Private Cloud
6.4. Hybrid Cloud
6.5. Other Deployment Models
7. CLOUD CONNECTOR MARKET ANALYSIS BY END USER
7.1. Introduction
7.2. IT and Telecommunications
7.3. Government and Defense
7.4. Banking, Financial Services, and Insurance (BFSI)
7.5. Retail and E-commerce
7.6. Healthcare and Life Sciences
7.7. Manufacturing and Industrial
7.8. Energy and Utilities
7.9. Transportation and Logistics
7.10. Others
8. CLOUD CONNECTOR MARKET ANALYSIS BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.2.4. Others
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. United Kingdom
8.4.3. France
8.4.4. Spain
8.4.5. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. United Arab Emirates
8.5.3. South Africa
8.5.4. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. Japan
8.6.3. South Korea
8.6.4. India
8.6.5. Australia
8.6.6. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Emerging Players and Growth Opportunities
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Vendor Competitiveness Matrix
10. COMPANY PROFILES
10.1. Cisco
10.2. Citrix Systems, Inc. (Cloud Software Group)
10.3. Hewlett Packard Enterprise
10.4. Disruptive Technologies
10.5. Alpha Serve
10.6. Lexmark





Frequently asked questions
What is the projected Cloud Connector Market size and growth rate?
The Cloud Connector Market is forecast to reach $8.18 billion by 2031, growing at 10.7% CAGR.
What are the primary growth drivers for cloud connector adoption?
Multi-cloud, data integration, scalable solutions, security, and workflow automation drive growth.
Which region is projected to dominate the Cloud Connector Market?
North America is projected to dominate due to its thriving technology sector.
What is the core function of a cloud connector?
The Cloud Connector Market facilitates seamless communication, data transfer, and integration between cloud services.
How do cloud connectors address security and compliance needs?
They offer data encryption, access control, compliance adherence, and centralized security.
How does workflow automation impact the Cloud Connector Market?
Workflow automation enhances efficiency and integrates emerging technologies like AI/ML.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Cloud Connector Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/cloud-connector-market