
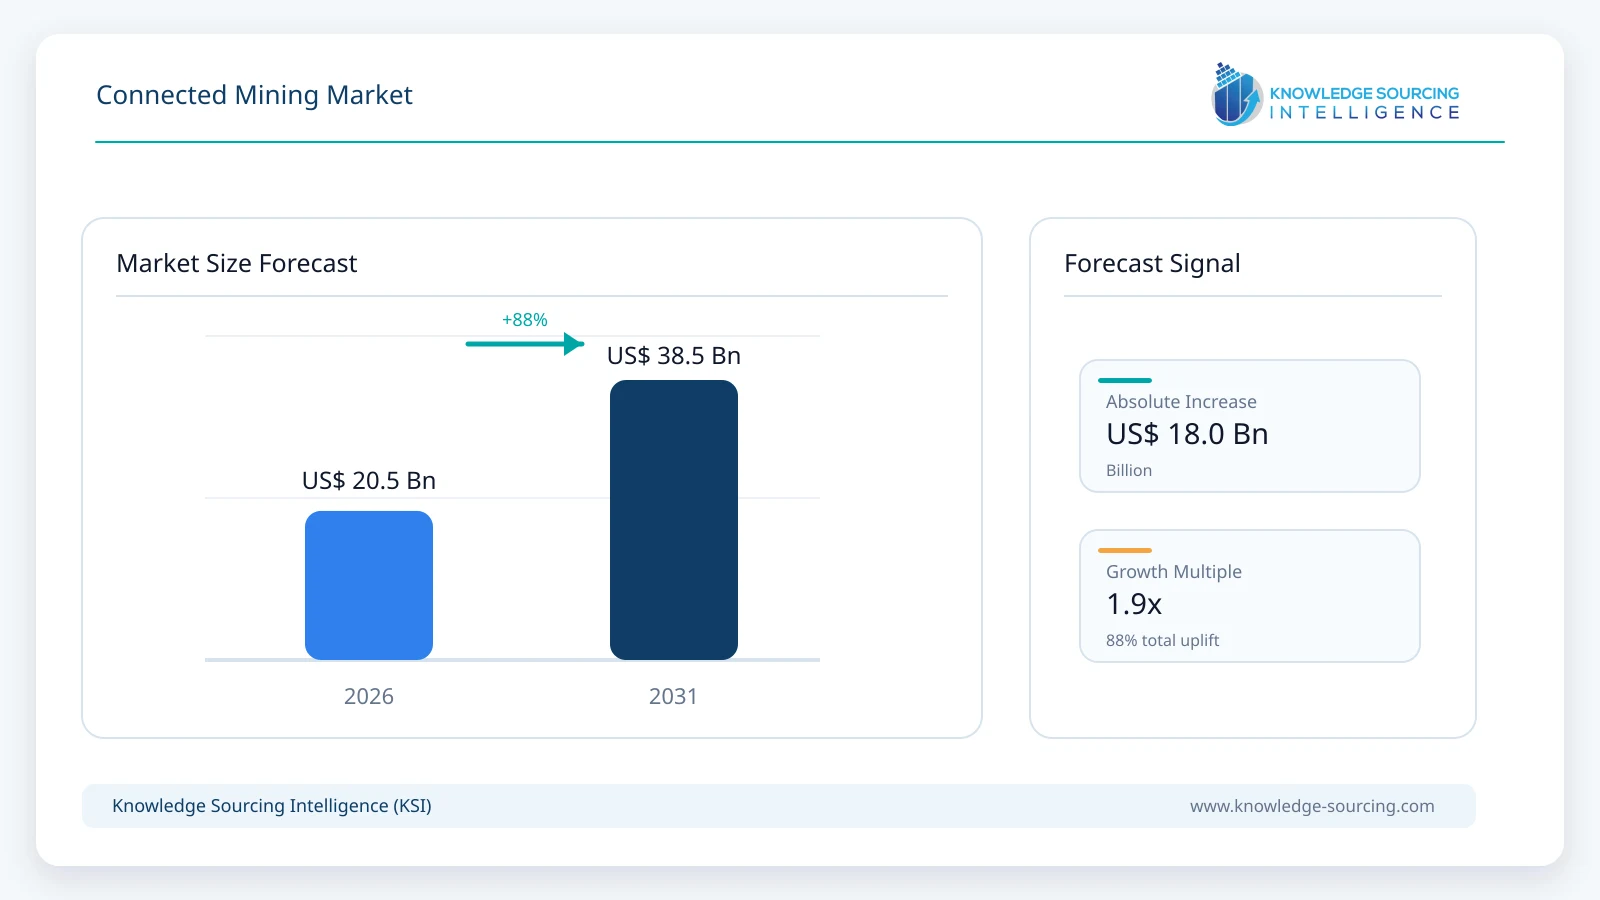
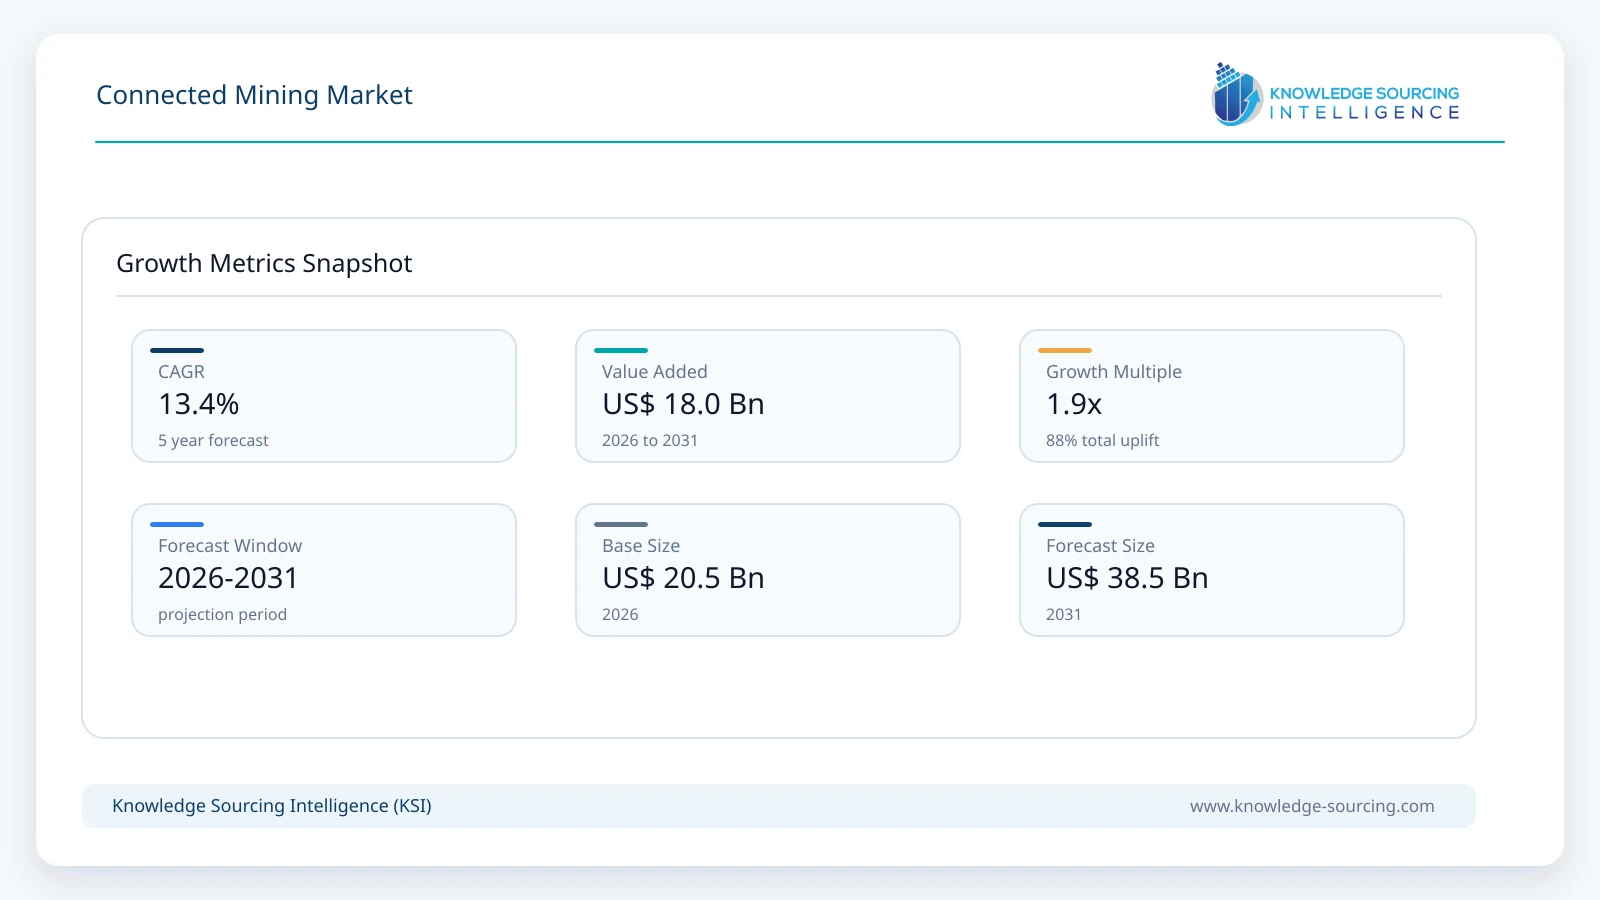
The Connected Mining Market is projected to expand at a CAGR of 13.4%, reaching USD 38.5 billion in 2031 from USD 20.5 billion in 2026.
Highlights:
- 1Connected control and automation systems account for approximately 27% of global market revenue in 2026.
- 2Surface mining represents about 60% of connected-mining expenditure, supported by large mobile-equipment fleets.
- 3Cloud-based deployment is projected to grow at roughly 16.5% annually as mixed-fleet analytics expand.
- 4Asia Pacific contributes approximately 42% of global connected-mining revenue in 2026.
- 5Komatsu commissioned its 1,000th autonomous ultra-class haul truck in April 2026.
- 6Private LTE and 5G networks are becoming foundational infrastructure for autonomous and remote mine operations.
Connected mining refers to the digital layer that links mining equipment, operational systems, people and process assets through real-time or near-real-time data. The market includes connected logistics, equipment monitoring, control and automation platforms, remote asset management, fleet management and tracking, IoT-based predictive maintenance, mine-site connectivity and directly associated consulting, integration and support services. It includes both surface and underground operations. Conventional mining equipment value is excluded unless connectivity, automation or digital-control functionality is directly embedded in the connected solution being measured.
The addressable base is large because high-value mining fleets operate continuously and small improvements in utilization, cycle time, energy consumption or unplanned downtime can produce significant economic benefits. Mining companies are therefore willing to invest in digital systems even when commodity-price conditions are mixed. Epiroc reported that customer interest remained strong in automation, mixed-fleet automation, digital safety solutions and electrification during 2025. Sandvik identifies automation and mining software and technology as one of its strategic growth areas for 2025-2030. These priorities indicate that connected mining is moving from a discrete technology program into a recurring equipment, software and service category within mine operating expenditure and sustaining capital.
Autonomous haulage illustrates the scale of adoption. Komatsu reported in April 2026 that it had commissioned 1,000 autonomous ultra-class haul trucks globally and that customers using FrontRunner had moved more than 11.5 billion metric tons of material. At BHP's Escondida Norte in Chile, 33 autonomous trucks and 11 autonomous drills operate in a fully autonomous pit that accounts for around 30% of Escondida production. Rio Tinto's Gudai-Darri mine integrates autonomous haul trucks and drills, AutoHaul rail, robotic laboratories and a digital twin. These deployments depend on connectivity, fleet orchestration, machine-health monitoring, positioning, analytics and remote operations, thereby creating revenue beyond the autonomous machine itself.
Market Trends
Mixed-Fleet Autonomy Is Broadening the Addressable Market
Connected mining historically developed around proprietary OEM ecosystems, but mine operators increasingly require platforms that can coordinate equipment from multiple manufacturers. Epiroc's LinkOA is positioned as an OEM-agnostic autonomy platform and supported Roy Hill's conversion of 78 haul trucks into the world's largest OEM-agnostic fully autonomous mine in 2025. Hitachi Construction Machinery's LANDCROS Connect Fleet Management System similarly aggregates operating data from equipment supplied by different manufacturers. This shift reduces dependence on single-OEM fleets and expands the addressable installed base for autonomy, fleet management and asset-health software across brownfield mines.
Private Wireless Networks Are Becoming Mine Operating Infrastructure
Autonomous and remotely operated equipment needs predictable low-latency communications across large pits, underground tunnels and moving work zones. Private LTE and 5G are therefore moving from communications projects into operational technology. Newmont deployed Ericsson Private 5G at the Cadia gold-copper mine to support teleremote dozers, while Nokia and Boldyn Networks deployed private 5G at Finland's Callio FutureMINE across underground levels reaching approximately 1.5 kilometres in depth. As positioning, video, machine control and safety applications share the same network, connectivity spending becomes more tightly integrated with mining automation budgets.
Predictive Maintenance Is Shifting From Dashboards to AI-Assisted Asset Health
Equipment monitoring is moving from periodic telematics toward high-frequency data analysis and anomaly detection. Hitachi Construction Machinery launched LANDCROS Connect Insight to retrieve operational data in near-real time and support asset-health diagnosis and predictive analysis. Its later investment in Rithmik followed a mine-site demonstration using operating data from 40 dump trucks and six ultra-large hydraulic excavators. Epiroc's Asset Health Information Service and other OEM platforms follow the same direction. This increases software and service revenue per connected asset because analytics, diagnostics and expert support sit above the basic sensor or telematics layer.
Safety Systems Are Moving Toward Automated Intervention
The safety layer of connected mining is also becoming more active. Hexagon launched its next-generation Vehicle Intervention System in September 2026, designed as an EMESRT Level 9 solution that can automatically intervene when collision risk thresholds are breached. Underground mines are adopting proximity detection, personnel tracking, situational awareness and collision-avoidance systems across mixed fleets. The combination of machine location, worker positioning, network connectivity and automated intervention expands spending beyond compliance monitoring into integrated operational control.
Market Drivers and Restraints
Productivity Pressure Makes Digital Investment Economically Measurable
Declining ore grades, longer haul distances, deeper underground operations and higher energy and labor costs raise the value of each incremental productivity gain. Connected systems improve dispatching, reduce queuing, identify idle assets, optimize maintenance windows and enable remote operations. BHP uses digital twins and AI to optimize mine haulage, fragmentation and material handling, while Epiroc reports customer productivity improvements of up to 8% from digitalization. Because these benefits can be measured against tonnes moved, equipment availability and cost per tonne, connected-mining investment can remain attractive even without rapid growth in total mine output.
Automation Expands the Revenue Opportunity Beyond Monitoring
The market is moving from visibility to control. Autonomous trucks, drills, water carts and remotely operated equipment require fleet-management software, positioning, edge computing, connectivity, collision protection, operational analytics and ongoing system support. Komatsu's 1,000-truck milestone and the expansion of Epiroc's LinkOA beyond mining demonstrate that autonomy has moved into repeatable commercial deployment. This raises connected revenue per mine because software and services remain necessary throughout the operating life of autonomous fleets.
Critical-Mineral Investment Supports Greenfield Digital Architecture
New copper, lithium, nickel and other critical-mineral capacity provides an opportunity to design connectivity, automation and data architecture into mines from the outset. Greenfield projects can integrate private networks, remote operations centers, autonomous-ready fleets, digital twins and centralized planning without the same legacy-system constraints faced by brownfield sites. Existing mines also require productivity improvements to supply rising mineral demand, widening the market for retrofit sensors, mixed-fleet management and predictive-maintenance systems.
Interoperability, Cybersecurity and Network Reliability Remain Adoption Constraints
Mining environments combine long-life equipment from multiple OEMs, specialized operational technology, enterprise IT and increasingly cloud-connected applications. Integrating those systems can be difficult, particularly where proprietary data structures or safety-critical controls are involved. Remote and underground mines also face network coverage challenges, while cyber risk increases as more operational assets are connected. These constraints slow full-site deployments and sustain demand for system integration, cybersecurity architecture and local edge processing rather than eliminating the connected-mining opportunity.
Segment Analysis
By Solution - Connected Control and Automation Systems
Connected control and automation systems form the largest solution category, generating an estimated USD 5.5 billion of revenue in 2026. The category includes autonomous and remote-control platforms, operational control systems, dispatch optimization, collision intervention and machine-to-machine coordination. Its value is reinforced by the transition from isolated autonomous assets toward orchestrated mine-wide systems. Fleet management and equipment monitoring remain substantial adjacent categories, while IoT-based predictive maintenance is expected to grow faster than the overall market as more mines use higher-frequency data, AI-assisted anomaly detection and remote expert diagnostics.
By Services - System Integration and Deployment
Services account for roughly one-fifth of connected-mining expenditure, with system integration and deployment representing the largest service pool. Mines must connect OEM telematics, private wireless networks, control systems, planning tools, safety platforms and enterprise applications while maintaining operational continuity. Integration demand is particularly strong in brownfield mines and mixed fleets. Support and maintenance becomes more important after deployment because mine connectivity and automation systems operate continuously and require software updates, cybersecurity controls, network optimization and specialist technical support.
By Mining Type - Surface Mining
Surface mining remains the larger connected-mining segment because open-pit operations use large fleets of haul trucks, loaders, drills and support equipment across areas where positioning and wireless connectivity are easier to deploy than in underground environments. Autonomous haulage has therefore scaled fastest in large iron ore, copper, coal and gold operations. Underground mining is expected to gain share through the forecast period as private wireless, positioning, ventilation-on-demand, remote drilling, collision avoidance and autonomous loading technologies mature for deep and complex environments.
By Deployment - On-Premises and Edge-Heavy Architectures
On-premises and edge-heavy deployment remains the largest architecture in 2026 because safety-critical control cannot depend entirely on remote cloud connectivity. Mine sites commonly process machine-control, positioning and collision data locally while sending selected information to cloud platforms for analytics, planning and fleet-wide visibility. Cloud-based revenue is nevertheless growing faster as operators centralize multi-site dashboards, asset-health analytics, maintenance planning and software delivery. The result is increasingly a hybrid architecture rather than a simple shift from on-premises to public cloud.
By Geography - Asia Pacific
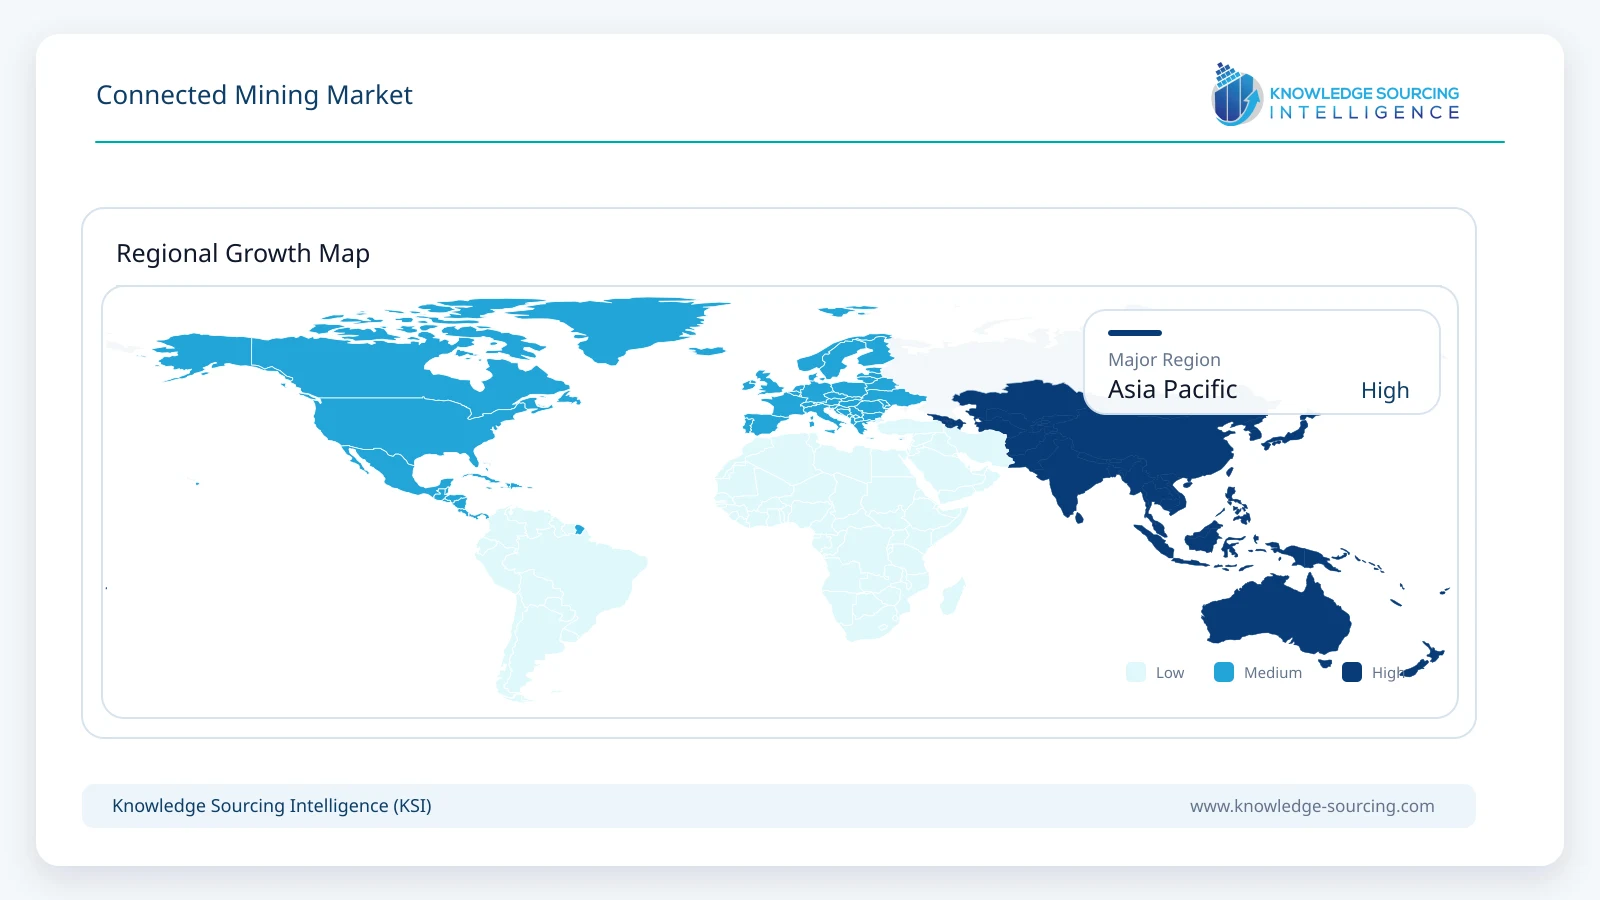
Asia Pacific is the largest regional market, exceeding USD 8.5 billion in 2026. Australia is a global center of autonomous mining, with major iron ore and gold operations deploying autonomous haulage, remote operations and private wireless networks at scale. China and India add large mining equipment bases and increasing digitalization, while Indonesia's coal and nickel industries provide additional demand for fleet management and connected equipment. North America follows through large surface mines, technology-provider concentration and growing autonomy in quarries and aggregates, while Latin America is supported by copper and iron ore operations in Chile, Peru and Brazil.
Competitive Environment
Competition spans mining-equipment OEMs, automation specialists, industrial-control companies, telecom suppliers and mining-software vendors. Caterpillar and Komatsu have strong positions in autonomous haulage and fleet systems. Epiroc and Sandvik combine underground equipment, automation, software and digital safety platforms. Hexagon has a broad portfolio across fleet management, collision avoidance, mine planning, positioning and autonomy, while Hitachi Construction Machinery is expanding LANDCROS Connect toward mixed-fleet management and near-real-time equipment analytics.
Industrial technology groups including ABB, Siemens, Schneider Electric and Rockwell Automation compete in process control, electrification, drives, remote monitoring and mine-to-port automation. Nokia and Ericsson provide private wireless infrastructure that supports autonomous equipment, video, positioning and remote operations. Mining software specialists such as RPMGlobal, Maptek, Micromine and IntelliSense.io compete in planning, scheduling, analytics and process optimization. Competitive advantage increasingly depends on interoperability: mines want platforms that connect legacy equipment, mixed fleets and operational systems rather than requiring a complete technology replacement.
Recent Developments
September 2026: Hexagon launched its next-generation Vehicle Intervention System for surface mines, adding automated collision intervention and EMESRT Level 9 protection.
June 2026: Epiroc won an order from Heidelberg Materials to deploy LinkOA autonomous haulage in an Australian quarry, extending the platform beyond large mining operations.
April 2026: Komatsu commissioned its 1,000th autonomous ultra-class haul truck, with FrontRunner customers having moved more than 11.5 billion metric tons of material.
January 2026: BHP reported that Escondida Norte had become fully autonomous, operating 33 autonomous trucks and 11 autonomous drills.
December 2025: Hitachi Construction Machinery invested in Rithmik Solutions to advance AI-based asset-health analysis for mining equipment.
September 2025: Nokia and Boldyn Networks deployed private 5G across multiple underground levels at Callio FutureMINE in Finland.
Connected Mining Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 20.5 billion |
| Total Market Size in 2031 | USD 38.5 billion |
| Forecast Unit | Billion |
| Growth Rate | 13.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Solution, Services, Mining Type, Deployment Type |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Solution
Connected Logistics
Connected Equipment Monitoring
Connected Control & Automation Systems
Remote Asset Management
Fleet Management & Tracking
IoT-based Predictive Maintenance
By Services
Consulting & Advisory Services
System Integration & Deployment
Support & Maintenance
By Mining Type
Surface Mining
Underground Mining
By Deployment Type
On-Premises / Edge
Cloud-based
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Chile
Peru
Others
Europe
United Kingdom
Germany
Sweden
Finland
Others
Middle East & Africa
South Africa
Saudi Arabia
Ghana
Others
Asia Pacific
Australia
China
India
Indonesia
Others
Geographical Segmentation
- Middle East and Africa
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Productivity Pressure Makes Digital Investment Economically Measurable
3.1.2. Automation Expands the Revenue Opportunity Beyond Monitoring
3.1.3. Critical-Mineral Investment Supports Greenfield Digital Architecture
3.2. Market Restraints
3.2.1. Interoperability, Cybersecurity and Network Reliability Remain Adoption Constraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Autonomous Haulage and Mixed-Fleet Control
4.2. Private LTE and 5G Networks
4.3. AI-Based Predictive Maintenance
4.4. Digital Twins and Integrated Remote Operations
4.5. Collision Avoidance and Vehicle Intervention
5. CONNECTED MINING MARKET BY SOLUTION
5.1. Introduction
5.2. Connected Logistics
5.3. Connected Equipment Monitoring
5.4. Connected Control & Automation Systems
5.5. Remote Asset Management
5.6. Fleet Management & Tracking
5.7. IoT-based Predictive Maintenance
6. CONNECTED MINING MARKET BY SERVICES
6.1. Introduction
6.2. Consulting & Advisory Services
6.3. System Integration & Deployment
6.4. Support & Maintenance
7. CONNECTED MINING MARKET BY MINING TYPE
7.1. Introduction
7.2. Surface Mining
7.3. Underground Mining
8. CONNECTED MINING MARKET BY DEPLOYMENT TYPE
8.1. Introduction
8.2. On-Premises / Edge
8.3. Cloud-based
9. CONNECTED MINING MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Chile
9.3.3. Peru
9.3.4. Others
9.4. Europe
9.4.1. United Kingdom
9.4.2. Germany
9.4.3. Sweden
9.4.4. Finland
9.4.5. Others
9.5. Middle East & Africa
9.5.1. South Africa
9.5.2. Saudi Arabia
9.5.3. Ghana
9.5.4. Others
9.6. Asia Pacific
9.6.1. Australia
9.6.2. China
9.6.3. India
9.6.4. Indonesia
9.6.5. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Caterpillar Inc.
11.2. Komatsu Ltd.
11.3. Epiroc AB
11.4. Sandvik AB
11.5. Hexagon AB
11.6. Hitachi Construction Machinery Co., Ltd.
11.7. ABB Ltd.
11.8. Siemens AG
11.9. Schneider Electric SE
11.10. Rockwell Automation, Inc.
11.11. Cisco Systems, Inc.
11.12. Nokia Corporation
11.13. Ericsson
11.14. Trimble Inc.
11.15. RPMGlobal Holdings Limited
11.16. Maptek Pty Ltd.
11.17. Micromine Limited
11.18. IntelliSense.io
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations





Frequently asked questions
What is the projected market value for Connected Mining by 2031?
The Connected Mining Market will reach USD 38.5 billion by 2031 with a 13.4% CAGR.
Which region holds the largest share in connected mining revenue?
Asia Pacific contributes approximately 42% of global revenue in 2026.
Which mining type accounts for the most connected-mining expenditure?
Surface mining represents about 60% of connected-mining expenditure.
What is the fastest-growing deployment type in connected mining?
Cloud-based deployment is projected to grow annually at roughly 16.5%.
What foundational infrastructure supports autonomous mine operations?
Private LTE and 5G networks are foundational for autonomous operations.
What factors drive investment in Connected Mining despite market conditions?
Improved utilization, reduced downtime, and efficiency create significant economic benefits.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Connected Mining Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/connected-mining-market