
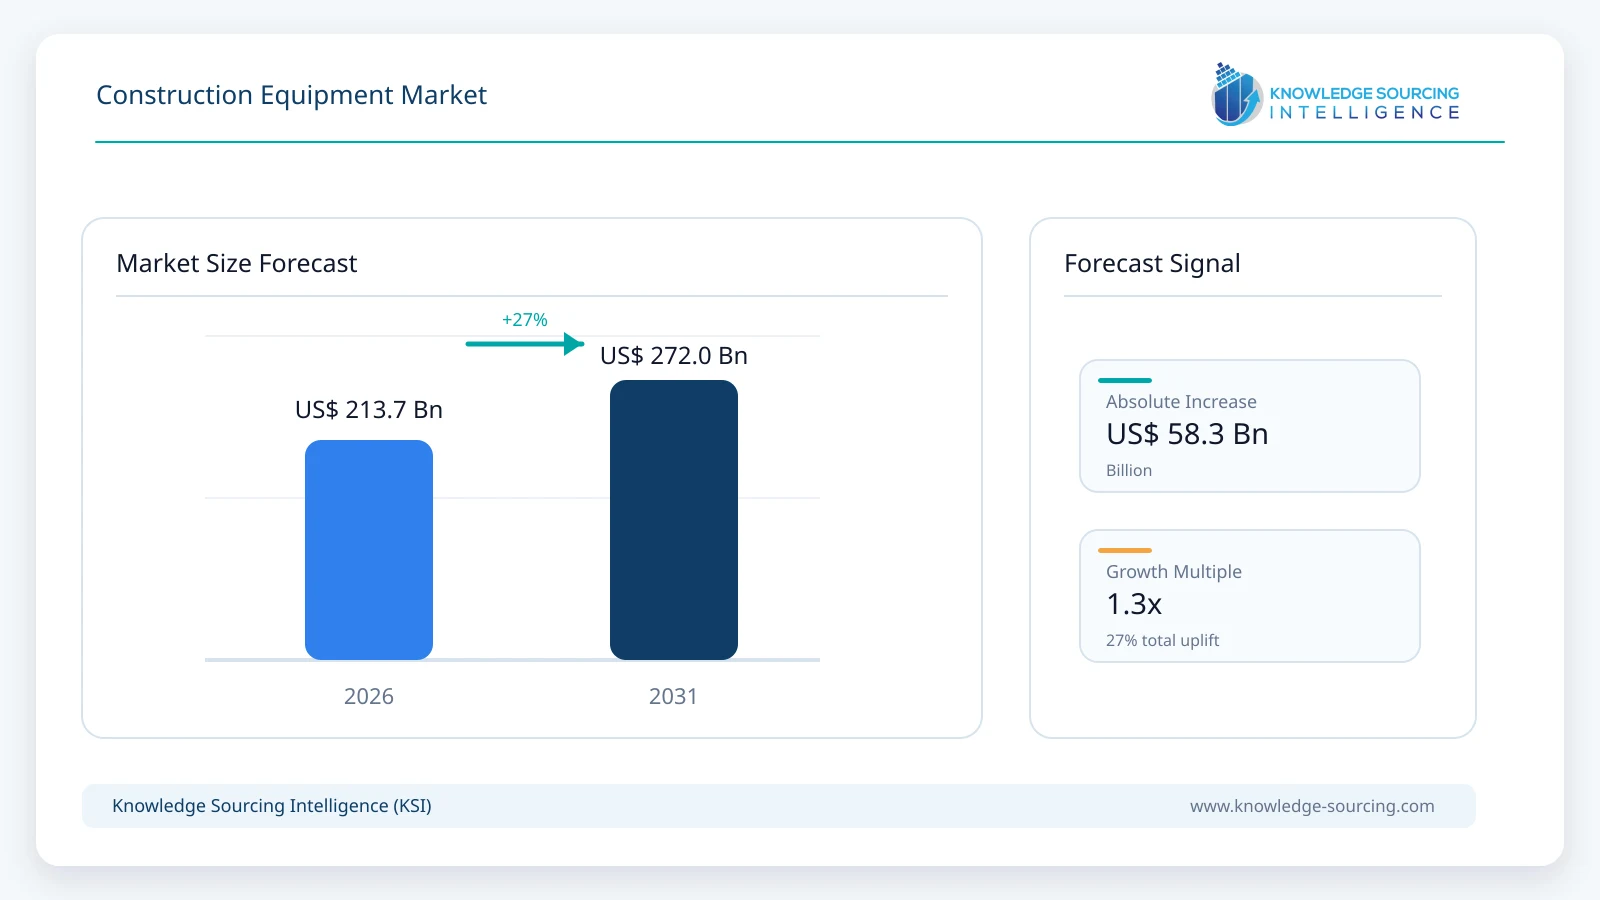
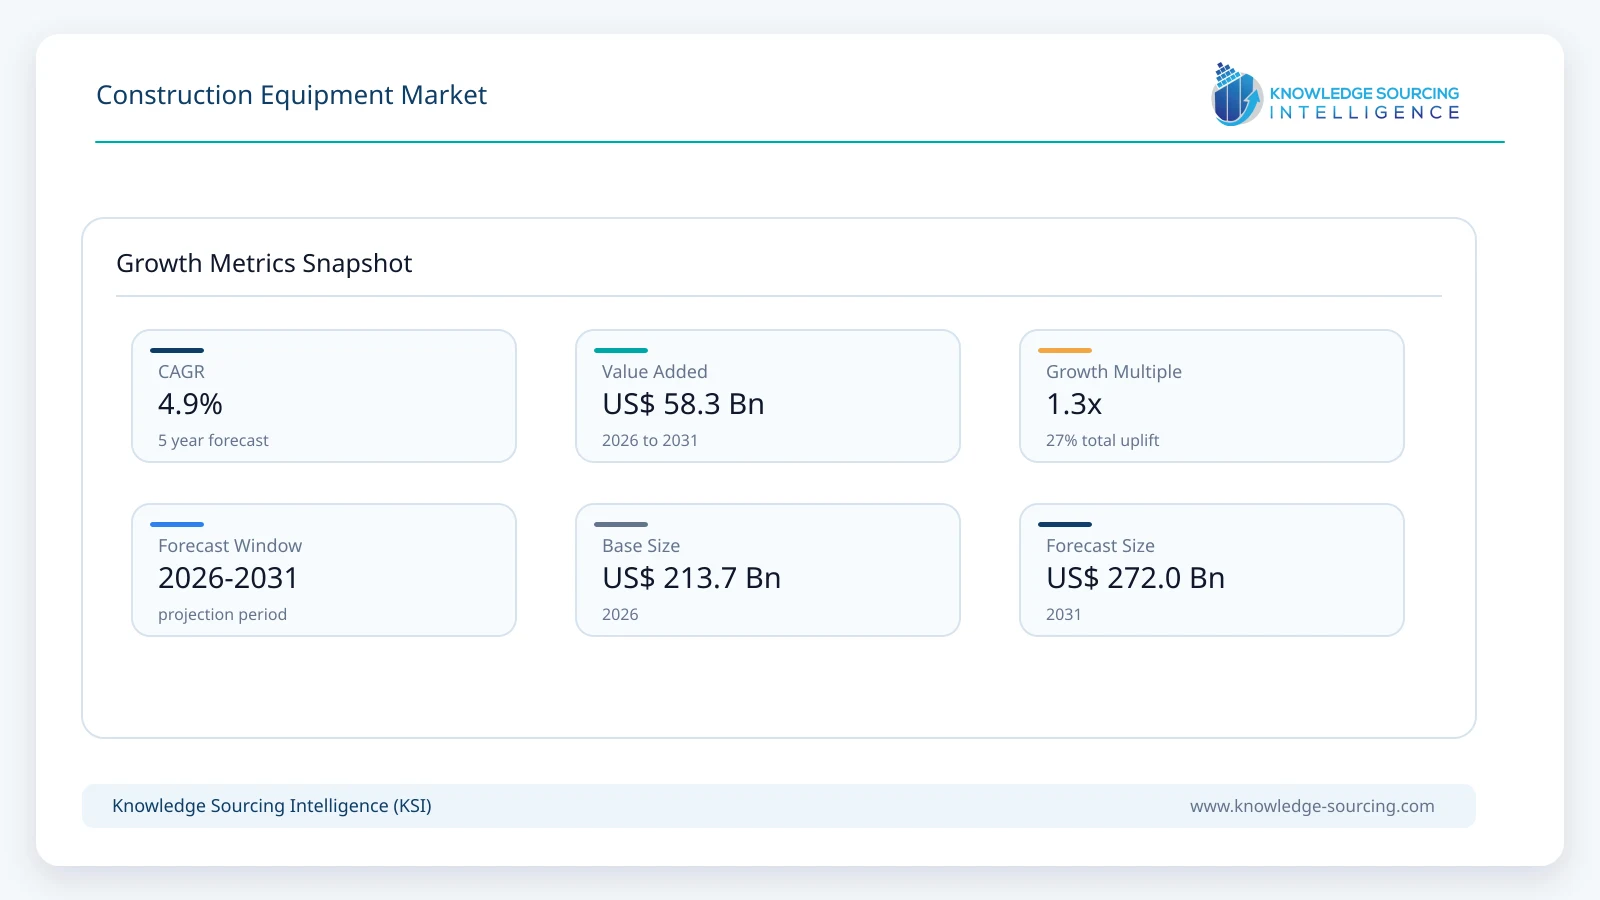
The global construction equipment market is projected to grow from USD 213.7 billion in 2026 to USD 272.0 billion by 2031, expanding at a CAGR of 4.9% over the forecast period.
Highlights:
- 1Infrastructure applications account for an estimated 45.5% of 2026 construction equipment revenue.
- 2Asia Pacific represents about 45.0% of 2026 revenue, led by China and India.
- 3Earthmoving equipment remains the largest category, generating approximately USD 98.3 billion in 2026.
- 4Electric and hybrid equipment expands fastest, supported by urban and low-emission construction sites.
- 5Machine control, telematics and autonomy increasingly shift competition toward lifecycle productivity and uptime.
Construction equipment demand is anchored in the continuous need to build, renew and maintain transport networks, utilities, industrial facilities and urban assets. The demand cycle is uneven rather than uniformly expansionary. Caterpillar reported a 15% year-on-year increase in Construction Industries sales to USD 6.93 billion in the fourth quarter of 2025, driven mainly by higher equipment sales to end users. Deere & Company reported a 29% increase in Construction & Forestry net sales to USD 3.79 billion in the second quarter of fiscal 2026, reflecting higher shipment volumes. In contrast, China entered 2026 with a weaker construction-investment backdrop: official data show infrastructure investment declined 4.0% year on year during January-August 2026, even as spending on equipment and instruments increased 9.3%. The combination indicates that the global market is being supported by replacement, productivity upgrades and selected infrastructure programs rather than a synchronized construction boom.
OEM strategy is consequently shifting from selling individual machines toward supporting an operating system around the fleet. Connected equipment enables utilization tracking, grade control, remote diagnostics, payload management and maintenance planning, while rental and equipment-as-a-service models give contractors access to newer technology without carrying the full capital cost. Volvo Construction Equipment reported 53,800 machine orders in 2025, up 1% on a reported basis and 22% when adjusted for the divestment of SDLG; adjusted net sales increased 4%. Komatsu has similarly emphasized connected construction, machine control and digital jobsite platforms, while Hitachi Construction Machinery is developing physical artificial intelligence that learns excavator operator actions. These investments are particularly relevant where skilled operators are scarce, and contractors are under pressure to complete work with smaller crews and tighter cost control.
Key Segment Values
Segment | Key Subsegment | Revenue Contribution | Details |
Equipment Type | Earthmoving Equipment | USD 98.3 billion | Largest equipment group; demand spans excavation, grading, loading and site preparation. |
Propulsion | Internal-Combustion Equipment | 92.0% share | Diesel remains dominant in high-utilization and remote applications through the forecast period. |
End Use | Infrastructure | 45.5% share | Roads, rail, utilities and public works provide the largest demand base. |
Geography | Asia Pacific | 45.0% share | Largest regional market, combining China, India, Japan, Australia and Southeast Asia. |
Technology Trend | Electric & Hybrid Equipment | Fastest propulsion growth | Adoption broadens from compact urban machines toward larger loaders, excavators and haulers. |
Market Dynamics
Infrastructure spending and fleet replacement support baseline demand
Infrastructure remains the most durable demand source because roads, railways, water systems, energy projects and industrial facilities require large equipment fleets across multiple phases of construction. India illustrates the strength of this pipeline: the Union Budget 2026-27 proposed public capital expenditure of INR 12.2 lakh crore, up from INR 11.2 lakh crore in the 2025-26 budget estimate, with additional proposals covering high-speed rail corridors, freight infrastructure and waterways. Developed markets contribute a different form of demand through replacement and modernization of aging infrastructure. For equipment suppliers, the commercial effect extends beyond new machine sales because long-lived fleets create recurring demand for parts, remanufacturing, attachments, financing and connected services.
Productivity pressure accelerates machine control, connectivity and automation
Contractors are increasingly evaluating equipment according to material moved per hour, rework avoided and operator productivity rather than rated power alone. Caterpillar announced in January 2026 that autonomous construction product lines would include excavators capable of autonomous trenching, loading and grading and loaders designed for autonomous material handling and truck loading. Komatsu used CONEXPO-CON/AGG 2026 to introduce its intelligent machine control 3.0 platform on new excavators and dozers and expanded Smart Construction tools that connect machines, drone data and three-dimensional jobsite models. The near-term market opportunity is therefore broader than fully driverless machinery: grade assistance, boundary control, payload weighing, remote operation and semi-autonomous task execution can be adopted incrementally within existing fleets.
Electrification expands, but adoption remains highly application-specific
Battery-electric equipment is moving into heavier classes, although economics differ sharply by duty cycle. In April 2026, Volvo Construction Equipment began serial production of its A30 Electric and A40 Electric articulated haulers with payloads of 29 tonnes and 39 tonnes, respectively. The company stated that the machines can provide up to six hours of operation on a charge depending on the application, with initial deliveries targeted to European customers. Compact excavators and loaders remain easier entry points because they often operate in urban sites, indoor locations or noise-sensitive environments with predictable charging access. Larger machines require more site-level planning around charging power, shift patterns and utilization, so diesel, electric and hybrid architectures are expected to coexist through 2031 rather than converge rapidly on a single powertrain.
Construction cycles, financing costs and tariffs create uneven equipment purchasing
Construction-equipment demand is cyclical because contractors can defer replacement, extend machine life or increase rental usage when project visibility weakens. Deere entered fiscal 2025 expecting U.S. and Canadian construction-equipment industry volumes to decline by roughly 10%, illustrating how quickly equipment demand can respond to interest rates, dealer inventories and project timing. Conditions improved into 2026, but OEM guidance still points to regional divergence. Trade measures also add uncertainty through imported components and localized manufacturing requirements. Large manufacturers can partly absorb this volatility through global production, aftermarket revenue and financing operations, while smaller suppliers are more exposed to single-region demand and component-price changes.
Charging infrastructure and total cost remain constraints on low-emission fleets
Zero-emission construction fleets require more than replacement of the machine itself. Contractors may need high-power electrical connections, mobile charging systems, battery scheduling and new maintenance practices, while temporary jobsites can move before infrastructure costs are recovered. Volvo Construction Equipment and Hitachi Energy signed a memorandum of understanding in May 2026 to address power supply, charging, energy management and operational integration as a combined construction-site system, illustrating the scale of the deployment challenge. Electric equipment is therefore likely to gain share first in applications where utilization is predictable, local emissions or noise matter, and charging can be planned around daily operating patterns.
Construction Equipment Market Segment Analysis
By Equipment Type
Earthmoving Equipment
Earthmoving equipment is estimated at approximately USD 98.3 billion in 2026, making it the largest equipment category. The segment includes excavators, wheel loaders, dozers, graders, backhoe loaders, and related machines used for excavation, grading, loading, and site preparation. Excavators remain particularly important because the same base machine can be adapted for trenching, demolition, utilities, road construction and general earthworks through different attachments. Equipment renewal is increasingly tied to fuel efficiency, hydraulic performance, machine control and operator-assistance systems. Volvo Construction Equipment stated at CONEXPO 2026 that excavators, wheel loaders and articulated haulers together represent around 70% of the global construction market, reinforcing the commercial concentration around core earthmoving platforms.
By Propulsion
Internal-Combustion Equipment
Internal-combustion equipment is estimated to account for approximately 92.0% of 2026 market revenue and remains the dominant propulsion platform. Diesel machinery continues to offer the combination of energy density, refueling speed and field support required for long shifts, remote sites and high-utilization earthmoving. The segment will remain the largest revenue pool through 2031 even as its share gradually declines. Electric and hybrid equipment is expected to grow faster, particularly in compact equipment and applications where emissions, noise and charging access are important. OEM investment is therefore increasingly multi-technology rather than a simple transition away from diesel, with manufacturers continuing to improve conventional engines while expanding battery-electric and hybrid portfolios.
By End Use
Infrastructure
Infrastructure accounts for an estimated 45.5% of construction equipment revenue in 2026. Roads, rail, airports, ports, utilities, water systems and energy projects use equipment across excavation, material handling, grading, compaction and concrete placement, creating demand for both heavy and compact machinery. Public investment provides a degree of resilience because projects can continue through weaker private residential cycles, although procurement can still be delayed by permitting and financing. The segment also provides a strong environment for digital adoption because large projects have measurable schedules, material quantities and grade requirements that benefit from machine control and connected jobsite systems.
Asia Pacific Market Analysis
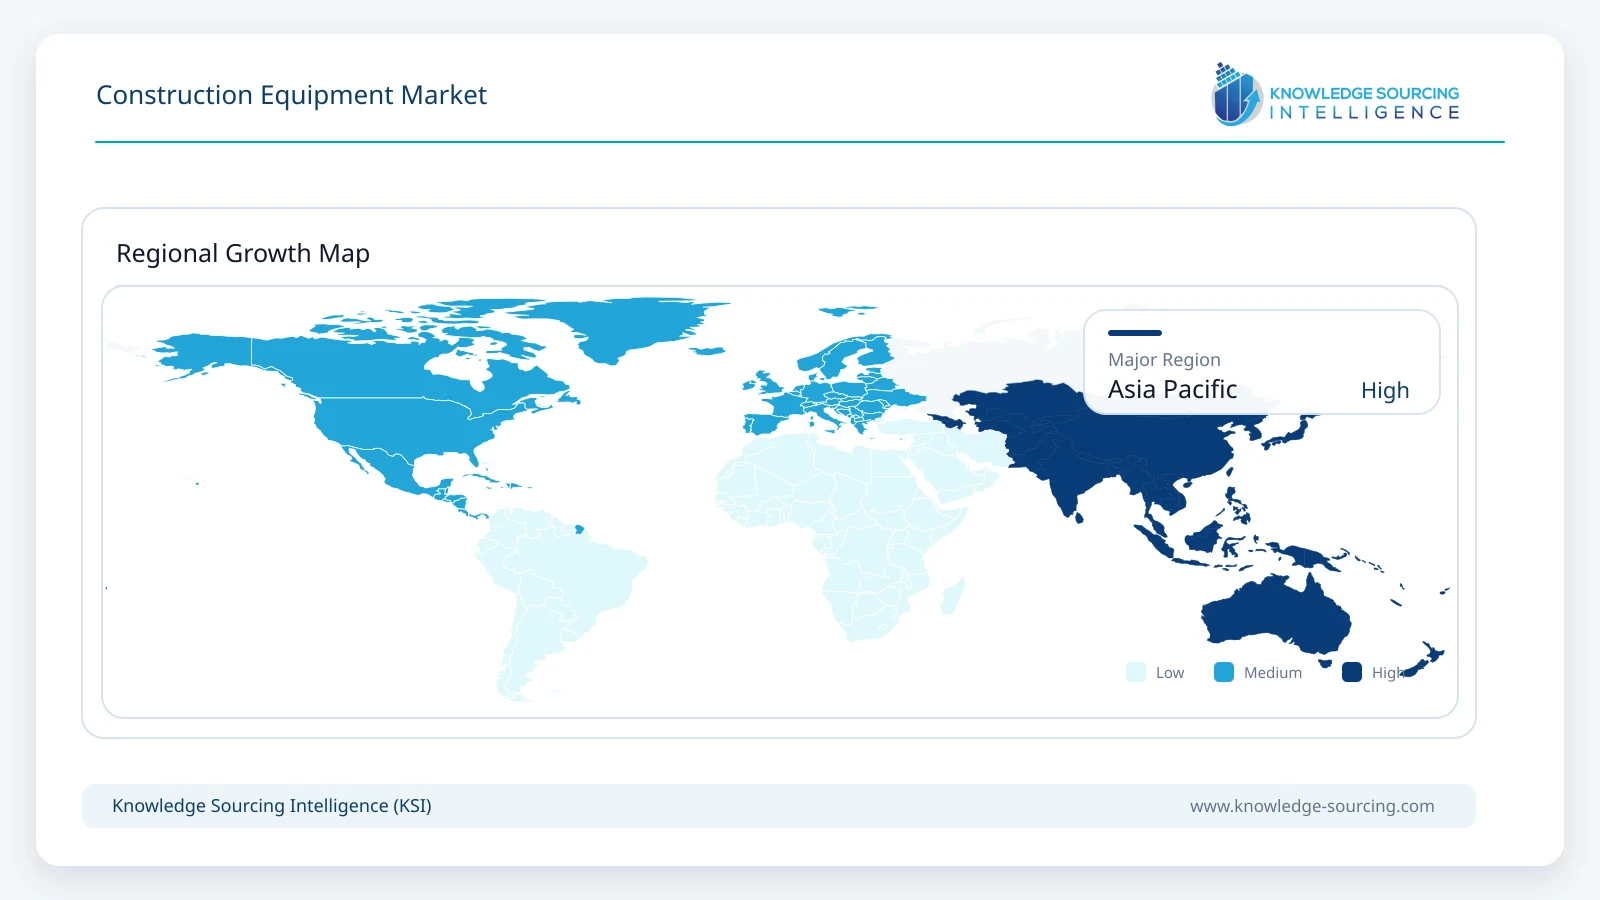
Asia Pacific is estimated to account for approximately 45.0% of global construction-equipment revenue in 2026, equivalent to about USD 96.2 billion. The region combines the world's largest construction-equipment manufacturing base with substantial infrastructure, industrial and urban development.
China remains a major equipment market and manufacturing center but is no longer a uniform growth engine. Official data for January-August 2026 show fixed-asset investment declining 7.2% year on year and infrastructure investment declining 4.0%, while purchases of equipment and instruments increased 9.3%. This mix favors replacement, manufacturing automation and selected transport or industrial projects over broad-based real-estate-led expansion.
India is providing a stronger infrastructure-growth counterweight. The FY2026-27 Union Budget proposed INR 12.2 lakh crore of public capital expenditure and included transport initiatives spanning high-speed rail, freight and waterways. Japan remains important through technologically advanced domestic OEMs and fleet replacement, while Australia and Southeast Asia add demand from infrastructure, quarrying, utilities and resource-linked construction. Asia Pacific will therefore remain the largest regional market through 2031, but growth will be distributed unevenly: India and selected Southeast Asian markets provide expansion, China contributes enormous scale with slower investment momentum, and mature markets increasingly favor productivity-enhancing replacement equipment.
Competitive Landscape
The market is concentrated around global original equipment manufacturers with broad dealer networks, financing capability and large installed bases, but competitive intensity differs by equipment class and region. Caterpillar and Komatsu maintain extensive portfolios across earthmoving and heavy equipment, while Volvo Construction Equipment, Hitachi Construction Machinery and Deere & Company have strong positions across excavators, loaders, articulated haulers, roadbuilding and compact equipment. Chinese manufacturers including SANY, XCMG and Zoomlion continue to expand internationally, increasing price and product competition in emerging markets. Competitive advantage is shifting toward lifecycle support: parts availability, telematics, software integration, financing, rental access, remanufacturing and dealer response can influence purchase decisions as strongly as machine specifications.
Recent Developments
September 9, 2026: Hitachi Construction Machinery announced that it would begin research and development in October 2026 on Physical AI trained on hydraulic excavator operator actions, targeting future autonomous excavation, loading and disaster-response applications.
April 9, 2026: Volvo Construction Equipment began serial production of the A30 Electric and A40 Electric articulated haulers in Sweden, extending battery-electric equipment into 29-tonne and 39-tonne payload classes.
March 3, 2026: Komatsu previewed the D61PXi-25 with intelligent machine control 3.0 and the D175AX-10 at CONEXPO-CON/AGG 2026, targeting higher productivity in grading and large-scale earthmoving.
March 2, 2026: Caterpillar presented expanded artificial intelligence, autonomy, connected fleet and rental capabilities at CONEXPO-CON/AGG 2026 as part of a broader construction-worksite technology platform.
January 7, 2026: Caterpillar announced new autonomous construction product lines covering excavator tasks including trenching, loading and grading and autonomous loader material-handling applications.
Construction Equipment Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 213.7 billion |
| Total Market Size in 2031 | USD 272.0 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 4.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Equipment Type, Propulsion, End Use, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
BY EQUIPMENT TYPE
Earthmoving Equipment
Material Handling Equipment
Concrete & Road Construction Equipment
Other Construction Equipment
BY PROPULSION
Internal-Combustion Engine Equipment
Battery-Electric Equipment
Hybrid & Other Low-Emission Powertrains
BY END USE
Infrastructure
Commercial & Residential Construction
Mining & Quarrying
Industrial & Manufacturing
Oil & Gas
Others
BY GEOGRAPHY
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Others
Middle East and Africa
Saudi Arabia
United Arab Emirates
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Australia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Infrastructure spending and fleet replacement
3.1.2. Productivity pressure and machine control adoption
3.1.3. Electrification of construction fleets
3.2. Market Restraints
3.2.1. Construction cycles, financing costs and tariffs
3.2.2. Charging infrastructure and total-cost constraints
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Regulatory and Emissions Landscape
4. CONSTRUCTION EQUIPMENT MARKET BY EQUIPMENT TYPE
4.1. Earthmoving Equipment
4.2. Material Handling Equipment
4.3. Concrete & Road Construction Equipment
4.4. Other Construction Equipment
5. CONSTRUCTION EQUIPMENT MARKET BY PROPULSION
5.1. Internal-Combustion Engine Equipment
5.2. Battery-Electric Equipment
5.3. Hybrid & Other Low-Emission Powertrains
6. CONSTRUCTION EQUIPMENT MARKET BY END USE
6.1. Infrastructure
6.2. Commercial & Residential Construction
6.3. Mining & Quarrying
6.4. Industrial & Manufacturing
6.5. Oil & Gas
6.6. Others
7. CONSTRUCTION EQUIPMENT MARKET BY GEOGRAPHY
7.1. North America
7.1.1. United States
7.1.2. Canada
7.1.3. Mexico
7.2. South America
7.2.1. Brazil
7.2.2. Argentina
7.2.3. Others
7.3. Europe
7.3.1. Germany
7.3.2. France
7.3.3. United Kingdom
7.3.4. Italy
7.3.5. Others
7.4. Middle East and Africa
7.4.1. Saudi Arabia
7.4.2. United Arab Emirates
7.4.3. South Africa
7.4.4. Others
7.5. Asia Pacific
7.5.1. China
7.5.2. Japan
7.5.3. India
7.5.4. South Korea
7.5.5. Australia
7.5.6. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Caterpillar Inc.
9.2. Komatsu Ltd.
9.3. Volvo Construction Equipment
9.4. Hitachi Construction Machinery Co., Ltd.
9.5. Deere & Company
9.6. Liebherr Group
9.7. SANY Heavy Industry Co., Ltd.
9.8. XCMG Group
9.9. Zoomlion Heavy Industry Science & Technology Co., Ltd.
9.10. HD Hyundai Construction Equipment Co., Ltd.
9.11. DEVELON (HD Hyundai Infracore)
9.12. JCB Ltd.
9.13. CNH Industrial N.V.
9.14. Kobelco Construction Machinery Co., Ltd.
9.15. Kubota Corporation
9.16. Wacker Neuson SE
9.17. Terex Corporation
9.18. Manitou Group
10. RECENT DEVELOPMENTS
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Research Methodology
11.5. Abbreviations





Frequently asked questions
What is the projected Construction Equipment Market size by 2031?
The Construction Equipment Market is projected to reach USD 272.0 billion by 2031.
What is the CAGR for the Construction Equipment Market from 2026-2031?
The Construction Equipment Market is expanding at a CAGR of 4.9% over the period.
Which region will dominate construction equipment revenue in 2026?
Asia Pacific represents 45.0% of 2026 revenue, led by China and India.
Which is the largest equipment category in 2026?
Earthmoving equipment is the largest, generating USD 98.3 billion in 2026.
What are the primary drivers supporting construction equipment demand?
Replacement, productivity upgrades, and selected infrastructure programs drive demand.
Which construction equipment type is expanding fastest?
Electric and hybrid equipment are expanding fastest.
Cite this report
Knowledge Sourcing Intelligence. (Nov 2026). Construction Equipment Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/construction-equipment-market