
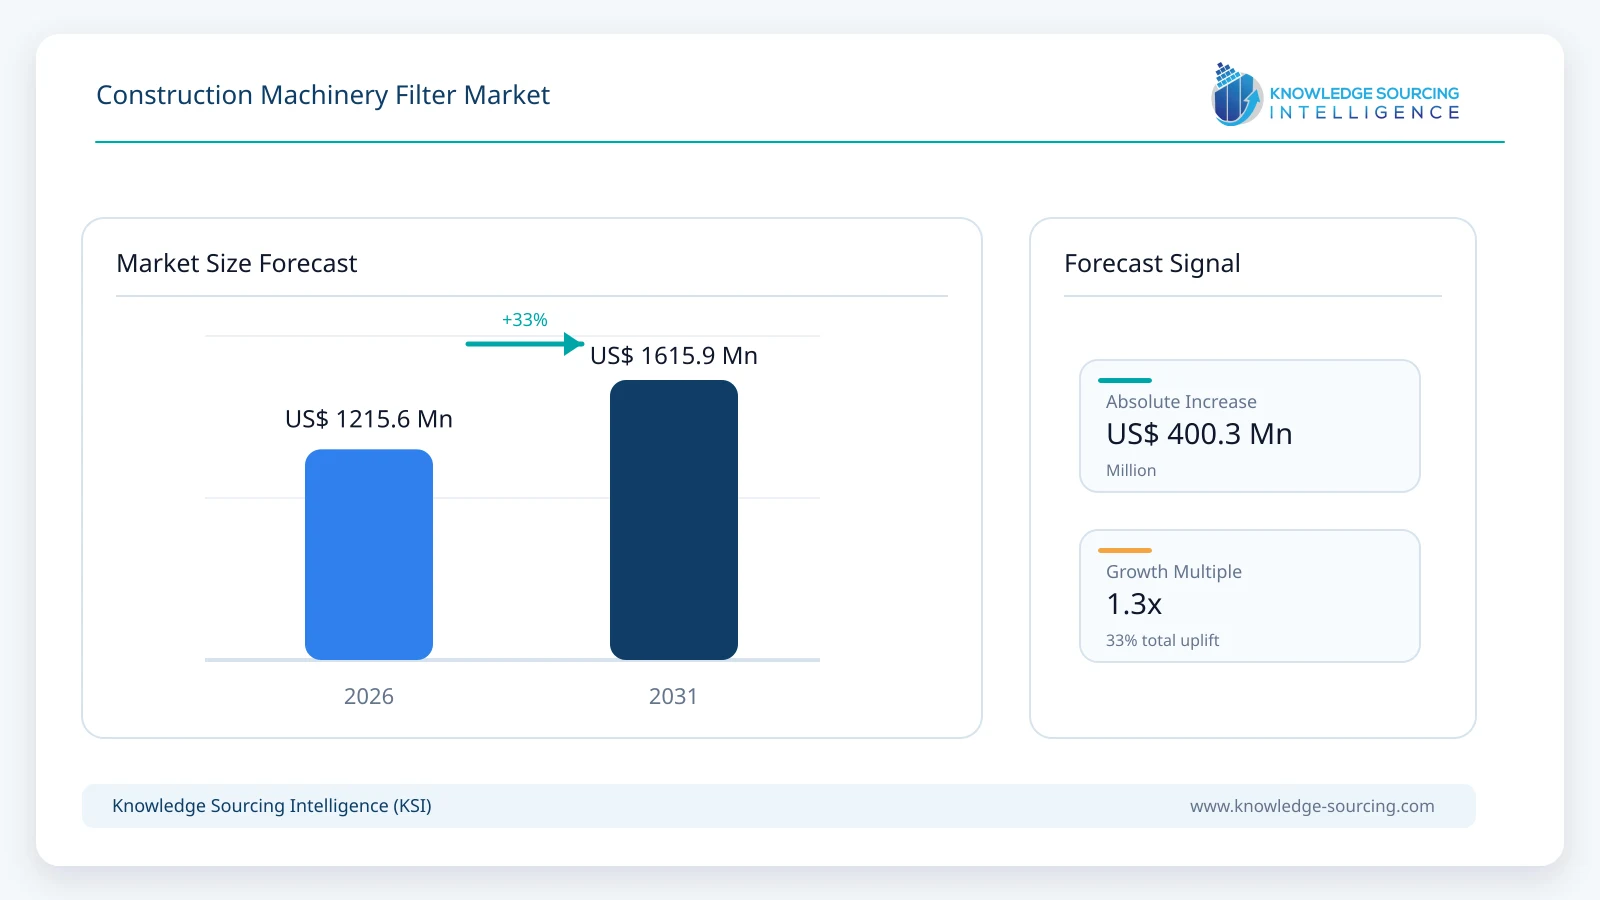
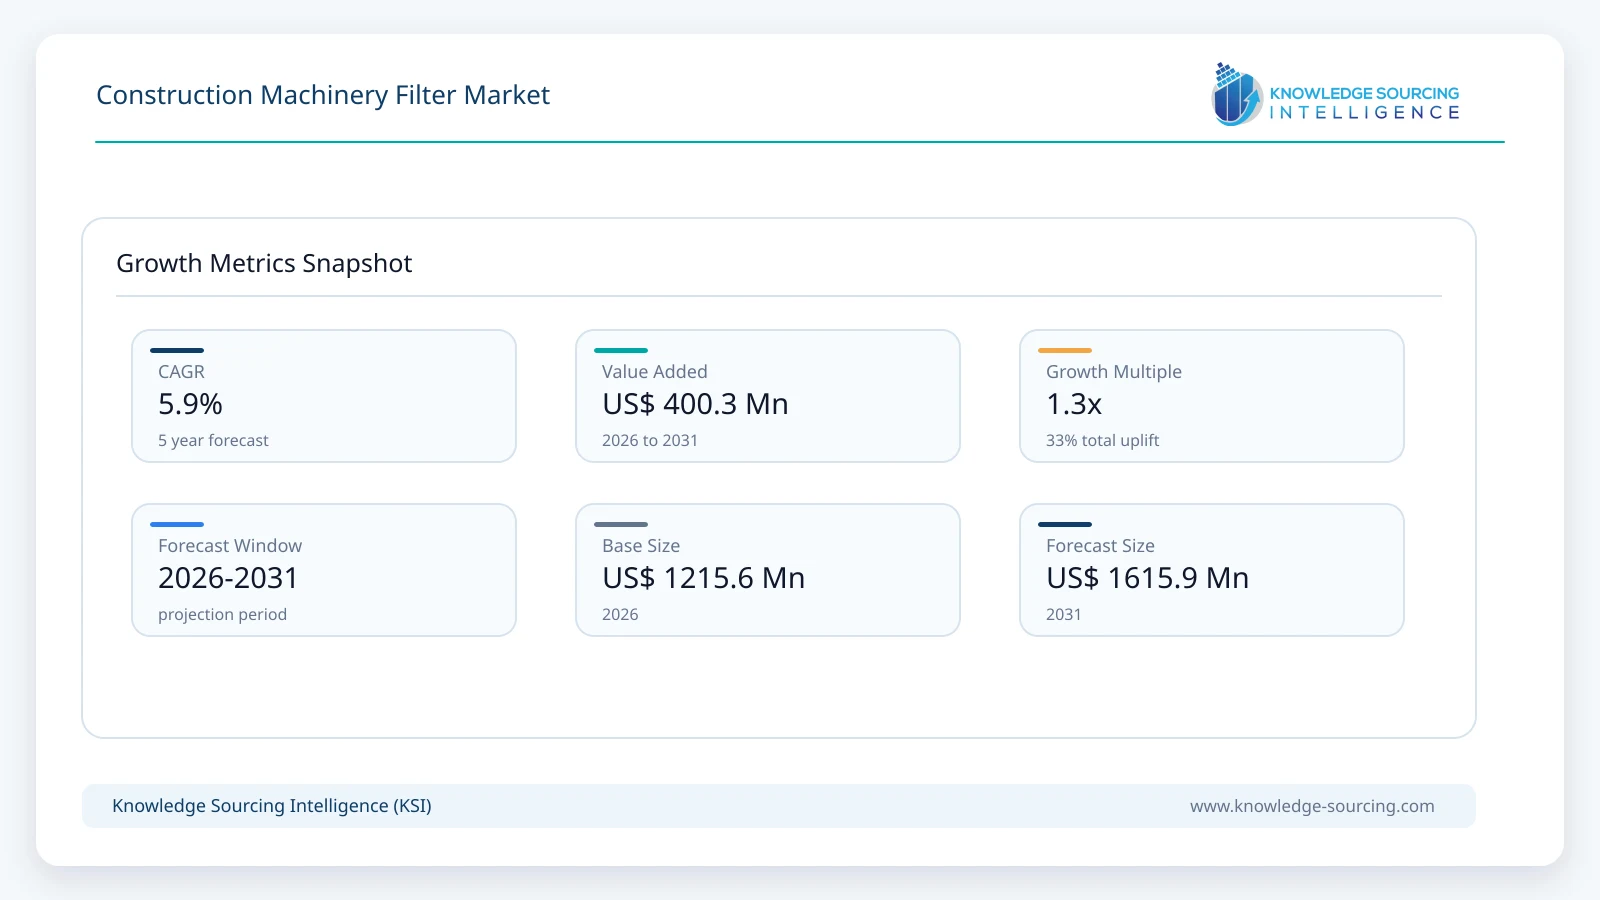
The Construction Machinery Filter Market is set to reach USD 1,615.88 million in 2031, growing at a CAGR of 5.9% between 2026 and 2031, from USD 1,215.60 million in 2026.
Highlights:
- 1Construction machinery filtersare integrated into Filter Paks for compact equipment, consolidating nearly all maintenance components into single part numbers for streamlined preventive upkeep and reduced inventory management.
- 2Advanced sensor integrationin gas filtration systems enables preemptive saturation detection and active self-regeneration cycles to maintain consistent air quality across high-demand engines.
- 3Progressive multi-stage filtrationon fuel systems with water separators optimizes performance in high-horsepower applications while ensuring reliable combustion efficiency.
- 4Crankcase ventilation filtrationincorporates advanced media to capture and recycle contaminants, supporting extended service intervals and minimizing downtime in continuous-duty operations.
Market Overview
The construction machinery filters market is estimated at USD 1,215.60 million in 2026 and is projected to reach a market size of USD 1,615.88 million by 2031, representing a 5.9% CAGR during 2026–2031. The market is benefiting from increased equipment utilization, stringent emission regulations, growing maintenance requirements, and emphasis on machinery uptime coupled with operational efficiency.
The demand for both air and oil filters is likely to continue to grow as construction equipment fleets develop and state-of-the-art machines frequently have two or more filtration points for each element. According to YAMASHIN, filters in various mechanical components required for construction machinery are becoming increasingly advanced.
In terms of application, the market is bifurcated into new-equipment (OEM) and replacement segments. New equipment demand aligns with the production of construction machinery, while replacement demand is consistently recurring because filters require periodic servicing. According to YAMASHIN, roughly 80% of its construction-machinery-filter revenue in FY2025 came from OEM products, underscoring the importance of the new-equipment channel for specialty filtration suppliers.
Hydraulic filters remain crucial, as hydraulic contamination can destroy cylinders, controls, and the hydraulic system itself. According to YAMASHIN, 70% of failures in hydraulic systems are due to contaminated fluid. There are also similarities between hydraulic filtration and other types of filtrations, such as engine oil, fuel, transmission, and air filtration in construction machinery.
Excavators, loaders, bulldozers, and off-highway trucks are significant filtration applications because they operate in a high-dust, high-load, durability process directly dependent on hydraulic, fuel oil, and air filtration systems. For instance, Parker focuses on filtration products for applications such as earthmoving and construction equipment, including excavators.
Asia-Pacific continues as a key opportunity area due to the rise in the construction-equipment base and machinery production ecosystem, strengthened by markets like China, Japan, India & other Asian equipment & filtration markets. YAMASHIN says it provides construction machinery filters across North America, Europe, China, and other Asian markets and is growing its business in China.
OEM supply for engineered filtration products continues to be substantial, while aftermarket provides consistent recurring replacement demand.
The buyer looks at the filter to evaluate it based on the filtration efficiency, service life, pressure drop, protection against system parts, replacement frequency, and downtime avoidance, rather than the price of the filter alone.
The filter manufacturers are diversifying their product portfolios with application-specific filters. For instance, Donaldson introduced a new range of hydraulic filter cartridges for construction and mining applications in July 2025, which shows continued expansion of its product development activity.
Environmental demands are leading to the increased need for higher-performance filtration solutions. According to YAMASHIN, tighter environmental regulations for global construction machinery are raising expectations regarding filtration performance, and its filters were adopted for newer Chinese construction machinery that meets the fourth round of environmental regulations.
Client Takeaways
Increased equipment utilization, greater replacement cycles, emissions requirements, and filtration technology are driving market growth.
Filtration from oil filter manufacturers that protects hydraulic and engine components, extends service life, reduces downtime, and promotes equipment efficiency is a growing requirement for machinery owners.
Hydraulic, air, fuel, engine-oil, and transmission filters together cover the major filtration buckets across construction machinery.
The Asia-Pacific, especially the big construction-requiring markets such as China and India, provides a significant opportunity besides established North American and European markets.
Filters represent new opportunities for construction-equipment manufacturers (OEMs) and filter manufacturers, machinery dealers, distributors, rental fleets, contractors, and independent aftermarket suppliers.
The OEM segment plays a key role in machine-integrated filtration, while aftermarket presents repeat replacement opportunities in the machinery lifecycle.
Market Drivers
Increasing Construction and Infrastructure Development
The growing sale and use of construction machinery, driven by sustained investments in roads, railways, urban infrastructure, energy, water systems, and other large-scale construction projects, is boosting repeat demand for machinery filters that support the engine hydraulic system, fuel system & air-intake system.
In India, public capital expenditure increased from ?2 lakh crore in FY2014–15 to ?12.2 lakh crore in FY2026–27 (Budget Estimate) as per PIB data, aiding infrastructure development on a sustained basis.
The Union Budget of India 2026–27 announced the Infrastructure Risk Guarantee Fund and City Economic Regions, increasing support for infrastructure development and urban investment.
The National Highways Authority of India (NHAI) constructed 5,614 km of national highways in FY2024–25, far above its annual target of 5,150 km as road-construction activity continues unabated.
The capital expenditure of NHAI increased to over ?2.50 lakh crore in FY2024–25, up around 21% over ?2.07 lakh crore in FY2023–24 as of April 2025.
Additionally, according to the United States Census Bureau, in July 2026, U.S. construction spending was estimated at USD 2.16 trillion at a seasonally adjusted annual rate, which shows ongoing construction development.
In 2024, total U.S. public construction spending was USD 492.7 billion through September, of which USD 456.5 billion was at state and local levels, as per the U.S. Conference of Mayors.
According to the same source, local and state construction spending is projected to be approximately USD 479 billion by 2025, which continues to drive sales of construction equipment used in infrastructure projects.
The UK predicts a 3.9% increase in output from new infrastructure construction in 2025, followed by a 2.4% increase in 2026. Project activity is expected to continue growing at a steady rate of +4.6% each year until 2027.
Infrastructure projects are growing in size and scale, with major activities taking place across roads, urban development, transportation, utilities, and other civil works, leading to higher use of excavators, loaders, bulldozers, and cranes, among others; in turn driving demand for air filters, fuel filters, hydraulic filters, and engine filters, supporting construction machinery filter market growth.
Major Segment Analysis
Replacement Market
By application, the construction machinery filter market is segmented into new markets and replacement markets, where the latter is expected to show considerable growth fueled by the active utilization of heavy machinery. Growing emphasis on optimizing machinery performance and energy efficiency has increased the demand for advanced filtration technology, propelling market expansion. The replacement market is expected to show considerable growth fueled by continued focus on improving and maintaining the working efficiency of construction machinery.
Millions of construction equipment and machinery units are sold worldwide annually to address the active utilization for advance tools and machinery in the sector. Therefore, maintaining the working efficiency of such machinery requires timely replacement of key components, including filters.
Global machinery manufacturing nations like China have shown positive uplift in their construction machinery sales according to the China Machinery Industry Federation (CMT). This further bolsters the replacement and maintenance scenario for heavy and off-road construction equipment.
Compliance with stringent emission standards such as USA EPA Tier 4 and China’s IV Non-Road Emission Standards further propels the market demand for next-generation filtration technology. As billions are invested in construction projects in such nations, this will likely expand the replacement scenario of old operating machinery.
Global regions such as Europe, where construction constitutes nearly 35% of total waste generation and 5-12% of national GHG emissions, have set sustainable directives to limit emissions, which have established a new framework for component replacement.
Geographical Outlook
North America: the US
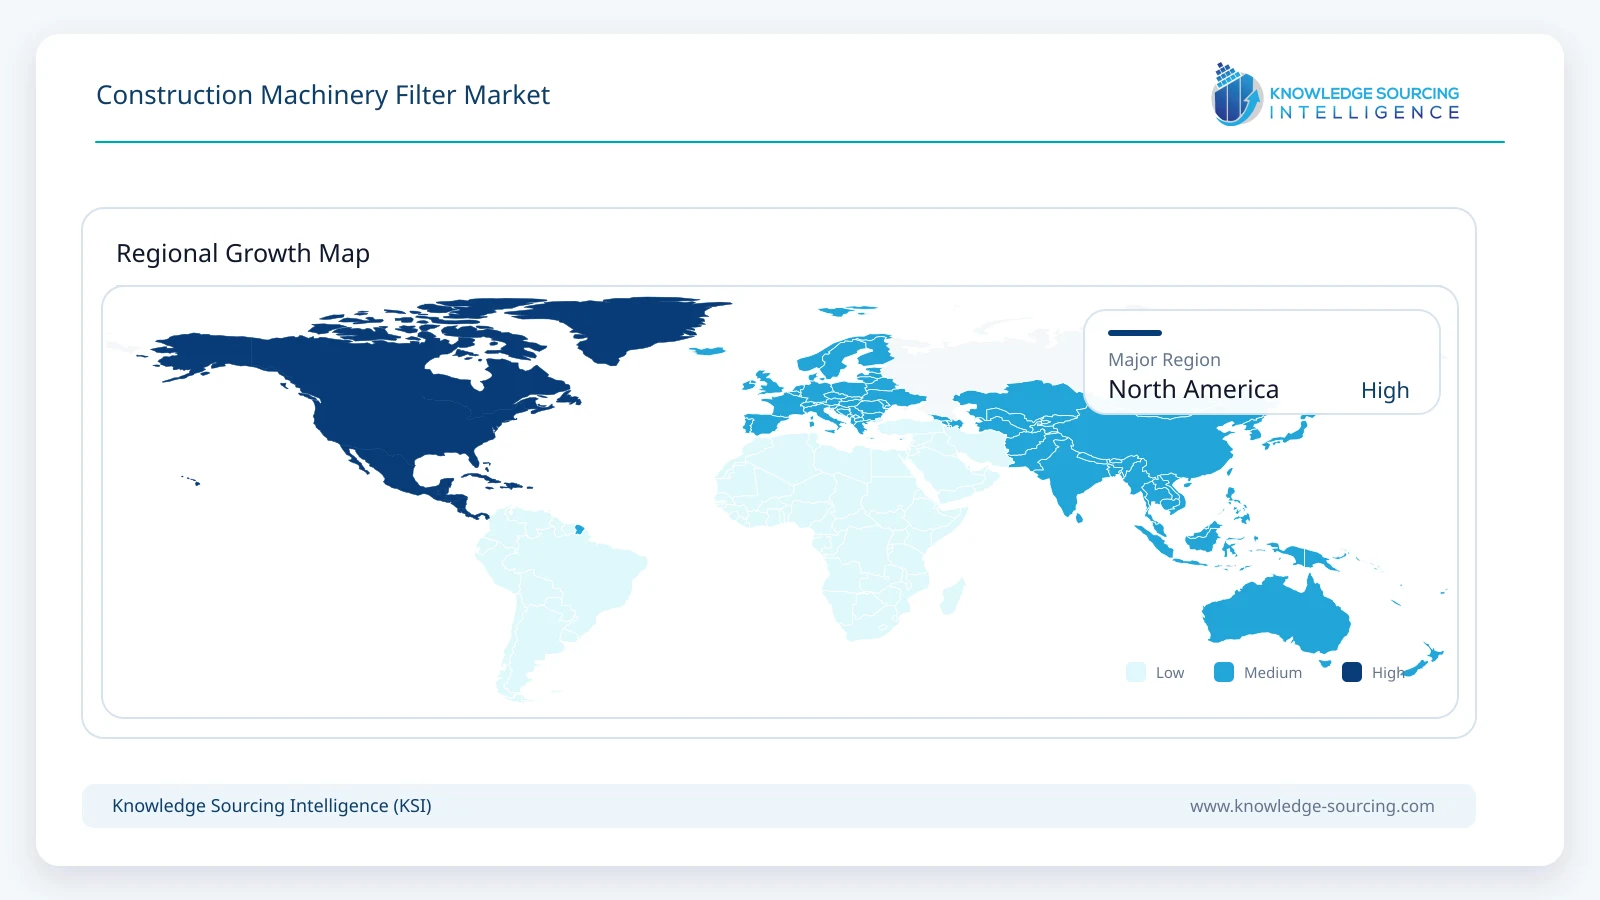
The United States construction machinery filter market is projected to show considerable growth owing to the high non-residential construction spending and innovations in filtration technology.
Improved infrastructure investment and spending in non-residential construction have propelled heavy machinery usage in the United States, which positively influences market growth. According to the US Census Bureau, non-residential construction spending in July 2026 reached USD 1,284.87 billion (At a Seasonally Adjusted Rate).
Growing environmental awareness, followed by the implementation of stringent emission standards such as EPA Tier 4, which are applied to off-road diesel engines used in construction vehicles and heavy machinery, has also transformed the market outlook in the United States.
Continued technological shift in the construction sector has provided new growth prospects for modern machinery and components, including filters, in the US market. Various key players have capitalized on this trend. For instance, in February 2026, Donaldson Company launched “ArmorSeal”, a next-generation air filtration product for off-highway construction machinery.
Adoption of a capital-intensive construction approach in the United States has expanded the usage scenario of heavy machinery in a vibrant construction environment, and as infrastructure projects backed by government funding are progressing, the requirement for effective filtration technology is poised for positive expansion.
Supportive market dynamics, such as the collaboration of filter OEMs such as MANN+HUMMEL with major construction machinery manufacturers in the United States, followed by an extensive supply chain network of aftermarket distributors, have improved the overall market transparency in the country.
Key Developments
August 2026: Parker Hannifin officially completed its major acquisition of Filtration Group Corporation, significantly expanding its global footprint in industrial, hydraulic, and heavy-duty filtration systems to strengthen aftermarket distribution channels across international markets.
August 2026: Germany-based investor VTC completed the acquisition of MANN+HUMMEL’s Water & Fluid Solutions membrane business, allowing the parent group to concentrate resources on core automotive, heavy machinery, and industrial air/oil filtration sectors.
February 2026: Donaldson Company rolled out its advanced ArmorSeal heavy-duty air filtration technology, engineered specifically to protect high-vibration construction and mining machinery engines from severe dust ingress while optimizing overall operating lifespans.
Company Profiles
Caterpillar Inc.'s strategy in the construction machinery filter market revolves around a proprietary, system-based design approach focused on Original Equipment Manufacturer (OEM) exclusivity and total cost of ownership reduction. Rather than manufacturing filters to broad, general industry standards, Caterpillar designs its filtration solutions specifically alongside its heavy machinery specifications to ensure optimal compatibility and system protection.
This strategy effectively captures long-term aftermarket revenue by encouraging fleet owners to rely exclusively on "genuine Cat filters" to safeguard their high-value equipment investments.
Construction Machinery Filter Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1,215.60 million |
| Total Market Size in 2031 | USD 1,615.88 million |
| Forecast Unit | Million |
| Growth Rate | 5.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Construction Machine, Material, Application, Region |
| Companies |
|
Market Segmentation
By Type
Hydraulic Fluid Filters
Return Filters
Line Filters
Others
Transmission Filters
Engine Oil Filters
Fuel Filters
Air Filters
By Construction Machine
Excavator
Loader
Backhoe Loader
Crawler Loader
Skid Steer Loader
Wheeled Loader
Bulldozer
Off-Highway Trucks
Others
By Material
Synthetic Fiber
Cellulose
Metal Mesh
Others
By Application
New Market
Replacement Market
By Region
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
Japan
India
South Korea
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. MARKET DYNAMICS
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
4. BUSINESS LANDSCAPE
4.1. Regulatory & Compliance Landscape
4.2. Raw Material Pricing & Cost Analysis
4.3. Import/Export Analysis
4.4. Aftermarket & Replacement Filter Analysis
4.5. Strategic Analysis
5. TECHNOLOGY AND INNOVATION OUTLOOK
5.1. Advanced Filtration Media Technologies
5.2. Hydraulic Filtration Technologies
5.3. Engine Air, Oil & Fuel Filtration Technologies
5.4. Filter Monitoring & Condition-Based Filtration Technologies
5.5. Sustainable & Extended-Life Filter Technologies
6. CONSTRUCTION MACHINERY FILTER MARKET BY TYPE (2021-2031)
6.1. Introduction
6.2. Hydraulic fluid filters
6.2.1. Return filters
6.2.2. Line filters
6.2.3. Others
6.3. Transmission filters
6.4. Engine oil filters
6.5. Fuel filters
6.6. Air filters
7. CONSTRUCTION MACHINERY FILTER MARKET BY CONSTRUCTION MACHINE (2021-2031)
7.1. Introduction
7.2. Excavator
7.3. Loader
7.3.1. Backhoe Loader
7.3.2. Crawler Loader
7.3.3. Skid Steer Loader
7.3.4. Wheeled Loader
7.4. Bulldozer
7.5. Off-Highway Trucks
7.6. Others
8. CONSTRUCTION MACHINERY FILTER MARKET BY MATERIAL (2021-2031)
8.1. Introduction
8.2. Synthetic Fiber
8.3. Cellulose
8.4. Metal Mesh
8.5. Others
9. CONSTRUCTION MACHINERY FILTER MARKET BY APPLICATION (2021-2031)
9.1. Introduction
9.2. New Market
9.3. Replacement Market
10. CONSTRUCTION MACHINERY FILTER MARKET BY REGION (2021-2031)
10.1. Introduction
10.2. North America
10.2.1. By Type
10.2.2. By Construction Machine
10.2.3. By Material
10.2.4. By Application
10.2.5. By Country
10.2.5.1. USA
10.2.5.2. Canada
10.2.5.3. Mexico
10.3. South America
10.3.1. By Type
10.3.2. By Construction Machine
10.3.3. By Material
10.3.4. By Application
10.3.5. By Country
10.3.5.1. Brazil
10.3.5.2. Argentina
10.3.5.3. Others
10.4. Europe
10.4.1. By Type
10.4.2. By Construction Machine
10.4.3. By Material
10.4.4. By Application
10.4.5. By Country
10.4.5.1. United Kingdom
10.4.5.2. Germany
10.4.5.3. France
10.4.5.4. Spain
10.4.5.5. Others
10.5. Middle East and Africa
10.5.1. By Type
10.5.2. By Construction Machine
10.5.3. By Material
10.5.4. By Application
10.5.5. By Country
10.5.5.1. Saudi Arabia
10.5.5.2. UAE
10.5.5.3. Others
10.6. Asia Pacific
10.6.1. By Type
10.6.2. By Construction Machine
10.6.3. By Material
10.6.4. By Application
10.6.5. By Source
10.6.6. By Country
10.6.6.1. China
10.6.6.2. Japan
10.6.6.3. India
10.6.6.4. South Korea
10.6.6.5. Taiwan
10.6.6.6. Others
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Players and Strategy Analysis
11.2. Market Share Analysis
11.3. Mergers, Acquisitions, Agreements, and Collaborations
11.4. Competitive Dashboard
12. COMPANY PROFILES
12.1. Baldwin Filters, Inc.
12.2. Bosch Rexroth GmbH
12.3. Caterpillar Inc.
12.4. Donaldson Company, Inc.
12.5. Fleetguard (Cummins)
12.6. Groupe HIFI (HIFI Filter)
12.7. Hengst SE & Co. KG
12.8. MAHLE GmbH
12.9. MANN+HUMMEL International GmbH Co. KG
12.10. Pall Corporation
12.11. Parker Hannifin Corporation
12.12. UFI Filters
12.13. YAMASHIN-FILTER CORP
13. RESEARCH METHODOLOGY
14. LIST OF FIGURES
15. LIST OF TABLES
Navigate
Trusted by the world's leading organizations











