
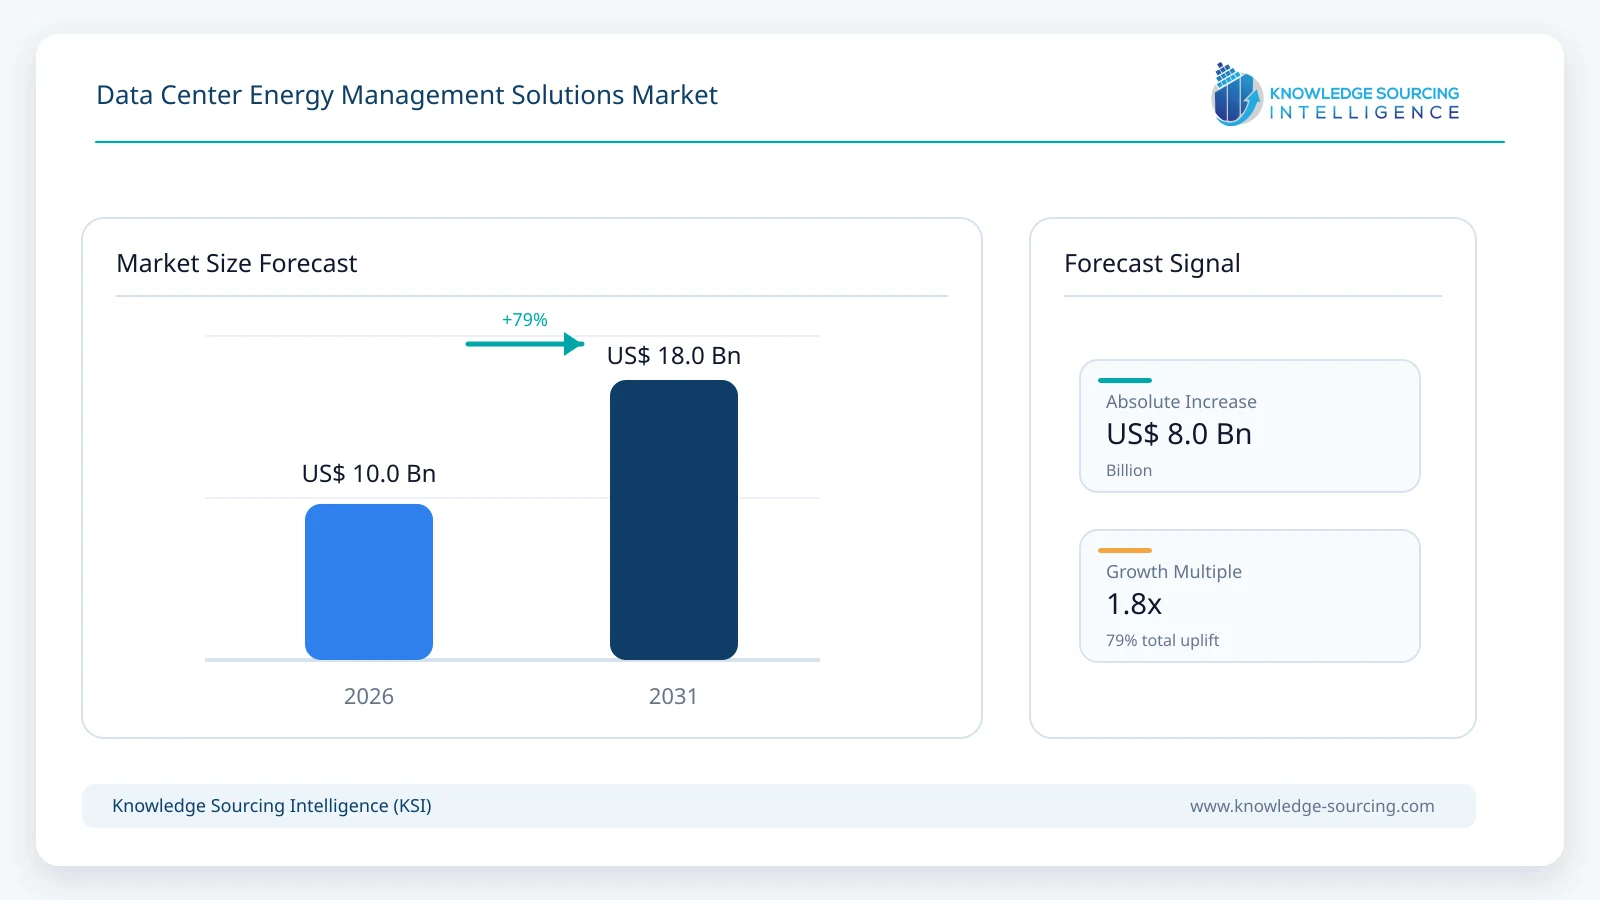
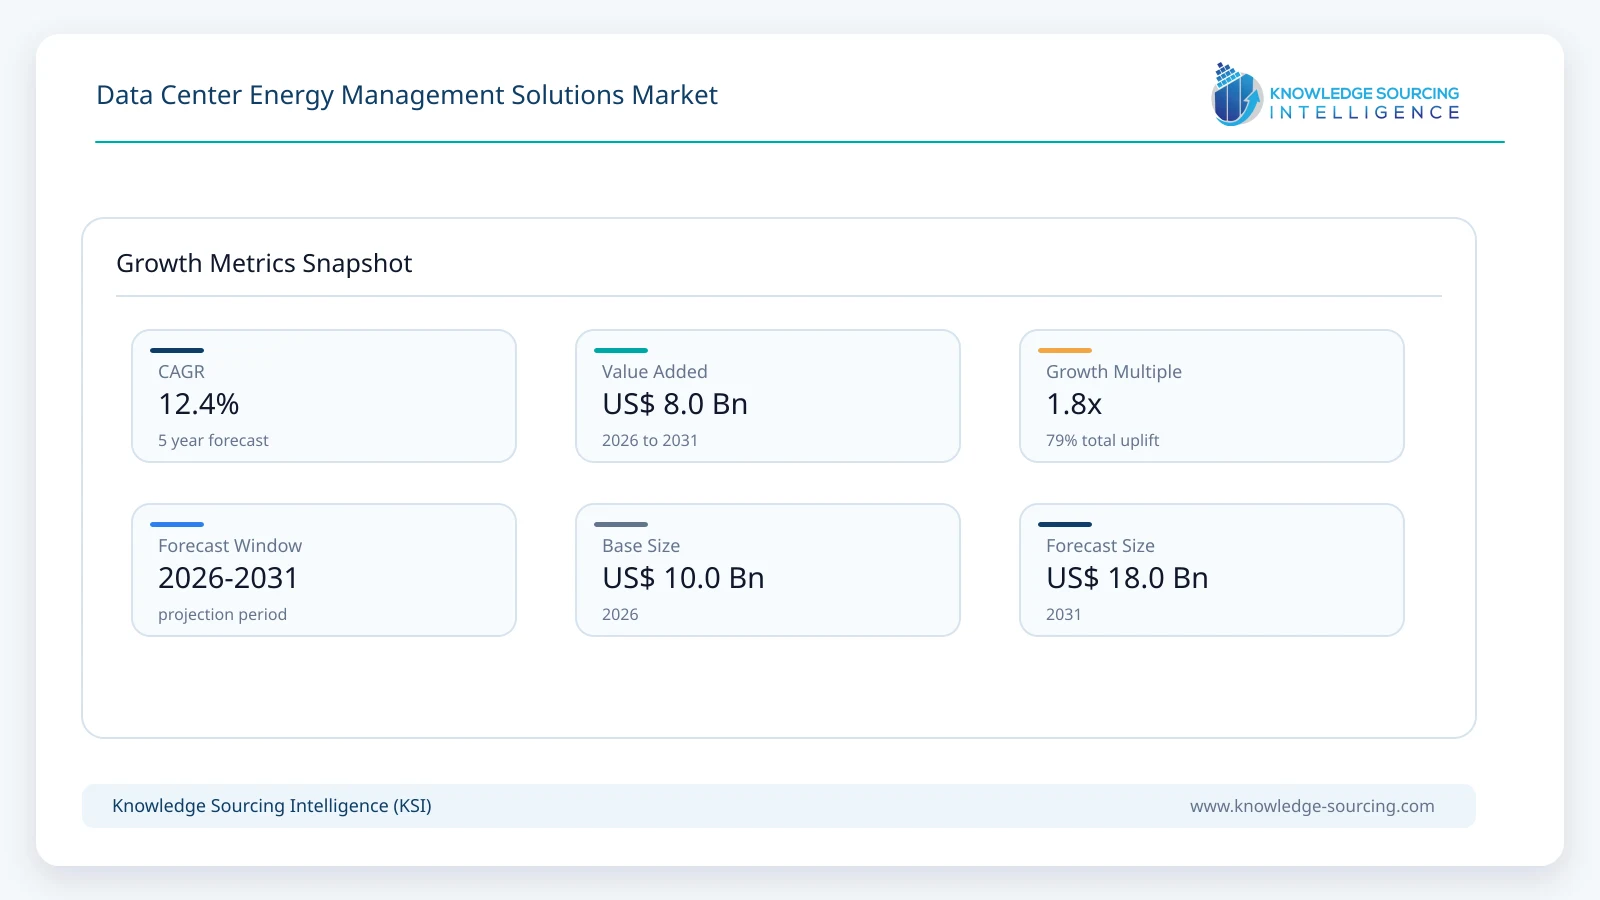
The Data Center Energy Management Solutions Market is forecast to grow at a CAGR of 12.40%, reaching USD 17.96 billion in 2031 from USD 10.01 billion in 2026.
Highlights:
- 1Growing electricity costs and higher rack densities are accelerating investment in intelligent energy optimisation solutions.
- 2Data Center Infrastructure Management (DCIM) software remains a commercially important solution due to its central role in operational visibility.
- 3North America continues to represent a major demand centre supported by hyperscale cloud expansion and AI infrastructure investment.
- 4AI-enabled energy analytics and predictive optimisation are becoming standard evaluation criteria during procurement.
- 5Energy efficiency regulations and sustainability reporting requirements are influencing technology adoption across multiple regions.
- 6Competition increasingly centres on integrated software-hardware platforms supported by lifecycle services and open system interoperability.
The Data Center Energy Management Solutions Market comprises software, hardware, and professional services that enable operators to monitor, control, analyse, and optimise energy consumption across data centre facilities. These solutions integrate electrical infrastructure, cooling systems, environmental monitoring, power distribution, lighting, and operational analytics into unified management platforms that improve energy efficiency while supporting service availability. As data centres continue to expand in capacity to accommodate artificial intelligence (AI), cloud computing, enterprise digital services, and edge infrastructure, energy management has become a core operational priority rather than a facility management function.
Energy has become one of the largest operating expenditures for data centre owners and operators. Rising electricity prices, increasing rack power densities, and stricter environmental reporting obligations are encouraging organisations to invest in technologies that provide real-time visibility into power consumption and cooling efficiency. Buyers are no longer seeking only infrastructure monitoring capabilities; procurement decisions increasingly prioritise predictive analytics, workload-aware energy optimisation, automated control systems, and integration with broader enterprise sustainability programmes.
Demand originates from enterprise data centres, hyperscale operators, colocation providers, government facilities, financial institutions, healthcare organisations, and manufacturing companies operating mission-critical computing environments. Purchasing decisions are influenced by power usage effectiveness (PUE), infrastructure resilience, scalability, interoperability with existing building management systems, cybersecurity requirements, and measurable operational savings. Many procurement teams evaluate solutions based on lifecycle cost reductions rather than initial acquisition expenses, reflecting the growing financial significance of electricity consumption throughout facility operations.
Industry structure reflects collaboration between electrical equipment manufacturers, software developers, facility management specialists, network infrastructure providers, and digital infrastructure service companies. Hardware vendors increasingly bundle intelligent monitoring devices with software analytics, while service providers support implementation, commissioning, optimisation, and long-term maintenance. The competitive environment therefore extends beyond standalone products towards integrated energy management ecosystems capable of supporting hybrid, hyperscale, and distributed computing environments.
Artificial intelligence workloads are reshaping infrastructure requirements across the industry. High-density servers demand more sophisticated cooling technologies and continuous monitoring of electrical loads. Operators require granular data collection from power distribution units, cooling equipment, and environmental sensors to prevent capacity constraints while maintaining operational efficiency. Consequently, investments are shifting towards intelligent automation that supports predictive maintenance, dynamic cooling adjustments, and continuous optimisation of energy consumption.
Market Drivers
Rising Energy Consumption from AI and High-Density Computing
Artificial intelligence infrastructure requires considerably higher power densities than conventional enterprise workloads. GPU-intensive servers increase electrical demand while generating greater thermal loads that require sophisticated cooling management. Data centre operators therefore seek advanced energy management platforms capable of balancing electrical distribution, cooling performance, and equipment utilisation in real time.
Suppliers are responding by integrating machine learning algorithms with monitoring platforms that identify inefficiencies before they affect operational reliability. These capabilities help customers reduce operating expenditure while supporting higher computing capacity without proportionate increases in facility expansion.
Sustainability Commitments and Carbon Reduction Targets
Corporate sustainability programmes increasingly include measurable objectives for reducing electricity consumption and greenhouse gas emissions across digital infrastructure. Investors, regulators, and customers expect organisations to disclose environmental performance using recognised reporting frameworks.
Energy management solutions support these objectives by providing accurate energy measurement, emissions reporting, and optimisation recommendations. Companies investing in such platforms improve compliance readiness while strengthening long-term operational efficiency, making sustainability a commercial purchasing consideration rather than solely a corporate responsibility initiative.
Expansion of Colocation and Hyperscale Data Centres
Global cloud adoption continues to encourage investment in hyperscale campuses and colocation facilities. These operators manage thousands of servers across geographically distributed sites, making manual energy management impractical.
Centralised monitoring platforms enable operators to compare facility performance, standardise operational procedures, and optimise energy consumption across multiple locations. Vendors offering scalable architectures with remote management capabilities therefore benefit from expanding infrastructure portfolios.
Increasing Focus on Operational Resilience
Power interruptions and thermal instability remain critical operational risks for data centres supporting financial services, healthcare, telecommunications, and government applications. Energy management systems provide continuous visibility into electrical infrastructure, enabling operators to detect abnormal conditions before service disruption occurs.
This preventive approach reduces unplanned downtime, improves equipment lifespan, and supports regulatory compliance for industries operating critical digital services.
Market Restraints and Challenges
High Integration Complexity
Many existing facilities operate heterogeneous electrical infrastructure sourced from multiple manufacturers over several decades. Integrating new software platforms with legacy equipment often requires customised interfaces, additional engineering, and prolonged implementation schedules.
These complexities increase deployment costs and may delay procurement decisions, particularly among enterprises operating ageing facilities with limited infrastructure standardisation.
Capital Investment Constraints
Although energy management solutions generate operational savings over time, implementation frequently requires investment in sensors, intelligent power distribution equipment, software licences, networking infrastructure, and consulting services.
Smaller enterprise operators often prioritise immediate computing capacity expansion over energy optimisation projects, extending purchasing cycles despite recognised efficiency benefits.
Cybersecurity Requirements
Energy management platforms increasingly connect operational technology with enterprise IT networks and cloud-based analytics platforms. This convergence introduces cybersecurity considerations that influence procurement evaluations.
Buyers demand secure communication protocols, access controls, software updates, and compliance with recognised cybersecurity standards. Vendors unable to demonstrate robust security capabilities may encounter slower adoption among highly regulated industries.
Skills Availability
Successful implementation depends upon engineering expertise covering electrical systems, facility operations, software integration, and analytics. Many organisations experience shortages of personnel capable of managing increasingly sophisticated energy optimisation platforms.
Service providers therefore play an expanding role through consulting, implementation support, remote monitoring, and managed operational services.
Major Segment Analysis
Data Center Infrastructure Management (DCIM) Software
DCIM software represents one of the most commercially important solution categories because it functions as the operational intelligence layer connecting electrical infrastructure, environmental systems, asset management, and capacity planning. Rather than monitoring isolated components, modern DCIM platforms deliver comprehensive visibility across power distribution, cooling performance, equipment utilisation, and facility capacity.
Buyers increasingly require software capable of integrating information from intelligent PDUs, cooling equipment, building management systems, and environmental sensors into a unified operational dashboard. Integration flexibility has become an important purchasing criterion since many organisations operate equipment supplied by multiple vendors.
Competition within this segment increasingly focuses on advanced analytics, predictive maintenance, digital twin capabilities, AI-assisted recommendations, and cloud-enabled remote management. Vendors also differentiate through open APIs that simplify integration with enterprise asset management, sustainability reporting, and IT service management platforms.
Commercially, DCIM software generates recurring revenue through subscriptions, maintenance agreements, software upgrades, and consulting services, creating long-term customer relationships beyond initial infrastructure deployment.
Regional Analysis
North America
North America represents a mature market supported by extensive hyperscale cloud infrastructure, AI computing investments, and stringent corporate sustainability commitments. Major cloud providers, colocation operators, financial institutions, and technology companies continue expanding facility capacity while seeking measurable reductions in operating costs. Buyers prioritise automation, predictive analytics, and interoperability with existing infrastructure.
Europe
European demand is strongly influenced by environmental regulations, energy efficiency policies, and corporate carbon reduction objectives. Electricity pricing and sustainability reporting obligations encourage investment in sophisticated monitoring platforms. Operators increasingly evaluate procurement based on lifecycle energy performance alongside infrastructure resilience.
Asia Pacific
Asia Pacific continues expanding digital infrastructure through cloud adoption, enterprise digitalisation, government investment programmes, and growing internet usage. China, India, Japan, and Southeast Asian economies are developing new hyperscale and edge facilities. Procurement decisions often balance cost efficiency with scalability, particularly among rapidly expanding cloud service providers.
Middle East & Africa
Governments across the Gulf region are investing in digital infrastructure to support economic diversification strategies. New data centre developments create opportunities for integrated energy management solutions designed for high ambient temperatures and demanding cooling requirements. Adoption elsewhere in the region remains influenced by infrastructure investment levels and energy availability.
South America
Brazil represents the largest regional demand centre due to expanding cloud infrastructure and enterprise digital investment. Organisations increasingly evaluate energy efficiency technologies to reduce operating costs amid electricity price volatility. Adoption remains comparatively gradual in smaller markets where capital investment constraints continue influencing procurement priorities.
Competitive Landscape
Competition is characterised by a combination of multinational industrial technology companies, digital infrastructure specialists, software developers, and facility optimisation providers, including Siemens AG, Schneider Electric SE, Honeywell International Inc., Johnson Controls International plc, Cisco Systems, Inc., Vertiv Holdings Co., ABB Ltd., Huawei Technologies Co., Ltd., Sunbird Software Inc., Hyperview Technologies Inc., and Vigilent Corporation.
Competitive differentiation depends on software functionality, interoperability, analytics capabilities, cybersecurity, lifecycle service offerings, and integration with broader facility infrastructure. Suppliers increasingly expand portfolios through strategic partnerships involving cloud platforms, cooling technologies, electrical infrastructure, and AI-enabled operational analytics. Geographic expansion continues through regional service networks supporting implementation, commissioning, and ongoing optimisation.
Recent Developments
June 2026: Schneider Electric announced that Northumbria Healthcare NHS Foundation Trust modernised its infrastructure using EcoStruxure™ Data Centre solutions, standardising UPS management and improving energy efficiency, operational visibility, and resilience across multiple healthcare facilities.
March 2026: Eaton launched Brightlayer Energy, an AI-powered Energy Management and Optimization System (EMOS) that delivers real-time energy forecasting, automated optimization, emissions monitoring, and distributed energy resource management, supporting more efficient operation of energy-intensive data centers and other critical facilities.
Regulatory and Policy Environment
Government energy efficiency policies and sustainability frameworks continue influencing procurement decisions across the industry. Regulations encouraging improved building energy performance, greenhouse gas disclosure, and efficient electricity consumption support adoption of intelligent monitoring technologies.
International standards including ISO 50001 for energy management systems provide structured approaches for continuous improvement in organisational energy performance. Data centre operators also increasingly reference standards published by organisations such as ASHRAE regarding thermal management and environmental operating conditions.
Within Europe, environmental reporting obligations and energy efficiency directives encourage investment in technologies capable of measuring and documenting operational performance. Similar sustainability initiatives are expanding across North America and Asia Pacific as governments pursue climate objectives while supporting digital infrastructure investment.
Compliance requirements increasingly extend beyond electrical efficiency to include operational transparency, resilience planning, cybersecurity, and environmental reporting, encouraging integrated software platforms capable of supporting multiple regulatory objectives simultaneously.
Outlook and Strategic Implications
The commercial outlook for the Data Center Energy Management Solutions Market will be shaped by expanding AI infrastructure, rising electricity demand, sustainability commitments, and increasing operational complexity. Investment priorities are expected to focus on intelligent software platforms that integrate power management, cooling optimisation, predictive maintenance, and environmental reporting within unified operational environments.
Procurement strategies are shifting towards long-term operational value instead of isolated equipment purchases. Buyers increasingly prefer scalable platforms supporting hybrid deployment models, open integration architectures, and continuous software enhancement. Service capabilities—including consulting, optimisation, and managed monitoring—will become increasingly important purchasing considerations alongside technical performance.
Competitive positioning will increasingly depend upon software intelligence, cybersecurity, interoperability, and measurable operational savings. Vendors capable of combining hardware expertise with advanced analytics and lifecycle services are likely to strengthen customer retention while expanding recurring revenue opportunities.
Despite continued challenges involving integration complexity, capital investment, and workforce capability, sustained investment in cloud infrastructure, AI computing, and sustainability initiatives is expected to maintain favourable demand conditions over the forecast period. Organisations able to demonstrate measurable improvements in energy efficiency, operational resilience, and regulatory compliance will remain well positioned as data centre operators continue prioritising operational excellence and long-term infrastructure optimisation.
Data Center Energy Management Solutions Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 10.01 billion |
| Total Market Size in 2031 | USD 17.96 billion |
| Forecast Unit | Billion |
| Growth Rate | 12.40% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Solution, Deployment, Data Center Type, End-User, Geography |
| Companies |
|
Market Segmentation
By Solution
By Deployment
By Data Center Type
By End-user
By Geography
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. GLOBAL DATA CENTER ENERGY MANAGEMENT SOLUTIONS MARKET BY SOLUTION
5.1. Introduction
5.2. Software
5.2.1. Building Energy Management System (BEMS)
5.2.2. Data Center Infrastructure Management (DCIM) Software
5.2.3. Energy Analytics and Optimization Software
5.3. Hardware
5.3.1. Smart Power Distribution Units (PDUs)
5.3.2. Environmental Monitoring and Cooling Solutions
5.3.3. Intelligent Lighting Control Solutions
5.3.4. Others
5.4. Services
5.4.1. Consulting
5.4.2. Installation and Integration
5.4.3. Support and Maintenance
6. GLOBAL DATA CENTER ENERGY MANAGEMENT SOLUTIONS MARKET BY DEPLOYMENT
6.1. Introduction
6.2. Cloud
6.3. On-Premises
7. GLOBAL DATA CENTER ENERGY MANAGEMENT SOLUTIONS MARKET BY DATA CENTER TYPE
7.1. Introduction
7.2. Enterprise Data Center
7.3. Colocation Data Center
7.4. Hyperscale Data Center
7.5. Edge Data Center
8. GLOBAL DATA CENTER ENERGY MANAGEMENT SOLUTIONS MARKET BY END-USER
8.1. Introduction
8.2. IT & Telecommunications
8.3. Colocation Service Providers
8.4. BFSI
8.5. Government
8.6. Healthcare
8.7. Manufacturing
8.8. Energy & Utilities
8.9. Others
9. GLOBAL DATA CENTER ENERGY MANAGEMENT SOLUTIONS MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. France
9.4.3. United Kingdom
9.4.4. Spain
9.4.5. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. United Arab Emirates
9.5.3. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. India
9.6.3. Japan
9.6.4. South Korea
9.6.5. Indonesia
9.6.6. Thailand
9.6.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Siemens AG
11.2. Schneider Electric SE
11.3. Honeywell International Inc.
11.4. Johnson Controls International plc
11.5. Cisco Systems, Inc.
11.6. Vertiv Holdings Co.
11.7. ABB Ltd.
11.8. Huawei Technologies Co., Ltd.
11.9. Sunbird Software Inc.
11.10. Hyperview Technologies Inc.
11.11. Vigilent Corporation
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations
Navigate
Trusted by the world's leading organizations











