
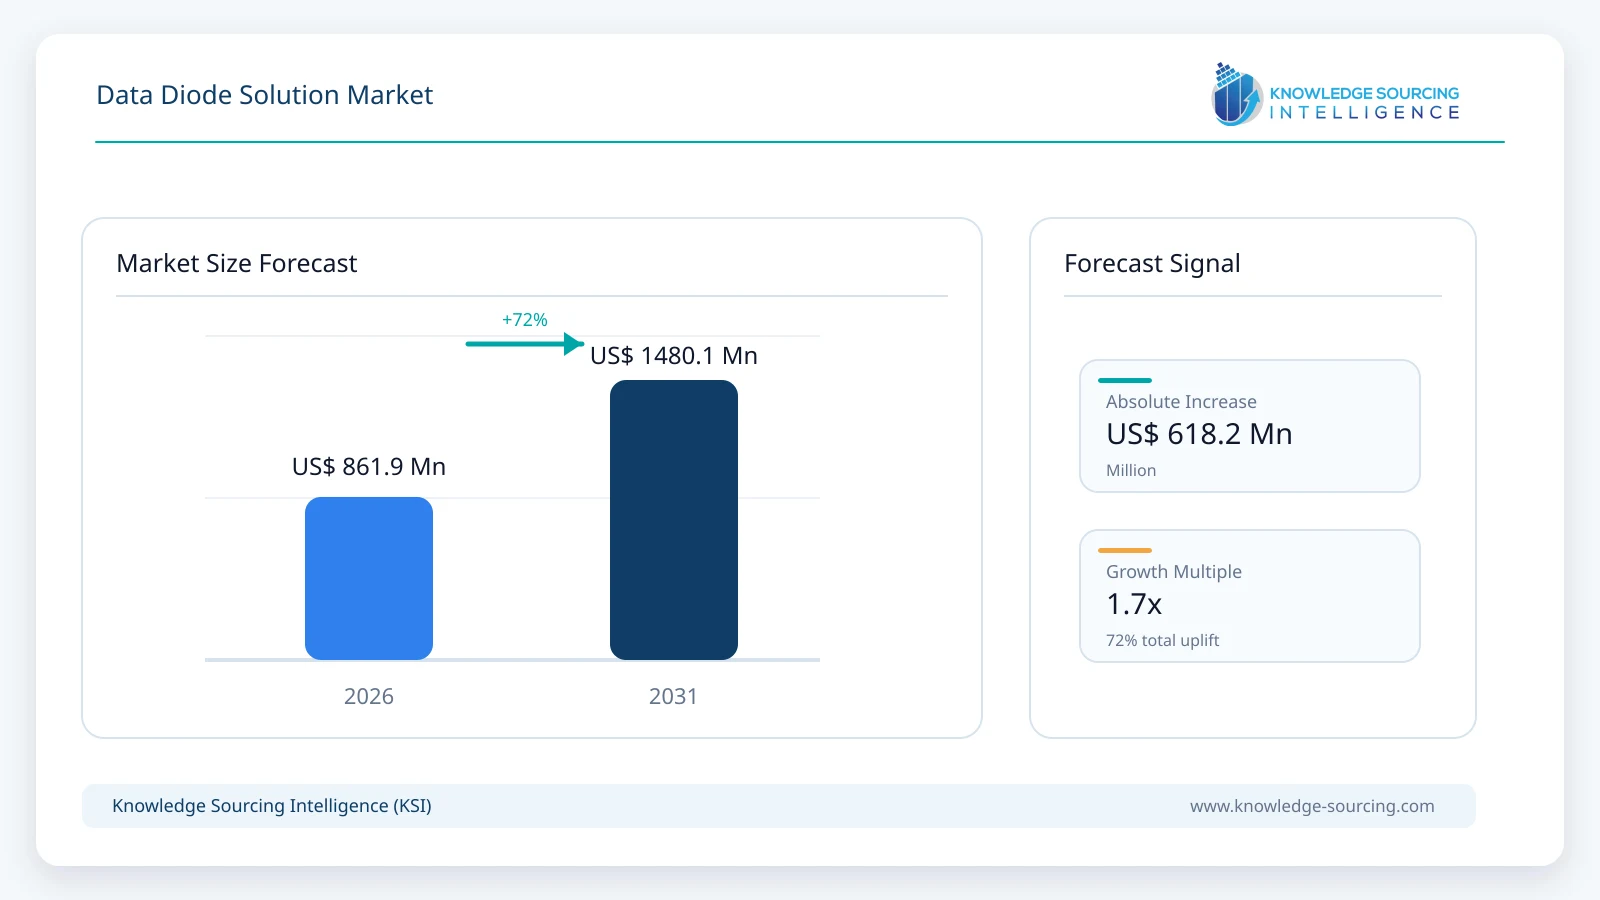
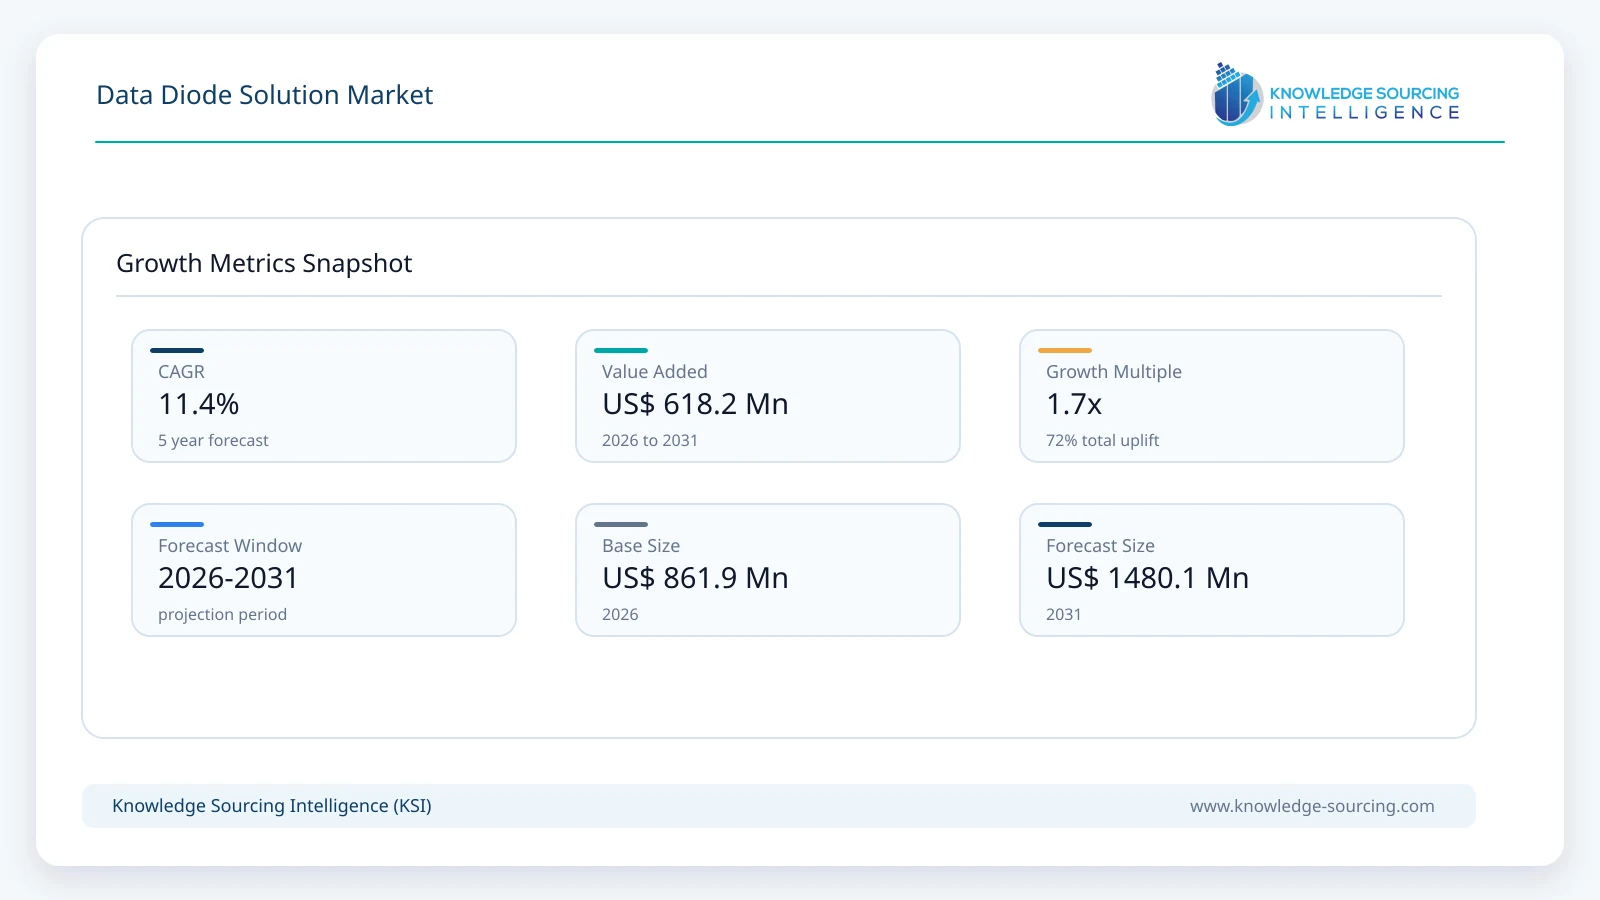
Data Diode Solution Market is forecast to grow at a CAGR of 11.4%, reaching USD 1,480.10 million in 2031 from USD 861.9 million in 2026.
Highlights:
- 1Increasing protection of operational technology (OT) networks is expanding demand for hardware-enforced one-way communication.
- 2Critical infrastructure operators are adopting data diodes to meet stricter cyber resilience and regulatory requirements.
- 3Government, defense, and energy organizations remain the primary buyers because of stringent security mandates.
- 4Integration with industrial control systems, SCADA, and Zero Trust architectures is broadening commercial applications.
- 5Suppliers are competing through certified security products, protocol support, systems integration, and lifecycle services.
This hardware-based architecture has become increasingly relevant for operators of industrial control systems, classified government networks, military platforms, power grids, transportation systems, and other environments where network compromise can interrupt essential operations or threaten national security. Guidance issued by cybersecurity agencies and critical infrastructure authorities continues to emphasize network segmentation and resilient system architecture as core defensive measures.
Purchasing decisions are primarily driven by security assurance rather than price alone. Buyers typically evaluate compliance with national cybersecurity frameworks, protocol compatibility with existing industrial control systems, certification status, deployment complexity, long-term maintenance, and vendor support capabilities. Government agencies, defense organizations, utilities, and industrial operators generally require proven performance under highly regulated operating conditions, resulting in lengthy qualification cycles and preference for suppliers with established deployment records.
Commercial value is distributed across hardware appliances, secure gateway software, protocol conversion, deployment services, lifecycle maintenance, and integration with industrial cybersecurity platforms. Vendors increasingly complement hardware offerings with centralized monitoring, logging, policy management, and managed support services to improve operational visibility without compromising one-way communication principles. Company announcements also indicate continued investment in expanding protocol support and interoperability as customers seek secure connectivity between legacy industrial assets and modern monitoring environments.
The market outlook through 2031 is expected to be influenced by continued modernization of critical infrastructure, expanding cybersecurity regulations, increasing geopolitical risk, and broader adoption of Zero Trust principles across operational environments. These conditions are encouraging organizations to replace purely software-based isolation with deterministic hardware security where uninterrupted operations carry high economic or national security consequences.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
NIST Cybersecurity Framework | CSF 2.0 (2024) | Expands emphasis on governance and cyber risk management across critical infrastructure. |
Primary Deployment Environment | Critical infrastructure OT networks | Continues to represent the principal commercial application for hardware-enforced one-way communication. |
Typical Customer Base | Government, defense, utilities, oil and gas, manufacturing | Procurement is concentrated in organizations operating high-value industrial or classified assets. |
Security Architecture Trend | Zero Trust adoption | Hardware isolation is increasingly integrated into broader Zero Trust security strategies. |
Deployment Priority | Industrial Control Systems (ICS)/SCADA protection | Operators continue strengthening separation between enterprise and operational networks. |
Market Drivers
Expansion of cybersecurity requirements for critical infrastructure
Operators of electricity transmission networks, water systems, transportation infrastructure, defense installations, and industrial manufacturing facilities are strengthening network isolation as cyber threats increasingly target operational technology. Regulatory guidance from agencies including NIST and sector-specific authorities places greater emphasis on resilient architecture, secure segmentation, and controlled data exchange between enterprise and operational networks. Hardware-enforced one-way communication satisfies these requirements by eliminating inbound attack paths rather than relying solely on configurable software controls. Vendors are responding by expanding certified product portfolios and support for industrial communication protocols commonly deployed across critical infrastructure environments.
Modernization of industrial control systems and remote operational monitoring
Industrial operators increasingly require production data, diagnostics, and asset-performance information to move securely from isolated operational networks to centralized monitoring platforms. Utilities, oil and gas operators, manufacturers, and transportation providers are modernizing supervisory control and data acquisition (SCADA) systems while maintaining strict separation from enterprise environments. Data diode solutions enable this operational visibility without introducing bidirectional network connectivity. Suppliers continue investing in protocol conversion, interoperability, and centralized management capabilities because customers seek integration with existing industrial infrastructure rather than complete replacement of legacy systems.
Growing adoption of Zero Trust security architectures
Zero Trust strategies increasingly extend beyond enterprise IT into operational technology environments where continuous verification alone cannot eliminate risks associated with bidirectional communication. Organizations responsible for national infrastructure and classified information are combining identity controls, continuous monitoring, and hardware-enforced network separation to reduce attack surfaces. Industry participants are therefore positioning data diodes as complementary components within broader cybersecurity architectures rather than standalone security appliances. Product development is increasingly focused on policy management, secure file transfer, telemetry sharing, and compatibility with existing cybersecurity platforms to address enterprise deployment requirements.
Rising investment in national defense and secure government communications
Government agencies continue allocating resources toward modernization of military communications, intelligence systems, border security, and classified digital infrastructure. These environments require deterministic protection mechanisms capable of supporting high-assurance information exchange while preventing unauthorized inbound access. Procurement priorities therefore extend beyond conventional cybersecurity software to specialized hardware capable of satisfying national security certification requirements. Companies serving defense customers continue investing in product assurance, secure manufacturing, and compliance with government procurement standards because certification status increasingly influences contract eligibility.
Market Restraints and Challenges
Lengthy certification and procurement cycles
Government agencies, defense organizations, and critical infrastructure operators typically require extensive security evaluation before approving deployment of data diode solutions. Product qualification often includes interoperability testing, cybersecurity assessment, environmental validation, and compliance with sector-specific security standards. These requirements extend procurement timelines and increase pre-commercialization costs for suppliers. Smaller vendors may face greater challenges because certification programs require sustained technical resources, specialized documentation, and continued compliance throughout product lifecycles, limiting rapid market entry despite technological capability.
Integration complexity within legacy industrial environments
Many industrial facilities continue operating control systems designed decades ago using proprietary communication protocols and customized network architectures. Integrating modern data diode solutions into these environments frequently requires protocol conversion, engineering services, application redesign, and extensive operational testing. Customers often prioritize uninterrupted production over rapid security upgrades, extending deployment schedules. Suppliers increasingly provide consulting, implementation support, and customized gateway configurations to reduce operational disruption during migration while maintaining compatibility with existing industrial assets.
Higher ownership costs compared with conventional network security
Hardware-based unidirectional gateways generally involve greater acquisition, installation, engineering, and lifecycle support costs than conventional firewalls or software segmentation tools. Organizations operating smaller industrial facilities or limited cybersecurity budgets may find investment difficult to justify when regulatory requirements remain less stringent. The total cost frequently includes specialized hardware, secure installation, protocol customization, ongoing maintenance, and operator training. Vendors are responding by expanding managed support services and scalable product portfolios, although cost remains a purchasing consideration outside highly regulated industry.
Limited customer base outside high-security environments
Data diode solutions deliver maximum value where network isolation is a regulatory or operational necessity. Commercial enterprises with lower cybersecurity risk profiles often prefer software-based segmentation because it offers greater flexibility, simpler deployment, and lower initial investment. As a result, demand remains concentrated among government, defense, utilities, energy, transportation, and other critical infrastructure sectors. Suppliers continue broadening application support and integration capabilities to expand adoption, but commercial penetration beyond high-assurance environments is likely to remain gradual during the forecast period.
Major Segment Analysis
Government and Defense
Government and defense represent the most commercially important application segment because these organizations operate classified networks, military command systems, intelligence platforms, border security infrastructure, and mission-critical communications that require deterministic protection against unauthorized inbound access. Procurement decisions emphasize certified security architecture, compliance with national cybersecurity requirements, long product support cycles, and compatibility with existing command, control, communications, computers, intelligence, surveillance, and reconnaissance (C4ISR) environments. Unlike commercial buyers, these organizations generally prioritize security assurance and operational resilience over acquisition cost.
Demand is also supported by continuing modernization of defense digital infrastructure and increased cyber resilience requirements for national security assets. Suppliers compete through evaluated products, secure manufacturing practices, protocol compatibility, and long-term maintenance capability rather than price alone. Bidirectional cybersecurity solutions continue to serve many enterprise applications, but hardware-enforced one-way communication remains an important requirement where classified information or operational continuity cannot tolerate inbound network risk. Performance within this segment therefore continues to influence technology development, certification investment, and product roadmaps across the broader data diode solution market.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
North America | Critical infrastructure cybersecurity regulations, defense modernization, utility investment | Lengthy procurement and certification processes |
Europe | NIS2 implementation, industrial cybersecurity, defense spending | Diverse national compliance requirements |
Asia Pacific | Industrial automation, power infrastructure expansion, government cyber investment | Uneven cybersecurity maturity across markets |
Middle East and Africa | Protection of energy infrastructure and national digital assets | Dependence on imported cybersecurity technologies |
North America
North America remains one of the most mature markets for data diode deployment due to extensive investment in critical infrastructure protection, defense modernization, and industrial cybersecurity. The United States continues to strengthen cybersecurity expectations for federal agencies and operators of critical infrastructure through guidance issued by agencies including the Cybersecurity and Infrastructure Security Agency (CISA) and the National Institute of Standards and Technology (NIST). Utilities, defense organizations, and industrial operators increasingly deploy hardware-enforced network isolation to protect operational technology environments from increasingly sophisticated cyber threats. Canada follows a similar direction through cybersecurity initiatives supporting energy, transportation, and public-sector resilience. Mature systems integration capabilities and an established supplier ecosystem further support regional demand.
Europe
European demand is being supported by stricter cybersecurity regulation and continued investment in protecting industrial infrastructure. The European Union's NIS2 Directive expands cybersecurity obligations across essential and important entities, encouraging operators to strengthen network architecture and risk management practices. Countries including Germany, the United Kingdom, France, and Italy continue investing in industrial cybersecurity for manufacturing, energy, transportation, and defense applications. European suppliers also benefit from long-standing expertise in high-assurance cybersecurity products. However, varying national procurement procedures and certification requirements can extend deployment timelines, particularly for cross-border projects involving government or defense customers.
Asia Pacific
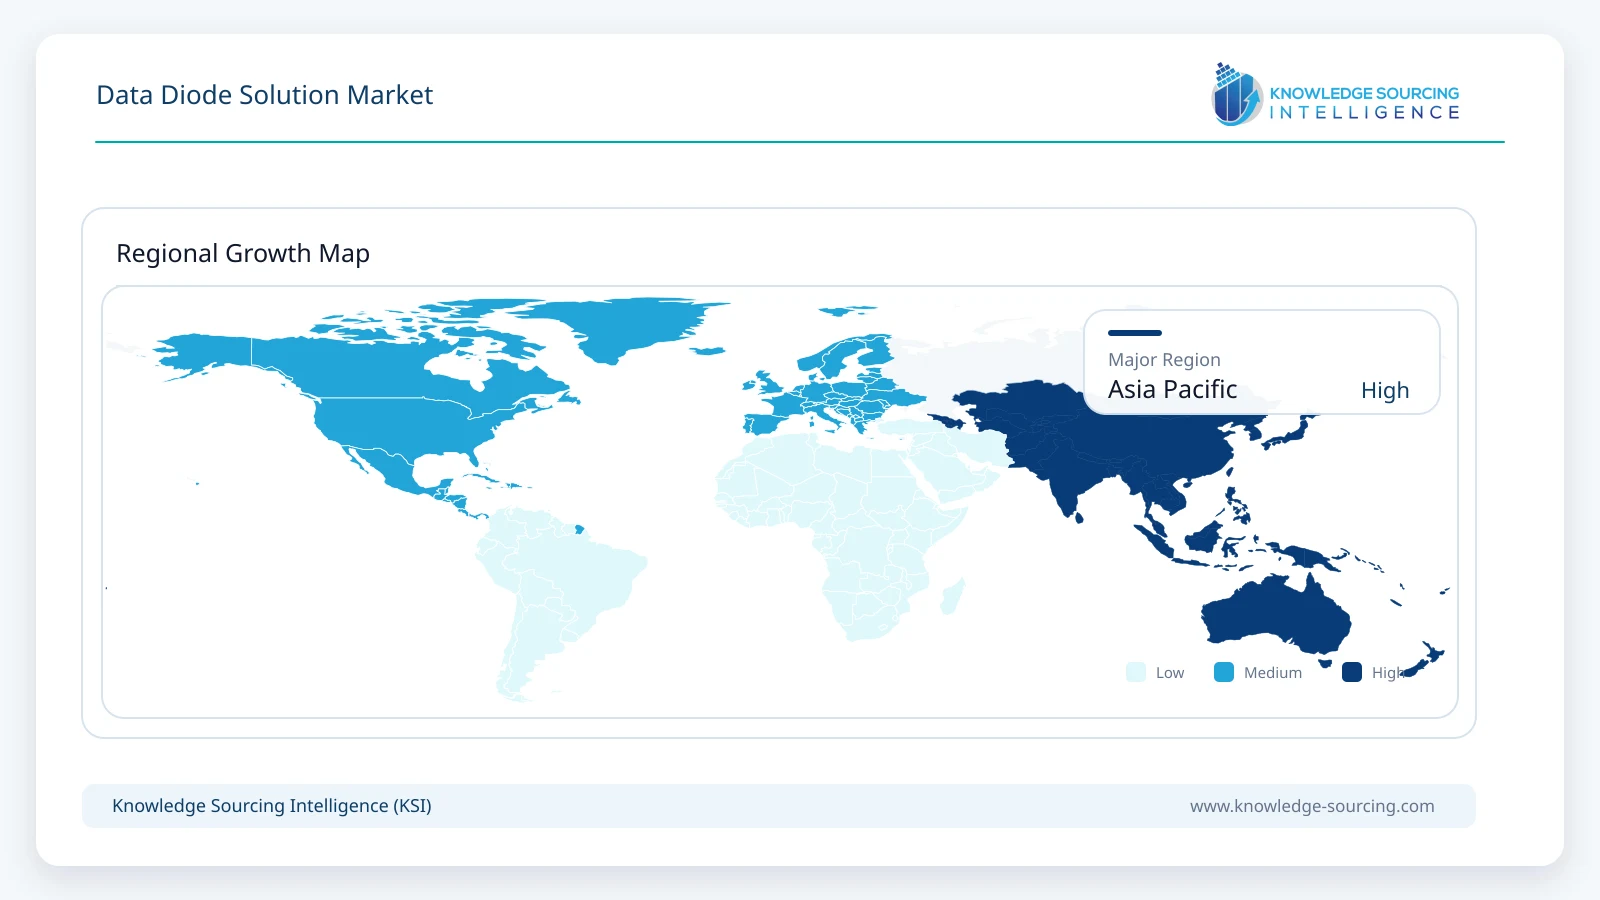
Industrial digitalization, expanding energy infrastructure, semiconductor manufacturing, and government investment in cyber resilience continue to support demand across Asia Pacific. China, Japan, South Korea, Taiwan, and India are strengthening cybersecurity capabilities for critical infrastructure while increasing investment in industrial automation and smart manufacturing. Operators are seeking secure methods of transferring operational data to enterprise environments without exposing production networks to external threats. Domestic cybersecurity capabilities continue to expand, although international suppliers remain important for specialized hardware security technologies. Differences in regulatory maturity and procurement standards across the region create varying adoption rates between developed and emerging economies.
Middle East and Africa
Protection of national energy infrastructure remains the primary demand driver across the Middle East and Africa. Oil and gas facilities, electricity networks, desalination plants, ports, and government organizations increasingly require stronger operational technology security because cyber incidents can directly affect economic activity and essential public services. Countries such as Saudi Arabia and the United Arab Emirates continue implementing national cybersecurity strategies while expanding investment in digital infrastructure. Adoption remains constrained by reliance on imported high-assurance cybersecurity products, specialized technical expertise, and relatively smaller local manufacturing ecosystems compared with North America and Europe.
Competitive Landscape
The data diode solution market is characterized by a relatively specialized competitive structure in which technological credibility, security certification, and long-term customer relationships carry greater weight than price competition. Companies including BAE Systems, ST Engineering, Advenica, Owl Cyber Defense, Waterfall Security Solutions, Belden Inc., Fox-IT (NCC Group), Deep Secure, INFODAS GmbH, genua GmbH, and OPSWAT Inc. primarily compete through secure hardware architecture, industrial protocol compatibility, systems integration expertise, and lifecycle support.
Competitive differentiation increasingly depends on compliance with government procurement requirements, interoperability with industrial control systems, and the ability to support complex operational technology environments. Vendors are expanding managed security services, centralized administration platforms, and protocol support while strengthening partnerships with industrial automation providers and system integrators. High qualification requirements, customer switching costs, specialized engineering expertise, and extensive certification processes continue to create meaningful barriers for new entrants, particularly within government, defense, and critical infrastructure applications.
Recent Developments
May 2026: Owl Cyber Defense launched the Incident Response Diode (IRD). The pocket-sized protocol filtering data diode enables hardware-enforced, one-way forensic evidence collection from compromised endpoints, helping incident response teams securely transfer data without creating return attack paths.
February 2026: Owl Cyber Defense announced U.S. Government validation of its Talon Torrent Protocol Filtering Diode. The verification confirmed the 100 Gbps hardware-enforced one-way transfer platform meets stringent protocol filtering requirements for defense and critical infrastructure deployments.
November 2025: BAE Systems announced securing over £27 billion in orders during 2025 so far, providing visibility for long-term growth. This substantial order intake signals an expansion of capacity and a supportive market for its defense and electronic systems, including high-assurance products.
October 2025: ST Engineering announced strong contract wins totaling $4.9 billion for 3Q2025, with new contracts secured for its Digital Systems and Cyber business. The wins reflect sustained market momentum and capacity expansion for its advanced cybersecurity systems, including high-assurance data diode solutions.
Regulatory and Policy Environment
Cybersecurity regulation continues to shape purchasing priorities across the data diode solution market because many end users operate regulated or nationally important infrastructure. In the United States, guidance from NIST and CISA encourages organizations to strengthen network segmentation, protect industrial control systems, and improve resilience against increasingly sophisticated cyber threats. While these frameworks do not prescribe specific technologies, hardware-enforced one-way communication aligns with recommended security architectures for high-consequence environments.
Within Europe, implementation of the NIS2 Directive expands cybersecurity obligations for operators of essential entities. Organizations are expected to strengthen governance, incident reporting, supply chain security, and operational resilience. These requirements encourage investment in technologies that reduce cyber exposure across operational technology environments while supporting compliance objectives.
National defense procurement standards, export control requirements, secure product evaluation programs, and industrial cybersecurity standards also influence supplier competitiveness. Vendors increasingly invest in independent product certification, secure development practices, vulnerability management, and long-term software support because procurement agencies frequently evaluate lifecycle assurance alongside technical performance. Regulatory expectations are therefore raising entry barriers while encouraging sustained investment in product quality and compliance capabilities.
Outlook and Strategic Implications
Demand during the 2026–2031 forecast period is expected to remain concentrated within sectors where operational disruption creates high financial, safety, or national security consequences. Critical infrastructure modernization, defense digitalization, stricter cybersecurity regulation, and broader adoption of operational technology security frameworks are likely to sustain investment in hardware-enforced one-way communication solutions. Commercial expansion beyond these sectors will depend largely on lower implementation costs, simplified integration with legacy industrial systems, and broader awareness of deterministic network protection.
Several strategic implications are expected to influence market participants:
Suppliers: Continued investment in protocol compatibility, product certification, managed services, and industrial systems integration will remain important competitive differentiators.
Critical infrastructure operators: Procurement decisions are likely to prioritize lifecycle support, regulatory compliance, and interoperability alongside cybersecurity performance.
System integrators: Demand for implementation, engineering, migration, and maintenance services should increase as industrial operators modernize legacy operational technology environments.
Policymakers and regulators: Continued emphasis on cyber resilience and infrastructure protection is expected to strengthen adoption of high-assurance security architectures across regulated sectors.
Although software-based security controls will remain important across enterprise environments, hardware-enforced data diode solutions are expected to retain a distinct position wherever inbound network communication presents unacceptable operational or security risk. The competitive environment will therefore continue to reward suppliers capable of combining certified security technologies with strong industrial integration capabilities and long-term customer support.
Data Diode Solution Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 861.9 million |
| Total Market Size in 2031 | USD 1,480.1 million |
| Forecast Unit | Million |
| Growth Rate | 11.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Application, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
- Non-Ruggedized Data Diode
- Ruggedized Data Diode
By Application
- Government and Defense
- Energy and Utilities
- Oil and Gas
- Critical Infrastructure
- Manufacturing
- Transportation
- BFSI
- Healthcare
- Others
By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Others
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Middle East and Africa
- Saudi Arabia
- UAE
- Asia Pacific
- Japan
- China
- India
- South Korea
- Taiwan
- Thailand
- Indonesia
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits to the Stakeholder
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Processes
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
4.5. Analyst View
5. DATA DIODE SOLUTION MARKET BY TYPE
5.1. Introduction
5.2. Non-Ruggedized Data Diode
5.2.1. Market Trends and Opportunities
5.2.2. Growth Prospects
5.2.3. Geographic Lucrativeness
5.3. Ruggedized Data Diode
5.3.1. Market Trends and Opportunities
5.3.2. Growth Prospects
5.3.3. Geographic Lucrativeness
6. DATA DIODE SOLUTION MARKET BY APPLICATION
6.1. Introduction
6.2. Government and Defense
6.2.1. Market Trends and Opportunities
6.2.2. Growth Prospects
6.2.3. Geographic Lucrativeness
6.3. Energy and Utilities
6.3.1. Market Trends and Opportunities
6.3.2. Growth Prospects
6.3.3. Geographic Lucrativeness
6.4. Oil and Gas
6.4.1. Market Trends and Opportunities
6.4.2. Growth Prospects
6.4.3. Geographic Lucrativeness
6.5. Critical Infrastructure
6.5.1. Market Trends and Opportunities
6.5.2. Growth Prospects
6.5.3. Geographic Lucrativeness
6.6. Manufacturing
6.6.1. Market Trends and Opportunities
6.6.2. Growth Prospects
6.6.3. Geographic Lucrativeness
6.7. Transportation
6.7.1. Market Trends and Opportunities
6.7.2. Growth Prospects
6.7.3. Geographic Lucrativeness
6.8. BFSI
6.8.1. Market Trends and Opportunities
6.8.2. Growth Prospects
6.8.3. Geographic Lucrativeness
6.9. Healthcare
6.9.1. Market Trends and Opportunities
6.9.2. Growth Prospects
6.9.3. Geographic Lucrativeness
6.10. Others
6.10.1. Market Trends and Opportunities
6.10.2. Growth Prospects
6.10.3. Geographic Lucrativeness
7. DATA DIODE SOLUTION MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. By Type
7.2.2. By Application
7.2.3. By Country
7.2.3.1. United States
7.2.3.1.1. Market Trends and Opportunities
7.2.3.1.2. Growth Prospects
7.2.3.2. Canada
7.2.3.2.1. Market Trends and Opportunities
7.2.3.2.2. Growth Prospects
7.2.3.3. Mexico
7.2.3.3.1. Market Trends and Opportunities
7.2.3.3.2. Growth Prospects
7.3. South America
7.3.1. By Type
7.3.2. By Application
7.3.3. By Country
7.3.3.1. Brazil
7.3.3.1.1.1. Market Trends and Opportunities
7.3.3.1.1.2. Growth Prospects
7.3.3.2. Argentina
7.3.3.2.1.1. Market Trends and Opportunities
7.3.3.2.1.2. Growth Prospects
7.3.3.3. Others
7.3.3.3.1.1. Market Trends and Opportunities
7.3.3.3.1.2. Growth Prospects
7.4. Europe
7.4.1. By Type
7.4.2. By Application
7.4.3. By Country
7.4.3.1. United Kingdom
7.4.3.1.1. Market Trends and Opportunities
7.4.3.1.2. Growth Prospects
7.4.3.2. Germany
7.4.3.2.1. Market Trends and Opportunities
7.4.3.2.2. Growth Prospects
7.4.3.3. France
7.4.3.3.1. Market Trends and Opportunities
7.4.3.3.2. Growth Prospects
7.4.3.4. Italy
7.4.3.4.1. Market Trends and Opportunities
7.4.3.4.2. Growth Prospects
7.4.3.5. Spain
7.4.3.5.1. Market Trends and Opportunities
7.4.3.5.2. Growth Prospects
7.4.3.6. Others
7.4.3.6.1. Market Trends and Opportunities
7.4.3.6.2. Growth Prospects
7.5. Middle East and Africa
7.5.1. By Type
7.5.2. By Application
7.5.3. By Country
7.5.3.1. Saudi Arabia
7.5.3.1.1. Market Trends and Opportunities
7.5.3.1.2. Growth Prospects
7.5.3.2. UAE
7.5.3.2.1. Market Trends and Opportunities
7.5.3.2.2. Growth Prospects
7.5.3.3. Others
7.5.3.3.1. Market Trends and Opportunities
7.5.3.3.2. Growth Prospects
7.6. Asia Pacific
7.6.1. By Type
7.6.2. By Application
7.6.3. By Country
7.6.3.1. Japan
7.6.3.1.1. Market Trends and Opportunities
7.6.3.1.2. Growth Prospects
7.6.3.2. China
7.6.3.2.1. Market Trends and Opportunities
7.6.3.2.2. Growth Prospects
7.6.3.3. India
7.6.3.3.1. Market Trends and Opportunities
7.6.3.3.2. Growth Prospects
7.6.3.4. South Korea
7.6.3.4.1. Market Trends and Opportunities
7.6.3.4.2. Growth Prospects
7.6.3.5. Taiwan
7.6.3.5.1. Market Trends and Opportunities
7.6.3.5.2. Growth Prospects
7.6.3.6. Thailand
7.6.3.6.1. Market Trends and Opportunities
7.6.3.6.2. Growth Prospects
7.6.3.7. Indonesia
7.6.3.7.1. Market Trends and Opportunities
7.6.3.7.2. Growth Prospects
7.6.3.8. Others
7.6.3.8.1. Market Trends and Opportunities
7.6.3.8.2. Growth Prospects
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. BAE Systems
9.2. ST Engineering
9.3. Advenica
9.4. Owl Cyber Defense
9.5. Waterfall
9.6. Belden Inc.
9.7. Fox-IT (NCC Group)
9.8. Deep Secure
9.9. INFODAS GmbH
9.10. Genua GmbH
9.11. OPSWAT Inc.





Frequently asked questions
What is the projected growth trajectory for the Data Diode Solution Market from 2026 to 2031?
The Data Diode Solution Market is forecast to grow at a robust Compound Annual Growth Rate (CAGR) of 11.4%. This growth will see the market expand from USD 861.9 million in 2026 to an estimated USD 1,480.10 million by 2031, primarily driven by increasing demand for hardware-enforced one-way communication.
Which industries are identified as the primary buyers and key application areas for Data Diode Solutions?
Government, defense, and energy organizations are the primary buyers due to stringent security mandates. The report highlights key application areas including industrial control systems, classified government networks, military platforms, power grids, and transportation systems, where network compromise can disrupt essential operations or national security.
What strategic drivers are expected to significantly influence the Data Diode Solution Market through 2031?
The Data Diode Solution Market outlook through 2031 is expected to be influenced by continued modernization of critical infrastructure and expanding cybersecurity regulations. Additionally, increasing geopolitical risk and broader adoption of Zero Trust principles across operational environments are encouraging organizations to replace purely software-based isolation with deterministic hardware security.
How are suppliers differentiating themselves and competing in the Data Diode Solution Market?
Suppliers are competing through certified security products, comprehensive protocol support, systems integration capabilities, and robust lifecycle services. Vendors are also increasingly complementing hardware offerings with centralized monitoring, logging, policy management, and managed support services to enhance operational visibility without compromising one-way communication principles.
What are the critical factors driving the increasing adoption of Data Diode Solutions, particularly in operational technology (OT) networks?
Increasing protection of operational technology (OT) networks is expanding demand, as critical infrastructure operators adopt data diodes to meet stricter cyber resilience and regulatory requirements. The integration with industrial control systems, SCADA, and Zero Trust architectures is broadening commercial applications, moving away from purely software-based isolation towards deterministic hardware security.
What key criteria primarily drive purchasing decisions for Data Diode Solutions among buyers?
Purchasing decisions are primarily driven by security assurance rather than price alone. Buyers typically evaluate compliance with national cybersecurity frameworks, protocol compatibility with existing industrial control systems, certification status, deployment complexity, long-term maintenance, and vendor support capabilities, often requiring proven performance in highly regulated operating conditions.
Cite this report
Knowledge Sourcing Intelligence. (Aug 2026). Data Diode Solution Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/data-diode-solution-market