
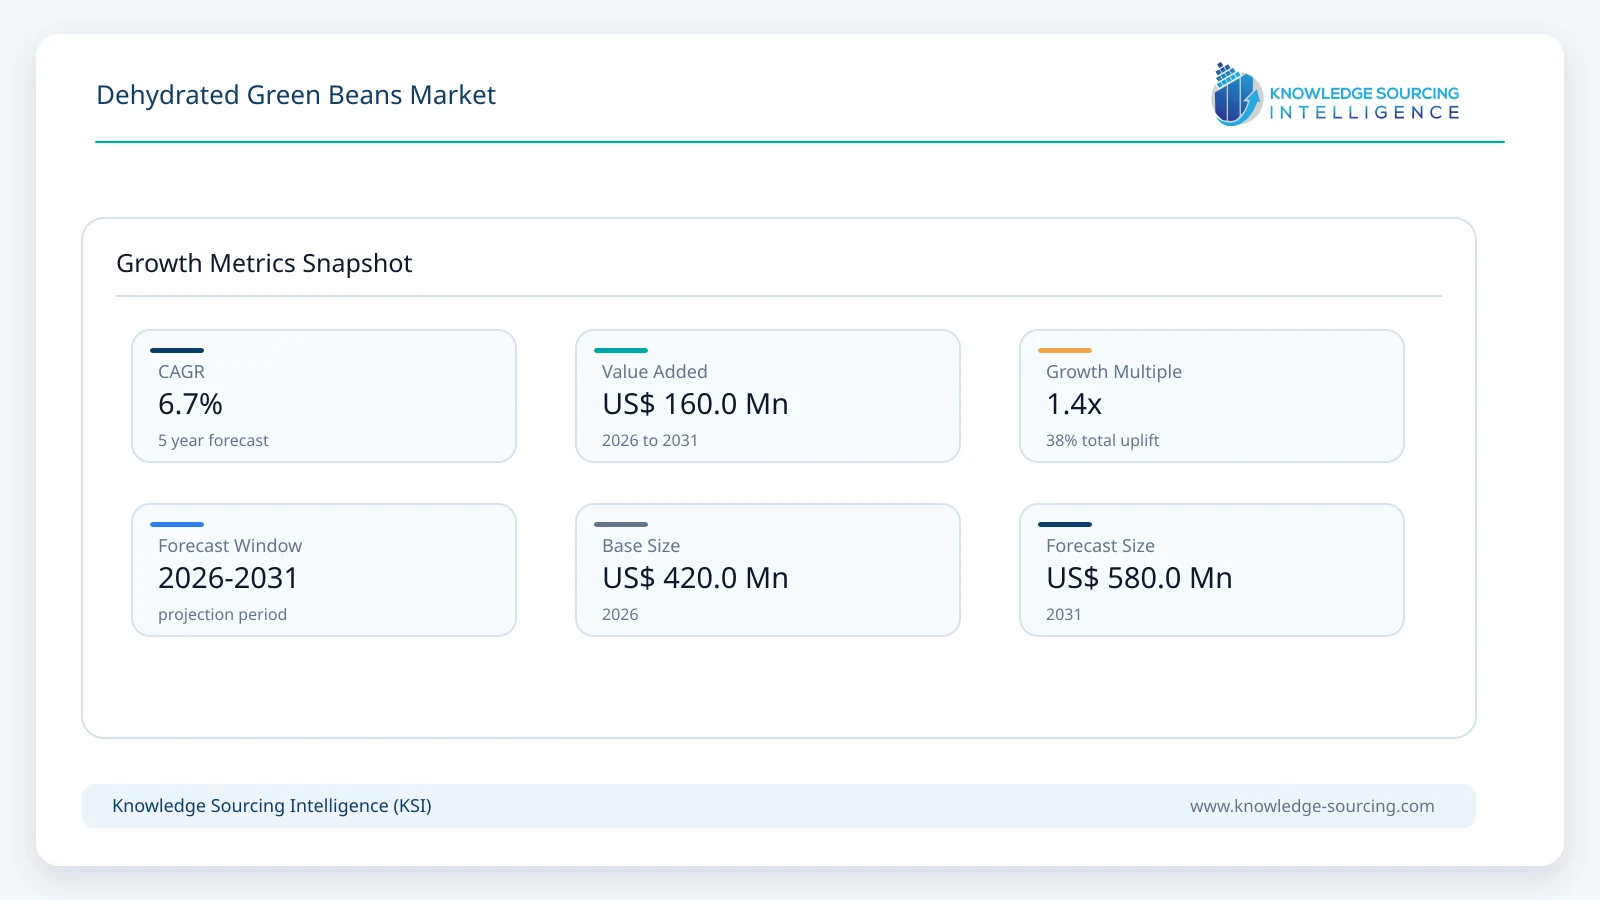
The global dehydrated green beans market is estimated at approximately USD 420.0 million in 2026 and is forecast to reach USD 580.0 million in 2031, representing a CAGR of 6.7% across the forecast period.
Highlights:
- 1Air-dried products account for approximately 62% of 2026 revenue because they serve high-volume soups, seasonings, ready meals and pet-food formulations at substantially lower cost than freeze-dried products.
- 2Cut pieces and flakes represent approximately 58% of 2026 market revenue, while powders and granules gain share in seasoning, nutrition and pet-food formulations.
- 3Soups, ready meals, sauces and seasoning systems together account for approximately 42% of market revenue.
- 4North America is estimated to represent approximately 34% of 2026 consumption value, while Asia Pacific remains the most important production and sourcing base.
- 5The revised market size is materially below legacy multi-billion-dollar estimates because dried green beans are a small specialty fraction of the roughly 23-25 million tonnes of green beans produced globally each year.
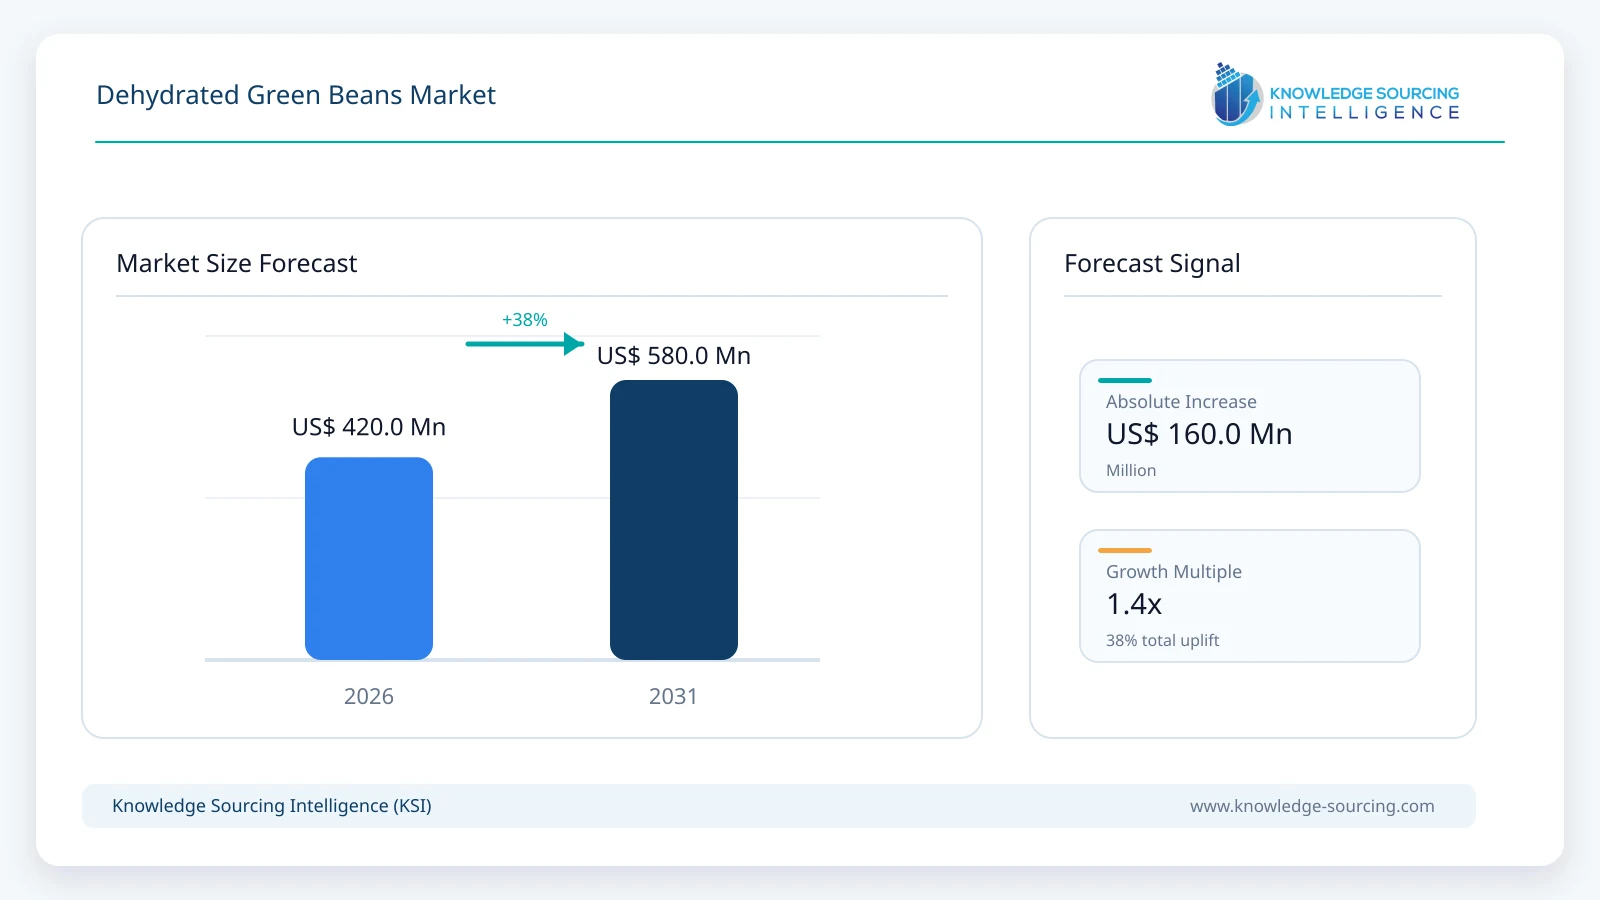
The earlier KSI value of USD 2.855 billion for 2025 implies an unusually large fraction of the global green-bean crop being diverted into dehydrated ingredients. Under a typical industrial value realization and a multi-fold fresh-to-dried weight reduction, that estimate would require several million tonnes of fresh green beans to be dehydrated each year, which is inconsistent with the niche supplier base and the dominance of fresh, frozen and canned channels. The revised estimate therefore uses a physical-volume smoke test anchored to global crop production, likely processing share, fresh-to-dried conversion and observed industrial/retail pricing.
The forecast assumes gradually improving penetration in clean-label seasonings, shelf-stable ready meals, vegetable snacks and premium freeze-dried applications. Growth accelerates modestly as manufacturers use dehydrated vegetables to reduce cold-chain exposure and simplify inventory management, but the market remains constrained by the limited size of the addressable green-bean ingredient pool and competition from frozen vegetables.
Dehydrated Green Beans Market Trends
Industrial Buyers Favor Flexible Formats
Large ingredient suppliers increasingly offer green beans as cross-cuts, granules and powders rather than only whole pieces. BCFoods supplies air-dried and freeze-dried green beans in granulated and powder formats, while Silva International offers multiple cut sizes and powder. This expands use in seasoning systems, soups, sauces, pet foods and extruded products.
Freeze Drying Captures Premium Applications
Freeze-dried green beans command a premium where color, structure and fast rehydration matter. Van Drunen Farms highlights piece identity and color retention, while BCFoods and Dehydrates Inc. offer freeze-dried options. Freeze drying remains a minority of total volume because of energy and equipment costs, but its revenue share is materially higher than its tonnage share.
Food-Safety Treatments Become a Differentiator
Industrial buyers increasingly require validated pathogen reduction and traceability. Silva offers steam sterilization, infrared treatment and off-site irradiation options and operates an FSSC 22000-certified facility. BCFoods also markets pathogen-control options. These capabilities matter especially for ready-to-eat applications and high-value nutrition products.
Sourcing Diversifies Beyond a Single Origin
China remains the dominant global producer of green beans, but commercial ingredient suppliers increasingly source from multiple regions. Silva lists China, France, Germany and Poland as raw-material origins, while BCFoods cites China, Poland and New Zealand. Multi-origin sourcing helps buyers manage crop variability, pesticide-residue requirements and logistics risk.
Dehydrated Green Beans Market Segment Analysis
By Drying Method
Air Dried
Air-dried green beans are estimated at approximately USD 260.0 million in 2026, or 62% of market revenue. Air drying offers the most economical route for soups, sauces, dry mixes, prepared meals, pet foods and seasonings where rehydration performance matters more than near-fresh appearance. Freeze drying is estimated at roughly 25% of revenue and carries a higher average selling price, while vacuum-dried and other methods account for the remaining share.
By Form
Cut Pieces and Flakes
Cut pieces and flakes are estimated at approximately USD 244.0 million in 2026, representing 58% of the market. These formats are widely used in soups, noodles, ready meals and prepared-food systems because they preserve visible vegetable identity. Powders and granules account for about 27% of revenue and are gaining share in seasonings, functional blends and pet food. Whole or snack-sized pieces account for the balance.
By Application
Soups, Ready Meals, Sauces and Seasonings
Soups, ready meals, sauces and seasoning systems are estimated at approximately USD 176.0 million in 2026, or 42% of market revenue. Silva explicitly lists soups, stews, ready meals, sauces, pasta/noodle products and snacks among applications for its dried green beans. The segment benefits from long shelf life, reduced transport weight and simple dry blending.
By Geography
North America
North America is estimated at approximately USD 143.0 million in 2026, or 34% of market consumption value. The region has a developed shelf-stable food, seasoning, snack and pet-food industry and includes major suppliers such as BCFoods, Silva International, Van Drunen Farms, Dehydrates Inc. and Harmony House.
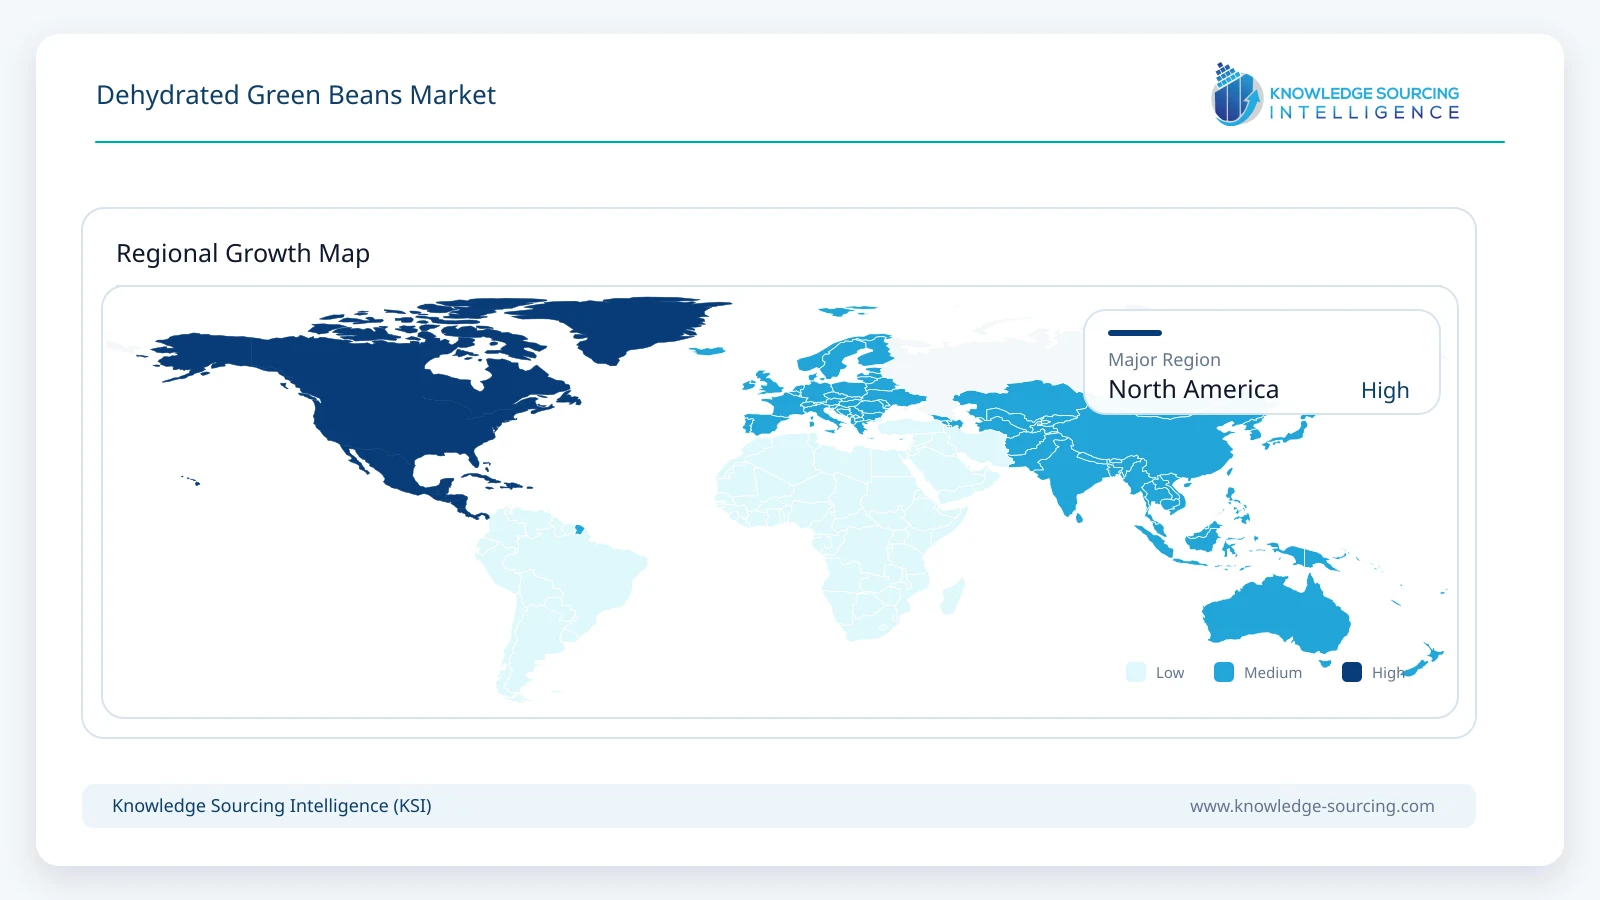
Asia Pacific is the largest production base, led by China, while Europe remains important for specialty vegetable ingredients and multi-origin sourcing.
Market Drivers
Demand for shelf-stable ingredients that reduce cold-chain and inventory requirements.
Growth in instant soups, noodles, seasoning systems, meal kits and prepared foods.
Premiumization of freeze-dried vegetable snacks and clean-label formulations.
Use of vegetable powders and granules in pet food, nutrition and savory applications.
Multi-origin sourcing and food-safety documentation requirements among large food manufacturers.
Market Restraints
High energy cost of freeze drying and vacuum drying.
Competition from frozen green beans, canned vegetables and cheaper dehydrated vegetables such as onion, carrot and cabbage.
Crop variability, pesticide-residue limits and dependence on large production bases such as China.
Loss of color, texture and flavor when lower-cost drying methods are poorly controlled.
Small addressable market relative to the total fresh green-bean crop.
Competitive Environment
Competition is fragmented across large dried-ingredient processors, regional dehydrators and specialty retail/bulk suppliers. BCFoods, Silva International and Van Drunen Farms have broad vegetable portfolios and established industrial customer bases. Dehydrates Inc. offers multiple green-bean formats and sourcing options, while Mevive International supplies dehydrated French/green beans from India. Carst & Walker now incorporates the F.R. Benson ingredient business, providing continuity for a long-standing UK dehydrated-ingredient supplier.
Supplier differentiation is based less on branded consumer recognition and more on crop sourcing, cut size, microbiological specification, organic/non-GMO options, sterilization, moisture control, color retention and the ability to deliver customized industrial specifications.
Recent Developments
2026: BCFoods continued to market green beans in both air-dried and freeze-dried formats, including granulated and powder products for industrial applications.
2026: Silva International listed multi-origin sourcing from China, France, Germany and Poland and offered steam, infrared and irradiation-based microbial-reduction options for dried green beans.
2024-2026: Carst & Walker integrated F.R. Benson & Partners into its UK ingredient business, maintaining a portfolio that includes dehydrated vegetables and other savoury ingredients.
2026: Mevive International continued commercial supply of air-dried dehydrated French/green beans in India and export markets, including 25 kg industrial packaging.
Market Outlook
The dehydrated green beans market should grow steadily rather than explosively. Air-dried ingredients will remain the volume base, while freeze-dried products capture higher-value snack, nutrition and premium prepared-food applications. Growth will be strongest where manufacturers value shelf life, lower transport weight and reduced cold-chain dependence. However, the market remains a niche within the broader dehydrated-vegetable industry, and future estimates should continue to be checked against physical crop availability rather than extrapolated from generic dehydrated-food CAGR assumptions.
Dehydrated Green Beans Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 420.0 million |
| Total Market Size in 2031 | USD 580.0 million |
| Forecast Unit | Million |
| Growth Rate | 6.7% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Drying Method, Form, Application, Geography |
| Companies |
|
Market Segmentation
By Drying Method
Air Dried
Freeze Dried
Vacuum Dried and Others
By Form
Cut Pieces and Flakes
Powder and Granules
Whole and Snack Pieces
By Application
Soups, Ready Meals, Sauces and Seasonings
Snacks and Savories
Infant and Nutrition Products
Pet Food
Others
By Geography
North America
South America
Europe
Middle East and Africa
Asia Pacific
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition and Scope
1.3. Currency and Assumptions
2. RESEARCH METHODOLOGY
2.1. Secondary Research
2.2. Primary Validation
2.3. Market Estimation and Physical-Volume Triangulation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
4. MARKET DYNAMICS
4.1. Drivers
4.2. Restraints
4.3. Opportunities
5. DEHYDRATED GREEN BEANS MARKET BY DRYING METHOD
5.1. Air Dried
5.2. Freeze Dried
5.3. Vacuum Dried and Others
6. DEHYDRATED GREEN BEANS MARKET BY FORM
6.1. Cut Pieces and Flakes
6.2. Powder and Granules
6.3. Whole and Snack Pieces
7. DEHYDRATED GREEN BEANS MARKET BY APPLICATION
7.1. Soups, Ready Meals, Sauces and Seasonings
7.2. Snacks and Savories
7.3. Infant and Nutrition Products
7.4. Pet Food
7.5. Others
8. DEHYDRATED GREEN BEANS MARKET BY GEOGRAPHY
8.1. North America
8.2. South America
8.3. Europe
8.4. Middle East and Africa
8.5. Asia Pacific
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Supplier Positioning
9.2. Product and Processing Capability
9.3. Sourcing and Food-Safety Differentiation
10. COMPANY PROFILES
10.1. BCFoods, Inc.
10.2. Silva International, Inc.
10.3. Van Drunen Farms
10.4. Dehydrates Inc.
10.5. Mevive International Food Ingredients
10.6. Harmony House Foods, Inc.
10.7. Carst & Walker / F.R. Benson
10.8. Suszarnia Warzyw Jaworski S.A.
10.9. Elchais Food Solutions
10.10. Tarege Trade House
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Abbreviations
Navigate
Trusted by the world's leading organizations











