
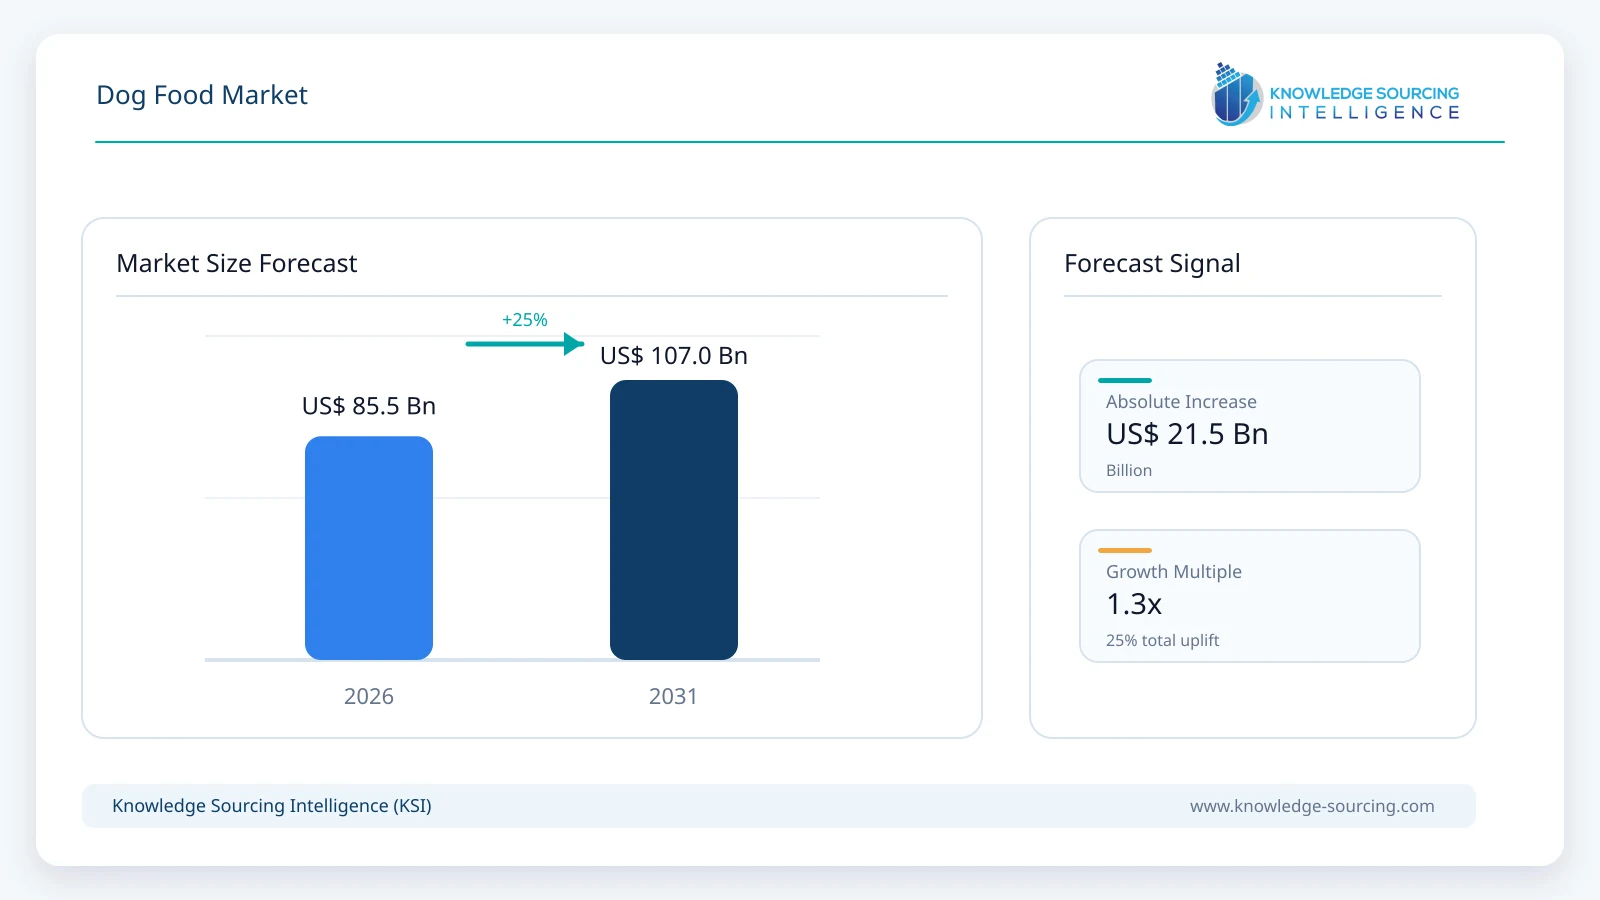
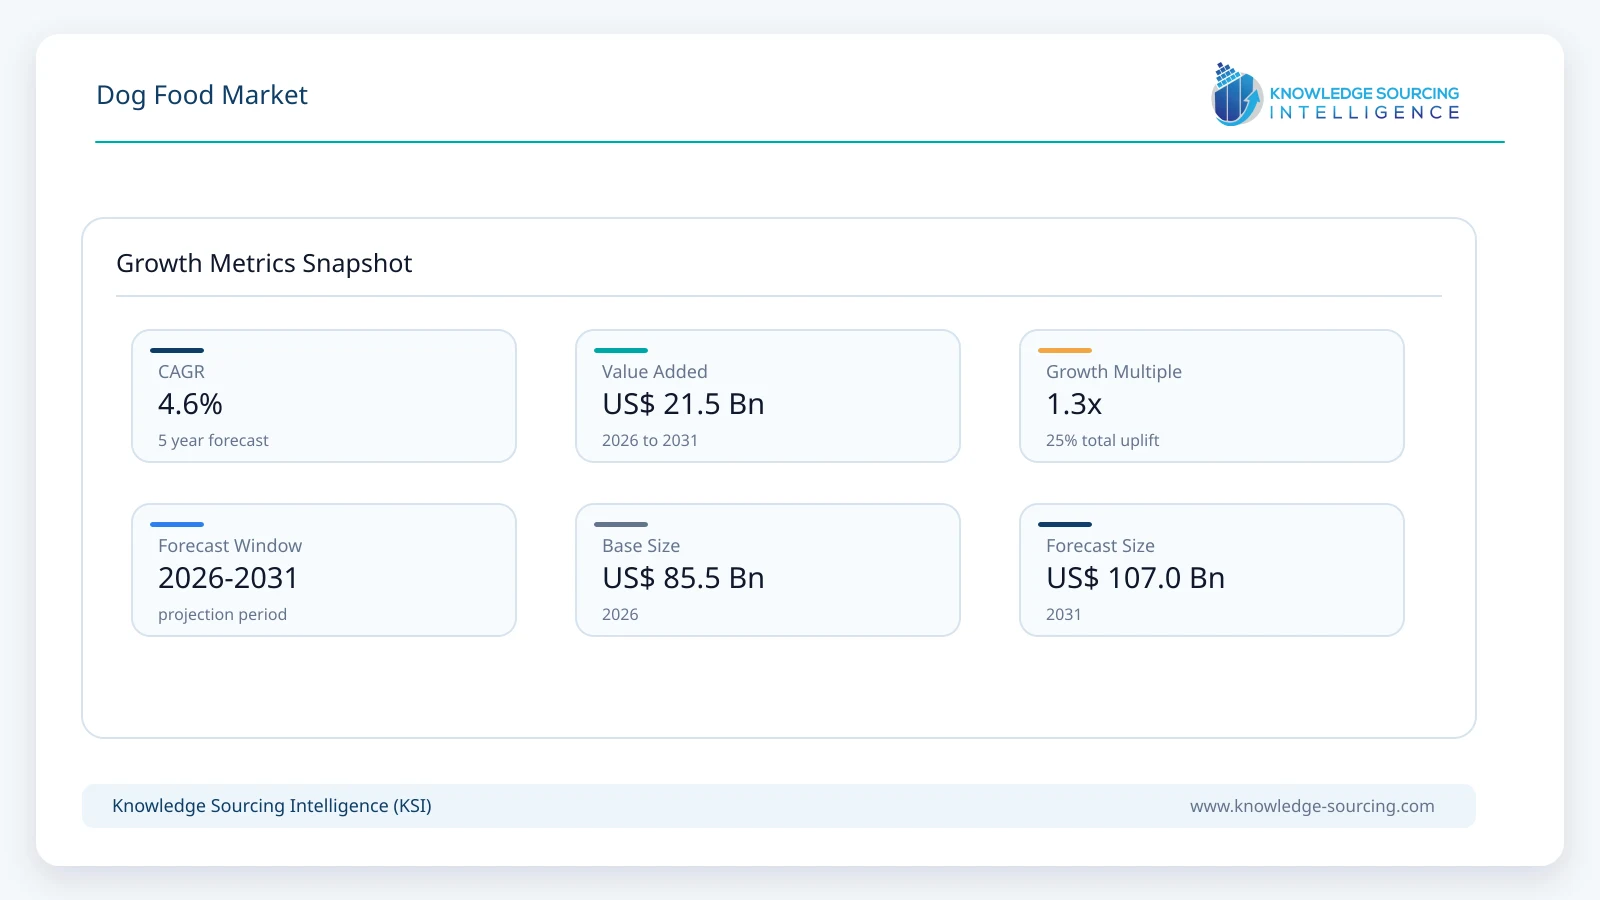
The global dog food market is projected to expand at a CAGR of 4.6%, reaching USD 107.0 billion in 2031 from USD 85.5 billion in 2026.
Highlights:
- 1Dry and kibble products account for approximately 54% of global dog food revenue in 2026.
- 2Adult-dog nutrition generates about 60% of global dog food market value in 2026.
- 3Premium dog food is projected to grow at approximately 5.8% annually through 2031.
- 4Online channels account for roughly 32% of global dog food sales value in 2026.
- 5North America represents approximately 39% of global dog food revenue in 2026.
- 6Fresh, therapeutic and functional formats are capturing value even as mainstream dry-food volumes soften.
Market Overview
Dog food demand spans dry kibble, wet food, semi-moist products and rapidly expanding fresh, frozen and freeze-dried formats. Mainstream dry food remains the largest revenue pool because of its affordability, storage convenience and broad retail distribution, but faster growth is occurring in higher-value products positioned around fresh ingredients, digestive health, weight management, allergies, mobility and breed- or life-stage-specific nutrition. Veterinary diets are also becoming a more important commercial segment as owners seek clinically supported products for chronic health conditions.
The market is highly branded but fragmented below the leading global suppliers. Mars Petcare and Nestlé Purina maintain broad portfolios across mainstream, premium and therapeutic categories, while Hill's has a strong veterinarian-led position. General Mills competes through Blue Buffalo, Edgard & Cooper and Tiki Pets and has moved directly into fresh dog food through Love Made Fresh. Freshpet is scaling refrigerated distribution and reported 30,721 retail locations at the end of June 2026. Post Consumer Brands remains significant in value-oriented dry dog food through Nutrish and Kibbles 'n Bits, although its 2026 results show that mainstream dry-dog volumes can be sensitive to consumer value and pricing.
Market Trends
Fresh and minimally processed dog food is moving into mainstream retail
Fresh dog food is one of the clearest value-growth areas in the category. Freshpet reported second-quarter 2026 net sales of USD 305.6 million, up 15.5%, and estimates that fresh could become a USD 10 billion category over time. General Mills launched Blue Buffalo Love Made Fresh as a major strategic entry into the same subcategory, allowing consumers to use fresh food either as a complete meal or alongside kibble. The format appeals to owners who associate refrigeration, recognizable ingredients, and shorter processing with higher nutritional quality. Fresh products remain more expensive and operationally complex than dry food, but their faster growth is increasing refrigerated space, manufacturing investment, and competitive attention.
Therapeutic and condition-specific diets are widening beyond traditional dry formulas
Veterinary and functional nutrition are becoming more sophisticated as companies develop products for gastrointestinal sensitivity, allergies, mobility, renal health, weight management and other chronic conditions. In July 2026, Royal Canin launched its first fresh therapeutic diet portfolio for dogs in the United States, available through veterinarians and designed for gastrointestinal needs, food sensitivities, and reduced appetite. Hill's reported 2025 growth in therapeutic and wellness categories, while Virbac and Farmina continue to compete in veterinary and condition-specific nutrition. This expands the premium end of the market and strengthens veterinarian influence over product selection.
Market Drivers
Recurring consumption from a large installed dog population supports a stable demand base
Dog food benefits from a recurring purchasing model because households buy nutrition throughout the life of the animal. Mature regions already contain very large dog populations, while commercial pet-food penetration is still rising in parts of Asia, Latin America and the Middle East. FEDIAF's 2026 reporting shows that nearly half of European households own at least one pet, supporting a large recurring food market even where dog-population growth is moderate. In emerging markets, higher urbanization, smaller households and greater awareness of complete commercial nutrition are shifting feeding away from household leftovers toward packaged food. This supports steady category growth even when individual formats experience short-term volume pressure.
Premiumization and health-focused feeding increase spending per dog
The second major driver is the increase in average spending per animal. Owners are purchasing premium kibble, fresh food, toppers, functional treats, and therapeutic diets that carry higher revenue per serving than conventional dry food. Freshpet's household penetration and buy-rate growth, Blue Buffalo's expansion into fresh food, and Royal Canin's launch of fresh therapeutic diets all point to the same underlying shift. The strongest value growth therefore occurs where companies can combine trusted brands, nutritional evidence and convenient formats rather than relying only on basic calorie delivery. Premiumization also allows suppliers to grow revenue in mature markets where total dog numbers are relatively stable.
Market Restraint
Affordability pressure limits premium conversion and weighs on mainstream dry volumes
The main restraint is household affordability. Protein, grain, packaging, freight and manufacturing costs can raise retail prices, while pet owners must balance food spending against veterinary care and other household expenses. General Mills reported mid-single-digit declines in dog-food net sales during parts of fiscal 2026 despite investment behind Blue Buffalo, while Post Consumer Brands reported a 4.0% decline in dry dog-food category consumption during its fiscal second quarter. Premium and fresh formats can continue growing, but wider adoption depends on whether consumers perceive a clear health or convenience benefit relative to the price premium. This keeps value-oriented dry food relevant and makes pricing discipline important across the market.
Segment Analysis
By Product Type - Dry and Kibble
Dry and kibble remain the largest product type and are projected to generate approximately USD 56.2 billion by 2031. The format benefits from long shelf life, easy storage, broad retail availability, and lower feeding cost per day than most wet or fresh alternatives. It also supports a wide range of price points, from economy food to premium high-protein and breed-specific formulas. However, recent U.S. company disclosures show that mainstream dry dog food is not uniformly expanding by volume. Growth increasingly depends on premium recipes, functional claims, and mixing with fresh or wet formats rather than simple unit expansion. Fresh, frozen and refrigerated products remain smaller but grow faster from a low base.
By Life Stage - Adult Dogs
Adult-dog nutrition is projected to reach approximately USD 63.5 billion by 2031. This remains the largest life-stage pool because adulthood covers the longest feeding period and includes mainstream maintenance, active-dog, indoor, weight-control, digestive and breed-specific products. Puppy food is smaller but typically carries higher nutrient density and premium positioning, while senior diets are expanding around joint health, cognitive support, weight management and digestibility.
By Price Positioning - Premium
Premium dog food is projected to account for approximately 42% of global market value by 2031. The segment includes high-meat-content kibble, fresh food, freeze-dried products, therapeutic diets, and formulas supported by stronger ingredient or nutritional claims. Premium growth is faster than the total market because it captures higher spending per dog and benefits from owners treating pets more like family members. Mars, Purina, Hill's, Blue Buffalo, Freshpet, Farmina, and other suppliers are investing heavily in this space. Economy products remain important in price-sensitive households, while mid-range food continues to represent the broadest mainstream volume pool.
By Distribution Channel - Online
Online dog food sales are projected to grow at approximately 6.4% annually between 2026 and 2031. Dog food is well suited to e-commerce because it is purchased repeatedly, can be subscribed to and is relatively inconvenient to carry in large bags. Digital channels also support specialized diets that may not have broad shelf distribution, and fresh-food brands can use direct delivery or click-and-collect to reach customers beyond traditional pet stores. Offline remains the larger channel through 2031 because supermarkets, mass merchants, pet specialty stores and veterinary clinics retain strong purchasing frequency and immediate product availability.
By Geography - North America
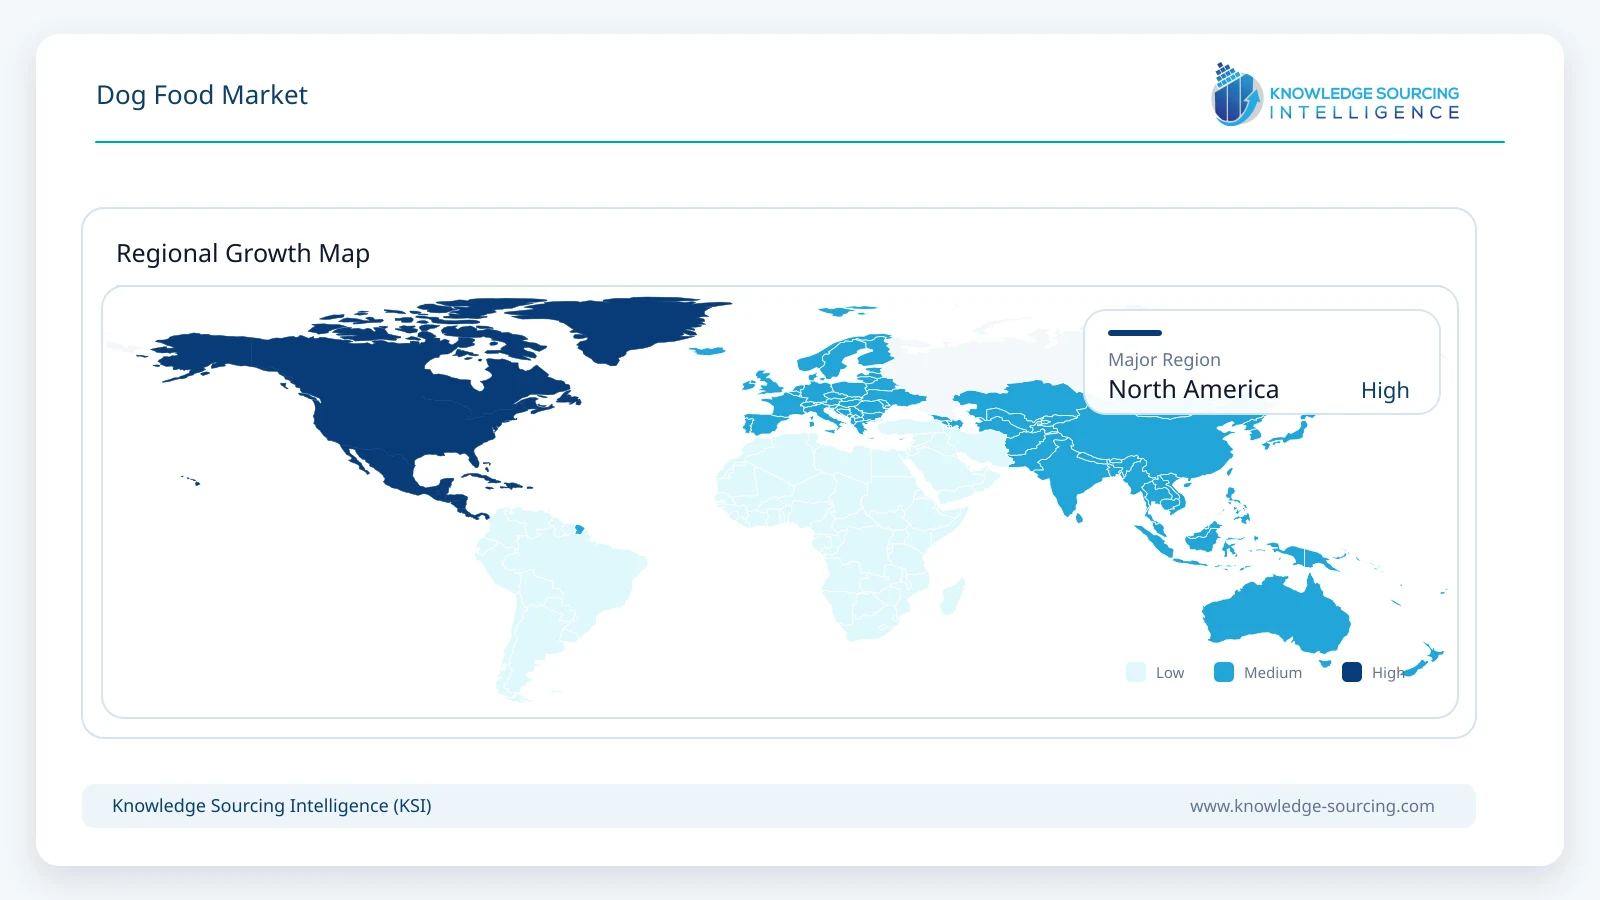
North America is projected to generate approximately USD 40.1 billion in dog food revenue by 2031. The region has a large installed dog population, high commercial-food penetration, and one of the deepest premium and therapeutic markets globally. Freshpet estimates the U.S. dog food and treats category at about USD 38 billion in 2026, while General Mills, Mars, Purina, Hill's and Post all maintain substantial regional positions. Europe is another large premium market, while Asia Pacific offers faster percentage growth from rising commercial-feed penetration, urban pet ownership and expanding local production.
Competitive Environment
Mars Petcare and Nestlé Purina are the broadest global competitors, spanning mass-market, premium, and veterinary nutrition. Hill's Pet Nutrition is especially strong in therapeutic and veterinarian-recommended products, while General Mills has expanded its premium position through Blue Buffalo, Edgard & Cooper and Tiki Pets. Freshpet is the most visible scaled specialist in refrigerated fresh dog food, while Post Consumer Brands competes in mainstream dry food through Nutrish and Kibbles 'n Bits. Regional and specialist suppliers including Farmina, Partner in Pet Food, Affinity Petcare, United Petfood, VAFO, Deuerer and Wellness Pet Company add competitive depth across Europe and premium niches.
Competitive advantage increasingly depends on brand trust, nutritional science, format innovation, supply-chain scale and omnichannel access. Fresh and therapeutic products require different manufacturing and distribution capabilities from dry kibble, creating room for specialists as well as large packaged-food companies. At the same time, affordability remains important in mainstream dry food, so suppliers must balance premium innovation with consumer value. This creates a market in which companies can grow through mix and share gains even when overall category volumes are relatively stable.
Recent Developments
July 2026: Royal Canin launched its first fresh therapeutic diet portfolio for dogs in the United States, available through veterinarians.
May 2026: Mars Petcare and Big Idea Ventures launched the 2026 Next Generation Pet Food Program with stronger emphasis on Asia and sustainable nutrition innovation.
May 2026: Freshpet reported first-quarter sales growth of 13.1% and raised its 2026 net-sales outlook as fresh pet food continued gaining household penetration.
April 2026: Post Consumer Brands launched a new Rachael Ray Nutrish campaign alongside a broader brand relaunch intended to strengthen mainstream pet-food performance.
March 2026: Nestlé Purina opened a CHF 370 million wet pet-food factory in Brazil to support regional growth and export demand.
Dog Food Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 85.5 billion |
| Total Market Size in 2031 | USD 107.0 billion |
| Forecast Unit | Billion |
| Growth Rate | 4.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Life Stage, Price Positioning, Distribution Channel |
| Companies |
|
Market Segmentation
By Product Type
Dry / Kibble
Wet Food
Semi-Moist Food
Fresh, Frozen and Freeze-Dried Food
By Life Stage
Puppy
Adult
Senior
By Price Positioning
Economy
Mid-Range
Premium
By Distribution Channel
Online
Offline
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Recurring Consumption from a Large Installed Dog Population Supports a Stable Demand Base
3.1.2. Premiumization and Health-Focused Feeding Increase Spending per Dog
3.2. Market Restraint
3.2.1. Affordability Pressure Limits Premium Conversion and Weighs on Mainstream Dry Volumes
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Fresh and Refrigerated Nutrition
4.2. Therapeutic and Functional Diets
4.3. Alternative Proteins and Sustainable Ingredients
5. DOG FOOD MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Dry / Kibble
5.3. Wet Food
5.4. Semi-Moist Food
5.5. Fresh, Frozen and Freeze-Dried Food
6. DOG FOOD MARKET BY LIFE STAGE
6.1. Introduction
6.2. Puppy
6.3. Adult
6.4. Senior
7. DOG FOOD MARKET BY PRICE POSITIONING
7.1. Introduction
7.2. Economy
7.3. Mid-Range
7.4. Premium
8. DOG FOOD MARKET BY DISTRIBUTION CHANNEL
8.1. Introduction
8.2. Online
8.3. Offline
9. DOG FOOD MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. USA
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. France
9.4.3. United Kingdom
9.4.4. Spain
9.4.5. Italy
9.4.6. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. South Africa
9.5.4. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. India
9.6.3. Japan
9.6.4. South Korea
9.6.5. Indonesia
9.6.6. Thailand
9.6.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Mars Petcare
11.2. Nestlé Purina PetCare
11.3. Hill's Pet Nutrition
11.4. General Mills, Inc.
11.5. Freshpet, Inc.
11.6. Post Consumer Brands
11.7. Diamond Pet Foods
11.8. Simmons Pet Food
11.9. Agrolimen
11.10. Farmina Pet Foods
11.11. Wellness Pet Company
11.12. Partner in Pet Food
11.13. United Petfood
11.14. VAFO Group
11.15. Deuerer
11.16. Virbac
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations
Navigate
Trusted by the world's leading organizations











