
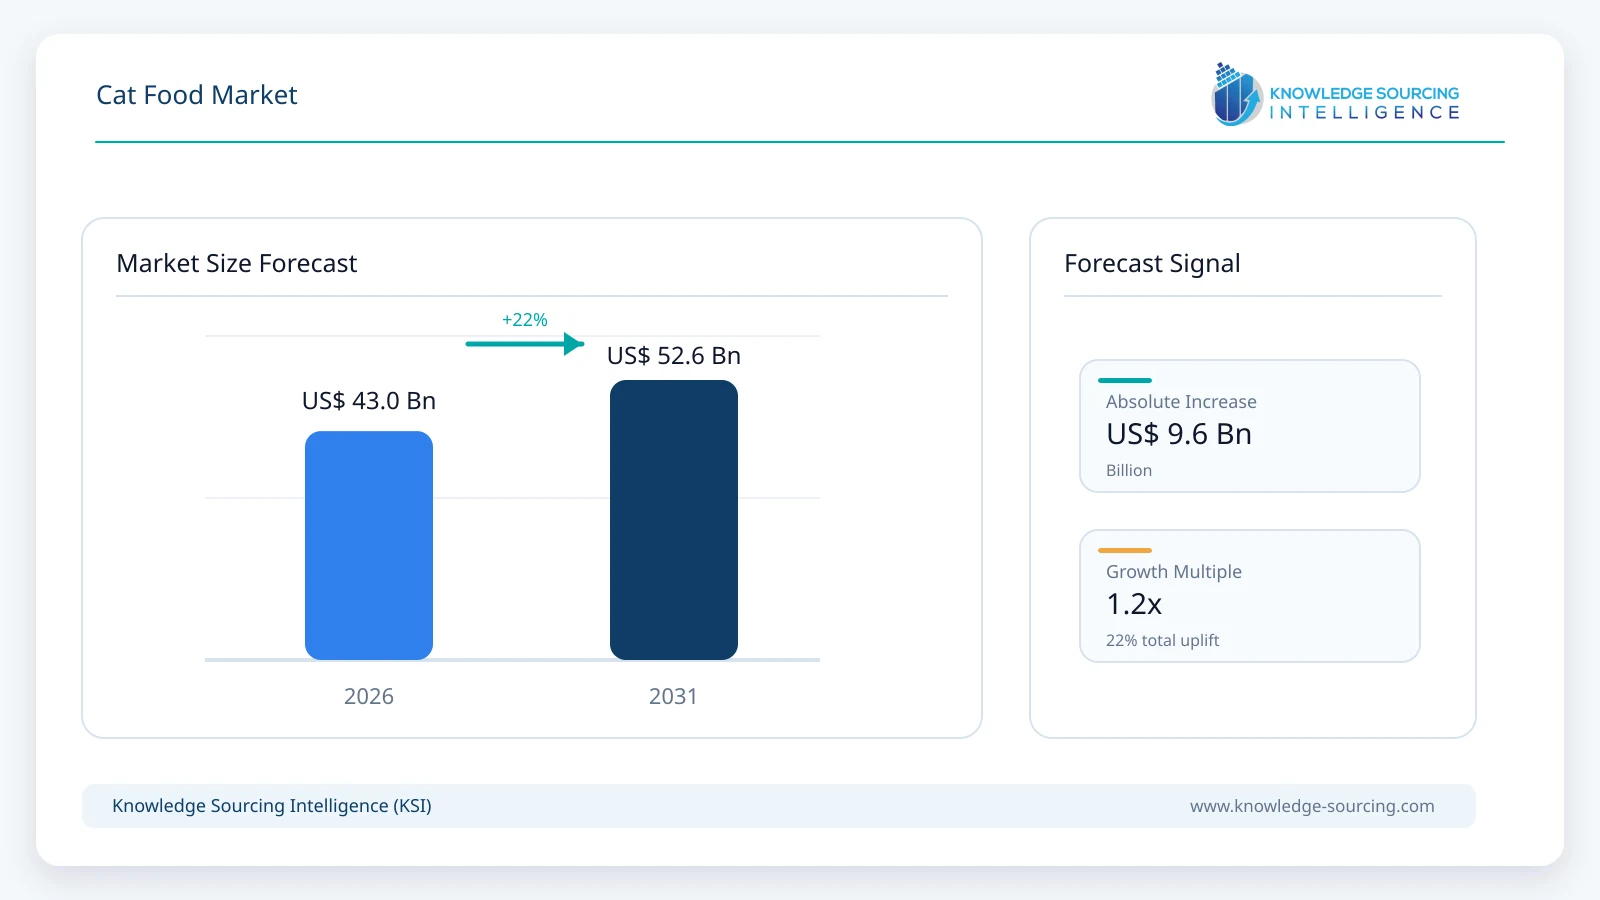
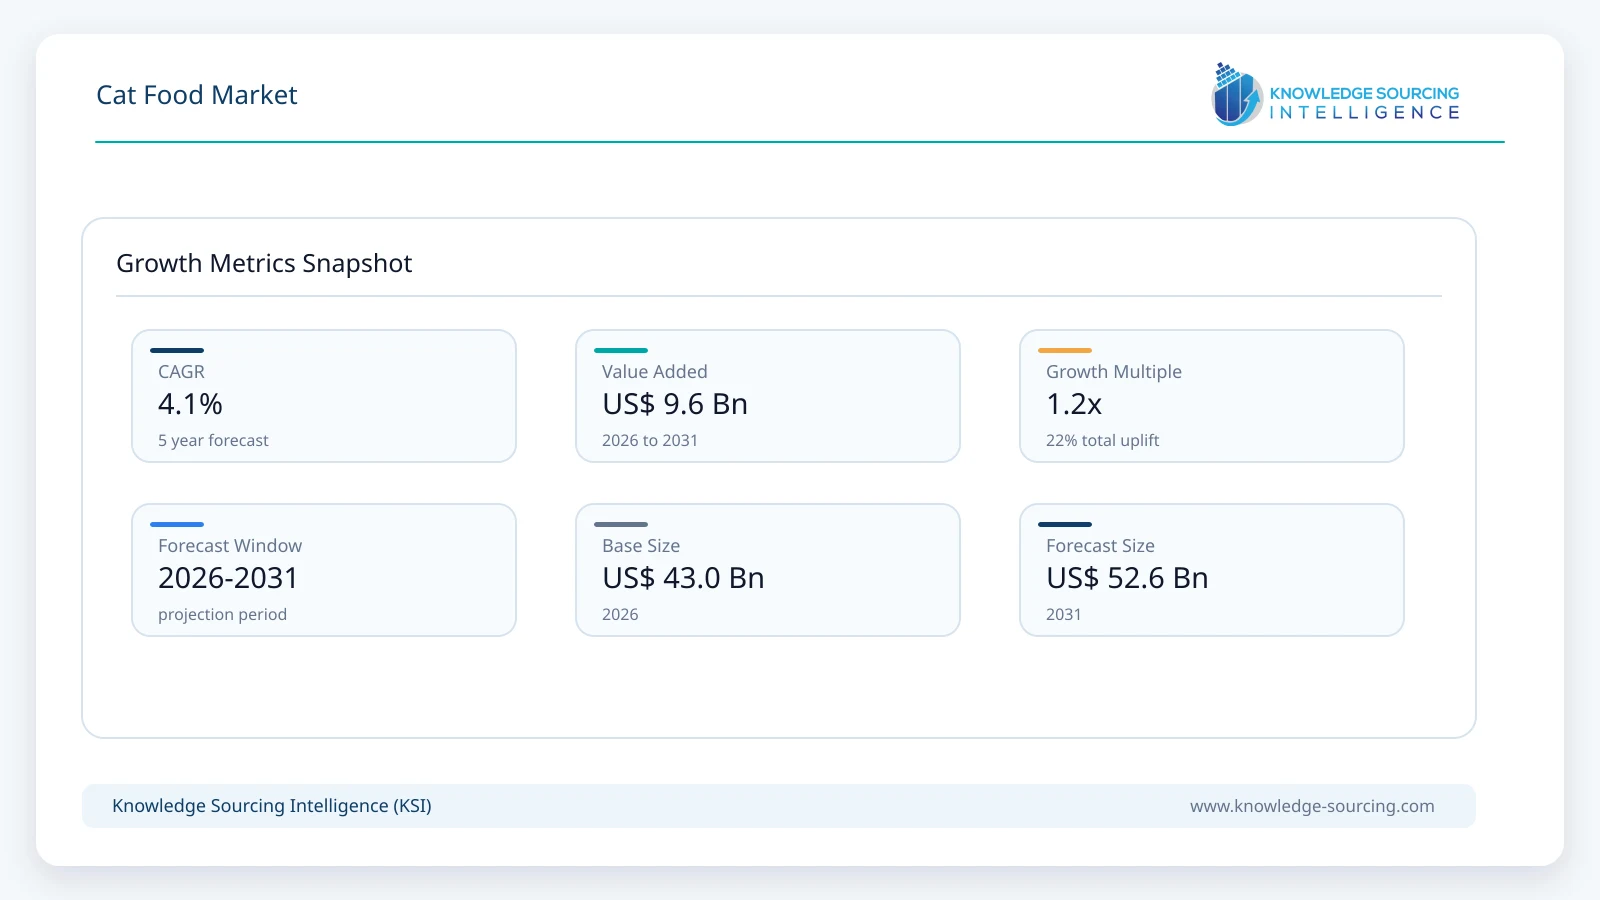
The global cat food market is expected to expand at a CAGR of 4.1%, rising from USD 43.0 billion in 2026 to USD 52.6 billion in 2031.
Highlights:
- 1Wet cat food accounts for approximately 47% of global market revenue in 2026.
- 2Adult-cat nutrition generates about USD 27.1 billion of market revenue in 2026.
- 3Premium cat food is projected to grow at approximately 5.6% annually through 2031.
- 4Online channels account for roughly 31% of global cat food sales value in 2026.
- 5Europe represents approximately 32% of global cat food revenue in 2026.
- 6Therapeutic, urinary-health and functional nutrition are increasing value per kilogram across mature markets.
Market Overview
Cat nutrition is segmented across kitten, adult and senior life stages, reflecting meaningful differences in energy density, protein requirements, digestive support and age-related health needs. Product demand spans wet food, dry or kibble, semi-moist products and frozen or freeze-dried formats, with wet food benefiting from hydration and palatability while dry food retains advantages in convenience and cost per serving. Price positioning remains commercially important because premium and therapeutic products command materially higher unit values than mainstream diets, while distribution continues shifting toward e-commerce, subscription purchasing and veterinarian-linked direct channels.
The market is led by scaled multinational pet-care companies but remains competitive across premium specialists and regional manufacturers. Nestlé's PetCare category represented 20.6% of group sales in 2025, while Hill's Pet Nutrition generated USD 4.61 billion in 2025 sales, up 2.9%, with growth led by therapeutic and wellness categories. General Mills continues to invest behind Blue Buffalo and Tiki Pets, while Post Consumer Brands has expanded its North American pet-food portfolio through brands including 9Lives and Nutrish. Competition is therefore concentrated at the top but remains broad across premium nutrition, therapeutic diets, wet-food specialists, and regional brands.
Market Trends
Wet and super-premium cat food are receiving disproportionate manufacturing investment
Wet cat food is attracting significant capital because it combines high palatability, hydration benefits and premium price points with strong consumer acceptance. Purina announced a CHF 520 million integrated wet pet-food plant in Mantova, Italy in July 2026 that will produce super-premium wet cat and dog food, and in September 2026 Nestlé announced a further CHF 157 million expansion in Thailand for brands including Felix, Friskies, Pro Plan and Purina One. Purina also opened a CHF 370 million wet pet-food facility in Brazil in March 2026. These investments suggest that wet food is becoming a central growth platform across both mature and emerging markets rather than merely a format alternative to kibble.
Functional and therapeutic nutrition is moving deeper into mainstream cat feeding
Cat nutrition is becoming more condition-specific as owners seek products addressing urinary health, digestion, weight management, skin and coat, renal support and age-related needs. Nestlé continues to invest behind Purina Pro Plan Veterinary Diets and direct-to-consumer veterinary channels, while Hill's reported 2025 growth in therapeutic and wellness categories. Premium specialists such as Farmina offer feline ranges organized around life stage and specific health needs, including urinary, digestion and weight-management formulas. This shift raises average selling prices and strengthens veterinarian influence over purchasing, particularly among older cats and animals with chronic conditions.
Market Drivers
A large and stable global cat population supports recurring food demand
Cat food benefits from a recurring consumption model because owners purchase food throughout the life of the animal, making the installed pet population more important than annual adoption alone. FEDIAF reports approximately 111 million cats across Europe, while UK Pet Food estimates about 13 million cats in the United Kingdom in 2026. Mature markets therefore have a substantial recurring consumption base even when pet ownership growth slows. Emerging markets add incremental upside as commercial pet-food penetration increases and households shift from table scraps or mixed feeding toward complete packaged diets. The combination of recurring consumption and improving commercial-feed penetration supports relatively stable market growth through economic cycles.
Premiumization and health-focused feeding raise spending per cat
Owners are increasingly willing to pay more for products positioned around ingredient quality, palatability, veterinary support, life stage and specific health outcomes. Purina's 2026 relaunch of Gourmet Perle across nearly 30 European markets specifically targets super-premium wet cat food, while Hill's continues to grow therapeutic and wellness nutrition. Premiumization is particularly important because cat populations in several mature countries are not expanding fast enough to support high volume growth on their own. Higher-value wet food, freeze-dried toppers, veterinary diets and functional formulations therefore increase revenue per animal and allow suppliers to grow value even in comparatively stable pet populations.
Market Restraint
Protein, packaging and manufacturing costs constrain affordability in mainstream segments
Cat food formulations rely heavily on animal proteins, fats, grains, vitamins, minerals and packaging materials that can experience substantial cost volatility. Wet food is especially exposed because retort pouches, cans, trays and high-moisture processing create higher manufacturing and logistics costs than dry kibble. Premium and therapeutic categories can absorb more pricing, but mainstream consumers may trade down, reduce treat purchases or shift between brands when price gaps widen. Manufacturers therefore face a balancing act between maintaining nutritional quality and protecting affordability, particularly in emerging markets and lower-income households where commercial pet-food penetration is still developing.
Segment Analysis
By Product Type - Wet Cat Food
Wet cat food is projected to reach approximately USD 25.3 billion by 2031. The segment benefits from strong feline palatability, higher moisture content, portioned packaging and the ability to support premium textures and functional formulations. Purina's recent manufacturing investments in Italy, Brazil and Thailand are heavily oriented toward wet pet food, while Nestlé's 2025 results identified wet cat food as a key U.S. PetCare growth driver. Wet food also lends itself to super-premium differentiation through mousse, gravy, flakes and single-serve formats. Dry kibble remains essential because it is economical, convenient and easy to store, but wet food is contributing a larger share of incremental market value because its average selling price per kilogram is higher.
By Life Stage - Adult Cats
Adult cats remain the largest life-stage segment and are projected to grow at approximately 3.8% annually between 2026 and 2031. The category spans maintenance diets, indoor formulas, weight-control products, hairball management and breed- or lifestyle-specific nutrition. Adult cats represent the largest installed population because this life stage covers several years of recurring consumption, giving manufacturers a broad base for both mainstream and premium product lines. Kitten nutrition is smaller but benefits from higher nutrient-density requirements, while senior nutrition grows faster from a lower base as cats live longer and age-related health needs increase.
By Price Positioning - Premium
Premium cat food is projected to account for approximately 43% of global market value by 2031. Growth is being supported by super-premium wet food, natural and limited-ingredient diets, veterinary nutrition and formulations that address specific health conditions. Premium products typically carry higher meat content, stronger claims around ingredient quality or science-backed nutrition and more sophisticated packaging. Nestlé's investment in super-premium wet food and Hill's growth in therapeutic and wellness products illustrate why this part of the market is expanding faster than economy food. The mid-range segment remains the largest volume pool, particularly in mainstream retail, but premium products capture a disproportionate share of revenue growth.
By Distribution Channel - Online
Online cat food sales are projected to reach approximately USD 18.1 billion by 2031. E-commerce is well suited to recurring pet-food purchases because subscriptions, automatic replenishment and saved-product preferences reduce shopping friction, while heavy bags and multipacks can be delivered directly to the home. Veterinary diets are also moving online through approved direct-to-consumer platforms; Nestlé reports double-digit growth for its Vet Direct channel in North America. Offline retail remains the larger channel overall because supermarkets, pet specialty stores and veterinary clinics provide immediate availability and product discovery, but online is taking share as consumers become more comfortable purchasing recurring nutrition digitally.
By Geography - Europe
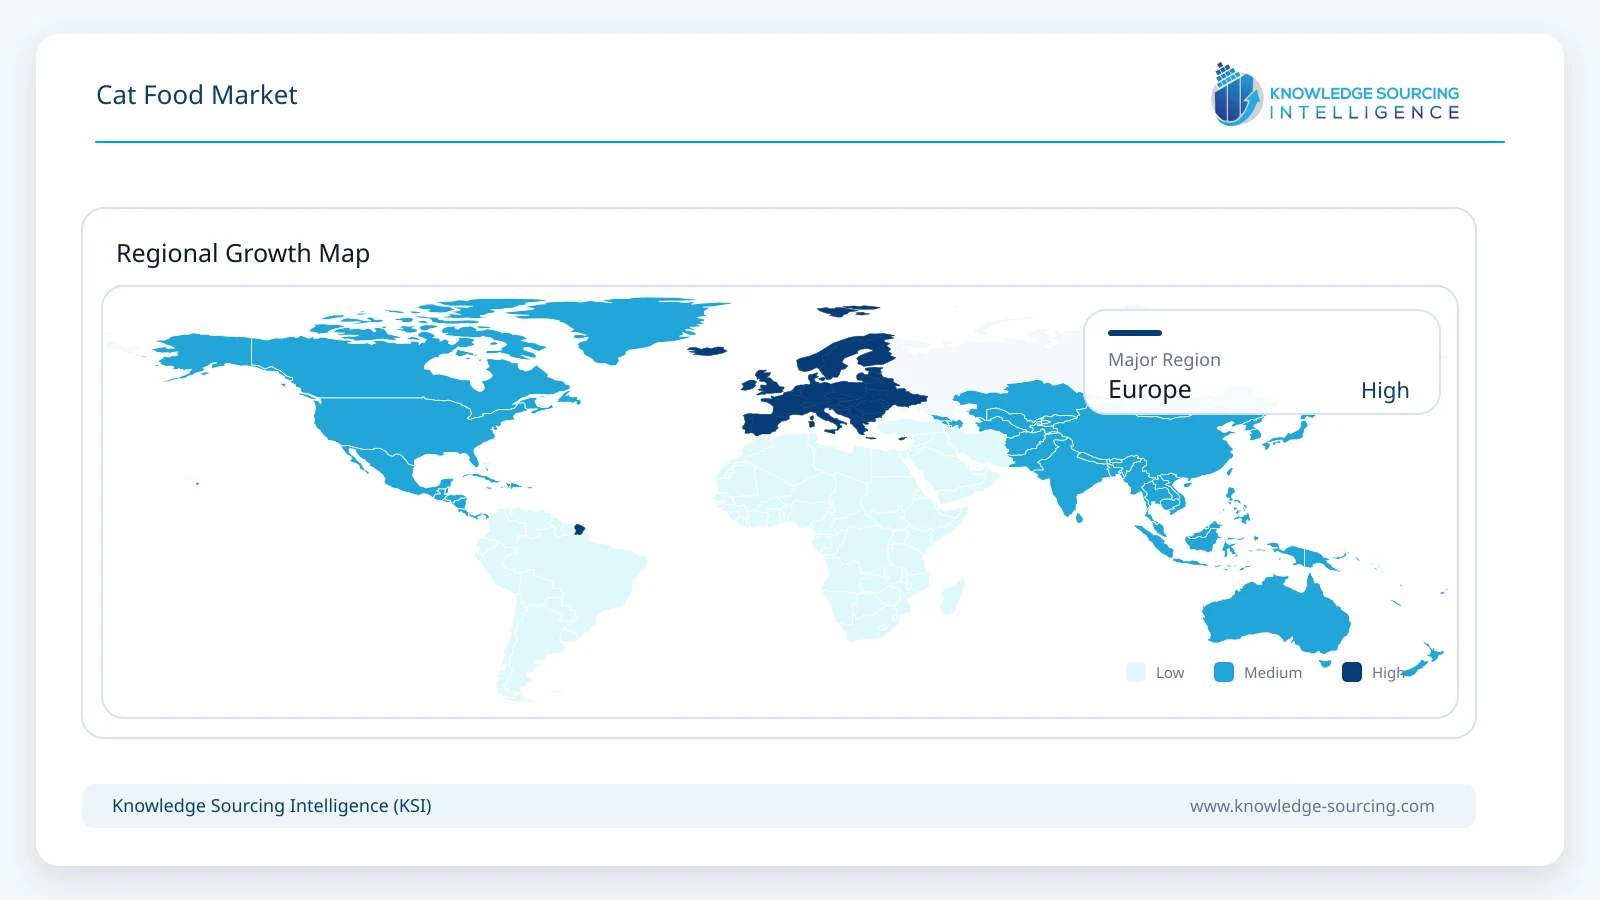
Europe is projected to reach approximately USD 16.5 billion in cat food revenue by 2031. The region combines a very large installed cat population with high commercial pet-food penetration, strong wet-food consumption and premium brand development. FEDIAF reports approximately 111 million cats across Europe, while Purina's 2026 Italian capacity announcement highlights the strategic importance of the European wet-food market. North America remains another high-value market, particularly for premium dry, wet and therapeutic nutrition, while Asia Pacific offers faster growth from increasing pet ownership, urbanization and improving commercial-feed penetration in China, Southeast Asia and parts of South Asia.
Competitive Environment
The market is led by Mars Petcare and Nestlé Purina, followed by Hill's Pet Nutrition, General Mills and a diverse group of premium and regional players. Mars competes across mainstream, premium and veterinary nutrition, while Nestlé Purina combines large-scale manufacturing with brands spanning economy, mainstream, premium and therapeutic segments. Hill's is especially strong in veterinarian-recommended and therapeutic nutrition. General Mills has expanded its premium pet portfolio through Blue Buffalo, Tiki Pets and other brands, while Post Consumer Brands has become more relevant in mainstream North American cat food after acquiring 9Lives, Nutrish and related pet-food assets from J.M. Smucker.
Competition is increasingly based on brand trust, formulation science, wet-food capability, veterinary relationships, digital commerce and regional manufacturing. Premium specialists such as Farmina, Affinity Petcare, Wellness Pet Company and Instinct compete on ingredient quality and targeted nutrition, while private-label and contract manufacturers remain important in value segments. Capacity investments are strategically significant because wet-food production requires more capital-intensive processing and packaging than dry kibble. Suppliers with strong regional wet-food capacity and established retail or veterinary distribution are therefore positioned to capture premium growth.
Recent Developments
September 2026: Nestlé announced a CHF 157 million expansion of Purina's Rayong, Thailand site for brands including Felix, Friskies, Pro Plan and Purina One.
July 2026: Nestlé Purina announced a CHF 520 million integrated plant in Mantova, Italy focused on super-premium wet pet food for cats and dogs.
June 2026: Purina Europe relaunched and expanded Gourmet Perle across nearly 30 markets, targeting the super-premium wet cat-food segment.
May 2026: Mars Petcare and Big Idea Ventures launched the 2026 Next Generation Pet Food Program with greater emphasis on Asia and sustainable nutrition innovation.
March 2026: Nestlé Purina opened a CHF 370 million wet pet-food factory in Brazil, nearly doubling its local wet-food production capacity.
Cat Food Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 43.0 billion |
| Total Market Size in 2031 | USD 52.6 billion |
| Forecast Unit | Billion |
| Growth Rate | 4.1% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Life Stage, Price Positioning, Distribution Channel |
| Companies |
|
Market Segmentation
By Product Type
Dry / Kibble
Wet Food
Semi-Moist Food
Frozen and Freeze-Dried Food
By Life Stage
Kitten
Adult
Senior
By Price Positioning
Economy
Mid-Range
Premium
By Distribution Channel
Online
Offline
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. A Large and Stable Global Cat Population Supports Recurring Food Demand
3.1.2. Premiumization and Health-Focused Feeding Raise Spending per Cat
3.2. Market Restraint
3.2.1. Protein, Packaging and Manufacturing Costs Constrain Affordability in Mainstream Segments
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Functional and Therapeutic Nutrition
4.2. Wet-Food Processing and Portion Formats
4.3. Alternative Proteins and Sustainable Ingredients
5. CAT FOOD MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Dry / Kibble
5.3. Wet Food
5.4. Semi-Moist Food
5.5. Frozen and Freeze-Dried Food
6. CAT FOOD MARKET BY LIFE STAGE
6.1. Introduction
6.2. Kitten
6.3. Adult
6.4. Senior
7. CAT FOOD MARKET BY PRICE POSITIONING
7.1. Introduction
7.2. Economy
7.3. Mid-Range
7.4. Premium
8. CAT FOOD MARKET BY DISTRIBUTION CHANNEL
8.1. Introduction
8.2. Online
8.3. Offline
9. CAT FOOD MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. USA
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. France
9.4.3. United Kingdom
9.4.4. Spain
9.4.5. Italy
9.4.6. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. South Africa
9.5.4. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. India
9.6.3. Japan
9.6.4. South Korea
9.6.5. Indonesia
9.6.6. Thailand
9.6.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Mars Petcare
11.2. Nestlé Purina PetCare
11.3. Hill's Pet Nutrition
11.4. General Mills, Inc.
11.5. Post Consumer Brands
11.6. Agrolimen
11.7. Farmina Pet Foods
11.8. Diamond Pet Foods
11.9. Deuerer
11.10. Simmons Pet Food
11.11. Wellness Pet Company
11.12. Instinct Pet Food
11.13. Virbac
11.14. i-Tail Corporation
11.15. United Petfood
11.16. VAFO Group
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES
Navigate
Trusted by the world's leading organizations











