
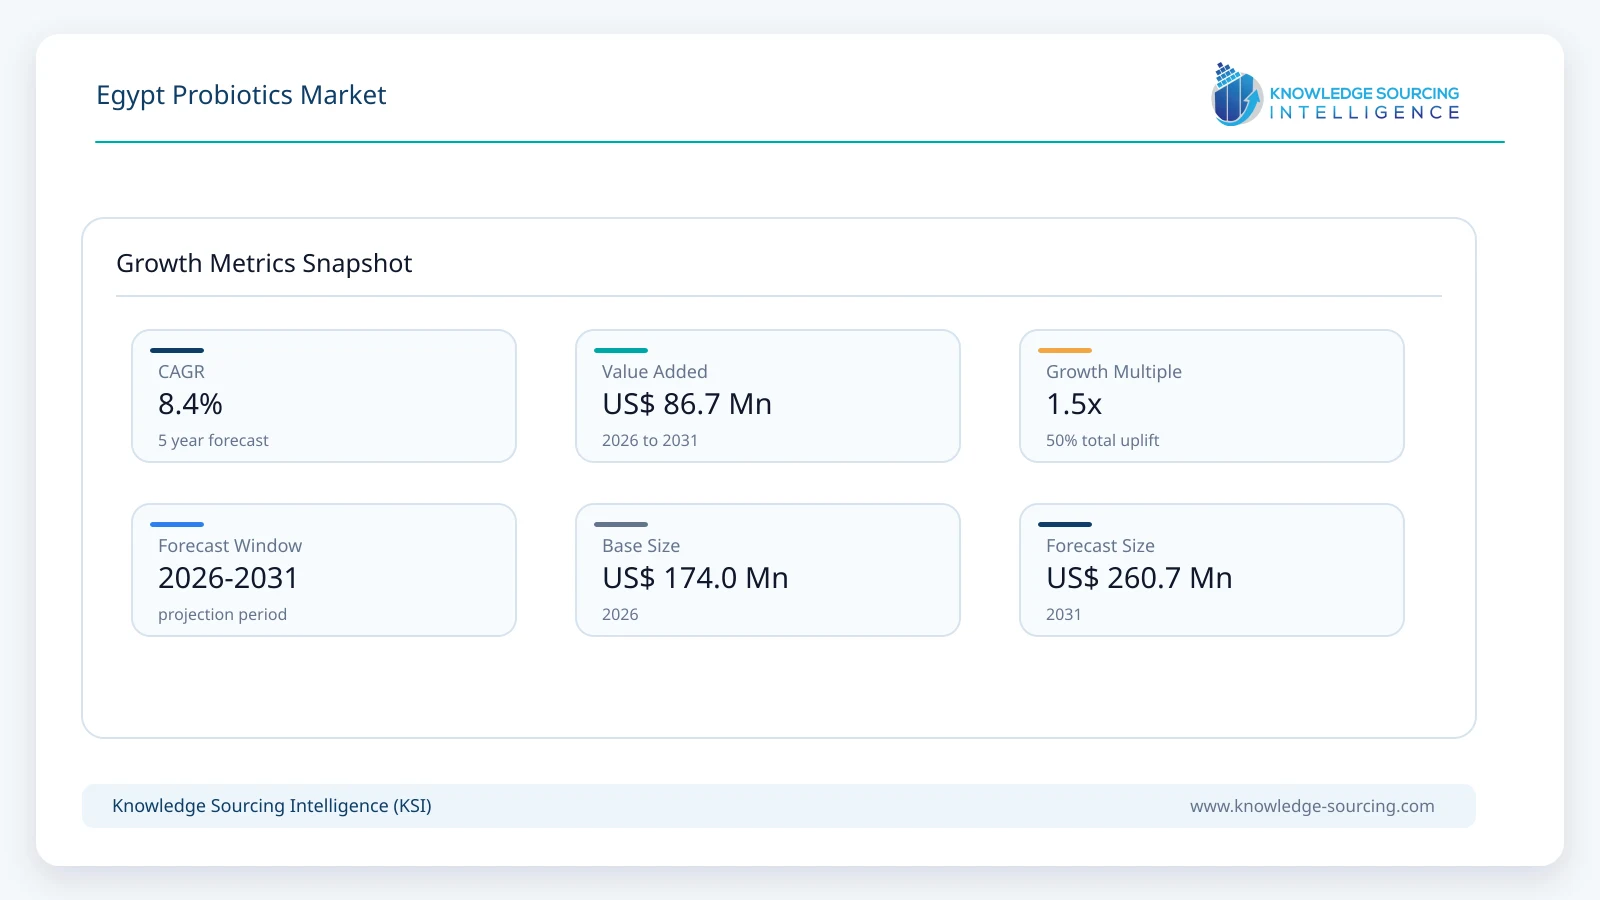
The Egypt probiotics market is forecast to grow at a CAGR of 8.42%, reaching USD 260.7 million in 2031 from USD 174.0 million in 2026.
Highlights:
- 1Egypt’s probiotics market reaches USD 260.7 million by 2031 from USD 174.0 million in 2026, reflecting an approved 8.42% CAGR.
- 2Juhayna reported 31% spoonable-yogurt and 45% drinkable-yogurt market shares in FY2025, indicating established fermented-food distribution channels.
- 3Danone Egypt committed EGP 250 million to a new production line in 2026, supporting local capacity and regional food exports.
- 4Juhayna collected more than 800 tons of milk daily through 20-plus centers across 14 Egyptian governorates in 2026.
- 5Egypt’s regulatory list sets a minimum 1.0×10? CFU level for listed probiotic food-supplement products registered through NFSA.
- 6Juhayna recorded EGP 8.6 billion revenue in first-quarter 2026, up 26%, supported by volume growth across dairy and fermented products.
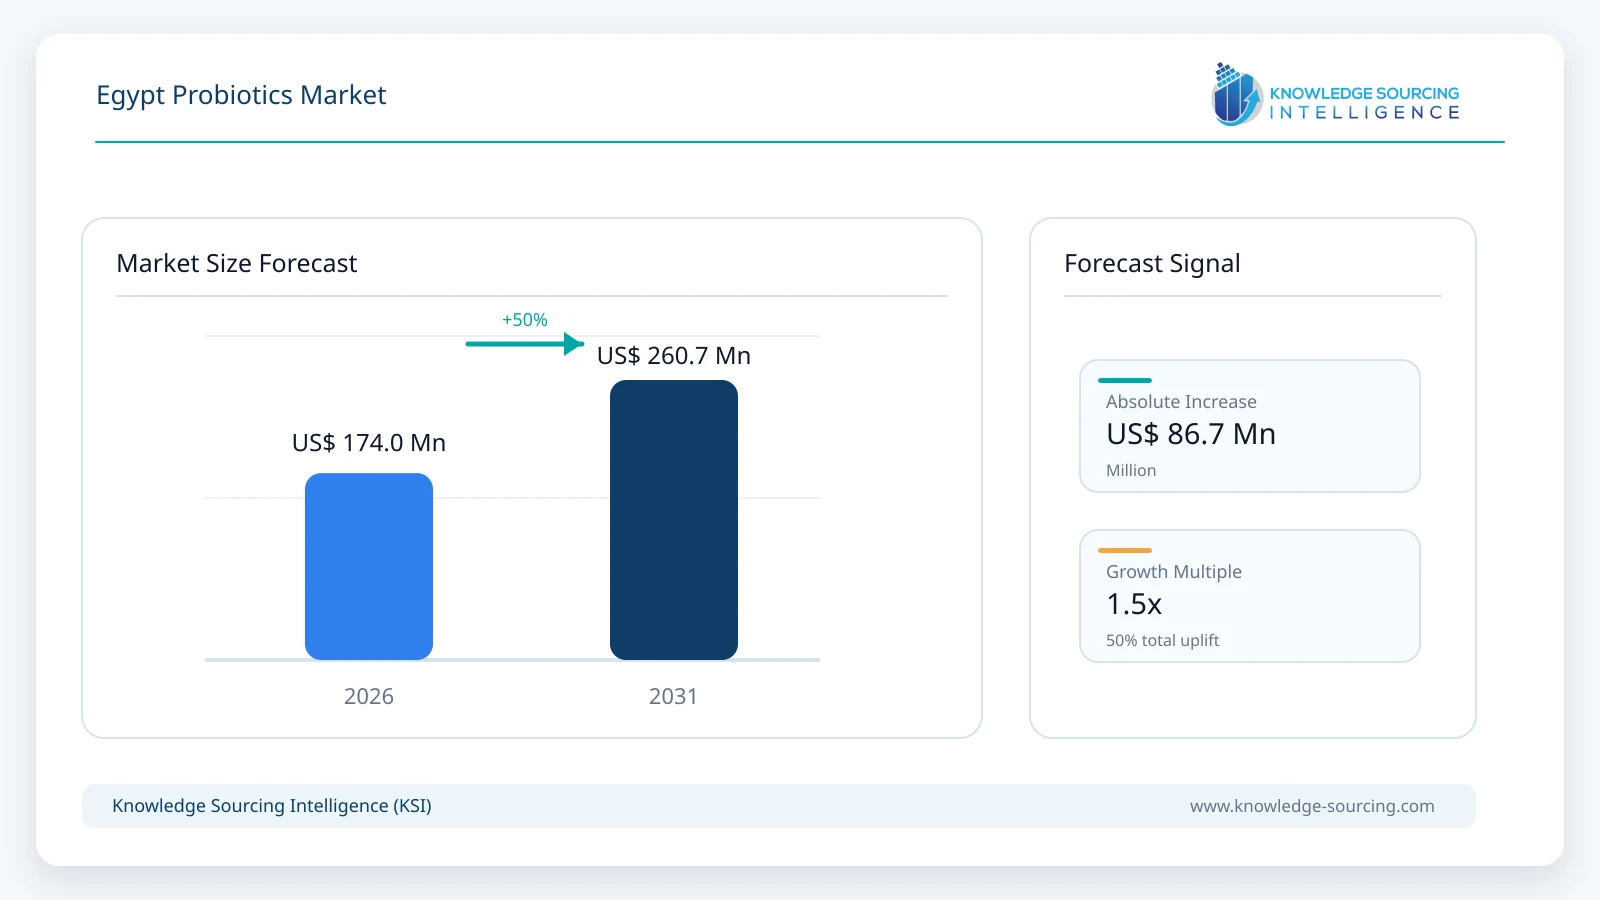
Probiotics in Egypt span fermented foods, functional beverages, dietary supplements, and animal nutrition products containing live microorganisms intended to provide health benefits. Demand is supported by established yogurt consumption, wider interest in digestive health, and expanding product formats. Commercial opportunity is concentrated around strain quality, viable counts, product stability, cold-chain execution, regulatory compliance, and affordable consumer formats.
Market Overview
Egypt’s probiotic market combines food, nutrition, pharmaceutical, and animal-feed channels rather than operating as a single product category. Yogurt and fermented dairy provide an established route for probiotic consumption, while capsules, powders, functional foods, and animal-feed products broaden the addressable customer base. Danone Egypt, for example, markets Activia yogurt containing Bifidus cultures, while its wider Egyptian portfolio includes several yogurt products using active cultures.
Growth depends less on simple category expansion than on the conversion of established dairy consumption into higher-value functional products, alongside wider use of probiotic supplements and specialized nutrition. Product developers must balance strain selection, viable-cell stability, taste, shelf life, dosage, storage, and retail economics.
Juhayna’s operating results illustrate the scale of Egypt’s established fermented-dairy channel. The company reported FY2025 revenue of approximately EGP 30 billion, up 23.5% year on year, with double-digit volume growth across its dairy, fermented, and juice businesses. Its FY2025 market-share disclosure reported 31% for spoonable yogurt and 45% for drinkable yogurt, providing an indication of the commercial importance of yogurt formats within Egypt’s broader nutrition market.
Product availability is also shaped by domestic manufacturing and distribution capability. Danone Egypt inaugurated a new production line at its Obour factory in May 2026 with an investment of EGP 250 million, intended to increase production capacity, support localization, and expand exports to Arab and African markets.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
|---|---|---|
Juhayna FY2025 revenue | EGP 30.0 billion, +23.5% | Shows strong commercial activity across Egypt’s packaged dairy, fermented-food, and juice channels. |
Spoonable yogurt market share | 31% in FY2025 | Indicates an established yogurt channel through which probiotic products can reach consumers. |
Drinkable yogurt market share | 45% in FY2025 | Highlights the scale of portable fermented formats and their relevance to product innovation. |
Danone Egypt production investment | EGP 250 million in 2026 | Adds domestic manufacturing capacity and supports localization and export activity. |
Juhayna milk collection network | 20+ centers, 800+ tons/day | Strengthens domestic raw-material supply, quality control, traceability, and cold-chain access. |
Probiotic minimum level in EDA white list | 1.0×10? CFU | Creates a measurable quality and formulation threshold for listed probiotic food supplements. |
Market Drivers
Established fermented-dairy consumption creates a practical route to probiotic adoption.
Yogurt already provides a familiar delivery format, reducing the behavioral barrier associated with introducing live cultures through entirely new products. Danone Egypt’s Activia formulation specifically contains Bifidus cultures, while Juhayna maintains extensive spoonable and drinkable yogurt portfolios. This gives probiotic suppliers access to established manufacturing, retail, and cold-chain systems rather than requiring a new distribution model.
Higher-value gut-health products are widening the category beyond conventional yogurt.
dsm-firmenich’s health and nutrition portfolio includes probiotics, prebiotics, postbiotics, and synbiotic solutions, reflecting product development around more targeted gut-health applications. In 2025, the company expanded its Humiome biotics platform and reported new concepts combining prebiotics, probiotics, and postbiotics. These developments support a shift toward products differentiated by strain, formulation, and intended health benefit rather than basic probiotic content.
Domestic dairy investment improves the supply base for fermented products.
Juhayna’s milk-collection network covers more than 14 governorates, with more than 20 collection centers and over 800 tons of milk collected each day. The company uses chilling, laboratory testing, quality grading, veterinary services, and technical training across the network. These controls matter for probiotic dairy because consistent milk quality and reliable cold-chain handling reduce variability in fermentation and finished-product quality.
Product innovation is expanding the range of consumer formats.
Juhayna’s portfolio includes Greek yogurt, stirred yogurt, fruit yogurt, drinkable yogurt, and other fermented products. Danone Egypt also maintains plain, Greek, flavored, and probiotic-oriented yogurt products. The breadth of these formats allows manufacturers to address differences in taste, texture, price, convenience, and perceived health value without requiring consumers to adopt a completely unfamiliar category.
Market Restraints and Challenges
Viable-cell stability raises manufacturing and distribution requirements.
Probiotic products must retain an adequate viable count through production, storage, distribution, and consumption. Egypt’s regulatory documentation requires probiotic identification and enumeration in CFU and calls for testing of contamination and pathogenic microorganisms for relevant products. These controls add laboratory, formulation, quality-assurance, and storage requirements compared with ordinary food products.
Regulatory classification differs between food and health-product channels.
The Egyptian Drug Authority and National Food Safety Authority continue to coordinate oversight of dietary supplements, while NFSA operates registration systems for food establishments and dietary-supplement facilities. EDA documentation also sets technical requirements for probiotic testing in pharmaceutical products. Suppliers therefore need to define the product category and intended claims early because registration, testing, labeling, and evidence requirements can differ by route to market.
Price sensitivity limits the scope for premium probiotic positioning.
Manufacturers operate in a market where consumers can choose between conventional yogurt, fortified dairy, supplements, and specialized probiotic products. Imported strains, specialized cultures, controlled storage, testing, and technical formulation can increase unit costs. Suppliers therefore need to demonstrate a clear product benefit while maintaining affordable pack sizes and efficient local production.
Raw-milk consistency remains important for probiotic dairy manufacturing.
Juhayna’s investment in milk collection, testing, grading, chilling, and farmer support shows the operational work required to secure consistent raw material. For probiotic dairy producers, variability in milk quality can affect fermentation, texture, shelf life, and production yields. Vertical integration and structured sourcing can reduce some of these risks, but smaller producers may have less control over upstream supply.
Major Segment Analysis
Functional Food and Beverages
Functional food and beverages represent a commercially important segment because probiotic consumption can be incorporated into familiar products rather than relying only on supplement purchases. Yogurt is particularly relevant because Egyptian manufacturers already operate large-scale fermented-dairy production and distribution systems. Juhayna reported 31% share in spoonable yogurt and 45% in drinkable yogurt for FY2025, demonstrating the scale of these channels even though these figures are company market-share measures rather than probiotic-market shares.
Product differentiation in this segment depends on culture selection, taste, texture, nutritional profile, pack size, shelf life, and price. Danone Egypt’s Activia product uses Bifidus cultures, while its broader yogurt range uses active cultures across several formats. This shows how probiotic positioning can be integrated into established dairy brands rather than marketed only through specialist health products.
Manufacturing scale also affects competitive economics. Danone’s EGP 250 million production-line investment in 2026 and Juhayna’s integrated milk-sourcing network indicate that companies are building local production and supply capabilities around established food categories. Suppliers of probiotic cultures therefore compete not only on strain performance but also on formulation support, technical service, stability, regulatory documentation, and the ability to support high-volume food production.
Regional Analysis
Greater Cairo and Delta Production Corridor
Greater Cairo and the surrounding industrial corridor provide an important commercial base because several large food manufacturers maintain production, distribution, and corporate operations in the area. Danone’s Obour facility and Juhayna’s manufacturing network illustrate the concentration of organized dairy production and supply-chain infrastructure. This favors suppliers that can provide local technical support, reliable deliveries, quality documentation, and cold-chain compatible solutions.
Upper Egypt
Upper Egypt has a more dispersed production and distribution structure, increasing the importance of logistics and local sourcing. Juhayna established its Assiut yogurt facility in response to local demand, giving the region dedicated manufacturing capacity for yogurt and yogurt drinks. Its wider milk-collection network now covers 14 governorates, supporting raw-material access outside the main industrial centers.
Alexandria and Northern Distribution Markets
Northern Egypt benefits from proximity to ports, industrial activity, and dense consumer markets. Import-dependent suppliers can use port access for probiotic cultures and specialized ingredients, while domestic producers can use established dairy distribution channels. Competition in this area is likely to favor suppliers that combine product availability with stable quality, short replenishment cycles, and regulatory documentation.
National Market Structure
Egypt’s national market remains sensitive to purchasing power, distribution reach, and product affordability. Domestic production provides an important counterweight to imported inputs because probiotic products require consistent supply and controlled handling. Juhayna’s integrated sourcing and manufacturing model illustrates how local producers can reduce dependence on fragmented upstream supply while maintaining nationwide distribution.
Competitive Landscape
The competitive structure combines multinational food companies, ingredient suppliers, pharmaceutical businesses, specialist probiotic developers, and Egyptian dairy manufacturers. Competition is therefore not based on a single product attribute. Companies must balance strain quality, formulation capability, manufacturing scale, distribution reach, regulatory support, brand credibility, and price.
Danone and Juhayna have an advantage in consumer-facing fermented dairy because both operate established yogurt portfolios and local production systems. Danone’s Egyptian business includes Activia and several conventional yogurt formats, while Juhayna maintains spoonable, drinkable, Greek, fruit, and other yogurt products. This creates multiple routes for probiotic or active-culture positioning within familiar food categories.
Ingredient and health-science suppliers compete through strain portfolios, scientific evidence, formulation support, and technical services. dsm-firmenich has expanded its Humiome platform across probiotics, prebiotics, postbiotics, and synbiotics, while BioGaia maintains probiotic products across adult, child, digestive, oral, and other health applications. BioGaia also lists Egypt as a market served through MinaPharm, showing the role of local distribution partners in specialist probiotic access.
The market also contains companies with different exposure across human nutrition, animal applications, pharmaceutical channels, and food ingredients. IFF and dsm-firmenich compete more heavily through ingredient and formulation capabilities, while companies such as Sandoz Egypt and Sanofi operate closer to healthcare and pharmaceutical channels. Local dairy producers compete through manufacturing scale, retail access, price, and consumer familiarity.
Recent Developments
May 2026: Danone Egypt inaugurated a new production line at its Obour factory with EGP 250 million of investment. The project expands local capacity while supporting localization and exports to Arab and African markets.
February 2026: Juhayna reported a nationwide milk-collection network exceeding 20 centers and 800 tons of daily collection across 14 governorates. The network strengthens raw-milk quality, cold-chain control, and supply reliability for dairy manufacturing.
January 2026: Juhayna highlighted its integrated dairy manufacturing system during a visit to its dairy facility, including automated production and quality-control operations. The investment focus supports domestic sourcing, production efficiency, and product consistency.
Regulatory and Policy Environment
Egypt’s regulatory framework separates important parts of the probiotic value chain between food and health-product oversight. The National Food Safety Authority provides registration and control mechanisms for food establishments and dietary-supplement facilities, while the Egyptian Drug Authority regulates relevant pharmaceutical and health-product categories. In January 2025, both authorities stated that they were continuing joint work on dietary-supplement oversight rather than transferring responsibility from one authority to the other.
The EDA’s probiotic documentation establishes measurable quality controls for products entering pharmaceutical or supplement channels. Its technical guidance requires identification of probiotic strains, viable CFU enumeration, contamination testing, and screening for pathogenic microorganisms. A separate EDA white list specifies a minimum total level of 10 million CFU for listed probiotics registered through NFSA and identifies permitted bacterial, fungal, and live-microorganism categories.
These requirements affect market entry, formulation economics, testing costs, labeling, and evidence generation. Suppliers targeting dietary supplements need stronger technical documentation than a basic food manufacturer may require, while food producers must also manage food-safety registration, manufacturing controls, storage, and labeling. Regulatory classification should therefore be established before product development and commercial launch.
Outlook and Strategic Implications
The Egypt probiotics market growth is supported by established fermented-dairy channels, specialist supplements, broader gut-health product development, and improving domestic food-manufacturing capacity. The commercial opportunity is strongest where probiotic functionality can be combined with familiar formats, affordable pricing, reliable shelf life, and credible product claims.
Local production investment will remain important because probiotic products depend on controlled manufacturing and dependable distribution. Danone’s new production line and Juhayna’s integrated dairy supply chain show how manufacturers are investing in capacity, sourcing, quality control, and market access rather than relying solely on imported finished products.
For suppliers, competitive differentiation will increasingly depend on strain documentation, viable-cell stability, formulation support, regulatory readiness, and supply reliability. Food manufacturers will prioritize cultures that perform consistently at commercial scale, while supplement companies will place greater weight on strain identity, dosage, evidence, and regulatory compliance. Distributors and healthcare-oriented businesses will need dependable product availability and documentation.
Over the 2026-2031 period, the market’s performance will depend on the ability of manufacturers to convert established dairy consumption into higher-value functional products while expanding supplement and specialized nutrition channels. Companies with local manufacturing access, strong distribution, validated strains, regulatory capability, and cost-efficient formulations will be better positioned to capture the market’s expansion.
Egypt Probiotics Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 174.0 million |
| Total Market Size in 2031 | USD 260.7 million |
| Forecast Unit | Million |
| Growth Rate | 8.42% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Form, Application, End-User |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Lactobacillus
Streptococcus
Bifidobacterium
Spore Formers
Others
By Form
Liquid
Dry
By Application
Functional Food and Beverages
Dietary Supplements
Animal Feed
By End-user
Human
Animal
By Region
Greater Cairo
Alexandria
Delta Region
Upper Egypt
Suez Canal Zone
Others
Table of Contents
1. Executive Summary
2. Market Snapshot
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. Business Landscape
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. Technological Outlook
5. Egypt Probiotics Market By Type
5.1. Introduction
5.2. Lactobacillus
5.3. Streptococcus
5.4. Bifidobacterium
5.5. Spore Formers
5.6. Others
6. Egypt Probiotics Market By Form
6.1. Introduction
6.2. Liquid
6.3. Dry
7. Egypt Probiotics Market By Application
7.1. Introduction
7.2. Functional Food and Beverages
7.3. Dietary Supplements
7.4. Animal Feed
8. Egypt Probiotics Market By End-User
8.1. Introduction
8.2. Human
8.3. Animal
9. Egypt Probiotics Market By Region
9.1. Introduction
9.2. Greater Cairo
9.3. Alexandria
9.4. Delta Region
9.5. Upper Egypt
9.6. Suez Canal Zone
9.7. Others
10. Competitive Environment and Analysis
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. Company Profiles
11.1. Danone
11.2. Nestlé S.A.
11.3. dsm-firmenich
11.4. Beyti Egypt
11.5. Dina Farms
11.6. Juhayna Food Industries
11.7. IFF (International Flavors & Fragrances)
11.8. Sandoz Egypt
11.9. Multi Vita
11.10. Hero Group
11.11. BioGaia AB
11.12. NovoGen Group
11.13. Sanofi
12. Research Methodology
LIST OF TABLES
LIST OF FIGURES





Frequently asked questions
What is the projected market value for Egypt's probiotics by 2031?
The Egypt Probiotics Market is forecast to reach USD 260.7 million by 2031.
What is the forecast CAGR for the Egypt probiotics market?
The Egypt Probiotics Market is projected to grow at an 8.42% CAGR.
Which major company holds significant market share in Egyptian yogurt?
Juhayna holds 45% drinkable and 31% spoonable yogurt shares.
What are the primary product categories for probiotics in Egypt?
They span fermented foods, functional beverages, supplements, and animal nutrition.
What are the main drivers of growth for Egypt's probiotics market?
Established yogurt consumption and wider interest in digestive health drive growth.
What commercial factors are crucial for probiotic success in Egypt?
Strain quality, viable counts, stability, cold-chain, and compliance are key.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Egypt Probiotics Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/egypt-probiotics-market