
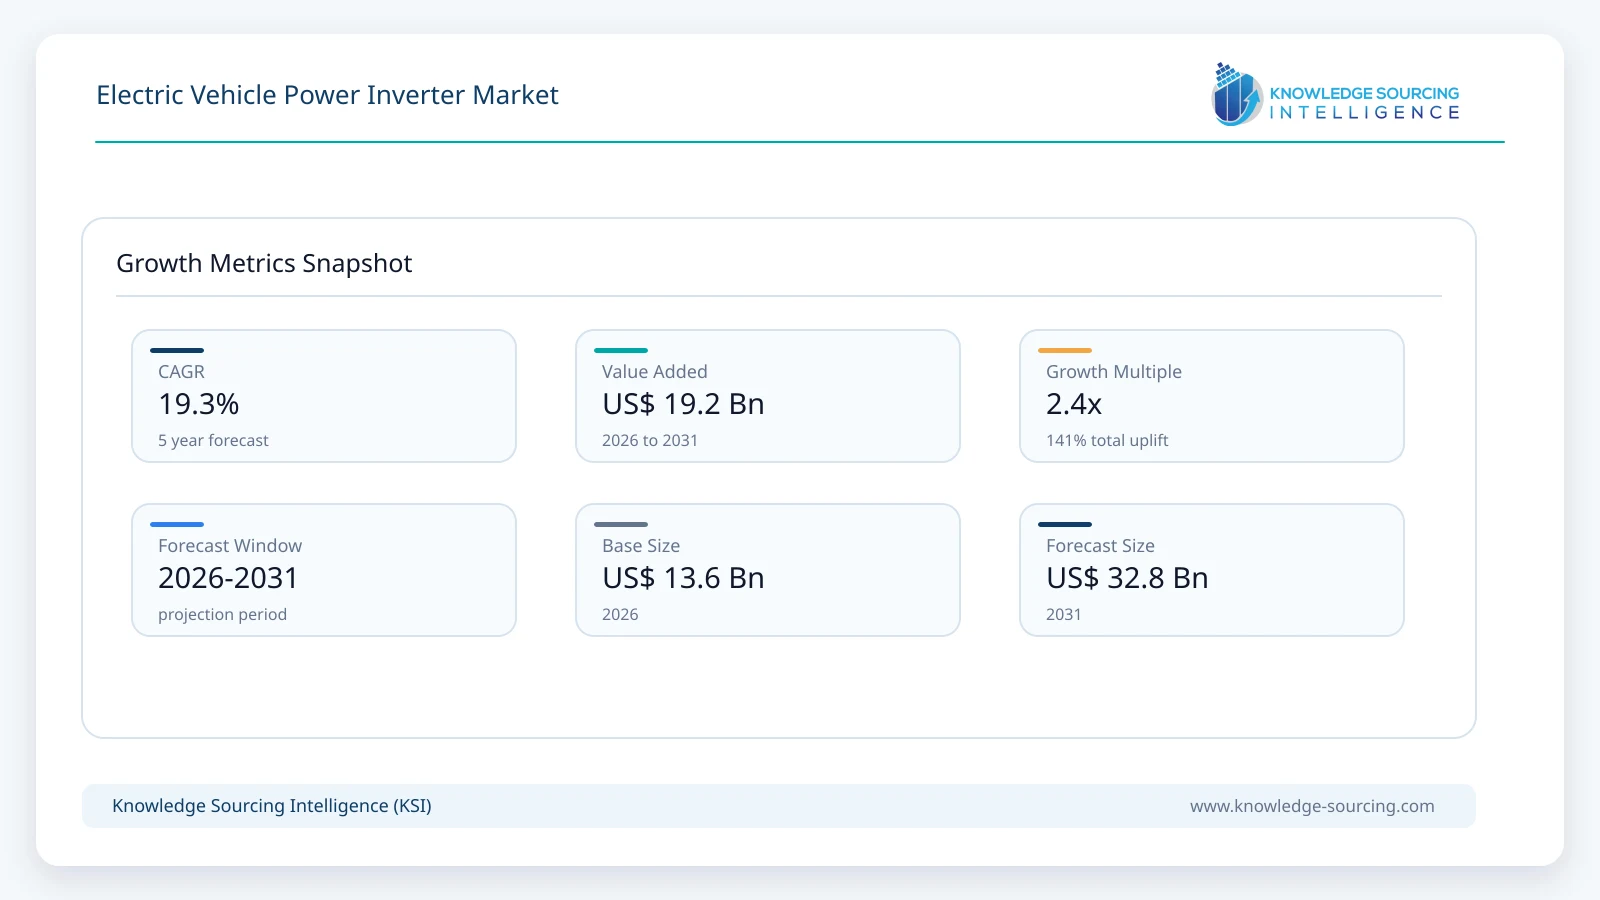
The Global Electric Vehicle Power Inverter market is forecast to grow at a CAGR of 19.3%, reaching USD 32.8 billion in 2031 from USD 13.6 billion in 2026.
Highlights:
- 1Battery electric vehicles account for approximately 54% of global EV power inverter market value in 2026supported by higher average traction power and growing dual-motor adoption.
- 2Passenger vehicles account for approximately 90% of market value in 2026driven by the scale of electrified passenger-car production across China, Europe and other major automotive markets.
- 3IGBT-based inverter systems account for approximately 65% of market value in 2026although silicon carbide is gaining rapidly in 800V and higher-performance platforms.
- 4OEM installations account for approximately 97% of global market value in 2026as inverter calibration and validation are completed as part of the original vehicle powertrain.
- 5Asia Pacific accounts for approximately 57% of global market value in 2026led by China's EV manufacturing scale and the region's dense automotive electronics supply chain.
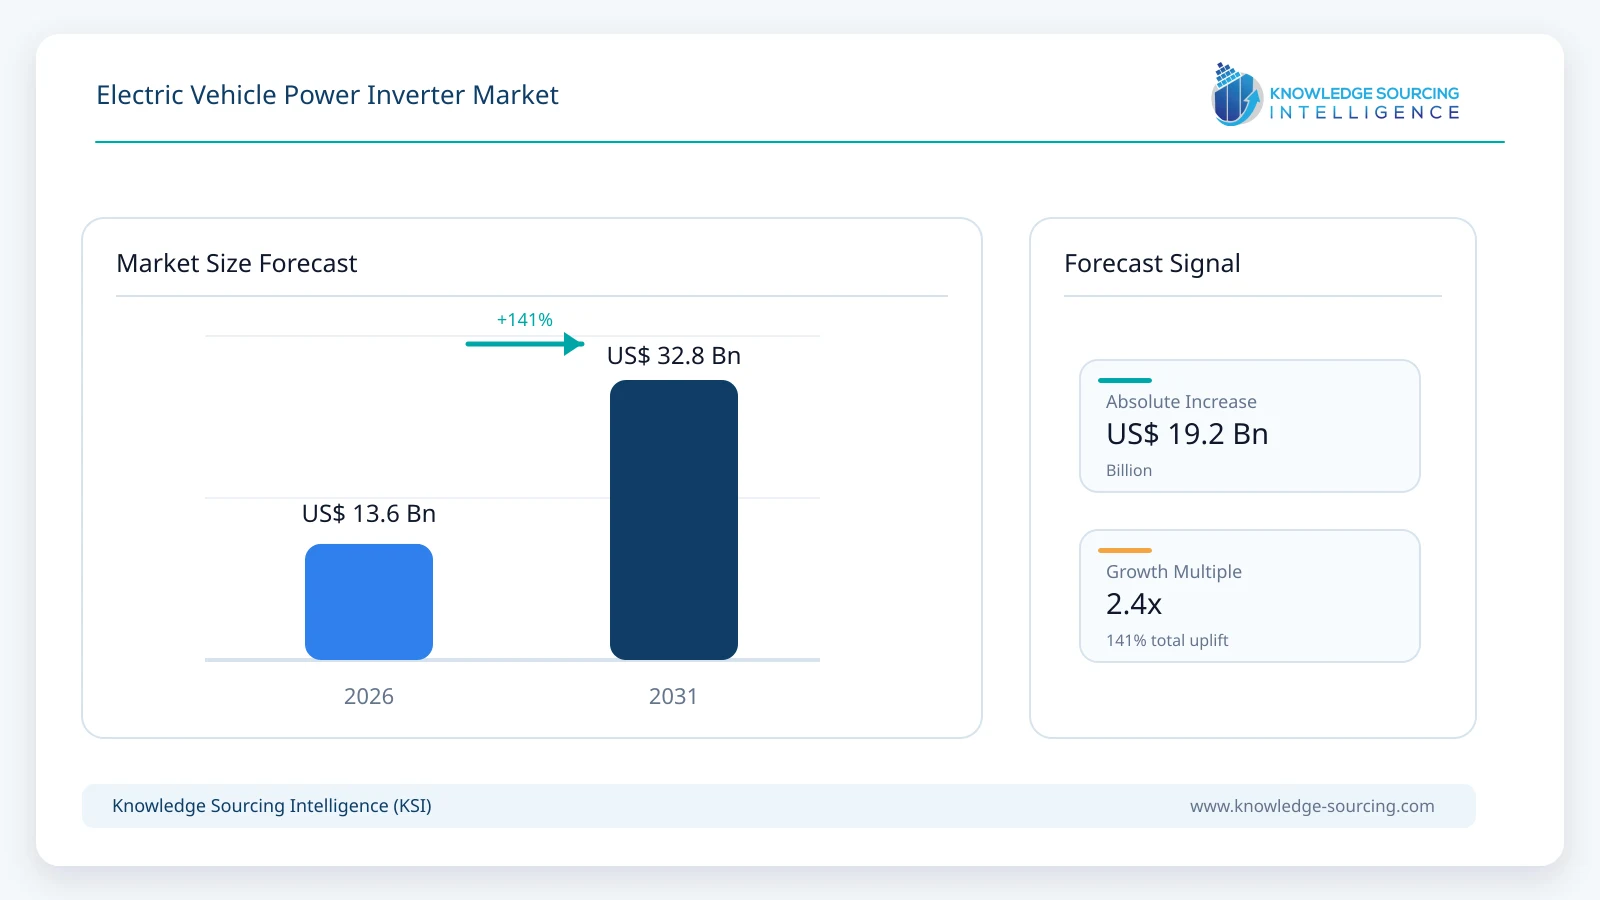
An electric vehicle power inverter converts high-voltage direct current from the battery into controlled alternating current for the traction motor and converts motor-generated AC back into DC during regenerative braking.
Electric-car sales are expected to reach about 23 million units globally in 2026, according to the International Energy Agency. This expands the addressable inverter base across passenger vehicles and commercial platforms. At the same time, average inverter content is changing as dual-motor vehicles, higher-voltage systems and more powerful commercial EVs require additional switching capacity, thermal management and control electronics.
The market is also being changed due to integration by key players. Suppliers are increasingly combining the inverter with the electric motor, reduction gear, DC/DC converter or other power-electronics functions, reducing packaging volume and assembly complexity.
Market Trends
SiC Moves Into Mainstream Platforms
Silicon carbide is moving beyond premium EVs as automakers seek higher inverter efficiency, lower switching losses, and more compact thermal systems. Bosch's fourth-generation inverter uses SiC technology across 400V and 800V applications and reaches efficiency of up to 99%, while BorgWarner's 800V inverter platform uses SiC power switches and dual-sided cooling for higher power density. DENSO, Schaeffler, Valeo, and other suppliers are also industrializing SiC-based designs. The commercial impact extends beyond the semiconductor itself because lower losses can reduce cooling requirements and help automakers improve driving range or free packaging space elsewhere in the electric drivetrain.
800V Architectures Expand
Higher-voltage architectures reduce current for a given power level and are becoming more common in vehicles where fast charging, high performance and compact electrical systems justify the additional component cost. Bosch offers its latest inverter for both 400V and 800V systems, while BorgWarner has secured high-volume 800V inverter programmes with European OEMs. Valeo's next-generation electrification platforms also target higher-voltage applications in China. The technology is spreading from flagship vehicles into a wider range of premium and upper-mainstream models, creating demand for SiC modules, advanced insulation, improved cooling and tighter control of switching behavior.
E-Drive Integration Accelerates
Vehicle manufacturers are consolidating motors, inverters, reduction gears and supporting electronics into integrated drive units to reduce weight, wiring, housings and assembly steps. Astemo supplies the motor and inverter incorporated into JATCO's 3-in-1 powertrain for the Nissan LEAF, while Nidec's E-Axle integrates the motor, inverter and reducer into one system. BorgWarner and ZF are also developing integrated electric-drive modules. This shift raises the importance of system-level engineering because inverter efficiency, motor characteristics, software and thermal behavior must be optimized together rather than treated as separate components.
Control Electronics Become More Integrated
Power-stage performance is no longer the only route to better inverter economics. Semiconductor suppliers are reducing external component count by combining gate driving, monitoring and safety functions into more integrated control devices. Infineon's 2026 EiceDRIVER family was introduced for BEV traction inverters with support for IGBTs and SiC MOSFETs while reducing the bill of materials for inverter control electronics. This gives Tier-1 suppliers a way to raise functional integration without increasing enclosure size and can shorten the path toward common inverter platforms used across several vehicle models.
Market Drivers
Electrified Vehicle Production Expands the Addressable Base
The International Energy Agency expects global electric-car sales to reach about 23 million units in 2026, equivalent to roughly 28% of total car sales, and full hybrids add another large inverter-bearing vehicle pool. Every high-voltage traction motor requires inverter control, making electrified-vehicle production the most direct volume driver for the market. Demand is also broadening geographically: Europe is expected to record substantial EV sales growth in 2026, while markets across Asia Pacific excluding China and parts of Latin America are expanding from smaller bases. Higher vehicle production creates additional opportunities for global Tier-1 suppliers as well as Chinese, Japanese and Korean manufacturers with localized power-electronics capacity.
Dual-Motor Layouts Increase Power-Electronics Content
A growing number of battery electric vehicles use separate front and rear traction motors for all-wheel drive, performance or efficiency optimization. Plug-in hybrids and range-extended vehicles can also contain more than one electric machine for traction and energy generation. Valeo's next-generation dual inverter illustrates how suppliers are adapting architectures to control multiple motors without simply duplicating complete inverter housings. Additional switching capacity, cooling and software still increase power-electronics content per vehicle, giving inverter suppliers a value opportunity beyond the growth in total vehicle units.
Commercial EVs Raise Average Power Requirements
Electric buses, trucks and larger light-commercial vehicles require greater continuous power and more demanding thermal performance than most passenger cars. Their inverters must manage high current for longer duty cycles and operate reliably under heavier loads. ZF, BorgWarner, Bosch and other suppliers have developed scalable power-electronics platforms for commercial applications, while integrated e-drive systems are moving into buses, delivery vehicles and trucks. Commercial vehicles remain a smaller unit pool than passenger cars, but their higher inverter power increases revenue per vehicle and adds another layer of market growth.
Market Restraints and Challenges
Cost Pressure Intensifies as Volumes Scale
Automotive OEMs continue to demand lower cost even as inverter efficiency, power density and functional safety requirements become more demanding. Higher semiconductor production, standardized platforms, localized manufacturing and tighter integration can reduce the cost of mature inverter designs. Chinese EV manufacturers add further pricing pressure because rapid platform cycles and high domestic volumes encourage aggressive cost targets. Suppliers must offset this pressure through SiC performance, common-platform engineering, software integration and manufacturing efficiency rather than relying solely on higher selling prices.
Integrated E-Axles Change Supplier Economics
The move from standalone inverters toward integrated e-axles and multi-in-one powertrain systems changes how inverter revenue is captured. OEMs may purchase one integrated drive module instead of separate motor, inverter and reduction-gear contracts, favoring suppliers that can engineer the complete system. Standalone specialists face greater pressure to integrate or partner, while diversified suppliers can use common cooling, control electronics and housings to lower system cost. The shift also makes platform qualification more complex because changes to one part of the e-drive can affect electrical, thermal and software performance across the complete unit.
Segment Analysis
By Propulsion Type: Battery Electric Vehicles
Battery electric vehicles are expected to generate approximately USD 21.0 billion in inverter revenue by 2031, keeping the largest propulsion position. BEVs generally use higher-power traction motors than full hybrids and are adopting dual-motor layouts at a faster rate, increasing power-electronics content per vehicle. They are also the primary market for 800V architectures and high-value SiC inverters because efficiency improvements translate directly into range and charging performance. China provides the largest production base, while European, Korean and North American OEM programmes add substantial high-specification demand. PHEVs continue to form an important market because they combine electric traction with combustion powertrains, but their inverter power is typically below that of larger BEV systems.
By Vehicle Type: Passenger Vehicles
Passenger vehicles are forecast to account for approximately USD 29.5 billion by 2031, with scale coming from BEV, PHEV and HEV production across mass-market and premium segments. Inverter requirements range from cost-focused 400V systems in compact vehicles to high-output 800V SiC units used in performance EVs and large SUVs. Suppliers increasingly design scalable architectures that can cover several vehicle classes with changes to semiconductor modules, software and cooling rather than completely new hardware. Commercial vehicles generate a smaller revenue pool but carry substantially higher power requirements per unit, particularly in electric buses, medium-duty trucks and heavy delivery vehicles.
By Power Semiconductor Technology: Silicon Carbide
SiC-based inverter systems are forecast to approach USD 19.0 billion by 2031, becoming the largest technology pool by value as adoption extends beyond premium BEVs. Silicon carbide allows higher switching frequency, lower losses and operation at elevated temperatures, giving automakers more flexibility in cooling-system design and vehicle packaging. Bosch, BorgWarner, Schaeffler, DENSO, Valeo and other suppliers have established SiC platforms for 400V and 800V applications. IGBT technology will retain an important role in hybrids and price-sensitive EVs because of its mature supply chain and lower component cost, preventing an immediate full-market transition.
By Distribution Channel: OEM
OEM installations are expected to account for approximately USD 31.8 billion by 2031, leaving a limited open aftermarket for complete traction inverters. The inverter is calibrated with the traction motor, battery, thermal system and vehicle-control software and must pass platform-specific durability, electromagnetic compatibility and functional-safety validation. Replacement demand exists when units fail, but most service parts move through automaker and Tier-1 networks rather than independent aftermarket channels. The commercial market is therefore driven primarily by design wins and multi-year production contracts, making early participation in vehicle-platform development critical for inverter suppliers.
Major Region: Asia Pacific
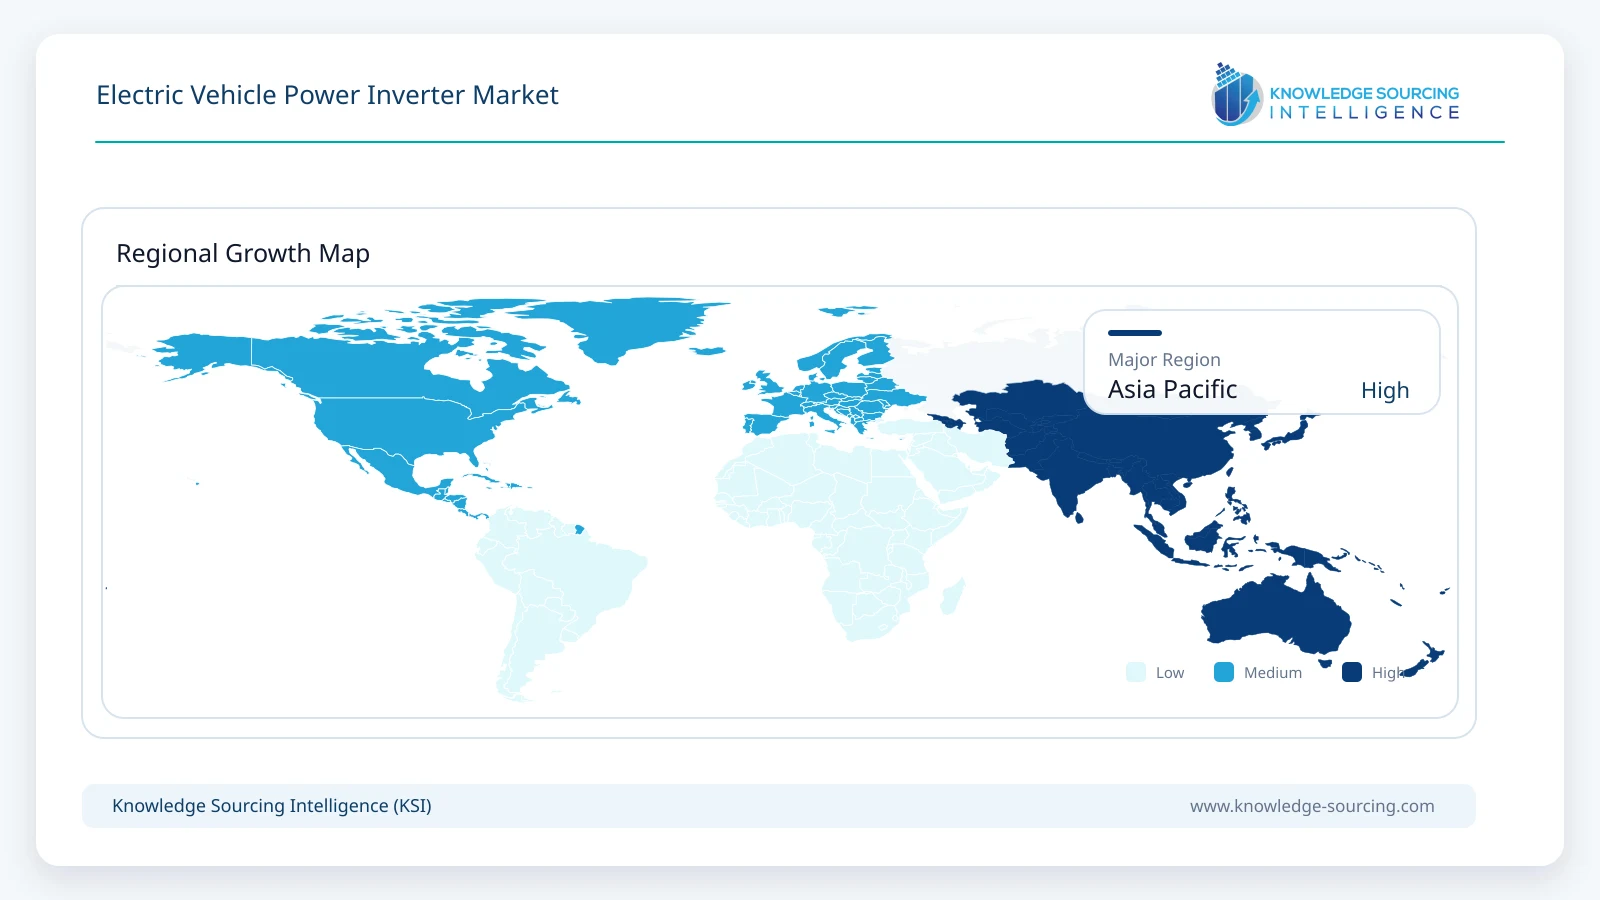
Asia Pacific is forecast to generate approximately USD 19.3 billion in inverter revenue by 2031, led by China and reinforced by major automotive electronics capabilities in Japan and South Korea. China combines high EV production with domestic semiconductor, motor and e-drive suppliers, creating the industry's most competitive cost environment. Japan remains important through Toyota, Honda and Nissan electrification programmes and suppliers such as DENSO, Mitsubishi Electric, Nidec and Meidensha, while South Korea adds Hyundai, Kia and a substantial electronics supply chain. India and Southeast Asia provide additional long-term volume as domestic EV manufacturing scales from a smaller base.
Major Country: China
China is expected to generate approximately USD 13.6 billion in EV power inverter revenue by 2031, supported by the world's largest electric-vehicle manufacturing base and rapid adoption of integrated e-drive platforms. Domestic automakers increasingly develop power electronics internally or source from Chinese Tier-1 suppliers, placing strong cost and development-speed pressure on multinational competitors. Schaeffler has already localized high-voltage inverter-brick production in Tianjin, BorgWarner is building on multiple high-volume inverter programmes, and Valeo's next-generation dual inverter entered series production in China in early 2026. The country's combination of scale, local semiconductor capacity and short vehicle-development cycles makes it a critical market for both technology deployment and manufacturing economics.
Competitive Environment and Analysis
The electric vehicle power inverter market combines diversified automotive Tier-1 suppliers, power-electronics specialists and integrated e-drive manufacturers. Bosch, DENSO, BorgWarner, Schaeffler, Astemo, Valeo, Mitsubishi Electric, ZF and Nidec compete across standalone inverters and integrated electric-drive systems. Their competitive advantage depends on semiconductor selection, thermal management, motor-control software, automotive qualification and the ability to support high-volume global vehicle launches. Several companies are also moving from individual components toward complete e-drive systems as OEMs seek fewer interfaces and more integrated sourcing.
Vitesco Technologies ceased to exist as an independent company after its merger into Schaeffler in October 2024, and Hitachi Astemo changed its corporate name to Astemo Ltd. in April 2025. Toyota Industries' publicly listed 1,500W and 2,400W DC-AC inverters are accessory power products rather than traction-motor inverters and should not be used as evidence of a leading position in this market. The revised company set concentrates on suppliers with direct traction inverter, power-control-unit or integrated e-drive participation.
Recent Developments
August 2026: BorgWarner secured extensions of multiple high-volume inverter programmes with a major European OEM, covering PHEV and 800V BEV applications using updated power electronics and SiC technology.
June 2026: Astemo confirmed that its motors and inverters were adopted for the Nissan LEAF electric powertrain supplied through JATCO's integrated 3-in-1 drive unit.
June 2026: Infineon introduced reinforced isolated EiceDRIVER gate-driver ICs for BEV traction inverters, supporting IGBT and SiC power stages with fewer external components.
April 2026: Valeo confirmed that its next-generation dual inverter and 5-in-1 electric-drive module had reached series production in China.
2026: Bosch continued commercial rollout of its fourth-generation inverter platform, offering SiC-based 400V and 800V configurations with efficiency of up to 99%.
Market Outlook
Electric vehicle power inverter demand through 2031 will be driven by a larger electrified-vehicle production base and a richer power-electronics mix per vehicle. SiC, 800V systems, dual-motor layouts and integrated e-drives should account for a growing share of value even as the cost of mature inverter designs declines. BEVs will take a larger portion of industry revenue as their unit volumes rise and higher-power platforms move into mainstream price bands.
Supplier competition will shift further toward system engineering rather than standalone hardware. OEMs are asking for compact electric-drive modules with coordinated motor control, cooling, power electronics and vehicle software, which favors companies able to combine semiconductor expertise with automotive integration. Asia Pacific will remain the largest production and demand region, but platform awards in Europe and North America will continue to influence technology direction, particularly in SiC, functional safety and 800V architecture.
Electric Vehicle Power Inverter Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 13.6 billion |
| Total Market Size in 2031 | USD 32.8 billion |
| Forecast Unit | Billion |
| Growth Rate | 19.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Propulsion Type, Vehicle Type, Power Semiconductor Technology, Distribution Channel |
| Companies |
|
Market Segmentation
By Propulsion Type
Hybrid Electric Vehicle
Plug-in Hybrid Electric Vehicle
Battery Electric Vehicle
By Vehicle Type
Passenger Vehicles
Commercial Vehicles
By Power Semiconductor Technology
IGBT
Silicon Carbide MOSFET
Others
By Distribution Channel
OEM
Aftermarket
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Spain
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Indonesia
Thailand
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits for the Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
3. EXECUTIVE SUMMARY
3.1. Key Findings
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter's Five Forces Analysis
4.4. Industry Value Chain Analysis
4.5. Analyst View
5. ELECTRIC VEHICLE POWER INVERTER MARKET BY PROPULSION TYPE
5.1. Introduction
5.2. Hybrid Electric Vehicle
5.3. Plug-in Hybrid Electric Vehicle
5.4. Battery Electric Vehicle
6. ELECTRIC VEHICLE POWER INVERTER MARKET BY VEHICLE TYPE
6.1. Introduction
6.2. Passenger Vehicles
6.3. Commercial Vehicles
7. ELECTRIC VEHICLE POWER INVERTER MARKET BY POWER SEMICONDUCTOR TECHNOLOGY
7.1. Introduction
7.2. IGBT
7.3. Silicon Carbide MOSFET
7.4. Others
8. ELECTRIC VEHICLE POWER INVERTER MARKET BY DISTRIBUTION CHANNEL
8.1. Introduction
8.2. OEM
8.3. Aftermarket
9. ELECTRIC VEHICLE POWER INVERTER MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. United Kingdom
9.3.2. Germany
9.3.3. France
9.3.4. Spain
9.3.5. Italy
9.3.6. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. Israel
9.4.4. South Africa
9.4.5. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. Japan
9.5.3. India
9.5.4. South Korea
9.5.5. Indonesia
9.5.6. Thailand
9.5.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Robert Bosch GmbH
11.2. DENSO Corporation
11.3. BorgWarner Inc.
11.4. Schaeffler AG
11.5. Astemo, Ltd.
11.6. Valeo SE
11.7. Mitsubishi Electric Corporation
11.8. ZF Friedrichshafen AG
11.9. Nidec Corporation
11.10. Hyundai Mobis Co., Ltd.
11.11. Meidensha Corporation
11.12. Delta Electronics, Inc.
11.13. Dana Incorporated
11.14. LG Magna e-Powertrain Co., Ltd.
11.15. AISIN Corporation
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Research Methodology
12.5. Abbreviations
Navigate
Trusted by the world's leading organizations











