
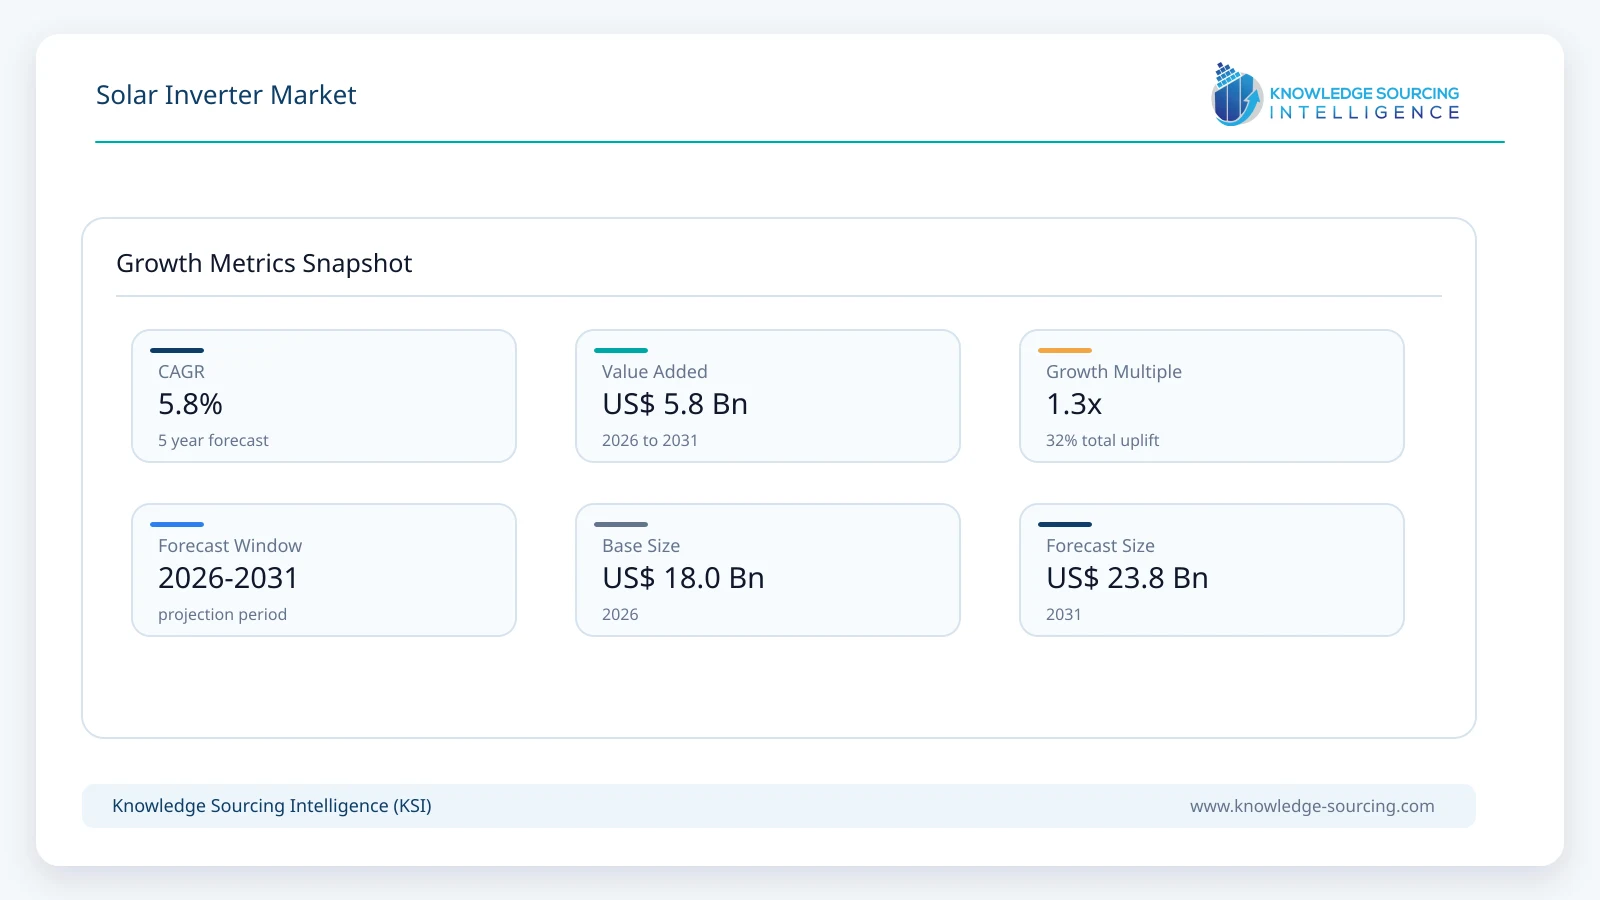
The Solar Inverter Market is forecast to increase from approximately USD 18.0 billion in 2026 to USD 23.8 billion in 2031 at a CAGR of approximately 5.8%.
Highlights:
- 1String inverters account for approximately 62% of global solar inverter market value in 2026 as their use expands across commercial, industrial and utility-scale installations.
- 2Standard grid-connected solar-only systems represent approximately 68% of market value in 2026, although hybrid solar-storage inverters record substantially faster growth through 2031.
- 3Utility-scale applications account for approximately 48% of market value in 2026, supported by more than 600 GW of annual global solar additions.
- 4Asia Pacific accounts for approximately 52% of market value in 2026, supported by exceptionally high solar deployment in China and India and a large domestic inverter-manufacturing base.
- 5Middle East and Africa is projected to record the fastest regional market growth at approximately 8.6% annually through 2031 as solar installations accelerate across Saudi Arabia, the UAE, South Africa and other emerging markets.
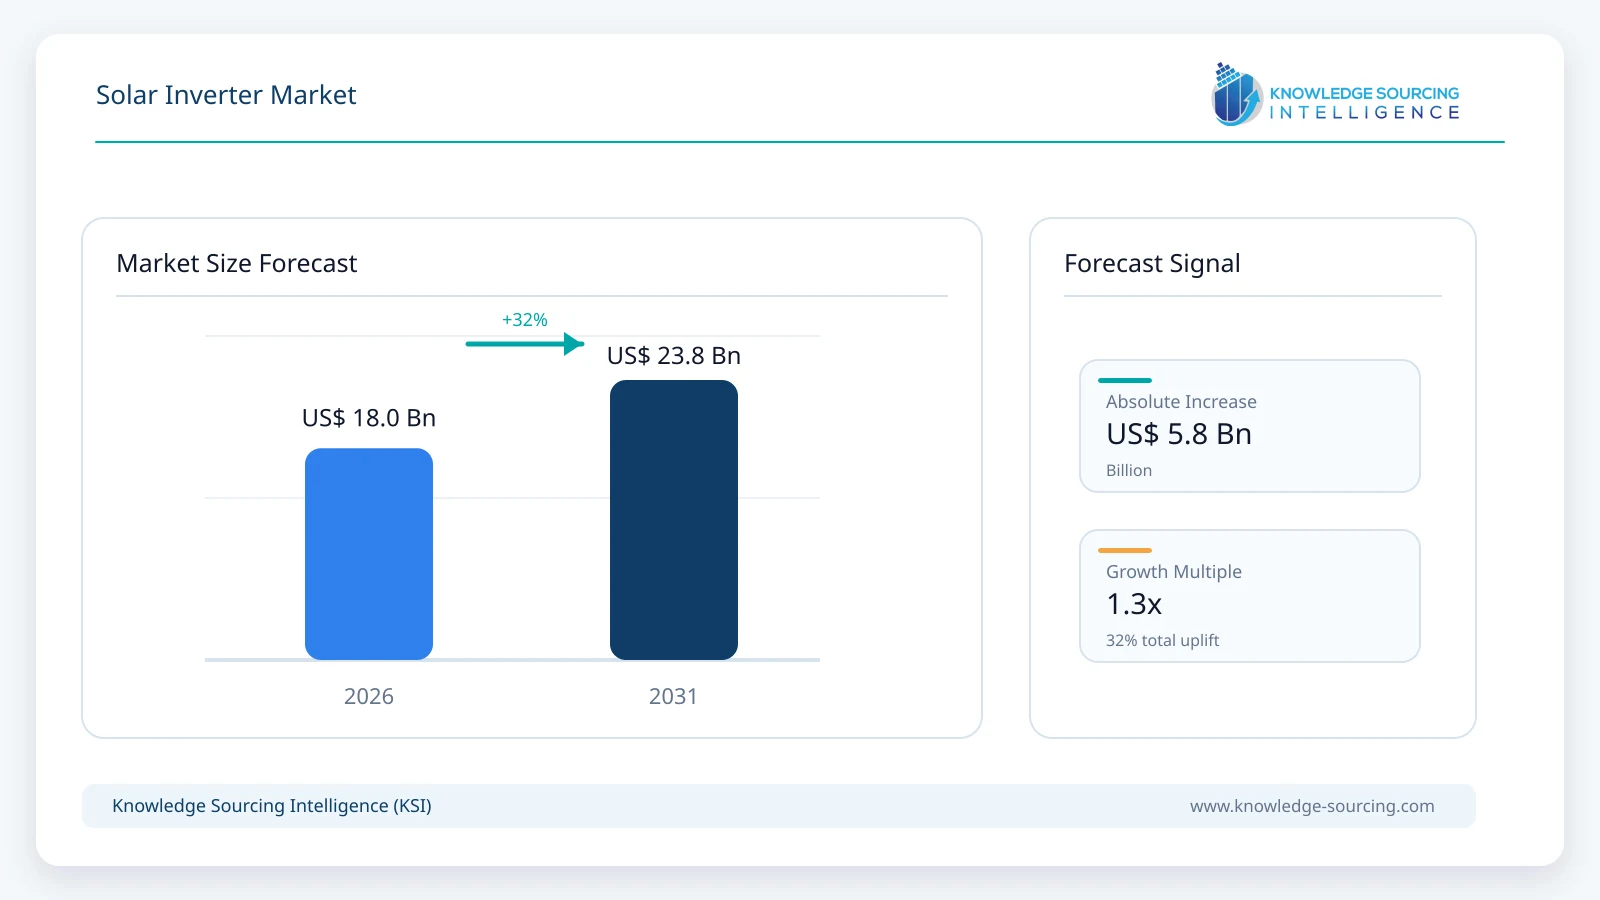
The estimate remains consistent with current deployment economics: global solar PV additions exceeded 600 GW in 2025, while the IEA estimates the average price of global inverter shipments at approximately USD 28/kW. Applying this order of magnitude to new PV capacity alone produces an annual inverter value close to the existing KSI base before considering replacement installations and significantly higher microinverter prices. The IEA reports average 2025 microinverter pricing of approximately USD 180/kW compared with around USD 25/kW for high-power three-phase systems, illustrating why market value does not move directly with installed solar capacity.
The market covers power-electronic equipment used primarily to convert electricity generated by solar PV systems into grid-compatible alternating current and manage system operation. It includes central, string and microinverter architectures as well as standard solar-only, hybrid solar-storage and off-grid configurations across residential, commercial and industrial, and utility-scale applications. Battery-only power conversion systems are excluded unless incorporated within a solar-linked hybrid inverter. Modern solar inverters increasingly perform voltage and frequency management, reactive-power control, fault ride-through, remote monitoring and communication with batteries, EV chargers and energy-management systems. The IEA describes the inverter as the control point or “brain” of modern solar installations, underscoring its growing operational importance as photovoltaic penetration increases.
Solar inverter demand is being shaped by simultaneous growth in installed photovoltaic capacity and falling equipment prices. The IEA estimates that annual global solar additions exceeded 600 GW for the first time in 2025, lifting cumulative capacity to around 2.8 TW. China commissioned nearly 370 GW, India added almost 50 GW, the European Union installed close to 70 GW and Saudi Arabia added nearly 7 GW, demonstrating that inverter demand is no longer concentrated in a small number of mature Western solar markets. The IEA expects distributed residential, commercial, industrial and off-grid solar to account for 42% of worldwide PV expansion between 2025 and 2030, while solar overall represents nearly 80% of projected renewable capacity growth.
Despite rapidly increasing shipment volumes, market revenue grows more slowly because inverter prices continue to decline. The IEA estimates a global average inverter shipment price of approximately USD 28/kW in 2025 and notes that Chinese manufacturers generally offer substantially lower pricing than suppliers headquartered elsewhere. China also accounted for around 80% of global manufacturing capacity for solar and battery inverters in 2025, creating intense price competition throughout utility, commercial and residential segments. SMA provides a useful indication of this pressure: the company sold 19.9 GW of PV inverter capacity in 2025, slightly above 2024, while overall group revenue decreased and its residential and commercial business remained affected by aggressive pricing.
Market Trends
Inverters Are Becoming Active Grid-Control Devices
Solar inverters are increasingly required to support rather than simply connect to electricity grids. High photovoltaic penetration can alter system frequency response, voltage behaviour and fault characteristics because inverter-based generators do not inherently behave like conventional synchronous generators. FERC approved additional U.S. reliability standards in July 2025 requiring inverter-based resources to remain connected during specified voltage and frequency disturbances, followed by further modelling and data-validation standards in February 2026. Manufacturers are responding by embedding grid-support functions, reactive-power control and increasingly grid-forming capabilities within inverter platforms. Huawei’s 2026 renewable-energy strategy places grid forming at the center of future PV and storage systems, while Sungrow’s SG465HX utility string inverter emphasizes enhanced grid compatibility.
Hybrid Solar-Storage Inverters Are Expanding
Rapid battery-storage deployment is increasing demand for bidirectional and hybrid inverter architectures that can coordinate PV generation, battery charging and discharging, household loads and grid interaction. Global battery-storage additions increased approximately 40% in 2025 to 108 GW, making storage the fastest-growing power technology, while approximately 20% of new capacity was installed behind the meter. This increasingly overlaps with distributed solar deployment and is encouraging manufacturers to integrate battery control directly into solar-inverter platforms. SMA introduced a new generation of three-phase hybrid inverters in June 2026 ranging from 5 kVA to 30 kVA with integrated energy management and optional backup, while SolarEdge launched its Nexis residential solar-and-storage architecture during 2026. The result is a gradual migration from standalone solar conversion equipment toward broader energy-management systems.
Cybersecurity Is Becoming a Procurement Criterion
Internet-connected inverters increasingly provide remote monitoring, firmware updates and grid-control capabilities, creating cybersecurity risks that are now influencing procurement policy. The IEA notes that unauthorized access to an inverter can potentially alter the operation of connected equipment and that supply-chain vulnerabilities can arise through software or remote-control infrastructure. China accounted for approximately 80% of global inverter-manufacturing capacity in 2025, increasing the policy significance of concentrated sourcing. In 2026, the European Union introduced restrictions affecting funding for projects using inverters from jurisdictions considered high-risk, while U.S. legislation has also imposed procurement restrictions affecting certain foreign equipment. The shift is encouraging localization, regional production and greater emphasis on secure communications, software maintenance and control-system architecture in addition to efficiency and cost.
Market Drivers
Global Solar PV Additions Above 600 GW Annually
Solar deployment remains the fundamental demand driver because virtually every photovoltaic installation requires inverter capacity. Global PV additions exceeded 600 GW in 2025, approximately 12% higher than the previous year, while cumulative capacity reached around 2.8 TW. Solar represented more than three-quarters of all new renewable capacity commissioned during the year. China alone installed nearly 370 GW, India almost 50 GW and the European Union approximately 70 GW. The forward pipeline remains substantial: the IEA projects around 4,600 GW of renewable capacity additions between 2025 and 2030, with utility-scale and distributed solar together representing nearly 80% of the expansion. This supports high inverter shipment volumes even where falling hardware prices limit the corresponding revenue growth rate.
Expansion of Distributed Solar PV
Distributed solar creates disproportionate value for inverter manufacturers because residential and commercial systems generally use smaller string, hybrid or microinverter architectures with considerably higher prices per kilowatt than large utility-scale equipment. The IEA expects residential, commercial, industrial and off-grid solar to account for approximately 42% of global photovoltaic capacity expansion between 2025 and 2030. Its 2025 pricing analysis places microinverters at around USD 180/kW compared with approximately USD 25/kW for high-power three-phase inverter systems, demonstrating the value difference between installation categories. Distributed systems also increasingly incorporate batteries, EV charging, backup capability and dynamic tariff management, allowing inverter suppliers to sell broader energy-management platforms rather than basic conversion hardware.
Rapid Battery-Storage Deployment
Battery expansion increases demand for hybrid and bidirectional inverter capabilities across both utility-scale and distributed installations. Global battery additions reached 108 GW in 2025, increasing around 40% year over year, with installed capacity approximately eleven times its 2021 level. Around 24 GW of utility-scale battery installations were directly co-located with renewable generation, while behind-the-meter storage continued expanding across residential and commercial markets. The relationship between solar and storage increases the functional value of inverter technology because equipment must coordinate generation, charging, discharge, grid services and local loads. Manufacturers including Huawei, Sungrow, SMA, SolarEdge, GoodWe and Growatt are consequently positioning hybrid and storage-compatible inverter platforms as central elements of their future product portfolios.
Market Restraints
Falling Inverter Prices Limit Revenue Growth
Strong competition and manufacturing scale are reducing inverter prices even as global shipment volumes rise. The IEA estimates the average global inverter shipment price at approximately USD 28/kW in 2025, while suppliers headquartered outside China often sell comparable equipment at significant premiums to Chinese manufacturers. This pricing pressure is already visible in manufacturer results. SMA reported 19.9 GW of inverter output sold in 2025, up 1.7%, but group sales declined slightly and its Home & Business Solutions revenue fell from €354.1 million in 2024 to €247.2 million in 2025 amid weak demand and aggressive pricing. As a result, solar capacity additions can expand substantially faster than inverter-market revenue, particularly in utility-scale applications where procurement is highly price sensitive and unit prices per kilowatt are lowest.
Supply-Chain Concentration and Cybersecurity Restrictions
The inverter supply chain is more geographically concentrated than many other downstream solar components. China accounted for approximately 80% of worldwide inverter-manufacturing capacity in 2025, while Europe represented around 8%, equivalent to approximately 95 GW of annual manufacturing capacity. The concentration creates procurement risks as governments introduce restrictions motivated by cybersecurity and supply-chain resilience. Moving purchases toward alternative suppliers can increase equipment costs and create short-term mismatches between locally available inverter models and project requirements. European manufacturing capacity is theoretically sufficient to meet regional demand in aggregate, but the IEA cautions that individual product classes may not align with local demand, potentially causing delays or higher costs. These constraints are therefore encouraging diversification while simultaneously increasing compliance and sourcing complexity.
Solar Inverter Market Segment Analysis
By Inverter Architecture
String Inverters
String inverters remain the largest architecture and are projected to reach approximately USD 15.7 billion in market value by 2031, representing growth of around 7.1% annually from 2026. Their position has expanded beyond traditional residential and commercial rooftops as higher-power string equipment increasingly competes with central inverters in utility-scale projects. Sungrow’s SG465HX, launched in January 2026, illustrates this progression toward several-hundred-kilowatt string architectures designed for large solar plants. String systems offer modularity, multiple maximum-power-point trackers and reduced single-point-of-failure exposure, allowing developers to isolate individual units rather than losing a large block of generation if one central inverter fails. The architecture also benefits from increasing module power ratings and higher DC voltages, which permit manufacturers to raise inverter capacity without proportionally increasing equipment count.
By Functionality
Standard Grid-Connected Inverters
Standard solar-only grid-connected inverters remain the largest functionality segment and are projected to generate approximately USD 15.5 billion by 2031. Their share nevertheless declines gradually as hybrid PV-storage equipment expands more quickly. Grid-connected inverters remain the default architecture for large utility plants and many commercial systems where batteries are absent or supplied through separate power-conversion equipment. Manufacturers continue increasing power density, MPPT flexibility, reactive-power capability and cybersecurity functionality in these products. SMA’s Sunny Tripower X 60, for example, provides up to 60 kW of output, five independent MPPT trackers and active and reactive power management for commercial installations. Hybrid architectures gain share fastest in residential and smaller commercial applications, but standard grid-connected equipment remains dominant through 2031 because utility-scale solar installations account for such a large proportion of annual global PV deployment.
By End User
Utility-Scale
Utility-scale installations remain the largest end-user category and are projected to reach approximately USD 11.7 billion by 2031. The segment benefits directly from the unprecedented pace of global solar construction, including nearly 370 GW of Chinese installations during 2025 and large capacity additions across India, the United States, Europe and the Middle East. Utility projects increasingly deploy high-power string inverters alongside traditional central architectures, while grid-support requirements are raising inverter functionality even when average equipment prices continue falling. FERC’s requirements covering ride-through and modelling of inverter-based resources demonstrate the increasing regulatory importance of predictable inverter behaviour in large power systems. Utility customers remain highly price sensitive, however, which limits revenue growth relative to the rapid increase in deployed inverter capacity.
Regional Outlook
Asia Pacific
Asia Pacific accounts for approximately 52% of global solar inverter market value in 2026 and is projected to reach around USD 12.4 billion by 2031. The region’s position reflects both exceptionally high photovoltaic deployment and the concentration of global inverter manufacturing.
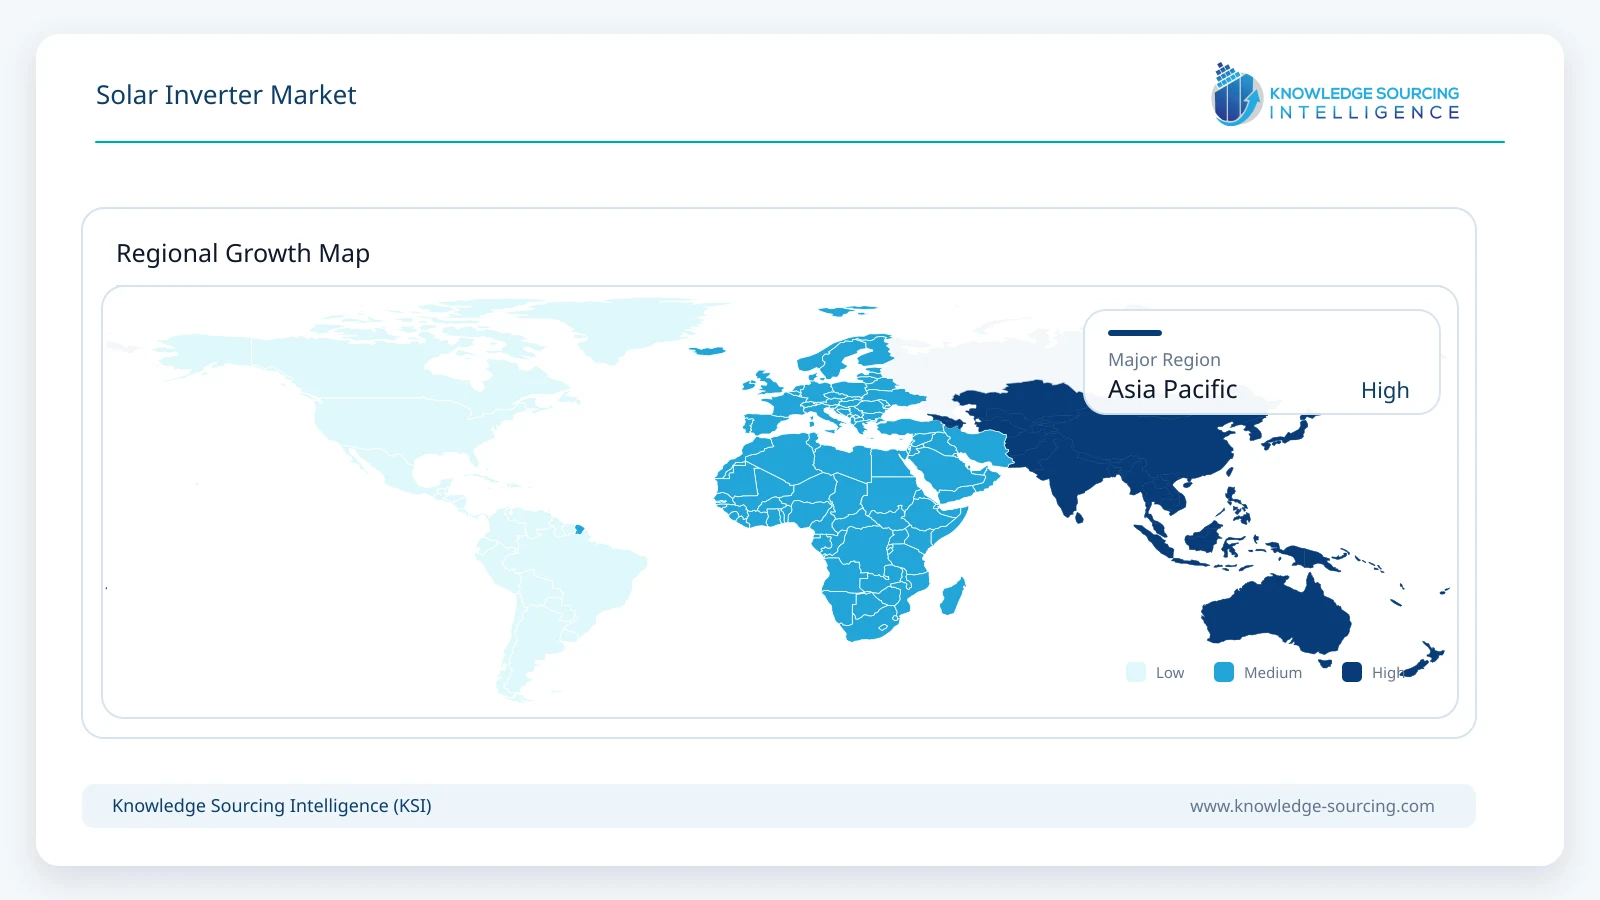
China commissioned nearly 370 GW of solar capacity in 2025 and accounted for around 80% of worldwide inverter production capacity, while India added almost 50 GW of solar during the year. India is also expanding domestic inverter manufacturing, with Waaree commissioning 3.05 GW of annual production capacity in Gujarat in December 2025. Asia Pacific remains the largest region through 2031 despite comparatively low unit prices because shipment volumes are significantly larger than in other markets and leading global suppliers including Huawei, Sungrow, Solis, Growatt, GoodWe, Sineng and TBEA are headquartered in the region.
Middle East and Africa
Middle East and Africa is projected to record the fastest regional growth at approximately 8.6% annually through 2031, although it remains substantially smaller than Asia Pacific. Renewable capacity additions approximately doubled in both sub-Saharan Africa and the Middle East and North Africa during 2025, reaching around 12 GW in each region. Saudi Arabia commissioned nearly 7 GW of solar PV, approximately four times its 2024 additions, while South Africa installed more than 3 GW for the first time. The inverter opportunity spans very different system types: Saudi Arabia and the UAE are developing large utility-scale projects that require high-capacity string and central systems, while African markets also generate demand for commercial, residential, mini-grid and off-grid equipment. Battery deployment is increasing simultaneously, with Middle Eastern battery additions exceeding 3 GW in 2025, supporting additional demand for hybrid and bidirectional inverter platforms.
Competitive Environment and Analysis
The global market combines very large Chinese power-electronics companies with established European, American and Asian inverter specialists. Huawei and Sungrow maintain broad portfolios across utility, commercial and residential applications, while Ginlong Solis, Growatt, GoodWe, Sineng Electric, TBEA and Kehua have developed significant international distribution and manufacturing scale. SMA, Fronius and Power Electronics maintain stronger positions in selected European and utility-scale markets, while SolarEdge and Enphase remain particularly important in distributed residential systems. Enphase differentiates through module-level microinverter architecture and reported approximately USD 873.7 million of physical-work-test order backlog with U.S. third-party ownership providers by May 2026. Competitive differentiation is increasingly based on grid functionality, cybersecurity, energy-management software and battery integration in addition to conversion efficiency and hardware cost.
Market Share Analysis
Manufacturing is highly concentrated geographically even though the supplier landscape contains numerous brands. China accounted for around 80% of global inverter-manufacturing capacity in 2025, compared with approximately 8% in Europe. Huawei and Sungrow benefit from large domestic deployment and broad international portfolios, while other Chinese companies including Solis, Growatt, GoodWe, Sineng, TBEA and Kehua reinforce the country’s manufacturing scale. European and U.S. companies remain influential in higher-value or specialized segments, particularly microinverters, module-level electronics, utility systems and markets where cybersecurity or domestic-content rules affect procurement. The growing importance of software creates an additional competitive layer because customers increasingly evaluate remote management, grid services, storage compatibility and lifecycle cybersecurity alongside inverter efficiency. Market leadership through 2031 is therefore likely to depend on combining manufacturing scale with localized service, secure digital platforms and compliance with increasingly fragmented national grid and sourcing requirements.
Recent Developments
June 2026: Huawei introduced its next-generation LUTERRA grid-forming energy-storage platform and expanded its strategy around grid-forming renewable-energy systems at Intersolar Europe.
June 2026: SMA introduced a new generation of three-phase hybrid inverters ranging from 5 kVA to 30 kVA with integrated energy management and optional backup functionality.
June 2026: SolarEdge expanded its MultiRange concept across its European commercial and industrial PV inverter portfolio alongside new commercial storage products.
May 2026: Enphase signed another U.S. supply agreement for IQ9 microinverters worth approximately USD 52 million, bringing its announced physical-work-test backlog with TPO providers to approximately USD 873.7 million.
March 2026: SolarEdge launched its next-generation Nexis residential solar-and-storage system in Germany with inverter capacity up to 20 kW and modular storage capability.
January 2026: Sungrow launched the SG465HX next-generation utility-scale string inverter at the World Future Energy Summit.
December 2025: Waaree commissioned a 3.05 GW annual solar inverter manufacturing facility in Gujarat, India.
Market Outlook
The solar inverter market is forecast to increase from approximately USD 18.0 billion in 2026 to USD 23.8 billion in 2031 at a CAGR of 5.8%. Shipment growth will remain considerably stronger than revenue growth because solar capacity additions continue accelerating while inverter prices decline through scale, automation and competition among Chinese manufacturers. More than 600 GW of PV was added during 2025 alone, and the IEA expects solar to provide the majority of worldwide renewable capacity expansion through 2030. String inverters retain the leading architecture as increasingly powerful units expand into utility applications, while standard grid-connected systems remain the largest functionality category even as hybrid inverter demand grows more quickly.
The industry’s value proposition is also changing. Inverters are becoming digitally connected control devices responsible for grid support, battery coordination, remote operation and increasingly household or plant-level energy management. Cybersecurity and grid-forming capability therefore become increasingly important procurement criteria, particularly in countries with high renewable penetration. Asia Pacific remains the largest market through 2031 due to the scale of China and India and the concentration of manufacturing, while Middle East and Africa records the fastest regional growth as utility-scale solar, distributed installations and battery storage expand from a smaller base.
Solar Inverter Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 18.0 billion |
| Total Market Size in 2031 | USD 23.8 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Inverter Architecture, Functionality, End-User, Geography |
| Companies |
|
Market Segmentation
BY INVERTER ARCHITECTURE
Central Inverters
String Inverters
Microinverters
Others
BY FUNCTIONALITY
Standard Grid-Connected Inverters
Hybrid Solar-Storage Inverters
Off-Grid Inverters
BY END USER
Residential
Commercial and Industrial
Utility-Scale
BY GEOGRAPHY
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Australia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Data Sources and Validation
2.4. Market Estimation
2.5. Segment Modelling
2.6. Data Triangulation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Solar Inverter Market Size, 2026-2031
3.3. Inverter Architecture Outlook
3.4. Functionality Outlook
3.5. End-User Outlook
3.6. Regional Opportunity Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Global Solar PV Additions Above 600 GW Annually
4.1.2. Expansion of Distributed Solar PV
4.1.3. Rapid Battery-Storage Deployment
4.2. Market Restraints
4.2.1. Falling Inverter Prices and Revenue Pressure
4.2.2. Supply-Chain Concentration and Cybersecurity Restrictions
4.3. Porter’s Five Forces Analysis
4.4. Industry Value Chain Analysis
4.5. Grid Codes and Regulatory Environment
4.6. Cybersecurity and Supply-Chain Analysis
5. TECHNOLOGICAL OUTLOOK
5.1. Grid-Forming Inverters
5.2. Hybrid Solar-Storage Inverters
5.3. Wide-Bandgap Power Semiconductors
5.4. AI-Based Energy Management
5.5. Remote Monitoring and Cybersecurity
6. SOLAR INVERTER MARKET BY INVERTER ARCHITECTURE
6.1. Introduction
6.2. Central Inverters
6.3. String Inverters
6.4. Microinverters
6.5. Others
7. SOLAR INVERTER MARKET BY FUNCTIONALITY
7.1. Introduction
7.2. Standard Grid-Connected Inverters
7.3. Hybrid Solar-Storage Inverters
7.4. Off-Grid Inverters
8. SOLAR INVERTER MARKET BY END USER
8.1. Introduction
8.2. Residential
8.3. Commercial and Industrial
8.4. Utility-Scale
9. SOLAR INVERTER MARKET BY GEOGRAPHY
9.1. North America
9.1.1. USA
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. Germany
9.3.2. France
9.3.3. United Kingdom
9.3.4. Spain
9.3.5. Italy
9.3.6. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. South Africa
9.4.4. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. India
9.5.3. Japan
9.5.4. South Korea
9.5.5. Australia
9.5.6. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Huawei Digital Power Technologies Co., Ltd.
11.2. Sungrow Power Supply Co., Ltd.
11.3. Ginlong Technologies Co., Ltd. (Solis)
11.4. Growatt New Energy Technology Co., Ltd.
11.5. GoodWe Technologies Co., Ltd.
11.6. SMA Solar Technology AG
11.7. SolarEdge Technologies, Inc.
11.8. Enphase Energy, Inc.
11.9. Sineng Electric Co., Ltd.
11.10. TBEA Sunoasis Co., Ltd.
11.11. Kehua Tech
11.12. Power Electronics S.L.
11.13. Delta Electronics, Inc.
11.14. Fronius International GmbH
11.15. TMEIC Corporation
12. APPENDIX
Navigate
Trusted by the world's leading organizations











