
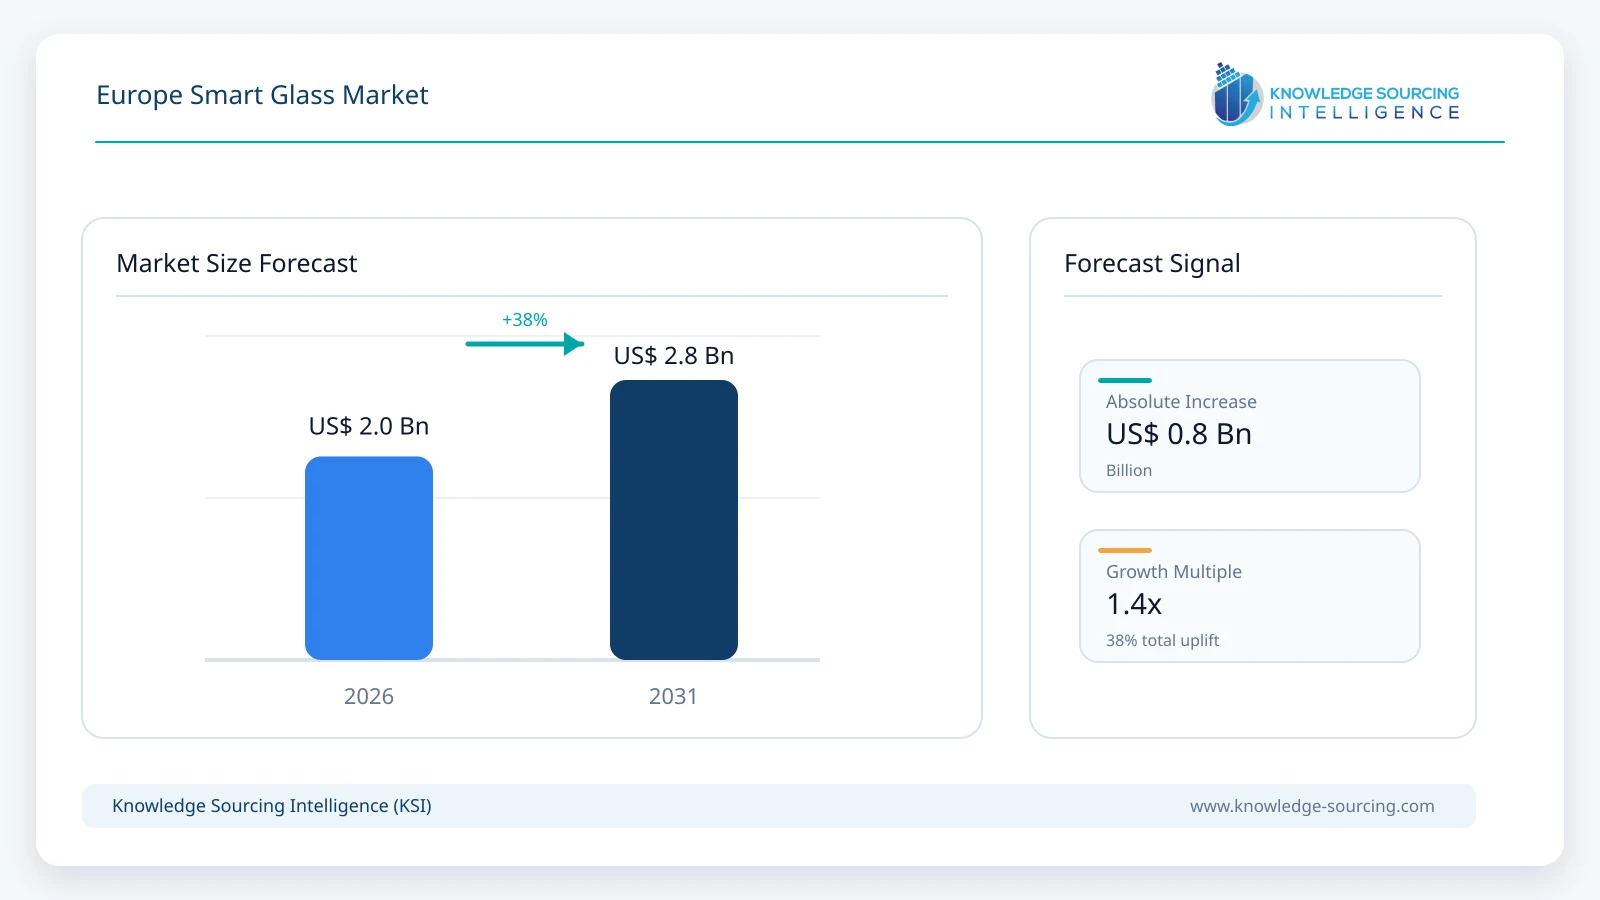
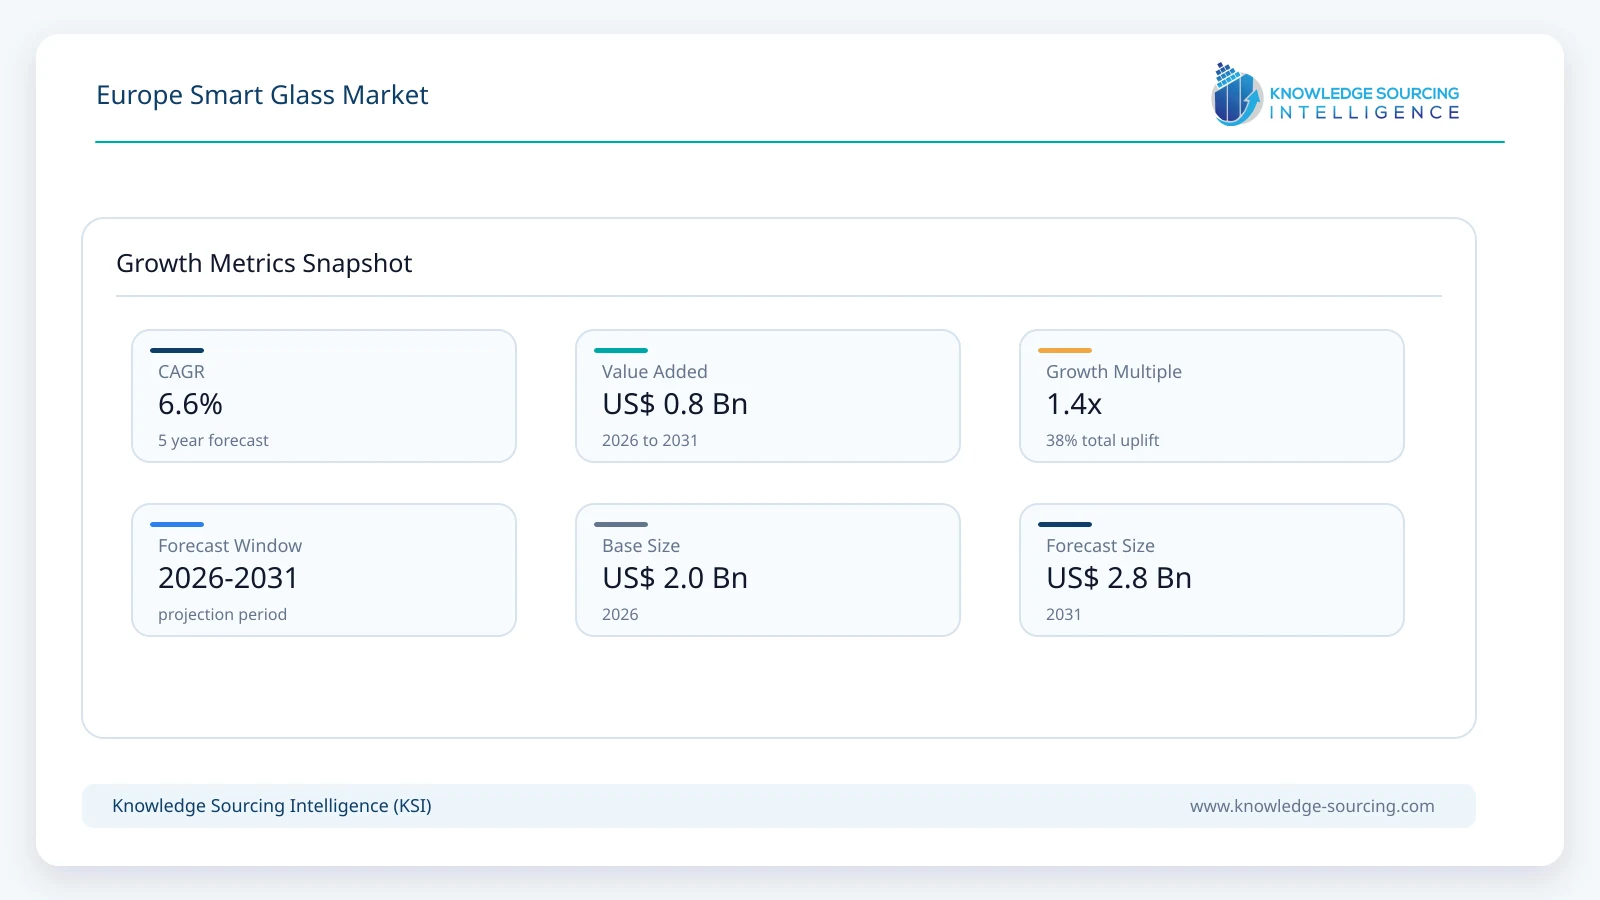
The Europe Smart Glass Market is expected to register 6.6% annual growth, rising from USD 2.05 billion in 2026 to USD 2.82 billion in 2031.
Highlights:
- 1Electrochromic technology accounts for approximately 43% of Europe smart-glass revenue in 2026.
- 2Automotive applications generate about 41% of regional smart-glass market value in 2026.
- 3Germany contributes approximately one-quarter of European smart-glass revenue in 2026.
- 4EU battery-electric cars reached 20.7% of registrations in the first half of 2026.
- 5The revised EPBD is increasing long-term demand for higher-performance and adaptive building envelopes.
- 6Weak construction activity and high installed cost keep smart glazing concentrated in premium applications.
Europe has two distinct smart-glass demand engines. The first is mobility, where premium vehicles, electric powertrains, panoramic roofs and larger glazed surfaces are increasing the value of light-control, privacy and thermal-management technologies. The European Automobile Manufacturers' Association reported that 260 automobile plants operated across the EU and United Kingdom in 2026, including 100 passenger-car plants and 127 facilities assembling battery-electric vehicles. EU car registrations increased in 2025 and accelerated further in the first half of 2026, when battery-electric vehicles reached 20.7% of registrations. This installed industrial base gives electrochromic, SPD and PDLC technologies a credible path from premium models into a broader group of vehicles, although penetration remains far below conventional automotive glazing.
The second demand engine is the built environment. The recast Energy Performance of Buildings Directive entered into force in May 2024 and required national transposition by May 2026. It introduces minimum energy-performance requirements for non-residential buildings and renovation trajectories for residential stock, creating a stronger policy framework for efficient façades, solar control and digitally managed building envelopes. Dynamic glazing can reduce glare and solar heat gain without external blinds while preserving daylight and views, which makes the technology relevant to offices, healthcare, education, airports, hospitality and premium residential projects. However, policy support does not translate directly into rapid smart-glass adoption because conventional high-performance insulating glass, shading systems and films remain substantially cheaper.
The European flat-glass industry also entered the forecast period under pressure. Glass for Europe reported in January 2025 that construction demand was at an all-time low and that almost 20% of EU flat-glass production capacity had closed over the previous ten months. A relatively moderate 2027 growth rate before adoption strengthens as national renovation plans mature, building owners replace façades, and automotive smart-glass content expands. The result is a lower and more conservative trajectory than forecasts that assume immediate double-digit regional growth.
Market Trends
Automotive Smart Glass Is Shifting From Isolated Features to Multi-Surface Integration
European premium vehicle manufacturers are expanding smart glass beyond auto-dimming mirrors and individual sunroofs. Gauzy announced in April 2025 that Mercedes-Benz selected a combined SPD and PDLC stack across approximately 75% of the glazing in its Vision V show car, including side windows, quarter windows and an interior partition. Mercedes-Benz had already used SPD technology in serial-production Magic Sky Control applications. The development illustrates the next phase of automotive smart glass: multiple glazing surfaces can be coordinated for shading, privacy, thermal comfort and display functions. Electrification strengthens the business case because solar heat load directly affects cabin air-conditioning demand and therefore vehicle energy consumption. Adoption remains premium-led, but serial-production experience is reducing integration risk for future platforms.
Building Renovation Is Becoming More Important Than New-Build Demand
Europe's building stock is old, while the annual renovation rate remains low. The revised EPBD is explicitly intended to increase renovation of the worst-performing buildings and requires national building-renovation plans. This shifts the addressable market toward façade replacement and major refurbishment rather than relying only on new offices or institutional buildings. SageGlass installations in France, Switzerland, Norway, Denmark and other European markets demonstrate that electrochromic glazing can be used in both new construction and renovation. The economics are strongest where glare control, cooling load, daylight, occupant comfort and architectural transparency have measurable value, such as offices, universities, healthcare buildings and public institutions.
PDLC and SPD Are Expanding the Market Beyond Exterior Façades
Electrochromic glass remains the highest-value architectural technology, but PDLC and SPD broaden the use case. PDLC provides rapid switching between transparent and privacy states and is increasingly used for partitions, meeting rooms, healthcare areas, hospitality interiors and transportation. SPD offers continuously variable shading and is more closely associated with premium mobility applications. Suppliers are also developing combined stacks, prefabricated units and film-based systems that can simplify installation. This creates a more diverse European market in which smart glass revenue is not dependent on one façade technology or one end-user sector.
Market Drivers
European Vehicle Manufacturing Supports High-Value Smart-Glazing Integration
Europe's automotive base remains one of the largest concentrations of premium vehicle manufacturing in the world. ACEA identifies 260 automobile plants across the EU and United Kingdom, and EU manufacturers spend more than EUR 84 billion annually on automotive R&D. Smart glass benefits from this innovation intensity because advanced glazing is increasingly integrated with panoramic roofs, interior electronics, heads-up displays, privacy functions and thermal management. The transition toward electric vehicles is particularly relevant: battery-electric vehicles captured 20.7% of EU registrations in the first half of 2026, up materially from the prior year. As glass areas increase and fixed mechanical shades are removed, variable-transmission glazing can provide both design and efficiency benefits.
EPBD Implementation Strengthens the Long-Term Economics of Adaptive Façades
The recast EPBD creates a stronger regulatory foundation for building-envelope investment. The directive requires national renovation plans, minimum energy-performance standards for non-residential buildings and progressive improvement of residential building stock. In July 2026, the European Commission opened infringement procedures against all 27 member states for incomplete transposition, underlining both the importance of the rules and the implementation challenge. Smart glass will not be mandated directly, but tighter envelope performance, solar-control requirements and whole-building energy assessments improve the relative value of technologies that dynamically manage heat and daylight.
European Glass Manufacturing and R&D Reduce Supply-Side Barriers
Europe has a deep flat-glass and automotive-glazing supply chain led by Saint-Gobain, AGC, NSG/Pilkington, Guardian and specialist processors. In February 2025, AGC and Saint-Gobain inaugurated the Volta pilot line in the Czech Republic, using a hybrid furnace that is 50% electrified and 50% oxy-gas fired while increasing recycled content. Although Volta is a base-glass decarbonization project rather than a smart-glass line, it demonstrates continued investment in the substrate and fabrication infrastructure on which advanced glazing depends. Regional availability of coatings, laminated glass, electronics integration and building-system expertise lowers the logistical barrier for dynamic-glass projects compared with regions that depend almost entirely on imported finished units.
Market Restraints
High Installed Cost Remains the Main Barrier to Mainstream Adoption
Dynamic glass remains significantly more expensive than conventional low-emissivity glazing, static solar-control coatings, blinds or applied films. The cost gap is magnified in renovation projects because electrical wiring, controls, replacement of insulated glass units and façade access can add installation expense. Smart windows can justify their premium where cooling, glare, occupant comfort or architectural quality have high economic value, but many residential and standard commercial projects still choose cheaper combinations of static glass and shading. This limits penetration even as building-energy regulation becomes stricter.
Weak Construction Activity Slows the Near-Term Architectural Cycle
The European flat-glass sector entered 2025-2026 with unusually weak construction demand. Glass for Europe reported that construction accounts for roughly three-quarters of flat-glass production and that almost 20% of EU production capacity had closed over a ten-month period as demand weakened. New construction is therefore not expected to generate an immediate smart-glass boom. Renovation policy is positive, but project development, financing, permitting and procurement take time.
Segment Analysis
By Technology - Electrochromic Glass
Electrochromic glass is the largest technology segment in Europe because it has the strongest position in commercial façades and an established role in premium transportation. It changes tint through an electrically controlled electrochemical process and can be integrated with building-management systems, daylight sensors and automated controls. The segment is supported by projects from SageGlass and other dynamic-window suppliers across offices, educational facilities and renovation projects. Electrochromic products carry a relatively high unit value and are well suited to exterior applications where continuously variable solar control is more important than instant privacy switching. PDLC is the next major technology by value and is gaining faster in interior privacy applications because switching is rapid and retrofit film formats can reduce installation complexity.
By Application - Automotive
Automotive is the largest application in 2026, ahead of architecture and construction. Europe has a dense premium-vehicle manufacturing base, high panoramic-roof penetration and rapid electrification, all of which increase the value of dynamic solar-control glass. Smart glass is used in dimmable roofs, side windows, mirrors, partitions and concept display surfaces. Architecture remains close behind because commercial façades carry higher smart-glass area per project, but adoption is more dependent on construction cycles and capital budgets. Rail, aerospace and marine applications form a smaller high-value transport segment, while power-generation and specialist industrial uses account for the balance.
By Country - Germany
Germany is the largest national market in Europe because it combines the region's largest premium automotive manufacturing cluster with stringent building standards and a substantial commercial property base. Mercedes-Benz, BMW, Volkswagen Group, Porsche and their supplier networks create a strong route for automotive smart-glass adoption, while energy-efficiency requirements support high-performance glazing in commercial and institutional buildings. France forms the second tier through Saint-Gobain's glass and glazing ecosystem, major automotive production and large public-building renovation programs. The United Kingdom, Italy and Spain follow, with demand driven by commercial real estate, premium vehicles, hospitality and specialist transport applications.
Competitive Environment
Competition in Europe spans integrated glass manufacturers, smart-material specialists, automotive technology suppliers and local fabricators. Saint-Gobain participates through SageGlass in architectural electrochromic windows and through its broader mobility-glazing activities. AGC Glass Europe supplies flat glass, coated products and automotive glazing and has significant regional manufacturing capacity. Gauzy is a leading SPD and PDLC technology supplier with automotive programs involving Mercedes-Benz and other premium OEMs. Gentex remains a major electrochromic automotive supplier, while Research Frontiers licenses SPD technology used in transport applications.
The architectural market is more fragmented. Smartglass International, eyrise, EControl-Glas, ChromoGenics and specialist laminators compete in switchable privacy, solar-control and façade applications. Conventional flat-glass companies such as NSG/Pilkington, Guardian Glass and Glas Trösch are relevant because smart-glass systems frequently depend on their substrates, insulating units, coatings or regional fabrication networks. Competitive differentiation increasingly depends on system integration, electrical controls, façade engineering, warranty support and demonstrated energy performance rather than on the smart film or coating alone.
Recent Developments
July 2026: The European Commission opened infringement procedures against all 27 EU states for incomplete EPBD transposition.
June 2026: ACEA reported 260 automobile plants across the EU and United Kingdom, including 127 assembling battery-electric vehicles.
July 2026: Battery-electric cars reached 20.7% of EU registrations in the first half of 2026, up strongly year over year.
April 2025: Mercedes-Benz selected Gauzy dual SPD and PDLC smart glass across approximately 75% of the Vision V show-car glazing.
February 2025: AGC and Saint-Gobain inaugurated the Volta hybrid flat-glass production line in the Czech Republic.
January 2025: The Saint-Gobain Research Paris extension opened with SageGlass electrochromic glazing integrated into the building envelope.
Europe Smart Glass Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.05 billion |
| Total Market Size in 2031 | USD 2.82 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Technology, Application, Country |
| Companies |
|
Market Segmentation
By Technology
Thermochromic Glass
Suspended Particle Device (SPD) Glass
Electrochromic Glass
Liquid Crystal / PDLC Glass
Photochromic Glass
Others
By Application
Automotive
Architecture and Construction
Transportation
Power Generation
Consumer Electronics
Others
By Country
Germany
France
United Kingdom
Italy
Spain
Rest of Europe
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. European Vehicle Manufacturing Supports High-Value Smart-Glazing Integration
3.1.2. EPBD Implementation Strengthens the Long-Term Economics of Adaptive Façades
3.1.3. European Glass Manufacturing and R&D Reduce Supply-Side Barriers
3.2. Market Restraints
3.2.1. High Installed Cost Remains the Main Barrier to Mainstream Adoption
3.2.2. Weak Construction Activity Slows the Near-Term Architectural Cycle
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Electrochromic Glass
4.2. Suspended Particle Device (SPD) Glass
4.3. Polymer Dispersed Liquid Crystal (PDLC) Glass
4.4. Thermochromic Glass
4.5. Photochromic and Other Responsive Glazing
5. EUROPE SMART GLASS MARKET BY TECHNOLOGY
5.1. Introduction
5.2. Thermochromic Glass
5.3. Suspended Particle Device (SPD) Glass
5.4. Electrochromic Glass
5.5. Liquid Crystal / PDLC Glass
5.6. Photochromic Glass
5.7. Others
6. EUROPE SMART GLASS MARKET BY APPLICATION
6.1. Introduction
6.2. Automotive
6.3. Architecture and Construction
6.4. Transportation
6.5. Power Generation
6.6. Consumer Electronics
6.7. Others
7. EUROPE SMART GLASS MARKET BY COUNTRY
7.1. Introduction
7.2. Germany
7.3. France
7.4. United Kingdom
7.5. Italy
7.6. Spain
7.7. Rest of Europe
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Saint-Gobain
9.2. AGC Glass Europe
9.3. Gauzy Ltd.
9.4. Gentex Corporation
9.5. Research Frontiers Incorporated
9.6. Smartglass International Ltd.
9.7. Merck KGaA
9.8. NSG Group
9.9. Guardian Glass
9.10. Glas Trösch Group
9.11. ChromoGenics AB
9.12. EControl-Glas GmbH & Co. KG
9.13. Polytronix, Inc.
9.14. Halio, Inc.
9.15. Webasto Group
9.16. BOS GmbH & Co. KG
9.17. Isoclima S.p.A.
9.18. Sekisui S-Lec B.V.
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations
Navigate
Trusted by the world's leading organizations











