
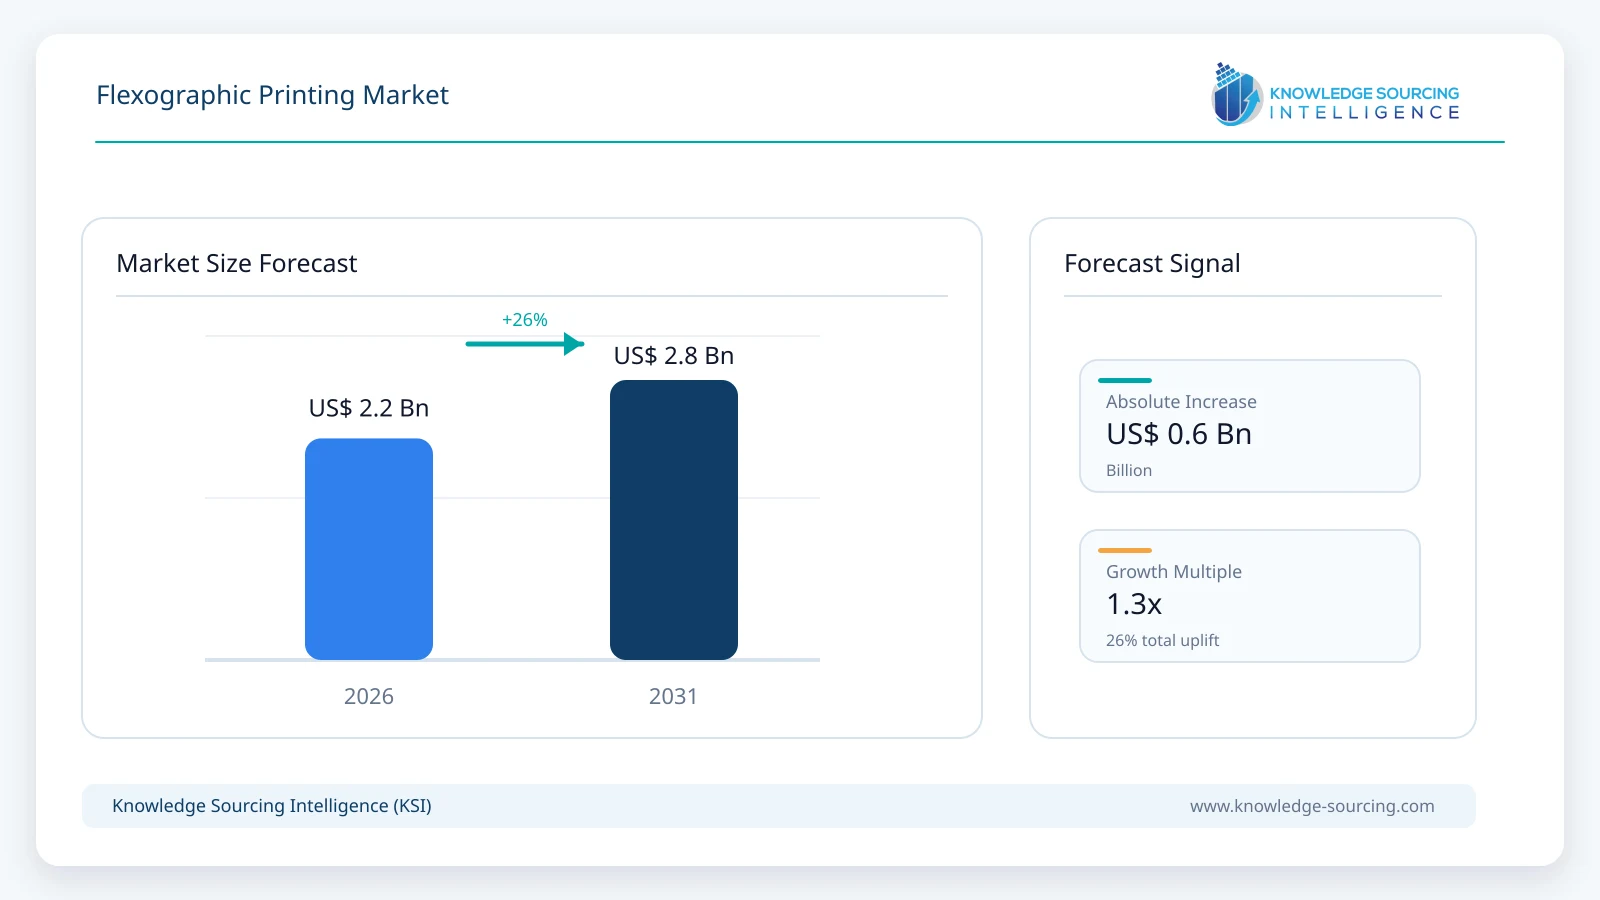
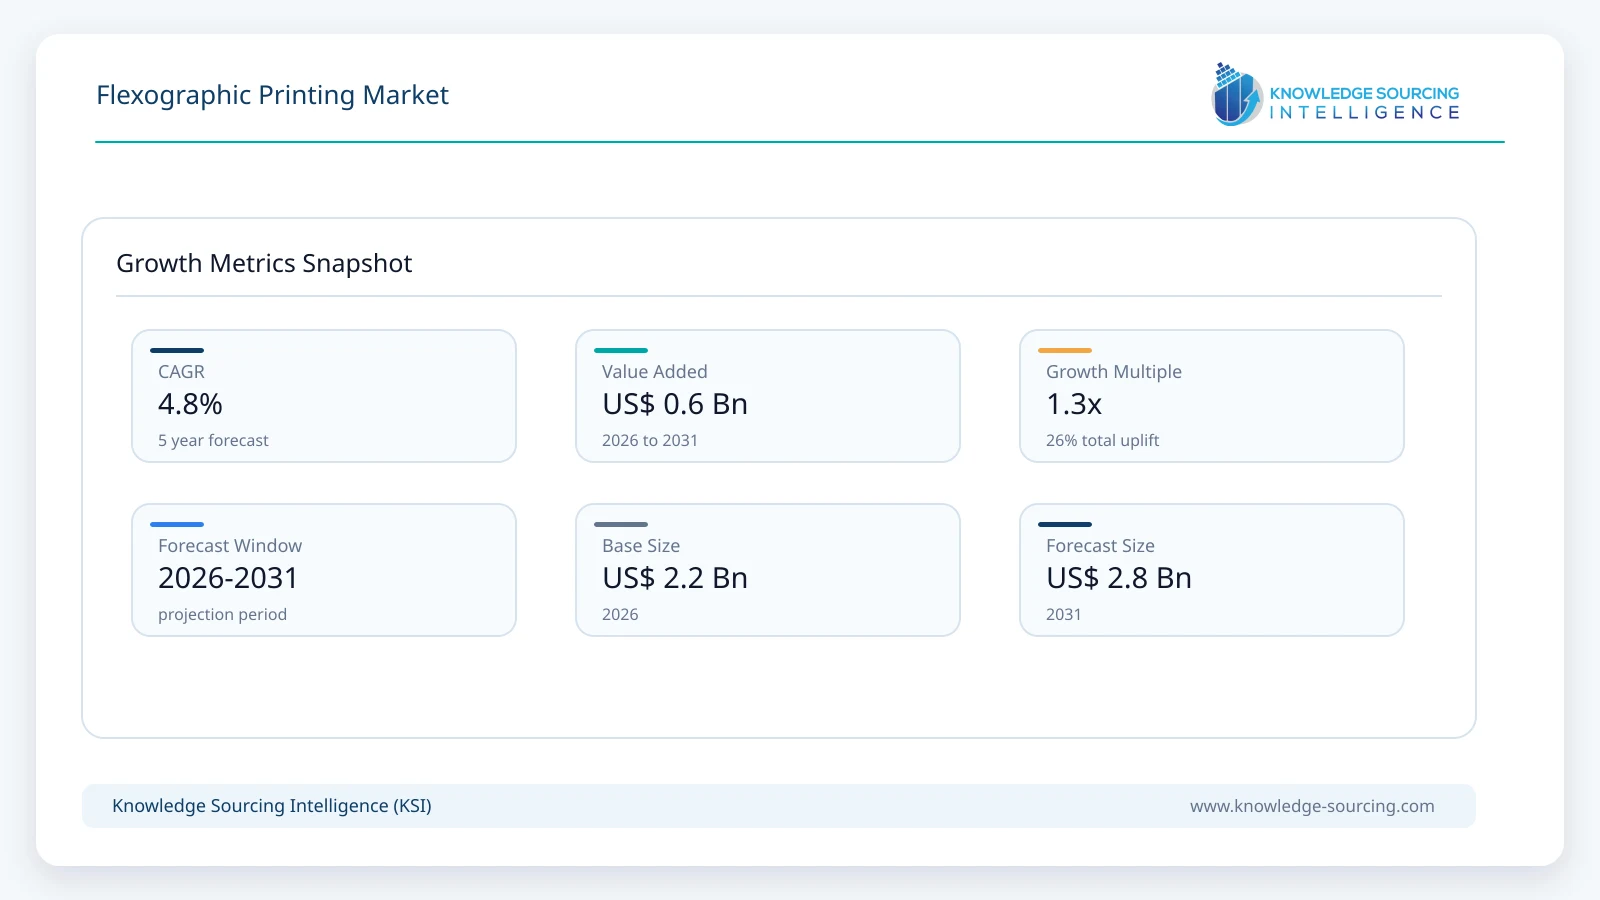
The global flexographic printing market is forecast to grow from USD 2.20 billion in 2026 to USD 2.78 billion in 2031, representing a CAGR of 4.8% during the forecast period.
Highlights:
- 1Central-impression presses are estimated to account for approximately 44.0% of global flexographic printing revenue in 2026.
- 2Wide-web presses are estimated to represent approximately 52.0% of 2026 market revenue because of their high average selling prices and use in flexible packaging.
- 3flexible packaging is estimated to account for approximately 54.0% of global revenue in 2026.
- 4Conventional all-flexo configurations are estimated to represent approximately 78.0% of 2026 market revenue, while hybrid systems continue to gain adoption.
- 5Asia Pacific is estimated to account for approximately 36.0% of global flexographic printing revenue in 2026.
- 6Automation, water-based printing and hybrid flexo-digital configurations are increasingly influencing replacement and new-capacity investment.
Market Overview
The flexographic printing market covers new flexographic presses and integrated press systems sold to label, flexible-packaging, corrugated, folding-carton, and converting operations. It includes central-impression, inline, stack, narrow-web, mid-web, wide-web, and hybrid presses where flexographic printing is a core process.
The study excludes the value of printed packaging output, print services, standalone inks, plates, anilox rolls, substrates, laminators, slitters, and converting that is not integrated into the press.
Flexographic printing remains a core process across flexible packaging, labels, shrink sleeves, pouches, corrugated and selected folding-carton applications. Equipment demand is structurally supported by packaging production but remains cyclical because presses are long-lived capital assets.
BOBST, Koenig & Bauer, Windmoeller & Hoelscher, Mark Andy, Nilpeter, OMET, Comexi, Uteco, Gallus, MPS, SOMA and BW Converting/PCMC maintain active press portfolios across wide-web, narrow-web, central-impression, inline and hybrid architectures.
Flexographic Printing Market Trends
Packaging conversion remains the core demand engine
Flexography remains competitive across flexible packaging, labels, shrink sleeves, pouches, lidding, corrugated, and selected folding-carton applications. Its ability to print on films, foils, papers, and laminates supports a broad installed base.
Automation reduces labor and makeready waste
Modern presses increasingly automate registration, impression setting, web handling, color control, and job recall. SOMA's IRIS and Mark Andy's servo-based Performance Series illustrate the industry's focus on reducing setup waste and dependence on highly experienced operators.
Hybrid printing expands short-run economics
Digital modules are increasingly integrated with flexographic print stations for variable data, white ink, embellishment, primers, and finishing. Hybrid presses allow converters to move shorter jobs into a digital workflow while retaining flexographic units for coatings, spot colors, or longer-run work.
Water-based and energy-efficient workflows support replacement
Brand-owner sustainability requirements are accelerating investment in water-based inks, more efficient drying/curing, lower waste, and press architectures that handle recyclable mono-material films. These drivers support selective replacement even in mature converter markets.
Market Segmentation by Press Architecture
Central-Impression Presses
Central-impression presses are estimated at approximately USD 0.97 billion in 2026. The segment leads revenue because wide-web flexible packaging presses carry high average selling prices and are widely used for films and laminates.
A common impression cylinder supports registration accuracy on stretchable substrates, keeping central-impression architecture important for high-volume flexible packaging.
Market Segmentation by Web Width
Wide-Web Presses
Wide-web presses are estimated at approximately USD 1.14 billion in 2026. The segment represents the largest value pool because these systems serve high-volume flexible packaging and generally carry higher selling prices than narrow-web equipment.
Demand is supported by film, pouch, lidding and other packaging applications requiring high throughput and broad substrate compatibility.
Market Segmentation by Application
Flexible Packaging
Flexible packaging applications are estimated at approximately USD 1.19 billion in 2026. Flexography remains competitive for films, foils, papers and laminates used in food, beverage, household, personal-care and industrial packaging.
Sustainability requirements are supporting investment in water-based inks, lower waste, efficient drying and capable of handling recyclable mono-material structures.
Market Segmentation by Technology Configuration
Conventional All-Flexo Presses
Conventional all-flexo presses are estimated at approximately USD 1.72 billion in 2026. They remain the dominant installed and new-configuration because flexography retains strong throughput economics across medium and long production runs.
Hybrid flexo-digital systems are gaining share in shorter-run and variable-data applications, but all-flexo platforms continue to account for most revenue.
Market Drivers
Packaging Conversion Remains the Core Demand Engine
Flexography remains competitive across flexible packaging, labels, shrink sleeves, pouches, lidding, corrugated, and selected folding-carton applications. Its ability to print on films, foils, papers, and laminates supports a broad installed base.
Automation Reduces Labor and Makeready Waste
Modern presses increasingly automate registration, impression setting, web handling, color control, and job recall. SOMA's IRIS and Mark Andy's servo-based Performance Series illustrate the industry's focus on reducing setup waste and dependence on highly experienced operators.
Hybrid Printing Expands Short-Run Economics
Digital modules are increasingly integrated with flexographic print stations for variable data, white ink, embellishment, primers, and finishing. Hybrid presses allow converters to move shorter jobs into a digital workflow while retaining flexographic units for coatings, spot colors, or longer-run work.
Water-Based and Energy-Efficient Workflows Support Replacement
Brand-owner sustainability requirements are accelerating investment in water-based inks, more efficient drying/curing, lower waste, and press architectures that handle recyclable mono-material films. These drivers support selective replacement even in mature converter markets.
Market Restraints
Capital-intensity and long replacement cycles
Presses can operate for many years with retrofits, service, and component upgrades. BOBST's Services & Performance business grew in 2025 even as new-machine sales declined, highlighting the substitution between new and installed-base upgrades.
Digital inkjet competition
Digital label and packaging presses compete directly for short runs, personalization, and rapid changeovers. Flexo retains a throughput advantage on medium and long runs, but digital technology limits growth in some narrow-web applications.
Cyclical converter investment
New press orders depend on packaging-converter profitability, capacity utilization, financing, and confidence. OEM backlogs can therefore fall sharply even when underlying packaging demand remains resilient.
Regional Outlook
Asia Pacific
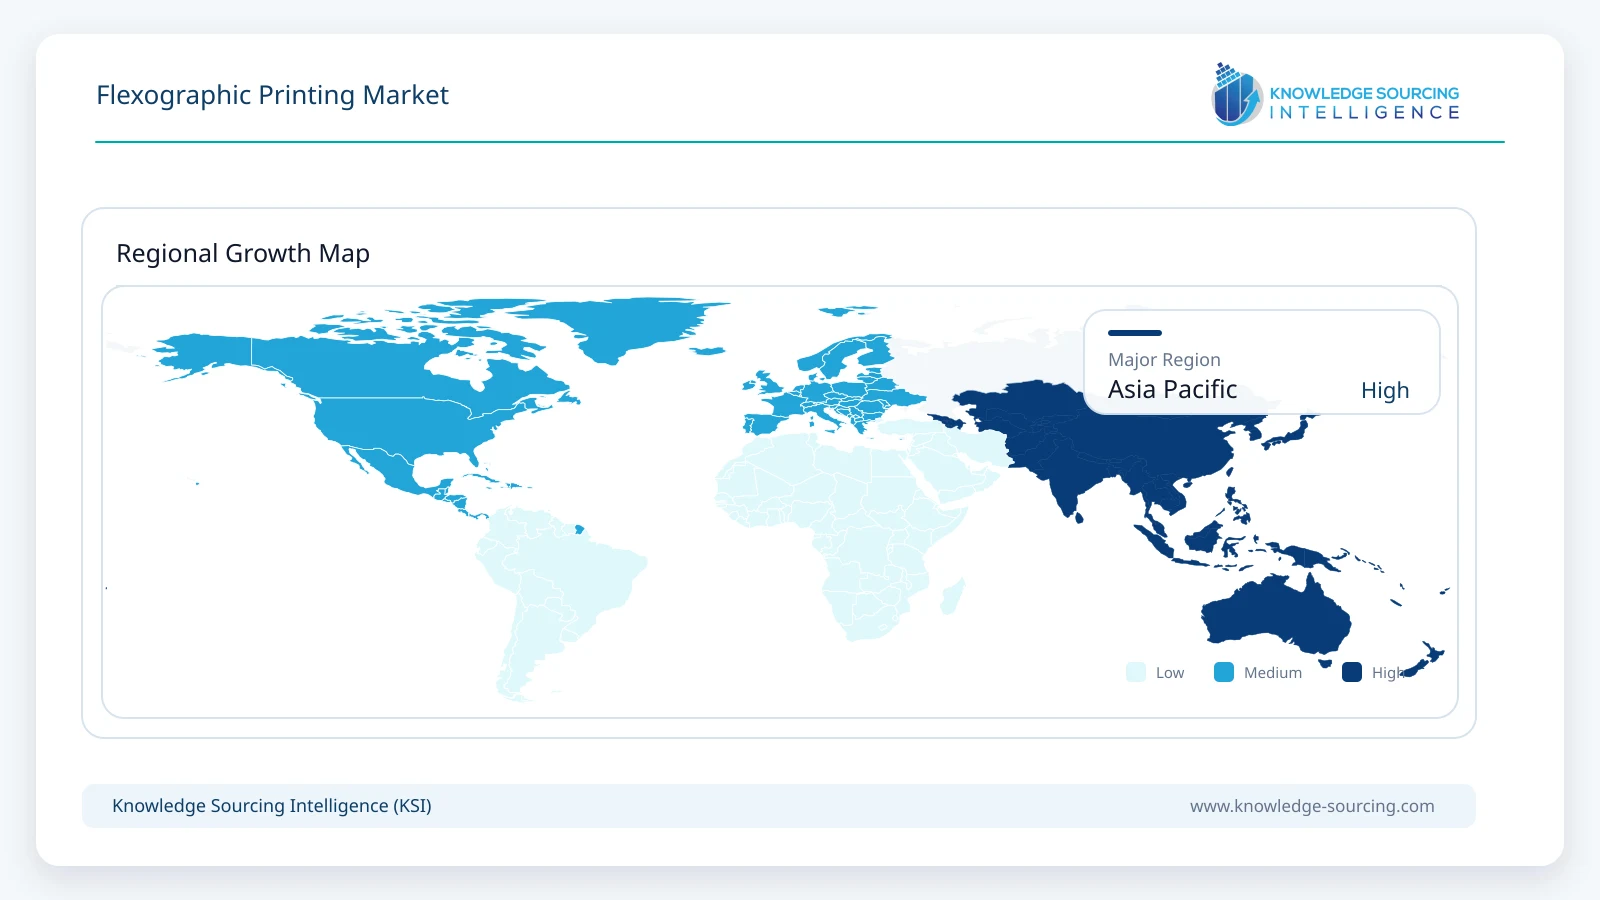
Asia Pacific is estimated at approximately USD 0.79 billion in 2026. The region combines a large packaging-conversion base with ongoing investment in flexible packaging, labels and corrugated capacity across China, India and Southeast Asia.
Regional growth is supported by expanding consumer-goods production, modern retail and converter investment, while competition from local machinery suppliers increases pricing pressure.
Competitive Landscape
The market is fragmented but the high end is concentrated among established OEMs with global service networks. Wide-web central-impression competition differs from narrow-web label competition, so no single supplier dominates all segments.
Competition is centered on manufacturers with active flexographic press portfolios spanning wide-web, narrow-web, central-impression, inline and hybrid systems.
Recent Developments
February 2026: BOBST reported 2025 Printing & Converting sales of CHF 938.6 million, 23.1% below 2024, while flexible-packaging sales were comparatively resilient.
March 2026: Mark Andy announced a new Evolution Series E5 installation at Piroto Labeling in the United Kingdom.
June 2026: SOMA demonstrated its Optima2 and Flexo IPU platform at its Esperienza Center, emphasizing water-based printing and automated register/impression control.
2026: Mark Andy is completing production of new 2200 presses and directing customers toward current Performance, Evolution, and Pro Series platforms.
Market Outlook
Flexographic printing is expected to grow steadily rather than rapidly through 2031. Flexible packaging and labels provide structural demand, but long press lives and digital competition prevent the market from matching the growth rate of printed-packaging output.
The strongest opportunities lie in automated central-impression presses, mid-web flexible packaging, hybrid label platforms, water-based workflows, and retrofit-compatible digital/automation tools. The market measures press sales only and excludes the far larger value of converted packaging.
Flexographic Printing Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.20 billion |
| Total Market Size in 2031 | USD 2.78 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 4.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Press Architecture, Web Width, Application, Geography |
| Companies |
|
Table of Contents
1. INTRODUCTION
1.1 Market Definition and Scope
1.2 Equipment Inclusions and Exclusions
2. RESEARCH METHODOLOGY
2.1 Secondary and Primary Research
2.2 Market Estimation and Forecasting
3. EXECUTIVE SUMMARY
3.1 Market Size and Growth
3.2 Key Findings
4. MARKET DYNAMICS
4.1 Drivers
4.2 Restraints
4.3 Technology Trends
5. FLEXOGRAPHIC PRINTING MARKET BY PRESS ARCHITECTURE
5.1 Central Impression
5.2 Inline
5.3 Stack
5.4 Hybrid and Other
6. MARKET BY WEB WIDTH
6.1 Narrow Web
6.2 Mid Web
6.3 Wide Web
7. MARKET BY APPLICATION
7.1 Flexible Packaging
7.2 Labels
7.3 Corrugated
7.4 Folding Carton and Other
8. MARKET BY GEOGRAPHY
8.1 North America
8.2 South America
8.3 Europe
8.4 Middle East and Africa
8.5 Asia Pacific
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1 OEM Positioning
9.2 Automation and Hybrid Technology
9.3 Recent Developments
10. COMPANY PROFILES
10.1 BOBST Group SA
10.2 Koenig & Bauer AG
10.3 Windmoeller & Hoelscher KG
10.4 Mark Andy Inc.
10.5 Nilpeter A/S
10.6 OMET Srl
10.7 Comexi Group
10.8 Uteco Converting S.p.A.
10.9 Gallus Ferd. Ruesch AG / HEIDELBERG
10.10 MPS Systems B.V.
10.11 SOMA spol. s r.o.
10.12 BW Converting / PCMC
10.13 Edale Ltd.
10.14 Lombardi Converting Machinery S.p.A.
10.15 Focus Label Machinery Ltd.
11. APPENDIX
Navigate
Trusted by the world's leading organizations











