
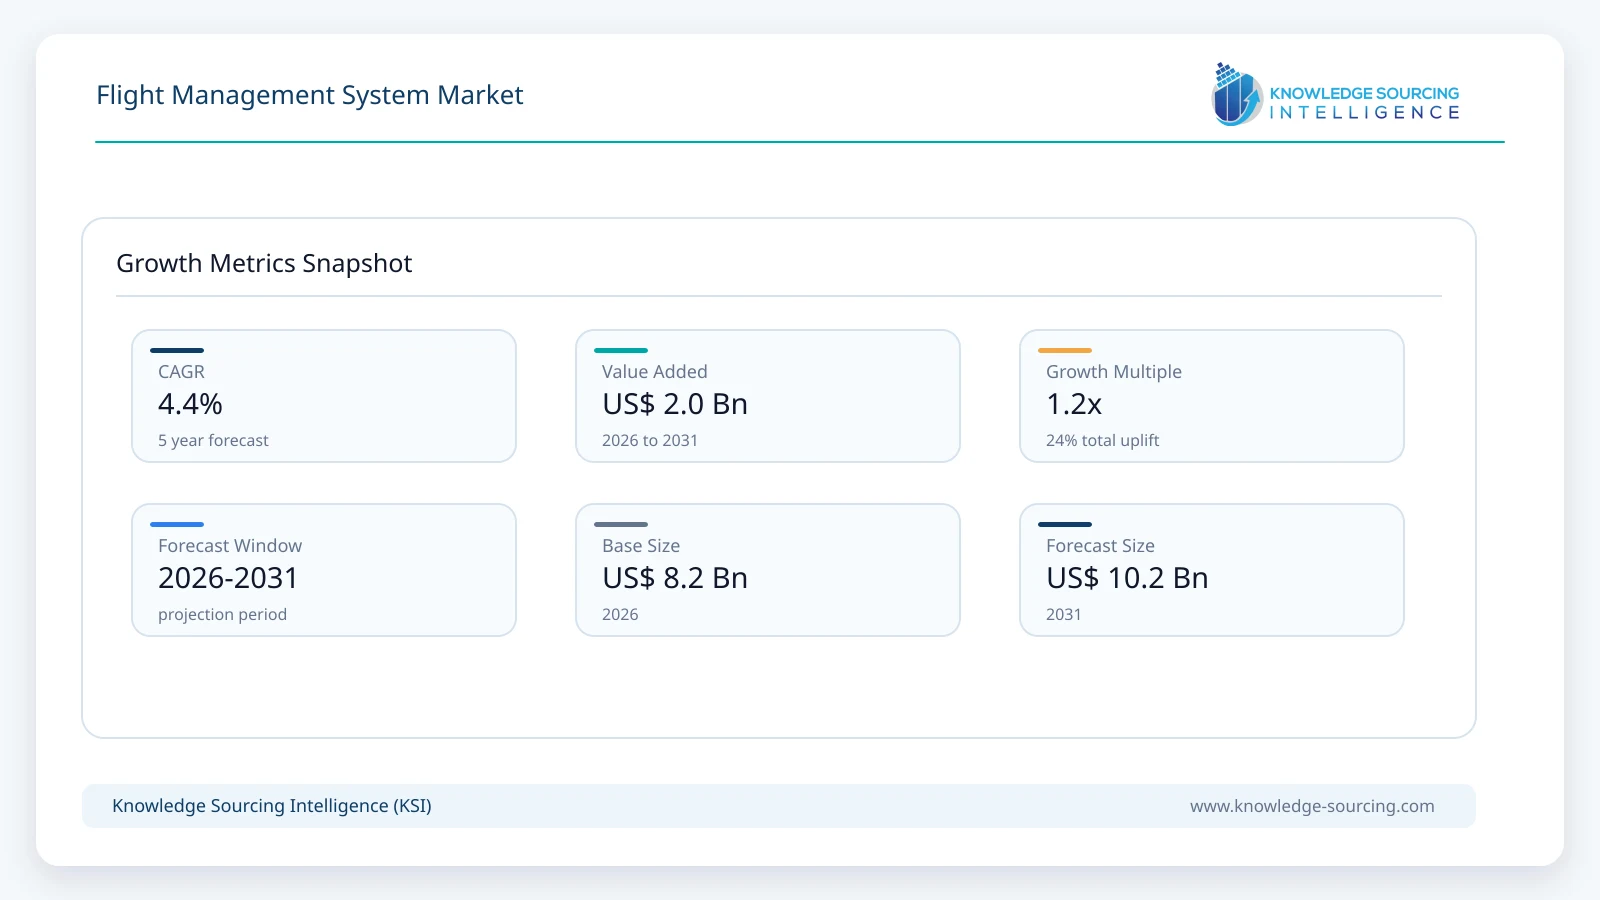
The Flight Management System Market is forecast to grow at a CAGR of 4.4%, reaching USD 10.20 billion in 2031 from USD 8.22 billion in 2026.
Highlights:
- 1Global aviation demand continues to expand the installed base of aircraft requiring flight management, navigation, flight-planning, and avionics capabilities.
- 2ICAO continues advancing Performance-Based Navigation (PBN), supporting demand for FMS capabilities that enable RNAV, RNP, optimized routes, and advanced approach procedures.
- 3Software, navigation databases, connectivity, and digital flight-planning functions are becoming increasingly important alongside certified FMS hardware.
- 4Retrofit programs are gaining importance as operators modernize legacy cockpits while extending aircraft service lives and addressing component obsolescence.
- 5General aviation, business aviation, military aviation, unmanned systems, and emerging advanced air mobility applications are broadening the technology opportunity beyond large commercial aircraft.
- 6Growing GNSS interference risks are increasing the importance of resilient navigation architectures, alternative positioning capabilities, and software-supported navigation continuity.
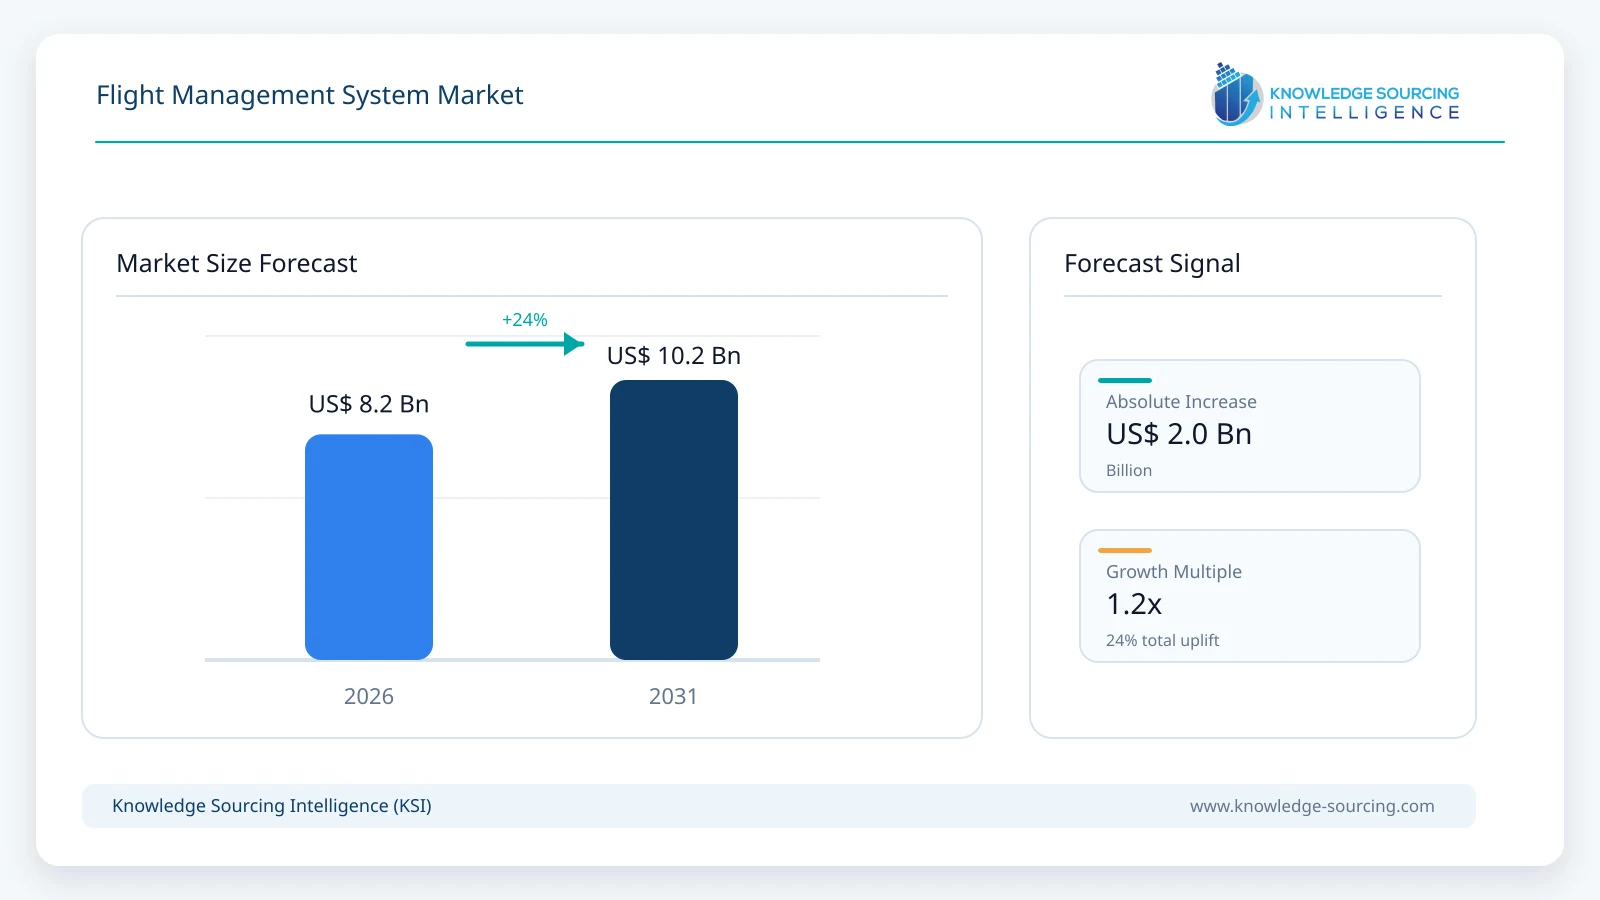
Flight management systems are central avionics platforms that support aircraft navigation, flight planning, route management, performance calculations, and the execution of increasingly sophisticated navigation procedures. Modern FMS architectures integrate information from navigation sensors, databases, aircraft performance models, flight plans, and cockpit systems to help flight crews manage aircraft movement efficiently and safely. The market therefore extends beyond the flight management computer itself to include associated software, navigation databases, integration, upgrades, and selected lifecycle support activities, subject to the revenue boundaries established in the market definition.
Current aviation activity provides a strong underlying demand base. The International Civil Aviation Organization reported in July 2026 that scheduled commercial airlines carried approximately 5 billion passengers on 38 million flights during 2025. ICAO also reported that the global accident rate declined from 2.6 to 2.2 accidents per million departures in 2025. These figures demonstrate the scale of aircraft utilization and the continuing emphasis on safe, reliable aircraft operations.
Airport-level activity provides another indicator of the expanding aviation ecosystem. Airports Council International reported that global airport passenger traffic reached 9.8 billion passengers in 2025, 3.7% higher than 2024 and 6.5% above 2019 levels. The dataset covered 2,817 airports across more than 180 countries and territories. Higher aircraft and airport utilization creates a larger operational environment in which navigation, flight planning, aircraft performance, and cockpit automation technologies must function reliably.
FMS procurement is increasingly influenced by the transition from conventional navigation toward performance-based and digitally integrated operations. ICAO describes PBN as a framework that uses RNAV and RNP specifications to provide more flexible routes and terminal procedures. The organization identifies benefits including improved airspace capacity, lower fuel waste, shorter flight tracks, and improved access to challenging airports. These requirements directly increase the importance of certified onboard systems capable of interpreting navigation databases and executing applicable procedures.
The competitive environment is also changing as aircraft systems become increasingly software-oriented. Airbus described its emerging software-defined aircraft architecture in 2026 as an approach that combines modular computing, connectivity, operational data, and software applications across flight and ground operations. The company noted that conventional aircraft often require physical access and significant downtime for avionics modifications, while future architectures are being designed to support more adaptable software-driven capabilities.
These changes are expanding the commercial definition of FMS value. Airlines and aircraft operators increasingly evaluate systems according to navigation accuracy, certification status, database coverage, interoperability, update processes, computing capability, cybersecurity, maintenance support, and upgrade flexibility. The ability to integrate FMS functions with electronic flight bags, dispatch systems, connected aircraft platforms, and cockpit displays is becoming increasingly relevant to procurement decisions.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Scheduled commercial aviation activity | Approximately 5 billion passengers and 38 million flights in 2025, according to ICAO | High aircraft utilization supports demand for reliable navigation and flight-management capabilities. |
Global airport passenger traffic | 9.8 billion passengers in 2025, according to ACI World | Expanding aviation activity supports aircraft fleet utilization, modernization, and associated avionics requirements. |
Performance-Based Navigation | ICAO maintains a global framework for RNAV and RNP implementation | PBN implementation increases the importance of FMS compatibility with advanced navigation procedures. |
Navigation database updates | Garmin's 2026 FMS documentation specifies 28-day navigation database updates | Recurring database requirements create continuing software and data-management demand. |
Aircraft retrofit activity | Garmin received multiple EASA approvals for retrofit avionics solutions in April 2026 | Regulatory approvals support modernization of legacy cockpits and extend retrofit opportunities. |
GNSS resilience | ICAO and European aviation stakeholders continue addressing GNSS interference and resilience | Navigation resilience is increasing the value of alternative and multi-sensor navigation capabilities. |
Key indicator: ICAO reported approximately 5 billion passengers across 38 million flights in 2025, while ACI World reported 9.8 billion airport passengers during the same year.
Commercial meaning: The scale of aviation activity creates a large installed base requiring new equipment, periodic upgrades, software updates, navigation data, maintenance, and lifecycle support.
Market Drivers
Performance-Based Navigation continues to increase the functional importance of FMS platforms
Performance-Based Navigation remains a central element of global airspace modernization. ICAO defines PBN around navigation performance requirements and the use of RNAV and RNP specifications rather than reliance solely on conventional sensor-specific routes. PBN supports flexible routes, terminal procedures, increased airspace capacity, reduced flight distance, and improved access to challenging airports. FMS platforms provide an important onboard mechanism for managing these procedures because flight crews must load, modify, monitor, and execute applicable routes and approaches using certified navigation databases and aircraft systems.
ICAO's regional implementation work also demonstrates that PBN remains an active modernization program rather than a completed transition. ICAO maintains regional PBN implementation plans for regions including Asia-Pacific, Europe, the Middle East, and South America. European aviation stakeholders have also continued addressing the operational effects of GNSS interference while discussing PBN implementation and navigation resilience.
Fleet expansion and aircraft utilization support demand for new and upgraded FMS equipment
Aircraft deliveries create direct original-equipment demand because new aircraft increasingly use integrated avionics architectures in which navigation, flight management, displays, communication, surveillance, and aircraft performance functions interact digitally. At the same time, high utilization of existing fleets creates aftermarket opportunities for upgrades, replacement systems, database services, and software improvements.
Airbus reported 114 commercial aircraft deliveries during the first quarter of 2026, while noting continued efforts to increase production despite supply-chain constraints affecting aircraft engines. The delivery pipeline illustrates how OEM production creates a continuing requirement for certified avionics systems.
For operators, the procurement decision increasingly extends beyond the initial avionics installation. Long aircraft lifecycles make compatibility with future software releases, navigation databases, maintenance processes, and certification requirements important considerations. Boeing's current BFMS offering illustrates this lifecycle approach by combining the flight management computer with navigation-data services, database-management tools, repairs, training, and support.
Fuel and operational efficiency encourage advanced flight-planning functionality
FMS technology contributes to operational efficiency by supporting flight-plan construction, route optimization, aircraft performance calculations, navigation procedures, and vertical navigation. The commercial value is particularly important for airlines because small improvements in flight distance, fuel planning, arrival sequencing, and operational predictability can accumulate across large fleets.
ICAO specifically identifies reduced fuel waste and shorter optimized flight tracks among the benefits of PBN. Boeing's current flight-performance portfolio also includes solutions such as Jeppesen FliteDeck Advisor and RouteSync, which connect operational data and flight-performance information with aircraft flight-management processes. These developments illustrate the movement toward integrated flight-management ecosystems rather than isolated cockpit computers.
Software-defined aircraft architectures increase the strategic importance of FMS software
Airbus is investing in software-defined aircraft concepts in which high-performance computing, connectivity, modular software, and operational data become more central to aircraft architecture. The company has highlighted the ability of future systems to support remote software updates, data exchange, predictive maintenance, and flight optimization while maintaining segregated and redundant safety architectures.
This direction increases the relative importance of software engineering, configuration management, certification, cybersecurity, and interoperability. FMS suppliers with strong software-development and certification capabilities can therefore capture opportunities beyond hardware replacement. It also creates opportunities for recurring revenues associated with software releases, navigation databases, connected services, and lifecycle upgrades.
Retrofit programs create demand from ageing aircraft and cockpit modernization
Retrofit programs remain important because operators cannot always replace aircraft solely to obtain modern avionics. A certified upgrade can extend aircraft usability while addressing component obsolescence, navigation requirements, display limitations, and changing operational procedures. Garmin's April 2026 announcement of multiple EASA-certified retrofit solutions demonstrates continued demand across helicopters, general aviation, and business aviation. The approvals included GI 275 helicopter upgrades and G5000 upgrades for Cessna Citation XLS+ and XLS Gen2 aircraft.
Universal Avionics also announced in June 2026 that its InSight Flight Display System had been selected for a missionized Learjet 35/36 fleet upgrade. The company stated that the solution was compatible with third-party equipment and its FMS, highlighting the role of interoperability in modernization programs.
Market Restraints and Challenges
Certification requirements increase development costs and extend deployment timelines
FMS technology is safety-critical, making certification a fundamental market barrier. Software, hardware, sensors, displays, databases, and integrated cockpit functions must satisfy applicable airworthiness and operational requirements before they can be used in certified aircraft. Certification becomes more complex when suppliers introduce new computing architectures, software functions, connectivity, or changes affecting established aircraft interfaces.
ICAO's PBN operational-approval framework also demonstrates that navigation capability is not determined solely by equipment installation. Operational authorization depends on aircraft equipment, engineering considerations, procedures, and regulatory oversight. This creates additional requirements for suppliers and operators implementing new navigation capabilities.
Legacy aircraft integration can reduce retrofit economics
Modern FMS equipment must often interact with existing autopilots, flight displays, navigation sensors, communication systems, databases, aircraft wiring, and other avionics. Legacy architectures may therefore require additional engineering, installation work, testing, and certification. Aircraft downtime can further increase the effective cost of an upgrade.
The retrofit market consequently depends on remaining aircraft service life, maintenance schedules, available certification pathways, parts availability, and the economic value of improved functionality. Operators are more likely to undertake modernization when the upgrade resolves an immediate compliance requirement, eliminates obsolete components, improves operational capability, or provides sufficient lifecycle savings.
Navigation resilience and GNSS interference create additional technical requirements
Aircraft increasingly depend on satellite navigation, but aviation authorities and industry stakeholders are paying greater attention to GNSS jamming and spoofing. ICAO and European aviation stakeholders have discussed mitigation measures and operational impacts associated with GNSS interference. The challenge is particularly relevant to FMS architecture because navigation integrity and continuity are fundamental to route management and advanced navigation procedures.
Suppliers are responding by combining satellite navigation with inertial and other navigation inputs. Safran's SkyNaute, for example, combines inertial and GNSS navigation and is designed for aircraft, helicopters, and drones. Safran announced in July 2026 that Eve Air Mobility selected SkyNaute for its eVTOL aircraft program, demonstrating the growing importance of navigation resilience in emerging aircraft architectures.
Cybersecurity and software assurance increase lifecycle costs
Greater connectivity increases the number of interfaces through which aircraft operational information can be exchanged. FMS-related systems can interact with flight-planning applications, navigation databases, electronic flight bags, communication systems, and airline operational platforms. This creates additional cybersecurity and configuration-management requirements.
Suppliers must therefore maintain software assurance, secure update mechanisms, data integrity, access controls, vulnerability-management processes, and appropriate certification documentation. These requirements increase lifecycle expenditure but are increasingly necessary as aircraft become connected digital platforms.
Component qualification and supply-chain constraints can affect delivery schedules
FMS hardware uses certified processors, memory, electronic components, displays, sensors, and other specialized equipment. Substitution is not always straightforward because an alternative component may require additional qualification and certification. The aerospace industry therefore faces a different supply-chain environment from consumer electronics, where manufacturers can often switch components rapidly.
Airbus identified engine availability as one factor affecting its first-quarter 2026 commercial aircraft delivery environment. Although engine supply is not itself an FMS constraint, it illustrates how bottlenecks elsewhere in the aircraft production system can influence the timing of aircraft deliveries and consequently the timing of associated avionics demand.
Major Segment Analysis
Commercial Aircraft
Commercial aircraft are expected to remain a major application segment because airlines operate large fleets, fly high annual utilization levels, and require certified navigation and flight-management systems across long aircraft lifecycles. The segment benefits from both new-aircraft installations and aftermarket modernization. ICAO's 2026 safety data, showing approximately 5 billion passengers and 38 million flights in 2025, provides evidence of the operational scale supporting this installed base.
Commercial FMS requirements are also becoming more software-intensive. Airlines need systems that support PBN procedures, navigation database updates, flight-plan management, performance calculations, vertical navigation, and interaction with other cockpit systems. Boeing's BFMS offering illustrates the broader ecosystem by combining the flight management computer with navigation-data services, database-management tools, repairs, training, and support.
Commercial aircraft operators are also balancing the economics of new installations and retrofits. New aircraft generally provide opportunities for line-fit avionics suppliers, while existing aircraft create demand for upgrades when legacy components become obsolete or operators seek new navigation capabilities. Suppliers that can support both original equipment and aftermarket programs can therefore maintain customer relationships across the aircraft lifecycle.
General Aviation and Business Aviation
General and business aviation provide an important complementary demand base, particularly for integrated flight decks, navigation systems, retrofit equipment, and digital flight-management functions. The segment differs from commercial aviation because aircraft fleets are more heterogeneous and include piston aircraft, turboprops, business jets, helicopters, and other specialized platforms. This diversity creates demand for scalable avionics that can be installed across multiple aircraft types.
Garmin's 2026 product activity demonstrates the importance of this segment. In July 2026, Garmin introduced AXIS, an integrated flight-display family for certified, experimental, and light-sport aircraft. The company stated that AXIS can incorporate IFR GPS, NAV/COMM, and audio-panel functions while supporting connectivity, flight-plan management, and navigation-data capabilities.
Garmin also introduced the G2000 PRIME integrated flight deck in July 2026 for high-performance piston and electric aircraft. The system includes enhanced FMS tools such as modified flight-plan functionality, graphical flight-plan comparisons, emergency-return functions, taxiway routing, and connected aircraft-management capabilities. These developments demonstrate how FMS functionality is increasingly embedded within broader integrated flight-deck architectures.
Regional Analysis
Region | Main Demand Signal | Principal Consideration |
North America | Large installed fleet, commercial aviation, general aviation, business aviation, and defense modernization | Certification, fleet maturity, and retrofit economics |
Europe | Aircraft manufacturing, PBN implementation, avionics modernization, and aerospace technology development | Regulatory requirements and GNSS resilience |
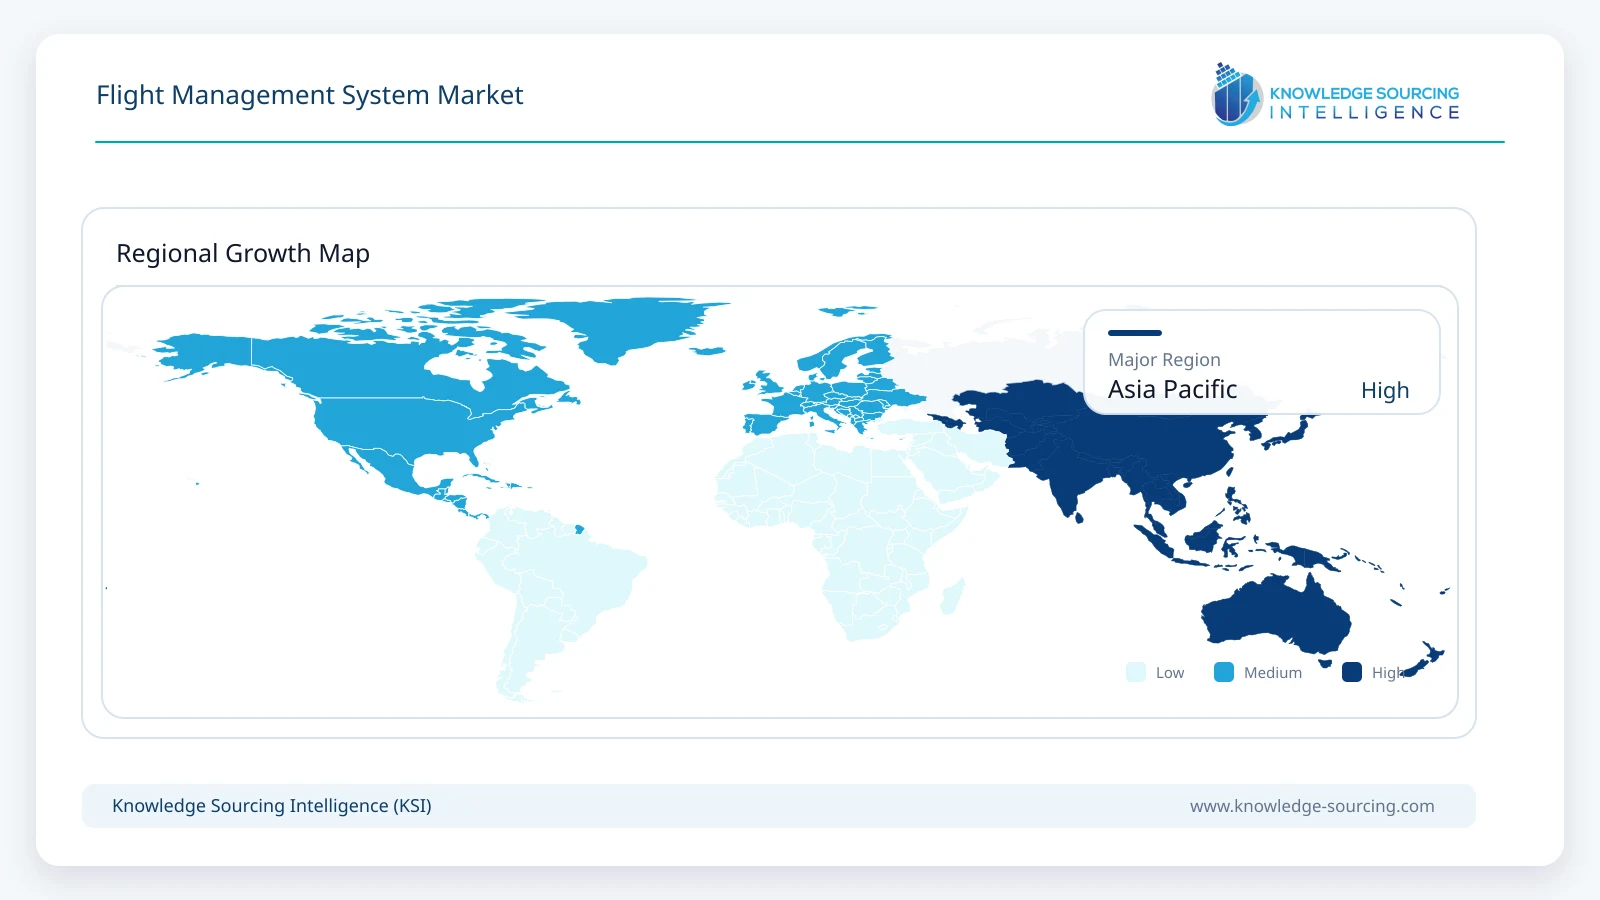
Asia-Pacific | Fleet expansion, passenger growth, airport investment, and emerging aerospace manufacturing | Uneven retrofit and maintenance capabilities across markets |
Middle East and Africa | Fleet expansion, international aviation hubs, defense modernization, and navigation infrastructure | Import dependence and specialist support requirements |
South America | Fleet renewal, regional aviation, PBN implementation, and aerospace manufacturing in Brazil | Capital availability and fleet replacement cycles |
North America
North America remains an important FMS market because of its extensive commercial and general aviation fleet, established aerospace manufacturing base, defense procurement, and mature aftermarket ecosystem. The United States also has a large installed base of business aircraft and general aviation platforms that creates continuing demand for cockpit modernization.
Modernization is supported by the availability of certified retrofit pathways. Garmin's 2026 EASA retrofit announcements, while European in regulatory scope, demonstrate a broader product strategy covering helicopters, business aviation, and general aviation. Universal Avionics also continues developing retrofit solutions and reported an August 2026 Brazilian certification for its InSight integrated flight display system, following FAA, Transport Canada, and EASA approvals.
Europe
Europe combines a major aircraft manufacturing ecosystem with strong regulatory coordination and significant airline activity. Airbus continues developing increasingly software-oriented aircraft architectures, while European aviation authorities and stakeholders continue implementing PBN and addressing GNSS interference. These factors create demand for FMS systems capable of supporting evolving navigation procedures and resilient navigation architectures.
European suppliers also occupy important positions across avionics, navigation, flight controls, and aerospace software. Safran's 2026 technology materials identify avionics, navigation, resilient PNT, critical computing, and cockpit solutions among its aerospace and defense activities.
Asia-Pacific
Asia-Pacific is supported by expanding aviation activity, fleet growth, airport investment, and increasing aerospace capabilities. ACI World reported that Asia-Pacific airports accounted for a substantial share of global passenger activity in 2025, while Tokyo Haneda ranked third globally by passenger traffic.
China, India, Japan, South Korea, and Australia provide different demand profiles. Large commercial fleets support line-fit and aftermarket FMS demand, while developing aerospace industries create opportunities for domestic integration and technology partnerships. Differences in fleet age, maintenance infrastructure, regulatory requirements, and local supplier capabilities will continue influencing procurement patterns across individual markets.
Middle East and Africa
The Middle East benefits from large international airline fleets, major aviation hubs, and continued investment in commercial and defense aviation. High aircraft utilization increases the importance of reliable navigation and flight-management systems, while long-haul operations require broad navigation database coverage and interoperability across international airspace.
African markets are smaller but provide opportunities associated with fleet modernization, navigation infrastructure development, and increasing adoption of performance-based procedures. Supplier success in the region depends not only on product certification but also on technical support, training, database availability, and maintenance capability.
South America
South American demand is influenced by fleet renewal, regional aviation activity, PBN implementation, and aircraft manufacturing capabilities. Brazil has a particularly important aerospace position through Embraer and its supporting industrial ecosystem. ICAO maintains a South American regional PBN implementation plan, demonstrating the continuing policy focus on modern navigation procedures.
Economic conditions and fleet replacement cycles can influence the timing of retrofit projects. Suppliers offering modular equipment, established certification pathways, and regional technical support can therefore have advantages in aftermarket programs.
Competitive Landscape
The FMS competitive environment is characterized by high certification barriers, long aircraft lifecycles, strong OEM relationships, and extensive requirements for software and technical support. Competition increasingly extends beyond the flight management computer to integrated flight decks, navigation databases, connected flight operations, flight-performance software, resilient navigation, and retrofit solutions.
Honeywell Aerospace Inc., Collins Aerospace, Safran Electronics & Defense, Thales, Garmin Ltd., Universal Avionics, Leonardo S.p.A., Boeing/Jeppesen, Lufthansa Systems, and the Skywise organization incorporating NAVBLUE represent important participants across different parts of the FMS and connected flight-management ecosystem. Their roles are not identical: some provide direct FMS products, while others participate through navigation data, integrated avionics, flight operations software, navigation systems, or related cockpit technologies. This distinction should be maintained in competitive benchmarking to avoid overstating direct FMS market participation.
Boeing's BFMS offering provides a useful example of this ecosystem. Boeing manufactures the flight management computer and supports navigation-data services, while its BFMS platform accepts navigation data from Jeppesen, Lufthansa Systems, and NAVBLUE. The platform also includes database-management tools, repairs, training, and support.
The market is therefore likely to reward suppliers that combine certified hardware, software development, navigation data, integration expertise, cybersecurity capabilities, retrofit certification, and global support. New entrants face substantial barriers because safety-critical systems require extensive certification and established aircraft relationships can persist for decades.
Recent Developments
August 2026: Universal Avionics announced Brazilian ANAC certification for its InSight integrated flight-display system. The approval adds Brazil to the existing FAA, Transport Canada, and EASA certification pathways and expands the company's retrofit installation opportunities.
July 2026: Garmin introduced AXIS, a highly integrated flight-display family combining display, navigation, communication, and audio functions. The system supports certified, experimental, and light-sport aircraft and adds connectivity and database-management capabilities relevant to modern FMS architectures.
July 2026: Safran Electronics & Defense announced the selection of its SkyNaute inertial navigation system by Eve Air Mobility for its eVTOL aircraft. Each aircraft is planned to receive two SkyNaute systems, emphasizing resilient navigation for emerging urban air-mobility platforms.
June 2026: Honeywell Aerospace became an independent publicly traded aerospace and defense company following the completion of its spin-off from Honeywell International Inc. The new company began trading on Nasdaq under the ticker HONA on June 29, 2026, creating a dedicated aerospace entity with its own capital allocation and strategic focus.
April 2026: Airbus launched Skywise as a new wholly owned subsidiary integrating NAVBLUE with Skywise digital services. The restructuring combines flight-operations expertise and digital aviation capabilities, with the new entity employing approximately 750 people globally and supporting Airbus and non-Airbus fleets.
Regulatory and Policy Environment
Flight management systems operate under stringent aviation certification and operational requirements because their functions can directly influence aircraft navigation and flight operations. Regulators and aviation authorities assess aircraft equipment, software, hardware, installation, system integration, operational procedures, and continuing airworthiness. Certification requirements can therefore influence product development schedules, engineering costs, retrofit economics, and supplier selection.
ICAO's Performance-Based Navigation framework remains particularly important. ICAO describes PBN as a means of establishing navigation requirements through RNAV and RNP specifications and maintains guidance covering implementation, navigation specifications, operational approval, and performance monitoring. The organization's PBN framework is intended to reduce unnecessary differences between regional navigation applications and support more harmonized international implementation.
GNSS resilience is also becoming an increasingly important policy and operational issue. ICAO regional stakeholders have documented concerns regarding jamming and spoofing and have discussed mitigation measures and continuity-of-operations concepts. These developments increase the importance of navigation architectures that can maintain acceptable performance when satellite signals are degraded or unavailable.
Software assurance and hardware qualification remain important for certified avionics. Industry standards such as RTCA DO-178C for airborne software and DO-254 for airborne electronic hardware form part of the broader certification environment used for safety-critical aviation systems. The exact certification basis varies according to aircraft category, system function, installation, and applicable authority requirements.
Emerging aircraft categories introduce additional regulatory considerations. Urban air mobility and unmanned aircraft require navigation, autonomy, communications, and airspace-integration capabilities that may differ from traditional commercial aircraft. Safran's 2026 SkyNaute selection for Eve Air Mobility demonstrates how navigation technology developed for established civil and defense applications is being adapted for emerging eVTOL platforms.
Outlook and Strategic Implications
The 2026–2031 outlook for the flight management system market is expected to be shaped by commercial aircraft deliveries, aircraft utilization, retrofit demand, PBN implementation, software-defined aircraft architectures, navigation-data requirements, and growing attention to navigation resilience. The market is moving toward integrated and software-centric architectures in which FMS functionality interacts with cockpit displays, flight-planning systems, aircraft performance applications, navigation databases, connectivity platforms, and operational data systems.
Commercial aviation will remain an important demand center because of the size of the global aircraft fleet and high aircraft utilization. ICAO's 2025 activity data and ACI World's 2025 airport traffic data demonstrate that aviation demand has moved beyond the immediate post-pandemic recovery period and reached historically high traffic levels.
Retrofit demand will remain strategically important because many operators will continue extending aircraft service lives. Certified modernization solutions can address obsolete components, improve navigation capability, support new procedures, and enhance cockpit functionality without requiring complete aircraft replacement. Garmin and Universal Avionics' 2026 certification and retrofit announcements illustrate the continuing commercial importance of this pathway.
Software is expected to become a more important competitive differentiator. Airbus' work on software-defined aircraft and Garmin's expansion of integrated flight-management and connected flight-deck functions indicate a broader industry shift toward software-enabled aircraft operations.
Several strategic priorities are likely to shape supplier positioning during the forecast period:
Aircraft manufacturers are expected to favor suppliers that can integrate FMS hardware, software, certification, connectivity, and lifecycle support within increasingly modular aircraft architectures.
Airlines are likely to evaluate FMS solutions according to navigation capability, fuel and operational efficiency, software support, database coverage, reliability, cybersecurity, and total lifecycle cost.
Avionics suppliers will continue investing in integrated computing, connected flight decks, navigation resilience, software upgrades, and retrofit certification.
General and business aviation suppliers are expected to emphasize modular installation, simplified upgrades, integrated displays, connectivity, database automation, and compatibility across diverse aircraft platforms.
Defense suppliers will continue emphasizing resilient positioning, navigation and timing, secure communications, mission-specific navigation, interoperability, and long-term platform support.
Regulators and air navigation stakeholders will continue emphasizing PBN implementation, navigation resilience, software assurance, cybersecurity, and safe integration of emerging aircraft into increasingly digital airspace environments.
Competitive advantage will increasingly depend on the ability to provide certified and interoperable FMS solutions across the aircraft lifecycle. Hardware reliability will remain fundamental, but software functionality, navigation-data quality, database-update processes, cybersecurity, connectivity, certification expertise, and retrofit capability will increasingly determine supplier differentiation.
The market should therefore be viewed as an interconnected ecosystem rather than a standalone avionics-computer category. Direct FMS manufacturers compete alongside navigation-data providers, integrated avionics suppliers, flight-operations software companies, and navigation-technology specialists. This structure creates opportunities for both established aerospace companies and specialized technology providers, while certification requirements and long customer qualification cycles continue to protect incumbent positions.
Emerging aircraft platforms may provide an additional long-term opportunity. Safran's SkyNaute selection for Eve Air Mobility, Garmin's expansion into electric and advanced general-aviation aircraft, and Airbus' development of software-defined aircraft architectures demonstrate that future navigation and flight-management requirements are extending into new aircraft configurations.
Overall, the 2026–2031 market outlook is closely connected to the modernization of global aviation infrastructure and aircraft technology. Suppliers that can combine certified navigation performance with software flexibility, resilient positioning, digital connectivity, and lifecycle support are positioned to address the broadest range of emerging requirements across commercial aviation, general aviation, business aviation, defense, unmanned systems, and advanced air mobility.
Source and methodology note: Market-size and CAGR figures should be inserted only after reconciliation with the final forecast model and should use one consistent base year, forecast year, currency, and CAGR calculation. The qualitative analysis above relies on primary or authoritative sources, including ICAO, ACI World, Airbus, Boeing, Honeywell Aerospace, Garmin, Safran, Thales, and Universal Avionics. No syndicated market-research company estimates have been used to substantiate the qualitative market claims.
Flight Management System Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 8.22 billion |
| Total Market Size in 2031 | USD 10.20 billion |
| Forecast Unit | Billion |
| Growth Rate | 4.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Aircraft Type, Fit, Installation Type, Geography |
| Companies |
|
Market Segmentation
By Component
- Hardware
- Software
By Aircraft Type
- Commercial Aircraft
- Military Aircraft
- General Aviation
- Unmanned Aerial Systems (UAS)
- Urban Air Mobility (UAM)
By Fit
- Line Fit
- Retrofit
By Installation Type
- Single-FMS
- Dual/Triple-Redundant FMS
By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Others
- Europe
- United Kingdom
- Germany
- France
- Italy
- Others
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Israel
- Others
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Currency
1.5. Assumptions
1.6. Base and Forecast Years Timeline
1.7. Limitations of the Study
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Sources
2.3. Market Estimation and Forecasting
2.4. Data Triangulation
3. EXECUTIVE SUMMARY
4. MARKET DYNAMICS
4.1. Market Segmentation
4.2. Market Drivers
4.3. Market Restraints
4.4. Market Opportunities
4.5. Porter’s Five Forces Analysis
4.5.1. Bargaining Power of Suppliers
4.5.2. Bargaining Power of Buyers
4.5.3. Threat of New Entrants
4.5.4. Threat of Substitutes
4.5.5. Competitive Rivalry
4.6. Market Life Cycle Analysis - Regional Snapshot
4.7. Market Attractiveness
5. FLIGHT MANAGEMENT SYSTEM MARKET BY COMPONENT
5.1. Hardware
5.2. Software
6. FLIGHT MANAGEMENT SYSTEM MARKET BY AIRCRAFT TYPE
6.1. Commercial Aircraft
6.2. Military Aircraft
6.3. General Aviation
6.4. Unmanned Aerial Systems (UAS)
6.5. Urban Air Mobility (UAM)
7. FLIGHT MANAGEMENT SYSTEM MARKET BY FIT
7.1. Line Fit
7.2. Retrofit
8. FLIGHT MANAGEMENT SYSTEM MARKET BY INSTALLATION TYPE
8.1. Single-FMS
8.2. Dual/Triple-Redundant FMS
9. FLIGHT MANAGEMENT SYSTEM MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. United Kingdom
9.3.2. Germany
9.3.3. France
9.3.4. Italy
9.3.5. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. United Arab Emirates
9.4.3. Israel
9.4.4. Others
9.5. Asia-Pacific
9.5.1. China
9.5.2. Japan
9.5.3. India
9.5.4. Australia
9.5.5. South Korea
9.5.6. Others
10. COMPETITIVE INTELLIGENCE
10.1. Company Benchmarking and Analysis
10.2. Product and Technology Comparison
10.3. Recent Investments, Partnerships, Contracts, and Deals
10.4. Strategies of Key Players
11. COMPANY PROFILES
11.1. Honeywell International Inc.
11.2. Jeppesen, a Boeing Company
11.3. Collins Aerospace
11.4. Safran Electronics & Defense
11.5. Lufthansa Systems
11.6. Leonardo S.p.A.
11.7. Universal Avionics Systems Corporation
11.8. Thales Group
11.9. Garmin Ltd.
11.10. NAVBLUE
Navigate
Trusted by the world's leading organizations











