
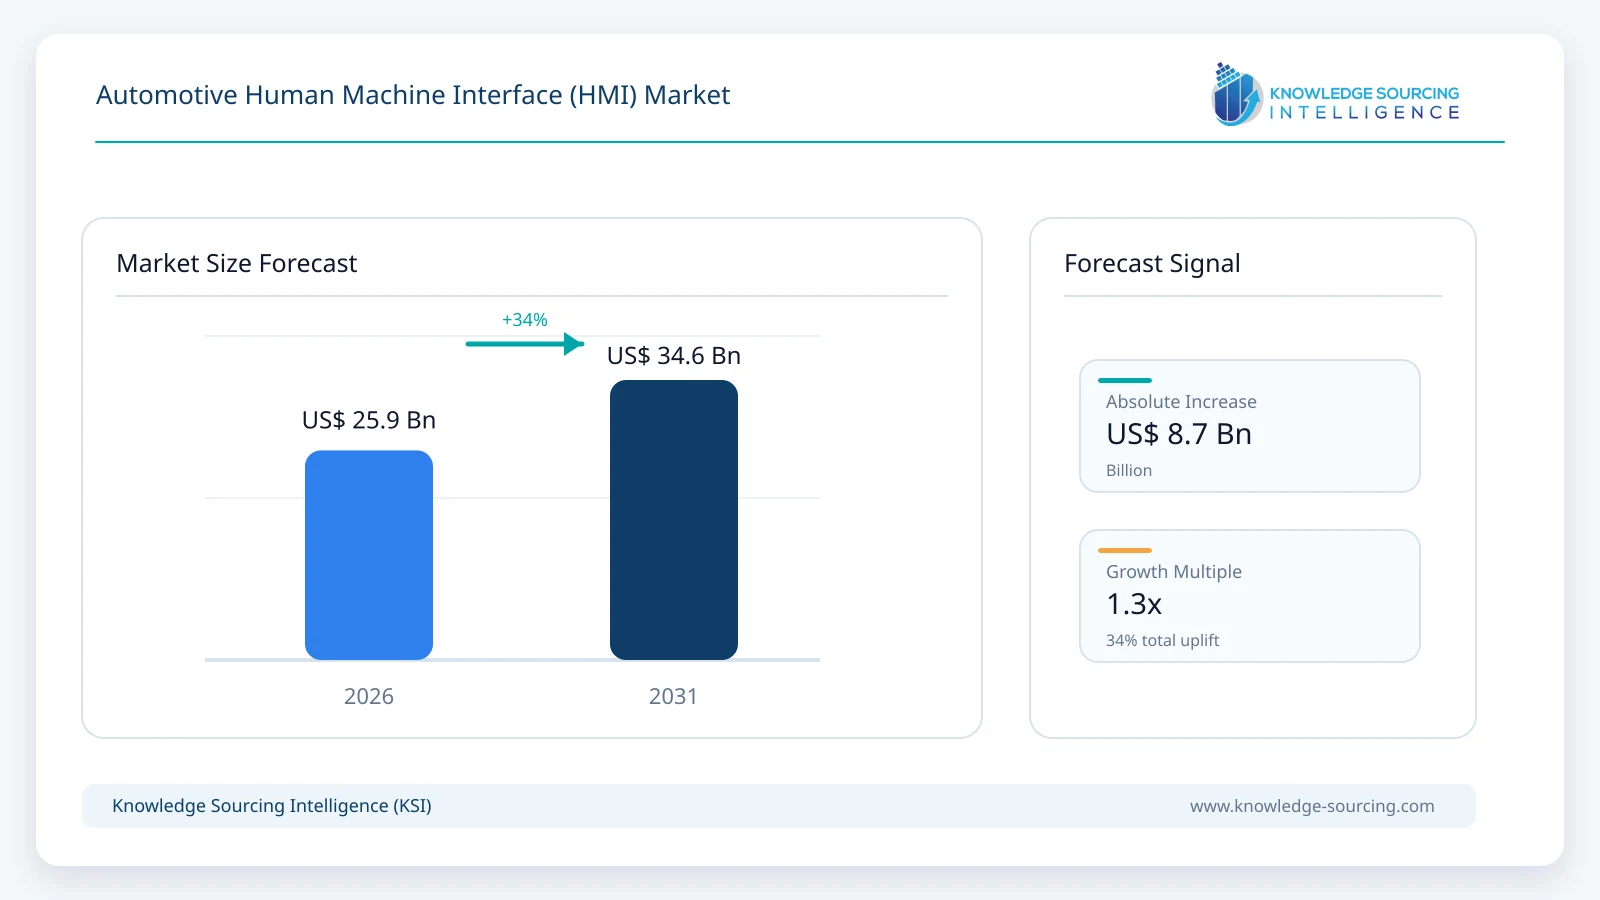
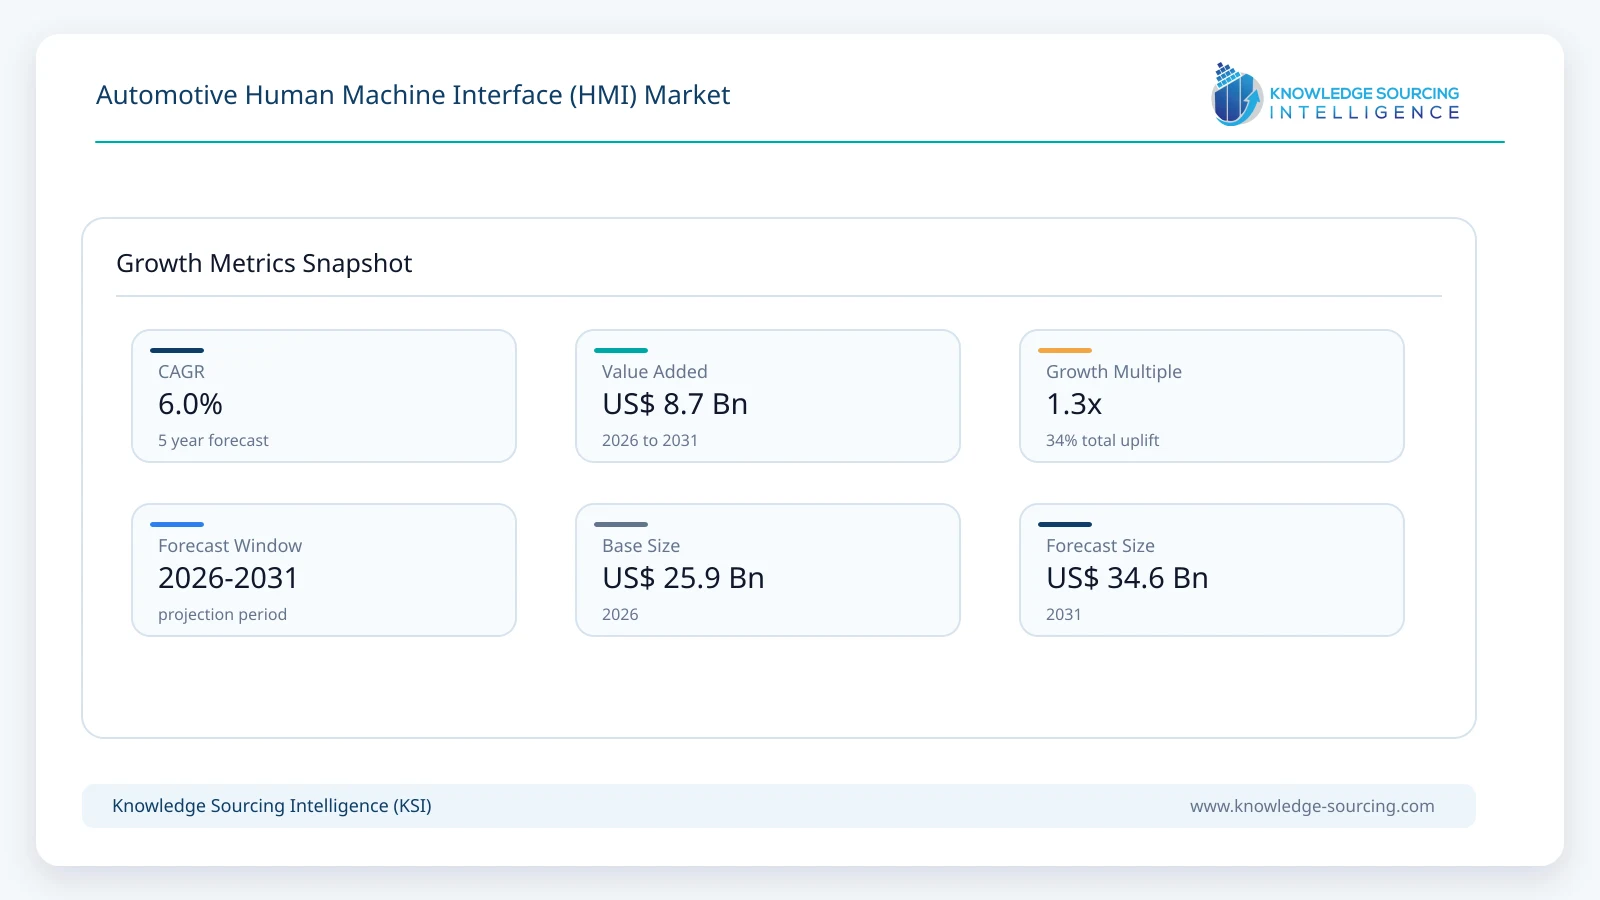
The Automotive Human Machine Interface (HMI) Market is forecast to grow at a CAGR of 5.96%, reaching USD 34.6 billion in 2031 from USD 25.9 billion in 2026.
Highlights:
- 1AI and Intuitive InteractionAutomotive HMI systems are increasingly incorporating artificial intelligence, including natural language processing, to support more intuitive driver and occupant interaction, moving away from rigid menu structures toward conversational interfaces.
- 2Software-Defined Vehicle (SDV) ArchitecturesThe industry-wide transition toward software-defined vehicle architectures is reshaping HMI development, enabling post-sale updates, feature-on-demand subscriptions, and greater functional flexibility throughout the vehicle’s lifecycle.
- 3Multimodal Interface ExpansionThere is a rapidly expanding demand for multimodal interfaces that combine various sensory inputs, such as head-up displays (HUD), advanced voice interaction, and haptic feedback surfaces, to improve safety and ease of use.
- 4Centralized Cockpit ConsolidationOEMs are consolidating multiple display and control functions, historically managed by separate Electronic Control Units (ECUs), into centralized cockpit computing platforms to improve system integration, reduce wiring complexity, and enhance scalability.
The Global Automotive Human Machine Interface (HMI) market encompasses the sophisticated hardware and software ecosystems that facilitate the flow of information between a vehicle’s occupants and its internal functions. Modern HMI development is no longer a localized design effort but a comprehensive architectural strategy involving high-performance computing (HPC), cloud-based over-the-air (OTA) updates, and multimodal interaction. To optimize the user experience, manufacturers are employing artificial intelligence and edge computing to ensure that information, ranging from real-time navigation and battery health to safety alerts, is presented clearly without causing driver distraction. As vehicles transition into "mobile living spaces," the HMI acts as the command center, integrating diverse inputs like gesture recognition, voice commands, and augmented reality (AR) to create a seamless digital environment.
Market Dynamics
Market Drivers
Integration of ADAS and Safety Systems: One of the primary drivers is the increasing integration of advanced driver assistance systems (ADAS). As these systems provide more complex situational data, there is a necessity for HMI platforms that can present critical information clearly and intuitively to ensure driver safety and situational awareness.
Connectivity and Digital Services: The expansion of connected vehicle services, including real-time navigation and remote diagnostics, requires robust interfaces capable of managing large volumes of data. The growth of electric vehicles (EVs) specifically demands specialized HMI modules for charging management and energy optimization.
Consumer Experience Expectations: Modern buyers increasingly view interface quality as a key differentiator. The demand for "smartphone-like" responsiveness and seamless integration with personal digital ecosystems is driving OEMs to invest heavily in high-resolution touchscreens and sophisticated operating systems.
Rise of Electric and Autonomous Mobility: The shift toward electrification requires new interface paradigms for monitoring battery status and energy recovery. Furthermore, as vehicles move toward higher levels of autonomy, the HMI’s role shifts from a driving tool to an infotainment and productivity hub.
Market Restraints and Opportunities
The Automotive HMI market faces challenges regarding high development costs, system complexity, and significant concerns over driver distraction. High-performance processors and large-format displays increase the vehicle's bill of materials, often confining the most advanced features to the premium segment. Cybersecurity also remains a critical hurdle as interfaces become more connected to external networks. However, massive opportunities exist in the democratization of HMI technology. Scalable, modular platforms allow for the introduction of digital interfaces in mid-range and entry-level models. Advances in AR and AI-based assistants provide OEMs with new ways to differentiate their brand identity. As mobility becomes more shared and autonomous, HMI software will emerge as the primary revenue generator through digital services and personalized user profiles.
Raw Material and Pricing Analysis
The automotive HMI market is sensitive to fluctuations in the availability and pricing of electronic components and display materials. Semiconductors used in graphical processing, system-on-chip solutions, and memory components represent a significant portion of HMI system costs. Disruptions in semiconductor supply chains can directly affect production schedules and pricing for cockpit electronics.
Display technologies also influence cost structures. The transition from conventional LCD panels to OLED and other advanced display types increases dependence on specialized materials and manufacturing processes. In addition, haptic actuators and sensor components rely on specific metals and electronic materials that are subject to global commodity price movements. These factors collectively contribute to pricing variability and encourage OEMs to pursue long-term supplier agreements and platform standardization.
Supply Chain Analysis
The supply chain for automotive HMI systems is characterized by high specialization and global interdependence. Semiconductor fabrication and display panel production are concentrated in East Asia, making the market sensitive to regional disruptions. Tier-1 suppliers play a central role by integrating hardware components with embedded software and ensuring compliance with automotive quality standards.
The traditional just-in-time manufacturing model used in the automotive sector exposes HMI supply chains to logistical risks, including shipping delays and trade policy changes. In response, OEMs and suppliers are increasingly exploring regional manufacturing and assembly options to reduce lead times and improve resilience. Localization of software development is also becoming more common, allowing interfaces to be adapted to regional language, regulatory, and consumer requirements.
Government Regulations
Jurisdiction | Regulatory Focus | Market Impact |
United States | Driver distraction guidelines and vehicle safety standards | Encourages voice-based controls and reduced reliance on visual-manual interaction |
European Union | Vehicle safety assessment protocols and interface usability | Influences the balance between touch interfaces and physical or haptic controls |
China | Intelligent connected vehicle standards and data governance | Requires compliance with cybersecurity and data localization rules |
India | Automotive safety and driver alert regulations | Expands baseline demand for digital clusters and warning interfaces |
Key Developments
September 2026: HARMAN International joined SDVerse, offering digital cockpit HMI engineering services covering infotainment, digital instrument clusters and head-up displays through reusable assets and AI-assisted development.
July 2026: Rightware released Kanzi 4.1, adding ray tracing, Figma importing, AI assistance and automotive project templates for creating advanced three-dimensional vehicle HMI experiences.
July 2026: Panasonic Automotive Systems announced Mazda’s adoption of its cockpit domain controller for the all-new CX-5, integrating infotainment, head-up display and instrument-cluster functions.
June 2026: Visteon Corporation announced its 12.3-inch Narrow Border Driver Display in the newly launched Lexus ES, marking Visteon’s first production program for Lexus driver-information systems.
Market Segmentation
By Product Type: Heads-up Display (HUD)
The heads-up display segment has gained critical importance as a driver-focused interface designed to present essential information within the driver’s primary field of view. By projecting data such as vehicle speed, navigation cues, and safety alerts directly onto the windshield, HUD systems significantly reduce the need for drivers to shift their attention away from the road. This functional role has positioned HUDs as a safety-oriented component rather than a purely luxury feature. Recent developments include the transition to augmented reality (AR) HUDs, which can highlight lane markings or identify hazards in real-time, further strengthening the link between HMI and active safety systems.
By Vehicle Type: Passenger Vehicle
Passenger vehicles account for the largest share of HMI demand, driven by intense competition among OEMs to provide superior in-cabin digital experiences. Features such as digital instrument clusters, voice-based controls, and smartphone integration are now widely expected across multiple price segments. The growth of electric passenger vehicles reinforces this trend, as these vehicles rely heavily on digital interfaces to communicate energy usage and charging station locations. Additionally, the emergence of shared mobility models is increasing the demand for personalized HMI profiles that can instantly adapt to different drivers via cloud-based software.
By Application: Infotainment Systems
Infotainment represents a core application for HMI software, bridging the gap between vehicle functions and consumer electronics. These systems manage audio, video, and social connectivity, often serving as the primary visual element in the vehicle's center stack. Modern HMI optimization allows for these systems to be updated over-the-air, ensuring that the vehicle's interface remains current with the latest apps and services. As passenger vehicles transition toward higher levels of automation, the infotainment application is expected to expand into a full-scale entertainment and office suite.
By Offerings: Software
Software has become the most dynamic component of the HMI market. While hardware like screens and buttons provide the physical interface, the software layer, including operating systems, middleware, and UI/UX design, determines the actual user experience. Software allows for the implementation of advanced Pricing Algorithms for features-on-demand, real-time demand forecasting for EV charging, and AI-driven personalization. The move toward a "software-defined vehicle" means that the HMI software is no longer static; it is a living platform that evolves through continuous updates, creating new revenue models for manufacturers and service providers.
Regional Analysis
North America Market Analysis
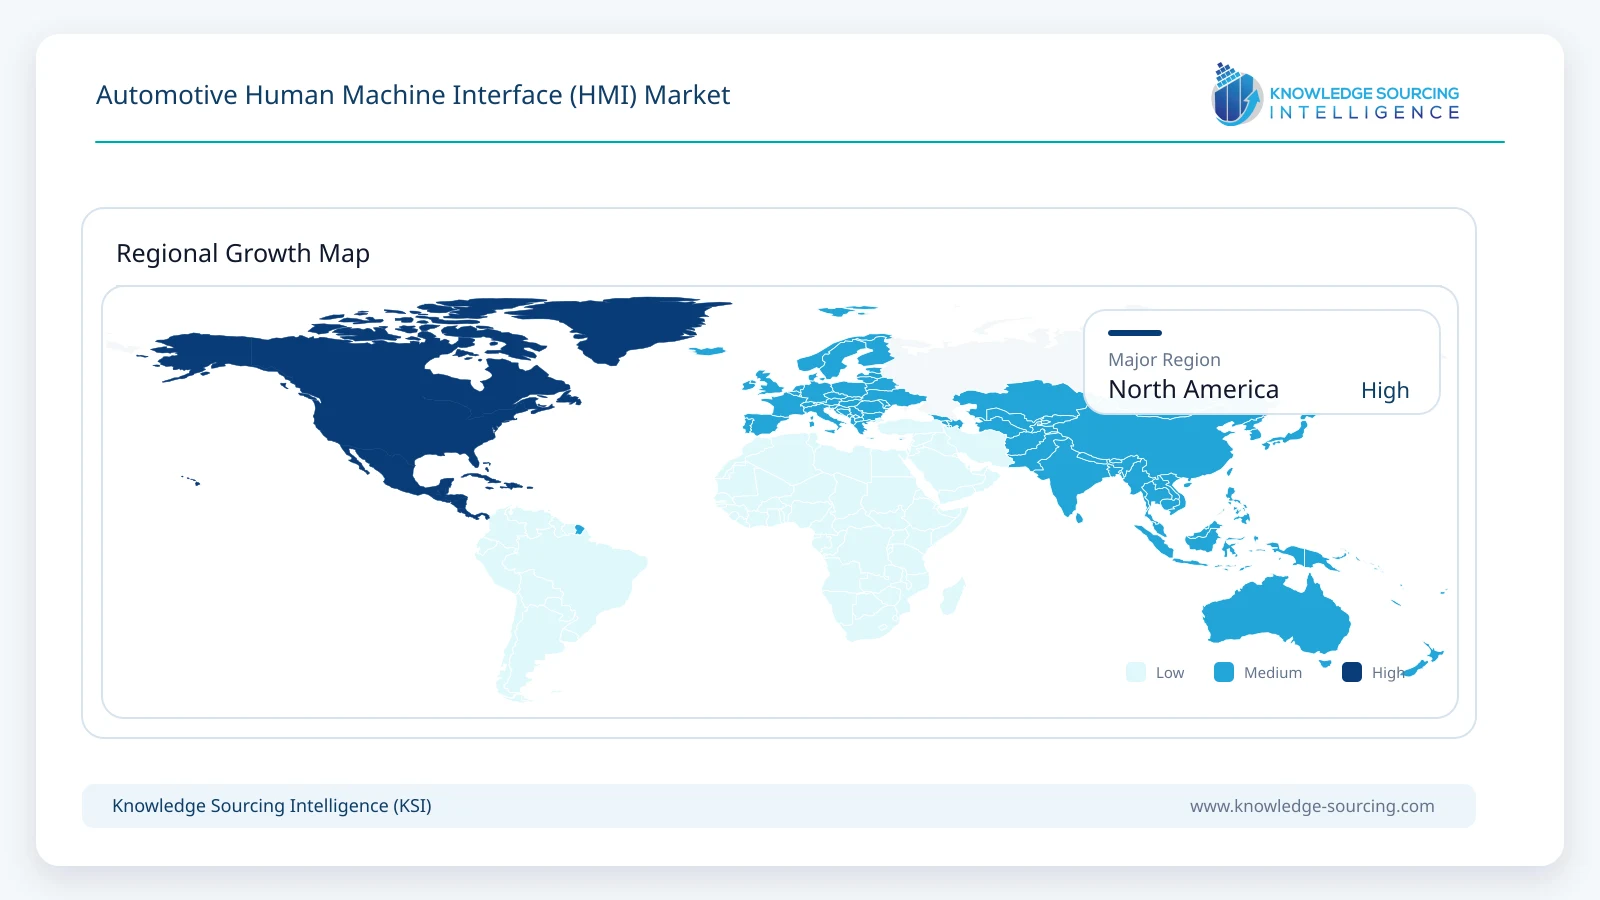
The United States represents a significant and mature market for advanced automotive HMI systems, supported by high consumer adoption of connected technologies and a strong presence of tech-forward OEMs and software giants. Demand in the U.S. is particularly strong for large-format displays, voice interaction, and software-driven features that integrate with smart home ecosystems. Regulatory attention from agencies like the NHTSA regarding driver distraction influences interface design, encouraging hands-free interaction and simplified visual layouts. Canada is also seeing increased demand for HMI systems, particularly those optimized for cold-weather operation and integrated with EV charging networks as part of its national green transport initiative.
South America Market Analysis
The South American automotive HMI market is shaped by a combination of cost sensitivity and the gradual digitalization of vehicle interiors. Brazil and Argentina are leading the regional transition, with local production facilities increasingly incorporating digital infotainment systems into mass-market models. While premium vehicles in this region adopt global HMI trends quickly, the broader market is transitioning from traditional analog clusters to mid-sized digital screens. Localized software development is crucial here, particularly for regional language support and navigation systems that can handle unique local infrastructure challenges. The growth of electric bus fleets in major cities like Santiago and São Paulo is providing the first major regional opportunity for advanced HMI in commercial transit.
Europe Market Analysis
Europe is a global leader in HMI implementation, largely due to its concentration of premium automotive manufacturers and stringent safety regulations. The European Union’s focus on road safety and carbon reduction has led to the early adoption of advanced HMI features that support ADAS and eco-driving. Germany, as a focal point for automotive engineering, drives demand for high-quality integrated cockpit environments where touch, voice, and physical controls are balanced for safety and ergonomics. Countries like France and the UK are also seeing rapid growth in HMI software as they push toward full electrification, requiring interfaces that can manage complex energy grids and renewable energy integration at the vehicle level.
Middle East and Africa Market Analysis
The Middle East and Africa region is in the early stages of advanced HMI adoption but shows significant growth potential in the premium and luxury segments. Saudi Arabia and the UAE are investing heavily in smart city projects and high-tech infrastructure, which naturally supports the adoption of connected and digitally enabled vehicles. In these markets, HMI design must account for extreme environmental conditions, emphasizing display readability under high ambient light and integrated climate control interfaces. In Africa, the HMI market is currently focused on basic connectivity and navigation, but as urban centers grow and vehicle fleets modernize, there is increasing interest in software-based vehicle diagnostics and maintenance alerts.
Asia Pacific Market Analysis
The Asia Pacific region is the most rapidly evolving market for automotive HMI, characterized by high consumer engagement with digital ecosystems and aggressive government support for "intelligent connected vehicles." China, as the world's largest automotive market, favors interfaces that integrate seamlessly with domestic cloud services and social media applications. Japan continues to lead in the development of HMI standards that prioritize safety and disaster resilience. In South Korea, India, and Southeast Asia, the rapid rise of electrified transport fleets and smart city projects has created a surge in demand for HMI solutions that can manage bidirectional data flow and real-time grid interaction. The region’s strong electronics manufacturing base also ensures a steady supply of the high-resolution panels and semiconductors required for modern HMI hardware.
List of Companies
Robert Bosch GmbH
Continental AG
Visteon Corporation
HARMAN International
Panasonic Corporation
Denso Corporation
Marelli Holdings Co., Ltd.
Valeo
DXC Technology
Rightware
HARMAN International
HARMAN International, a subsidiary of Samsung Electronics, focuses on software-centric cockpit platforms and personalized in-cabin experiences. By leveraging its expertise in consumer electronics and high-end audio, HARMAN delivers integrated HMI solutions that transform the vehicle into a connected hub. Its "Ready" suite of products emphasizes modularity and fast time-to-market for OEMs. The company's software platforms allow for individualized audio zones and advanced display management, ensuring that both drivers and passengers have tailored interfaces. HARMAN's global reach includes extensive partnerships with major European and American automakers to deploy cloud-connected HMI ecosystems.
Visteon Corporation
Visteon is a global leader in automotive cockpit electronics, emphasizing centralized cockpit computing and scalable platforms suited for everything from entry-level to luxury vehicles. Its flagship SmartCore™ domain controller is a pioneering technology that integrates independent functional domains, such as instrument clusters and infotainment, into a single, high-performance chip. This consolidation reduces power consumption and weight while providing a seamless user interface across multiple screens. Visteon’s focus on "all-digital" cockpits aligns with the industry's shift toward EVs, where digital HMI is essential for managing complex electrical systems and providing real-time data to the driver.
Robert Bosch GmbH
Robert Bosch GmbH integrates HMI development with broader vehicle systems, aligning interface functionality with safety, automation, and vehicle control technologies. As one of the world's largest automotive suppliers, Bosch provides end-to-end HMI solutions that include hardware like curved displays and software powered by artificial intelligence. Its latest developments involve Large Language Models (LLMs) that allow the vehicle to understand and react to natural speech and visual context. Bosch’s HMI strategy is deeply rooted in the concept of the "Third Living Space," where the vehicle interior becomes a workspace or relaxation area, managed through intuitive, AI-driven digital interfaces.
Automotive Human-Machine Interface (HMI) Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 25.9 billion |
| Total Market Size in 2031 | USD 34.6 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.96% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Offerings, Vehicle Type, Geography |
| Companies |
|
Market Segmentation
By Product Type
Heads-up Display
Gesture Recognition and Speech Interface
Steering-based Controls
Center Stack Display
Instrument Clusters
Multi-Function Buttons, Touchpads, Controllers
By Offerings
Hardware
Software
Services
By Vehicle Type
Passenger Vehicles
Light Commercial Vehicle
Heavy Commercial Vehicle
By Application
Infotainment Systems
Navigation Systems
Advanced Driver Assistance Systems (ADAS) Controls
Climate & Comfort Controls
Vehicle Diagnostics and Maintenance
Safety & Alerts
By Sales Channel
OEMs
Aftermarket
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Spain
Others
Middle East And Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. GLOBAL AUTOMOTIVE HUMAN MACHINE INTERFACE (HMI) MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Heads-up Display
5.3. Gesture Recognition and Speech Interface
5.4. Steering-based Controls
5.5. Center Stack Display
5.6. Instrument Clusters
5.7. Multi-Function Buttons, Touchpads, Controllers
6. GLOBAL AUTOMOTIVE HUMAN MACHINE INTERFACE (HMI) MARKET BY OFFERINGS
6.1. Introduction
6.2. Hardware
6.3. Software
6.4. Services
7. GLOBAL AUTOMOTIVE HUMAN MACHINE INTERFACE (HMI) MARKET BY VEHICLE TYPE
7.1. Introduction
7.2. Passenger Vehicles
7.3. Light Commercial Vehicle
7.4. Heavy Commercial Vehicle
8. GLOBAL AUTOMOTIVE HUMAN MACHINE INTERFACE (HMI) MARKET BY APPLICATION
8.1. Introduction
8.2. Infotainment Systems
8.3. Navigation Systems
8.4. Advanced Driver Assistance Systems (ADAS) Controls
8.5. Climate & Comfort Controls
8.6. Vehicle Diagnostics and Maintenance
8.7. Safety & Alerts
9. GLOBAL AUTOMOTIVE HUMAN MACHINE INTERFACE (HMI) MARKET BY SALES CHANNEL
9.1. Introduction
9.2. OEMs
9.3. Aftermarket
10. GLOBAL AUTOMOTIVE HUMAN MACHINE INTERFACE (HMI) MARKET BY GEOGRAPHY
10.1. Introduction
10.2. North America
10.2.1. USA
10.2.2. Canada
10.2.3. Mexico
10.3. South America
10.3.1. Brazil
10.3.2. Argentina
10.3.3. Others
10.4. Europe
10.4.1. United Kingdom
10.4.2. Germany
10.4.3. France
10.4.4. Spain
10.4.5. Others
10.5. Middle East and Africa
10.5.1. Saudi Arabia
10.5.2. UAE
10.5.3. Others
10.6. Asia Pacific
10.6.1. China
10.6.2. India
10.6.3. Japan
10.6.4. South Korea
10.6.5. Indonesia
10.6.6. Thailand
10.6.7. Others
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Players and Strategy Analysis
11.2. Market Share Analysis
11.3. Mergers, Acquisitions, Agreements, and Collaborations
11.4. Competitive Dashboard
12. COMPANY PROFILES
12.1. HARMAN International
12.2. Valeo S.A.
12.3. Intellias Ltd.
12.4. Denso Corporation
12.5. Rightware
12.6. Clarion (Faurecia SE)
12.7. Continental AG
12.8. Robert Bosch GmbH
12.9. Socionext America Inc
12.10. Visteon Corporation
12.11. Aptiv PLC
12.12. Panasonic Corporation
12.13. Marelli Holdings Co., Ltd.
12.14. Synaptics Incorporated
13. APPENDIX
13.1. Currency
13.2. Assumptions
13.3. Base and Forecast Years Timeline
13.4. Key benefits for the stakeholders
13.5. Research Methodology
13.6. Abbreviations
Navigate
Trusted by the world's leading organizations











