
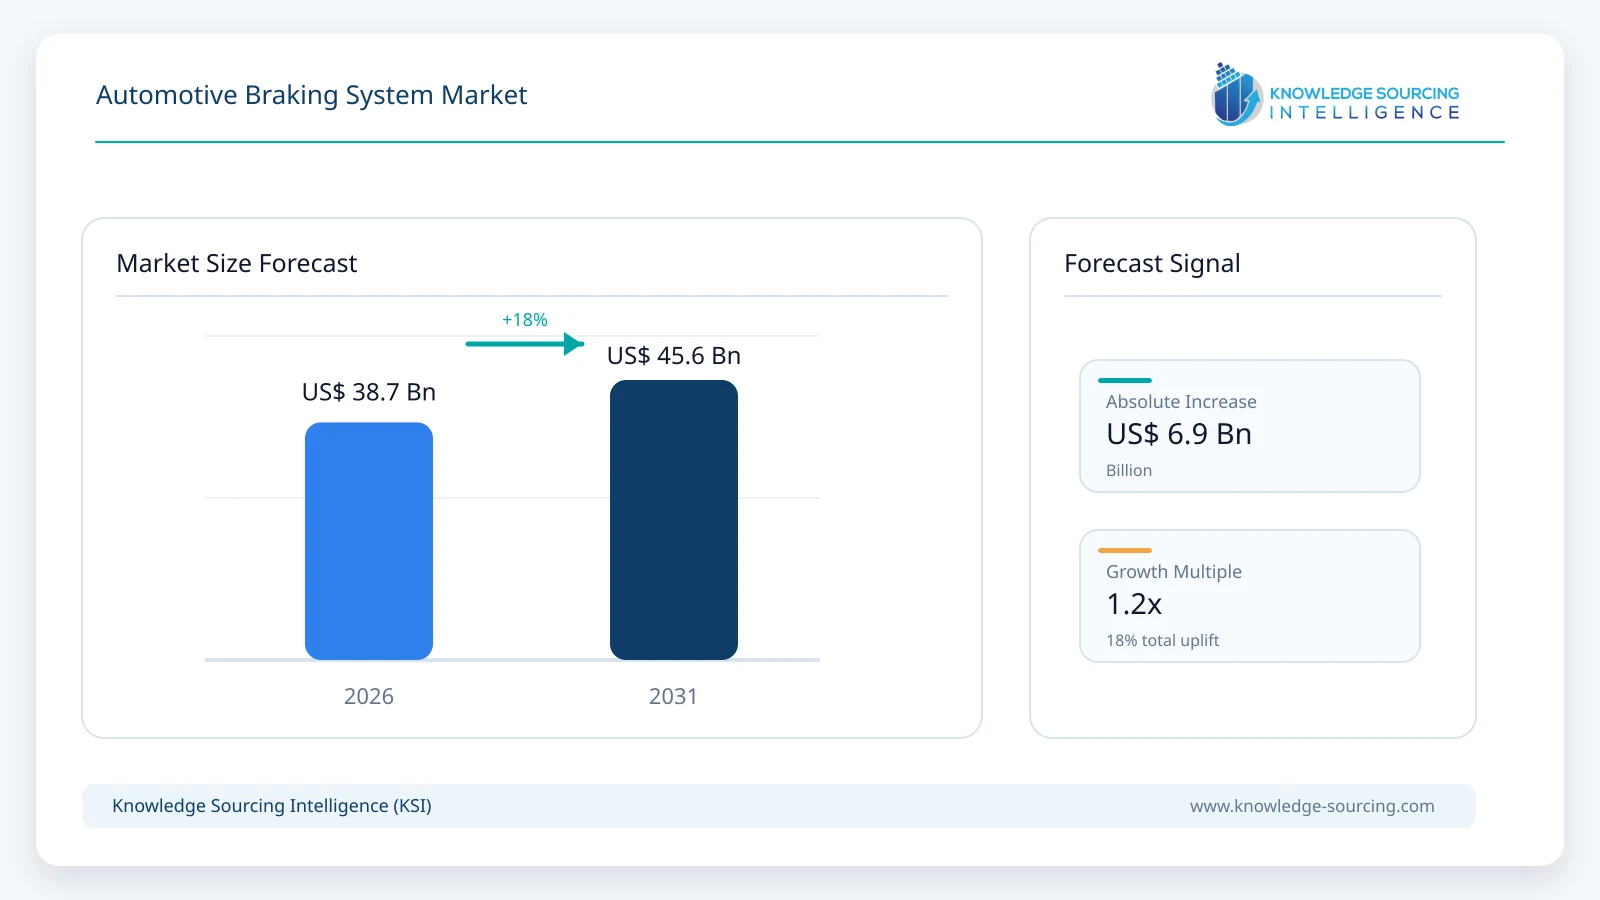
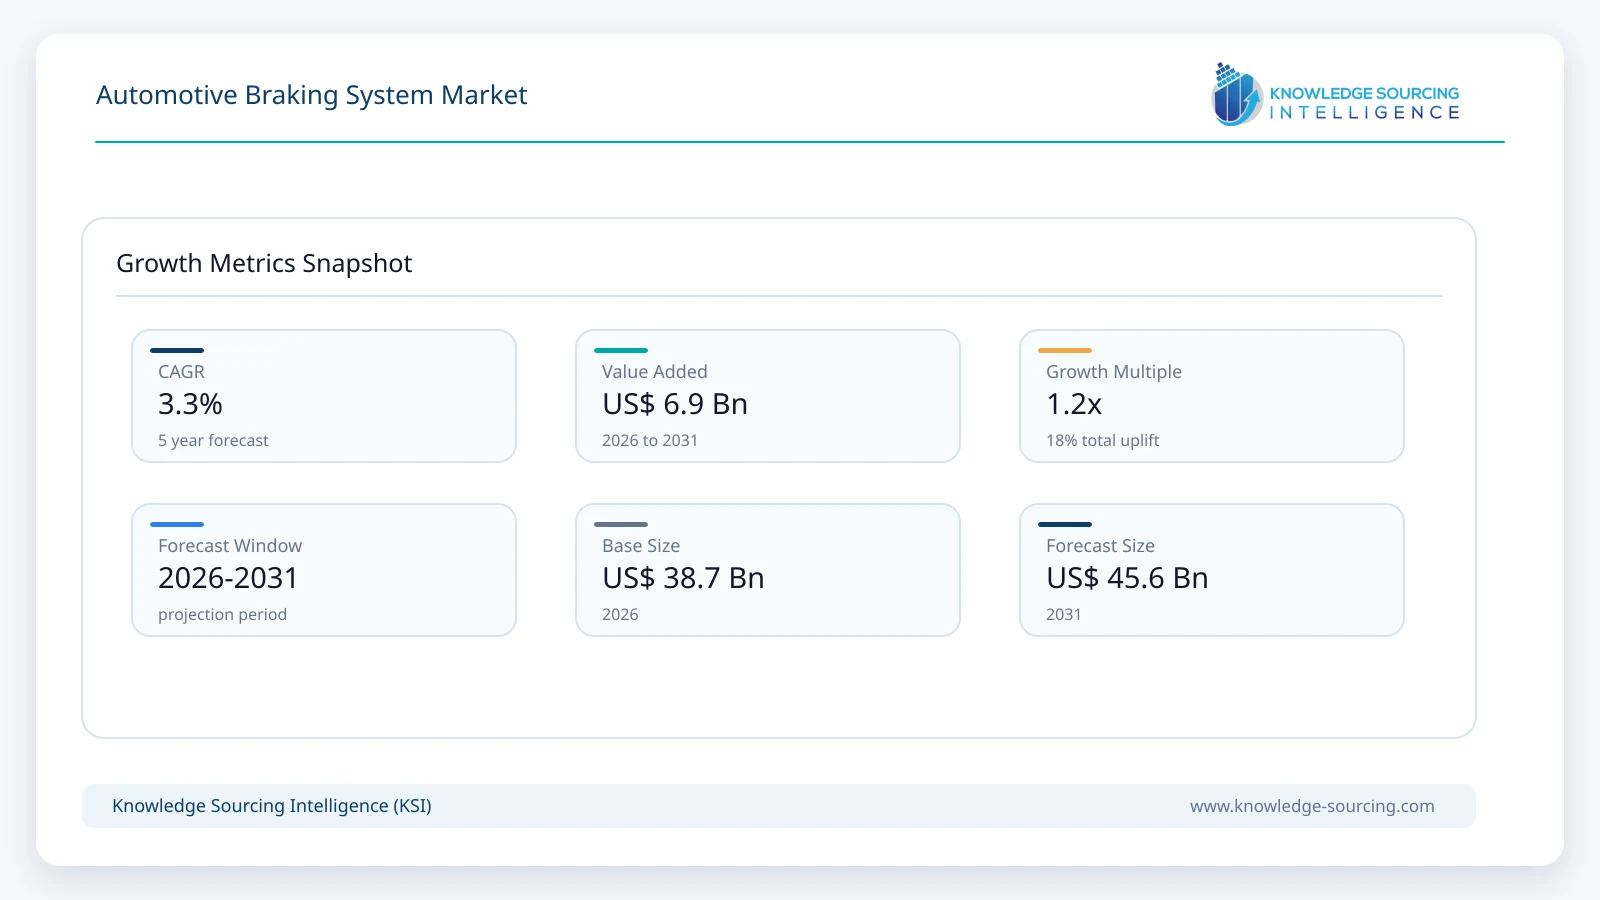
The Automotive Braking System Market is projected to grow at a CAGR of 3.3%, reaching USD 45.6 billion in 2031 from USD 38.7 billion in 2026.
Highlights:
- 1Disc-brake value is projected to reach 76% of the 2031 market as fitment expands.
- 2Integrated brake control is strengthening as electric vehicles require coordinated friction and regeneration.
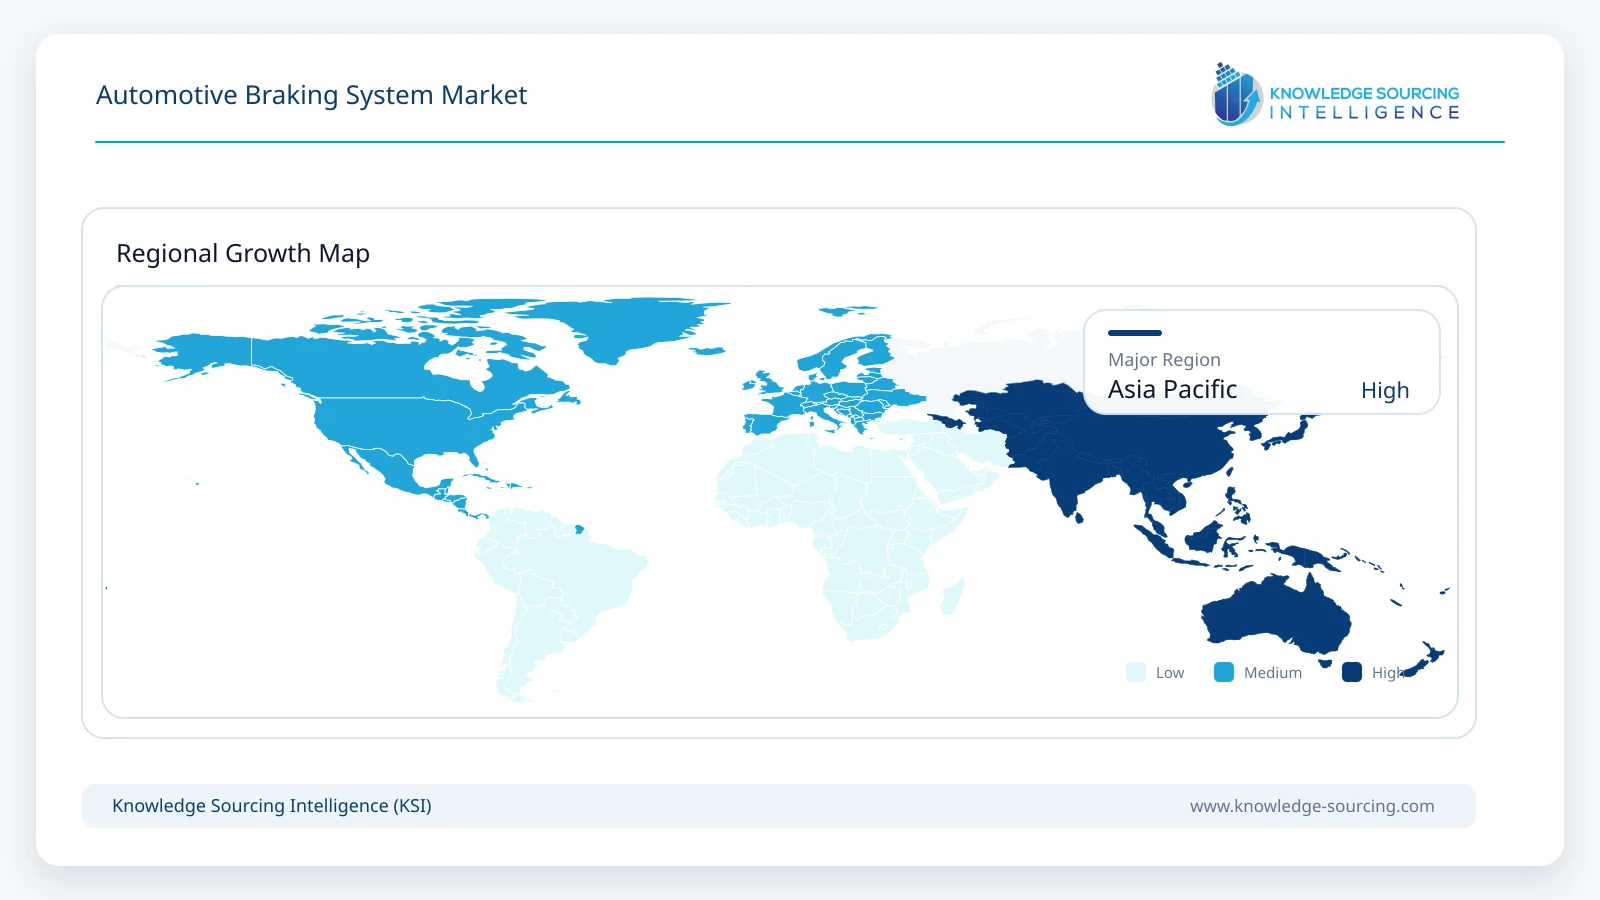
- 3Asia Pacific remains the largest regional braking supply and vehicle-production center.
- 4Commercial-vehicle platforms sustain demand for durable pneumatic and electronically managed braking systems.
- 5Euro 7 brake-particle rules are influencing friction materials, coatings and replacement product design.
- 6Automated emergency braking links higher-level safety functions with reliable brake actuation and redundancy.
The automotive braking system market encompasses original-equipment and replacement braking assemblies and components for passenger cars, light commercial vehicles, trucks and buses. Disc and drum systems include their attributable friction materials, calipers or wheel cylinders, discs or drums, actuating hardware and electronic control content. Antilock braking, stability control, electronic brakeforce distribution and automated emergency-braking capability increasingly influence the specification of the underlying system, although the value of vehicle cameras and unrelated driver-assistance electronics is outside the braking supply boundary.
Manufacturers compete across different layers of the system. AUMOVIO and ZF provide integrated electronic brake architectures, ADVICS combines hydraulics, calipers and control functions, and Brembo, Akebono and other friction specialists address both original-equipment and replacement channels. Knorr-Bremse is particularly relevant to heavy-vehicle pneumatic and electronically controlled braking. Investment in production qualification, friction materials and software validation determines which suppliers can translate the technology shift into contracted vehicle-program revenue.
Market Overview
Disc brakes convert kinetic energy into heat through controlled pad-to-rotor contact, while drum systems use shoe friction within an enclosed assembly. A braking installation also depends on proportioning, pressure generation, modulation and fail-safe operation, creating very different bill-of-materials profiles for a compact passenger car and a high-load truck. Production volumes establish the first-fit requirement, but installed vehicles generate recurring revenue from pads, discs, drums, seals and other wearing parts. Vehicle weight, duty cycle, road conditions and driving patterns materially influence this replacement frequency.
The control architecture is changing around those mechanical fundamentals. AUMOVIO’s MK C2 combines the brake booster, master cylinder and stability functions in one unit, while the company has secured its first series order for a distributed electrohydraulic design scheduled for production in late 2027. ZF offers hydraulic, hybrid and fully electromechanical brake-by-wire configurations. ADVICS supplies cooperative regenerative systems that coordinate mechanical braking with electric-drive energy recovery. These technologies are commercial alternatives at different stages of maturity rather than a universal replacement for conventional hydraulic brakes.
Regulatory requirements reinforce the importance of engineering validation. The European Union’s Euro 7 framework introduces brake-particle controls on a staged schedule, encouraging lower-wear formulations and treated rotor surfaces. The United States requires automatic emergency braking on affected light vehicles under FMVSS No. 127 from September 2029, increasing the need for responsive and dependable electronic brake commands. Suppliers consequently face linked demands for friction performance, particle reduction, diagnostic capability and functional safety. Success depends on meeting those requirements while preserving manufacturability, serviceability and competitive cost across high-volume vehicle programs.
Market Trends
Brake-by-Wire Moves from Engineering Demonstration to Sourced Programs
AUMOVIO disclosed its first series order in September 2026 for a distributed electrohydraulic brake system, with production planned for the end of 2027. The architecture places two compact actuators at different points in the vehicle and controls them electronically from the pedal through the fallback level. It extends a commercially proven integrated-brake product family rather than representing a broad, immediate conversion to fluid-free brakes.
ZF offers an alternative route through modular hydraulic, hybrid and electromechanical configurations. Sourcing decisions will depend on the failure-management strategy, electrical redundancy and savings in weight or assembly content achievable on each platform. Automakers with conventional platforms may retain hydraulic fallback while purpose-built electric vehicles have greater freedom to redesign braking layout.
Brake Particle Emissions Alter Material and Rotor Engineering
The Euro 7 framework extends vehicle-emissions requirements to brake wear particles, bringing friction-material composition into type-approval and aftermarket design decisions. ZF introduced its MAXX Uniper heavy-vehicle air disc brake in September 2026 with a coated rotor intended to reduce brake dust emissions. ADVICS adopted a non-asbestos, copper-free friction formulation for the Mazda CX-5 after balancing dust objectives against stopping performance.
Brake suppliers cannot optimize particulate performance in isolation. Reduced wear must coexist with cold and hot friction consistency, corrosion resistance, acceptable noise and predictable service life. The commercial advantage therefore favors suppliers capable of validating the pad-and-disc combination rather than marketing one low-dust component without the associated system evidence.
Regenerative Blending Refines the Hydraulic Control Package
In hybrid and electric vehicles, the traction motor can decelerate the vehicle and recover energy until battery, traction or stability constraints limit available regenerative torque. Mechanical brakes must then provide the remaining deceleration without uncomfortable transitions. ADVICS confirmed adoption of its revised cooperative regenerative-braking system in the Toyota RAV4 in December 2025, including a change to an electric-cylinder pressure source.
Higher electric-vehicle penetration does not necessarily increase wear-part revenue per vehicle, because regenerative operation can reduce routine pad and rotor use. It does, however, support demand for electronically managed actuation and friction systems engineered to remain reliable after infrequent use. This makes blended braking a value-mix change rather than an assumption of proportionate growth in every mechanical component.
Heavy-Vehicle Redundancy Becomes a Procurement Requirement
Knorr-Bremse set out a 2027 series-production plan for redundant commercial-vehicle braking in July 2026. Its architecture uses fail-active control so a fault does not necessarily prevent the vehicle from completing a controlled maneuver. Such systems are commercially relevant to advanced heavy-truck automation and to fleets that require predictable braking under variable loads.
The engineering burden is different from passenger-car braking: long service duty, thermal energy, trailer coordination, pneumatic interfaces and repair access shape the purchasing decision. Reliable electronics and diagnostic coverage can command added value, but fleet customers remain sensitive to service intervals and replacement-parts availability.
Segment Analysis
By Brake Type: Disc Brakes
Disc brakes account for approximately 73% of the 2026 market of global market value. Their position reflects widespread use on passenger-car front axles, growing rear-disc adoption and extensive replacement demand for pads and rotors. Caliper designs must balance heat rejection, mass, drag and package size, especially where wheel geometry limits the available installation envelope.
Brembo supplies mainstream replacement and higher-performance disc systems, while ADVICS and ZF integrate friction hardware with electronic parking and service-braking functions. Disc-brake content is expected to gain relative weight as commercial-vehicle applications adopt air disc configurations and electronically managed systems become more common. Drum brakes retain an economic place in lower-cost rear-axle applications and selected fleet configurations.
By Technology: Automatic Emergency Braking
Automatic emergency braking is an increasingly influential specification category because electronic hazard-response commands require dependable actuation and control coordination. Brake systems with advanced emergency-braking capability are expected to account for about USD 15.50 billion in 2031, encompassing their associated braking assemblies and controls rather than camera or radar hardware. Stronger U.S. compliance requirements reinforce the need for rapid pressure build-up and fault-managed operation.
AUMOVIO’s integrated braking systems and Bosch’s brake-by-wire control work illustrate how brake pressure generation is migrating closer to electronic chassis management. Vehicle manufacturers retain flexibility over sensing hardware and software, but brake suppliers must validate the mechanical response and fallback mechanisms. That division of responsibility is central to the value of an AEB-capable braking architecture.
By Vehicle Type: Passenger Cars
Passenger cars remain the largest buyer group, as braking architectures are installed across substantial annual vehicle output and subsequently sustain recurring maintenance demand. Their broad range, from budget hatchbacks to large electric SUVs, creates materially different content per vehicle. Premium programs can support advanced boosters, electronic parking brakes and brake-by-wire systems, whereas entry-level vehicles place greater pressure on machining, materials and module cost.
The passenger-car segment is projected to account for approximately USD 32.38 billion by 2031. Higher safety-system fitment and electrification support electronic content, while mature markets continue to generate significant replacement demand. LCVs, trucks and buses remain smaller in total system value but carry different engineering economics, particularly in air-brake durability, high-load braking and fleet servicing.
Market Drivers
Large Vehicle Production and Replacement Base
Automakers purchase braking assemblies for every new vehicle, giving qualified suppliers recurring program demand even when advanced technologies diffuse slowly. Production growth in China and India supports localized caliper, rotor, friction-material and control-module supply. The high-volume character of these programs rewards machining consistency, manufacturing utilization and component localization.
The installed fleet adds a second demand stream. Pads, rotors, drums and hydraulic parts wear or deteriorate according to mileage, loading, road conditions and maintenance practice. Aftermarket specialists can serve several vehicle generations, but must invest continuously in catalogue coverage, fitment accuracy and distributor availability.
Electronic Safety Requirements and Faster Brake Response
Automatic emergency braking and electronic stability functions demand rapid, repeatable modulation of braking force. The U.S. FMVSS No. 127 requirement from September 2029 gives passenger-car and light-truck manufacturers a defined compliance deadline, while regional approval frameworks establish broader braking-performance requirements. Such rules favor brake modules that communicate reliably with vehicle control systems.
Suppliers are consequently investing in integrated pressure generation, electronic redundancy and diagnostics. The value lies not solely in adding a controller, but in delivering a validated stopping response under battery-voltage variation, component faults and changing road adhesion.
Electric-Vehicle Demand for Blended Braking
Electrified drivetrains allocate deceleration between regenerative motor torque and conventional friction brakes. The IEA reported more than 20 million global electric-car sales during 2025 and projects continued growth, increasing the engineering relevance of blended-braking control. Vehicles designed around electric platforms can also accommodate new actuator and pedal interfaces.
ADVICS’s RAV4 regenerative-brake adoption shows that these systems extend beyond pure battery-electric models. Brake suppliers are able to increase control and actuation content while also adapting pads and discs to lower-frequency friction use, corrosion exposure and different brake-feel targets.
Brake-Particle Limits Encourage Product Renewal
Euro 7 introduces brake-emission requirements that make friction materials and rotor surfaces part of a wider compliance program. ADVICS and ZF have introduced 2026 products addressing particle performance without abandoning conventional braking architectures. Manufacturers with measurement capability and validated pad-disc combinations can support both OEM approvals and replacement-product needs.
Long qualification cycles favor established suppliers able to reproduce results across vehicle weights, duty cycles and operating temperatures. Regional friction-material preferences and environmental requirements encourage further tailoring, adding engineering value without assuming every vehicle requires an entirely new brake assembly.
Heavy Commercial Vehicles and Higher System Content
Trucks, trailers and buses require dependable deceleration under high payloads, long operating hours and demanding thermal duty. Air disc brakes, pneumatic systems and electronic control interfaces support durability, diagnostic access and fleet uptime. The transition toward advanced truck automation adds demand for defined fail-operational functions.
Knorr-Bremse’s planned redundant-brake series production illustrates a procurement path for higher-value heavy-vehicle systems. Adoption will be selective, because fleet operators weigh safety benefits against initial price, service support, spare-parts availability and training needs.
Market Restraints
Price Pressure on High-Volume Brake Assemblies
Braking is safety-critical, yet original-equipment purchasing remains tightly controlled by annual productivity targets and platform cost limits. Disc and drum assemblies contain castings, machined surfaces, friction materials and multiple purchased subcomponents, limiting suppliers’ ability to absorb sustained metal and energy-cost increases.
New electronic features can raise per-vehicle content but also require engineering, software and warranty expenditure. Suppliers unable to spread those fixed costs across sufficient vehicle volumes may find that higher specification does not translate into stronger margins.
Extensive Qualification and Liability Exposure
Brake materials and actuation changes require testing across different road friction, temperatures, payloads, repeated stops and fault conditions. A new rotor coating or controller strategy can alter stopping performance, wear patterns, noise or pedal feel, making platform approval more demanding than a routine component substitution.
Series-production customers expect traceable quality and long-life reliability. The validation burden increases for electronically controlled or redundant systems because mechanical performance and software fault handling must be evaluated together. These requirements can delay introductions and favor established suppliers.
Electronic Architecture and Functional-Safety Complexity
Brake-by-wire designs introduce dependencies on electrical power, software execution, sensors, actuators and vehicle communication networks. A fault-safe design must retain required braking performance when one of those elements becomes unavailable. This introduces redundancy, diagnostic coverage and cybersecurity obligations absent from basic hydraulic installations.
Automakers therefore weigh package efficiency and control flexibility against electronics cost and integration risk. Mixed architecture adoption is likely to continue, especially where existing vehicle platforms can meet their safety targets with electrohydraulic rather than fully electromechanical solutions.
Brake Wear Reduction Limits Certain Replacement Categories
Regenerative deceleration reduces the use of friction brakes in some electric-vehicle operating conditions, potentially extending replacement intervals. Low-drag calipers and more durable coatings can also reduce mechanical wear. These developments may restrain the growth of conventional pad and rotor volumes per vehicle even while the installed base rises.
At the same time, infrequently used friction brakes must resist corrosion and respond immediately during emergency stops. Suppliers need alternative value through advanced materials and complete-system compatibility rather than relying on historical replacement rates.
Commodity Exposure and Global Supply-Chain Variability
Brake production depends on cast iron, steel, aluminum, polymers, specialty friction additives and electronic components. Changes in input costs, trade restrictions and regional sourcing requirements can affect delivery economics, especially when vehicle programs commit suppliers to fixed-price agreements.
Localizing manufacturing can reduce logistics risk but entails equipment and qualification expenditure. The resulting network must still deliver stable friction characteristics and dimensional tolerances across plants, restricting how quickly supply can shift between countries.
Regional Outlook
Asia Pacific
Asia Pacific represents approximately 52% of the 2026 market and remains the largest regional revenue base. China contributes extensive passenger-car and electric-vehicle production, Japan and South Korea host established brake engineering capabilities, and India supports further assembly localization. High output creates demand for large-scale castings, calipers, electronic modules and friction materials as well as an expanding replacement component population.
The region is projected to reach USD 24.62 billion in 2031 as electrified models add blended-braking capability and suppliers increasingly integrate pressure-generation electronics. Cost competitiveness remains decisive: production programs favor local supply, high component commonality and reliable quality. The region’s aggregate market position is therefore supported by both sheer manufacturing throughput and gradual technology migration.
South America
Brazil anchors South American brake demand through domestic vehicle assembly, commercial fleets and a substantial installed vehicle base. Replacement demand is important across passenger cars, delivery vehicles and trucks because road conditions and vehicle utilization affect the wear and maintenance schedule. Production and sourcing capacity in Argentina provide a secondary, more cyclical requirement for OEM brake assemblies.
South America is expected to expand at approximately 4.94% annually over 2026–2031, faster than the other major regions. That trajectory reflects recovery potential from a comparatively small base, localized vehicle manufacturing and a growing need for commercial-vehicle service parts. Exchange-rate exposure and variable imported component costs remain constraints, so regional suppliers with local production and distribution are better positioned to maintain service levels.
Competitive Landscape
Competition extends across integrated braking electronics, mechanical actuation, friction systems and aftermarket replacement. ZF and AUMOVIO compete in electronically controlled and brake-by-wire architectures; Bosch provides actuation, ABS and stability-control technology; ADVICS combines hydraulic modules, cooperative regenerative systems and friction components. Brembo emphasizes calipers, discs and complete performance-oriented braking packages, while Akebono retains specialist expertise in friction materials. These firms do not compete with identical product mixes or revenue definitions.
Heavy-commercial-vehicle requirements create a distinct supplier hierarchy. Knorr-Bremse and ZF serve pneumatic braking, air-disc hardware, electronic control and fleet service networks. Astemo, HL Mando, Brakes India and selected regional manufacturers add braking solutions across different vehicle classes. AUMOVIO’s launch as an independent company in 2025 and Astemo’s rebranding in the same year require attention when comparing historical sales and corporate portfolios; legacy names are not treated as separate competitors.
Supplier strength increasingly depends on access to complete-system validation rather than a single branded component. Vehicle manufacturers evaluate friction wear, actuator redundancy, environmental performance, calibration resources and parts-service capability together. At the same time, fleet and independent aftermarket buyers retain strong preferences for price transparency, broad coverage and dependable replenishment. Market-share claims must consequently distinguish original-equipment electronics, friction parts and commercial-vehicle platforms.
Recent Developments
16 September 2026: ZF introduced the MAXX Uniper heavy-vehicle air disc brake, combining high braking torque with a coated rotor designed to lower brake particle emissions.
10 September 2026: AUMOVIO unveiled its distributed electrohydraulic braking system and announced a first series order from a Chinese automaker, with production scheduled for late 2027.
8 September 2026: ZF presented new TRW DTEC brake pads and discs for the independent aftermarket, reporting reduced brake PM10 emissions in dynamometer testing.
6 August 2026: Astemo announced plans to absorb its brake-manufacturing subsidiary Astemo Ueda, with the merger scheduled for January 2027 to strengthen braking-technology development and production.
14 July 2026: Knorr-Bremse announced that series production of its fail-active redundant braking system for highly automated commercial vehicles is planned for 2027.
2 July 2026: ADVICS announced that its Sustena low-particle brake pads had been adopted for the Mazda CX-5 launched in Japan in May 2026.
Market Outlook
The brake system market will remain principally dependent on vehicle manufacture and replacement cycles, but a growing share of engineering effort and supplier differentiation will concentrate on actuation electronics, software-integrated control and friction-material performance. Disc brakes retain a broad application base, while electrohydraulic systems are likely to provide a practical transition path for platforms not designed around fully electric brake actuation. Regenerative braking changes the relationship between mechanical wear and vehicle usage, requiring new product economics for some replacement components.
By 2031, suppliers that can manage vehicle-specific validation, supply-chain localization and the interaction between active safety, brake wear and serviceability should be positioned more favorably than those competing predominantly on basic component cost. The opportunity differs by region and vehicle class: Asian assembly plants sustain scale, selected emerging markets offer stronger percentage growth from smaller bases, and heavy-duty platforms reward proven durability and redundancy. Even advanced architectures must ultimately demonstrate reliable stopping and acceptable total ownership cost.
Automotive Braking System Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 38.7 billion |
| Total Market Size in 2031 | USD 45.6 billion |
| Forecast Unit | Billion |
| Growth Rate | 3.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Brake Type, Technology, Vehicle Type, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Brake Type
Disc Brake
Drum Brake
By Technology
Anti-Lock Braking System (ABS)
Electronic Stability Control (ESC)
Traction Control System (TCS)
Electronic Brakeforce Distribution (EBD)
Automatic Emergency Braking
By Vehicle Type
Passenger Cars
Light Commercial Vehicles (LCVs)
Trucks
Buses
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
United Arab Emirates
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Taiwan
Thailand
Indonesia
Others
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. Market Size and Forecast, 2026–2031
1.3. Segment and Regional Outlook
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Large Vehicle Production and Replacement Base
3.1.2. Electronic Safety Requirements and Faster Brake Response
3.1.3. Electric-Vehicle Demand for Blended Braking
3.1.4. Brake-Particle Limits Encourage Product Renewal
3.1.5. Heavy Commercial Vehicles and Higher System Content
3.2. Market Restraints
3.2.1. Price Pressure on High-Volume Brake Assemblies
3.2.2. Extensive Qualification and Liability Exposure
3.2.3. Electronic Architecture and Functional-Safety Complexity
3.2.4. Brake Wear Reduction Limits Certain Replacement Categories
3.2.5. Commodity Exposure and Global Supply-Chain Variability
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Conventional Hydraulic and Friction Systems
4.2. Electronic Stability and Brakeforce Controls
4.3. Regenerative and Brake-by-Wire Integration
4.4. Brake-Particle and Wear-Reduction Technologies
5. AUTOMOTIVE BRAKING SYSTEM MARKET BY BRAKE TYPE
5.1. Introduction
5.2. Disc Brake
5.3. Drum Brake
6. AUTOMOTIVE BRAKING SYSTEM MARKET BY TECHNOLOGY
6.1. Introduction
6.2. Anti-Lock Braking System (ABS)
6.3. Electronic Stability Control (ESC)
6.4. Traction Control System (TCS)
6.5. Electronic Brakeforce Distribution (EBD)
6.6. Automatic Emergency Braking
7. AUTOMOTIVE BRAKING SYSTEM MARKET BY VEHICLE TYPE
7.1. Introduction
7.2. Passenger Cars
7.3. Light Commercial Vehicles (LCVs)
7.4. Trucks
7.5. Buses
8. AUTOMOTIVE BRAKING SYSTEM MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. Overview
8.2.2. By Brake Type
8.2.3. By Technology
8.2.4. By Vehicle Type
8.2.5. By Country
8.2.5.1. United States
8.2.5.2. Canada
8.2.5.3. Mexico
8.3. South America
8.3.1. Overview
8.3.2. By Brake Type
8.3.3. By Technology
8.3.4. By Vehicle Type
8.3.5. By Country
8.3.5.1. Brazil
8.3.5.2. Argentina
8.3.5.3. Others
8.4. Europe
8.4.1. Overview
8.4.2. By Brake Type
8.4.3. By Technology
8.4.4. By Vehicle Type
8.4.5. By Country
8.4.5.1. United Kingdom
8.4.5.2. Germany
8.4.5.3. France
8.4.5.4. Italy
8.4.5.5. Spain
8.4.5.6. Others
8.5. Middle East and Africa
8.5.1. Overview
8.5.2. By Brake Type
8.5.3. By Technology
8.5.4. By Vehicle Type
8.5.5. By Country
8.5.5.1. Saudi Arabia
8.5.5.2. United Arab Emirates
8.5.5.3. South Africa
8.5.5.4. Others
8.6. Asia Pacific
8.6.1. Overview
8.6.2. By Brake Type
8.6.3. By Technology
8.6.4. By Vehicle Type
8.6.5. By Country
8.6.5.1. China
8.6.5.2. India
8.6.5.3. Japan
8.6.5.4. South Korea
8.6.5.5. Taiwan
8.6.5.6. Thailand
8.6.5.7. Indonesia
8.6.5.8. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. ZF Friedrichshafen AG
10.2. AUMOVIO SE
10.3. Robert Bosch GmbH
10.4. ADVICS CO., LTD.
10.5. Brembo N.V.
10.6. Akebono Brake Industry Co., Ltd.
10.7. Astemo, Ltd.
10.8. Knorr-Bremse AG
10.9. HL Mando Corporation
10.10. Brakes India Private Limited
10.11. AISIN Corporation
10.12. Disc Brakes Australia Pty Ltd
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations





Frequently asked questions
What is the projected market value of automotive braking systems by 2031?
The Automotive Braking System Market is projected to reach USD 45.6 billion by 2031.
What is the Compound Annual Growth Rate for this market (2026-2031)?
The Automotive Braking System Market is projected to grow at a CAGR of 3.3%.
Which region is the largest for automotive braking system supply and production?
Asia Pacific remains the largest regional supply and vehicle-production center.
What key technology shift influences the Automotive Braking System Market?
Integrated brake control strengthens, especially for electric vehicles.
Which regulations are influencing future automotive braking system design?
Euro 7 brake-particle rules influence friction materials and product design.
Which vehicle platforms sustain demand for durable braking systems?
Commercial-vehicle platforms sustain demand for durable, electronically managed braking.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Automotive Braking System Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/automotive-braking-system-market