
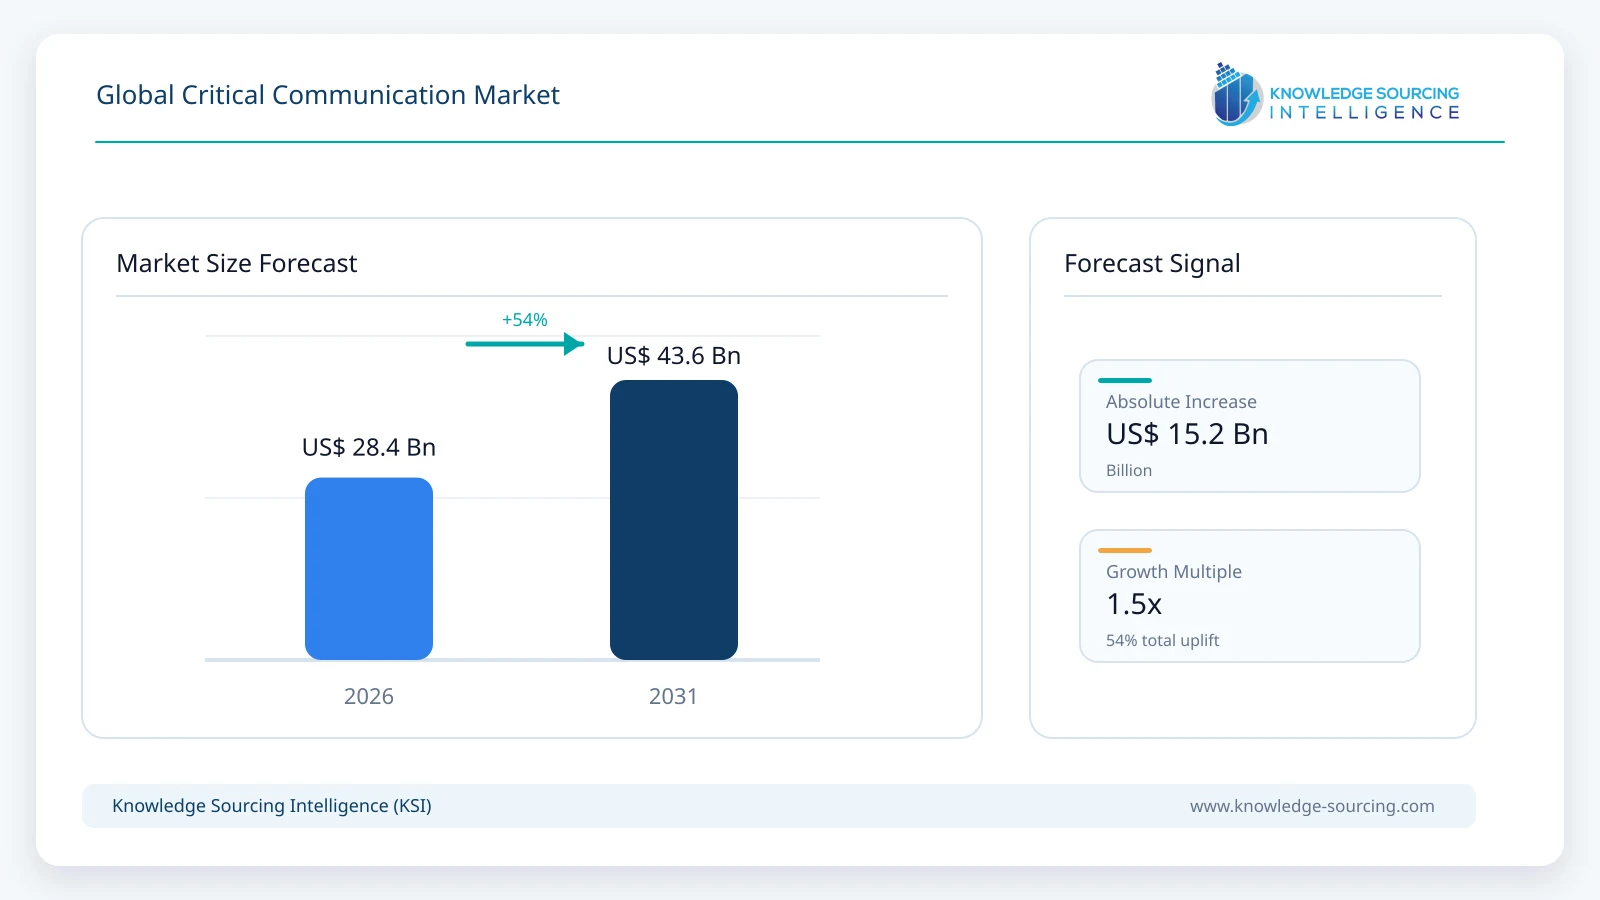
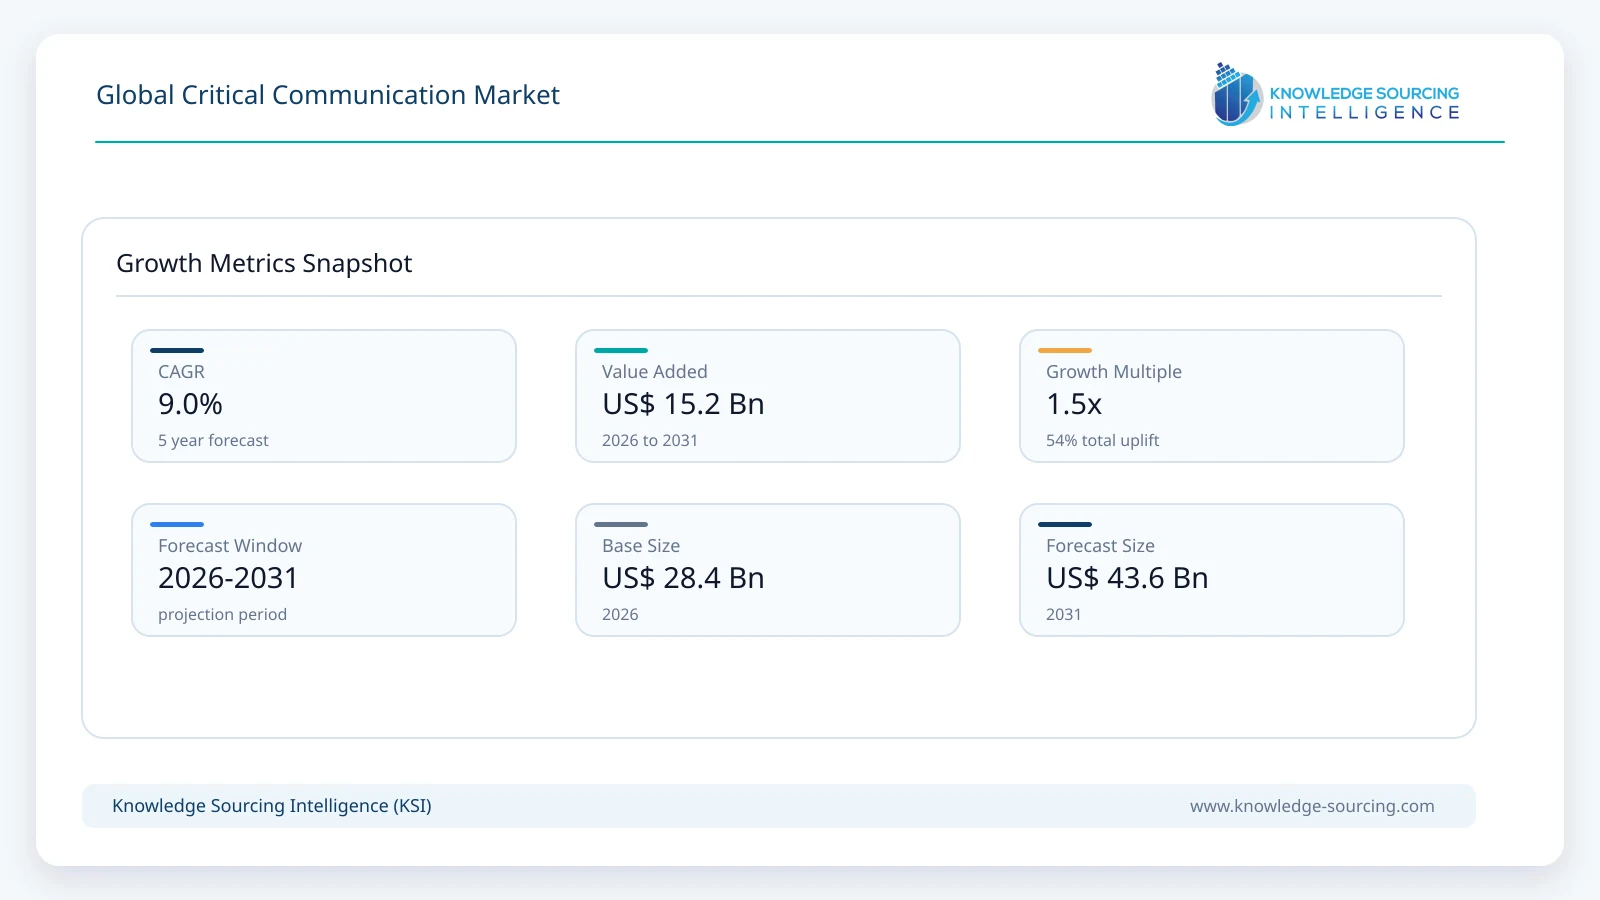
The global critical communication market is estimated at USD 28.4 billion in 2026 and is projected to reach USD 43.6 billion by 2031, representing a CAGR of 9.0% during the forecast period.
Highlights:
- 1Hardware accounts for approximately 57.0% of global critical communication revenue in 2026.
- 2Land mobile radio and professional mobile radio systems account for approximately 52.0% of 2026 revenue.
- 3Public protection and disaster relief accounts for approximately 44.0% of 2026 market revenue.
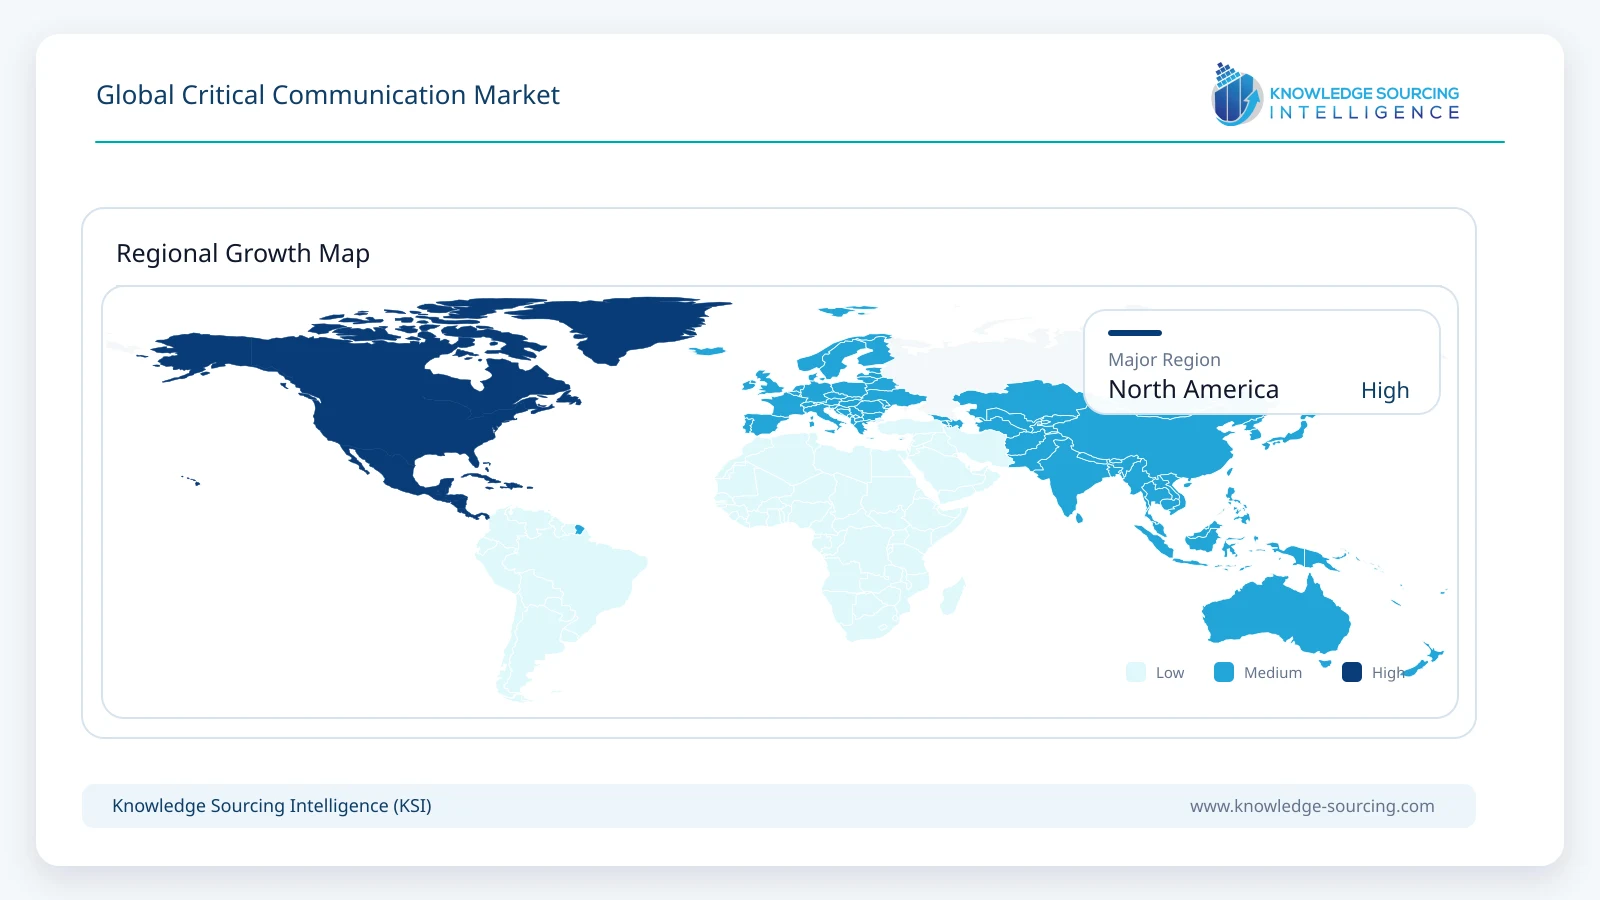
- 4North America accounts for approximately 39.0% of global critical communication revenue in 2026.
- 5Hybrid LMR-broadband architectures are expanding as agencies add data capabilities without sacrificing resilient voice communications.
Market Overview
Spending is supported by the continued operation and modernization of large P25, TETRA, and other professional-radio installed bases, alongside investment in mission-critical LTE and 5G, dispatch software, secure broadband devices, recording, cybersecurity, and managed services. Motorola Solutions, L3Harris, Airbus, Hytera, Nokia, Ericsson, Sepura, Tait, Zetron, Frequentis, and other established suppliers serve public-safety and critical-infrastructure customers across these layers.
The market is not undergoing a simple replacement of radio by cellular broadband. Public-safety agencies and critical-infrastructure operators are pursuing staged migration in which TETRA, P25, and other LMR systems continue to provide proven voice resilience while LTE and 5G add video, mapping, data applications, AI-assisted workflows, and richer cross-agency collaboration. This hybrid phase creates demand for dual-mode devices, interoperability software, mission-critical core networks, dispatch modernization, and managed services. Over the forecast period, broadband-related revenue grows faster than traditional narrowband equipment, but LMR remains a substantial part of the installed base and replacement cycle.
Market Drivers and Trends
Migration from voice-centric LMR to mission-critical broadband
Public safety organizations increasingly require secure video, real-time location, body-camera feeds, drone data, database access, and multimedia coordination in addition to push-to-talk voice. 3GPP mission-critical services and private LTE/5G architectures are therefore becoming central to modernization programs. Nokia and Ericsson are actively positioning 4G/5G mission-critical networks for public safety and critical infrastructure, while LMR suppliers are adding broadband interoperability. The transition is gradual because coverage, direct-mode communication, availability, and operational familiarity remain critical requirements.
Multi-network resilience is becoming a design priority
Critical communication users increasingly expect devices and applications to move between radio, public or private broadband, Wi-Fi, and satellite connectivity without losing operational context. Motorola Solutions announced satellite connectivity for APX NEXT radios in 2026, while L3Harris introduced the XL Converge 300P with P25, LTE, 5G, Wi-Fi, and non-terrestrial network connectivity. This multi-layer approach reduces dependence on any single access network and supports operations during disasters, congestion, remote deployments, and infrastructure outages.
Control rooms are shifting toward software-centric workflows
Dispatch, recording, incident management, mapping, analytics, and communication orchestration are increasingly delivered through software platforms. Cloud and hybrid architectures allow agencies to update capabilities more rapidly while preserving on-premise or sovereign deployment where required. AI is also moving into call handling, translation, information retrieval, and operator assistance. This trend raises the recurring software and services component of the market even when radio hardware remains in service for many years.
Market Restraints
Migration risk and long asset lives slow replacement cycles
Mission-critical networks are designed for long operational lifecycles, and agencies cannot tolerate service interruption during modernization. Existing P25 and TETRA networks often have substantial sunk investment, established coverage, encryption, trained users, and direct-mode capabilities. Broadband migration therefore requires interoperability, phased procurement, parallel operation, and extensive validation. These requirements extend project timelines and can delay full revenue conversion from legacy systems to new broadband platforms.
Spectrum, interoperability, and procurement complexity
Critical communication deployments depend on spectrum policy, national security requirements, encryption standards, procurement cycles, and inter-agency governance. Public-safety programs can involve national or regional networks, multiple emergency services, commercial mobile operators, and specialized device suppliers. Interoperability across standards and generations remains essential. Procurement delays, budget constraints, or policy changes can therefore shift revenue between years even when long-term modernization demand remains intact.
Segment Analysis
By Offering - Hardware
Hardware generated an estimated USD 16.2 billion in 2026. Radios, rugged broadband devices, base stations, repeaters, gateways, antennas, dispatch consoles, and related network infrastructure remain the largest spending category because mission-critical users require purpose-built equipment with high availability, long field life, and secure operation. Replacement cycles, capacity upgrades, and the addition of broadband-capable devices continue to support demand across public safety, transport, utilities, and industrial networks.
By Network Technology - Land Mobile Radio / Professional Mobile Radio
Land mobile radio and professional mobile radio systems generated an estimated USD 14.8 billion in 2026. P25, TETRA, DMR, and related systems remain the largest technology base because they provide established coverage, direct-mode communication, hardened voice services, and operational familiarity for mission-critical users. Modernization increasingly adds broadband interoperability rather than immediately replacing these networks, extending demand for radio infrastructure, subscriber devices, maintenance, and migration support.
By End User - Public Protection and Disaster Relief
Public protection and disaster relief generated an estimated USD 12.5 billion in 2026. Police, fire, emergency medical services, disaster-response agencies, and national public-safety organizations require continuous, secure communications under congested or degraded network conditions. Ongoing investment covers radio replacement, dispatch modernization, broadband integration, location and video services, cybersecurity, and interoperability between agencies and jurisdictions.
Geographic Analysis
North America
North America generated an estimated USD 11.1 billion in 2026. The region combines a large P25 installed base, substantial state and local public-safety spending, nationwide broadband initiatives, and significant defense and critical-infrastructure communications demand. Modernization programs increasingly combine radio-network upgrades with broadband devices, dispatch software, video, cybersecurity, recording, and managed services.
Competitive Environment
The market includes vertically integrated public-safety vendors, telecom infrastructure suppliers, defense communications companies, specialist radio manufacturers, and control-room software providers. Motorola Solutions has the broadest commercial position across LMR, broadband devices, network infrastructure, command-center software, and services. L3Harris is a major supplier in secure public-safety and defense communications. Airbus, Hytera, Sepura, Tait, and JVCKENWOOD compete in professional radio and hybrid devices, while Nokia and Ericsson bring carrier-grade LTE/5G network capabilities. Frequentis and Zetron are important in control-room and dispatch environments.
The competitive structure increasingly rewards interoperability rather than closed single-network architectures. Suppliers are extending products across TETRA/P25, broadband, Wi-Fi, satellite, cloud, and software-defined environments. As a result, competitive differentiation is shifting toward resilience, cybersecurity, standards compliance, lifecycle services, AI-assisted operations, and the ability to integrate legacy and next-generation networks without interrupting mission-critical workflows.
Recent Developments
September 2026: Louisiana awarded Motorola Solutions a USD 139 million, 10-year public-safety technology contract including mission-critical network enhancements, mobile video, evidence management, and command-center technology.
June 2026: Motorola Solutions showcased DIMETRA Connect and broader mission-critical connectivity developments at Critical Communications World 2026, emphasizing hybrid TETRA and broadband resilience.
June 2026: Ericsson presented next-generation mission-critical 4G/5G networks for public safety, defense, and critical infrastructure at CCW and Eurosatory 2026.
May 2026: L3Harris introduced the XL Converge 300P portable public-safety radio, combining P25, LTE, 5G, Wi-Fi, and satellite connectivity in one device.
March 2026: Motorola Solutions acquired Exacom, adding cloud-native recording and logging capabilities for mission-critical 911 and radio communications.
Market Outlook
Critical communication spending should grow steadily through 2031 as agencies modernize without sacrificing resilience. LMR will remain operationally important, particularly for direct-mode and hardened voice communications, but incremental investment shifts toward broadband cores, hybrid devices, software, dispatch modernization, cybersecurity, and managed services. The result is a market in which hardware continues to generate the largest revenue pool while software and broadband grow faster.
The most durable opportunity lies in architectures that allow users to preserve existing mission-critical assets while adding 4G/5G, satellite, and software capabilities. Vendors able to integrate multiple networks, support sovereign and secure deployments, and maintain long lifecycle support should remain well positioned as national and regional modernization programs move from planning into implementation.
Critical Communication Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 28.4 billion |
| Total Market Size in 2031 | USD 43.6 billion |
| Forecast Unit | Billion |
| Growth Rate | 9.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Offering, Network Technology, End User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Offering
Hardware
Handheld and Mobile Devices
Network Infrastructure
Dispatch and Control-Room Hardware
Software
Services
Integration Services
Maintenance and Support
Managed Services
Consulting and Other Services
By Network Technology
Land Mobile Radio / Professional Mobile Radio
P25
TETRA
DMR and Other LMR
Mission-Critical LTE
Mission-Critical 5G
Hybrid and Multi-Network Solutions
By End User
Public Protection and Disaster Relief
Defense and Secure Government
Energy and Utilities
Transport
Mining and Industrial
Healthcare and Other Users
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Nordic Countries
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
South Korea
India
Australia
Others
Table of Contents
1. INTRODUCTION
1.1 Market Definition and Scope
1.2 Mission-Critical and Business-Critical Boundary
1.3 Technology Definitions
2. MARKET CONTEXT
2.1 Mission-Critical Network Architecture
2.2 LMR-to-Broadband Transition
3. EXECUTIVE SUMMARY
3.1 Market Size and Growth
3.2 Key Findings
4. MARKET DYNAMICS
4.1 Growth Drivers
4.2 Market Restraints
4.3 Technology and Procurement Trends
5. CRITICAL COMMUNICATION MARKET BY OFFERING
5.1 Hardware
5.1.1 Handheld and Mobile Devices
5.1.2 Network Infrastructure
5.1.3 Dispatch and Control-Room Hardware
5.2 Software
5.3 Services
5.3.1 Integration Services
5.3.2 Maintenance and Support
5.3.3 Managed Services
5.3.4 Consulting and Other Services
6. MARKET BY NETWORK TECHNOLOGY
6.1 Land Mobile Radio / Professional Mobile Radio
6.1.1 P25
6.1.2 TETRA
6.1.3 DMR and Other LMR
6.2 Mission-Critical LTE
6.3 Mission-Critical 5G
6.4 Hybrid and Multi-Network Solutions
7. MARKET BY END USER
7.1 Public Protection and Disaster Relief
7.2 Defense and Secure Government
7.3 Energy and Utilities
7.4 Transport
7.5 Mining and Industrial
7.6 Healthcare and Other Users
8. MARKET BY GEOGRAPHY
8.1 North America
8.1.1 United States
8.1.2 Canada
8.1.3 Mexico
8.2 South America
8.2.1 Brazil
8.2.2 Argentina
8.2.3 Others
8.3 Europe
8.3.1 Germany
8.3.2 France
8.3.3 United Kingdom
8.3.4 Nordic Countries
8.3.5 Others
8.4 Middle East and Africa
8.4.1 Saudi Arabia
8.4.2 UAE
8.4.3 South Africa
8.4.4 Others
8.5 Asia Pacific
8.5.1 China
8.5.2 Japan
8.5.3 South Korea
8.5.4 India
8.5.5 Australia
8.5.6 Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1 Vendor Positioning
9.2 LMR-to-Broadband Migration Strategies
9.3 Partnerships, Contracts and Recent Developments
10. COMPANY PROFILES
10.1 Motorola Solutions, Inc.
10.2 L3Harris Technologies, Inc.
10.3 Nokia Corporation
10.4 Telefonaktiebolaget LM Ericsson
10.5 Airbus Secure Land Communications
10.6 Hytera Communications Corporation Limited
10.7 Sepura Limited
10.8 Tait Communications
10.9 JVCKENWOOD Corporation
10.10 Icom Incorporated
10.11 BK Technologies Corporation
10.12 Frequentis AG
10.13 Zetron, Inc.
10.14 DAMM Cellular Systems A/S
10.15 Teltronic S.A.U.
11. APPENDIX
11.1 Currency
11.2 Market Definitions
11.3 Definitions and Abbreviations





Frequently asked questions
What is the Global Critical Communication Market size and growth forecast (2026-2031)?
Projected to reach USD 43.6 billion by 2031, with a 9.0% CAGR.
Which critical communication component accounts for the most revenue?
Hardware accounts for 57.0% of market revenue in 2026.
What primary systems dominate critical communication market revenue?
Land mobile radio (LMR) and professional mobile radio (PMR) lead with 52.0%.
Which end-user sector drives the largest critical communication market share?
Public protection and disaster relief (PPDR) accounts for 44.0%.
Which region holds the largest share of the critical communication market?
North America leads, accounting for 39.0% of 2026 global revenue.
What is a key strategic trend in the critical communication market?
Migration to mission-critical broadband with hybrid LMR-broadband architectures is key.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Global Critical Communication Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/global-critical-communication-market