
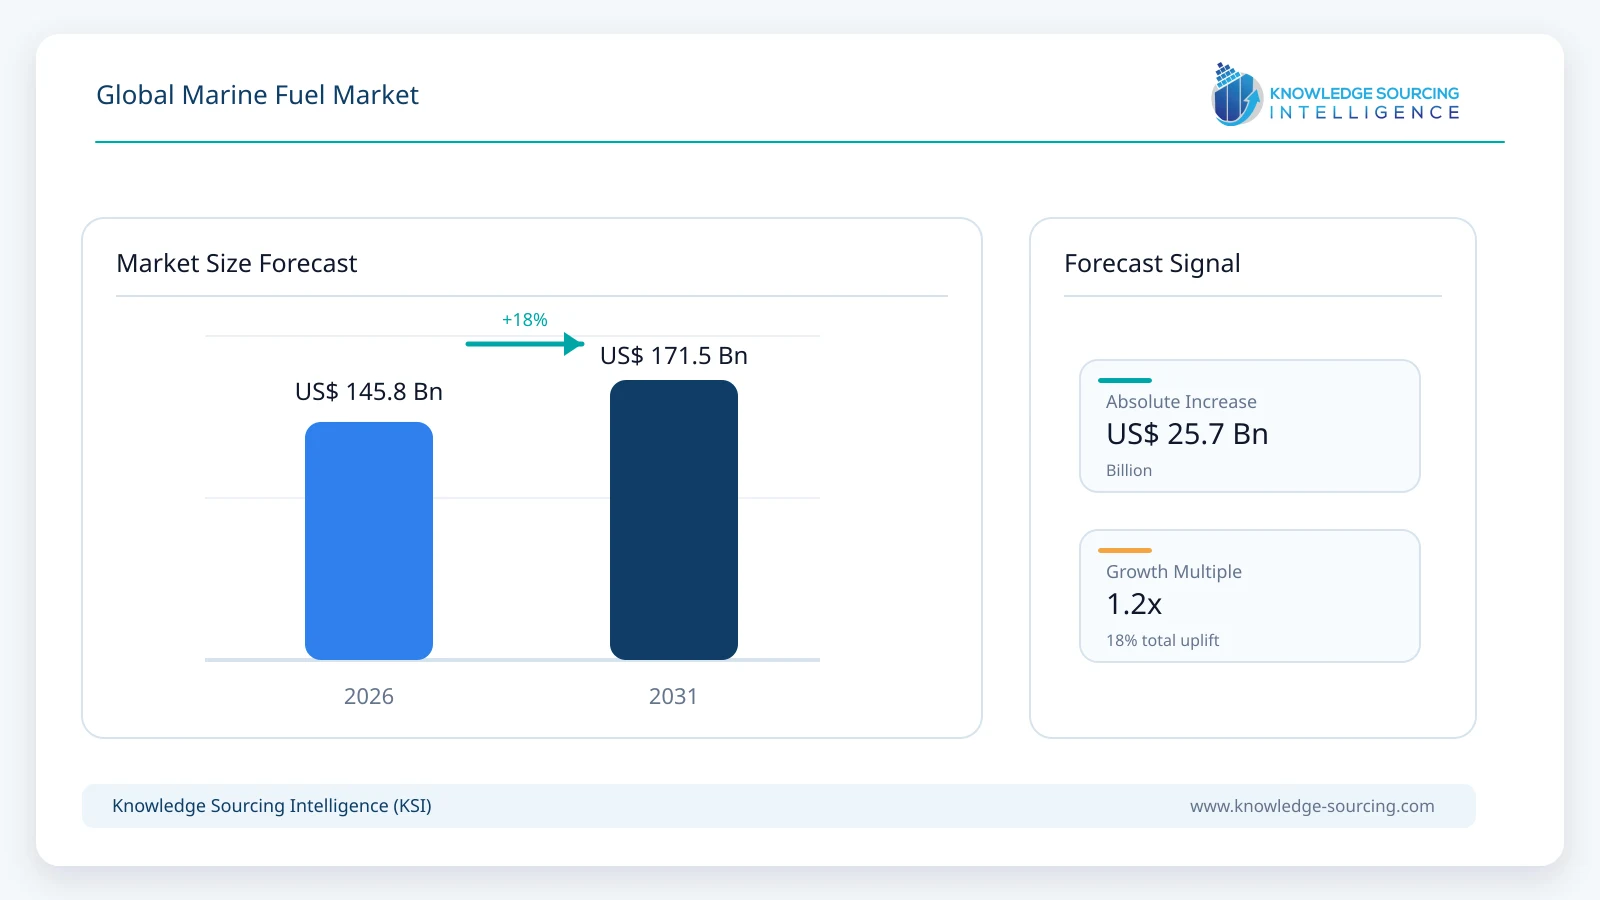
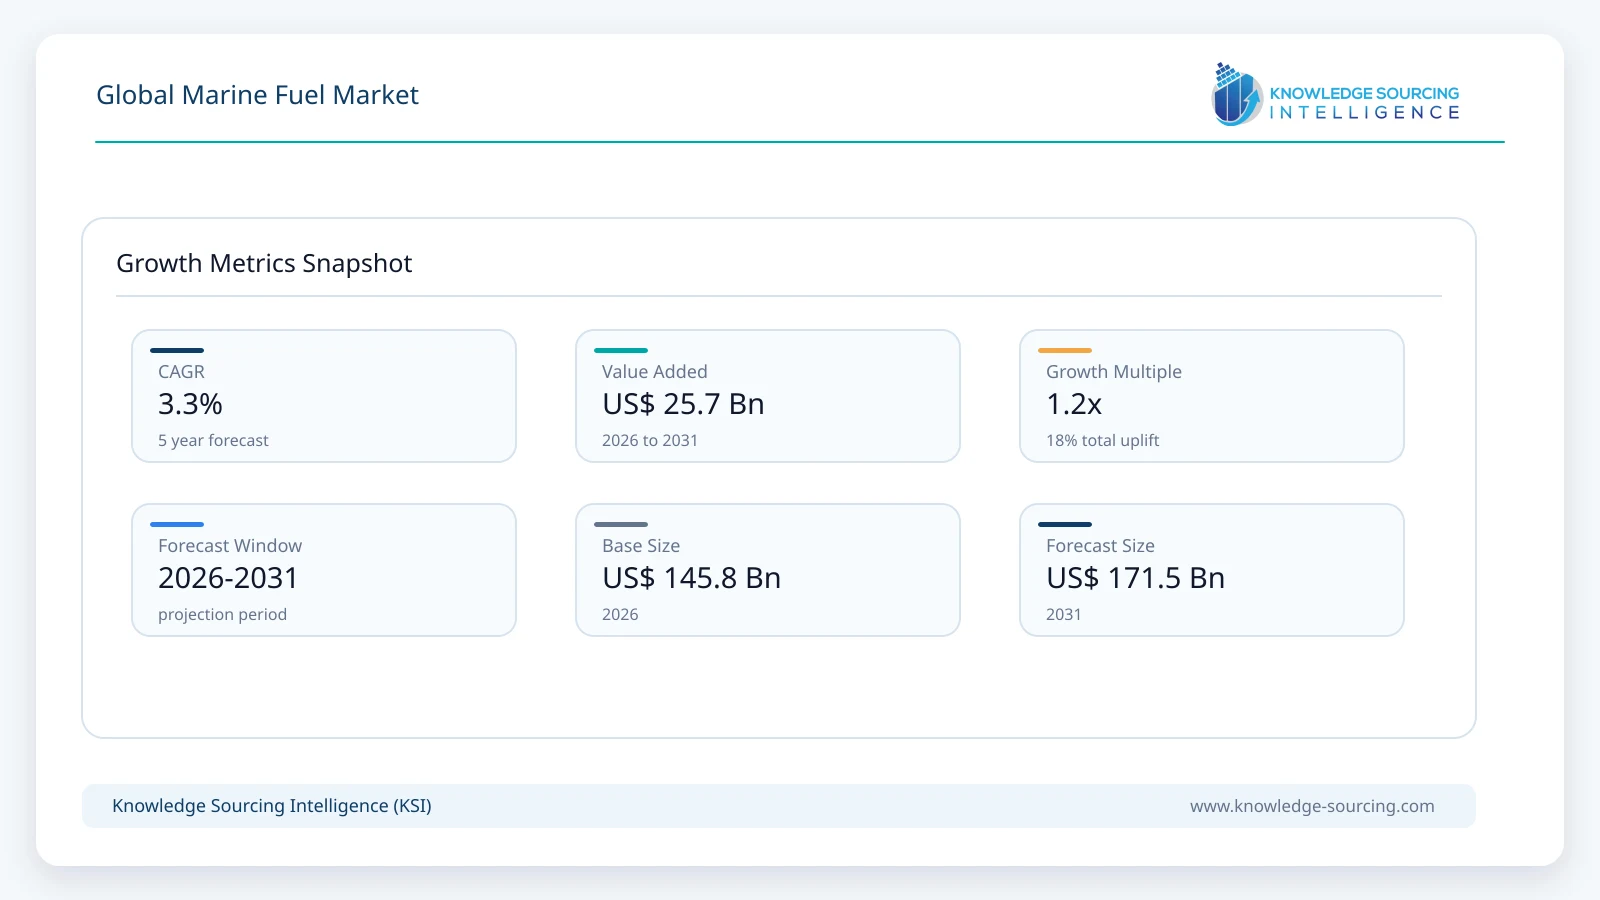
The global marine fuel market is forecast to grow from USD 145.8 billion in 2026 to USD 171.5 billion by 2031, representing a CAGR of 3.3% during the forecast period.
Highlights:
- 1VLSFO accounts for approximately 52% of global marine fuel market value in 2026.
- 2MGO/MDO is projected to grow at approximately 7.4% annually through 2031.
- 3Commercial shipping accounts for approximately 80% of marine fuel demand in 2026.
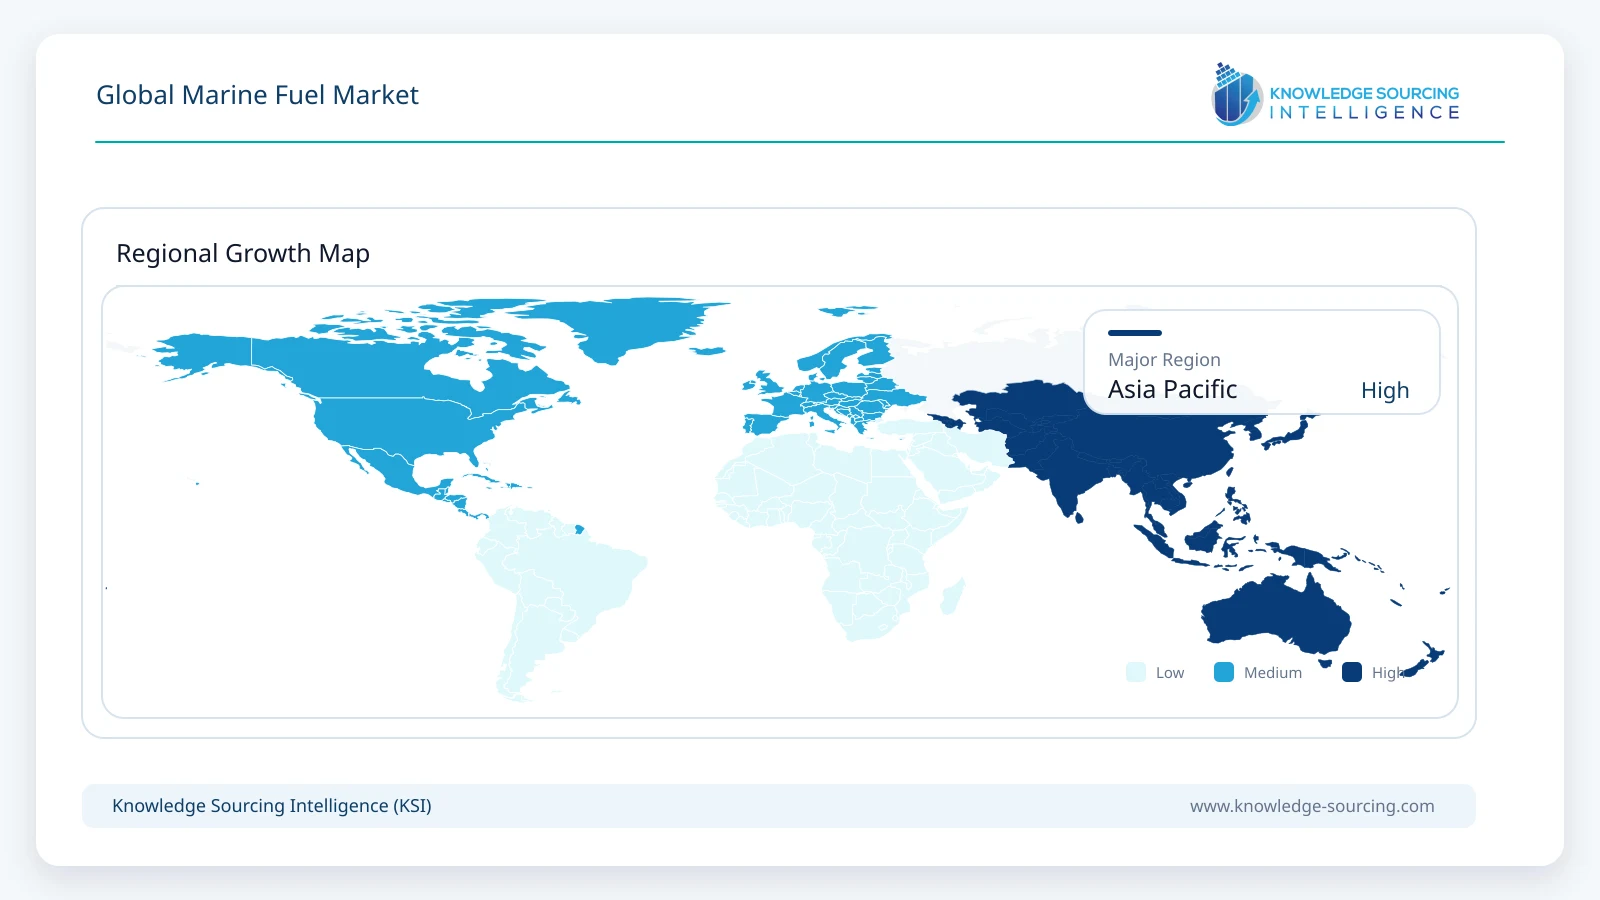
- 4Asia Pacific represents approximately 44% of global marine fuel market value in 2026.
- 5Singapore marine fuel sales reached a record 56.77 million tonnes in 2025.
Marine fuel remains a critical input for global shipping, supporting container vessels, bulk carriers, tankers, passenger ships, offshore vessels and government fleets. Demand is closely linked to fleet deployment, sailing distance, vessel speed, cargo movement and fuel efficiency.
UN Trade and Development reports that more than 80% of international merchandise trade by volume is transported by sea. Global commercial fleet capacity reached approximately 2.44 billion deadweight tonnes at the beginning of 2025, increasing 3.4% year over year, while container-ship capacity rose 9.7%. Maritime trade grew 2.2% during 2024, but ton-miles increased by nearly 6% as geopolitical disruption forced vessels onto longer routes. The divergence between cargo growth and sailing distance is important for fuel demand because longer voyages can increase total propulsion requirements even when trade-volume growth is moderate.
Fuel selection is also becoming more diversified. Conventional oil-based marine fuels continue to dominate the operating fleet, while LNG, methanol, biofuels and other alternatives gain importance in new vessel orders and port infrastructure. DNV recorded 275 alternative-fuel vessel orders during 2025, including 188 LNG-fuelled vessels and 61 methanol-fuelled vessels. Alternative-fuel ships represented 38% of newbuilding gross tonnage ordered during the year, showing that the fuel transition is progressing most rapidly through new fleet investment.
Major Market Drivers
Expansion of Merchant Fleet Capacity and Longer Maritime Trade Routes
Growth in the merchant fleet continues to support marine fuel demand. UN Trade and Development recorded approximately 112,500 commercial vessels of at least 100 gross tonnes at the beginning of 2025, with global carrying capacity reaching about 2.44 billion deadweight tonnes. Container capacity increased particularly rapidly, while bulk carriers remained the largest vessel category by deadweight capacity.
Fuel consumption is also influenced by sailing distance. Trade-route disruption in the Red Sea and other corridors has forced many vessels to reroute around the Cape of Good Hope, increasing voyage lengths. UNCTAD reported nearly 6% growth in global ton-miles during 2024, substantially above maritime trade-volume growth. Longer routes increase propulsion hours and bunker consumption per cargo movement, supporting fuel demand across container shipping, bulk commodities and tanker transportation despite improvements in vessel efficiency.
Environmental Regulations Are Reshaping Marine Fuel Purchasing
Sulfur and greenhouse-gas regulations are increasingly influencing marine fuel procurement. IMO sulfur requirements have already shifted a significant share of global demand toward VLSFO and marine distillates, while scrubber-equipped vessels continue to consume high-sulfur residual fuel.
FuelEU Maritime adds a further emissions dimension for ships calling at European Union ports. Ships above 5,000 gross tonnes are required to reduce the average greenhouse-gas intensity of onboard energy by 2% from 2025 and 6% from 2030 relative to the regulatory reference value. The regulation evaluates fuel performance on a lifecycle basis and allows operators to select different fuels and technologies according to vessel requirements.
IMO is also developing a broader global framework for reducing shipping emissions. The proposed Net-Zero Framework was approved in principle at MEPC 83 in April 2025, although formal adoption was postponed after the extraordinary session in October 2025 was adjourned for one year. Regulatory direction nevertheless continues to affect fleet investment, fuel contracting and bunkering infrastructure.
Major Market Restraints
Crude Oil and Bunker Price Volatility
Marine fuel represents a significant share of voyage operating expenditure, making the market highly sensitive to crude-oil prices, refinery margins and regional product availability. Prices can change rapidly when geopolitical developments, refinery outages, sanctions or trade disruptions affect crude and petroleum-product flows.
Fuel-price volatility affects both ship operators and suppliers. Shipping companies respond through slow steaming, route optimization, bunker-port selection, hedging and fuel-efficiency initiatives, while suppliers must manage inventory, credit and price exposure. Significant price movements can also alter the economic comparison between VLSFO, high-sulfur fuel, marine gas oil and alternative fuels.
Alternative-Fuel Infrastructure and Technology Uncertainty
The shipping industry is developing several potential replacement fuels rather than converging on one universal solution. LNG currently has the most established alternative bunkering infrastructure, while methanol adoption is increasing rapidly in selected vessel classes. Biofuels can be blended into existing fuel systems in many applications, whereas ammonia remains at an earlier stage of commercial deployment.
DNV recorded 188 LNG-fuelled vessel orders and 61 methanol-fuelled vessel orders during 2025, compared with considerably fewer ammonia-fuelled orders. (dnv.com)
The development of multiple fuel pathways creates a coordination challenge. Shipowners need confidence that fuel will be available along key routes, while producers and ports require sufficient demand before committing capital to new production and bunkering infrastructure. This slows the pace at which conventional marine fuels can be displaced across the global fleet.
Market Trends
VLSFO Remains the Primary Low-Sulfur Marine Fuel
Very low sulfur fuel oil remains the principal compliance fuel for vessels operating without exhaust-gas cleaning systems. Its availability across major global ports and compatibility with existing engines have enabled ship operators to comply with IMO sulfur limits without major propulsion modifications.
VLSFO accounts for approximately 52% of global marine fuel market value in 2026 and remains the largest fuel category through 2031. High-sulfur residual fuel continues to serve scrubber-equipped vessels, while marine gas and diesel oil gain share in areas subject to more stringent emissions limits.
Singapore Is Developing a Multi-Fuel Bunkering Model
Singapore remains the world’s largest bunkering hub and provides an important indication of how marine fuel supply is evolving. The Maritime and Port Authority reported marine fuel sales of 56.77 million tonnes in 2025, an all-time record and 3.4% higher than in 2024. Alternative marine fuel sales increased from 1.35 million tonnes in 2024 to 1.95 million tonnes in 2025.
Singapore is developing infrastructure for LNG, biofuels and methanol alongside conventional bunkers. Three methanol bunkering licences became effective on January 1, 2026 and remain valid through December 2030. This multi-fuel approach is likely to become increasingly common across large international bunkering centres.
Biofuels Are Expanding as a Near-Term Decarbonization Option
Marine biofuels are gaining interest because they can reduce lifecycle greenhouse-gas emissions while using much of the existing liquid-fuel storage, bunkering and vessel infrastructure. This reduces the technical barriers to adoption compared with fuels requiring entirely new propulsion systems.
Singapore permits licensed suppliers to provide qualifying marine biofuels and recognizes internationally accepted sustainability certification. Its framework also references ISO 8217:2024, which includes specifications relevant to marine fuels containing fatty-acid methyl esters and paraffinic diesel fuels.
Commercial suppliers are expanding their capabilities accordingly. Uni-Fuels announced on February 12, 2026 that it had renewed its ISCC EU and ISCC PLUS certifications following its first ISCC-certified marine biofuel delivery during 2025.
LNG Maintains the Largest Alternative-Fuel Newbuilding Base
LNG continues to hold the strongest position among alternative marine fuels for large commercial vessels because engines, storage technology and bunkering infrastructure are available at greater scale than for most alternatives.
DNV reported that LNG accounted for 188 alternative-fuel vessel orders in 2025, while approximately 58% of container-ship newbuilding gross tonnage ordered during the year was LNG-fuelled.
Methane-slip reduction and access to renewable or synthetic methane remain important to LNG’s long-term emissions performance, but existing infrastructure supports its role during the maritime fuel transition.
Segment Analysis
By Fuel Type
Very Low Sulfur Fuel Oil
Very low sulfur fuel oil accounts for approximately 52% of global marine fuel market value in 2026, making it the largest fuel type. Its position is supported by the IMO sulfur limit and widespread use among vessels that do not operate exhaust-gas cleaning systems.
VLSFO remains the largest fuel category through 2031. Demand continues to be supported by the large installed base of conventionally powered ships and extensive global bunkering availability. High-sulfur fuel remains important for scrubber-equipped vessels, while marine distillates gain share in areas subject to tighter emissions requirements.
By Application
Commercial Shipping
Commercial shipping accounts for approximately 80% of global marine fuel market value in 2026, reflecting the scale of container shipping, dry bulk, tanker and general cargo activity. More than 80% of global merchandise trade by volume is transported by sea, creating a large recurring fuel-consumption base. (unctad.org)
The segment remains dominant through 2031. Vessel-efficiency improvements reduce fuel consumption per unit of cargo, but fleet expansion, longer trade routes and growing container capacity support overall demand.
By End User
Container Shipping
Container shipping accounts for approximately 29% of global marine fuel market value in 2026. Container ships generally operate at higher speeds than many bulk carriers and are strongly exposed to schedule reliability, port congestion and route disruptions.
UN Trade and Development reported that global container-ship carrying capacity increased 9.7% during 2024, reaching approximately 364 million deadweight tonnes at the beginning of 2025. This was significantly faster than overall merchant fleet growth.
Container shipping also plays an important role in the transition toward alternative fuels. DNV reported that containerships accounted for 68% of alternative-fuel vessel orders during 2025, making the segment one of the most important early adopters of LNG, methanol, and other fuel technologies.
By Geography
Asia Pacific
Asia Pacific accounts for approximately 44% of global marine fuel market value in 2026, making it the largest regional market. The region combines the world’s largest bunkering hub in Singapore with major ports, shipyards, refineries and maritime trade centres across China, South Korea, Japan and India.
Singapore sold a record 56.77 million tonnes of marine fuel in 2025, while container throughput reached 44.66 million TEUs. Alternative marine fuel sales increased to 1.95 million tonnes during the year.
Asia Pacific remains the largest regional market through 2031 as trade flows, container activity and multi-fuel bunkering capacity expand. Singapore, China, South Korea and Japan are also expected to remain important locations for LNG, methanol, biofuel and future ammonia bunkering infrastructure.
Competitive Landscape
The marine fuel market includes integrated energy companies, refiners, physical bunker suppliers and international trading companies. Shell, BP, ExxonMobil, TotalEnergies, Chevron, Sinopec and Indian Oil combine fuel production with varying levels of marine distribution, while companies such as Vitol, Bunker Holding, Peninsula, TFG Marine, World Kinect, Monjasa and Uni-Fuels focus heavily on marine fuel procurement, trading, physical supply and logistics.
Competition increasingly extends beyond conventional bunker availability. Shipping companies require low-sulfur fuels, credit support, price-risk management, global port coverage and access to an expanding range of biofuel, LNG and methanol products. Sustainability documentation and fuel-emissions data are also becoming increasingly important for vessels operating under FuelEU Maritime and other carbon-regulation frameworks.
Conventional marine fuel supply remains fundamental because the majority of the operating fleet continues to depend on petroleum-derived fuels. Large suppliers are therefore developing broader portfolios that combine conventional bunkers with lower-carbon alternatives.
Recent Developments
September 2026: Bunker Holding strengthened its commercial leadership structure to support its “Fueling the Future” strategy, focusing on customer value, stronger collaboration, commercial capabilities, and long-term growth across its global marine-fuel business.
May 2026: TFG Marine completed its first electronic bunker delivery notice trial at Port Louis, Mauritius, with ZeroNorth, advancing digital documentation, transparency, auditability, and efficiency across marine-fuel bunkering operations.
May 2026: TFG Marine increased its working-capital capacity through a USD 300 million DBS facility, supported by electronic bunker delivery notices to improve transparency and digitalisation across marine-fuel transactions.
April 2026: World Fuel Services established over-the-water methanol bunkering capability with West Coast Clean Fuels after successfully completing a South Florida delivery, creating a scalable marine-fuel solution across U.S. ports.
April 2026: Uni-Fuels reported 2025 marine-fuel volumes exceeding 535,000 metric tonnes, up 112% year-on-year, while expanding its global operating footprint to 156 ports and strengthening international bunkering operations.
March 2026: Uni-Fuels expanded bunkering operations across Thailand, including Bangkok, Laem Chabang, Sriracha, Phuket and other Gulf of Thailand and Andaman Sea locations.
Regulatory Outlook
IMO sulfur regulations remain the principal global specification governing conventional marine fuel sulfur content. The next phase of regulation increasingly focuses on greenhouse-gas intensity and lifecycle emissions.
IMO approved the draft Net-Zero Framework at MEPC 83 in April 2025, including a proposed global marine fuel standard and greenhouse-gas pricing mechanism. Formal adoption was not completed in October 2025 after the extraordinary session was adjourned for one year.
FuelEU Maritime already applies within the European Union. Ships above 5,000 gross tonnes calling at EU ports are required to reduce the annual average greenhouse-gas intensity of onboard energy by 2% from 2025 and 6% from 2030, with progressively tighter requirements thereafter.)
These requirements support demand for compliant VLSFO and marine gas oil while accelerating investment in LNG, sustainable biofuels, methanol and other lower-carbon marine fuels.
Market Outlook
The global marine fuel market growth remains moderate as merchant fleet expansion and increasing voyage distances are partially offset by improved vessel efficiency, slow steaming and progressive adoption of alternative fuels.
VLSFO remains the largest fuel category through 2031, while marine gas oil and marine diesel oil grow faster as emissions-control requirements expand. High-sulfur residual fuel continues to serve vessels equipped with exhaust-gas cleaning systems.
Commercial shipping remains the principal source of demand, with container vessels, bulk carriers and tankers accounting for most marine fuel consumption. Asia Pacific continues to lead global demand through its concentration of major ports, shipping routes, refineries and bunkering centres.
The fuel transition becomes increasingly visible through LNG, marine biofuels and methanol, but conventional oil-based bunkers continue to represent the majority of marine fuel consumption through 2031.
Marine Fuel Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 145.8 billion |
| Total Market Size in 2031 | USD 171.5 billion |
| Forecast Unit | Billion |
| Growth Rate | 3.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Fuel Type, Application, End-user, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Regulatory and Fuel-Transition Outlook
IMO 2020 Sulfur Regulations
Emission Control Areas
IMO 2023 GHG Strategy
Proposed IMO Net-Zero Framework
FuelEU Maritime
EU Emissions Trading System
LNG as Marine Fuel
Marine Biofuels
Methanol
Ammonia and Hydrogen
Bunkering Infrastructure Development
By Fuel Type
Residual Fuel Oil / High Sulfur Fuel Oil
Very Low Sulfur Fuel Oil
Marine Gas Oil / Marine Diesel Oil
By Application
Commercial Shipping
Passenger & Leisure
Offshore & Energy
Defense & Government
Others
By End User
Container Shipping
Bulk Shipping
Oil Tanker
Gas Tanker
Chemical Tanker
General Cargo
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Netherlands
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Singapore
India
Japan
South Korea
Taiwan
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits for Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
2.3. Primary Research Framework
2.4. Secondary Research Framework
2.5. Data Triangulation
2.6. Forecast Methodology
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Merchant Fleet Expansion and Longer Maritime Trade Routes
4.1.2. IMO Sulfur Rules and FuelEU Maritime Compliance
4.1.3. Expansion of Multi-Fuel Bunkering Infrastructure
4.1.4. Container, Bulk Commodity and Energy Transportation Demand
4.2. Market Restraints
4.2.1. Crude Oil, Refining and Bunker Price Volatility
4.2.2. Alternative-Fuel Infrastructure and Technology Uncertainty
4.2.3. High Capital Cost of Dual-Fuel Vessels and Fleet Retrofitting
4.2.4. Regulatory Uncertainty Around Global Shipping Decarbonization Measures
4.3. Market Opportunities
4.4. Porter’s Five Forces Analysis
4.5. Industry Value Chain Analysis
4.6. Strategic Recommendations
5. REGULATORY AND FUEL-TRANSITION OUTLOOK
5.1. IMO 2020 Sulfur Regulations
5.2. Emission Control Areas
5.3. IMO 2023 GHG Strategy
5.4. Proposed IMO Net-Zero Framework
5.5. FuelEU Maritime
5.6. EU Emissions Trading System
5.7. LNG as Marine Fuel
5.8. Marine Biofuels
5.9. Methanol
5.10. Ammonia and Hydrogen
5.11. Bunkering Infrastructure Development
6. GLOBAL MARINE FUEL MARKET BY FUEL TYPE
6.1. Introduction
6.2. Residual Fuel Oil / High Sulfur Fuel Oil
6.3. Very Low Sulfur Fuel Oil
6.4. Marine Gas Oil / Marine Diesel Oil
7. GLOBAL MARINE FUEL MARKET BY APPLICATION
7.1. Introduction
7.2. Commercial Shipping
7.3. Passenger & Leisure
7.4. Offshore & Energy
7.5. Defense & Government
7.6. Others
8. GLOBAL MARINE FUEL MARKET BY END USER
8.1. Introduction
8.2. Container Shipping
8.3. Bulk Shipping
8.4. Oil Tanker
8.5. Gas Tanker
8.6. Chemical Tanker
8.7. General Cargo
9. GLOBAL MARINE FUEL MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. Germany
9.3.2. France
9.3.3. United Kingdom
9.3.4. Spain
9.3.5. Netherlands
9.3.6. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. South Africa
9.4.4. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. Singapore
9.5.3. India
9.5.4. Japan
9.5.5. South Korea
9.5.6. Taiwan
9.5.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Shell plc
11.2. TotalEnergies SE
11.3. BP p.l.c.
11.4. Exxon Mobil Corporation
11.5. Vitol Group
11.6. Bunker Holding Group A/S
11.7. Peninsula
11.8. TFG Marine Pte. Ltd.
11.9. World Kinect Corporation
11.10. Sinopec
11.11. Indian Oil Corporation Limited
11.12. Uni-Fuels Holdings Limited
12. APPENDIX





Frequently asked questions
What is the projected market size of the Global Marine Fuel Market by 2031?
Projected to reach USD 171.5 billion by 2031, with a 3.3% CAGR.
Which marine fuel type holds the largest market value share in 2026?
VLSFO accounts for approximately 52% of market value in 2026.
Which industry segment accounts for the most marine fuel demand?
Commercial shipping accounts for 80% of marine fuel demand in 2026.
Which region holds the largest share of the Global Marine Fuel Market?
Asia Pacific represents 44% of Global Marine Fuel Market value in 2026.
What are the major drivers of the marine fuel market growth?
Expansion of merchant fleet capacity and longer maritime trade routes.
What is the outlook for alternative fuels in marine shipping?
Alternative fuels gained importance, 38% of newbuilding gross tonnage in 2025.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Global Marine Fuel Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/global-marine-fuel-market