
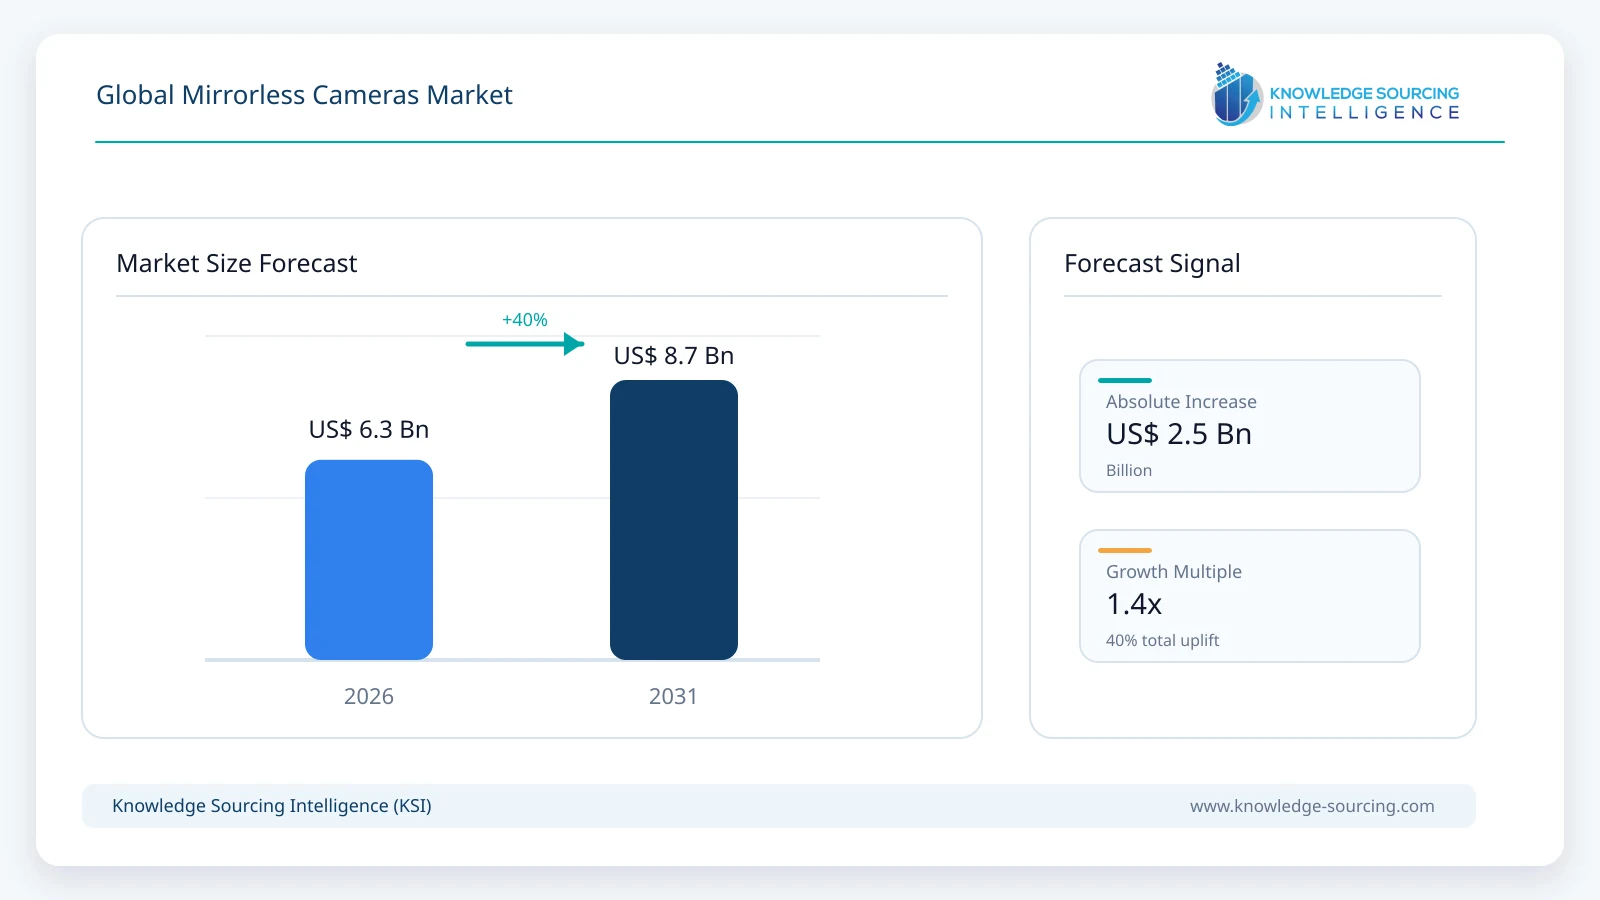
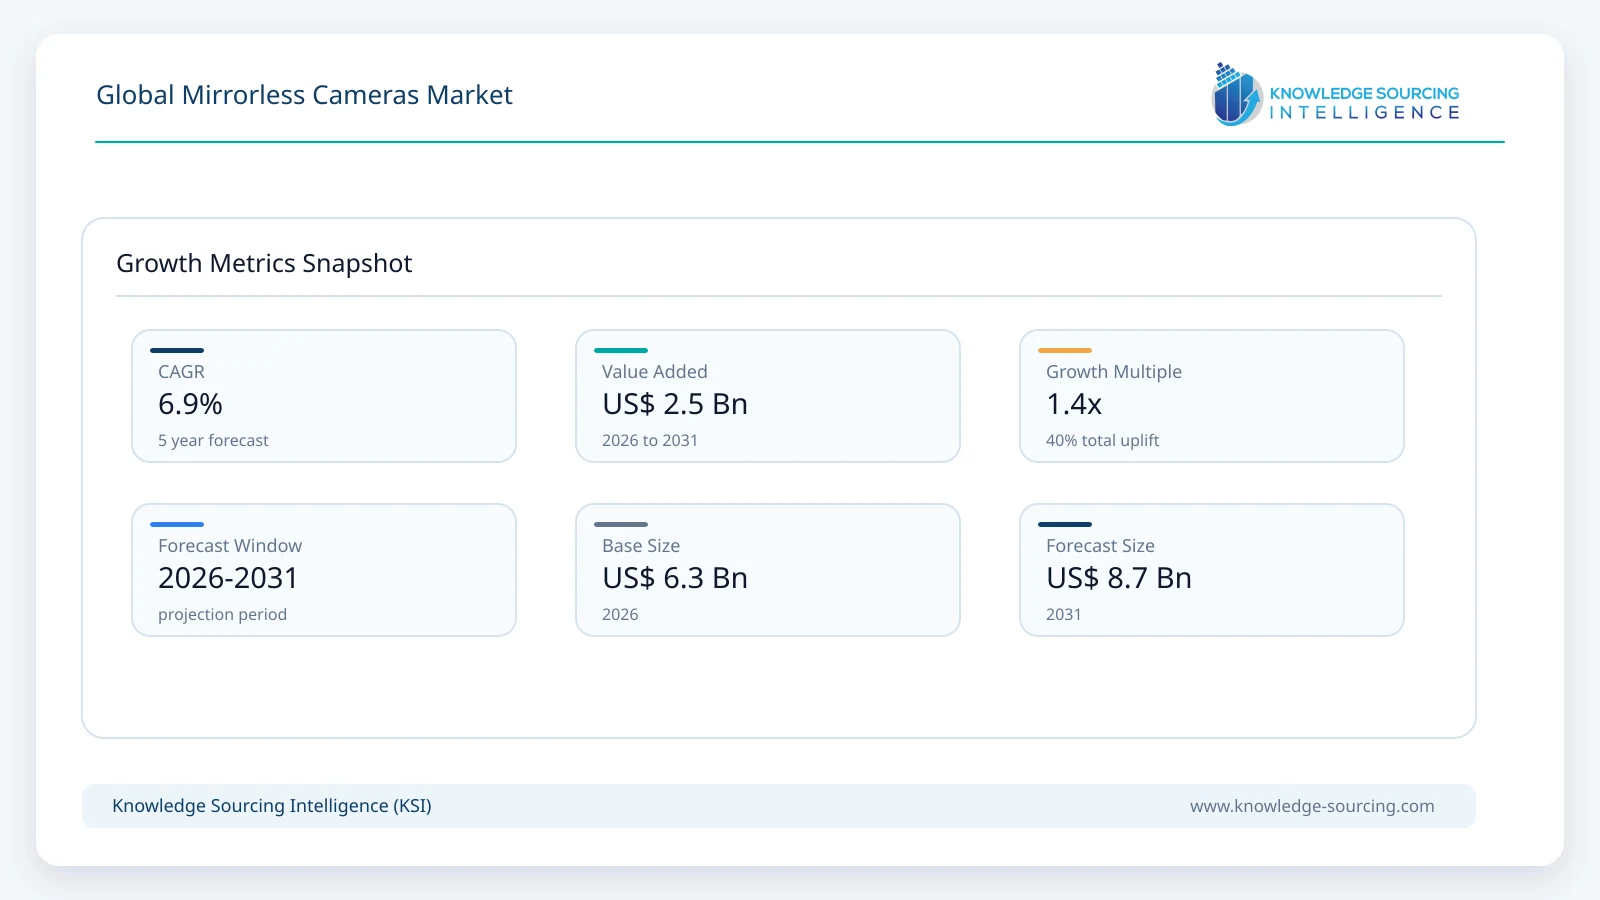
The global mirrorless camera market is estimated at USD 6.25 billion in 2026 and is projected to reach USD 8.74 billion by 2031, growing at a CAGR of 6.94% during the forecast period.
Highlights:
- 1Mirrorless camera demand is increasingly supported by hybrid photo-video workflows and creator-focused purchasing decisions.
- 2Product differentiation has shifted from hardware specifications toward autofocus, video capability, computational imaging, and lens ecosystems.
- 3Premium interchangeable-lens systems continue to attract enthusiasts and professional users replacing ageing DSLR equipment.
- 4Asia Pacific remains central to manufacturing, product development, and domestic demand, while North America and Europe sustain premium camera purchases.
- 5Competition increasingly extends beyond camera bodies to lenses, software features, firmware support, and creator ecosystem partnerships.
Demand increasingly reflects changing imaging workflows rather than simple camera replacement cycles. Buyers now evaluate products based on autofocus performance, video recording capability, computational processing, wireless connectivity, battery efficiency, and long-term access to compatible lenses and accessories.
Purchasing behavior has become increasingly selective. Casual photography continues to migrate toward premium smartphones, leaving dedicated cameras concentrated among users requiring optical flexibility, larger image sensors, interchangeable lenses, and professional production capabilities. This shift has encouraged manufacturers to prioritize higher-value products, firmware upgrades, premium optics, and ecosystem expansion instead of pursuing shipment volume alone.
Industry shipment data illustrates this structural transition. According to the Camera & Imaging Products Association (CIPA), interchangeable-lens cameras represented the majority of global digital camera shipments during 2025, while mirrorless systems accounted for approximately 85% of interchangeable-lens shipments, reinforcing the industry's migration away from DSLR platforms.
Competition increasingly depends on complete imaging ecosystems rather than camera specifications alone. Lens availability, creator-focused software, artificial intelligence-assisted autofocus, video production features, cloud connectivity, and long-term firmware support influence purchasing decisions across both professional and enthusiast segments. Manufacturers are also balancing premium product positioning with supply-chain resilience, component availability, and investments in regional manufacturing capacity to sustain profitability despite relatively modest industry shipment volumes.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Global digital camera shipments | 9.44 million units (2025) | Indicates continued recovery in dedicated camera demand. |
Interchangeable-lens camera shipments | 7.00 million units (2025) | Professional and enthusiast systems remain the industry's largest revenue contributor. |
Mirrorless share of interchangeable-lens shipments | Approximately 85% (2024) | Mirrorless systems have become the industry's primary interchangeable-lens platform. |
Camera production | 9.13 million units (2025) | Manufacturers maintained higher production to support recovering global demand. |
Export-oriented shipments | 8.44 million units (2025) | International markets remain the principal revenue source for camera manufacturers. |
Key indicator: Mirrorless cameras represented roughly 85% of interchangeable-lens shipments in 2024.
Commercial meaning: Product development, lens investment, and channel strategies increasingly revolve around mirrorless platforms.
Market Drivers
Expansion of hybrid photo and video production. Professional photographers, independent filmmakers, corporate media teams, and digital creators increasingly require equipment that produces high-resolution still images alongside advanced video formats within a single device. This has raised demand for mirrorless systems offering rapid autofocus, in-body image stabilization, high-frame-rate recording, and efficient data workflows. Company product launches and investor communications from major manufacturers increasingly prioritize hybrid imaging capabilities, reflecting customer demand for versatile equipment rather than separate photography and cinema platforms. Official CIPA shipment trends also indicate continued strength in interchangeable-lens systems supporting these professional applications.
Replacement of ageing DSLR equipment. Many photographers continue replacing DSLR bodies purchased during the previous decade as manufacturers shift research, product launches, and lens development toward mirrorless platforms. Customers increasingly value faster subject recognition, electronic viewfinders, silent shooting, improved low-light performance, and continuous firmware enhancements unavailable on legacy DSLR systems. CIPA data confirms mirrorless cameras account for the overwhelming majority of interchangeable-lens shipments, demonstrating that replacement demand has become concentrated within mirrorless ecosystems rather than traditional DSLR platforms. Suppliers are responding by expanding native lens portfolios and introducing accessories designed specifically for mirrorless users.
Growth of premium lens ecosystems. Purchasing decisions increasingly depend on long-term access to compatible lenses instead of camera bodies alone. Professional users often invest in systems supporting multiple focal lengths, specialized optics, and future upgrades without changing mounts. Manufacturers continue expanding native lens portfolios while third-party suppliers broaden compatibility across major mirrorless mounts. Recent industry disclosures indicate continued investment in interchangeable-lens development despite relatively stable camera shipment volumes, reflecting higher customer spending on complete imaging systems rather than standalone hardware.
Higher spending by enthusiast photographers. Dedicated photography enthusiasts increasingly prioritize image quality, portability, weather sealing, and computational features that smartphones cannot fully replicate. Instead of replacing cameras frequently, buyers are investing in premium bodies offering longer operational lifecycles supported by firmware upgrades and accessory ecosystems. Manufacturers have adjusted product portfolios toward higher-value models that improve profitability despite moderate shipment growth. This strategy aligns with official shipment data showing stronger performance in interchangeable-lens categories than lower-value consumer imaging products.
Market Restraints and Challenges
Smartphone imaging continues reducing entry-level demand. Smartphone manufacturers continue improving computational photography, video stabilization, artificial intelligence-assisted image processing, and low-light performance. Casual users increasingly satisfy everyday photography requirements without purchasing dedicated cameras, narrowing the customer base primarily to enthusiasts and professionals. Manufacturers therefore compete for higher-value customers instead of pursuing mass-market adoption, increasing dependence on premium pricing and specialized product differentiation rather than shipment expansion.
High ownership costs beyond the camera body. Purchasing a mirrorless system frequently requires additional investment in interchangeable lenses, memory cards, batteries, external microphones, stabilization equipment, and editing software. Professional users generally accept these costs because of commercial requirements, but entry-level buyers often postpone purchases or remain within smartphone ecosystems. Companies continue introducing more affordable camera bodies, yet complete system ownership remains considerably more expensive than consumer mobile photography.
Supply-chain dependence on precision electronic components. Mirrorless cameras require advanced image sensors, processors, displays, optical components, and semiconductor devices sourced through globally distributed supply chains. Component shortages, logistics disruptions, and manufacturing concentration can extend product lead times and complicate inventory planning. Several imaging companies have identified supply-chain resilience and procurement risk as continuing operational priorities in recent corporate disclosures, encouraging investments in diversified manufacturing and supplier networks even after broader semiconductor conditions improved.
Long replacement cycles among existing users. Professional photographers generally retain camera bodies for several years, replacing equipment only when meaningful improvements justify additional investment. Incremental hardware upgrades may not immediately stimulate purchasing activity unless accompanied by measurable gains in autofocus, video capability, workflow efficiency, or lens compatibility. Manufacturers therefore face increasing pressure to differentiate products through software features, creator services, and ecosystem expansion instead of relying solely on periodic hardware refreshes.
Major Segment Analysis
Professional Mirrorless
Professional mirrorless cameras represent the most commercially important segment because purchasing decisions extend well beyond the camera body. Commercial photographers, broadcasters, filmmakers, sports photographers, wildlife specialists, and production studios typically invest in complete imaging ecosystems comprising lenses, accessories, software, and long-term service support. Procurement priorities emphasize autofocus reliability, continuous shooting performance, low-light capability, thermal management during extended video recording, weather sealing, and compatibility with established lens mounts. These requirements support higher average selling prices and recurring revenue through accessory and lens purchases.
Competition within this segment increasingly focuses on operational efficiency rather than headline specifications. Buyers expect regular firmware updates, AI-assisted subject recognition, advanced video codecs, and seamless integration with editing workflows. Although entry-level models broaden access to interchangeable-lens photography, professional systems remain an important revenue source because purchasing decisions are influenced by reliability, long product lifecycles, and ecosystem continuity rather than initial acquisition cost alone.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
North America | Creator economy, commercial media production, professional photography | Mature replacement market and smartphone substitution |
Europe | Professional imaging, broadcasting, premium consumer demand | Inflationary pressure affecting discretionary purchases |
Asia Pacific | Manufacturing base, domestic demand, expanding creator market | Intense price competition across product tiers |
Middle East and Africa | Commercial media, tourism, government investment | Limited specialist retail and service infrastructure |
North America remains an important market for premium mirrorless cameras because commercial photography, advertising, sports broadcasting, film production, and digital content creation sustain demand for high-performance imaging systems. The United States accounts for the largest share of regional purchases, supported by an established network of specialist retailers, rental providers, and professional service programs. Buyers increasingly prioritize hybrid cameras that support both still photography and professional video production, encouraging manufacturers to introduce premium full-frame models and expand after-sales support.
European demand is supported by commercial photography, creative industries, documentary production, and professional broadcasting across Germany, the United Kingdom, France, and other established markets. Environmental regulations and product sustainability expectations increasingly influence purchasing decisions, encouraging manufacturers to strengthen repair services, firmware support, and product longevity. Premium interchangeable-lens systems continue to attract enthusiasts despite slower replacement cycles resulting from economic uncertainty.
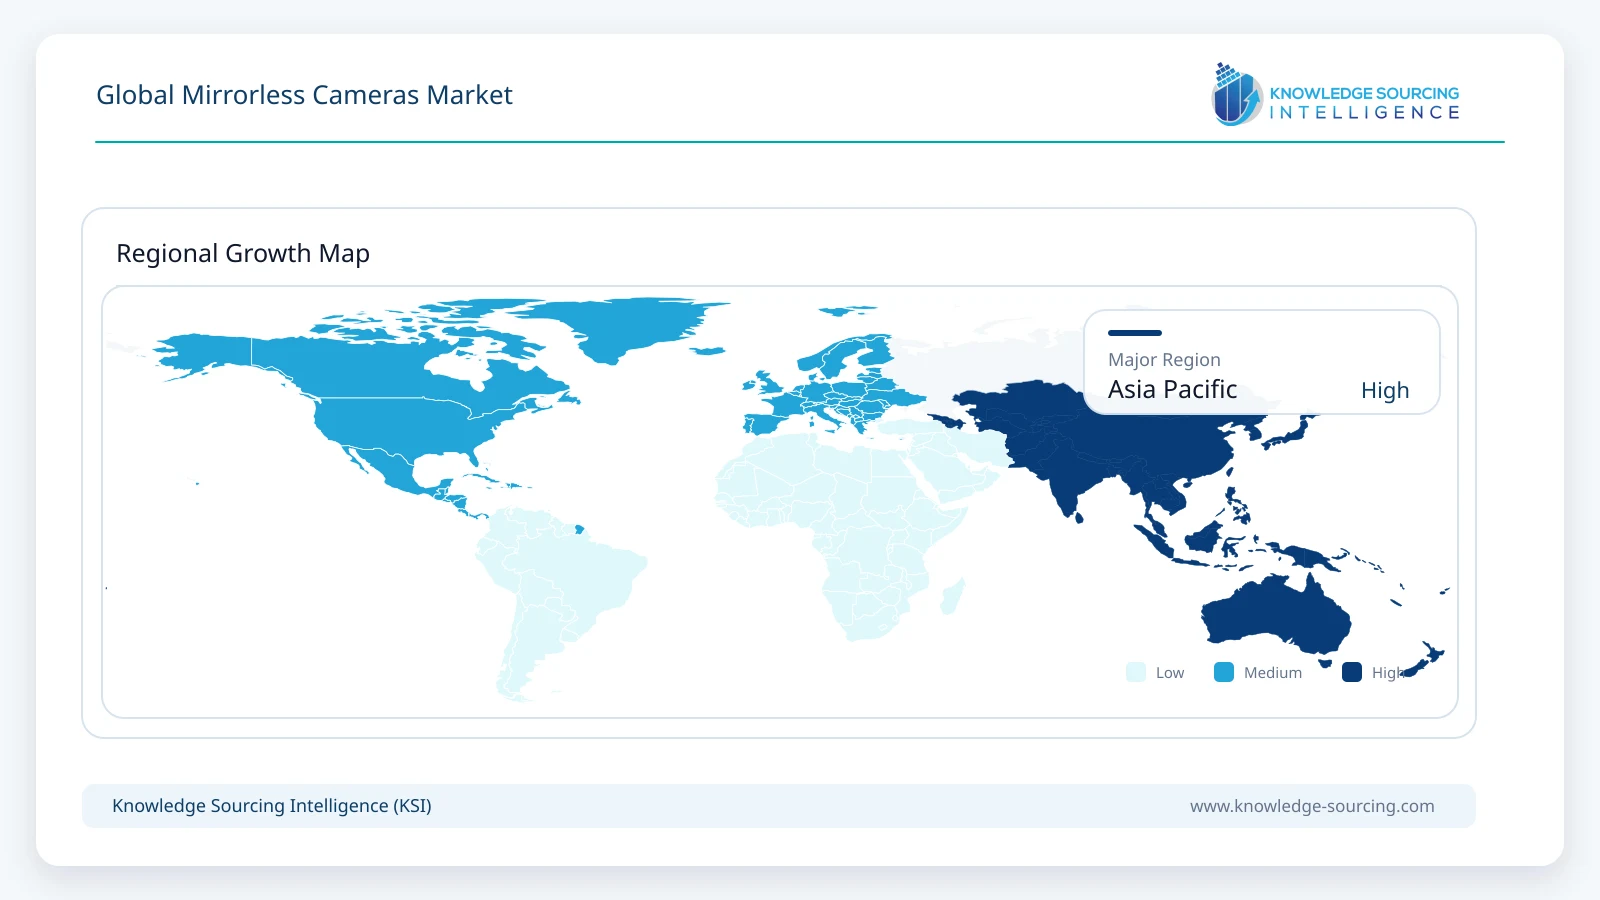
Asia Pacific occupies a central position across the mirrorless camera value chain because it combines manufacturing capacity, component production, research and development, and growing domestic demand. Japan remains home to most global camera manufacturers, while China provides manufacturing capability and a rapidly expanding creator economy. India, South Korea, and Southeast Asian countries are recording stronger interest in content creation, wedding photography, and digital media production, broadening the customer base for entry-level and mid-range mirrorless systems alongside professional equipment.
The Middle East and Africa represent a smaller but commercially relevant market supported by tourism, sports events, government media organizations, and expanding digital content production. Demand is concentrated in countries such as the United Arab Emirates and Saudi Arabia, where investment in entertainment, cultural events, and media production supports purchases of professional imaging equipment. Distribution networks and technical service availability remain less extensive than in mature markets, influencing purchasing decisions toward internationally recognized brands with established regional support.
Competitive Landscape
The global mirrorless cameras market remains moderately concentrated, with competition shaped by imaging technology, lens ecosystems, software capability, and brand credibility rather than shipment volume alone. Sony Corporation, Canon Inc., and Nikon Corporation compete across professional and enthusiast segments through full-frame product portfolios, proprietary lens systems, autofocus performance, and creator-focused firmware enhancements. Fujifilm Holdings Corporation differentiates through APS-C and medium-format systems, while Panasonic Holdings Corporation strengthens its position in hybrid imaging by combining professional video capabilities with mirrorless platforms.
Specialized manufacturers including OM Digital Solutions Corporation, Leica Camera AG, Sigma Corporation, Hasselblad, and Blackmagic Design focus on distinct customer groups requiring portability, premium optics, medium-format imaging, cinema production, or specialist workflow integration. Competition increasingly extends to lens availability, software updates, creator services, and long-term ecosystem support. Companies are also expanding native lens portfolios, strengthening regional service networks, and improving supply-chain resilience to maintain product availability while responding to evolving professional imaging requirements.
Recent Developments
January 2026 – Nikon released ZR firmware expansion for Z CINEMA: Nikon updated the ZR cinema camera with improved recording duration, timecode support, and workflow enhancements, strengthening its RED-integrated full-frame mirrorless video ecosystem for creators.
September 2025 – Nikon launched ZR full-frame cinema camera: Nikon introduced the ZR under its Z CINEMA series, combining RED technology, R3D NE recording, 6K RAW video, and compact design for professional filmmakers and hybrid creators.
June 2025 – Fujifilm launched the FUJIFILM X-E5 mirrorless camera: Fujifilm unveiled the X-E5 featuring a 40.2MP X-Trans CMOS 5 HR sensor, X-Processor 5, compact body, and five-axis IBIS, targeting enthusiasts seeking premium portable photography.
February 2025 – RED released Z-mount cinema cameras through Nikon collaboration: RED Digital Cinema introduced V-RAPTOR [X] Z Mount and KOMODO-X Z Mount cameras, expanding Nikon Z-mount compatibility and creating new professional mirrorless video workflows.
Regulatory and Policy Environment
Mirrorless camera manufacturers operate within a regulatory framework that extends beyond product safety to include environmental compliance, wireless communications, international trade, and intellectual property protection. Requirements such as the European Union's Restriction of Hazardous Substances (RoHS), Waste Electrical and Electronic Equipment (WEEE) Directive, REACH chemical regulations, and battery legislation affect material selection, manufacturing processes, recycling obligations, and after-sales responsibilities.
International trade policies also influence production strategies because camera manufacturing depends on globally distributed supply chains spanning image sensors, semiconductors, optical glass, displays, and precision mechanical components. Export controls, tariff adjustments, and customs regulations can affect production costs and sourcing decisions. Compliance with wireless communication standards, cybersecurity expectations for connected devices, and intellectual property licensing remains essential as manufacturers continue integrating cloud connectivity, wireless transfer, and software-driven imaging functions into mirrorless camera platforms.
Outlook and Strategic Implications
Mirrorless cameras are expected to strengthen their position as the primary interchangeable-lens imaging platform during the 2026–2031 forecast period. Future demand will depend less on expanding the overall camera user base and more on increasing value per customer through premium bodies, specialized optics, software features, and integrated imaging ecosystems. Professional creators, commercial studios, and advanced enthusiasts will continue to represent the most resilient customer groups because their purchasing decisions are linked to operational performance rather than casual photography.
Several strategic priorities are expected to shape market performance over the forecast period:
Manufacturers are likely to prioritize AI-assisted autofocus, computational imaging, and hybrid photo-video capabilities to support professional workflows.
Native lens expansion, firmware support, and ecosystem compatibility will remain important factors influencing customer retention and long-term revenue.
Supply-chain diversification and manufacturing resilience will continue receiving investment to reduce sourcing risks associated with precision electronic components.
Regional growth opportunities will increasingly emerge from expanding creator economies in Asia Pacific and selected Middle Eastern markets, while North America and Europe remain important markets for premium replacement demand.
Commercial success will increasingly depend on ecosystem strength rather than individual camera specifications. Suppliers capable of combining imaging hardware, optics, software, professional services, and long-term platform support are expected to remain better positioned to capture higher-value customer segments as industry shipment volumes stabilize.
Mirrorless Cameras Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 6.25 billion |
| Total Market Size in 2031 | USD 8.74 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.94% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Distribution Channel, Geography |
| Companies |
|
Market Segmentation
By Type
- Entry-level Mirrorless
- Mid-range Mirrorless
- Professional Mirrorless
By Distribution Channel
- Online
- Offline
By Geography
- North America
- USA
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Others
- Europe
- United Kingdom
- Germany
- France
- Spain
- Others
- Middle East and Africa
- Saudi Arabia
- UAE
- Israel
- Others
- Asia Pacific
- China
- Japan
- India
- South Korea
- Taiwan
- Thailand
- Indonesia
- Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits for the Stakeholder
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Processes
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
4.5. Analyst View
5. GLOBAL MIRRORLESS CAMERA MARKET, BY TYPE
5.1. Introduction
5.2. Entry-level Mirrorless
5.2.1. Market Trends and Opportunities
5.2.2. Growth Prospects
5.2.3. Geographic Lucrativeness
5.3. Mid-range Mirrorless
5.3.1. Market Trends and Opportunities
5.3.2. Growth Prospects
5.3.3. Geographic Lucrativeness
5.4. Professional Mirrorless
5.4.1. Market Trends and Opportunities
5.4.2. Growth Prospects
5.4.3. Geographic Lucrativeness
6. GLOBAL MIRRORLESS CAMERA MARKET, BY DISTRIBUTION CHANNEL
6.1. Introduction
6.2. Online
6.2.1. Market Trends and Opportunities
6.2.2. Growth Prospects
6.2.3. Geographic Lucrativeness
6.3. Offline
6.3.1. Market Trends and Opportunities
6.3.2. Growth Prospects
6.3.3. Geographic Lucrativeness
7. GLOBAL MIRRORLESS CAMERA MARKET, BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. By Type
7.2.2. By Distribution Channel
7.2.3. By Country
7.2.3.1. USA
7.2.3.1.1. Market Trends and Opportunities
7.2.3.1.2. Growth Prospects
7.2.3.2. Canada
7.2.3.2.1. Market Trends and Opportunities
7.2.3.2.2. Growth Prospects
7.2.3.3. Mexico
7.2.3.3.1. Market Trends and Opportunities
7.2.3.3.2. Growth Prospects
7.3. South America
7.3.1. By Type
7.3.2. By Distribution Channel
7.3.3. By Country
7.3.3.1. Brazil
7.3.3.1.1. Market Trends and Opportunities
7.3.3.1.2. Growth Prospects
7.3.3.2. Argentina
7.3.3.2.1. Market Trends and Opportunities
7.3.3.2.2. Growth Prospects
7.3.3.3. Others
7.3.3.3.1. Market Trends and Opportunities
7.3.3.3.2. Growth Prospects
7.4. Europe
7.4.1. By Type
7.4.2. By Distribution Channel
7.4.3. By Country
7.4.3.1. United Kingdom
7.4.3.1.1. Market Trends and Opportunities
7.4.3.1.2. Growth Prospects
7.4.3.2. Germany
7.4.3.2.1. Market Trends and Opportunities
7.4.3.2.2. Growth Prospects
7.4.3.3. France
7.4.3.3.1. Market Trends and Opportunities
7.4.3.3.2. Growth Prospects
7.4.3.4. Spain
7.4.3.4.1. Market Trends and Opportunities
7.4.3.4.2. Growth Prospects
7.4.3.5. Others
7.4.3.5.1. Market Trends and Opportunities
7.4.3.5.2. Growth Prospects
7.5. Middle East and Africa
7.5.1. By Type
7.5.2. By Distribution Channel
7.5.3. By Country
7.5.3.1. Saudi Arabia
7.5.3.1.1. Market Trends and Opportunities
7.5.3.1.2. Growth Prospects
7.5.3.2. UAE
7.5.3.2.1. Market Trends and Opportunities
7.5.3.2.2. Growth Prospects
7.5.3.3. Israel
7.5.3.3.1. Market Trends and Opportunities
7.5.3.3.2. Growth Prospects
7.5.3.4. Others
7.5.3.4.1. Market Trends and Opportunities
7.5.3.4.2. Growth Prospects
7.6. Asia Pacific
7.6.1. By Type
7.6.2. By Distribution Channel
7.6.3. By Country
7.6.3.1. China
7.6.3.1.1. Market Trends and Opportunities
7.6.3.1.2. Growth Prospects
7.6.3.2. Japan
7.6.3.2.1. Market Trends and Opportunities
7.6.3.2.2. Growth Prospects
7.6.3.3. India
7.6.3.3.1. Market Trends and Opportunities
7.6.3.3.2. Growth Prospects
7.6.3.4. South Korea
7.6.3.4.1. Market Trends and Opportunities
7.6.3.4.2. Growth Prospects
7.6.3.5. Taiwan
7.6.3.5.1. Market Trends and Opportunities
7.6.3.5.2. Growth Prospects
7.6.3.6. Thailand
7.6.3.6.1. Market Trends and Opportunities
7.6.3.6.2. Growth Prospects
7.6.3.7. Indonesia
7.6.3.7.1. Market Trends and Opportunities
7.6.3.7.2. Growth Prospects
7.6.3.8. Others
7.6.3.8.1. Market Trends and Opportunities
7.6.3.8.2. Growth Prospects
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Sony Corporation
9.2. Canon Inc.
9.3. Nikon Corporation
9.4. Fujifilm Holdings Corporation
9.5. Panasonic Holdings Corporation
9.6. OM Digital Solutions Corporation
9.7. Leica Camera AG
9.8. Sigma Corporation
9.9. Hasselblad
9.10. Blackmagic Design
LIST OF FIGURES
LIST OF TABLES
Navigate
Trusted by the world's leading organizations











