
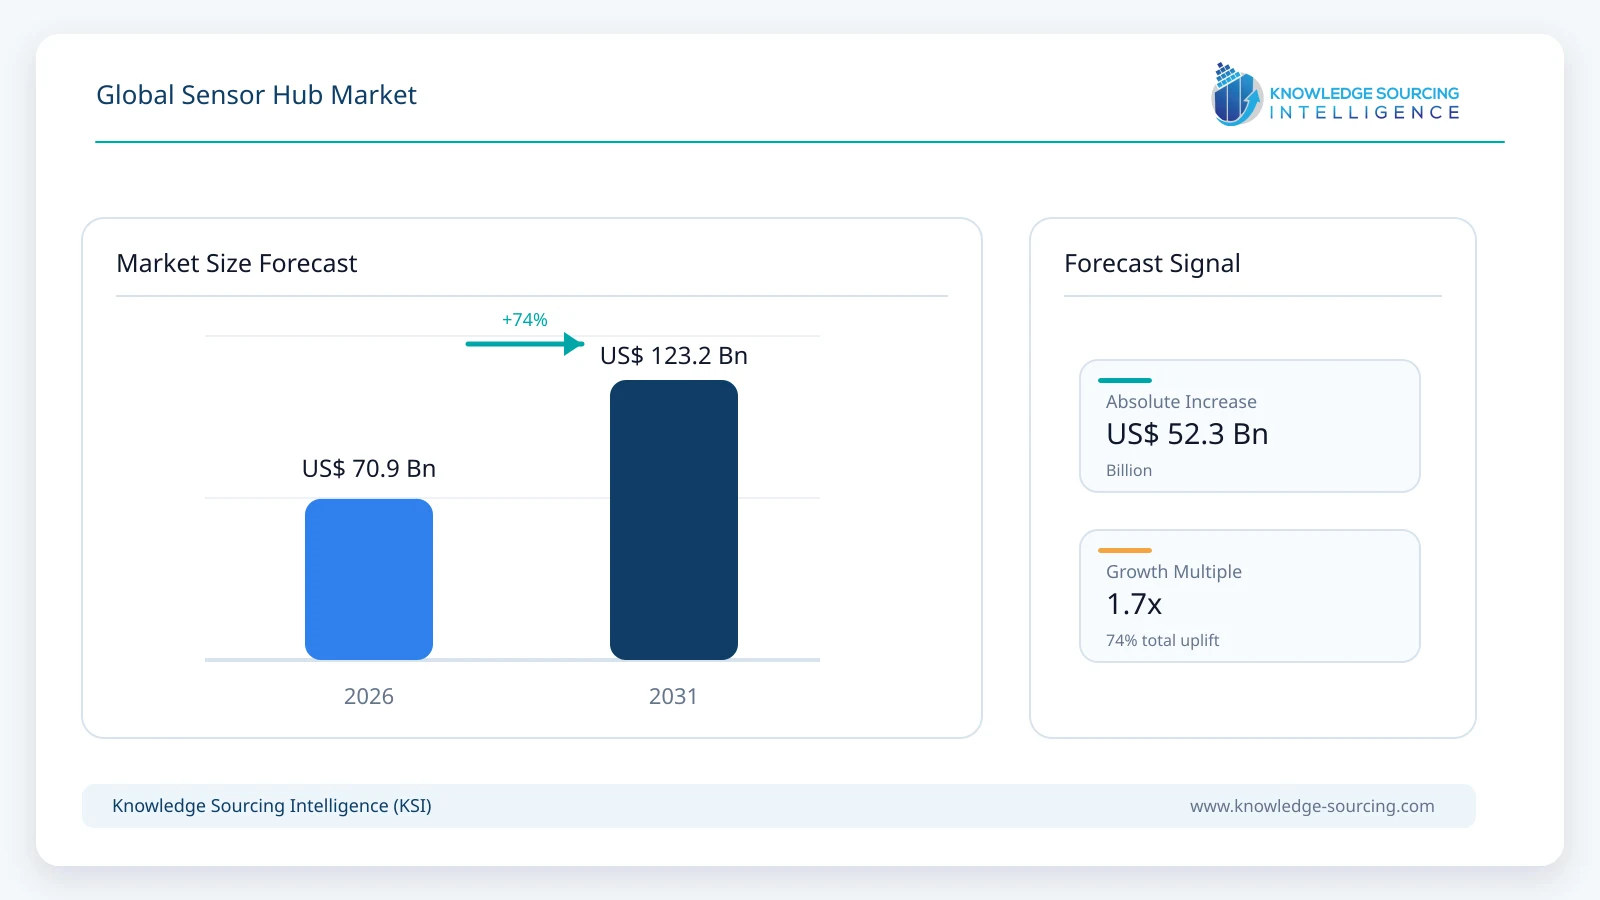
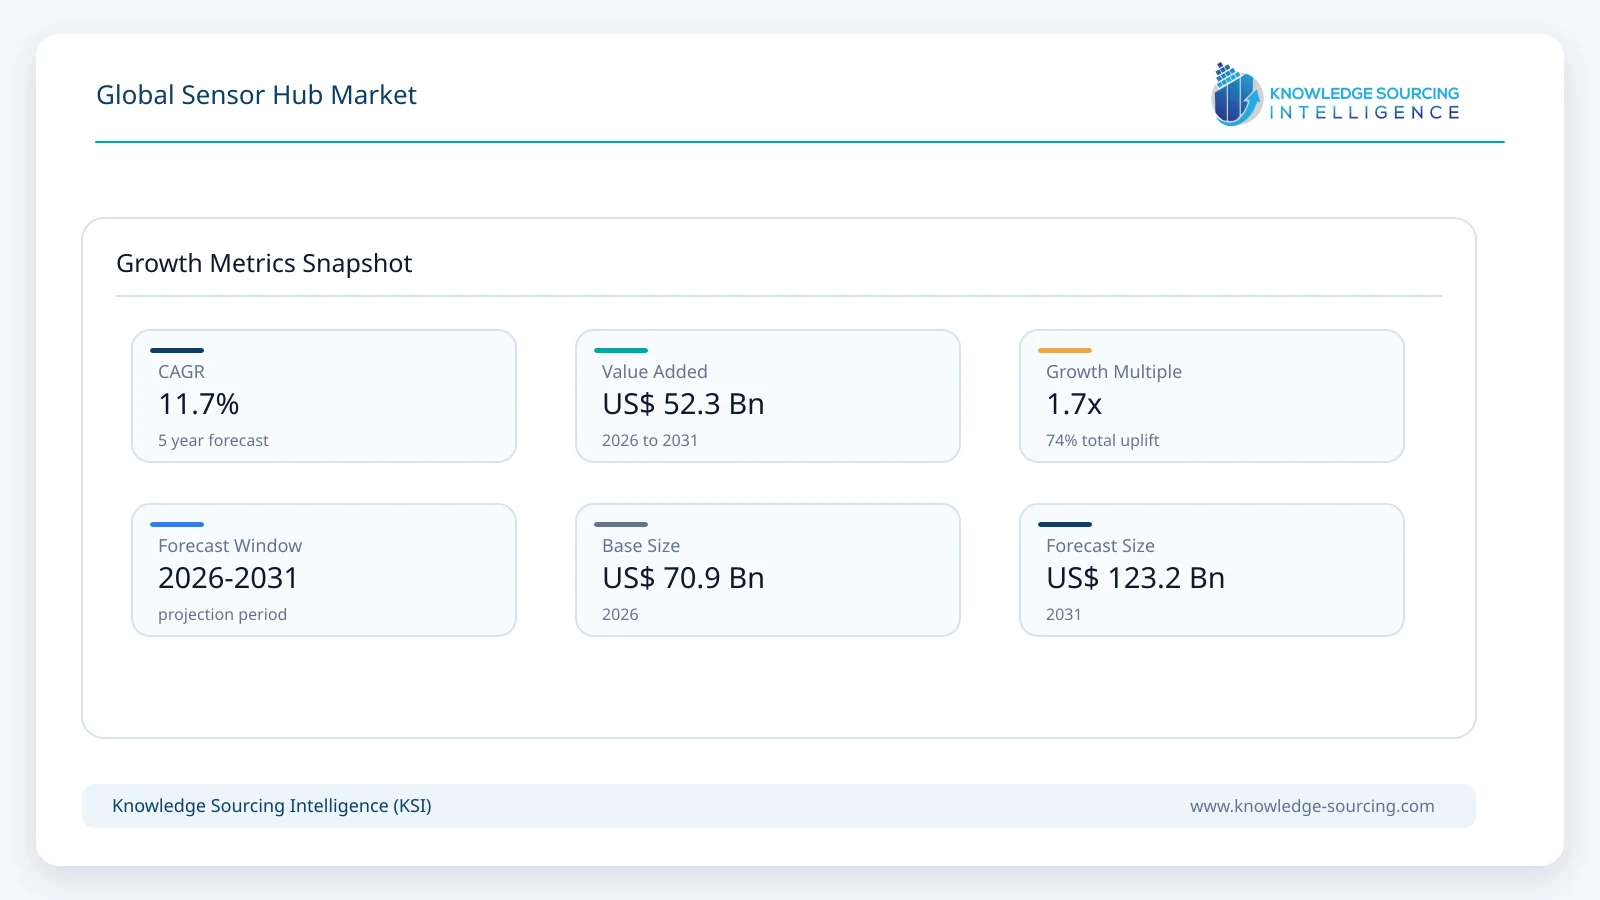
The Global Sensor Hub Market is forecast to grow at a CAGR of 11.7%, reaching USD 123.2 billion in 2031 from USD 70.9 billion in 2026.
Highlights:
- 1Sensor hubs reduce application processor workloads, extending battery life in connected electronic devices.
- 2Wearables, smartphones, automotive electronics, and industrial IoT remain the primary demand centers.
- 3Ultra-low-power processing and on-device sensor fusion increasingly influence product selection decisions.
- 4Semiconductor suppliers are integrating AI capabilities into sensor hubs to support edge intelligence.
- 5Asia Pacific combines large-scale electronics manufacturing with expanding semiconductor investment.
- 6Competition increasingly depends on power efficiency, software ecosystems, and long-term OEM relationships.
Market Overview
Purchasing decisions increasingly extend beyond processor performance alone. Device manufacturers evaluate power consumption, sensor fusion capability, software compatibility, functional safety, artificial intelligence support, package size, and integration with existing semiconductor platforms before selecting suppliers. Consumer electronics manufacturers prioritize battery optimization and rapid software development, while automotive and industrial buyers emphasize functional reliability, long product lifecycles, cybersecurity, and compliance with industry standards.
Demand is distributed across multiple industries rather than being concentrated within a single application. Smartphones and wearable devices continue to represent an important volume market, yet automotive electronics, industrial automation, medical monitoring equipment, and smart home devices are becoming increasingly relevant as sensor density rises. The transition toward edge computing also increases the commercial importance of sensor hubs because more data processing is being performed locally to reduce latency, bandwidth usage, and cloud processing costs.
Supplier competition increasingly reflects complete platform capability rather than standalone hardware performance. Semiconductor vendors are combining sensor hubs with machine learning accelerators, integrated microcontrollers, wireless connectivity, and development software to simplify product design for original equipment manufacturers (OEMs). This shift strengthens long-term customer relationships while raising switching costs across multiple end-use industries. Industry investment therefore increasingly targets integrated low-power architectures that support future intelligent sensing applications rather than isolated sensing components.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Global smartphone shipments | Approximately 1.24 billion units (2024) | Smartphones remain the largest volume platform incorporating multi-sensor architectures. |
Global wearable device demand | Hundreds of millions of units shipped annually | Continuous health monitoring increases demand for low-power sensor processing. |
Automotive electronics content | Increasing sensor count per vehicle | ADAS, driver monitoring, and vehicle safety systems require dedicated sensor processing. |
Industrial IoT deployment | Accelerating edge-device installations | Local sensor processing reduces communication latency and network traffic. |
Semiconductor investment | Multi-billion-dollar global fab expansion programs | Greater production capacity supports long-term supply of embedded processing devices. |
Market Drivers
Expansion of always-on sensing in consumer electronics. Smartphones, smartwatches, hearables, fitness trackers, and extended reality devices continue to integrate additional motion, environmental, location, and biometric sensors while maintaining long battery life. Dedicated sensor hubs reduce the processing burden placed on application processors by continuously collecting and filtering sensor data at very low power. Semiconductor suppliers including Texas Instruments, STMicroelectronics, Qualcomm, Bosch Sensortec, and NXP continue expanding integrated low-power sensing platforms to meet OEM demand for compact architectures, simplified system design, and extended operating time. The commercial effect extends beyond component shipments because higher sensor counts increase semiconductor content per device while strengthening long-term supplier relationships.
Automotive electronic architectures require continuous multi-sensor processing. Modern vehicles increasingly depend on sensor fusion to support advanced driver assistance systems, occupant monitoring, navigation, inertial measurement, predictive maintenance, and vehicle health diagnostics. Electrified vehicles further increase semiconductor content by integrating additional environmental and motion sensors throughout powertrain and battery management systems. Automotive manufacturers prioritize reliability, long product availability, functional safety, and software support over component cost alone. These procurement requirements encourage semiconductor suppliers to invest in automotive-qualified sensor processing platforms that operate under demanding thermal and reliability conditions while meeting automotive safety standards.
Industrial IoT and edge intelligence increase demand for localized processing. Manufacturing facilities, logistics operators, utilities, and infrastructure owners increasingly deploy connected sensing equipment to monitor machinery, energy systems, environmental conditions, and predictive maintenance applications. Processing sensor data locally reduces communication traffic, minimizes latency, and enables continuous operation even when cloud connectivity is limited. Microcontroller-based sensor hubs and dedicated sensor processing ICs therefore provide an attractive balance between computational capability and energy efficiency. Semiconductor companies are responding by integrating artificial intelligence functions, embedded security, and flexible software development tools that simplify deployment across industrial automation, smart building, healthcare, and connected infrastructure applications.
Market Restraints and Challenges
Rising integration complexity across heterogeneous sensor platforms. Device manufacturers increasingly combine motion, environmental, imaging, audio, biometric, and positioning sensors within a single product. Each sensor operates with different sampling rates, communication interfaces, calibration requirements, and software stacks, making system integration more demanding. Industrial and automotive customers also require interoperability with existing electronic control units and operating systems. Semiconductor suppliers therefore invest heavily in software development kits, sensor fusion algorithms, and reference designs, yet integration effort remains a meaningful cost for OEMs, particularly in products with stringent power and functional safety requirements.
Lengthy qualification cycles in automotive, industrial, and healthcare applications. Consumer electronics products typically reach commercial production faster than industrial or automotive systems. In contrast, vehicle manufacturers and industrial equipment suppliers require extended validation, environmental testing, electromagnetic compatibility assessment, and long-term reliability verification before approving semiconductor components. Healthcare equipment manufacturers must also comply with strict regulatory and quality requirements. These lengthy qualification cycles delay revenue realization for suppliers and increase development costs, while making market entry more difficult for smaller semiconductor companies without established certification capabilities or long-term customer relationships.
Supply-chain concentration and advanced semiconductor manufacturing dependence. Sensor hubs rely on advanced semiconductor fabrication, specialized packaging, and precision sensor technologies that involve globally distributed supply chains. Capacity constraints at wafer foundries, substrate suppliers, or packaging facilities can extend lead times and disrupt production planning. Several semiconductor manufacturers have responded by diversifying manufacturing partners, increasing inventory resilience, and expanding regional production capabilities. Nevertheless, dependence on specialized fabrication processes remains a structural industry challenge because many sensor hub products require mature mixed-signal manufacturing technologies alongside advanced embedded processing capabilities.
Major Segment Analysis
Sensor Integrated Microcontroller (MCU-based Sensor Hub)
Sensor integrated microcontrollers represent one of the most commercially important processor categories because they combine sensor management, embedded processing, memory, and low-power control within a single device. This architecture reduces component count, simplifies printed circuit board design, and lowers overall system power consumption. It is particularly well suited for battery-powered equipment, including wearable devices, smart home products, industrial sensors, portable medical equipment, and asset tracking systems, where energy efficiency directly affects product performance and replacement cycles.
Buyer priorities extend beyond processor speed. OEMs increasingly evaluate software ecosystem maturity, peripheral integration, security functions, wireless compatibility, and ease of firmware development when selecting MCU-based sensor hubs. Semiconductor suppliers therefore compete by providing complete development environments, certified software libraries, integrated sensor fusion capabilities, and long-term product availability. Compared with discrete sensor processors, MCU-based solutions generally reduce design complexity while offering sufficient computational capability for most embedded sensing applications, making them an attractive option across multiple end-user industries.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
North America | Automotive electronics, industrial automation, medical devices, AI-enabled edge computing | High development costs and dependence on global semiconductor supply chains |
Europe | Automotive manufacturing, industrial automation, Industry 4.0 initiatives | Stringent regulatory and functional safety requirements |
Asia Pacific | Consumer electronics production, semiconductor manufacturing, IoT deployment | Intense pricing pressure and geopolitical supply-chain risks |
Middle East and Africa | Smart infrastructure, telecommunications, industrial digitalization | Limited local semiconductor manufacturing capacity |
North America
Demand is supported by advanced semiconductor design capabilities, automotive electronics development, industrial automation, aerospace systems, and medical device manufacturing. The United States remains the regional center for semiconductor innovation, supported by investment in domestic manufacturing, artificial intelligence hardware, and edge computing infrastructure. Large OEMs increasingly require sensor hubs capable of supporting on-device processing, cybersecurity, and long product lifecycles. Procurement decisions therefore place considerable emphasis on software support, functional reliability, and supply continuity rather than component pricing alone.
Europe
Automotive manufacturing remains the primary commercial driver across Europe, supported by increasing deployment of advanced driver assistance systems, electrified vehicle platforms, and industrial automation equipment. Germany, France, and the Nordic manufacturing base continue integrating additional sensing capability into production equipment and mobility solutions. European buyers also operate within one of the world's most demanding regulatory environments, encouraging suppliers to prioritize functional safety, environmental compliance, traceability, and product reliability throughout the semiconductor supply chain.
Asia Pacific
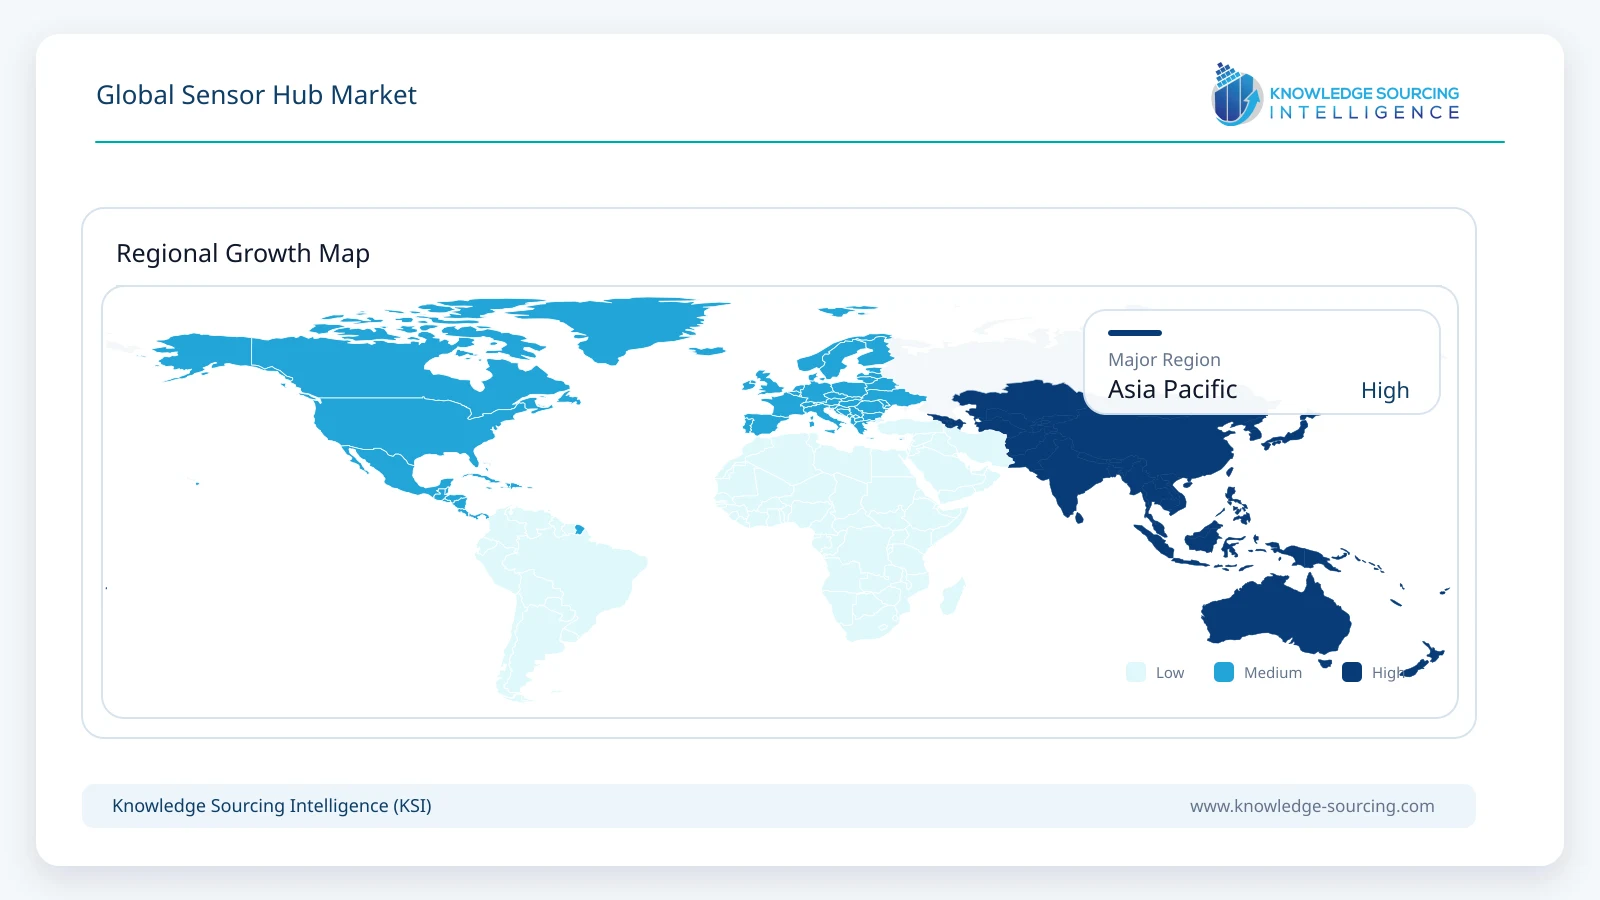
Asia Pacific combines the world's largest electronics manufacturing ecosystem with expanding semiconductor investment, making it central to both demand and production. China, Japan, South Korea, Taiwan, and increasingly India contribute through smartphone manufacturing, consumer electronics assembly, automotive production, and industrial automation. Regional semiconductor companies continue expanding fabrication capacity and packaging capabilities to support rising electronics demand. High-volume production also intensifies competition, encouraging suppliers to improve power efficiency, component integration, and manufacturing yield while maintaining competitive pricing.
Middle East and Africa
Commercial demand remains smaller than in other major regions but continues to diversify through industrial digitalization, smart city programs, connected infrastructure, energy projects, and telecommunications investment. Gulf countries increasingly deploy intelligent building systems, industrial monitoring platforms, and connected transport infrastructure that require reliable sensor processing. Most semiconductor devices continue to be imported, making regional supply dependent on international distribution networks. As digital infrastructure expands, opportunities are expected to increase for sensor hub suppliers serving industrial automation, utilities, and smart infrastructure projects.
Competitive Landscape
Competition in the global sensor hub market is technology-driven and moderately consolidated, with established semiconductor companies competing through power efficiency, software ecosystems, application-specific optimization, and long-term OEM partnerships rather than price alone. Texas Instruments, STMicroelectronics, Bosch Sensortec, Infineon Technologies, ROHM (LAPIS Semiconductor), Microchip Technology, CEVA, Analog Devices, Qualcomm, and NXP Semiconductors address different portions of the value chain, ranging from standalone sensor hub integrated circuits to microcontroller-based platforms and sensor fusion software.
Product differentiation increasingly depends on ultra-low-power processing, integrated artificial intelligence capabilities, functional safety support, wireless connectivity, and software development tools that reduce product development time. Automotive and industrial customers typically prioritize long product availability, certification support, and supply continuity, while consumer electronics manufacturers emphasize compact form factors, battery efficiency, and rapid integration. High design complexity, established software ecosystems, intellectual property, and long qualification cycles continue to create barriers for new entrants, reinforcing the competitive position of established semiconductor suppliers.
Recent Developments
February 2026 – Infineon Technologies announced the acquisition of ams OSRAM’s non-optical analog/mixed-signal sensor portfolio for €570 million. The transaction expands Infineon’s automotive, industrial, medical, and AI sensor capabilities while strengthening its global sensor systems business.
February 2026 – STMicroelectronics completed its acquisition of NXP Semiconductors’ MEMS sensors business. Originally announced in July 2025, the deal broadens ST’s automotive safety and industrial sensor portfolio, reinforcing its leadership in MEMS-based sensing technologies.
August 2025 – Bosch Sensortec introduced the BMI330 inertial measurement unit (IMU). Designed for industrial, robotics, navigation, and smart agriculture, the sensor delivers reliable motion sensing up to 105°C while maintaining low power consumption and seamless design compatibility.
June 2025 – Bosch Sensortec unveiled the BHI385 smart sensor hub platform alongside the BMI330 at Sensors Converge 2025. The next-generation sensor hub enhances always-on sensing, AI-enabled motion processing, and wearable, IoT, and edge-device performance.
Regulatory and Policy Environment
Sensor hub suppliers operate within a regulatory environment that combines semiconductor manufacturing policies, electronic product safety standards, environmental regulations, cybersecurity requirements, and sector-specific certification frameworks. Rather than regulating sensor hubs directly, these rules influence how manufacturers design, qualify, and deploy sensor-processing solutions across end-user industries.
In automotive applications, compliance with ISO 26262 functional safety requirements remains an important purchasing consideration for components supporting advanced driver assistance systems, driver monitoring, and vehicle control. Industrial deployments frequently require conformity with IEC 61508 functional safety principles, while healthcare applications must satisfy medical device regulations applicable in target markets. These requirements increase product development costs but also strengthen demand for highly reliable, well-documented semiconductor platforms.
Environmental legislation continues to influence semiconductor manufacturing and material selection. Compliance with the European Union's RoHS (Restriction of Hazardous Substances) and REACH regulations has become standard practice for suppliers serving global electronics manufacturers. At the same time, cybersecurity requirements for connected devices are becoming more rigorous across multiple jurisdictions, encouraging semiconductor vendors to integrate hardware-based security functions, secure boot capability, encrypted communications, and trusted execution environments within embedded processing platforms.
Government support for domestic semiconductor manufacturing is also reshaping long-term supply conditions. Public investment programs in the United States, the European Union, Japan, South Korea, India, and other economies seek to strengthen regional semiconductor production capacity, improve supply-chain resilience, and reduce dependence on geographically concentrated manufacturing. Although these initiatives primarily target semiconductor production rather than sensor hubs specifically, they are expected to improve long-term component availability and encourage additional investment in embedded processing technologies.
Outlook and Strategic Implications
Commercial demand for sensor hubs during the 2026–2031 forecast period will increasingly depend on the expansion of intelligent edge devices rather than growth in any single end-use industry. As connected products incorporate more sensors and perform greater levels of local data processing, manufacturers will require architectures capable of delivering low-power operation, real-time sensor fusion, embedded artificial intelligence, and robust security without increasing system complexity.
The market is also expected to benefit from the convergence of automotive electronics, industrial automation, healthcare monitoring, wearable technology, and smart infrastructure. Buyers are increasingly seeking complete hardware and software platforms that reduce development effort and accelerate product qualification. Consequently, semiconductor suppliers that combine integrated processing, software support, security functions, and long-term product availability are likely to strengthen customer retention and expand design wins across multiple industries.
Several strategic themes are expected to influence competitive positioning over the forecast period:
OEMs will increasingly prioritize suppliers offering integrated hardware, software, and long-term lifecycle support over standalone semiconductor components.
Semiconductor manufacturers are expected to expand investment in ultra-low-power architectures, embedded AI accelerators, and secure edge processing capabilities.
Automotive and industrial customers will continue emphasizing functional safety, cybersecurity, and long-term supply assurance during supplier selection.
Regional manufacturing diversification is likely to reduce supply-chain concentration risks while improving resilience against future geopolitical and logistics disruptions.
Companies capable of balancing power efficiency, processing capability, software maturity, and supply reliability will be best positioned to secure long-term design opportunities. As sensing becomes a core function of connected electronic systems, competition is expected to shift further from individual semiconductor specifications toward complete intelligent sensing platforms that simplify integration while supporting increasingly complex edge computing workloads.
Global Sensor Hub Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 70.9 billion |
| Total Market Size in 2031 | USD 123.2 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 11.7% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Processor Type, End-Users, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Processor Type
Application Sensor Processor
Discrete Sensor Processor
Sensor Integrated Microcontroller (MCU-based Sensor Hub)
Sensor Hub IC / Dedicated Sensor Hub SoC
Others
By End-Users
Consumer Electronics
Automotive
Industrial
Aerospace and Defense
Healthcare
Telecommunications
Wearables
Internet of Things (IoT)
Smart Home and Building Automation
Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
China
Japan
India
South Korea
Taiwan
Thailand
Indonesia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits for the Stakeholder
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Processes
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
4.5. Analyst View
5. GLOBAL SENSOR HUB MARKET, BY PROCESSOR TYPE
5.1. Introduction
5.2. Application Sensor Processor
5.2.1. Market Trends and Opportunities
5.2.2. Growth Prospects
5.2.3. Geographic Lucrativeness
5.3. Discrete Sensor Processor
5.3.1. Market Trends and Opportunities
5.3.2. Growth Prospects
5.3.3. Geographic Lucrativeness
5.4. Sensor Integrated Microcontroller (MCU-based Sensor Hub)
5.4.1. Market Trends and Opportunities
5.4.2. Growth Prospects
5.4.3. Geographic Lucrativeness
5.5. Sensor Hub IC / Dedicated Sensor Hub SoC
5.5.1. Market Trends and Opportunities
5.5.2. Growth Prospects
5.5.3. Geographic Lucrativeness
5.6. Others
5.6.1. Market Trends and Opportunities
5.6.2. Growth Prospects
5.6.3. Geographic Lucrativeness
6. GLOBAL SENSOR HUB MARKET, BY END-USERS
6.1. Introduction
6.2. Consumer Electronics
6.2.1. Market Trends and Opportunities
6.2.2. Growth Prospects
6.2.3. Geographic Lucrativeness
6.3. Automotive
6.3.1. Market Trends and Opportunities
6.3.2. Growth Prospects
6.3.3. Geographic Lucrativeness
6.4. Industrial
6.4.1. Market Trends and Opportunities
6.4.2. Growth Prospects
6.4.3. Geographic Lucrativeness
6.5. Aerospace and Defense
6.5.1. Market Trends and Opportunities
6.5.2. Growth Prospects
6.5.3. Geographic Lucrativeness
6.6. Healthcare
6.6.1. Market Trends and Opportunities
6.6.2. Growth Prospects
6.6.3. Geographic Lucrativeness
6.7. Telecommunications
6.7.1. Market Trends and Opportunities
6.7.2. Growth Prospects
6.7.3. Geographic Lucrativeness
6.8. Wearables
6.8.1. Market Trends and Opportunities
6.8.2. Growth Prospects
6.8.3. Geographic Lucrativeness
6.9. Internet of Things (IoT)
6.9.1. Market Trends and Opportunities
6.9.2. Growth Prospects
6.9.3. Geographic Lucrativeness
6.10. Smart Home and Building Automation
6.10.1. Market Trends and Opportunities
6.10.2. Growth Prospects
6.10.3. Geographic Lucrativeness
6.11. Others
6.11.1. Market Trends and Opportunities
6.11.2. Growth Prospects
6.11.3. Geographic Lucrativeness
7. GLOBAL SENSOR HUB MARKET, BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. By Processor Type
7.2.2. By End-Users
7.2.3. By Country
7.2.3.1. USA
7.2.3.1.1. Market Trends and Opportunities
7.2.3.1.2. Growth Prospects
7.2.3.2. Canada
7.2.3.2.1. Market Trends and Opportunities
7.2.3.2.2. Growth Prospects
7.2.3.3. Mexico
7.2.3.3.1. Market Trends and Opportunities
7.2.3.3.2. Growth Prospects
7.3. South America
7.3.1. By Processor Type
7.3.2. By End-Users
7.3.3. By Country
7.3.3.1. Brazil
7.3.3.1.1. Market Trends and Opportunities
7.3.3.1.2. Growth Prospects
7.3.3.2. Argentina
7.3.3.2.1. Market Trends and Opportunities
7.3.3.2.2. Growth Prospects
7.3.3.3. Others
7.3.3.3.1. Market Trends and Opportunities
7.3.3.3.2. Growth Prospects
7.4. Europe
7.4.1. By Processor Type
7.4.2. By End-Users
7.4.3. By Country
7.4.3.1. United Kingdom
7.4.3.1.1. Market Trends and Opportunities
7.4.3.1.2. Growth Prospects
7.4.3.2. Germany
7.4.3.2.1. Market Trends and Opportunities
7.4.3.2.2. Growth Prospects
7.4.3.3. France
7.4.3.3.1. Market Trends and Opportunities
7.4.3.3.2. Growth Prospects
7.4.3.4. Spain
7.4.3.4.1. Market Trends and Opportunities
7.4.3.4.2. Growth Prospects
7.4.3.5. Others
7.4.3.5.1. Market Trends and Opportunities
7.4.3.5.2. Growth Prospects
7.5. Middle East and Africa
7.5.1. By Processor Type
7.5.2. By End-Users
7.5.3. By Country
7.5.3.1. Saudi Arabia
7.5.3.1.1. Market Trends and Opportunities
7.5.3.1.2. Growth Prospects
7.5.3.2. UAE
7.5.3.2.1. Market Trends and Opportunities
7.5.3.2.2. Growth Prospects
7.5.3.3. Israel
7.5.3.3.1. Market Trends and Opportunities
7.5.3.3.2. Growth Prospects
7.5.3.4. Others
7.5.3.4.1. Market Trends and Opportunities
7.5.3.4.2. Growth Prospects
7.6. Asia Pacific
7.6.1. By Processor Type
7.6.2. By End-Users
7.6.3. By Country
7.6.3.1. China
7.6.3.1.1. Market Trends and Opportunities
7.6.3.1.2. Growth Prospects
7.6.3.2. Japan
7.6.3.2.1. Market Trends and Opportunities
7.6.3.2.2. Growth Prospects
7.6.3.3. India
7.6.3.3.1. Market Trends and Opportunities
7.6.3.3.2. Growth Prospects
7.6.3.4. South Korea
7.6.3.4.1. Market Trends and Opportunities
7.6.3.4.2. Growth Prospects
7.6.3.5. Taiwan
7.6.3.5.1. Market Trends and Opportunities
7.6.3.5.2. Growth Prospects
7.6.3.6. Thailand
7.6.3.6.1. Market Trends and Opportunities
7.6.3.6.2. Growth Prospects
7.6.3.7. Indonesia
7.6.3.7.1. Market Trends and Opportunities
7.6.3.7.2. Growth Prospects
7.6.3.8. Others
7.6.3.8.1. Market Trends and Opportunities
7.6.3.8.2. Growth Prospects
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Texas Instruments Inc.
9.2. STMicroelectronics N.V.
9.3. Bosch Sensotec
9.4. Infineon Technologies AG
9.5. LAPIS Semiconductor Co. Ltd (ROHM)
9.6. Microchip Technology Inc.
9.7. CEVA (CMA CGM Group)
9.8. Analog Devices Inc.
9.9. Qualcomm
9.10. NXP Semiconductors
LIST OF FIGURES
LIST OF TABLES





Frequently asked questions
What is the projected market size for sensor hubs by 2031?
The Global Sensor Hub Market is forecast to reach USD 123.2 billion by 2031.
What is the compound annual growth rate (CAGR) for the market?
The Global Sensor Hub Market is forecast to grow at an 11.7% CAGR (2026-2031).
Which industries are primary demand centers for sensor hubs?
Wearables, smartphones, automotive electronics, and industrial IoT are primary centers.
Which region shows significant electronics manufacturing and semiconductor investment?
Asia Pacific combines large-scale electronics manufacturing with expanding semiconductor investment.
What factors increasingly influence sensor hub product selection?
Ultra-low-power processing and on-device sensor fusion influence product selection.
What drives competition among sensor hub suppliers?
Power efficiency, software ecosystems, and long-term OEM relationships drive competition.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Global Sensor Hub Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/global-sensor-hub-market