
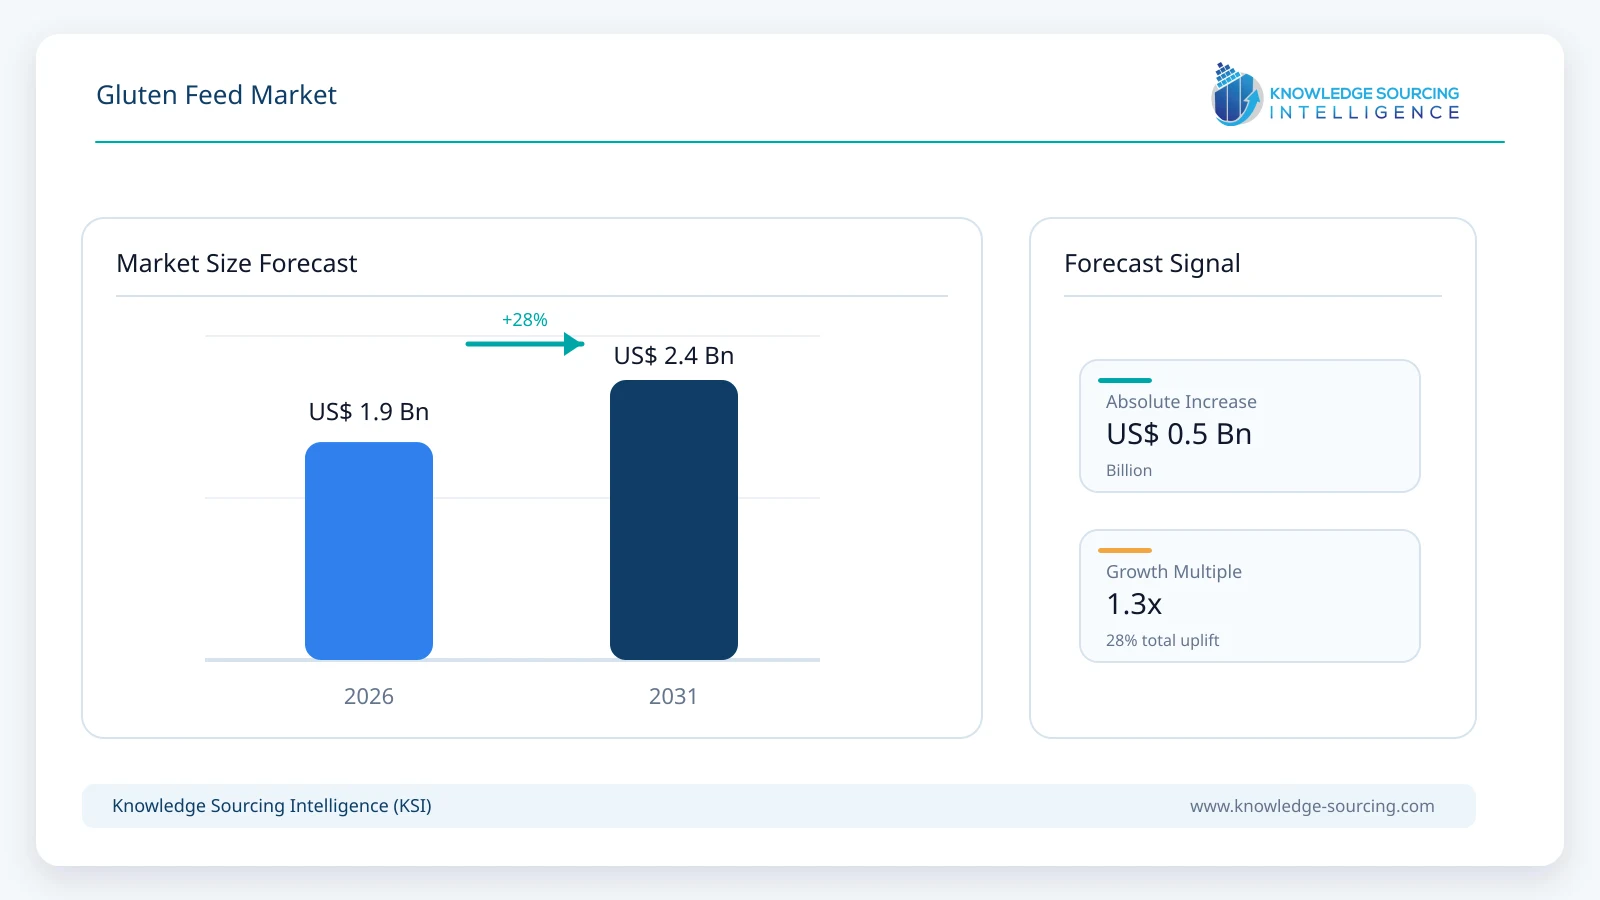
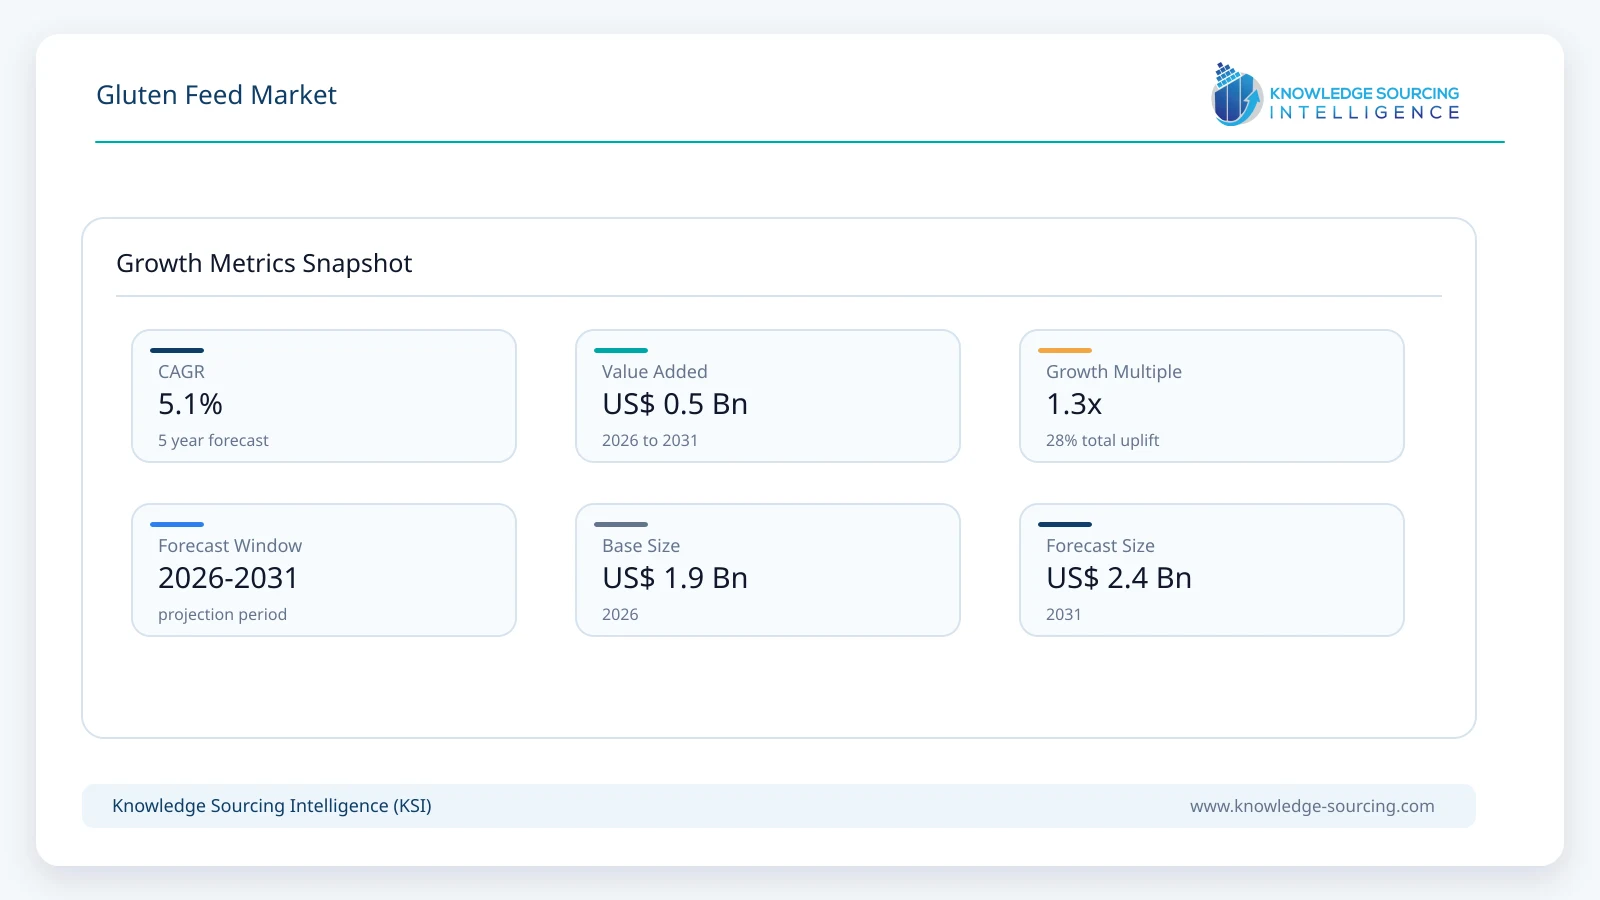
The gluten feed market is projected to expand from USD 1.86 billion in 2026 to USD 2.39 billion in 2031, representing a CAGR of 5.1% during the forecast period.
Highlights:
- 1Corn/maize gluten feed accounts for about 82% of 2026 market revenue, reflecting the scale of global corn wet milling.
- 2Cattle and other ruminants represent approximately 60% of 2026 demand because gluten feed combines digestible fibre, energy, and moderate protein.
- 3North America accounts for about 41% of 2026 revenue, while Asia Pacific is expected to record the fastest regional growth through 2031.
Market Overview
Gluten feed is generated primarily when cereal grains are processed for starch and sweeteners through wet milling. The residual fibre fraction is combined with soluble nutrient streams and sold as a moderate-protein feed ingredient. Its economics are therefore linked to both livestock-feed demand and the operating rates of starch-processing facilities.
The United States provides a strong physical anchor for the market. USDA reported 3.16 million tons of wet-mill corn gluten feed production in 2024, alongside 2.43 million tons of wet corn gluten feed containing 40-60% moisture. USDA feedstuff quotations also demonstrate the value difference between dry and wet forms: on April 2, 2026, Central U.S. corn gluten feed pellets averaged USD 155.71 per ton FOB truck, compared with USD 31.60 per ton for wet corn gluten feed. These observed volumes and prices imply a substantial U.S. revenue pool before adding European, Asian, Latin American, and other production.
Europe provides a second important production base. Starch Europe reports that 70 plants in 18 EU member states process about 22 million tonnes of agricultural raw materials and produce more than 5 million tonnes of proteins and fibres annually alongside starch and starch derivatives. Not all of this output is gluten feed, but it establishes the scale of the co-product stream generated by regional wheat and maize processing. Asia adds significant corn wet-milling capacity through China, India, Thailand, and other markets, creating a geographically broader supply base than is visible from U.S. data alone.
Gluten Feed Market Growth Drivers
Expansion of global livestock and compound-feed demand
Growth in animal-protein output increases the addressable demand base for feed ingredients that provide energy, fibre, and protein at competitive formulation costs. The OECD-FAO Agricultural Outlook 2025-2034 projects world meat production to rise by 13%, or 46 million tonnes carcass-weight equivalent, to about 406 million tonnes by 2034. Asia is expected to account for 55% of the increase, while poultry contributes a large share of incremental output. Gluten feed does not substitute identically across every species, but expansion in livestock production supports greater demand for flexible feed ingredients and co-products, particularly in commercial compound-feed systems.
Cost-efficient use of wet-milling co-products
Corn gluten feed combines digestible fibre, residual starch, energy, and moderate protein, making it particularly useful in cattle and other ruminant diets. Feed formulators can vary inclusion rates according to local prices for corn, soybean meal, DDGS, wheat by-products, and other alternatives. This economic flexibility supports demand when gluten feed is competitively priced relative to conventional energy and protein ingredients. Because the product monetizes a co-product stream from starch processing, suppliers also benefit from an established raw-material base rather than requiring a dedicated crop solely for feed production.
Starch-processing scale supports recurring co-product availability
Gluten feed supply is structurally connected to starch and sweetener manufacturing. The European starch industry alone produces more than 5 million tonnes of proteins and fibres each year, while U.S. wet-milling plants generate several million tons of dry and wet corn gluten feed. Continued utilization and modernization of these processing assets supports recurring feed co-product availability. Drying and pelletizing extend the commercial radius of gluten feed by improving storage, handling, and freight economics compared with high-moisture material.
Circular-economy value of feed co-products
Gluten feed enables starch processors to convert fibre and soluble nutrient fractions into marketable animal nutrition products rather than lower-value waste streams. This whole-crop utilization supports resource efficiency and can improve the economics of cereal processing. For feed buyers, the use of co-products can also diversify formulations away from a narrow dependence on primary feed grains and oilseed meals.
Market Restraints
Strong substitution pressure from DDGS, soybean meal, wheat middlings, soybean hulls, rapeseed meal, and other feed co-products can quickly change inclusion economics.
Wet gluten feed has a limited transportation radius because high moisture reduces storage life and raises freight cost per unit of dry matter.
Nutrient composition can vary with the wet-milling process, steep-liquor addition, residual starch, moisture, and raw-material quality, requiring feed-formulation control.
Higher fibre and amino-acid limitations generally restrict inclusion in poultry and swine diets compared with ruminant diets, limiting demand diversification.
Supply is partly driven by starch and sweetener production economics rather than feed demand itself, which can create regional imbalances between co-product availability and livestock consumption.
Segment Analysis
Largest source: Corn/Maize Gluten Feed
Corn/maize gluten feed is estimated to account for about 82% of global gluten feed revenue in 2026. Corn wet milling has a large industrial footprint in North America, China, Europe, and parts of Asia, and the resulting gluten feed is widely commercialized in dry, pelletized, and wet forms. USDA production of 3.16 million tons of corn gluten feed and 2.43 million tons of wet corn gluten feed in 2024 demonstrates the scale of this stream in the United States alone. Wheat gluten feed remains an important European and selected Asian product, particularly where wheat starch production is established, but represents a smaller global revenue pool.
Largest application: Cattle and Other Ruminants
Cattle and other ruminants are estimated to represent about 60% of gluten feed revenue in 2026. Corn gluten feed is particularly compatible with ruminant feeding because of its digestible fibre, energy contribution, and moderate protein content. Roquette, AGRANA, Friendship Corn Starch, and other suppliers explicitly position gluten feed for dairy and beef cattle applications. Swine and poultry also use the ingredient, but fibre content and amino-acid balance typically constrain inclusion rates, making ruminants the structurally dominant demand segment.
Geographical Outlook
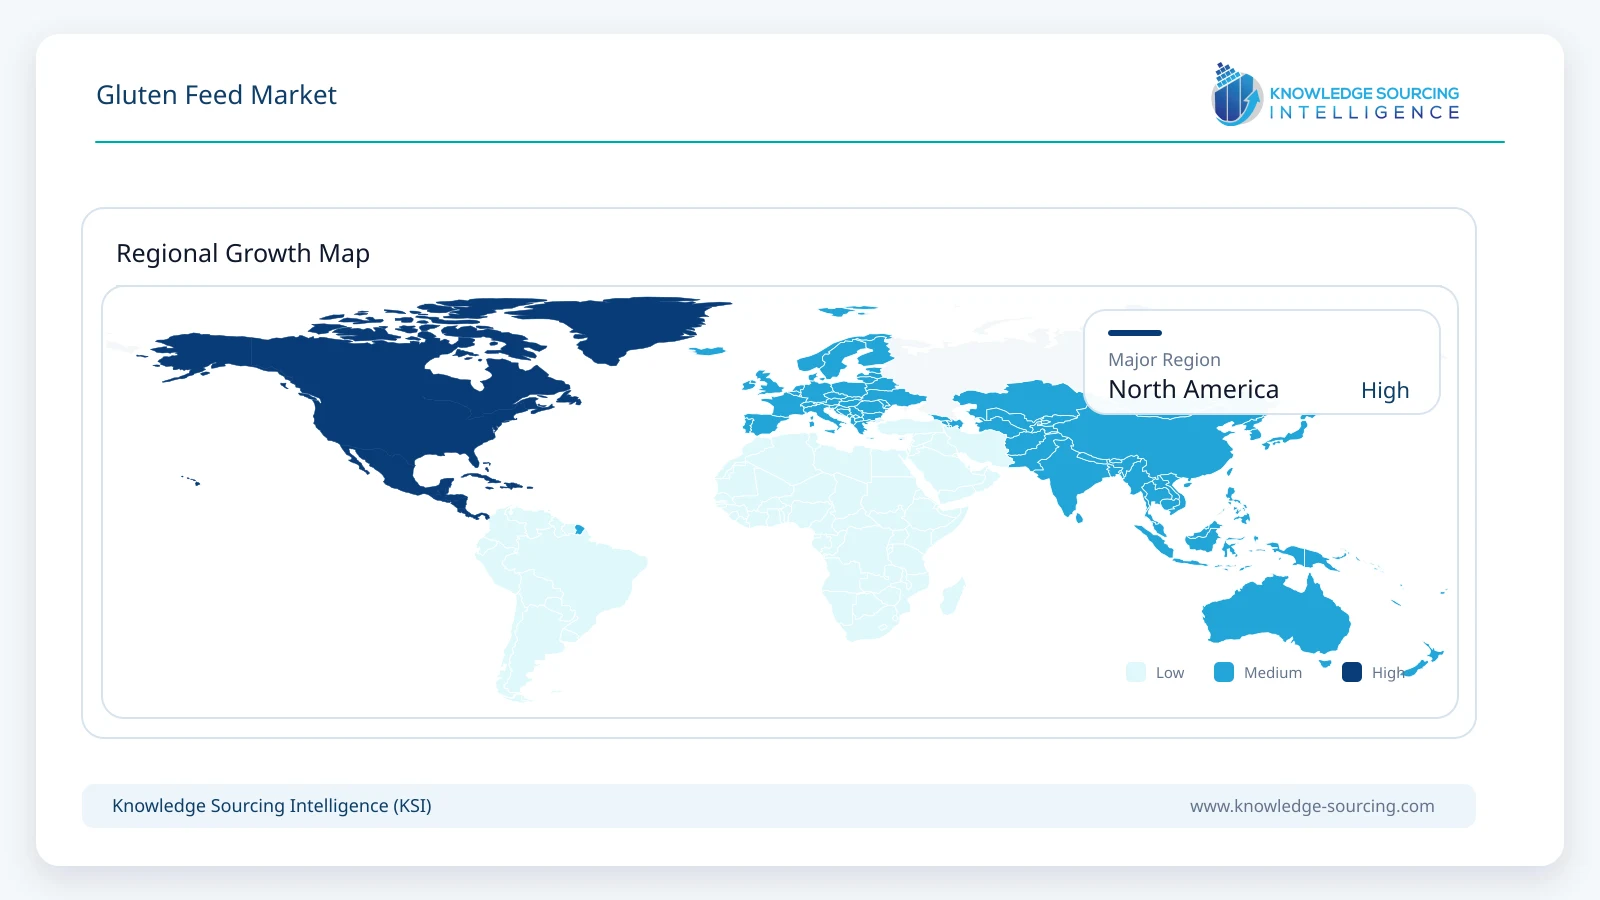
North America is estimated to account for approximately 41% of global gluten feed revenue in 2026. The United States combines a large corn wet-milling industry, transparent co-product production statistics, established cattle and dairy sectors, and active regional trade in both dry and wet gluten feed. Europe represents the second major market, supported by extensive wheat and maize starch processing and established use of cereal co-products in compound feed. Asia Pacific is projected to record the fastest regional growth through 2031 as livestock and poultry output expands and corn-processing capacity supports local availability. The OECD-FAO outlook indicates that Asia will account for 55% of global meat-production growth to 2034, providing a supportive demand backdrop. Latin America and the Middle East and Africa remain smaller markets but participate through livestock production, imported feed ingredients, and selected starch-processing capacity.
Competitive Environment
The gluten feed market includes large integrated starch processors, regional wet-milling companies, and specialist feed-ingredient suppliers. Direct current participation has been verified for ADM, Cargill, Roquette, AGRANA, Tereos, Primient, Grain Processing Corporation, Ingredion, Shandong Golden Corn, Friendship Corn Starch, Shandong Fulaier Biological Technology, Jinzhou Shengxiang Biotechnology, Shouguang Taihe Biotechnology, Yashika Proteins, and COFCO Biotechnology Marketing.
Recent Market Developments
July 2026: ADM announced a multimillion-dollar investment at its Optima, Oklahoma grain elevator that is expected to significantly increase throughput of corn and corn gluten feed pellets, with completion targeted for mid-2027.
April 2026: Primient launched a Biosolutions business unit structure that includes Agrifunctionals, covering animal-nutrition and other co-product markets alongside its corn-processing platform.
April 2, 2026: USDA AMS reported Central U.S. corn gluten feed pellet prices averaging USD 155.71 per ton FOB truck, up from USD 122.83 a year earlier, while wet gluten feed averaged USD 31.60 per ton.
2024 production summary: USDA reported 3.16 million tons of U.S. wet-mill corn gluten feed and 2.43 million tons of wet corn gluten feed, with both broadly stable to slightly higher year over year.
Market Outlook
The gluten feed market is expected to grow steadily rather than at a high single-digit rate through 2031. Demand benefits from expansion in livestock production and the need for cost-flexible feed formulations, while supply is supported by large cereal wet-milling industries. However, the market remains highly sensitive to relative ingredient prices and freight economics. Dry and pelletized material will retain most market value because it can travel farther and has better storage characteristics, while wet gluten feed will remain locally important near processing plants. Asia Pacific should increase its share gradually as regional livestock output grows. Suppliers with scale, consistent nutrient specifications, efficient drying and pelletizing, and proximity to dense livestock markets are positioned most strongly.
Gluten Feed Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.86 billion |
| Total Market Size in 2031 | USD 2.39 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.1% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Source, Form, Application, Geography |
| Companies |
|
Market Segmentation
By Source
Corn/Maize Gluten Feed
Wheat Gluten Feed
Other Cereal-Based Gluten Feed
By Form
Dry/Pelletized and Meal Gluten Feed
Wet Gluten Feed
By Application
Cattle and Other Ruminants
Swine
Poultry
Aquaculture and Other Animal Feed
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Netherlands
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Thailand
Indonesia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Definition
1.2. Scope of the Study
1.3. Market Segmentation
1.4. Currency
1.5. Assumptions
1.6. Base and Forecast Years Timeline
2. RESEARCH METHODOLOGY
2.1. Research Process
2.2. Research Data
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Market Size and Forecast
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Expansion of Global Livestock and Compound-Feed Demand
4.1.2. Cost-Efficient Use of Wet-Milling Co-Products
4.1.3. Starch-Processing Scale Supports Recurring Co-Product Availability
4.1.4. Circular-Economy Value of Feed Co-Products
4.2. Market Restraints
4.2.1. Competition from Alternative Feed Ingredients
4.2.2. Freight and Storage Limitations of Wet Gluten Feed
4.2.3. Nutrient Variability and Formulation Constraints
4.3. Porter’s Five Forces Analysis
4.4. Industry Value Chain Analysis
5. GLUTEN FEED MARKET, BY SOURCE
5.1. Introduction
5.2. Corn/Maize Gluten Feed
5.3. Wheat Gluten Feed
5.4. Other Cereal-Based Gluten Feed
6. GLUTEN FEED MARKET, BY FORM
6.1. Introduction
6.2. Dry/Pelletized and Meal Gluten Feed
6.3. Wet Gluten Feed
7. GLUTEN FEED MARKET, BY APPLICATION
7.1. Introduction
7.2. Cattle and Other Ruminants
7.3. Swine
7.4. Poultry
7.5. Aquaculture and Other Animal Feed
8. GLUTEN FEED MARKET, BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. United Kingdom
8.4.2. Germany
8.4.3. France
8.4.4. Italy
8.4.5. Spain
8.4.6. Netherlands
8.4.7. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. South Africa
8.5.4. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. Japan
8.6.3. India
8.6.4. South Korea
8.6.5. Thailand
8.6.6. Indonesia
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Product and Form Positioning
9.3. Regional Supply and Freight Dynamics
9.4. Mergers, Acquisitions, Investments, and Agreements
10. COMPANY PROFILES
10.1. Archer Daniels Midland Company (ADM)
10.2. Cargill, Incorporated
10.3. Roquette Frères
10.4. AGRANA Beteiligungs-AG
10.5. Tereos Group
10.6. Primient
10.7. Grain Processing Corporation
10.8. Ingredion Incorporated
10.9. Shandong Golden Corn Co., Ltd.
10.10. Friendship Corn Starch Co., Ltd.
10.11. Shandong Fulaier Biological Technology Co., Ltd.
10.12. Jinzhou Shengxiang Biotechnology Co., Ltd.
10.13. Shouguang Taihe Biotechnology Co., Ltd.
10.14. Yashika Proteins Pvt. Ltd.
10.15. Jilin COFCO Bio-Chem and Bio-Energy Marketing Co., Ltd.
11. APPENDIX
11.1. Abbreviations
11.2. Additional Sources and Data Notes
Navigate
Trusted by the world's leading organizations











