
The Indian Animal Feed market is forecast to grow at a CAGR of 6.1%, reaching USD 19.64 billion in 2031 from USD 14.61 billion in 2026.
Highlights:
- 1Growth in milk, egg, meat, and aquaculture production continues to expand feed consumption across livestock categories.
- 2Commercial feed manufacturers are increasing investments in production capacity, formulation capabilities, and distribution networks.
- 3Feed cost remains heavily influenced by corn, soybean meal, and other agricultural commodity prices.
- 4Poultry and cattle feed account for a large share of organized feed demand due to the scale of India's protein and dairy industries.
- 5Government programs supporting livestock productivity and fodder development are improving long-term feed demand fundamentals.
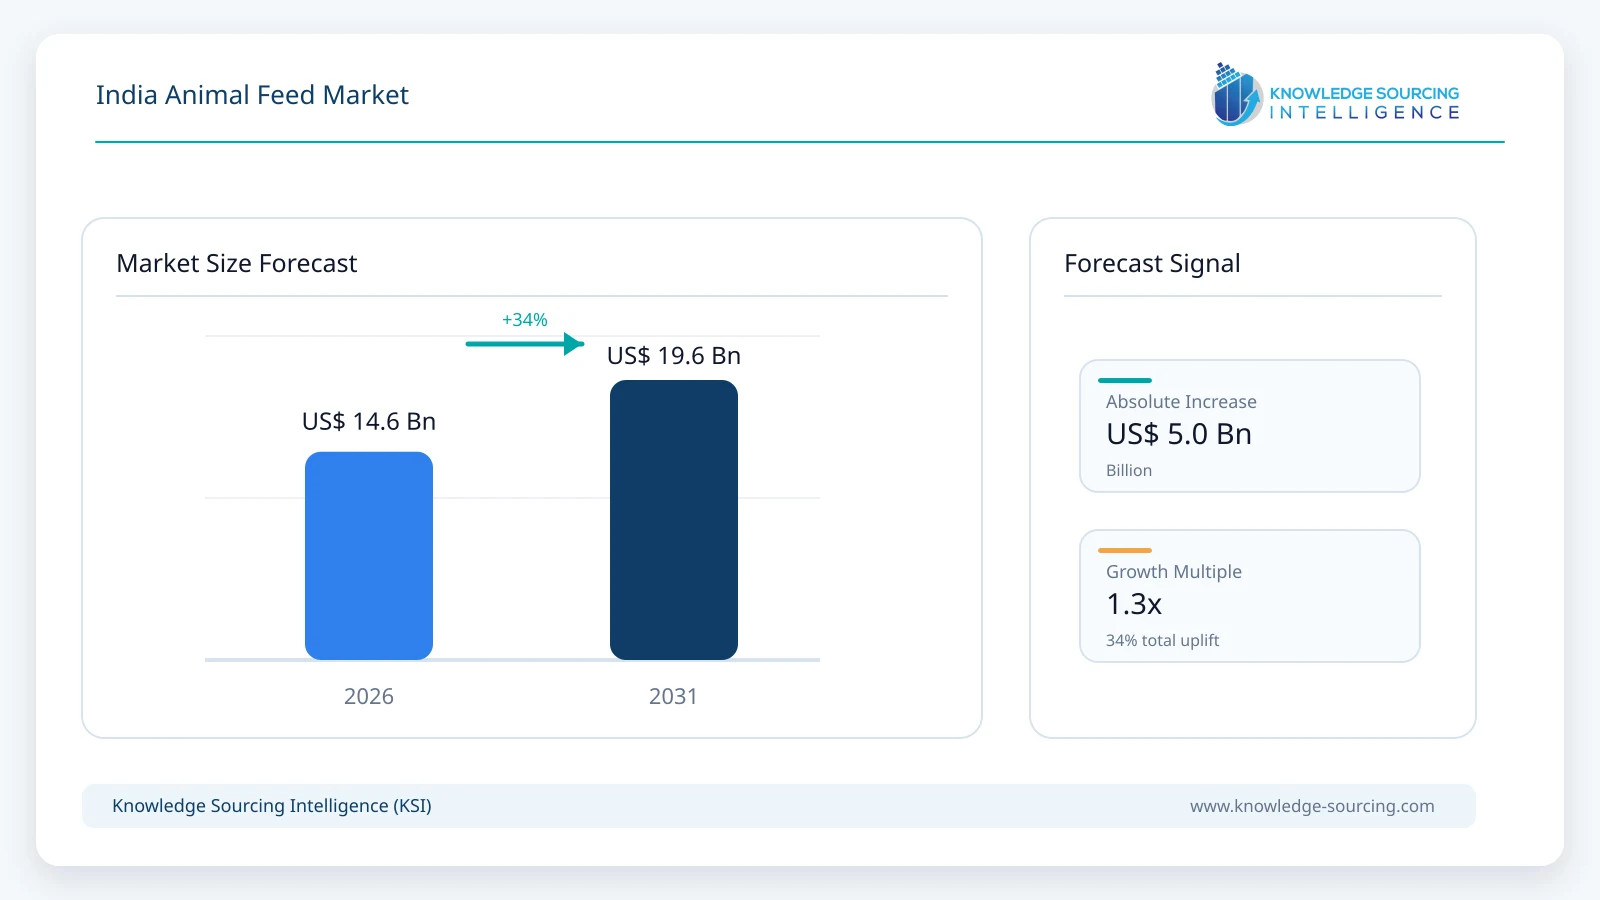
Market Overview
Growth reflects structural changes in livestock production, particularly the gradual shift from farm-mixed feed toward scientifically formulated compound feed. Commercial livestock operators increasingly seek higher feed conversion efficiency, improved animal health, and more predictable production outcomes, creating opportunities for organized feed manufacturers.
India remains the world's largest milk producer and one of the largest producers of eggs, fish, and livestock products. Government statistics show milk production reached 239.3 million tonnes during 2023-24, while egg production exceeded 142 billion units. Continued expansion in these downstream sectors directly influences feed consumption volumes because feed represents one of the highest operating costs in animal production systems.
Value creation within the market extends beyond feed manufacturing. Grain suppliers, oilseed processors, feed additive producers, veterinary nutrition companies, integrated poultry firms, dairy cooperatives, aquaculture operators, distributors, and livestock farmers all participate in the industry's value chain. Product performance, feed conversion ratios, nutritional consistency, disease resistance, and input cost management increasingly influence purchasing decisions.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Milk Production | Over 239 million tonnes (2023-24) | Expanding dairy output supports demand for nutritional feed solutions. |
Egg Production | More than 140 billion eggs annually | Commercial poultry production remains a major feed-consuming sector. |
Fish Production | Above 18 million tonnes | Aquaculture expansion supports higher-value compound feed demand. |
Livestock Population | More than 536 million animals | A large livestock base provides a substantial addressable feed market. |
Poultry Population | Over 850 million birds | Sustains large-scale demand for poultry feed formulations. |
Cooperative Milk Network | Millions of dairy producers are integrated into organized collection systems | Supports commercialization of feed purchasing and advisory services. |
Key Indicator: Feed typically represents the largest operating expense in commercial poultry and aquaculture production systems.
Commercial Meaning: Small improvements in feed efficiency can materially affect producer profitability and supplier competitiveness.
Market Drivers
Expansion of India's dairy production base
India's dairy industry continues to increase output and improve productivity. Government data shows milk production has risen consistently during the past decade, supported by breed improvement programs, veterinary services, and commercial dairy investments. Feed manufacturers benefit because dairy producers increasingly adopt balanced rations and nutritional supplements to improve milk yield and herd health. Higher productivity targets are encouraging demand for compound cattle feed, mineral mixtures, and specialty nutrition products.
Commercialization of poultry production
Large poultry integrators and commercial farms require standardized feed formulations to maintain feed conversion efficiency and flock performance. Poultry feed represents one of the largest operating expenses for broiler and layer producers. As commercial poultry production expands, manufacturers continue investing in feed mills, quality control systems, and nutrition programs. Demand increasingly favors scientifically formulated feed that supports growth rates while controlling production costs.
Growth of aquaculture and fisheries value chains
India's aquaculture industry has become an increasingly important consumer of compound feed. Shrimp farming and freshwater aquaculture require nutritionally optimized feed products to achieve target yields and disease management objectives. Companies such as Avanti Feeds have expanded their presence in specialized aquaculture nutrition, reflecting rising demand from commercial fish and shrimp producers. Feed quality increasingly affects farm economics because feed often accounts for the largest share of production costs.
Government support for livestock productivity and fodder development
Programs such as the National Livestock Mission support breed improvement, fodder development, entrepreneurship, and livestock productivity enhancement. Recent policy initiatives include support for fodder cultivation, livestock infrastructure, and productivity improvements across multiple animal categories. These programs strengthen long-term feed demand by improving the economics of livestock production.
Rising adoption of scientifically formulated feed
Traditional feeding practices continue to account for a substantial share of livestock nutrition in India. However, commercial dairy farms, poultry operators, and aquaculture producers increasingly recognize the benefits of balanced nutrition. Feed manufacturers are responding through specialized formulations, enzyme supplementation, amino acid enrichment, and performance-focused feed solutions. This transition increases value per tonne of feed sold and supports premium product categories.
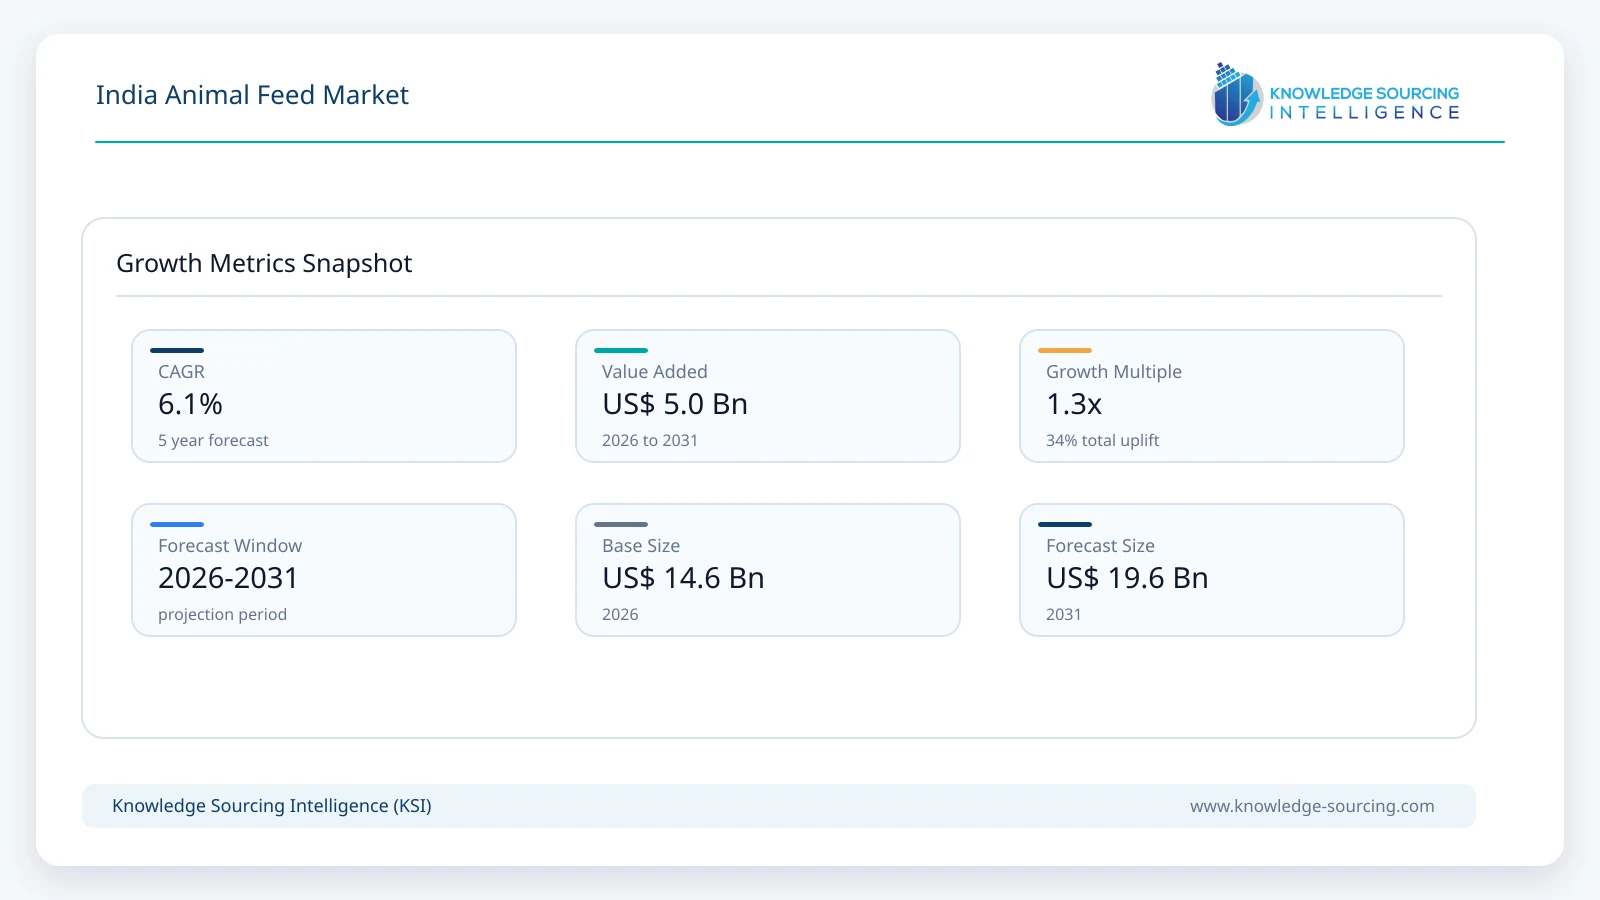
Market Restraints and Challenges
Volatility in corn and soybean meal prices
Corn and soybean meal remain essential feed ingredients across poultry, cattle, and aquaculture applications. Weather disruptions, crop yields, export policies, and competing food-sector demand can influence availability and pricing. Feed manufacturers often face margin pressure when raw material costs rise faster than their ability to pass increases to customers. Smaller producers are particularly exposed because they typically possess less purchasing power and limited hedging capability.
Persistent fodder availability constraints
Several Indian states continue to face shortages of green fodder and feed resources. While government initiatives seek to expand fodder cultivation and improve feed resource management, regional deficits remain a recurring challenge. Livestock producers operating in feed-deficient regions often experience higher feeding costs and lower productivity.
Fragmented livestock ownership structure
A large share of India's dairy and livestock production remains concentrated among smallholders. Many farmers continue to rely on farm-produced feed and agricultural by-products rather than commercial feed products. This limits penetration rates for organized feed manufacturers and increases distribution complexity. Expanding adoption often requires farmer education, technical support, and localized sales networks.
Disease outbreaks and biosecurity risks
Poultry diseases, aquatic animal health issues, and livestock disease events can disrupt production cycles and temporarily reduce feed demand. Disease-related mortality, movement restrictions, and production losses affect both livestock producers and feed suppliers. Manufacturers increasingly invest in feed safety protocols and nutritional solutions designed to support animal health.
Price-sensitive customer base
Feed commonly represents the largest operating expense for poultry, dairy, and aquaculture producers. Purchasing decisions frequently prioritize cost-effectiveness alongside nutritional performance. Manufacturers, therefore, face pressure to balance ingredient quality, formulation performance, and affordability. Competitive pricing conditions can constrain margins, particularly during periods of commodity inflation.
Major Segment Analysis
Compound Feed
Among the market segments, compound feed represents one of the most commercially important categories because it serves organized poultry operations, commercial dairy farms, aquaculture producers, and integrated livestock enterprises. Demand is driven by the need for consistent nutritional quality, predictable animal performance, and improved feed conversion efficiency.
Commercial livestock operators increasingly evaluate feed products based on measurable production outcomes. Poultry producers monitor weight gain and feed conversion ratios, dairy operators focus on milk yield and herd health, while aquaculture producers seek improved growth rates and survival rates. These performance requirements favor compound feed products developed through nutritional science rather than traditional feeding approaches.
Competition within the segment extends beyond price. Manufacturers differentiate through formulation expertise, feed additives, technical advisory services, veterinary support, ingredient quality control, and distribution reach. Companies capable of demonstrating productivity improvements often maintain stronger customer relationships and higher-value product portfolios.
The segment also benefits from increasing integration within the poultry and aquaculture industries. Integrated production systems require standardized feed inputs across multiple production stages, supporting stable demand for commercial feed manufacturers.
Competitive Landscape
Competition in the Indian animal feed market combines multinational nutrition companies, integrated livestock producers, regional feed manufacturers, and specialized aquaculture feed suppliers. Market structure remains moderately fragmented, with competition varying across feed categories and geographic regions.
Companies such as Alltech, Cargill, Archer Daniels Midland, BASF SE, and DSM Nutritional Products compete through nutrition science, feed additives, research capabilities, and global formulation expertise. Their strategies often emphasize feed efficiency, animal health, and productivity improvements.
Indian companies, including Godrej Agrovet, Suguna Foods, Venky's, SKM Animal Feeds and Foods, Golden Feeds, Avitech, and Amrit Feeds, maintain strong positions through regional distribution, customer relationships, and localized market knowledge. Integrated poultry companies benefit from internal feed demand and operational scale.
Avanti Feeds occupies a distinct position through its focus on aquaculture nutrition. Japfa Comfeed India strengthens competition in commercial livestock feed, while regional manufacturers compete aggressively on pricing, service, and market access.
Barriers to entry arise from raw material sourcing requirements, quality control expectations, distribution infrastructure, formulation expertise, and customer trust. Large commercial livestock producers increasingly prefer suppliers capable of ensuring product consistency, technical support, and reliable delivery.
Recent Developments
June 2026: Cargill launched a two-year Integrated Dairy Development Initiative in Maharashtra with Syngenta Foundation India and Digital Green India, targeting 8,000+ dairy farmers across 140+ villages through nutrition, veterinary, and digital advisory support.
February 2026: Cargill inaugurated a new animal feed manufacturing facility in Punjab with an investment of approximately Rs 300 crore. The expansion increases production capacity and strengthens the company's presence in northern India's livestock sector.
February 2026: Zenex Animal Health India acquired a majority stake in Netherlands-based VievePharm, a specialist in natural animal nutrition. The deal expands Zenex’s feed-additive and phytogenic livestock-nutrition offerings while enhancing its European footprint.
August 2025: dsm-firmenich inaugurated a new feed-additive plant in Jadcherla, Hyderabad, introducing local production of Mycofix Secure and Mycofix Shield and creating an integrated Animal Nutrition & Health manufacturing “Super Site” in India.
August 2025: Godrej Agrovet reported strong Animal Feed expansion, with Q1 FY2026 cattle-feed volume up 11%, broiler-feed volume up 13% and layer-feed volume up 4%, demonstrating broad-based feed-volume growth across key categories.
Regulatory and Policy Environment
The regulatory environment is shaped by the Department of Animal Husbandry and Dairying, state animal husbandry departments, feed quality standards, veterinary regulations, and livestock development programs. Government policy increasingly emphasizes productivity enhancement, disease control, genetic improvement, and feed resource development.
The National Livestock Mission remains a central policy mechanism supporting livestock entrepreneurship, breed improvement, and fodder development. Recent modifications expanded support across additional livestock categories while maintaining a strong focus on productivity enhancement and resource availability.
Feed manufacturers must also comply with quality standards related to ingredient sourcing, nutritional specifications, labeling, and feed safety. Increasing attention to traceability and feed quality is likely to benefit organized manufacturers with established compliance capabilities.
Outlook and Strategic Implications
Demand fundamentals remain favorable because livestock production continues to expand across dairy, poultry, and aquaculture sectors. Growth is expected to be supported by increasing productivity requirements rather than solely by livestock population growth. Farmers are under pressure to improve feed efficiency, animal health outcomes, and production economics.
Several strategic themes are expected to shape competition through 2031:
Expansion of compound feed adoption among commercial livestock producers.
Greater use of nutritional additives and performance-enhancing formulations.
Continued investment in feed manufacturing capacity and supply-chain infrastructure.
Increased focus on feed efficiency and sustainability.
Broader adoption of scientific feeding practices among dairy producers.
Expansion of specialized aquaculture nutrition products.
For feed manufacturers, the most attractive opportunities are likely to emerge from value-added nutrition products rather than commodity feed alone. For livestock producers, feed quality and conversion efficiency will remain critical determinants of profitability. For investors, long-term demand will remain closely linked to India's expanding dairy, poultry, and aquaculture industries, which continue to require higher productivity from existing livestock assets.
India Animal Feed Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 14.61 billion |
| Total Market Size in 2031 | USD 19.64 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.1% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Livestock, Form, Production System |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Fodder and Forage
Compound Feed
Feed Additives
By Livestock
Poultry
Cattle
Swine
Aquaculture
Others
By Form
Dry Feed
Liquid Feed
By Production System
Integrated Feed Production Systems
Commercial Feed Mills
By Source
Organic Feed
Conventional Feed
By Raw Material
Corn
Soybean Meal
Rendered Meal
Wheat Bran & Others
By Distribution Channel
Direct Sales (B2B)
Distributors & Dealers
Retail Sales
Online Channels
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation Overview
2.5. Key Market Highlights
3. MARKET DYNAMICS
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Market Challenges
3.5. Porter’s Five Forces Analysis
3.6. Value Chain Analysis
3.7. Regulatory & Policy Landscape
3.8. Strategic Recommendations
4. TECHNOLOGY AND INNOVATION OUTLOOK
5. INDIA ANIMAL FEED MARKET BY TYPE
5.1. Introduction
5.2. Fodder and Forage
5.3. Compound Feed
5.4. Feed Additives
6. INDIA ANIMAL FEED MARKET BY LIVESTOCK
6.1. Introduction
6.2. Poultry
6.3. Cattle
6.4. Swine
6.5. Aquaculture
6.6. Others
7. INDIA ANIMAL FEED MARKET BY FORM
7.1. Introduction
7.2. Dry Feed
7.3. Liquid Feed
8. INDIA ANIMAL FEED MARKET BY PRODUCTION SYSTEM
8.1. Introduction
8.2. Integrated Feed Production Systems
8.3. Commercial Feed Mills
9. INDIA ANIMAL FEED MARKET BY SOURCE
9.1. Introduction
9.2. Organic Feed
9.3. Conventional Feed
10. INDIA ANIMAL FEED MARKET BY RAW MATERIAL
10.1. Introduction
10.2. Corn
10.3. Soybean Meal
10.4. Rendered Meal
10.5. Wheat Bran & Others
11. INDIA ANIMAL FEED MARKET BY DISTRIBUTION CHANNEL
11.1. Introduction
11.2. Direct Sales (B2B)
11.3. Distributors & Dealers
11.4. Retail Sales
11.5. Online Channels
12. COMPETITIVE LANDSCAPE
12.1. Major Players & Strategy Analysis
12.2. Market Share Analysis
12.3. Product Portfolio Benchmarking
12.4. Mergers, Acquisitions & Collaborations
12.5. R&D and Innovation Analysis
12.6. Regional Presence Analysis
12.7. Competitive Dashboard
13. COMPANY PROFILES
13.1. Cargill, Incorporated
13.2. Archer Daniels Midland (ADM)
13.3. BASF SE
13.4. Alltech, Inc.
13.5. dsm-firmenich
13.6. Godrej Agrovet Limited
13.7. Venky’s (India) Limited
13.8. Avanti Feeds Limited
13.9. Japfa Comfeed India Private Limited
13.10. Suguna Foods Private Limited
13.11. SKM Animal Feeds and Foods (India) Pvt. Ltd.
13.12. Anmol Feeds
13.13. Hindustan Animal Feeds
14. RESEARCH METHODOLOGY
15. CONCLUSION AND KEY INSIGHTS





Frequently asked questions
What is the forecasted CAGR for the India Animal Feed market (2026-2031)?
The India Animal Feed Market is forecast to grow at a 6.1% CAGR.
What is the projected market size of India Animal Feed by 2031?
The India Animal Feed Market is projected to reach USD 19.64 billion by 2031.
What were the primary growth drivers for the market?
Growth in milk, egg, meat, and aquaculture production are key drivers.
Which animal feed categories dominate organized demand in India?
Poultry and cattle feed account for a large share of demand.
What significant shift is occurring in India's animal feed market?
A shift from farm-mixed feed to scientifically formulated compound feed.
What was the market valuation for India Animal Feed in 2026?
The India Animal Feed Market was valued at USD 14.61 billion in 2026.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). India Animal Feed Market Size, Share & Forecast (2026–2031). https://www.knowledge-sourcing.com/report/india-animal-feed-market