
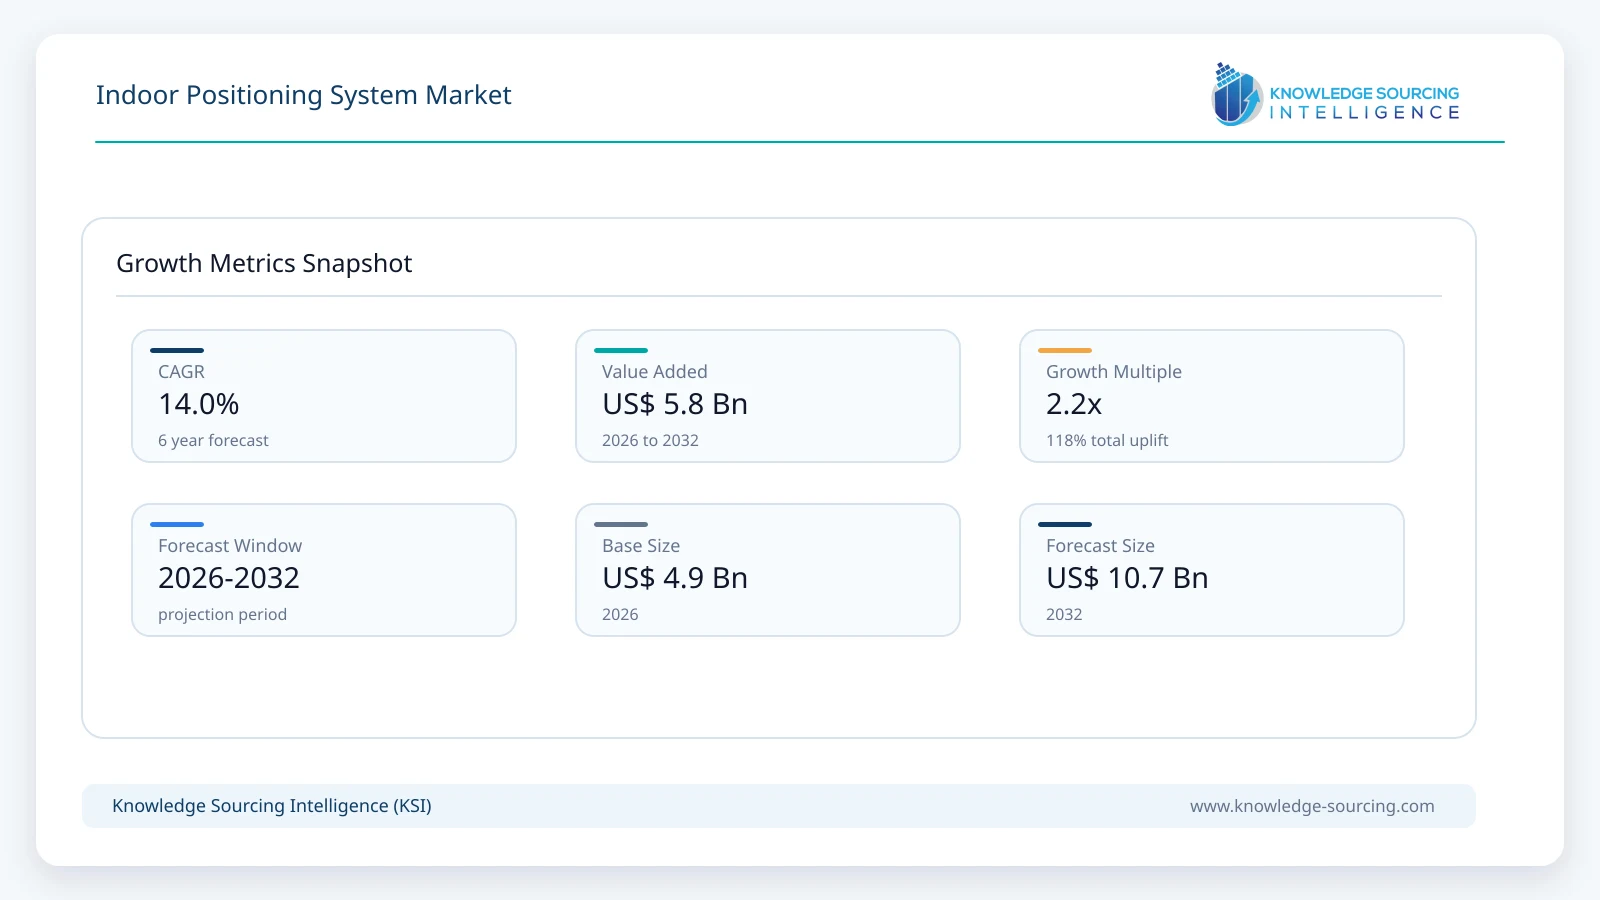
The Indoor Positioning System market is forecast to grow at a CAGR of 14.0%, reaching USD 10.7 billion in 2032 from USD 4.9 billion in 2026.
Highlights:
- 1Selected segmentManufacturing and warehousing represent an estimated US$1.67 billion in 2026, or 34.3% of the market, rising to US$4.38 billion by 2032 at a 17.4% CAGR. The segment benefits from automation, material-flow visibility and production-system integration.
- 2Hardware integrationEnterprise access points capable of location functions can lower incremental installation cost, although dedicated UWB remains important for precision industrial tracking and automated control.
- 3Commercial bottleneckRF calibration, multipath effects, battery replacement and ongoing map maintenance can outweigh the initial tag price when sites operate at scale.
- 4Platform economicsProcurement is shifting from standalone maps toward location data integrated with MES, WMS, EHR and facility-management processes, where recurring software and support create durable revenue.
- 5Competitive positioningDirect IPS and RTLS vendors should be separated from chip suppliers and consumer mapping ecosystems, which influence technology adoption but do not necessarily sell enterprise IPS deployments.
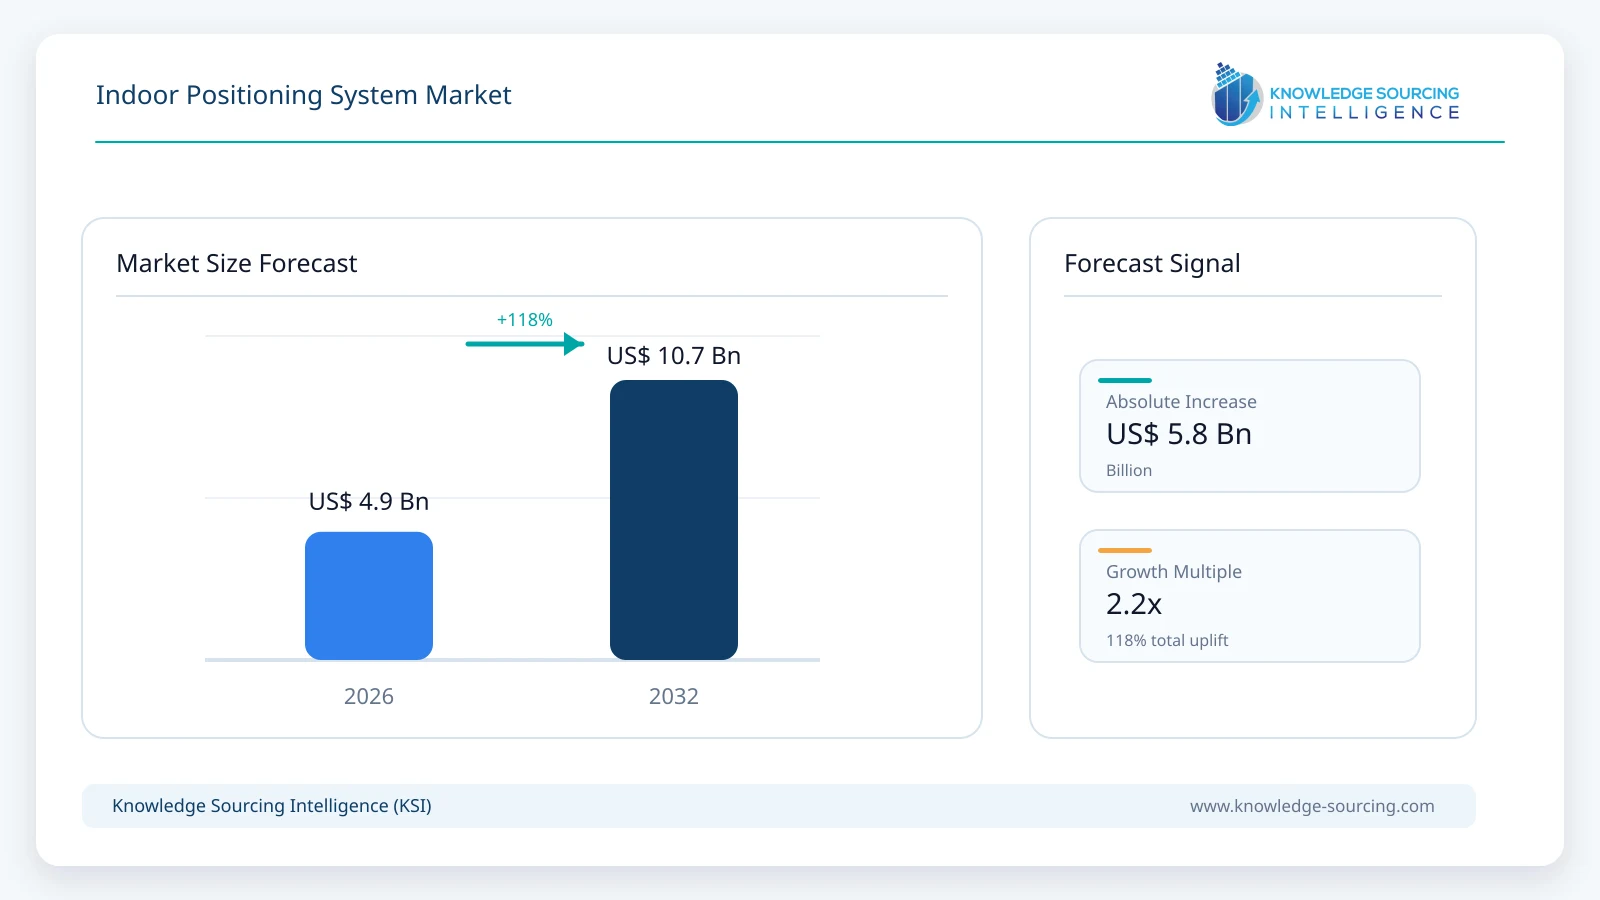
Indoor positioning systems are becoming an operational layer for facilities where satellite navigation does not provide dependable room-level, aisle-level or floor-level coordinates. The market spans positioning hardware, location engines and the engineering services needed to connect spatial data with workflows. It represents a tightly defined enterprise market, rather than the full expenditure on Wi-Fi networks, smartphones or general-purpose warehouse automation. A deployment earns its place in the market when an organization pays for location-specific tags, anchors, maps, software subscriptions or implementation. This boundary matters because the same facility can buy a wireless network for connectivity, use its signals for indoor navigation and install a separate ultra-wideband system for precision asset tracking. Counting the entire network and both positioning systems would inflate market revenues. The competitive advantage increasingly resides in integrating these layers without charging customers twice for common infrastructure.
Technology choices now follow commercial requirements rather than a single universal accuracy benchmark. Bluetooth Low Energy is suitable for many room-level location, visitor navigation and asset-presence applications, whereas ultra-wideband supports workflows requiring tighter spatial precision and more frequent updates. Wi-Fi fine timing measurements can leverage compatible access points, but installed hardware, client support and the physical environment still determine achievable performance. Bluetooth Core 6.0 introduced Channel Sounding, including phase-based ranging and round-trip timing, creating a standards-based route to better distance estimation. It is not equivalent to an automatic deployment of centimeter-level positioning across existing venues. Cisco has documented Wi-Fi FTM and UWB functions in its 2026 AnyLocate architecture, while HPE describes location services embedded in enterprise networking infrastructure. This evolution changes vendor economics: connectivity suppliers can make indoor location more accessible, but specialist providers still win when applications demand workflow software, calibration, quality-of-service assurance and high-value integration with operating systems. Site owners therefore evaluate lifecycle cost, not just hardware accuracy.
Market Dynamics
Infrastructure convergence and procurement economics
The strongest adoption catalyst is the growing ability to reuse existing enterprise infrastructure for indoor location services. A logistics facility upgrading its wireless network can potentially activate positioning functions alongside connectivity, avoiding a second parallel deployment. However, reuse depends on the access point model, software licensing, installation geometry and device capability, so the savings are not automatic. Cisco AnyLocate combines Wi-Fi fine timing measurements with UWB-supported location functions, while HPE is making positioning data more accessible to partner applications through open interfaces. For vendors, this challenges hardware-only propositions because the customer may already possess a partial sensing layer. Specialist providers respond by concentrating on accuracy validation, real-time workflow triggers and deployments where conventional access points do not achieve the required reliability. For buyers, the primary financial calculation is the avoided cost of equipment searches, inventory buffers, missed process steps or visitor-navigation failures. Demonstrating those outcomes becomes essential as basic location coordinates increasingly resemble a feature of the network rather than an independently priced service.
Standards, accuracy and implementation limits
Demand is also shaped by the difference between ranging capability and dependable operational positioning. Bluetooth Channel Sounding standardizes secure distance measurement between compatible devices, but a complete indoor positioning solution still needs reference locations, geometry, location computation and a map. In reflective industrial buildings, metal racks, moving machinery and multiple floors can change radio behavior, complicating performance guarantees. Ultra-wideband systems can support tighter position estimates and rapid updates, yet require planning for anchors, power, cabling and tagged assets. KINEXON offers both wired high-precision and more flexible mesh deployments, illustrating why suppliers maintain different architectures for different applications. These choices alter capital expenditure, installation disruption and support intensity. An enterprise should therefore evaluate performance against its actual workflow, including how many moving objects must be located, tolerated latency and the costs of an incorrect position. Product datasheet accuracy alone does not establish that a solution will deliver measurable efficiency improvements inside a live, complex facility.
Commercial restraints and privacy requirements
Deployments face practical constraints that remain underrepresented in many market descriptions. Beacons and tags must be purchased, commissioned, maintained and sometimes replaced. Facility layout changes can degrade radio maps, while battery inventories and device losses create recurring work for operations teams. Location data can also identify employees or visitors, making lawful processing, transparency, retention policies and access controls essential in regulated jurisdictions. Data protection law does not categorically require local edge computation, however; the choice between cloud and on-premise processing depends on the applicable legal basis, architecture and risk assessment. The page also previously linked US wireless E911 location rules to a presumed requirement for building owners to install IPS. Those rules focus on wireless carriers obligations to deliver emergency caller location information and should not be used as evidence of a universal commercial building mandate. Accurate regulatory framing improves buyer trust and prevents unsupported demand forecasts. Vendors able to simplify installation and document location-data governance may reduce procurement friction without claiming regulation itself guarantees adoption.
Major Segment Analysis: Manufacturing & Warehousing
Manufacturing and warehousing form the selected segment for detailed market analysis because the commercial value of location data is directly connected to physical throughput and process control. Indicative estimates place the sector at US$1.67 billion in 2026, representing 34.3% of the global market. Revenue is projected to reach US$4.38 billion in 2032 at a 17.4% CAGR, reflecting increasing coverage of large industrial facilities and a rising value of software-integrated contracts. The strongest use cases include tracking work-in-progress containers, monitoring the movement of automated vehicles, identifying misplaced tools and generating event-based updates to manufacturing execution systems. KINEXON combines UWB location hardware with a software platform linked to warehouse, manufacturing and enterprise systems, while Ubisense emphasizes industrial location events that drive automated action. In these settings, a delayed or incorrect location can trigger an unnecessary search, a production interruption or a safety issue. Buyers therefore pay for reliable, context-rich operations data rather than a simple moving dot on a dashboard.
The segment also exposes an important distinction between revenue growth and technological adoption. A site using tags to locate equipment may expand coverage from one line to an entire factory, creating demand for additional tags, anchors and software capacity. Yet locations already served by Wi-Fi or hybrid Bluetooth systems may not require a proportionate increase in dedicated hardware. Software suppliers can benefit from the number of integrated workflows, while hardware suppliers experience stronger demand during initial installation or major refresh cycles. Sewio packages UWB tracking hardware with location software for industrial environments, and Zebra offers an enterprise platform that converts sensor data into operational context. In both cases, the measurable return depends on process redesign and data integration, not merely purchasing tags. Vendors need to substantiate improvements in retrieval time, utilization, order progression and production synchronization before large deployments are approved. The competitive position shifts toward firms able to connect real-time location information with established factory applications, implement repeatable integrations and deliver predictable performance under difficult radio conditions.
Other end-user segments
Retail, hospitals, transport hubs and entertainment facilities adopt IPS for distinctly different financial reasons and should not be grouped into a residual category. In retail, wayfinding can reduce friction for shoppers, while the business case for location analytics depends on measurable conversion or staff productivity improvements. Hospitals often start with asset search, equipment utilization, staff safety or patient-flow management, where room-level reliability and integration with clinical systems matter more than consumer-style navigation. CenTrak and HID both provide healthcare-focused location services, demonstrating the importance of operational applications beyond visitor mapping. In airports and large transport facilities, floor-aware navigation and accessible routing can improve passenger movement, although successful deployment requires continually updated indoor maps and signage systems. Pointr provides indoor navigation for airports and other complex sites, while Esri links facility mapping with operational positioning applications. Hospitality and entertainment venues typically prioritize wayfinding, workforce coordination and visitor experience. These segments require separate procurement assumptions and should not be combined with industrial deployments using identical price and accuracy parameters.
Regional Analysis
North America
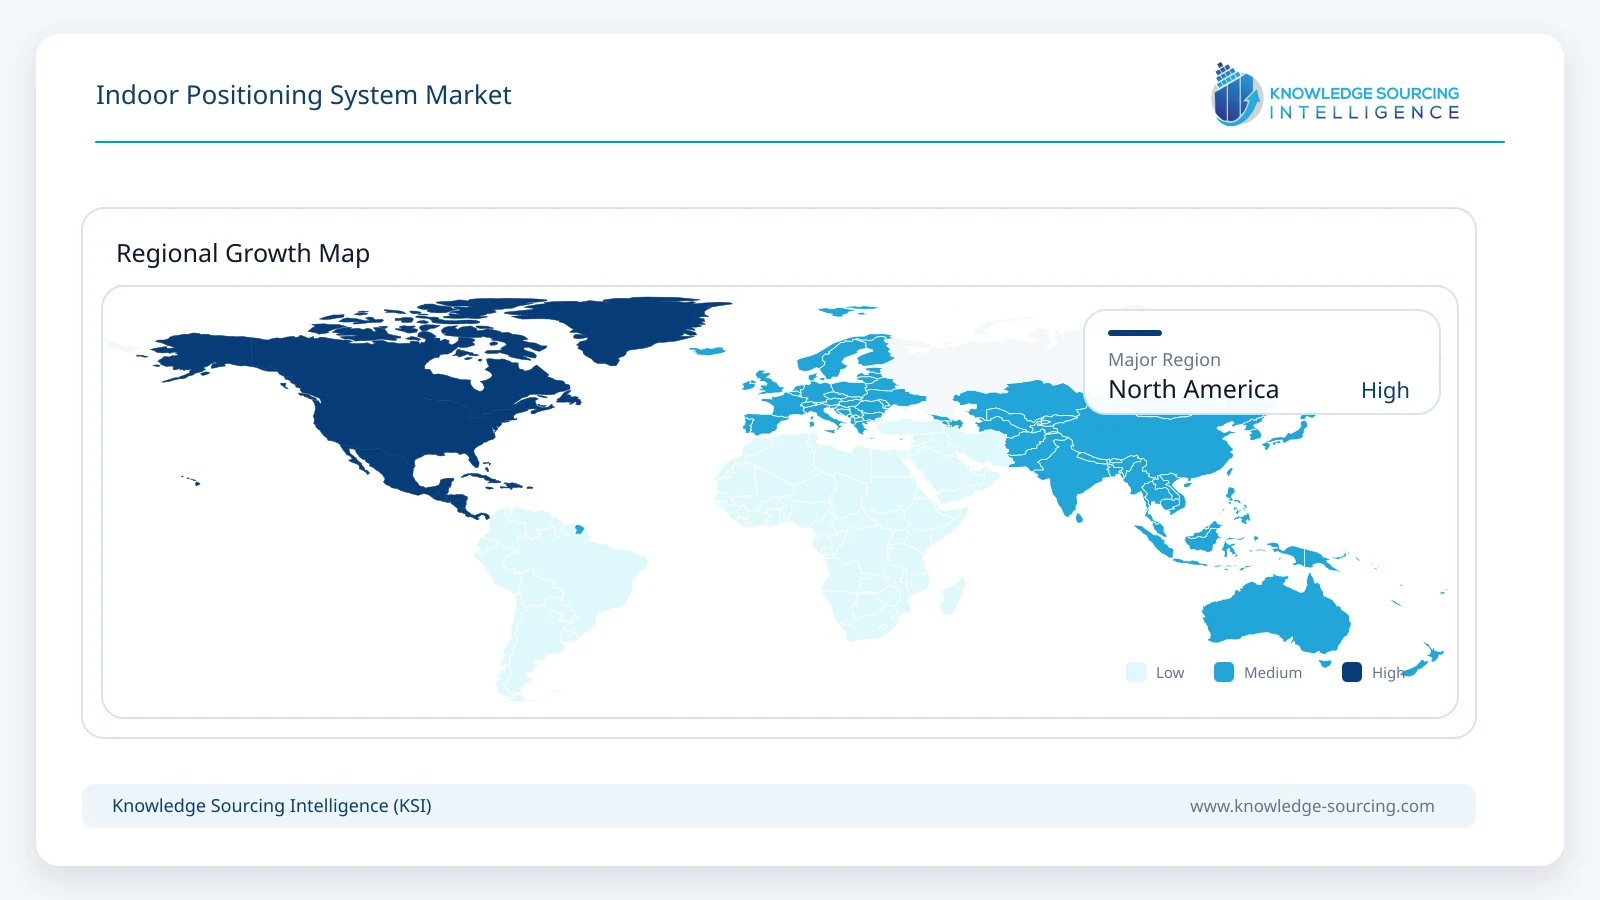
North America has a strong commercial foundation for indoor positioning because many large enterprises already operate wireless networks, automation systems and digitally managed facilities. Industrial projects can pair ultra-wideband tags with warehouse-management or manufacturing-execution software, while healthcare deployments concentrate on reducing equipment search time and improving staff safety. The United States also has established public-safety requirements for wireless emergency caller location, but these requirements concern carrier performance and do not independently establish a mandate for all buildings to buy IPS. The region’s competitive landscape includes wireless infrastructure suppliers, industrial tracking vendors and specialist clinical RTLS companies, each selling different components of a facility-level solution. Procurement teams often demand integration with existing systems, cybersecurity review and evidence that spatial data produces benefits beyond ordinary asset identification. The result is a market with several economically distinct tiers: precision systems for industrial workflows, network-enabled location analytics and indoor navigation for public facilities. Comparing their prices or installed sites without normalizing the scope can produce misleading regional estimates.
South America
South America presents selective opportunities for indoor location systems as distribution networks, manufacturing facilities and large public venues modernize their operations. Warehouse and factory operators can use asset positioning to improve material retrieval, coordinate vehicle movement and link physical events with enterprise applications. Adoption depends on the ability to demonstrate savings against initial installation and ongoing maintenance. In budget-sensitive deployments, Wi-Fi or Bluetooth can offer a lower-cost starting point where room-level positioning is sufficient. More demanding industrial use cases may justify UWB systems when precision and update frequency affect throughput or safety. Regional suppliers frequently depend on local integrators for site surveys, calibration and after-sales support. As a result, commercial performance varies by facility type and project maturity rather than following national technology spending in a uniform way.
Europe
Europe combines substantial industrial positioning demand with an emphasis on data protection, interoperable systems and operational efficiency. Manufacturing applications need reliable identification of material flows, production assets and moving equipment, creating opportunities for UWB and software-enabled location platforms. Suppliers including Ubisense, Quuppa and KINEXON demonstrate different methods for converting positioning measurements into industrial workflows. The region’s venue operators also deploy indoor mapping and navigation for staff and visitors. Procurement requirements are influenced by the handling of identifiable location data, especially when personnel are tracked. That creates demand for privacy-by-design settings, defined retention periods and transparent access rules, without implying that European law generally prohibits cloud processing. Supplier competition therefore hinges partly on deployment architecture and the ability to integrate with a customer’s existing IT and operational systems. Europe’s growth prospects are also sensitive to capital budgets and the economics of replacing legacy installations. Buyers that can activate positioning through network refreshes may delay separate beacon investments while increasing spending on applications and engineering services.
Middle East and Africa
Indoor positioning demand in the Middle East and Africa is linked to large transport hubs, healthcare facilities, hospitality developments and increasingly automated industrial sites. Airports and mixed-use complexes can combine indoor maps with positioning to support passenger wayfinding, accessibility and operational coordination. Healthcare operators may adopt asset-location systems to reduce equipment search time and improve patient-flow visibility. However, large building footprints and complex layouts raise the importance of accurate mapping, radio calibration and long-term system maintenance. Procurement decisions also depend on integration with existing facilities software and the availability of local installation partners. In industrial projects, UWB can support precise movement tracking, while network-enabled approaches may be more economical for navigation applications. Suppliers capable of delivering end-to-end deployment and support can be better positioned than those offering standalone positioning hardware without local services.
Asia Pacific
Asia Pacific combines industrial location requirements with large-scale indoor navigation opportunities. Manufacturing facilities in China, Japan, India and other production markets can use RTLS platforms to track work-in-progress, coordinate material handling and monitor vehicles or reusable equipment across production floors. Airports, transit facilities, shopping centres and campuses also create demand for floor-aware navigation and location-based operational services. Technology selection depends on the precision required and the network infrastructure already available. Bluetooth and Wi-Fi solutions can reduce additional hardware expenditure in navigation-led deployments, whereas UWB is often more appropriate when process control demands highly dependable location events. Systems integrators play an important role because local radio conditions, facility layouts and enterprise-software integration vary widely. Revenue opportunities depend on conversion from pilot deployments to repeatable multi-site projects, rather than the number of smartphones or wireless access points already installed in a country.
Competitive Environment and Analysis
Competitive intensity is increasing as multiple technology stacks can now solve overlapping indoor-location requirements. Network companies such as Cisco and HPE offer infrastructure-enabled location services, while specialized firms including Quuppa, Sewio, CenTrak and KINEXON focus on positioning engines, tags, workflow software or industry-specific deployments. Esri and Pointr provide mapping and wayfinding capabilities that can complement radio-based positioning rather than replace its entire infrastructure. These business models are not interchangeable, and a single deployment may use more than one supplier. The company roster therefore prioritizes organizations with independently identifiable IPS, RTLS or indoor navigation offerings. General semiconductor suppliers such as Broadcom and Qualcomm belong in the supply-chain discussion unless their specific enterprise location revenue is identifiable; Apple and Google are influential platform ecosystems but should not automatically be assigned direct enterprise IPS market share. As pricing moves toward subscriptions and bundled platform access, provider comparisons need consistent definitions of hardware sales, implementation fees, recurring software and channel revenue. Meaningful vendor comparisons therefore require consistent treatment of hardware receipts, implementation services, platform subscriptions and distribution-channel revenue.
Recent Developments
October 2026: Cisco updated its AnyLocate documentation for compatible Catalyst wireless platforms, describing UWB and Wi-Fi fine timing measurement use cases for asset tracking, indoor wayfinding and access-point positioning.
June 2026: Esri announced that ArcGIS IPS would no longer be offered as a separately priced product, with additional integration into ArcGIS capabilities planned for its October 2026 software releases.
May 2026: Esri outlined ArcGIS IPS updates in ArcGIS Pro 3.7 and supporting mobile software, including improvements to beacon planning, location-data setup and maintenance workflows.
Indoor Positioning System Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 4.9 billion |
| Total Market Size in 2032 | USD 10.7 billion |
| Forecast Unit | Billion |
| Growth Rate | 14.0% |
| Study Period | 2021 to 2032 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2032 |
| Segmentation | Component, End-User Industry, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Component
Hardware
Software
Services
By End-User Industry
Manufacturing & Warehousing
Retail
Transportation
Healthcare
Hospitality, Media & Entertainment
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
China
Japan
India
Australia
Taiwan
Thailand
Indonesia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of Study
1.4. Market Segmentation
2. RESEARCH METHODOLOGY
2.1. Research Data
2.2. Assumptions
2.3. Estimation and Reconciliation
3. EXECUTIVE SUMMARY
3.1. Research Highlights
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porters Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry
4.4. Industry Value Chain Analysis
5. INDOOR POSITIONING SYSTEM MARKET, BY COMPONENT
5.1. Introduction
5.2. Hardware
5.3. Software
5.4. Services
6. INDOOR POSITIONING SYSTEM MARKET, BY END-USER INDUSTRY
6.1. Introduction
6.2. Manufacturing & Warehousing
6.3. Retail
6.4. Transportation
6.5. Healthcare
6.6. Hospitality, Media & Entertainment
6.7. Others
7. INDOOR POSITIONING SYSTEM MARKET, BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. United States
7.2.2. Canada
7.2.3. Mexico
7.3. South America
7.3.1. Brazil
7.3.2. Argentina
7.3.3. Others
7.4. Europe
7.4.1. Germany
7.4.2. France
7.4.3. United Kingdom
7.4.4. Italy
7.4.5. Others
7.5. Middle East and Africa
7.5.1. Saudi Arabia
7.5.2. UAE
7.5.3. Israel
7.5.4. Others
7.6. Asia Pacific
7.6.1. China
7.6.2. Japan
7.6.3. India
7.6.4. Australia
7.6.5. Taiwan
7.6.6. Thailand
7.6.7. Indonesia
7.6.8. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Emerging Players and Market Opportunities
8.3. Mergers, Acquisitions, Agreements and Collaborations
8.4. Vendor Competitiveness Matrix
9. COMPANY PROFILES
9.1. Cisco Systems
9.2. Hewlett Packard Enterprise (HPE Aruba Networking)
9.3. Zebra Technologies
9.4. Esri
9.5. CenTrak
9.6. HID Global
9.7. Ubisense
9.8. Pointr
9.9. IndoorAtlas
9.10. KINEXON
9.11. Sewio
9.12. Quuppa
10. LIST OF FIGURES
11. LIST OF TABLES





Frequently asked questions
What is the forecasted market size for Indoor Positioning Systems by 2032?
The Indoor Positioning System Market is projected to reach USD 10.7 billion by 2032.
What is the projected CAGR for the IPS market (2026-2032)?
The Indoor Positioning System Market is forecast to grow at a 14.0% CAGR.
Which industry segment dominates IPS market revenue by 2032?
Manufacturing and warehousing lead, reaching $4.38 billion by 2032.
What are the primary commercial bottlenecks for large-scale IPS deployments?
RF calibration, battery replacement, and map maintenance are bottlenecks.
How is procurement evolving within the Indoor Positioning System market?
Procurement shifts to location data integrated with MES, WMS, EHR.
What key technologies are important for indoor positioning solutions?
Bluetooth Low Energy and Ultra-Wideband are key positioning technologies.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Indoor Positioning System Market - Strategic Insights and Forecasts (2026-2032). https://www.knowledge-sourcing.com/report/indoor-positioning-system-market