
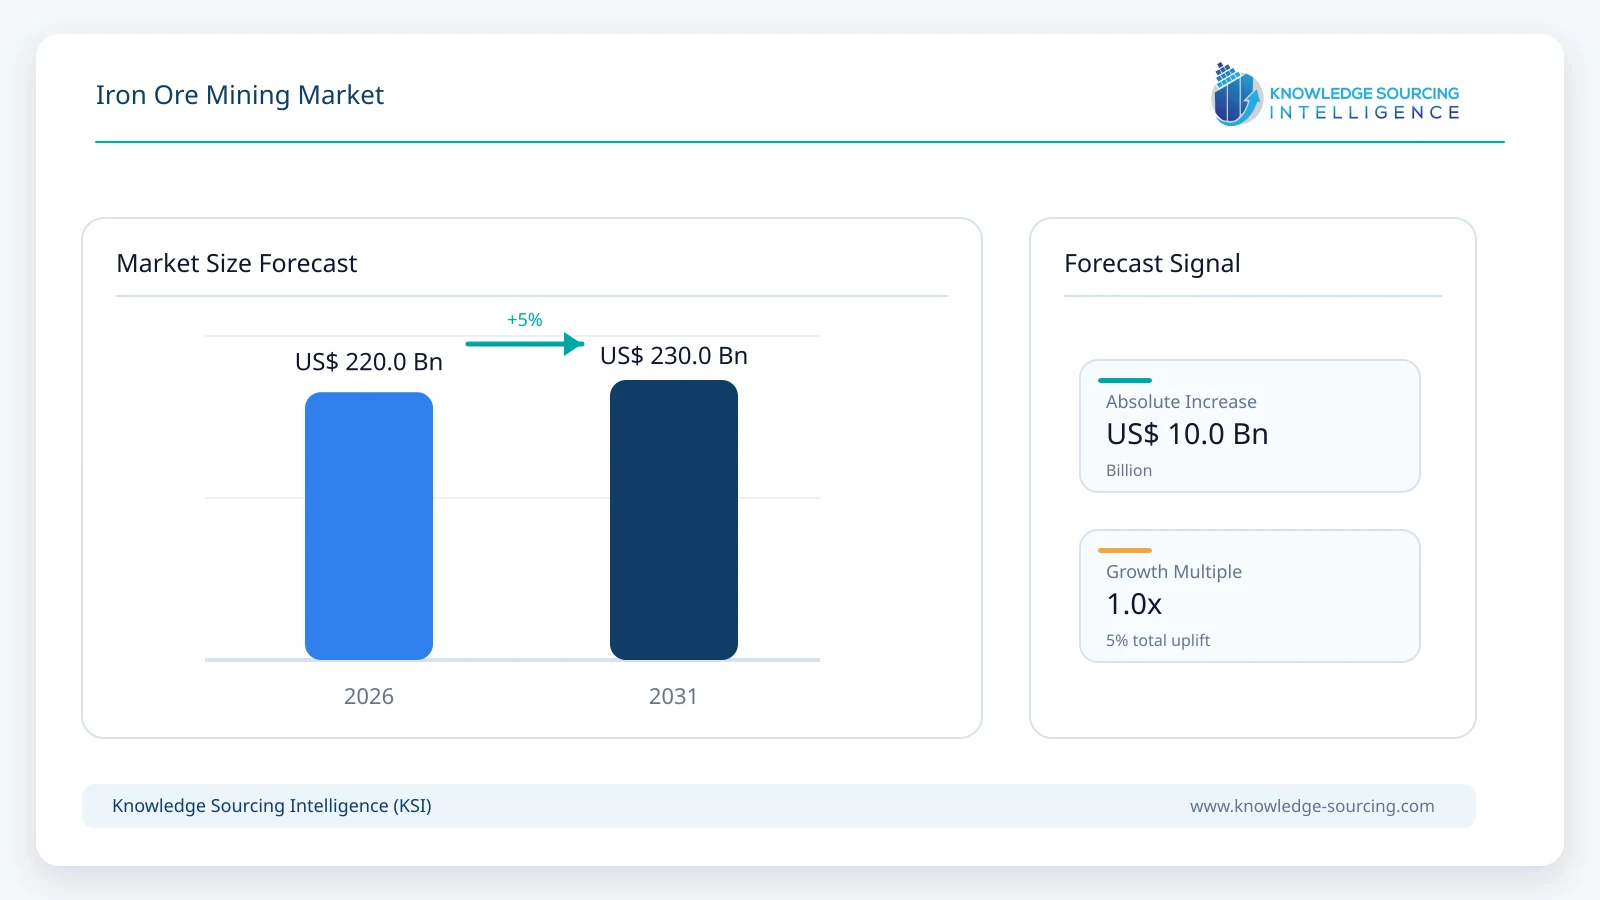
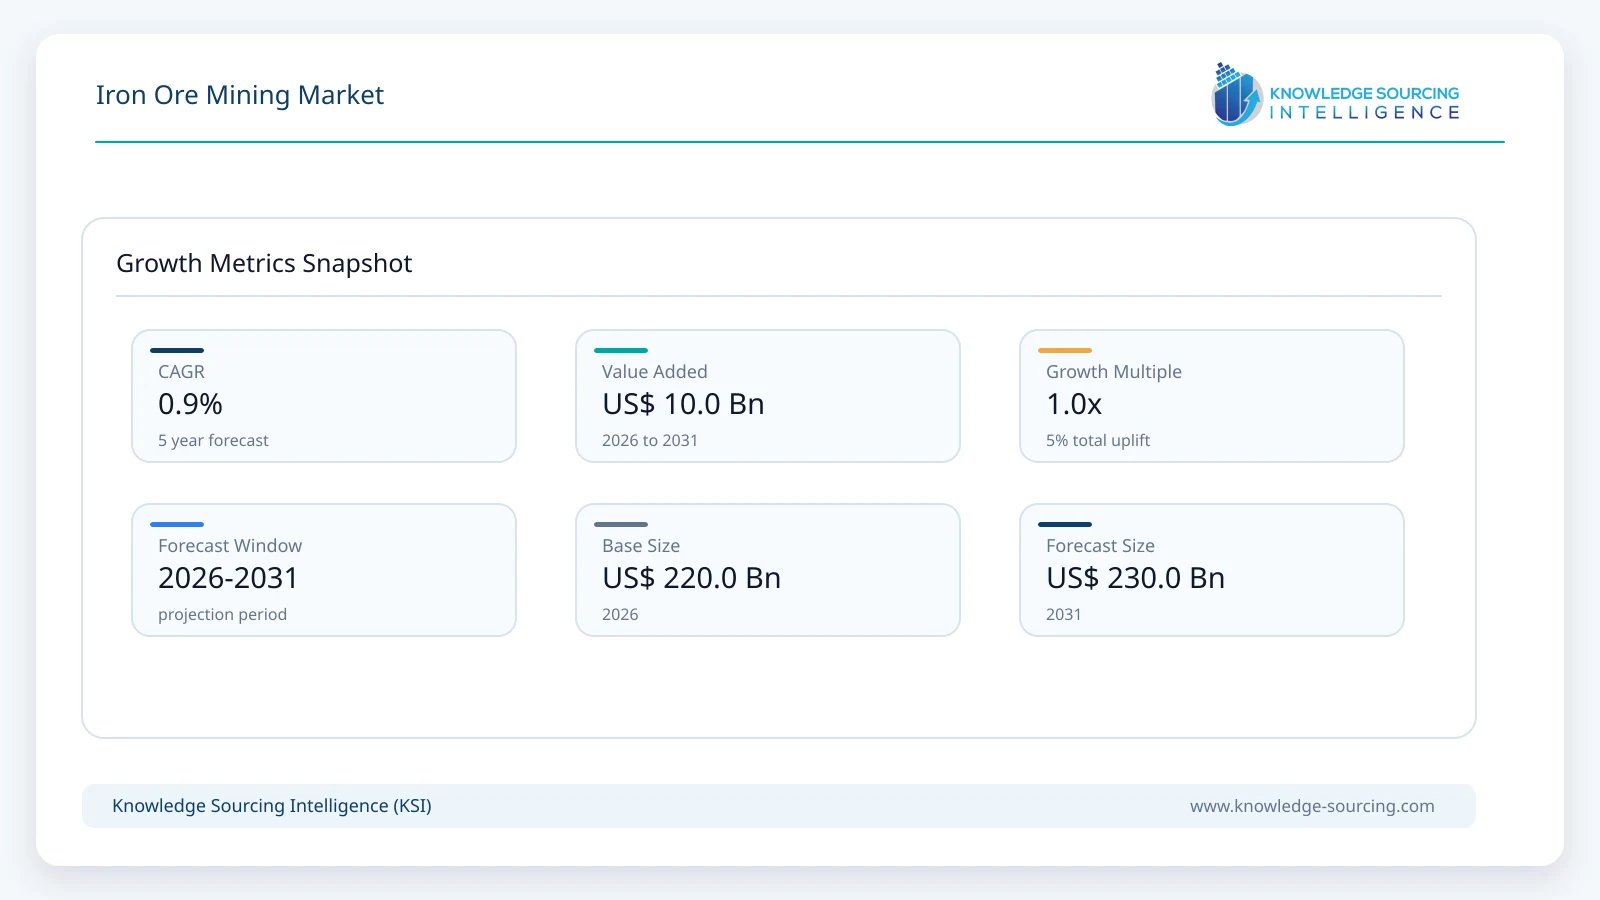
The global iron ore mining market is estimated at USD 220.0 billion in 2026 and is projected to reach approximately USD 230.0 billion by 2031, representing a CAGR of about 0.9% during the forecast period.
Highlights:
- 1Asia Pacific remains the largest producing region, led by Australia, China and India.
- 2Global mined iron ore production is approximately 2.57 billion tonnes in 2026.
- 3Iron ore prices are expected to soften as supply growth outpaces modest steel-demand growth.
- 4Simandou adds a new high-grade supply source and begins reshaping seaborne trade flows.
- 5High-grade fines and DR-quality pellets gain strategic importance as steelmakers pursue lower-emission production.
- 6India remains the fastest-growing major steel-demand market, supporting stronger regional iron ore consumption.
Iron ore is the primary source of iron used in steelmaking, and nearly all saleable production ultimately serves blast furnaces, direct-reduction plants or integrated steelmaking routes. The market is highly concentrated geographically. Australia, Brazil, India and China together account for the majority of global mined output, while Australia and Brazil dominate seaborne exports. USGS production data for 2025 place Australia at roughly 980 million tonnes, Brazil at 420 million tonnes, India at 310 million tonnes and China at 290 million tonnes of usable ore. BHP's 2026 Western Australia Iron Ore technical filing indicates world production of approximately 2.57 billion tonnes in 2026, increasing gradually toward the end of the decade.
Market value is not rising at the same rate as production. The World Bank expects iron ore prices to decline in 2026 and 2027 as additional supply from Africa, Brazil and Australia meets modest steel-demand growth. Worldsteel forecasts global finished steel demand at 1.724 billion tonnes in 2026, only 0.3% above 2025, before a stronger 2.2% increase in 2027. China remains the largest steel-consuming country but demand is forecast to decline 1.5% in 2026, while India grows 7.4%. This shifts incremental iron ore demand toward India and other developing markets even as China's mature steel sector continues to determine seaborne pricing.
Product quality is becoming more important within this slower-growth volume environment. Lower-emission steelmaking places greater value on ores with higher iron content and lower impurities because they can reduce coke use, slag volume and energy consumption. Kumba reported an average realized export price of USD 90 per wet metric tonne in the first half of 2026, 8% above the 62% Fe FOB-equivalent benchmark because of product quality. LKAB supplies pellets around 67% Fe and fines above 70% Fe, while Champion Iron is commissioning direct-reduction-quality concentrate. These premiums create a value-growth opportunity even when benchmark fines pricing is subdued.
Market Trends
Simandou Is Changing the Seaborne Supply Balance
The emergence of Guinea's Simandou project is the most important structural supply change in the iron ore market. Rio Tinto achieved first high-grade sales from Simandou in April 2026 and maintained 2026 sales guidance of 5-10 million tonnes, with a material ramp expected thereafter. Simandou introduces additional high-grade ore into a market historically dominated by Australia and Brazil and is expected to increase Atlantic-to-Asia seaborne availability. The project strengthens long-term supply security for steelmakers but also adds downward pressure to benchmark pricing if demand growth remains modest.
High-Grade Ore Is Gaining a Decarbonization Premium
Steel-sector decarbonization is creating stronger differentiation between ore grades. Blast furnaces can reduce fuel use and slag generation by consuming higher-grade inputs, while gas- or hydrogen-based direct reduction requires tight impurity specifications and generally higher iron content than conventional blast-furnace feed. Kumba reported an 8% realized-price premium over the 62% Fe FOB-equivalent benchmark in the first half of 2026. LKAB markets high-grade DR pellets, and Champion Iron's DRPF program targets direct-reduction-grade concentrate. This shifts competitive positioning from pure tonnage toward grade, pelletizing capability and impurity management.
India Is Becoming More Important to Global Demand Growth
China remains the largest iron ore consumer through its enormous steel industry, but incremental demand is moving toward India and other developing economies. Worldsteel expects Indian finished-steel demand to increase 7.4% in 2026 and 9.2% in 2027, supported by infrastructure, construction, automotive demand and capital expenditure. India is also a major iron ore producer, with NMDC targeting substantial production expansion toward 2030. This combination of stronger domestic steel growth and expanding local ore supply creates a more self-contained but rapidly growing regional market.
Mine Electrification and Green Iron Are Moving Closer to Commercial Deployment
Major producers are increasingly linking iron ore mining strategy with low-carbon ironmaking and mine-site decarbonization. Fortescue produced first hot metal at its Christmas Creek Green Metal Project in August 2026 using an electric smelting process designed to support lower-emission iron production from Pilbara ore. Rio Tinto and BHP are also investing in operational decarbonization, renewable power and technology partnerships. These projects do not materially change total iron ore tonnage in the near term, but they influence ore specifications, capital allocation and the premium attached to products that perform efficiently in lower-carbon steel routes.
Market Drivers
Steel Production Remains the Core Demand Base
Steelmaking accounts for almost all iron ore consumption, making global crude and finished steel demand the primary market driver. Worldsteel expects finished-steel demand to stabilize in 2026 before stronger growth in 2027, with demand outside China becoming more important. Infrastructure, transport, machinery, energy systems and urban construction ultimately support iron ore demand through steel production, but these downstream industries should not be counted as separate iron ore end markets because they consume steel rather than ore directly.
Developing-Market Infrastructure Supports Volume Growth
Infrastructure expansion in India, Southeast Asia, Africa and parts of the Middle East supports long-term steel demand even as Chinese property-related demand matures. India is the strongest large-market example, while Vietnam and several African economies are also increasing steel consumption. This geographic diversification supports modest global iron ore volume growth and reduces dependence on a single end-market trajectory, although China remains the largest determinant of seaborne price formation.
High-Grade and Pellet Feed Demand Supports Product Premiums
A market with modest volume growth can still create value through product mix. Steel mills under emissions pressure increasingly favor high-grade fines, lump and pellets that reduce coke consumption and slag volume. Direct-reduction expansion raises the importance of DR-grade pellet feed and concentrate. Producers such as Vale, Kumba, LKAB and Champion Iron are positioned to benefit where their ore quality or beneficiation systems allow them to capture a premium over standard 62% Fe fines.
Market Restraints
Rising Supply and Softer Chinese Demand Limit Price-Led Market Growth
The principal constraint is the combination of additional supply and subdued growth in the world's largest consuming market. The World Bank expects iron ore prices to soften as new production from Africa, Brazil and Australia enters the market. China's finished-steel demand is forecast to decline in 2026 and remain broadly flat in 2027, reducing the likelihood of a sustained demand-driven price spike. Higher production therefore does not translate directly into higher market value, and producers must rely increasingly on cost control, high-grade premiums and operational productivity.
Global Iron Ore Mining Market Segment Analysis
By Product Type
Fines
Fines remain the largest product segment and are estimated at approximately USD 132 billion in 2026. Standard fines dominate seaborne trade because they can be blended and sintered by integrated steelmakers and are produced at enormous scale in Australia and Brazil. Lump ore carries application-specific premiums because it can be charged directly into blast furnaces, while pellets and concentrates command higher value per tonne where beneficiation and pelletizing create superior iron content or lower impurity levels. DR-quality concentrates and pellets are expected to grow faster than standard fines from a smaller base.
By Grade
62% to 65% Fe
Ore in the 62% to 65% Fe range remains the commercial center of the seaborne market because the 62% benchmark is widely used for pricing and many major Australian and Brazilian products trade around this reference. Lower-grade material competes primarily on cost and blending value, while above-65% Fe products are gaining strategic importance for lower-emission steelmaking. Premiums for high-grade ore vary with steel margins, coke costs, environmental restrictions and pellet demand rather than moving uniformly with the benchmark.
By Steelmaking Route
Blast Furnace
Blast-furnace steelmaking remains the largest iron ore consumption route in 2026 because China, Japan, South Korea, India and Europe continue to operate large integrated steel fleets. The route consumes fines through sinter, lump ore and blast-furnace pellets. Direct-reduction iron represents the faster-growing route as new gas- and hydrogen-based projects are developed, but its share of global iron ore demand remains much smaller. The shift toward DRI increases demand for high-grade pellet feed rather than reducing aggregate iron ore use.
By Geography
Asia Pacific
Asia Pacific is estimated to generate approximately USD 125 billion of iron ore mining revenue in 2026, led by Australia, China and India. Australia remains the largest global producer and exporter, while India and China have large domestic mining industries supplying their steel sectors.
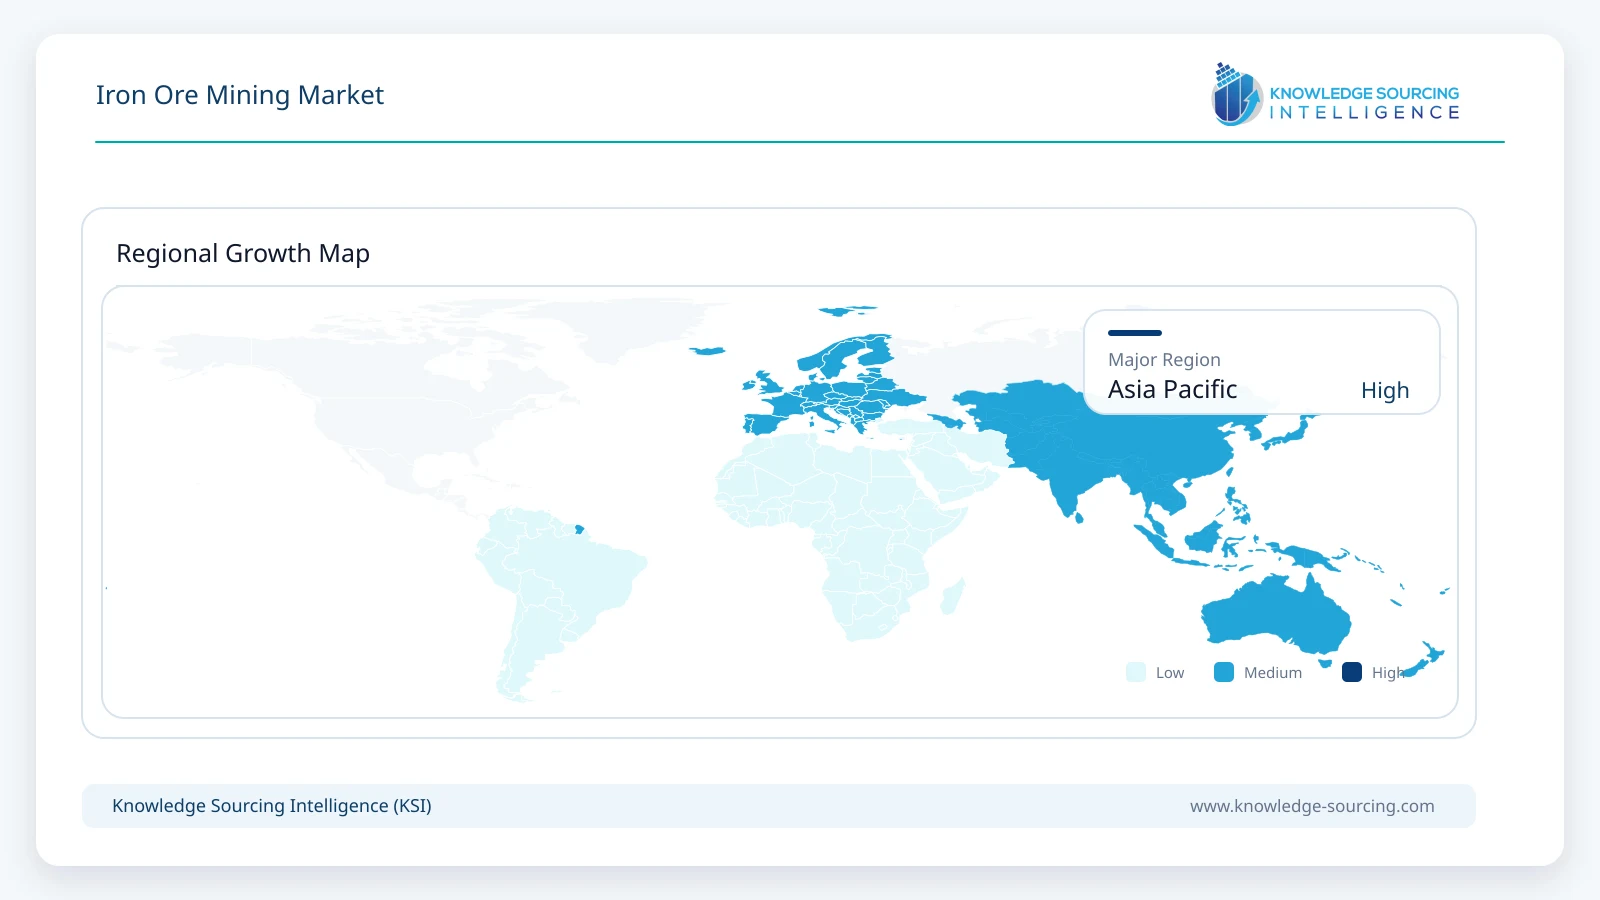
South America is the second major production region because of Brazil's scale, led by Vale and CSN Mineração. Europe is smaller in tonnage but strategically important in high-grade magnetite and pellet supply through LKAB and other producers.
Competitive Environment
The competitive landscape is highly concentrated at the top but includes a broad second tier of national and regional miners. Rio Tinto, BHP, Vale and Fortescue dominate the global seaborne market through large low-cost operations in Australia and Brazil. Anglo American's Kumba Iron Ore supplies premium South African ore, while LKAB specializes in high-grade magnetite pellets and fines in Europe. NMDC is India's largest state-backed iron ore miner and is pursuing substantial capacity expansion. Cleveland-Cliffs, ArcelorMittal Mining, Champion Iron, CSN Mineração, CITIC Pacific Mining, Mineral Resources, Ferrexpo, Metalloinvest, SNIM, CAP Minería, Ansteel Mining and Shougang Hierro Perú represent additional meaningful producers across pellets, concentrates, fines and lump.
Company positioning is increasingly influenced by ore quality, logistics control, mine cost, growth projects and decarbonization pathways. Rio Tinto is ramping Simandou while maintaining Pilbara sales above 320 million tonnes annually. BHP continues to expand Western Australia Iron Ore infrastructure toward more than 305 million tonnes per year over the medium term. Fortescue shipped more than 200 million tonnes in FY2026 for the first time, while Vale reported its highest second-quarter iron ore production since 2018. These scale advantages make the largest suppliers difficult to displace, but high-grade specialists retain strong pricing power in decarbonization-sensitive steel markets.
Recent Developments
August 2026: Fortescue produced first hot metal at its Christmas Creek Green Metal Project, advancing lower-emission ironmaking using Pilbara ore.
August 2026: BHP reported record FY2026 iron ore production and shipments at Western Australia Iron Ore.
July 2026: Rio Tinto reported first high-grade Simandou sales and maintained 2026 Simandou sales guidance of 5-10 million tonnes.
July 2026: Vale reported 84.3 million tonnes of Q2 iron ore production, its highest second-quarter output since 2018.
July 2026: Kumba reported an average realized export price of USD 90/wmt, 8% above the 62% Fe FOB-equivalent benchmark.
June 2026: Fortescue surpassed 200 million tonnes of iron ore shipments in a single financial year for the first time.
Global Iron Ore Mining Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 220.0 billion |
| Total Market Size in 2031 | USD 230.0 billion |
| Forecast Unit | Billion |
| Growth Rate | 0.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Grade, Steelmaking Route, Geography |
| Companies |
|
Market Segmentation
By Product Type
Fines
Lump Ore
Pellets
Concentrates
By Grade
Below 62% Fe
62% to 65% Fe
Above 65% Fe
By Steelmaking Route
Blast Furnace
Direct Reduction
Other Uses
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Chile
Peru
Others
Europe
Sweden
Russia
Ukraine
Others
Middle East & Africa
South Africa
Mauritania
Iran
Guinea
Others
Asia Pacific
Australia
China
India
Kazakhstan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Steel Production Remains the Core Demand Base
3.1.2. Developing-Market Infrastructure Supports Volume Growth
3.1.3. High-Grade and Pellet Feed Demand Supports Product Premiums
3.2. Market Restraints
3.2.1. Rising Supply and Softer Chinese Demand Limit Price-Led Market Growth
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Beneficiation and Ore Upgrading
4.2. Pelletizing and Direct-Reduction-Grade Feed
4.3. Autonomous Haulage and Mine Automation
4.4. Electrified Mining Equipment and Renewable Mine Power
4.5. Tailings Management and Water Recovery
4.6. Digital Orebody Modeling and Grade Control
5. GLOBAL IRON ORE MINING MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Fines
5.3. Lump Ore
5.4. Pellets
5.5. Concentrates
6. GLOBAL IRON ORE MINING MARKET BY GRADE
6.1. Introduction
6.2. Below 62% Fe
6.3. 62% to 65% Fe
6.4. Above 65% Fe
7. GLOBAL IRON ORE MINING MARKET BY STEELMAKING ROUTE
7.1. Introduction
7.2. Blast Furnace
7.3. Direct Reduction
7.4. Other Uses
8. GLOBAL IRON ORE MINING MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Chile
8.3.3. Peru
8.3.4. Others
8.4. Europe
8.4.1. Sweden
8.4.2. Russia
8.4.3. Ukraine
8.4.4. Others
8.5. Middle East & Africa
8.5.1. South Africa
8.5.2. Mauritania
8.5.3. Iran
8.5.4. Guinea
8.5.5. Others
8.6. Asia Pacific
8.6.1. Australia
8.6.2. China
8.6.3. India
8.6.4. Kazakhstan
8.6.5. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Producers and Strategy Analysis
9.2. Production Cost and Grade Positioning
9.3. Growth Projects and Logistics Infrastructure
9.4. High-Grade Ore and Decarbonization Strategy
9.5. Competitive Dashboard
10. COMPANY PROFILES
10.1. Rio Tinto Group
10.2. BHP Group Limited
10.3. Vale S.A.
10.4. Fortescue Ltd.
10.5. Anglo American plc / Kumba Iron Ore Limited
10.6. LKAB
10.7. NMDC Limited
10.8. Cleveland-Cliffs Inc.
10.9. ArcelorMittal Mining
10.10. Champion Iron Limited
10.11. CSN Mineração S.A.
10.12. CITIC Pacific Mining Management Pty Ltd.
10.13. Mineral Resources Limited
10.14. Ferrexpo plc
10.15. Metalloinvest Management Company LLC
10.16. Société Nationale Industrielle et Minière (SNIM)
10.17. CAP S.A. / Compañía Minera del Pacífico
10.18. Ansteel Mining Group
10.19. Shougang Hierro Perú S.A.A.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











