
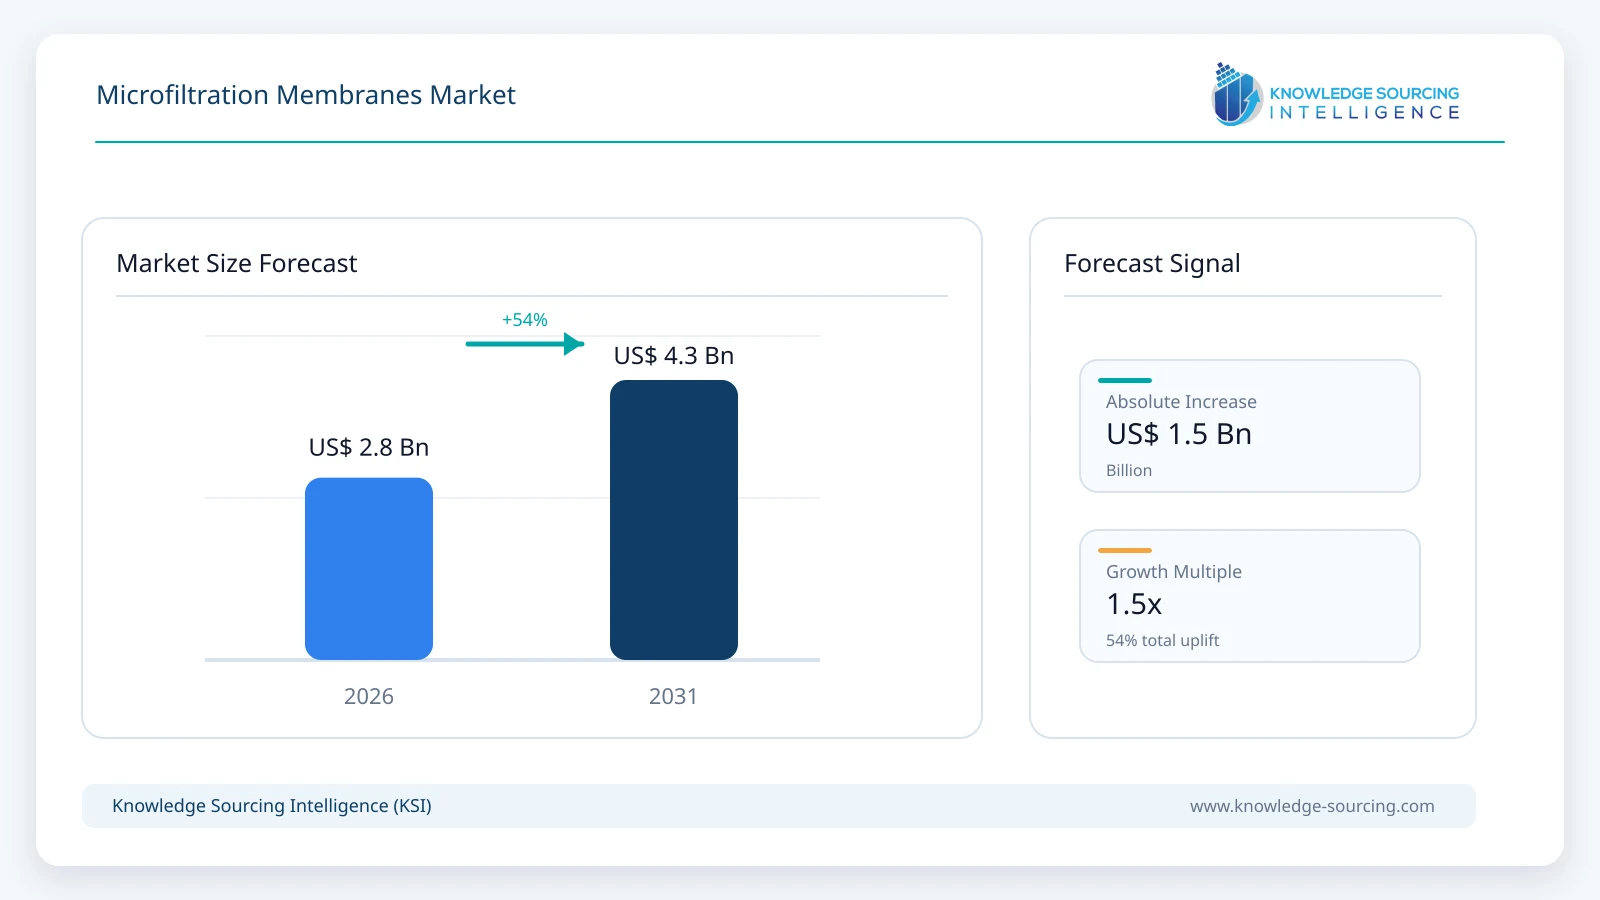
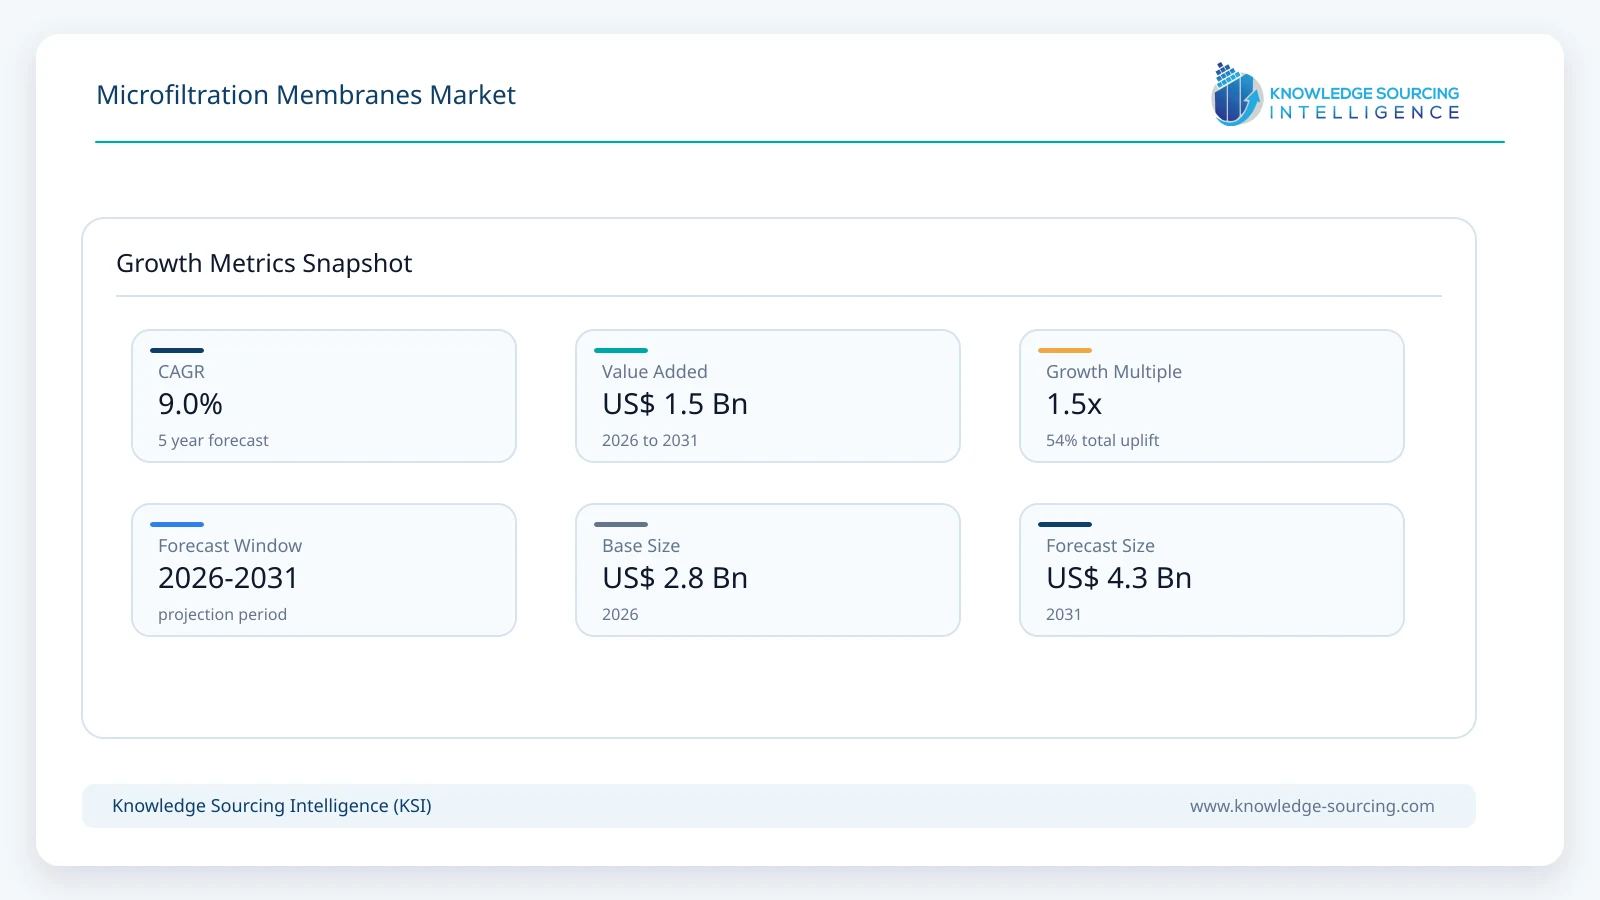
The microfiltration membranes market is forecast to grow at a CAGR of approximately 9.0%, reaching USD 4.3 billion in 2031 from USD 2.8 billion in 2026.
Highlights:
- 1Polymeric membranes account for approximately 84% of market value in 2026, with PVDF/PTFE and PES/polysulfone representing the largest material groups.
- 2Cross-flow and tangential-flow configurations account for approximately 53% of market value in 2026, supported by food processing, cell harvesting, wastewater and higher-solids applications.
- 3Water and wastewater treatment accounts for approximately 31% of market demand in 2026, narrowly ahead of pharmaceutical and biotechnology applications.
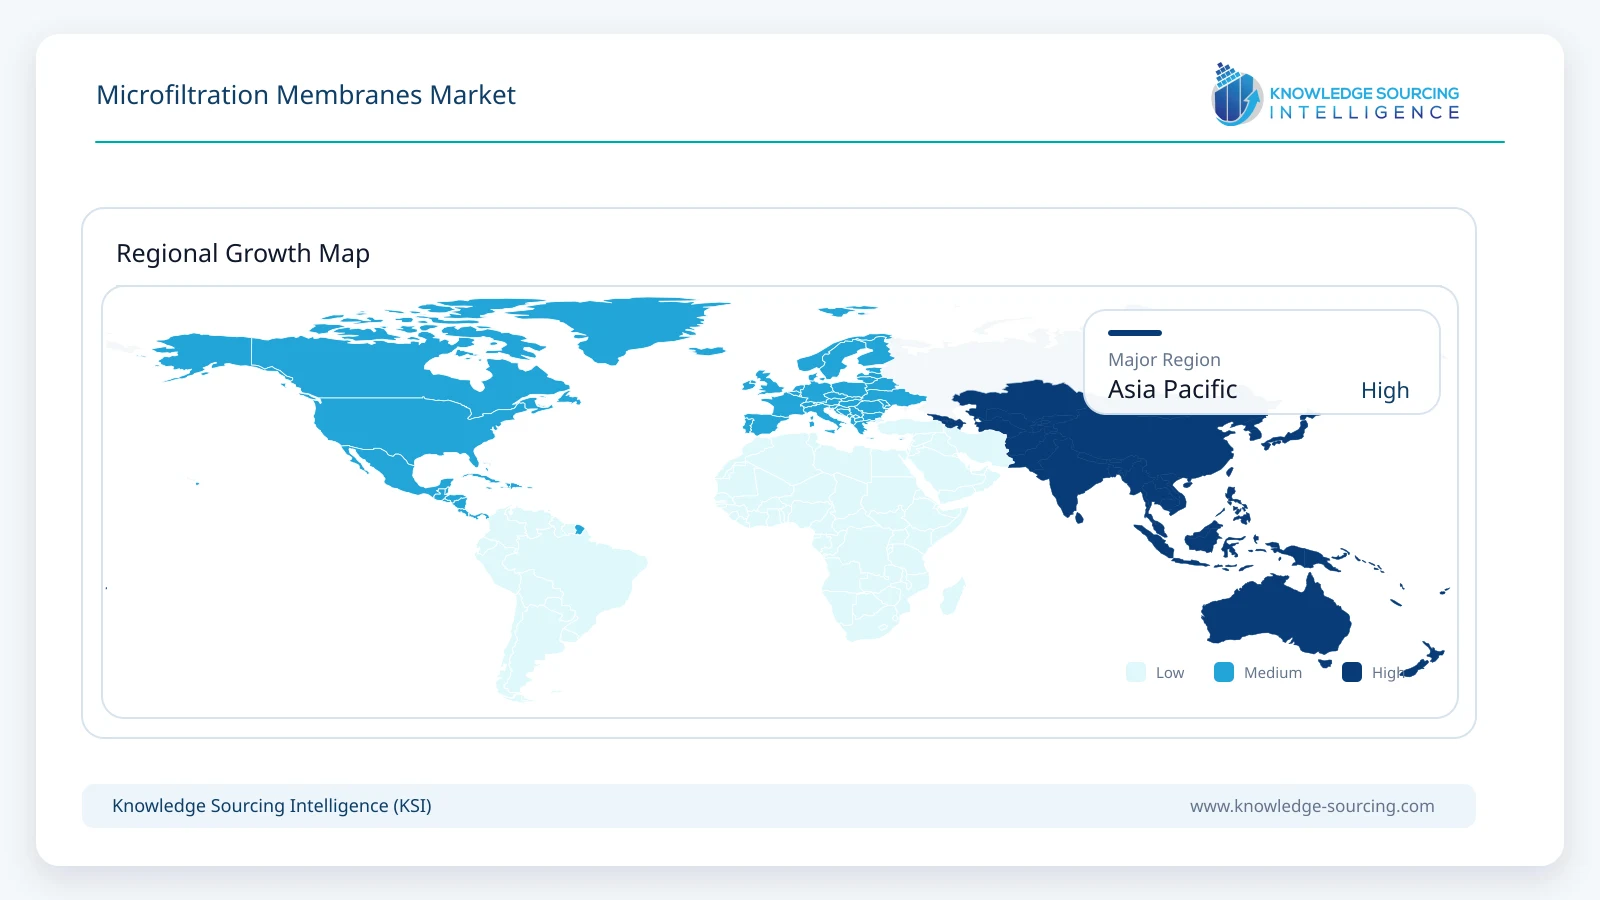
- 4Asia Pacific accounts for approximately 36% of global market value in 2026, supported by water infrastructure, industrial processing and food manufacturing.
- 5Ceramic membranes and PFAS-free polymer formulations are expected to grow faster than the overall market through 2031, although from smaller installed bases.
- 6The market is forecast to expand from USD 2.8 billion in 2026 to USD 4.3 billion in 2031, representing approximately 9.0% CAGR.
Market Overview
Microfiltration is a pressure-driven membrane separation process generally used to retain particles and microorganisms in the approximately 0.1-10 µm range. Sartorius defines microfiltration as retaining contaminants between 0.1 µm and 10 µm, while Pentair classifies its microfiltration portfolio in the approximately 0.1-1 µm range. Typical applications include bacterial removal, cell clarification, suspended-solids separation, dairy fractionation, beverage clarification, membrane-bioreactor treatment and pharmaceutical bioburden control.
The commercial scope includes flat-sheet, hollow-fiber, tubular, cartridge, capsule and other membrane formats where the separating medium itself operates in the microfiltration range. Complete wastewater-treatment plants, pumps, housings, skids and engineering revenue are excluded unless directly attributable to the membrane module. Ultrafiltration, nanofiltration and reverse-osmosis products are also excluded even where the same supplier manufactures them.
This boundary produces a considerably smaller and more internally consistent market than a model that counts complete filtration systems. Major suppliers illustrate the fragmented nature of the value pool. Pentair sells dedicated X-Flow microfiltration products for dairy, beer, wine, juice and protein separation; Alfa Laval produces microfiltration flat-sheet membranes from approximately 0.1 to 0.5 µm for food, biotech and pharmaceutical processing; Sartorius supplies 0.1, 0.2 and 0.45 µm hollow-fiber and sterilizing-grade membranes; Merck supplies Durapore-based microfiltration modules and 0.2 µm sterilizing filters; and Kubota uses 0.2 µm microporous flat-sheet membranes in its MBR systems.
Market Trends
• PFAS Regulation Is Beginning to Change Membrane-Material Selection
Fluorinated polymers such as PVDF and PTFE have historically been important because of their chemical resistance and filtration performance. Regulatory scrutiny of PFAS is now encouraging suppliers to develop alternative materials where technically feasible.
Pentair X-Flow announced in May 2026 that it is preparing to transition its tubular membrane portfolio from PVDF to polyethersulfone (PES), using a PFAS-free polymer while maintaining retrofit compatibility with installed systems. The new membranes will incorporate Pentair’s Helix flux-enhancing technology.
Sartorius is pursuing a similar direction in bioprocess filtration and highlights its Sartopore Evo PES membrane filters as part of its response to proposed PFAS restrictions. The trend does not imply rapid elimination of fluoropolymers across every application, but it increases R&D spending and supports faster growth for PES, polysulfone, ceramic and other alternatives.
• Biopharmaceutical Manufacturing Is Increasing Demand for High-Value Microfiltration
Biopharma microfiltration serves several stages, including cell harvesting, clarification, bioburden reduction, microbial quality control and final sterile filtration. These applications have significantly higher value per square metre than many municipal water applications because membranes must meet strict validation, extractables, sterilization, and regulatory requirements.
Merck’s Prostak modules use microporous PVDF membranes for tangential-flow clarification and are available from laboratory through production scales. Sartorius offers reusable hollow-fiber microfiltration modules with 0.1, 0.2 and 0.45 µm pore sizes and filtration areas extending to approximately 15 m².
The continuing expansion of biologics, vaccines and advanced therapies therefore increases membrane demand even when batch volumes are smaller than conventional pharmaceutical production because consumable intensity and specification requirements are higher.
• Dairy and Beverage Processing Is Moving Away From Conventional Filtration Media
Microfiltration is increasingly replacing diatomaceous-earth and other conventional clarification technologies in beer, wine and beverages and is being used for selective dairy-protein fractionation.
Pentair’s X-Flow R100 and R120 systems use hollow-fiber microfiltration membranes with 0.2-0.8 µm pores for wine, juice, milk, vinegar and beer. The company states that beer membrane filtration can replace conventional kieselguhr-based filtration. Its P170A product is designed for separation of milk and plant proteins.
Alfa Laval also supplies dedicated microfiltration membranes for food and dairy processing and states that its membrane service lives can exceed five years under suitable operating conditions.
• Water Reuse Is Expanding the Installed Base of Microporous Membranes
Membrane bioreactors use microfiltration or ultrafiltration membranes to replace secondary clarification and produce high-quality treated water. Kubota’s submerged membrane system uses an average 0.2 µm pore size, blocking solids and E. coli and allowing treated water to be reused for applications such as irrigation and toilet flushing.
Kubota is also expanding its decentralized water-reuse activities in North America. In 2026, the company described membrane bioreactors and onsite reuse systems as part of its U.S. decentralized water infrastructure strategy.
Water reuse therefore creates both new membrane installations and replacement demand from the expanding installed base.
Segment Analysis
• By Material: Polymeric Membranes
Polymeric membranes account for approximately 84% of global market value in 2026. The segment includes PVDF, PTFE, PES, polysulfone, cellulose-based membranes, nylon and related polymers.
PVDF and other fluorinated polymers remain important where chemical resistance, durability and hydrophobic characteristics are required, while PES and polysulfone are increasingly used in food, pharmaceutical and industrial applications. Pentair identifies polysulfone, PES, polyethylene and polypropylene among the commonly used membrane polymers across filtration processes.
Ceramic membranes represent a smaller value pool but offer high-temperature tolerance, chemical resistance and longer operating life. Their higher initial cost limits penetration in lower-value applications, while strong durability makes them attractive in harsh industrial and food-processing environments.
• By Filtration Mode: Cross Flow
Cross-flow and tangential-flow configurations account for approximately 53% of market value in 2026. In cross-flow systems, feed travels parallel to the membrane surface, reducing accumulation of retained material and allowing filtration of higher-solids streams.
The configuration is important in dairy fractionation, beverage clarification, biotechnology harvesting and industrial wastewater treatment. Merck’s Prostak modules and Sartorius hollow-fiber microfiltration systems are examples of tangential-flow systems used in pharmaceutical and biotechnology processing.
Direct-flow filtration remains commercially important for sterile filtration, microbial testing, venting and lower-solids applications. Sartorius’ 0.2 and 0.45 µm single-use filtration units and Merck’s sterilizing-grade filters illustrate the high-value direct-flow portion of the market.
• By Application: Water and Wastewater Treatment
Water and wastewater treatment accounts for approximately 31% of market value in 2026, making it the largest individual application group. Demand includes membrane bioreactors, tertiary filtration, wastewater reuse and pretreatment.
The segment’s value is supported by substantial membrane area installed in municipal and industrial systems, although revenue per square metre is generally lower than in biopharmaceutical applications. Kubota’s 0.2 µm MBR systems demonstrate direct use of microfiltration membranes in wastewater treatment and water reuse.
Pharmaceutical and biotechnology applications represent the second-largest value pool and carry higher average selling prices. Food and beverage processing follows, supported by dairy fractionation, beer and wine clarification and protein processing.
Market Drivers
• Water Scarcity and Wastewater Reuse Increase Membrane Deployment
Municipalities and industrial facilities increasingly need to recover water rather than discharge it after one use. Membrane filtration provides a physical barrier against suspended matter and microorganisms and can serve either as a finished treatment step or pretreatment for downstream RO and other processes.
Microfiltration’s comparatively low operating pressure makes it suitable where dissolved-salt removal is unnecessary. In MBR systems it can replace conventional secondary clarification, allowing treatment plants to reduce footprint while producing water suitable for reuse.
• Biopharmaceutical Production Requires Repeated Filtration Steps
Modern biopharmaceutical processes contain multiple filtration stages from cell harvesting through final sterile filtration. Each batch can use multiple disposable cartridges, capsules or membrane modules, creating recurring consumables demand rather than only capital-equipment demand.
Sartorius reported EUR 3.54 billion in group sales in 2025 across its broader bioprocess and laboratory portfolio. While only a fraction is attributable to microfiltration, the scale of its business and dedicated filtration range illustrates the size of the biopharma consumables ecosystem supporting membrane demand.
• Membrane Processing Can Reduce Energy and Consumable Use
Microfiltration can replace filter aids, centrifugation or other separation steps in selected applications. Pentair positions beverage microfiltration as an alternative to diatomaceous-earth filtration, while Alfa Laval notes that microfiltration operates at relatively low pressure and can reduce reliance on disposable cartridges in process applications.
The economic benefit is therefore determined not only by membrane price but by labor, water, waste disposal, cleaning and product-recovery economics.
Market Restraints
• Fouling Reduces Flux and Membrane Life
Microfiltration membranes are exposed directly to suspended solids, cells, proteins, oils and biological material. These contaminants can accumulate on or within the membrane and reduce permeate flux.
Cross-flow operation, backwashing, chemical cleaning and surface modification can limit fouling but increase equipment and operating complexity. Applications with highly variable feed composition may therefore continue using centrifugation, depth filtration or hybrid separation systems.
• Adjacent Filtration Technologies Compete With Microfiltration
The boundary between microfiltration and ultrafiltration is application-dependent. Some water-treatment suppliers increasingly use UF membranes to provide virus removal in addition to bacteria and suspended-solids control.
Pentair, for example, distinguishes its microfiltration products from UF products with tighter retention characteristics and markets UF extensively for potable water, wastewater and RO pretreatment.
Depth filtration, cartridge filters, centrifuges and conventional media also compete in selected pharmaceutical and food-processing applications, preventing microfiltration from capturing the entire separation market.
Regional Outlook
• Asia Pacific
Asia Pacific accounts for approximately 36% of global market value in 2026 and represents the largest region. China, Japan, India and Southeast Asia combine large water-treatment requirements with substantial food, beverage, pharmaceutical and industrial manufacturing bases.
Japan is an important technology center through companies including Kubota, Toray and Asahi Kasei, while China and India are expanding municipal and industrial wastewater infrastructure. Rising biopharmaceutical manufacturing in China, India, Singapore and South Korea adds a higher-value filtration layer to the region’s demand.
• North America
North America remains particularly important in pharmaceutical and biotechnology filtration and has high membrane expenditure per installation. Merck Millipore, Pall/Danaher and Sartorius maintain major bioprocess customer bases in the region, while municipal water reuse and industrial wastewater provide additional demand.
Europe is another major market because of its pharmaceutical, dairy and beverage processing industries and increasingly strict sustainability requirements. Pentair X-Flow and Alfa Laval have particularly strong European process-filtration positions.
Competitive Landscape
The market is fragmented across water-treatment specialists, process-separation companies and bioprocess filtration suppliers.
Pentair X-Flow offers dedicated hollow-fiber and tubular microfiltration membranes for food, beverage and industrial separation. Kubota is an established supplier of 0.2 µm flat-sheet membranes used in MBR wastewater systems. Alfa Laval supplies flat-sheet and process microfiltration membranes for dairy, food, biotechnology and pharmaceutical applications.
Merck KGaA / MilliporeSigma and Sartorius hold strong positions in pharmaceutical and biotechnology microfiltration, including clarification, sterile filtration and microbial quality-control applications. Pall Corporation / Danaher is another major bioprocess filtration participant.
The company universe should be updated from the previous report. General Electric should no longer be listed as a current standalone membrane supplier, and the old Koch Membrane Systems name is outdated. Current competitive analysis should instead focus on active filtration suppliers and their present ownership and product portfolios.
Recent Developments
May 2026: Pentair X-Flow announced plans to transition its tubular membrane portfolio from PVDF to PFAS-free PES while retaining compatibility with existing installations.
2026: Sartorius continued expanding its PES-based process filtration portfolio, including Sartopore Evo filters positioned in response to proposed PFAS restrictions.
July 2026: Kubota Corporation announced a U.S. pilot program in partnership with AirJoule to deploy atmospheric water-generation systems, integrating water-from-air technology with its existing MBR and onsite water-reuse capabilities into a broader decentralized water-circulation model.
2026: Pentair showcased its X-Flow membrane technologies for water and wastewater applications at IFAT Munich, alongside its Codeline pressure vessels and biogas upgrading solutions.
2025-2026: Alfa Laval continued expanding its membrane-processing offering across dairy, food and pharmaceutical applications, including microfiltration products manufactured at its membrane center.
Market Outlook
Water and wastewater remain the largest application by value, but pharmaceutical and biotechnology filtration is expected to increase its share because of higher consumable intensity and the continued expansion of biologics manufacturing. Food and beverage applications remain structurally important, particularly in dairy fractionation and beverage clarification.
Polymeric membranes remain dominant through 2031, but the material mix changes as PFAS concerns encourage development of PES and other non-fluorinated alternatives. Ceramic membranes expand more rapidly in harsh process environments where longer service life can justify their higher capital cost.
The market’s strongest opportunities therefore lie not simply in increasing membrane area, but in higher-value membranes offering reduced fouling, improved cleanability, regulatory compliance, lower extractables and longer operating life.
Microfiltration Membranes Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.8 billion |
| Total Market Size in 2031 | USD 4.3 billion |
| Forecast Unit | Billion |
| Growth Rate | 9.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Material, Filtration Mode, Application, Geography |
| Companies |
|
Market Segmentation
By Material
Fluorinated Polymers
PVDF
PTFE
PES and Polysulfone
Cellulosic and Nylon Membranes
Ceramic Membranes
Other Materials
By Filtration Mode
Cross Flow / Tangential Flow
Direct Flow / Dead-End Filtration
By Application
Water and Wastewater Treatment
Pharmaceutical and Biotechnology
Food and Beverage
Chemicals and Industrial Processing
Electronics and High-Purity Processing
Laboratory and Microbiological Testing
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Denmark
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Singapore
Indonesia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition and Revenue Boundary
1.3. Microfiltration versus Ultrafiltration Scope
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Research
2.4. Supplier Revenue and Product Analysis
2.5. Membrane Area and Replacement Modelling
2.6. Application-Level Demand Modelling
2.7. Data Triangulation and Validation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Microfiltration Membranes Market Size, 2026-2031
3.3. Material Outlook
3.4. Filtration Mode Outlook
3.5. Application Outlook
3.6. Regional Opportunity Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Water Reuse and Wastewater Recovery
4.1.2. Expansion of Biopharmaceutical Manufacturing
4.1.3. Replacement of Conventional Clarification Technologies
4.2. Market Restraints
4.2.1. Membrane Fouling and Cleaning Requirements
4.2.2. Competition From Ultrafiltration and Conventional Filtration
4.3. Market Opportunities
4.4. Porter’s Five Forces Analysis
4.5. Industry Value Chain Analysis
4.6. Membrane Replacement and Lifecycle Economics
4.7. Environmental and Regulatory Considerations
5. TECHNOLOGY OUTLOOK
5.1. Hollow-Fiber Microfiltration
5.2. Flat-Sheet Microfiltration
5.3. Tubular Membranes
5.4. Sterilizing-Grade Cartridge and Capsule Filters
5.5. Ceramic Microfiltration
5.6. PFAS-Free and Low-Fouling Membrane Materials
6. MICROFILTRATION MEMBRANES MARKET BY MATERIAL
6.1. Fluorinated Polymers
6.1.1. PVDF
6.1.2. PTFE
6.2. PES and Polysulfone
6.3. Cellulosic and Nylon Membranes
6.4. Ceramic Membranes
6.5. Other Materials
7. MICROFILTRATION MEMBRANES MARKET BY FILTRATION MODE
7.1. Cross Flow / Tangential Flow
7.2. Direct Flow / Dead-End Filtration
8. MICROFILTRATION MEMBRANES MARKET BY APPLICATION
8.1. Water and Wastewater Treatment
8.2. Pharmaceutical and Biotechnology
8.3. Food and Beverage
8.4. Chemicals and Industrial Processing
8.5. Electronics and High-Purity Processing
8.6. Laboratory and Microbiological Testing
8.7. Others
9. MICROFILTRATION MEMBRANES MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. Germany
9.3.2. United Kingdom
9.3.3. France
9.3.4. Italy
9.3.5. Spain
9.3.6. Denmark
9.3.7. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. South Africa
9.4.4. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. Japan
9.5.3. India
9.5.4. South Korea
9.5.5. Singapore
9.5.6. Indonesia
9.5.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Water and Wastewater Membrane Positioning
10.3. Bioprocess and Pharmaceutical Filtration Positioning
10.4. Food and Beverage Process-Membrane Positioning
10.5. Polymeric versus Ceramic Capabilities
10.6. PFAS-Free and Material-Innovation Strategies
10.7. Manufacturing Footprint and Supply Security
10.8. Partnerships, Investments and Product Development
10.9. Competitive Dashboard
11. COMPANY PROFILES
11.1. Pentair plc
11.2. Kubota Corporation
11.3. Alfa Laval AB
11.4. Sartorius AG
11.5. Merck KGaA
11.6. Danaher Corporation /
11.7. Toray Industries, Inc.
11.8. Asahi Kasei Corporation
11.9. MANN+HUMMEL
11.10. Kovalus Separation Solutions
12. APPENDIX
12.1. Market Definition and Scope
12.2. Membrane Pore-Size Definitions
12.3. Revenue Inclusion and Exclusion Criteria
12.4. Currency and Conversion Assumptions
12.5. Base Year and Forecast Period
12.6. Market Estimation Approach
12.7. Primary and Secondary Research Framework
12.8. Segment Reconciliation
12.9. Data Triangulation and Validation
Research Methodology
The microfiltration membranes market is estimated through a combination of supplier-level analysis, membrane-area modelling, replacement demand and end-use activity. The scope includes microfiltration membrane sheets, modules, cartridges and capsules with pore sizes generally between approximately 0.1 µm and 10 µm. Complete filtration systems, tanks, pumps, skids and engineering services are excluded except where their value is inseparable from the membrane module.
The market model separates microfiltration from ultrafiltration, nanofiltration and reverse osmosis. This distinction is necessary because several leading suppliers operate across all four technologies and company-level membrane revenue cannot be treated entirely as microfiltration revenue.
The 2026 estimate of USD 2.8 billion is triangulated using the attributable microfiltration portions of the portfolios of Pentair X-Flow, Kubota, Sartorius, Merck, Pall/Danaher, Alfa Laval and other suppliers; global membrane-market boundaries; pharmaceutical filtration consumables; water and wastewater installations; and food-processing membrane demand. The prior broader estimate is not retained because it cannot be reconciled cleanly without including adjacent membrane technologies or complete filtration systems.
Segment estimates are built separately. Polymeric membranes dominate installed membrane area and commercial value. Water and wastewater treatment is the largest individual application, while pharmaceuticals and biotechnology contribute disproportionately high value per membrane area. Asia Pacific leads regional demand because of its water infrastructure and industrial scale, while North America has a larger share of high-value bioprocess filtration.
Growth is not applied uniformly. Pharmaceutical and biotechnology filtration, ceramic membranes and PFAS-free polymer technologies grow faster than conventional water-treatment replacement demand. These paths reconcile to USD 4.3 billion in 2031, equivalent to approximately 9.0% CAGR.
Navigate
Trusted by the world's leading organizations











