
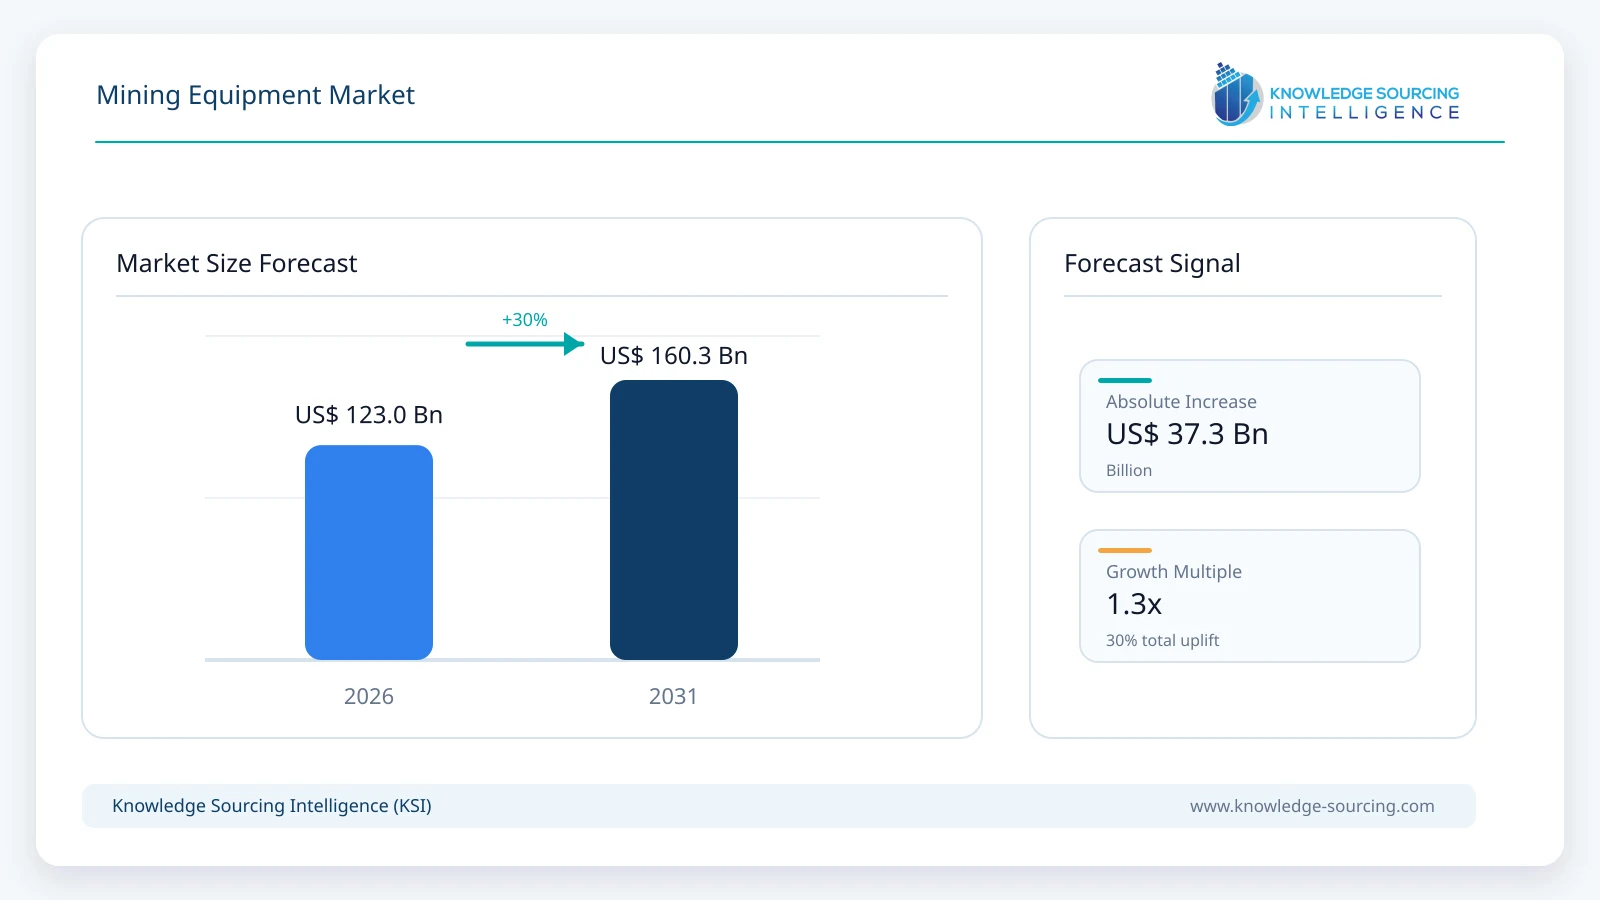
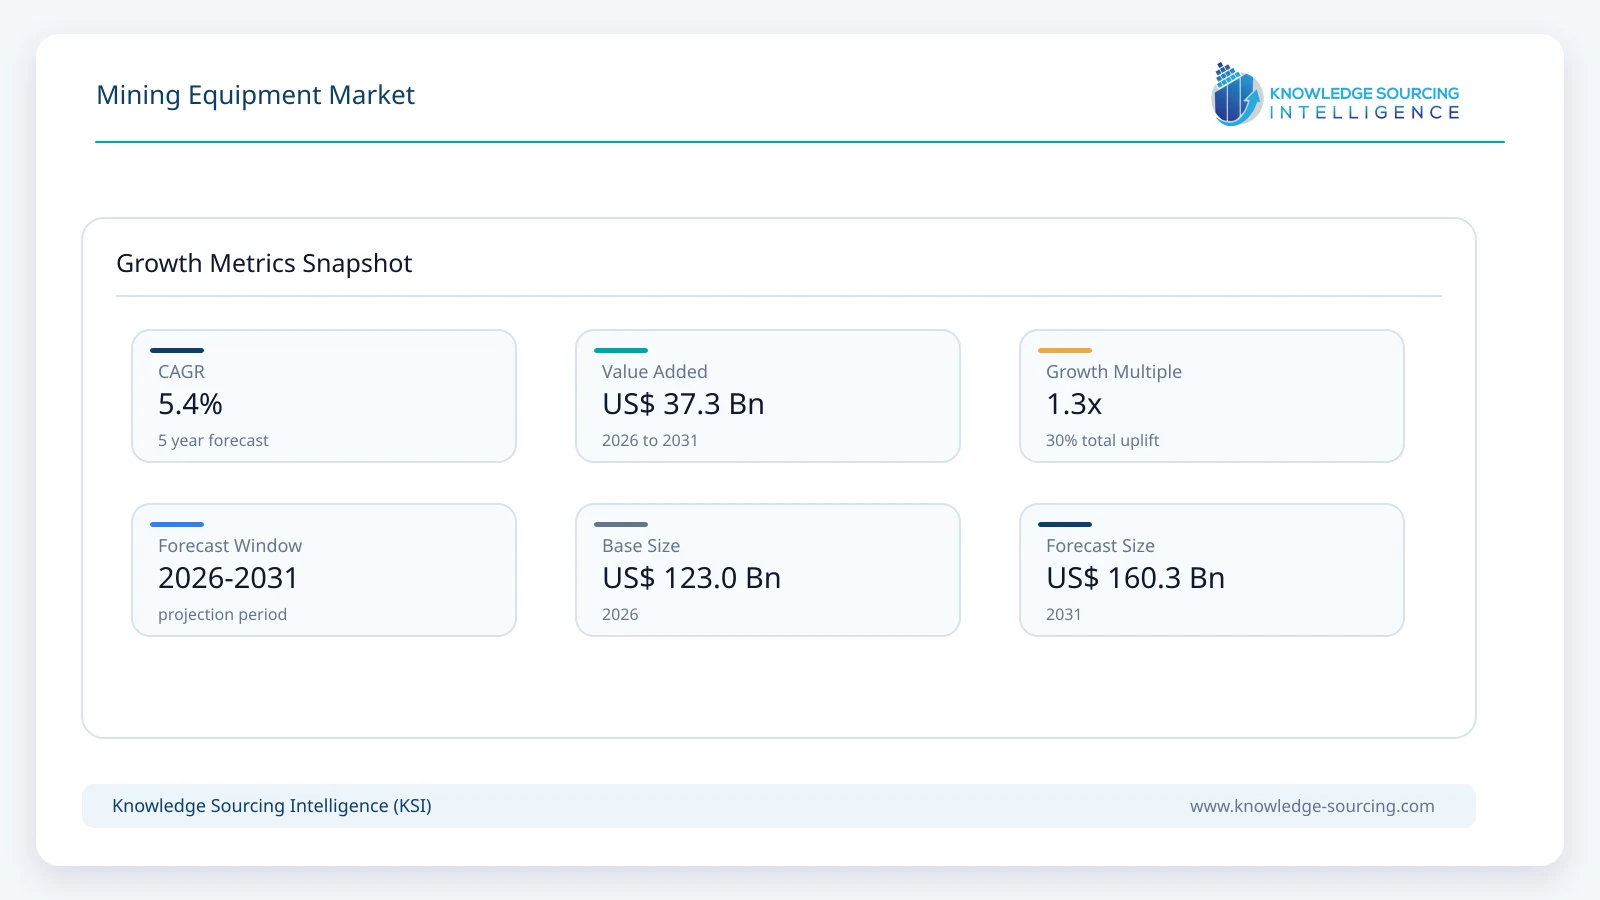
The global mining equipment market is projected to increase from USD 123.0 billion in 2026 to USD 160.3 billion in 2031, representing a CAGR of 5.4% across the forecast period.
Highlights:
- 1Metal mining contributes an estimated 55.6% of 2026 demand, led by copper and iron ore.
- 2Asia Pacific accounts for about 44.3% of 2026 revenue, supported by large-scale mining activity.
- 3Loading and haulage equipment remains the largest equipment class, representing about USD 42.6 billion in 2026.
- 4Fully autonomous equipment records the strongest technology growth as large mines standardize unmanned haulage.
- 5Battery-electric adoption is advancing fastest underground, where ventilation and heat reductions improve operating economics.
Mining equipment procurement is being supported by a broad combination of sustaining capital, fleet replacement, brownfield expansion and new project development. The demand profile is strongest where operators must move larger quantities of material to maintain output from lower-grade ore bodies or where new projects are being developed for copper, gold, iron ore, critical minerals and selected industrial minerals. The International Energy Agency (IEA) reported that copper-focused companies increased investment by 8% in 2025 even as total critical-mineral investment declined, reflecting stronger long-term conviction in copper than in several battery-material markets. The same outlook continues to show a structural supply gap for copper into the next decade, which supports continued spending on mine development, concentrators, haulage systems and associated equipment.
The market is also becoming more service- and software-intensive. Modern fleets increasingly combine the machine with fleet-management platforms, remote operations, collision avoidance, predictive maintenance and automation. This raises the strategic value of installed-base support and makes dealer reach, parts availability, software compatibility and lifecycle service important competitive factors alongside equipment price and payload. Epiroc reported that aftermarket activities accounted for 66% of its 2025 revenue mix, illustrating the economic importance of service in equipment-intensive mining operations. Metso similarly reported that aftermarket represented 60% of 2025 sales within its Minerals segment.
Selected Segment Estimates
Dimension | Selected Subsegment | 2026 Indicator | Forecast Interpretation |
Equipment Type | Loading & Haulage Equipment | USD 42.6 billion | Largest equipment class; replacement cycles remain tied to production intensity and fleet age. |
Mining Method | Surface Mining | 62.5% share | Large open-pit operations sustain demand for ultra-class haulage, shovels, drills and dozers. |
Automation Level | Fully Autonomous Equipment | 13.5% share | Fastest technology expansion as autonomy scales across haulage and selected drilling applications. |
Application | Metal Mining | 55.6% share | Largest application, supported by copper, iron ore, gold and other base-metal projects. |
Geography | Asia Pacific | 44.3% share | Largest regional market, led by China, Australia, India and Southeast Asian mining investment. |
Powertrain Trend | Battery-Electric Mobile Equipment | Rapidly expanding niche | Adoption concentrated in underground fleets where ventilation savings improve total cost economics. |
Market Dynamics
Critical-mineral and copper investment supports equipment demand
Copper is becoming one of the clearest equipment-demand anchors for the forecast period. The IEA's 2026 critical-minerals outlook indicates that copper-focused companies increased investment in 2025 even while capital spending across critical minerals declined overall. The longer-term supply picture remains constrained by declining ore grades, high project costs and long development timelines. For equipment suppliers, this creates demand through both new-mine development and brownfield debottlenecking. New projects require complete equipment fleets, while existing operations require additional haulage, drilling, crushing, grinding and materials-handling capacity to maintain or expand throughput. The effect is visible in supplier order books: Metso has continued to secure large concentrator and crushing packages for copper projects, including further equipment for Grupo Mexico's La Caridad operation in June 2026.
Fleet productivity and lower ore grades increase replacement intensity
Equipment replacement is increasingly justified by cost per tonne rather than by age alone. Large mines operate continuously and face rising pressure to maintain throughput as haul distances change, pits deepen and ore grades decline. This increases the value of higher-payload haul trucks, efficient loading systems, high-precision drilling and mineral-processing equipment with better energy and water performance. The effect is reinforced by the scale of modern equipment fleets, where a relatively small improvement in availability or cycle time can produce material annual savings. Caterpillar's 2025 results showed higher equipment sales to end users, while Epiroc reported 15% organic growth in equipment orders within its Equipment & Service business area. These indicators support a market in which mines continue to invest selectively in productivity-enhancing equipment even when commodity cycles are mixed.
Automation and electrification move into fleet-scale deployment
Automation is now established at industrial scale in surface haulage and is spreading across drilling, underground loading, fleet coordination and safety systems. Komatsu reached 1,000 commissioned autonomous ultra-class haul trucks in April 2026, while Caterpillar reported 827 autonomous haul trucks in operation during 2025. Electrification is progressing more selectively, with underground mines providing the strongest early economics because battery-electric equipment can reduce diesel use, heat generation and ventilation requirements. In April 2025, Epiroc secured a five-year SEK 2.2 billion contract to supply autonomous and electric surface drilling equipment to Fortescue, while Sandvik received a roughly SEK 750 million order for a predominantly battery-electric underground fleet for South32's Hermosa project. These orders show that electrification is moving beyond small pilots into multi-year fleet procurement.
Commodity cyclicality and project timing remain the principal restraints
Mining-equipment demand remains exposed to commodity prices and project sanctioning cycles. The IEA reported a 9% decline in critical-mineral investment during 2025, with particularly sharp reductions among lithium-focused companies. A weaker commodity can therefore reduce demand for new fleets even when long-term resource requirements remain favorable. Large equipment also has long useful lives, encouraging operators to extend rebuild cycles when capital budgets tighten. This makes aftermarket demand more stable than original equipment purchases but can produce uneven annual ordering for large machines and processing systems. Suppliers with broad commodity exposure, installed-base service networks and recurring parts revenue are consequently better positioned to absorb individual commodity downturns.
Infrastructure, charging and integration requirements slow zero-emission adoption
Battery-electric and autonomous fleets require more than replacement of the base machine. Mines may need charging or battery-swap infrastructure, grid upgrades, communications networks, fleet-control systems, operator training and redesigned maintenance procedures. These requirements are especially important at remote mines with constrained power supply or mixed fleets from multiple original equipment manufacturers. Battery-electric adoption is therefore likely to advance first where operating benefits are highest, particularly underground, and where mines have sufficient remaining life to justify infrastructure investment. Trolley assist, diesel-electric architectures and hybrid solutions are likely to coexist with full battery systems during the forecast period, especially in surface haulage where payload, duty cycle and charging requirements remain demanding.
Mining Equipment Market Segment Analysis
By Equipment Type
Loading and Haulage Equipment
Loading and haulage equipment is estimated at approximately USD 42.6 billion in 2026, making it the largest equipment class within the market. The segment includes large mining trucks, underground haul trucks, loaders and related production equipment used to move ore and waste through surface and underground operations. Its scale reflects both high unit values and intensive utilization. Growth through 2031 is supported by mine expansions, deeper pits, longer haul distances and replacement of older fleets with machines that support autonomous operation, electric drive systems and integrated fleet management. Ultra-class surface haulage remains concentrated among large global suppliers, while underground loading and haulage is more competitive and increasingly differentiated by battery-electric capability.
By Mining Method
Surface Mining
Surface mining accounts for an estimated 62.5% of 2026 market revenue. Open-pit iron ore, copper, gold, coal and industrial-mineral operations require some of the highest-value equipment in the market, including ultra-class haul trucks, electric rope and hydraulic shovels, rotary drills, dozers and large crushing systems. The segment also has the clearest commercial case for autonomous haulage because repetitive routes and controlled mine environments allow large fleets to be standardized. Surface equipment will remain the larger revenue pool through 2031, although underground mining is expected to record stronger adoption of battery-electric equipment because of ventilation and heat-management benefits.
By Automation Level
Fully Autonomous Equipment
Fully autonomous equipment is estimated to represent about 13.5% of the market in 2026, but it is expected to expand considerably faster than the overall market. Autonomous haulage is the most mature application, with Caterpillar and Komatsu each operating at large global scale, while drilling, remote loading and mixed-fleet autonomy are developing rapidly. Adoption is strongest at large mines where utilization, safety and repeatable haul cycles can support the systems integration required. The growth opportunity is not limited to new machines, as retrofit and OEM-agnostic automation systems allow mines to automate portions of existing fleets.
By Application
Metal Mining
Metal mining represents an estimated 55.6% of 2026 market revenue and remains the largest application category. Copper is especially important because electrification, grid expansion and renewable-energy investment are raising long-term demand while new mine supply remains difficult to develop. Iron ore continues to support large surface fleets and processing systems, while gold provides a broad mix of surface and underground demand. Metal-mining customers are also among the leading adopters of autonomous, digital and low-emission equipment because large, long-life operations can spread technology investment across substantial production volumes.
Technology and Demand Indicators
Indicator | Latest Development | Market Impact |
Caterpillar autonomy | 827 autonomous haul trucks in operation during 2025 | Shows surface autonomy is operating at fleet scale. |
Komatsu autonomy | 1,000th autonomous ultra-class haul truck commissioned in April 2026 | Confirms continued expansion of autonomous haulage across major mines. |
Epiroc automation | More than 3,900 automated machines by year-end 2025 | Indicates demand for OEM and mixed-fleet automation beyond haulage. |
Epiroc electrification | Electric drill, loader and truck fleet exceeded 600 units in 2025 | Demonstrates commercial scale of electric mining equipment. |
Sandvik BEV orders | Approx. SEK 750 million Hermosa order announced April 2025 | Shows battery-electric fleets are entering large greenfield underground projects. |
Asia Pacific Market Analysis
Asia Pacific is estimated to account for approximately 44.3% of global mining-equipment revenue in 2026, equivalent to about USD 54.5 billion. The region combines several distinct demand centers. China has the world's largest industrial and mining equipment manufacturing base and continues to invest in smart-mine automation across coal and metals.
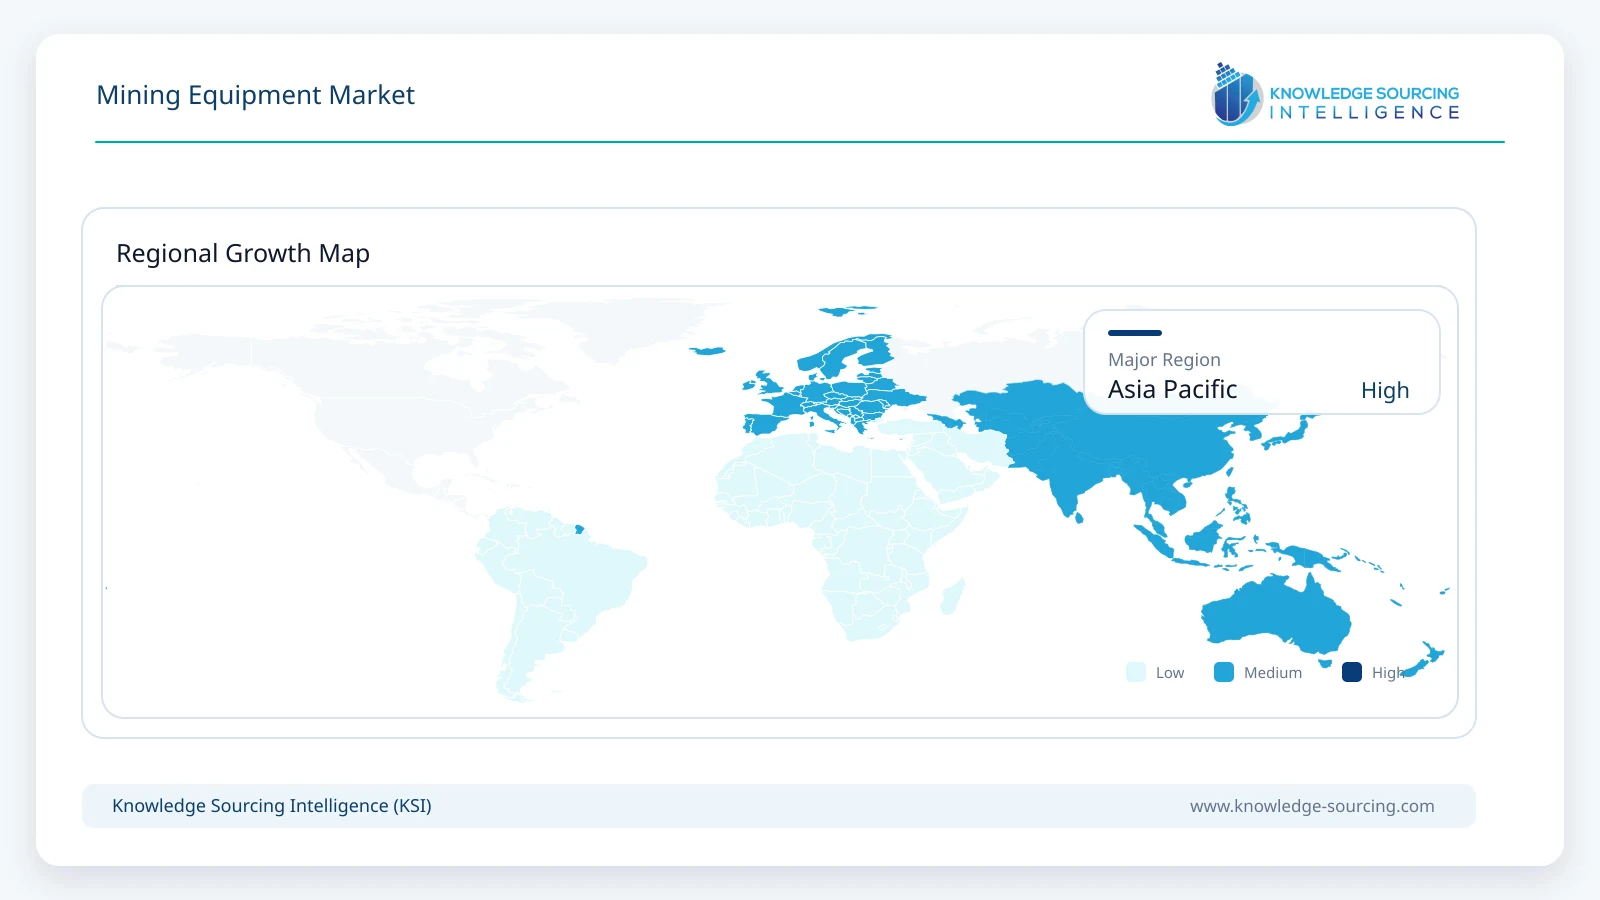
Australia remains one of the most valuable markets for large surface equipment because of the scale of its iron ore, coal, gold and base-metal operations and its rapid adoption of autonomous haulage. India supports demand through coal production, iron ore, limestone and growing underground mechanization, while Indonesia is a major equipment market for coal and nickel.
Australia is also a leading deployment market for next-generation equipment. Epiroc's five-year Fortescue contract covers roughly 50 autonomous and electric surface drill rigs, and Komatsu reported 500 Autonomous Haulage System trucks operating in Australia by September 2025. The region's large mines, high labor costs, remote operating environments and long mine lives create strong economics for autonomy and remote operations. At the same time, Chinese manufacturers are increasing their competitive presence in equipment categories where price, lead time and domestic supply are important. This combination of production scale, replacement demand and technology adoption is expected to keep Asia Pacific the largest regional market through 2031.
Competitive Landscape
Competition is concentrated by equipment category rather than across the entire market. Caterpillar and Komatsu hold strong positions in large surface mining fleets and autonomous haulage. Sandvik and Epiroc are especially strong in underground hard-rock equipment, drilling, automation and battery-electric systems. Metso and FLSmidth are major suppliers of mineral-processing systems, while Liebherr, Hitachi Construction Machinery, SANY, XCMG and other heavy-equipment manufacturers compete across selected surface categories. Competitive advantage increasingly depends on the installed base, dealer and service coverage, parts availability, digital integration and the ability to support fleet automation or electrification over the life of a mine.
· Caterpillar Inc.
· Komatsu Ltd.
· Sandvik AB
· Epiroc AB
· Liebherr Group
· Hitachi Construction Machinery Co., Ltd.
· Metso Corporation
· FLSmidth & Co. A/S
· The Weir Group PLC
· SANY Heavy Industry Co., Ltd.
· XCMG Group
· Zoomlion Heavy Industry Science & Technology Co., Ltd.
· Volvo Construction Equipment
· HD Hyundai Construction Equipment Co., Ltd.
· Normet Group Oy
· MacLean Engineering
· Gainwell Engineering Pvt. Ltd.
· J.H. Fletcher & Co.
Recent Developments
September 2026: Caterpillar and Luck Stone expanded autonomous hauling to two additional Virginia quarry operations after more than 3.5 million tons had been hauled autonomously at the Bull Run pilot site.
June 2026: Metso received an additional order valued at more than EUR 20 million for a crushing package at Grupo Mexico's La Caridad copper concentrator in Mexico.
April 2026: Komatsu commissioned its 1,000th autonomous ultra-class haul truck, a 930E-5AT deployed at Nevada Gold Mines in the United States.
April 2025: Sandvik announced an approximately SEK 750 million equipment order for South32's Hermosa project in Arizona, with most of the fleet consisting of battery-electric vehicles.
April 2025: Epiroc announced a five-year contract valued at approximately SEK 2.2 billion to supply Fortescue with fully autonomous and electric surface drilling equipment in Australia.
Mining Equipment Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 123.0 billion |
| Total Market Size in 2031 | USD 160.3 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Equipment Type, Mining Method, Automation Level, Mobile Equipment Powertrain, Application, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Equipment Type
Loading & Haulage Equipment
Drilling & Blasting Equipment
Crushing & Screening Equipment
Mineral Processing Equipment
Ground Support & Utility Equipment
Other Mining Equipment
By Mining Method
Surface Mining
Underground Mining
By Automation Level
Conventional / Manual Equipment
Semi-Autonomous and Remote-Controlled Equipment
Fully Autonomous Equipment
By Mobile Equipment Powertrain
Internal-Combustion Engine Equipment
Battery-Electric Equipment
Hybrid, Trolley-Assist and Other Electric-Drive Systems
By Application
Metal Mining
Coal Mining
Industrial and Other Minerals
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Chile
Peru
Others
Europe
Germany
Sweden
Finland
United Kingdom
Others
Middle East and Africa
South Africa
Saudi Arabia
Democratic Republic of the Congo
Others
Asia Pacific
China
Australia
India
Indonesia
Japan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Critical-mineral and copper investment
3.1.2. Fleet productivity and ore-grade pressure
3.1.3. Automation and electrification
3.2. Market Restraints
3.2.1. Commodity cyclicality and project timing
3.2.2. Infrastructure and integration requirements
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Regulatory and Safety Landscape
4. MINING EQUIPMENT MARKET BY EQUIPMENT TYPE
4.1. Loading & Haulage Equipment
4.2. Drilling & Blasting Equipment
4.3. Crushing & Screening Equipment
4.4. Mineral Processing Equipment
4.5. Ground Support & Utility Equipment
4.6. Other Mining Equipment
5. MINING EQUIPMENT MARKET BY MINING METHOD
5.1. Surface Mining
5.2. Underground Mining
6. MINING EQUIPMENT MARKET BY AUTOMATION LEVEL
6.1. Conventional / Manual Equipment
6.2. Semi-Autonomous and Remote-Controlled Equipment
6.3. Fully Autonomous Equipment
7. MINING EQUIPMENT MARKET BY MOBILE EQUIPMENT POWERTRAIN
7.1. Internal-Combustion Engine Equipment
7.2. Battery-Electric Equipment
7.3. Hybrid, Trolley-Assist and Other Electric-Drive Systems
8. MINING EQUIPMENT MARKET BY APPLICATION
8.1. Metal Mining
8.2. Coal Mining
8.3. Industrial and Other Minerals
9. MINING EQUIPMENT MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Chile
9.2.3. Peru
9.2.4. Others
9.3. Europe
9.3.1. Germany
9.3.2. Sweden
9.3.3. Finland
9.3.4. United Kingdom
9.3.5. Others
9.4. Middle East and Africa
9.4.1. South Africa
9.4.2. Saudi Arabia
9.4.3. Democratic Republic of the Congo
9.4.4. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. Australia
9.5.3. India
9.5.4. Indonesia
9.5.5. Japan
9.5.6. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Caterpillar Inc.
11.2. Komatsu Ltd.
11.3. Sandvik AB
11.4. Epiroc AB
11.5. Liebherr Group
11.6. Hitachi Construction Machinery Co., Ltd.
11.7. Metso Corporation
11.8. FLSmidth & Co. A/S
11.9. The Weir Group PLC
11.10. SANY Heavy Industry Co., Ltd.
11.11. XCMG Group
11.12. Zoomlion Heavy Industry Science & Technology Co., Ltd.
11.13. Volvo Construction Equipment
11.14. HD Hyundai Construction Equipment Co., Ltd.
11.15. Normet Group Oy
11.16. MacLean Engineering
11.17. Gainwell Engineering Pvt. Ltd.
11.18. J.H. Fletcher & Co.
12. RECENT DEVELOPMENTS
13. APPENDIX
13.1. Currency
13.2. Assumptions
13.3. Base and Forecast Years Timeline
13.4. Research Methodology
13.5. Abbreviations





Frequently asked questions
What is the projected market size for mining equipment by 2031?
The Mining Equipment Market is projected to reach $160.3 billion by 2031, growing at 5.4% CAGR.
Which region will dominate mining equipment revenue in 2026?
Asia Pacific accounts for 44.3% of 2026 revenue, leading globally.
What is the largest equipment class by value in 2026?
Loading and haulage equipment is largest, valued at $42.6 billion in 2026.
Which application segment drives the most mining equipment demand?
Metal mining is the largest application, contributing 55.6% of 2026 demand.
What technology records the strongest growth in mining equipment?
Fully autonomous equipment records the strongest technology growth.
What key trend is shaping the Mining Equipment Market?
The Mining Equipment Market is becoming more service- and software-intensive.
Cite this report
Knowledge Sourcing Intelligence. (Nov 2026). Mining Equipment Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/mining-equipment-market