
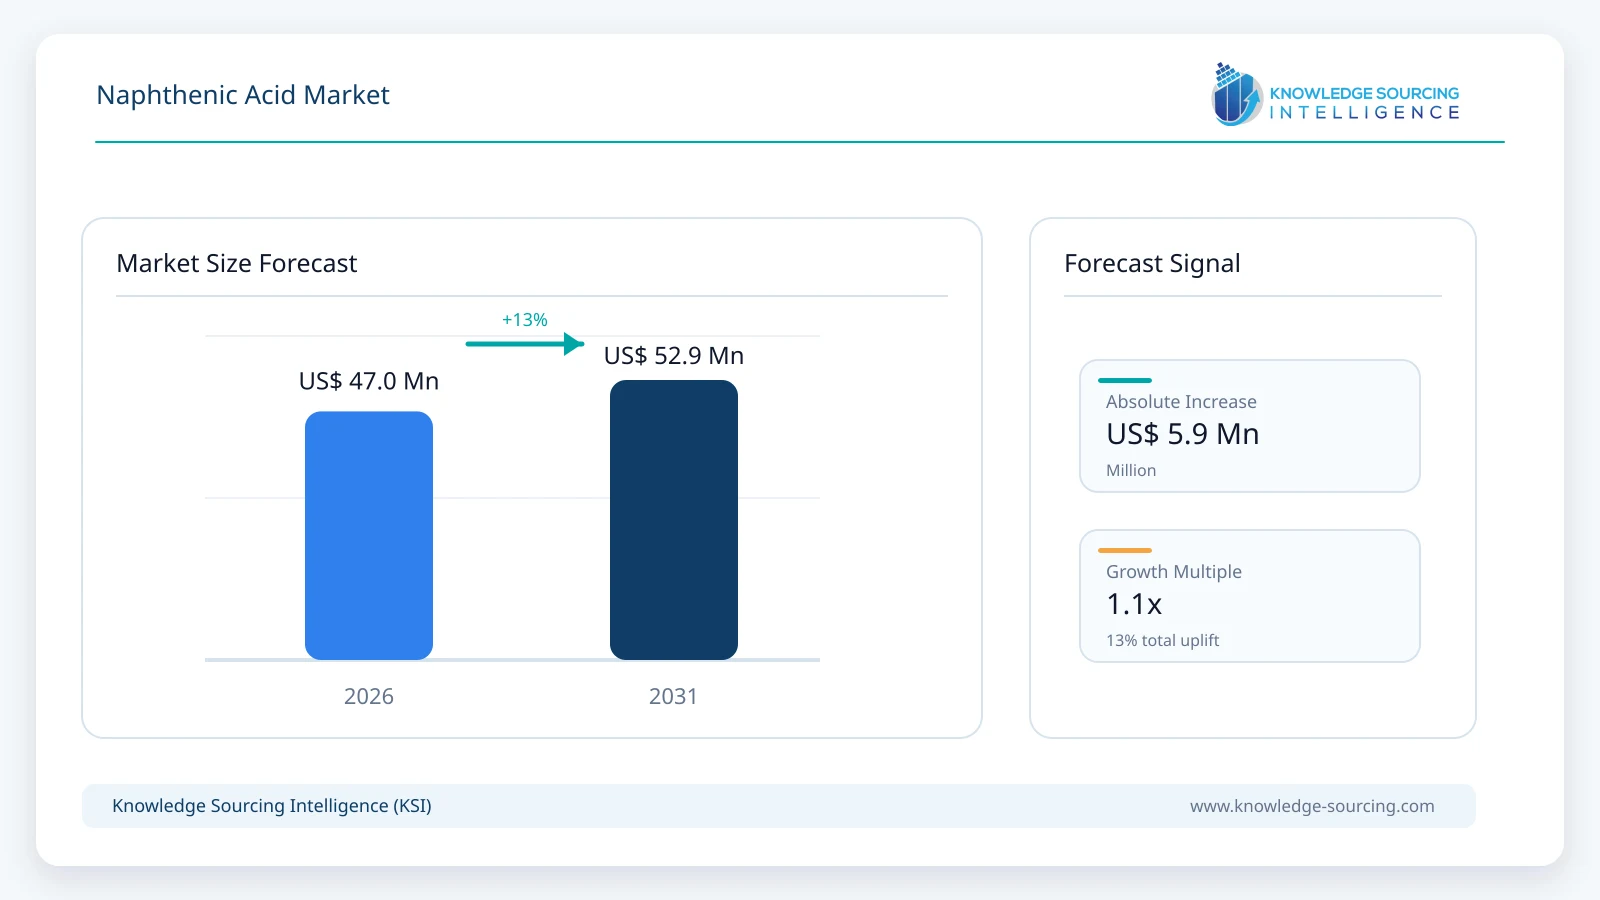
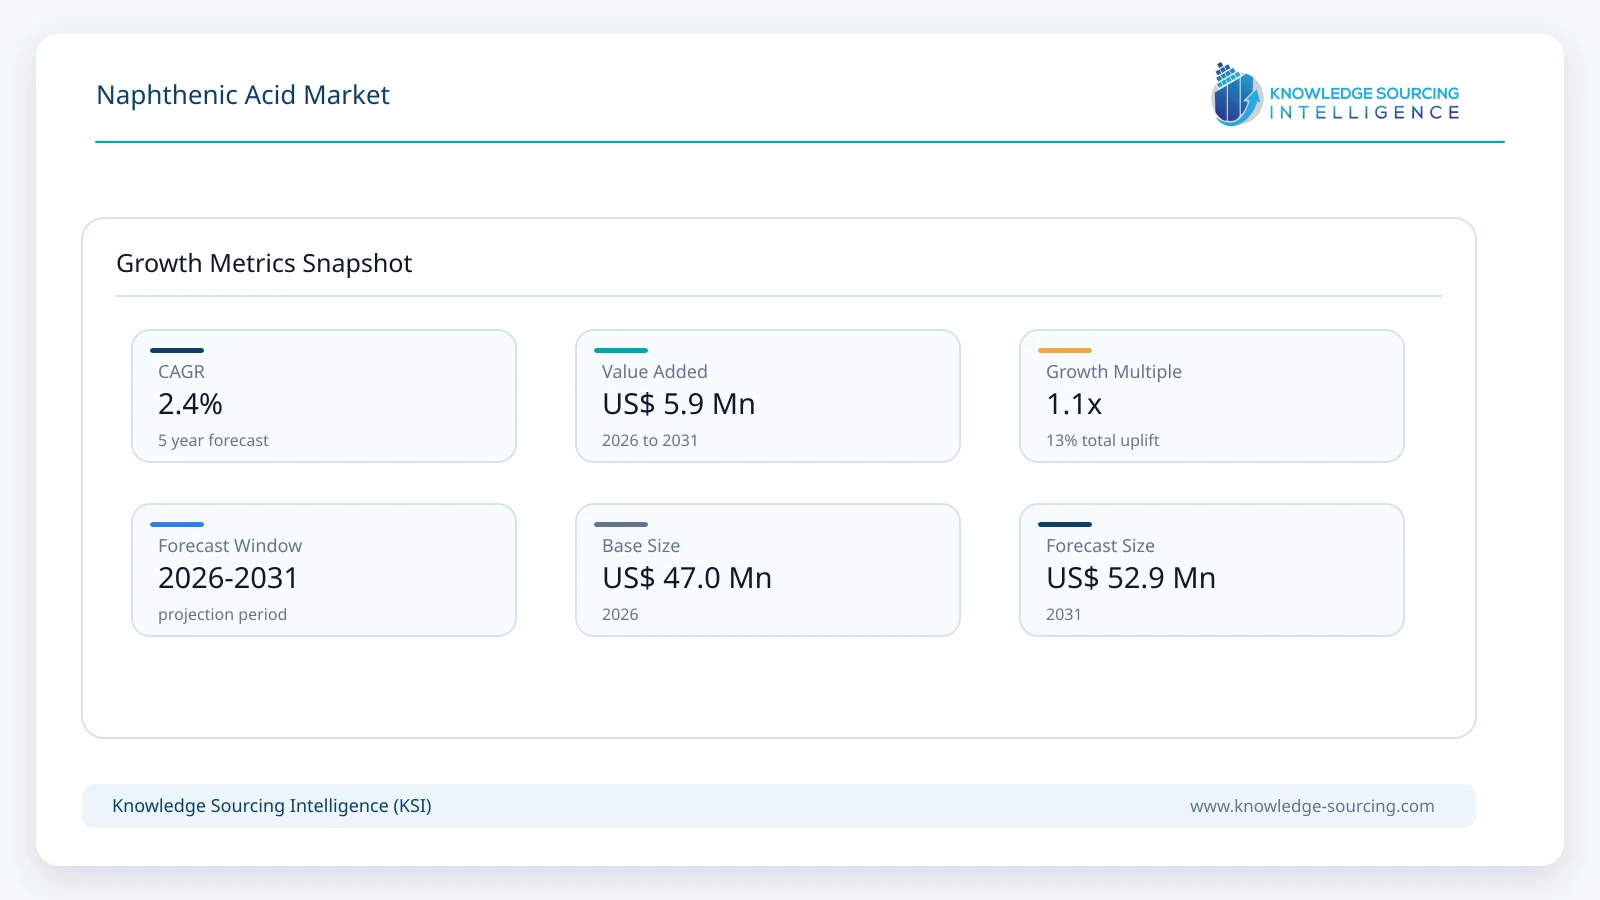
The Naphthenic Acid Market is expected to grow at a 2.41% CAGR, achieving USD 52.91 million in 2031 from USD 46.98 million in 2026.
Highlights:
- 1The naphthenic acid market is expanding steadily at a 2.41% CAGR and is reaching USD 52.91 million by 2031, driven by specialty chemical demand across industrial applications.
- 2Fuel and lubricant additives are commanding the largest approximate segment share of around 40-45%, as producers are converting acids into metal naphthenates for oxidation stability and corrosion protection.
- 3Asia Pacific is holding the leading regional share of roughly 35-40%, with manufacturers continuously increasing consumption through expanding lubricant, coatings, and industrial processing activities.
- 4Refineries are recovering higher volumes of naphthenic acids from high-TAN crude streams, improving feedstock availability while supporting downstream specialty chemical manufacturing integration.
- 5Buyers are prioritizing higher-purity grades and regulatory documentation, especially under REACH frameworks, strengthening long-term supplier relationships in coatings and lubricant formulations.
- 6Industrial maintenance and coatings applications are generating recurring replacement demand, providing relatively stable consumption even as project-based volumes fluctuate across regions.
Market Overview
Consequently, market dynamics are influenced not only by downstream industrial demand but also by refinery feedstock selection, extraction economics, and environmental compliance requirements. Official treatment technology providers indicate that recovery of naphthenic acids has increasingly become a value-generating activity alongside corrosion management in refining operations.
Industrial purchasing remains concentrated among manufacturers of metal naphthenates, lubricant additives, rubber chemicals, paint driers, and specialty preservatives. Buyers generally prioritize acid composition, consistency, purity, metal content, oxidation stability, and regulatory documentation over commodity pricing alone. High-purity grades command stronger commercial value because impurities directly influence catalyst preparation, coating performance, lubricant stability, and downstream formulation quality.
Value creation is distributed across refinery recovery, purification, formulation, and specialty chemical manufacturing rather than simple bulk chemical production. Refiners recover crude naphthenic acids from petroleum fractions, while specialty chemical manufacturers further refine or chemically convert these materials into metal soaps and functional additives serving industrial applications. Demand therefore depends on activity across refining, coatings, lubricants, construction materials, and industrial maintenance rather than a single end-use sector.
Regulatory oversight has become more influential in purchasing decisions. Chemical registration, hazard communication, environmental handling requirements, and occupational safety obligations affect supplier qualification, particularly in Europe where substances and related derivatives remain subject to the requirements of the REACH framework and classification obligations administered by the European Chemicals Agency.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Primary feedstock | Petroleum refinery streams containing high-TAN crude | Supply depends on refinery operating strategy rather than standalone chemical production. |
Merichem NAPFINING™ installations | 80+ licensed units worldwide | Demonstrates continued refinery investment in naphthenic acid recovery technologies. |
Regulatory framework | REACH registration and classification requirements | Compliance documentation increasingly influences supplier selection in European markets. |
Principal downstream products | Metal naphthenates, lubricant additives, coating driers, preservatives | Diversified industrial applications reduce dependence on a single customer industry. |
Market Drivers
Recovery of value from high-acidity crude processing. Refiners processing higher-TAN crude increasingly view naphthenic acid recovery as both a corrosion mitigation measure and an opportunity to generate additional value from refinery side streams. Rather than disposing of acidic fractions, operators are investing in treatment technologies capable of extracting commercially usable acids for downstream specialty chemical production. Merichem reports more than 80 licensed NAPFINING™ units globally, indicating continued commercial interest in recovery technologies where suitable refinery economics exist. This improves feedstock availability for specialty producers while encouraging closer integration between refining and downstream chemical manufacturing.
Sustained industrial demand for metal naphthenates and performance additives. Naphthenic acids remain important intermediates in producing metal naphthenates used as paint driers, catalysts, wood preservatives, lubricant additives, and rubber processing chemicals. Purchasing decisions are driven less by commodity volumes than by product consistency and performance in downstream formulations. Industrial customers increasingly require narrow compositional ranges to ensure predictable drying characteristics, corrosion protection, and lubricant performance. Suppliers capable of providing consistent purity, technical support, and regulatory documentation strengthen long-term customer relationships while reducing qualification costs for formulators.
Increasing preference for higher-purity specialty grades. Product specifications have become more demanding as environmental compliance, occupational safety, and formulation performance receive greater scrutiny from industrial buyers. Higher-purity naphthenic acids reduce contamination risks during production of specialty metal salts and improve reproducibility in coatings, catalysts, and lubricant formulations. Chemical suppliers including Merck KGaA, Sigma-Aldrich, and TCI Chemicals emphasize analytical quality, documentation, and laboratory-grade consistency across specialty chemical portfolios, reflecting broader customer demand for controlled product quality rather than only bulk availability. Regulatory documentation has become an increasingly important purchasing criterion alongside technical performance.
Replacement demand from industrial maintenance and coatings applications. Industrial coatings, corrosion protection systems, and lubricant formulations continue to generate recurring consumption because these products require periodic replacement rather than one-time installation. Manufacturing facilities, mining operations, marine infrastructure, and transportation equipment require ongoing maintenance cycles that sustain demand for specialty additives. Although individual application volumes fluctuate with industrial production, recurring maintenance activity provides a relatively stable consumption base compared with project-dependent specialty chemicals.
Market Restraints and Challenges
Dependence on refinery feedstock characteristics limits supply flexibility. Unlike many specialty chemicals that can be manufactured through dedicated synthesis, naphthenic acid production depends on the availability of suitable petroleum fractions. Changes in refinery crude slates, lower processing of high-TAN crude, or operational adjustments can reduce recoverable feedstock volumes. Supply expansion therefore requires both suitable crude availability and economically viable recovery operations, limiting manufacturers' ability to respond rapidly to changes in downstream demand. This structural dependence introduces supply uncertainty that is not easily mitigated through conventional capacity expansion.
Environmental compliance increases production and qualification costs. Registration, classification, worker safety requirements, and environmental handling obligations continue to raise compliance costs across the value chain. European regulatory oversight requires manufacturers and downstream users to maintain updated substance documentation, hazard communication, and safe handling procedures under the REACH framework. Compliance expenses are particularly challenging for smaller specialty chemical suppliers because documentation, testing, and regulatory maintenance represent fixed costs regardless of production volume.
Variable chemical composition complicates downstream standardization. Naphthenic acids comprise complex mixtures whose composition varies according to crude oil origin and refinery processing conditions. Variations in molecular distribution, acidity, sulfur content, and impurities influence downstream product performance. Manufacturers supplying paint driers, lubricant additives, and metal naphthenates frequently require tighter quality specifications than untreated refinery streams can provide. Additional purification raises production costs while increasing analytical testing requirements before materials can enter higher-value specialty applications.
Competition from alternative additive chemistries. Several downstream applications increasingly evaluate synthetic carboxylic acids, alternative metal-organic compounds, and other specialty additives that meet evolving environmental and performance requirements. Buyers compare not only purchase price but also regulatory acceptance, service life, compatibility with modern formulations, and long-term environmental obligations. As formulation technologies evolve, naphthenic acid suppliers must continue improving purity, technical support, and application performance to maintain competitiveness in specialty chemical markets rather than relying solely on established industrial usage.
Major Segment Analysis
Fuel and Lubricant Additives
Fuel and lubricant additives represent the most commercially important application segment because naphthenic acids serve as intermediates for producing metal naphthenates that improve oxidation stability, corrosion protection, detergent performance, and lubricant durability in industrial and automotive applications. Purchasing decisions in this segment prioritize acid number consistency, low impurity levels, and compatibility with additive packages rather than price alone. Industrial lubricant formulators typically require long-term supply agreements and documented quality control to ensure consistent product performance across multiple operating conditions.
Competition within this segment depends on purification capability, technical support, and application-specific formulation expertise. High-purity naphthenic acids command greater value because trace contaminants can reduce additive performance and shorten lubricant service life. Suppliers are responding by expanding analytical capabilities, improving batch consistency, and strengthening regulatory documentation, particularly for customers operating under stringent industrial and environmental compliance requirements. Compared with applications such as wood preservatives or rubber additives, lubricant formulations generally involve longer qualification cycles and higher switching costs, supporting stable supplier relationships once products are approved.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
North America | Mature refining industry, lubricant manufacturing, specialty chemical production | Refinery feedstock variability and environmental compliance |
Europe | REACH compliance, coatings, specialty chemicals | Stringent chemical registration and sustainability requirements |
Asia Pacific | Industrial manufacturing expansion, coatings, lubricant demand | Uneven product quality and dependence on imported specialty grades |
Middle East and Africa | High refinery throughput and downstream petrochemicals | Limited regional specialty chemical conversion capacity |
North America benefits from an established petroleum refining industry capable of processing diverse crude slates alongside a mature specialty lubricant and coatings sector. The United States remains the primary regional consumer owing to extensive industrial maintenance activity and well-developed downstream chemical manufacturing. Refineries continue investing in technologies that improve acid recovery while reducing corrosion associated with high-acidity crude processing, supporting availability of refinery-derived feedstocks for specialty chemical producers.
European demand is shaped more by regulatory compliance than production volume. Manufacturers supplying coatings, catalysts, and lubricant additives must comply with the European Union's REACH regulation and Classification, Labelling and Packaging (CLP) requirements, making product documentation and substance registration central purchasing criteria. Buyers increasingly favor suppliers able to provide comprehensive technical dossiers and consistent quality, creating higher entry barriers for smaller manufacturers.
Asia Pacific continues to account for a broad manufacturing base across coatings, automotive components, industrial machinery, and specialty chemicals. China, India, Japan, and South Korea generate sustained consumption through expanding lubricant production, industrial maintenance, and chemical processing activities. Regional demand is supported by manufacturing investment and growing domestic formulation capacity, although premium grades are still imported for applications requiring tighter quality specifications.
The Middle East and Africa benefit from extensive crude oil production and refining capacity, particularly across Gulf Cooperation Council countries. Although refinery operations provide suitable feedstocks for naphthenic acid recovery, much of the higher-value downstream conversion into specialty additives remains concentrated in North America, Europe, and parts of Asia. Increasing investment in downstream petrochemical diversification may gradually strengthen regional specialty chemical production during the forecast period.
Competitive Landscape
The naphthenic acid market exhibits characteristics of a specialized, application-driven market where product quality, regulatory compliance, and technical support create stronger competitive differentiation than production scale alone. Companies including Merck KGaA, Sigma Aldrich, Merichem Company, Dorf Ketal Chemicals, Haihang Industry, TCI Chemicals, Vizag Chemicals, Jigchem Chemical, and Umicore participate across different portions of the value chain, ranging from laboratory-grade chemicals and refinery processing technologies to specialty chemical intermediates.
Competition increasingly centers on purification technology, product consistency, analytical capability, regulatory documentation, and long-term customer qualification. Companies also continue investing in operational efficiency, digital quality management, sustainable manufacturing practices, and resilient supply chains to address increasingly stringent customer specifications and evolving environmental obligations. Recent annual reports from companies such as Umicore and Merck KGaA indicate continued emphasis on operational efficiency, compliance, and value-added specialty materials rather than commodity chemical expansion.
Recent Developments
August 2026: Nexal Inc. updated its industrial-grade Naphthenic Acid offering, listing ?80.0 wt% purity, 200–220 mg KOH/g acid value and 400 tons supply capacity, indicating continued commercial availability of bulk naphthenic acid.
August 2026: RongNa Biotechnology Co., Ltd. listed a 99% purity Naphthenic Acid product, available through its chemical manufacturing supply networks for research and industrial applications.
June 2026: Ergon Solutions, Inc. entered a Strategic Marketing Assistance Agreement with SA Services, LLC to promote and support Ergon’s specialty-oil products, including naphthenic-based offerings, across the North American oilfield sector.
April 2026: Ergon announced a $0.70-per-gallon increase for its HyVolt Dielectric Fluids, HyGold Base Oils and HyPrene Process Oils in North America, effective April 17, reflecting tighter pricing conditions for naphthenic specialty oils.
Regulatory and Policy Environment
Regulatory compliance remains a fundamental commercial consideration throughout the naphthenic acid value chain. Within the European Union, manufacturers and importers must satisfy REACH registration, safety documentation, classification, and downstream communication requirements before products can be supplied commercially. These obligations increase qualification costs but also strengthen demand for suppliers with established compliance capabilities.
Occupational safety regulations governing handling, storage, transportation, and labeling continue to influence purchasing decisions in North America and Europe. Environmental regulations affecting petroleum refining indirectly shape feedstock availability because refinery processing strategies determine recoverable naphthenic acid volumes. Consequently, regulatory developments influence both supply economics and downstream customer qualification requirements rather than demand alone.
Outlook and Strategic Implications
Demand during the 2026-2031 forecast period is expected to remain supported by industrial lubricants, coatings, specialty catalysts, and metal naphthenate production rather than rapid expansion into new applications. Commercial performance will depend on suppliers' ability to provide consistent quality, reliable documentation, and application-specific technical support while managing feedstock variability arising from refinery operations.
Strategic priorities across the value chain are expected to include:
Investment in higher-purity naphthenic acid production for specialty applications.
Greater emphasis on regulatory compliance and product stewardship.
Stronger integration between refinery recovery technologies and downstream specialty chemical manufacturing.
Expansion of analytical quality control and customer-specific formulation support.
Supply-chain diversification to reduce dependence on individual refinery feedstock sources.
Companies that combine secure feedstock access with advanced purification capability and established regulatory expertise are expected to strengthen their position in higher-value industrial applications, while suppliers competing primarily on commodity pricing are likely to face increasing margin pressure as customer specifications continue to tighten.
Naphthenic Acid Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 46.98 million |
| Total Market Size in 2031 | USD 52.91 million |
| Forecast Unit | Million |
| Growth Rate | 2.41% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Application, Geography |
| Companies |
|
Market Segmentation
By Type
By Application
By Geography
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. NAPHTHENIC ACID MARKET BY TYPE
5.1. Introduction
5.2. Refined Naphthenic Acid
5.3. High-Purity Naphthenic Acid
6. NAPHTHENIC ACID MARKET BY APPLICATION
6.1. Introduction
6.2. Rubber Additives
6.3. Wood Preservatives
6.4. Fuel And Lubricant Additives
6.5. Paint And Ink Driers
6.6. Others
7. NAPHTHENIC ACID MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. USA
7.2.2. Canada
7.2.3. Mexico
7.3. South America
7.3.1. Brazil
7.3.2. Argentina
7.3.3. Others
7.4. Europe
7.4.1. Germany
7.4.2. France
7.4.3. United Kingdom
7.4.4. Spain
7.4.5. Others
7.5. Middle East and Africa
7.5.1. Saudi Arabia
7.5.2. UAE
7.5.3. Others
7.6. Asia Pacific
7.6.1. China
7.6.2. India
7.6.3. Japan
7.6.4. South Korea
7.6.5. Indonesia
7.6.6. Thailand
7.6.7. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Sigma Aldrich
9.2. Haihang Industry
9.3. Merichem Company
9.4. Umicore
9.5. Merck KGaA
9.6. TCI Chemicals
9.7. Jigchem Chemical
9.8. Vizag Chemicals
9.9. Dorf Ketal Chemicals
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key benefits for the stakeholders
10.5. Research Methodology
10.6. Abbreviations
Navigate
Trusted by the world's leading organizations











