
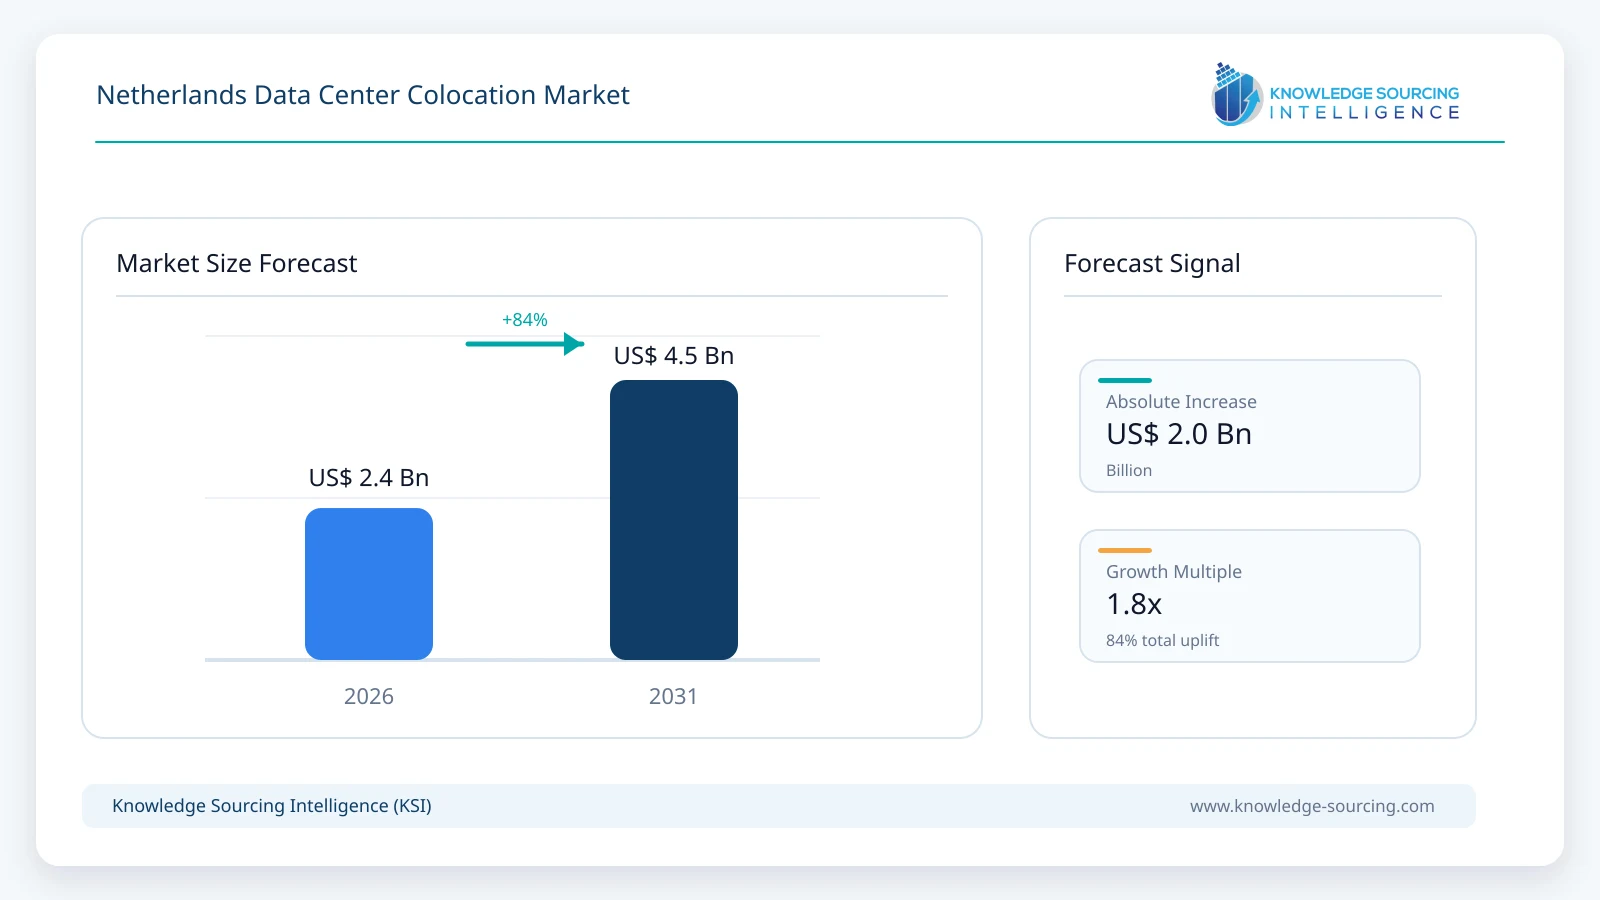
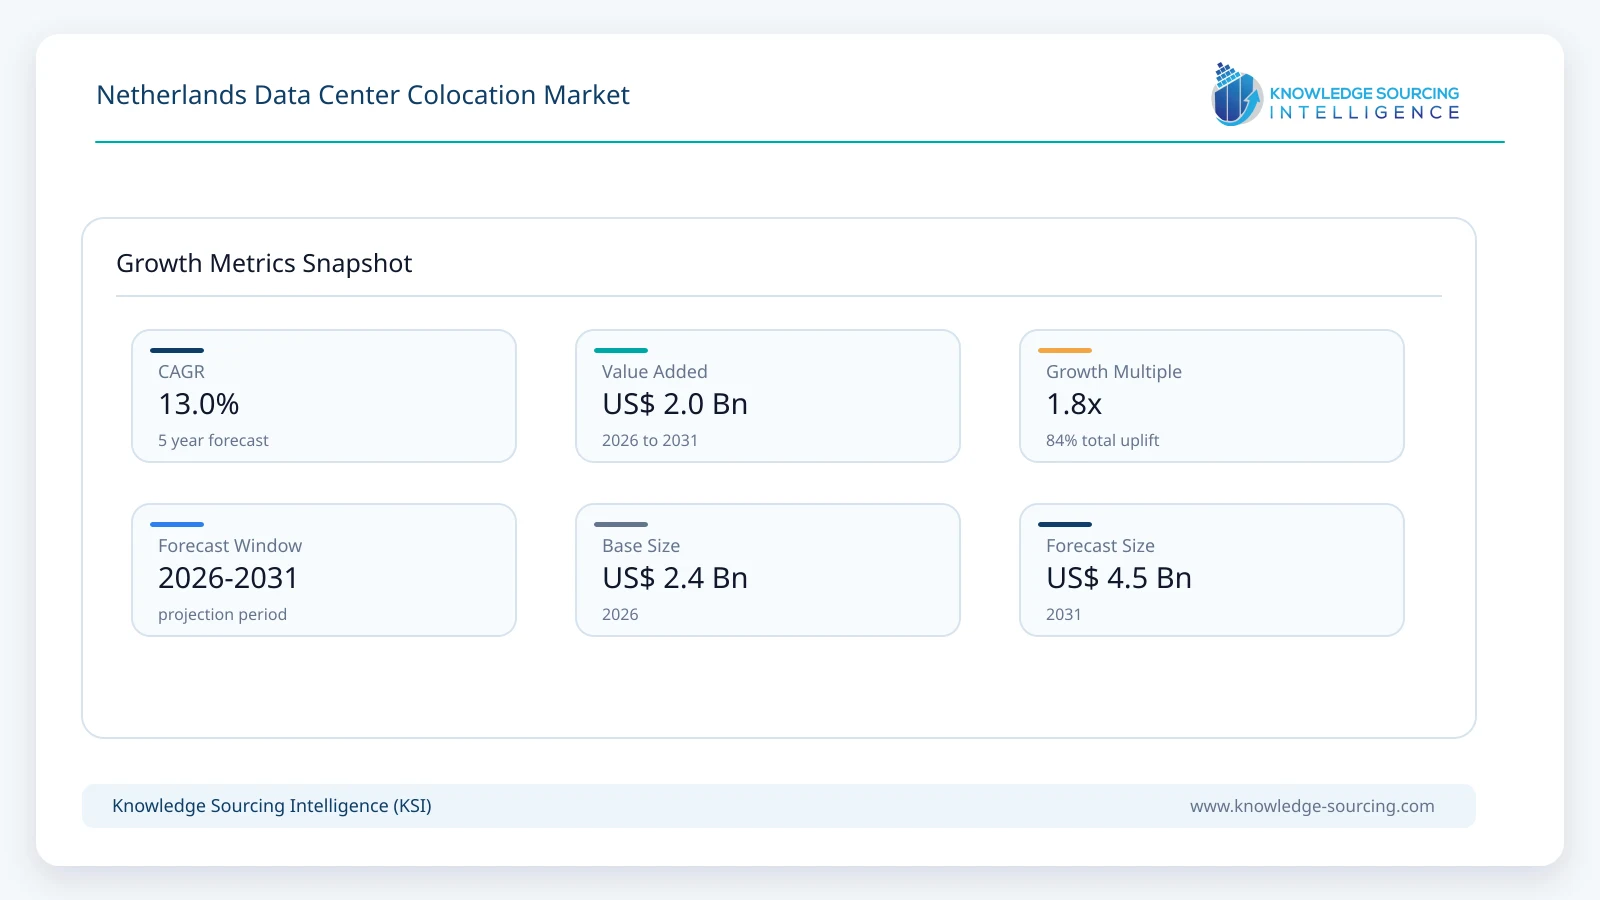
The Netherlands data center colocation market is forecast to grow at a CAGR of 13.0%, reaching USD 4.46 billion in 2031 from USD 2.42 billion in 2026.
Highlights:
- 1Growing AI, cloud, and enterprise workloads continue to strengthen colocation demand across the Netherlands.
- 2Power availability has become a more decisive purchasing criterion than rack pricing alone.
- 3Wholesale colocation benefits from hyperscale cloud expansion and large enterprise capacity planning.
- 4Sustainability requirements increasingly influence facility design, energy sourcing, and customer procurement.
- 5Network density around Amsterdam continues to support international connectivity and interconnection demand.
Market Overview
Enterprise buying behavior has also changed over the past several years. Large organizations increasingly evaluate colocation providers according to available electrical capacity, renewable energy sourcing, operational resilience, expansion flexibility, and proximity to internet exchanges before signing multi-year contracts. Small and medium-sized enterprises remain active buyers, although they typically prioritize operational reliability, predictable monthly costs, managed services, and rapid deployment over customized infrastructure. This divergence has encouraged providers to broaden service portfolios while investing in both hyperscale-ready campuses and flexible retail colocation offerings.
Demand is supported by continued migration toward hybrid cloud architectures, rising interconnection requirements, increasing enterprise data volumes, and growing deployment of AI workloads that require high-density computing environments. Amsterdam remains one of Europe's most connected digital hubs through its extensive carrier ecosystem and the presence of the Amsterdam Internet Exchange (AMS-IX), supporting domestic and international traffic flows. At the same time, electricity network constraints, permitting complexity, and land availability increasingly influence investment decisions, project timing, and customer site selection. The Dutch Data Center Association identifies grid capacity and available space among the industry's principal structural challenges, even as digital infrastructure continues to expand its role within the national economy.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Sustainable electricity procurement | 99% of purchased electricity for Dutch colocation data centers came from sustainable sources (2023) | Sustainability has become a competitive requirement for enterprise procurement. |
Enterprise cloud adoption | 90% of Dutch companies with 250+ employees use paid cloud services | Continued cloud adoption supports long-term colocation demand and hybrid IT deployments. |
Built-up data center footprint | 239 hectares of data center surface area | Existing infrastructure provides a mature platform for expansion, although land availability remains constrained. |
Water consumption | 1.0 million m³ for the Information and Communication sector | Water efficiency remains an increasingly important operational consideration for facility development. |
Industry outlook | Grid congestion and skilled labor shortages identified among the sector's principal challenges | Future investment increasingly depends on infrastructure availability rather than customer demand alone. |
Market Drivers
Expansion of AI computing and hybrid cloud infrastructure. Enterprise computing strategies increasingly combine private infrastructure with public cloud environments, creating sustained demand for carrier-neutral colocation facilities that offer direct cloud connectivity and scalable power capacity. AI model training, inference workloads, and data-intensive applications require higher rack densities, advanced cooling systems, and resilient network infrastructure. Providers including Equinix, Digital Realty, NorthC, and CyrusOne continue expanding high-capacity facilities and interconnection capabilities to accommodate enterprise and hyperscale customer requirements. Industry publications also indicate that AI-driven computing is becoming an increasingly important source of future capacity demand.
Dense network connectivity strengthens enterprise location preferences. Procurement decisions increasingly prioritize network ecosystems over standalone facility specifications because enterprises seek low-latency access to cloud providers, telecommunications carriers, internet exchanges, and business partners. The Netherlands benefits from the concentration of interconnected facilities surrounding Amsterdam and the presence of AMS-IX, enabling customers to reduce network latency while simplifying interconnection with domestic and international service providers. This connectivity advantage supports demand from cloud operators, financial institutions, digital platforms, content providers, and multinational enterprises seeking resilient European infrastructure.
Corporate sustainability objectives influence infrastructure procurement. Environmental performance has become an integral component of enterprise infrastructure purchasing rather than a secondary evaluation factor. Large organizations increasingly assess renewable electricity sourcing, energy efficiency, emissions reporting, and environmental certifications during supplier selection. The Dutch Data Center Association reports that nearly all electricity purchased by Dutch colocation facilities originates from sustainable sources, while industry initiatives increasingly focus on improving cooling efficiency, energy optimization, and responsible resource use. These requirements encourage operators to invest in efficient facility designs that satisfy both customer procurement policies and evolving environmental expectations.
Market Restraints and Challenges
Electricity grid congestion delays new capacity deployment. Power availability has become one of the primary constraints on expansion rather than customer demand. The Dutch electricity transmission operators and industry bodies have repeatedly identified grid congestion across several regions, making it increasingly difficult for developers to secure timely high-voltage connections for new facilities. Company disclosures from operators such as Digital Realty and Equinix also recognize utility availability as an important factor influencing campus development schedules. While some providers are adopting phased construction, battery storage, demand-response solutions, and closer coordination with utilities, prolonged grid reinforcement timelines continue to delay revenue realization and limit the pace of new colocation supply.
Lengthy permitting processes and tighter spatial planning increase project risk. New data center development in the Netherlands faces stricter planning requirements following increased government attention to land use, energy consumption, and environmental impacts. Provincial and municipal authorities now apply more comprehensive assessments covering energy efficiency, heat reuse, environmental performance, and local infrastructure capacity before approving new projects. These additional requirements improve long-term sustainability but extend development timelines and increase pre-construction costs. Smaller developers and new entrants often experience greater difficulty navigating these approval processes because they possess fewer local planning resources and established regulatory relationships.
Rising infrastructure costs increase customer qualification thresholds. AI-ready facilities require substantially higher investment in electrical systems, cooling technologies, backup generation, and network infrastructure than conventional enterprise data centers. High-density deployments often exceed traditional rack power requirements, forcing operators to redesign power distribution and cooling architecture before accommodating customer workloads. These investments raise capital intensity and increase the minimum contract size needed to achieve acceptable returns. Consequently, providers increasingly prioritize long-term enterprise and hyperscale customers that can commit to multi-year capacity agreements, while smaller customers may encounter higher pricing or reduced availability for premium facilities.
Skilled workforce shortages affect operational scalability. The increasing technical complexity of modern colocation facilities has expanded demand for engineers specializing in electrical infrastructure, mechanical systems, cybersecurity, automation, and critical facility operations. Industry organizations, including the Dutch Data Center Association, continue to identify workforce availability as a structural challenge affecting maintenance, commissioning, and future expansion. Competition for experienced personnel has intensified as cloud providers, telecommunications companies, and digital infrastructure operators recruit from the same talent pool. Operators are responding through apprenticeship programs, partnerships with educational institutions, and greater investment in facility automation, although workforce constraints remain evident across the value chain.
Major Segment Analysis
Wholesale Colocation
Wholesale colocation represents the most commercially important segment because it serves hyperscale cloud providers, global digital platforms, telecommunications operators, and large enterprises requiring dedicated, high-capacity infrastructure rather than individual cabinets or cages. Purchasing decisions within this segment extend beyond rack pricing to include available electrical capacity, campus expansion potential, network diversity, sustainability credentials, and contractual flexibility. Multi-megawatt deployments and long-term occupancy agreements provide operators with greater revenue visibility while supporting investment in larger campuses and advanced power infrastructure.
Demand has strengthened as organizations expand hybrid cloud environments and deploy AI workloads that require high-density computing and resilient connectivity. Customers increasingly prefer providers capable of delivering phased capacity growth without disrupting existing operations. This has encouraged companies such as Equinix, Digital Realty, CyrusOne, NorthC, and Switch Datacenters to expand interconnected campuses, enhance cloud connectivity, and invest in higher-density facility designs. At the same time, wholesale developments remain particularly exposed to electricity availability, permitting timelines, and construction costs because these projects require substantial utility capacity before commercial operations can begin. Consequently, competition increasingly centers on securing power access, accelerating project delivery, and providing scalable infrastructure capable of supporting long-term enterprise expansion rather than competing solely on rental rates.
Competitive Landscape
The Netherlands data center colocation market exhibits a moderately concentrated structure, with competition centered on network ecosystems, power availability, operational resilience, sustainability performance, and the ability to support long-term enterprise and hyperscale deployments. Equinix, Digital Realty, NorthC, CyrusOne, Iron Mountain Data Centers, QTS Realty Trust, nLighten, AtlasEdge, and Switch Datacenters compete by expanding interconnected campuses, increasing renewable energy procurement, strengthening cloud connectivity, and improving service portfolios for hybrid IT environments. Product differentiation is less dependent on physical rack space than on interconnection density, compliance capabilities, service-level commitments, and expansion flexibility. As grid capacity becomes more constrained, providers with secured utility connections and developable land gain a competitive advantage. Several operators are also investing in higher rack-density designs, liquid-cooling readiness, and automated facility management to accommodate AI-related workloads. These capabilities raise switching costs for enterprise customers that require continuous availability, regulatory compliance, and proximity to cloud platforms and carrier ecosystems, making long-term customer retention an important competitive factor.
Recent Developments
September 2026: Eurofiber Cloud Infra wins SURF’s Dutch AI Factory contract, providing high-performance computing data center services in Groningen. The facility will reuse heat for approximately 2,000 homes and employ water-free cooling.
August 2026: Eurofiber secures €2.2 billion in sustainability-linked financing, strengthening its capacity to invest in European digital infrastructure, expand cloud infrastructure services, and support long-term network and infrastructure development.
June 2026: Eurofiber, INSPIR8ION, Q*Bird, Cisco, and CGI launch the Quantum Communication Fieldlab Rotterdam, enabling practical testing and validation of quantum-secure communications for critical infrastructure and public-sector applications.
March 2026: Eurofiber and Colt announce a quantum-secured fiber corridor, connecting Amsterdam with London and Brussels to strengthen secure, low-latency connectivity for financial institutions and improve resilience against emerging quantum-computing threats.
December 2025: Antin Infrastructure Partners agreed to acquire NorthC Datacenters from DWS, gaining a leading Dutch colocation platform operating 25 facilities across the Netherlands, Germany, and Switzerland with more than 140 MW of secured capacity.
Regulatory and Policy Environment
Dutch policy increasingly links data center development with national energy transition objectives, spatial planning, and infrastructure resilience. National and local authorities require new projects to demonstrate efficient energy use, responsible land utilization, and compatibility with regional electricity networks before development approval. These requirements have increased planning complexity but also encourage investment in more efficient facility designs and stronger environmental performance.
The Netherlands also operates within the broader European Union regulatory framework governing cybersecurity, sustainability, and digital infrastructure. Requirements under the revised NIS2 Directive, the Energy Efficiency Directive, and the Corporate Sustainability Reporting Directive (CSRD) increase expectations for operational resilience, incident reporting, energy transparency, and environmental disclosure. For colocation providers, compliance has become an increasingly important element of enterprise procurement because customers seek infrastructure partners capable of supporting their own governance and reporting obligations.
Grid congestion remains the most immediate regulatory and operational issue affecting future supply. Transmission operators continue investing in network reinforcement, while policymakers encourage greater flexibility in electricity consumption, battery storage, and heat reuse. Operators increasingly engage with utilities during project planning to secure long-term electrical capacity and reduce development risk. The evolving regulatory environment therefore favors providers with established compliance capabilities, strong relationships with local authorities, and the financial capacity to meet increasingly demanding technical and environmental standards.
Outlook and Strategic Implications
Demand fundamentals remain favorable throughout the 2026–2031 forecast period as enterprises expand hybrid cloud environments, AI adoption increases computing density, and digital services continue generating larger volumes of data requiring resilient colocation infrastructure. Future market performance, however, will depend less on customer demand than on the industry's ability to secure power capacity, complete new developments within regulatory requirements, and improve infrastructure efficiency.
Several strategic priorities are likely to shape investment decisions over the forecast period:
Infrastructure operators: Prioritize locations with secured grid access, scalable campus designs, and high-density cooling capabilities to support AI deployments.
Enterprise buyers: Increasingly evaluate providers on power availability, sustainability performance, regulatory compliance, and cloud connectivity rather than rental pricing alone.
Technology and equipment suppliers: Opportunities will expand for liquid cooling, intelligent power management, battery storage, and energy optimization solutions.
Policymakers and utilities: Continued investment in electricity transmission capacity and streamlined permitting processes will influence the pace of future data center expansion.
Competition is therefore expected to shift further toward infrastructure quality, operational resilience, and long-term capacity availability. Providers capable of combining reliable power access, dense interconnection ecosystems, environmental compliance, and scalable deployment options will be better positioned to secure large enterprise contracts and sustain utilization as AI and cloud workloads continue to reshape infrastructure requirements.
Netherlands Data Center Colocation Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.42 billion |
| Total Market Size in 2031 | USD 4.46 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 13.01% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Colocation Model, Enterprise Size, Industry Vertical, Tier Type |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Colocation Model
Wholesale
Retail
By Enterprise Size
Small and Medium Enterprises (SMEs)
Large Enterprises
By Industry Vertical
IT and Telecommunications
BFSI
Government and Public Sector
Healthcare and Life Sciences
Manufacturing
Media and Entertainment
Retail and E-commerce
Energy and Utilities
Others
By Tier Type
Tier I
Tier II
Tier III
Tier IV
Table of Contents
1. INTRODUCTION
1.1. Market Definition
1.2. Market Segmentation
2. RESEARCH METHODOLOGY
2.1. Research Data
2.2. Assumptions
3. EXECUTIVE SUMMARY
3.1. Research Highlights
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porters Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
5. NETHERLANDS DATA CENTER COLOCATION MARKET ANALYSIS, BY COLOCATION MODEL
5.1. Introduction
5.2. Wholesale
5.3. Retail
6. NETHERLANDS DATA CENTER COLOCATION MARKET ANALYSIS, BY ENTERPRISE SIZE
6.1. Introduction
6.2. Small and Medium Enterprises (SMEs)
6.3. Large Enterprises
7. NETHERLANDS DATA CENTER COLOCATION MARKET ANALYSIS, BY INDUSTRY VERTICAL
7.1. Introduction
7.2. IT and Telecommunications
7.3. BFSI
7.4. Government and Public Sector
7.5. Healthcare and Life Sciences
7.6. Manufacturing
7.7. Media and Entertainment
7.8. Retail and E-commerce
7.9. Energy and Utilities
7.10. Others
8. NETHERLANDS DATA CENTER COLOCATION MARKET ANALYSIS, BY TIER TYPE
8.1. Introduction
8.2. Tier I
8.3. Tier II
8.4. Tier III
8.5. Tier IV
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Emerging Players and Market Lucrativeness
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Vendor Competitiveness Matrix
10. COMPANY PROFILES
10.1. Equinix, Inc.
10.2. Digital Realty
10.3. NorthC
10.4. CyrusOne
10.5. Iron Mountain Data Centers
10.6. QTS Realty Trust
10.7. nLighten
10.8. AtlasEdge
10.9. Switch Datacenters





Frequently asked questions
What is the projected market size for Netherlands data center colocation in 2031?
The Netherlands Data Center Colocation Market is projected to reach USD 4.46 billion by 2031.
What is the forecast CAGR for the Netherlands colocation market (2026-2031)?
The Netherlands Data Center Colocation Market is forecast to grow at a 13.01% CAGR.
What are the primary drivers for the Netherlands colocation market growth?
AI, cloud, enterprise workloads, and sustainability are key drivers.
Which city is a key digital hub in the Netherlands colocation market?
Amsterdam remains a crucial digital hub for connectivity and traffic.
What are the main challenges for Netherlands data center colocation growth?
Grid capacity, land availability, and permitting complexity are key challenges.
What criteria influence large enterprise colocation purchasing decisions?
Power, renewable energy, resilience, and flexibility influence decisions.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Netherlands Data Center Colocation Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/netherlands-data-center-colocation-market