
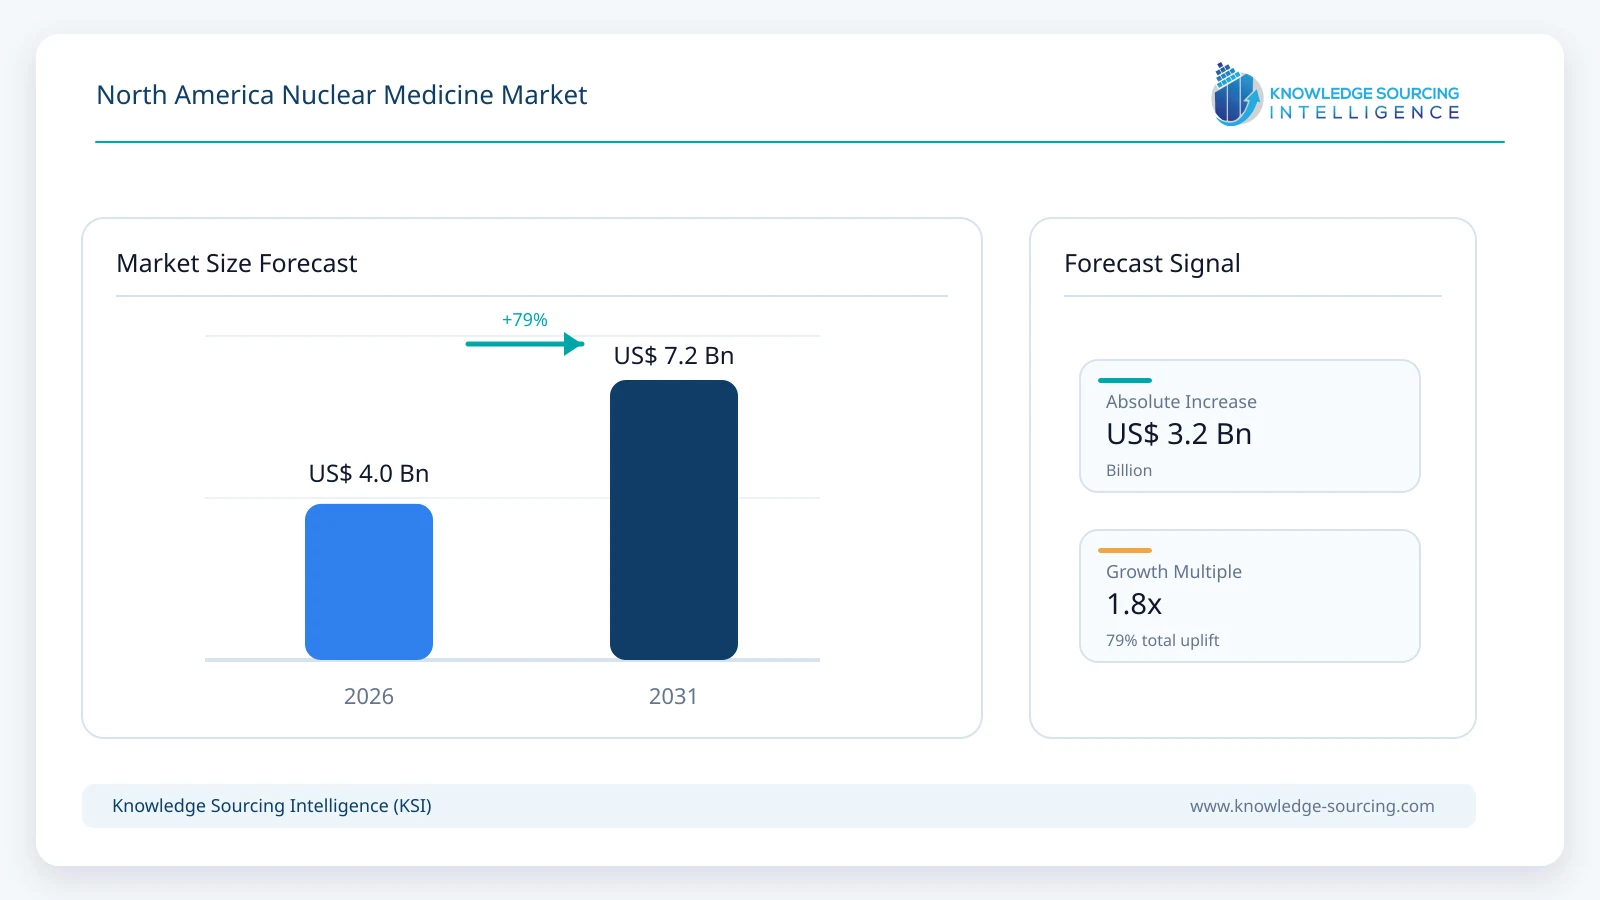
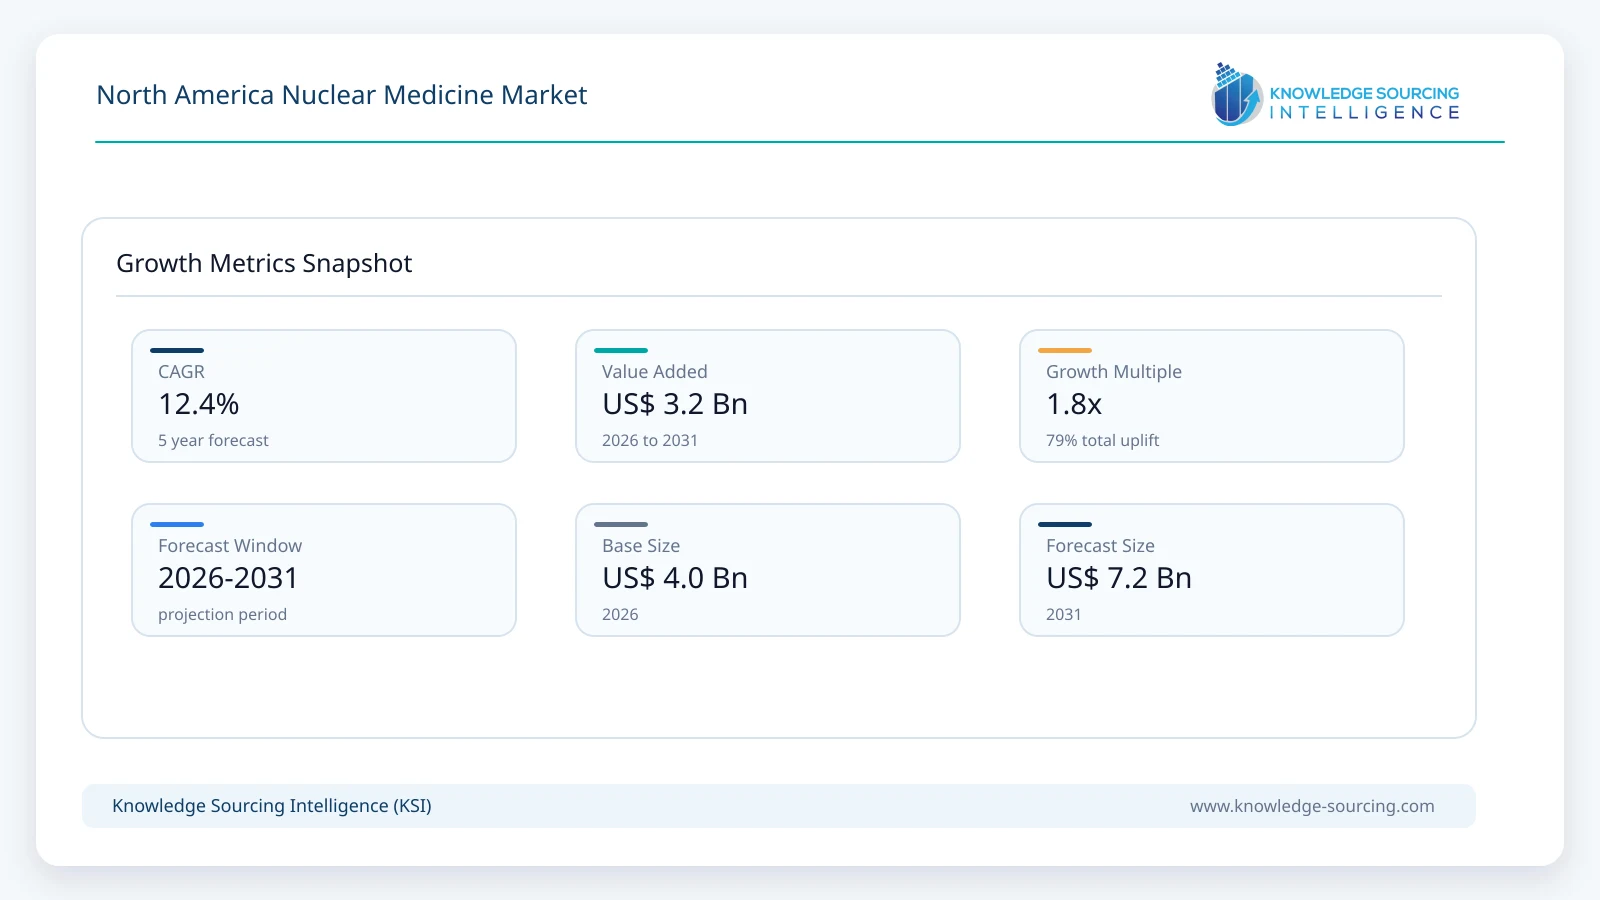
The North America nuclear medicine market is projected to increase from USD 4.02 billion in 2026 to USD 7.21 billion in 2031, representing a CAGR of 12.4% over the forecast period.
Highlights:
- 1North America represents approximately 46% of global nuclear medicine revenue in 2026.
- 2Therapeutic radiopharmaceuticals account for about 32% of regional revenue and grow fastest.
- 3Hospitals contribute approximately 64% of 2026 revenue because therapy needs licensed infrastructure.
- 4PET gains value share through PSMA, amyloid and disease-specific molecular imaging workflows.
- 5The United States accounts for roughly 88.5% of North American revenue in 2026.
- 6Canadian lutetium-177 capacity strengthens regional isotope supply and supports therapy expansion.
North America combines a mature diagnostic imaging base with a rapidly expanding radiopharmaceutical ecosystem. SPECT remains widely used because technetium-99m supports high-volume cardiac perfusion, bone, renal and endocrine procedures. PET has a smaller procedure base but a higher commercial value per scan, particularly where imaging agents are tied to cancer staging, treatment selection or neurological disease pathways. The U.S. reimbursement environment is also becoming more supportive of higher-cost diagnostic agents. Beginning in 2025, the Centers for Medicare & Medicaid Services (CMS) moved qualifying diagnostic radiopharmaceuticals above a per-day cost threshold to separate payment under the Hospital Outpatient Prospective Payment System, improving the economics of specialised tracers.
Regional differentiation increasingly comes from radiopharmaceutical supply and delivery rather than scanner hardware alone. Cardinal Health reports a U.S. network of more than 130 nuclear pharmacies and more than 30 PET sites and manufacturing facilities, giving providers access to time-sensitive unit doses across a large geography. Canada adds strategic isotope-production capability, including lutetium-177 production at Bruce Power, while Mexico remains a smaller market concentrated in major private and tertiary hospitals. OECD data also show a substantial equipment-intensity gap across the region: the combined density of computed tomography, magnetic resonance imaging and PET equipment is materially higher in the United States than in Canada or Mexico, reinforcing the very different commercial maturity of the three countries.
Market Dynamics
Radioligand Therapy Is Expanding High-Value Treatment Revenue
Radioligand therapy is the strongest value-growth driver in North America through 2031. Novartis reported Pluvicto sales of USD 651 million in the second quarter of 2026, up 43% in constant currencies, and specifically cited strong U.S. demand in the pre-taxane metastatic castration-resistant prostate cancer setting. The July 2026 U.S. label expansion into PSMA-positive metastatic androgen pathway modulation-naive or -sensitive prostate cancer broadens the addressable population further. Curium's September 2026 approval of BEXLUTRY adds another lutetium-177 treatment option for adults with somatostatin receptor-positive gastroenteropancreatic neuroendocrine tumours. Each therapy course also increases demand for qualifying PET scans, dosimetry, radiation-safety processes and specialist treatment capacity.
Reimbursement Changes Are Improving Access to High-Cost Diagnostic Radiopharmaceuticals
U.S. reimbursement changes reduce a longstanding barrier for specialised diagnostic tracers. CMS finalised separate payment for diagnostic radiopharmaceuticals with a per-day cost above USD 630 under the 2025 Hospital Outpatient Prospective Payment System rather than packaging those products into the nuclear medicine procedure payment. For 2026, CMS also established a USD 10 add-on payment for technetium-99m doses derived from domestically produced molybdenum-99. These policies do not remove all access constraints, but they improve the economics for hospitals using higher-cost tracers and strengthen incentives for domestic isotope supply, particularly as oncology and neurology imaging become more tracer-specific.
Dense Radiopharmacy and PET Manufacturing Networks Support Commercial Scale
Short half-lives make nuclear medicine unusually dependent on local manufacturing, nuclear pharmacies and reliable last-mile logistics. The United States has a commercial advantage because its supply network is dense enough to support both routine technetium-based imaging and an expanding portfolio of PET tracers. Cardinal Health alone reports more than 130 nuclear pharmacies and more than 30 PET sites and manufacturing facilities in the United States, while its announced investment programme is expanding PET cyclotron coverage and theranostic manufacturing. Curium, Jubilant Radiopharma, Lantheus and other suppliers add further manufacturing and distribution depth. This infrastructure supports faster commercial uptake when new radiopharmaceuticals receive regulatory approval.
Isotope Supply, Workforce and Site Readiness Remain Capacity Constraints
Growth remains constrained by isotope availability, trained personnel and the limited number of sites equipped to deliver complex radiopharmaceutical therapies. Hospitals need nuclear-medicine physicians, radiopharmacists, physicists and technologists, along with licensed preparation areas, radiation monitoring, patient scheduling and waste-management processes. Alpha emitters add another layer of supply risk because clinical development has historically been limited by isotope availability. Cardinal Health expanded actinium-225 production capacity in Indianapolis in April 2026, while Canadian investments are increasing lutetium-177 capability, but the pace of treatment adoption can still exceed the speed at which new production and treatment sites become operational.
North America Nuclear Medicine Market Segment Analysis
By Application
Diagnostic Nuclear Medicine
Diagnostic nuclear medicine remains the largest application segment, accounting for approximately 68% of regional revenue in 2026. SPECT continues to support the broadest routine procedure base, particularly in cardiac perfusion, skeletal imaging, renal function and endocrine care. PET captures a larger share of incremental value because the tracer portfolio is becoming more disease-specific. PSMA PET is now closely linked to prostate-cancer staging and radioligand treatment selection, while amyloid PET and other neurology tracers support more specialised diagnostic pathways. Lantheus reported USD 240.4 million of PYLARIFY sales and USD 39.6 million of Neuraceq sales in the second quarter of 2026, demonstrating the commercial scale achievable when a tracer becomes embedded in high-value clinical workflows.
By Application
Therapeutic Radiopharmaceuticals
Therapeutic radiopharmaceuticals are the fastest-growing application through 2031 and already represent approximately 32% of North American revenue in 2026. Lutetium-177 therapies form the current commercial base, particularly in prostate cancer and neuroendocrine tumours, while actinium-225 and other alpha-emitter programmes expand the longer-term pipeline. The regional value opportunity extends beyond drug revenue because each therapy requires diagnostic imaging, treatment-site preparation, dose handling, radiation-safety services and follow-up imaging. North America is positioned to capture a disproportionate share of this growth because U.S. reimbursement, commercial radiopharmacy density and Canadian isotope-production investments provide a stronger delivery ecosystem than is available in many other markets.
Market and Demand Indicators
Indicator | Latest Development | Market Impact |
Radioligand therapy | Pluvicto Q2 2026 sales reached USD 651M, up 43% in constant currencies. | Confirms rapid commercial scaling, with U.S. demand a major contributor. |
U.S. label expansion | FDA expanded Pluvicto on July 31, 2026 into an earlier metastatic prostate-cancer setting. | Broadens the treatment population and linked PSMA PET demand. |
Commercial diagnostics | Lantheus reported USD 240.4M PYLARIFY and USD 39.6M Neuraceq sales in Q2 2026. | Shows the scale of disease-specific PET tracer revenue. |
Reimbursement | CMS separately pays qualifying high-cost diagnostic radiopharmaceuticals under OPPS from 2025. | Improves hospital economics for specialised imaging agents. |
Distribution network | Cardinal Health reports 130+ U.S. nuclear pharmacies and 30+ PET sites/manufacturing facilities. | Supports time-critical delivery and faster national commercialisation. |
Canadian isotope capacity | CNSC amended Bruce Power's licensing basis for Lu-177 production in August 2026. | Strengthens regional isotope availability and therapy supply resilience. |
United States Market Analysis
The United States is the commercial centre of the North American nuclear medicine market and accounts for approximately 88.5% of regional revenue in 2026. Its advantage combines high healthcare spending, a large oncology patient base, strong PET utilisation, favourable access to new tracers and the region's deepest radiopharmacy infrastructure. OECD Health at a Glance 2025 identifies the United States as having the second-highest PET scanner density among OECD countries in the latest comparable data and reports a combined 86 computed tomography, magnetic resonance imaging and PET scanners per million population, well above the OECD average of 51. This equipment base, combined with broad commercial distribution, makes the U.S. the first major market for many newly approved radiopharmaceuticals.
The highest growth is expected in radioligand therapy, oncology PET and quantitative imaging rather than conventional SPECT procedure volumes. CMS payment changes improve access to higher-cost diagnostic agents, while the July 2026 Pluvicto label expansion and September 2026 BEXLUTRY approval increase therapy capacity requirements across academic centres and community oncology networks. Cardinal Health is also expanding actinium-225 production and plans further PET cyclotron investment across U.S. markets. Canada remains strategically important for isotope production and selected advanced imaging centres, while Mexico is a smaller market with lower equipment density and a greater concentration of advanced nuclear medicine in major urban hospitals and private networks.
Competitive Landscape
Competition spans radiopharmaceutical developers, isotope producers, radiopharmacy networks and imaging-equipment manufacturers. Novartis / Advanced Accelerator Applications leads the current therapeutic radioligand category through Pluvicto and Lutathera. Lantheus has a strong U.S. diagnostic position through PYLARIFY and Neuraceq, while Curium combines broad nuclear-medicine manufacturing and distribution with an expanding theranostics portfolio. Cardinal Health and Jubilant Radiopharma provide critical radiopharmacy and distribution capacity, while SHINE Technologies, BWXT Medical, Nordion and NorthStar Medical Radioisotopes strengthen the North American isotope-supply ecosystem.
Imaging-system competition remains important because new tracers and therapies require better quantification, workflow integration and treatment planning. GE HealthCare, Siemens Healthineers, Philips, Canon Medical, United Imaging and Spectrum Dynamics compete across PET/CT, SPECT/CT, detectors, software and service. Competitive advantage increasingly depends on the ability to support a complete clinical workflow, including tracer access, scanner performance, image quantification, treatment-site logistics and regulatory compliance. Curium's proposed merger with Lantheus, valued at up to USD 8.0 billion, illustrates how scale in diagnostics, therapeutics, manufacturing and distribution is becoming strategically important in the region.
Recent Developments
September 2026: Curium announced U.S. FDA approval of BEXLUTRY for adults with SSTR-positive GEP-NETs.
August 2026: The Canadian Nuclear Safety Commission amended Bruce Power's licensing basis for lutetium-177 production.
August 2026: Curium announced a definitive agreement to merge with Lantheus in a transaction valued up to USD 8.0 billion.
July 2026: The U.S. FDA expanded Pluvicto into PSMA-positive metastatic androgen pathway modulation-naive or -sensitive prostate cancer.
July 2026: The U.S. FDA cleared Cubresa BrainPET, a dedicated brain PET system developed by the Canadian company Cubresa.
April 2026: Cardinal Health announced expanded actinium-225 production capacity at its Indianapolis theranostics facility.
North America Nuclear Medicine Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 4.02 billion |
| Total Market Size in 2031 | USD 7.21 billion |
| Forecast Unit | Billion |
| Growth Rate | 12.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Applications, Procedures, End-User , Geography |
| Companies |
|
Market Segmentation
BY APPLICATION
Diagnosis
Therapeutic
BY PROCEDURE
PET Scan
SPECT Scan
Radioimmunotherapy and Radioligand Therapy
Thyroid Ablation
Brachytherapy
Others
BY END USER
Hospitals
Diagnostic Centres
Research Institutions
BY COUNTRY
United States
Canada
Mexico
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Radioligand Therapy Is Expanding High-Value Treatment Revenue
3.1.2. Reimbursement Changes Are Improving Access to High-Cost Diagnostic Radiopharmaceuticals
3.1.3. Dense Radiopharmacy and PET Manufacturing Networks Support Commercial Scale
3.2. Market Restraints
3.2.1. Isotope Supply, Workforce and Site Readiness Remain Capacity Constraints
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Regulatory and Reimbursement Landscape
4. TECHNOLOGICAL OUTLOOK
4.1. SPECT and SPECT/CT
4.2. PET and PET/CT
4.3. Digital Detectors and Quantitative Imaging
4.4. Radioligand Therapy and Theranostics
4.5. Alpha Emitters and Emerging Radionuclides
5. NORTH AMERICA NUCLEAR MEDICINE MARKET BY APPLICATION
5.1. Diagnosis
5.2. Therapeutic
6. NORTH AMERICA NUCLEAR MEDICINE MARKET BY PROCEDURE
6.1. PET Scan
6.2. SPECT Scan
6.3. Radioimmunotherapy and Radioligand Therapy
6.4. Thyroid Ablation
6.5. Brachytherapy
6.6. Others
7. NORTH AMERICA NUCLEAR MEDICINE MARKET BY END USER
7.1. Hospitals
7.2. Diagnostic Centres
7.3. Research Institutions
8. NORTH AMERICA NUCLEAR MEDICINE MARKET BY COUNTRY
8.1. United States
8.2. Canada
8.3. Mexico
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Novartis / Advanced Accelerator Applications
10.2. Curium Pharma
10.3. Lantheus Holdings, Inc.
10.4. Telix Pharmaceuticals Limited
10.5. Cardinal Health, Inc.
10.6. Jubilant Radiopharma
10.7. Bracco
10.8. Eckert & Ziegler
10.9. Nordion (Sotera Health)
10.10. BWXT Medical Ltd.
10.11. SHINE Technologies, LLC
10.12. NorthStar Medical Radioisotopes, LLC
10.13. GE HealthCare
10.14. Siemens Healthineers
10.15. Koninklijke Philips N.V.
10.16. Canon Medical Systems Corporation
10.17. United Imaging Healthcare
10.18. Spectrum Dynamics Medical
11. RECENT DEVELOPMENTS
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Research Methodology
12.5. Abbreviations
Navigate
Trusted by the world's leading organizations











