
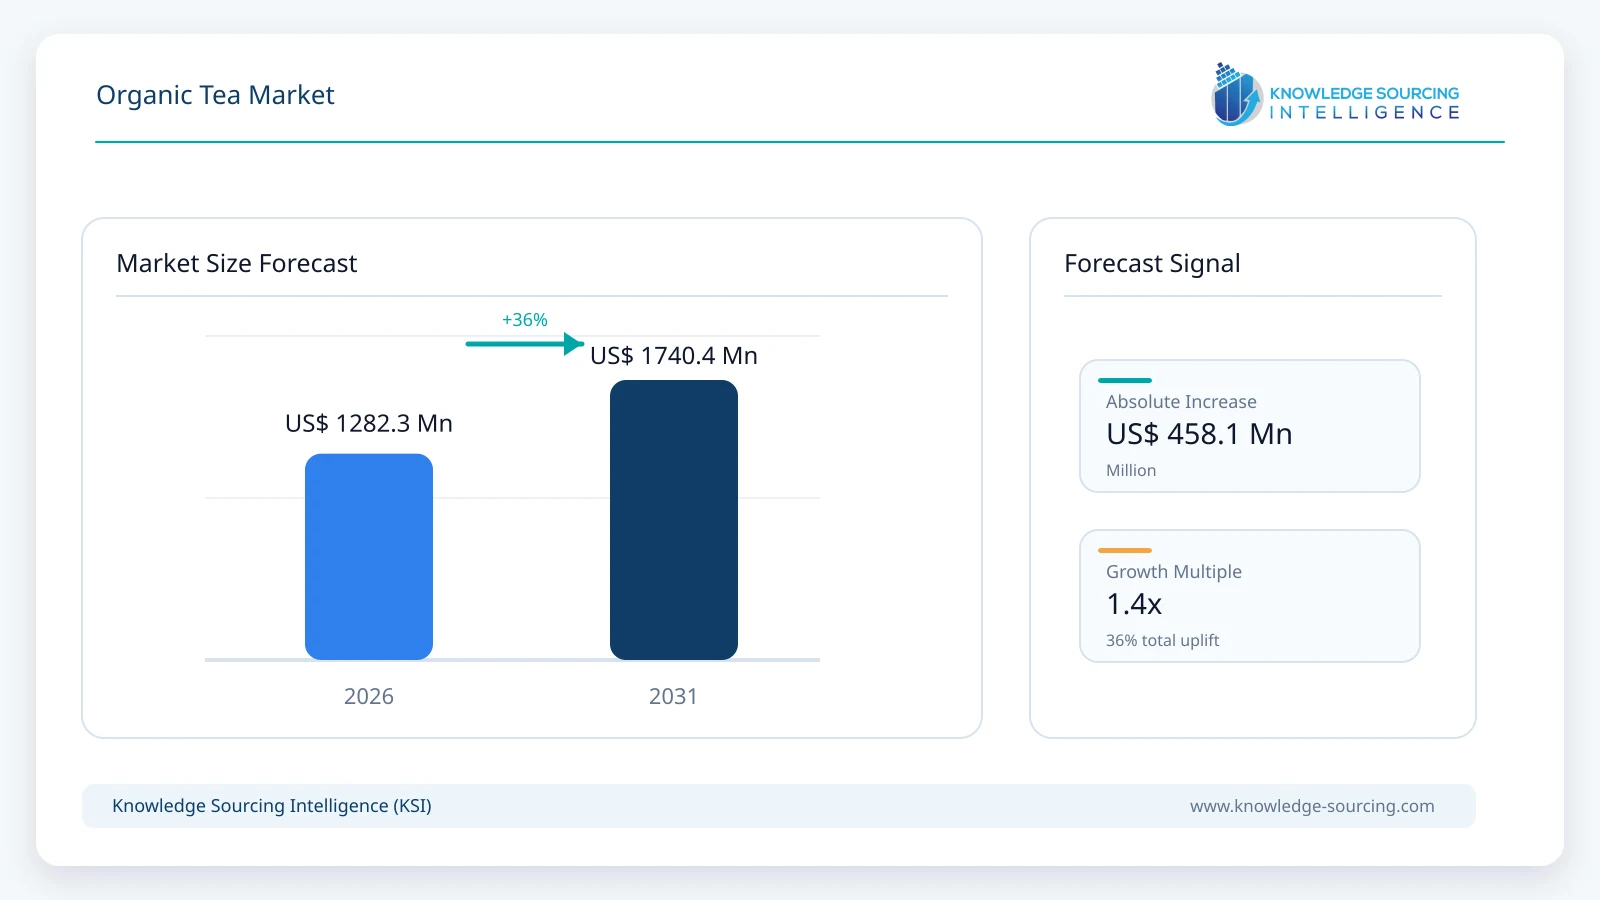
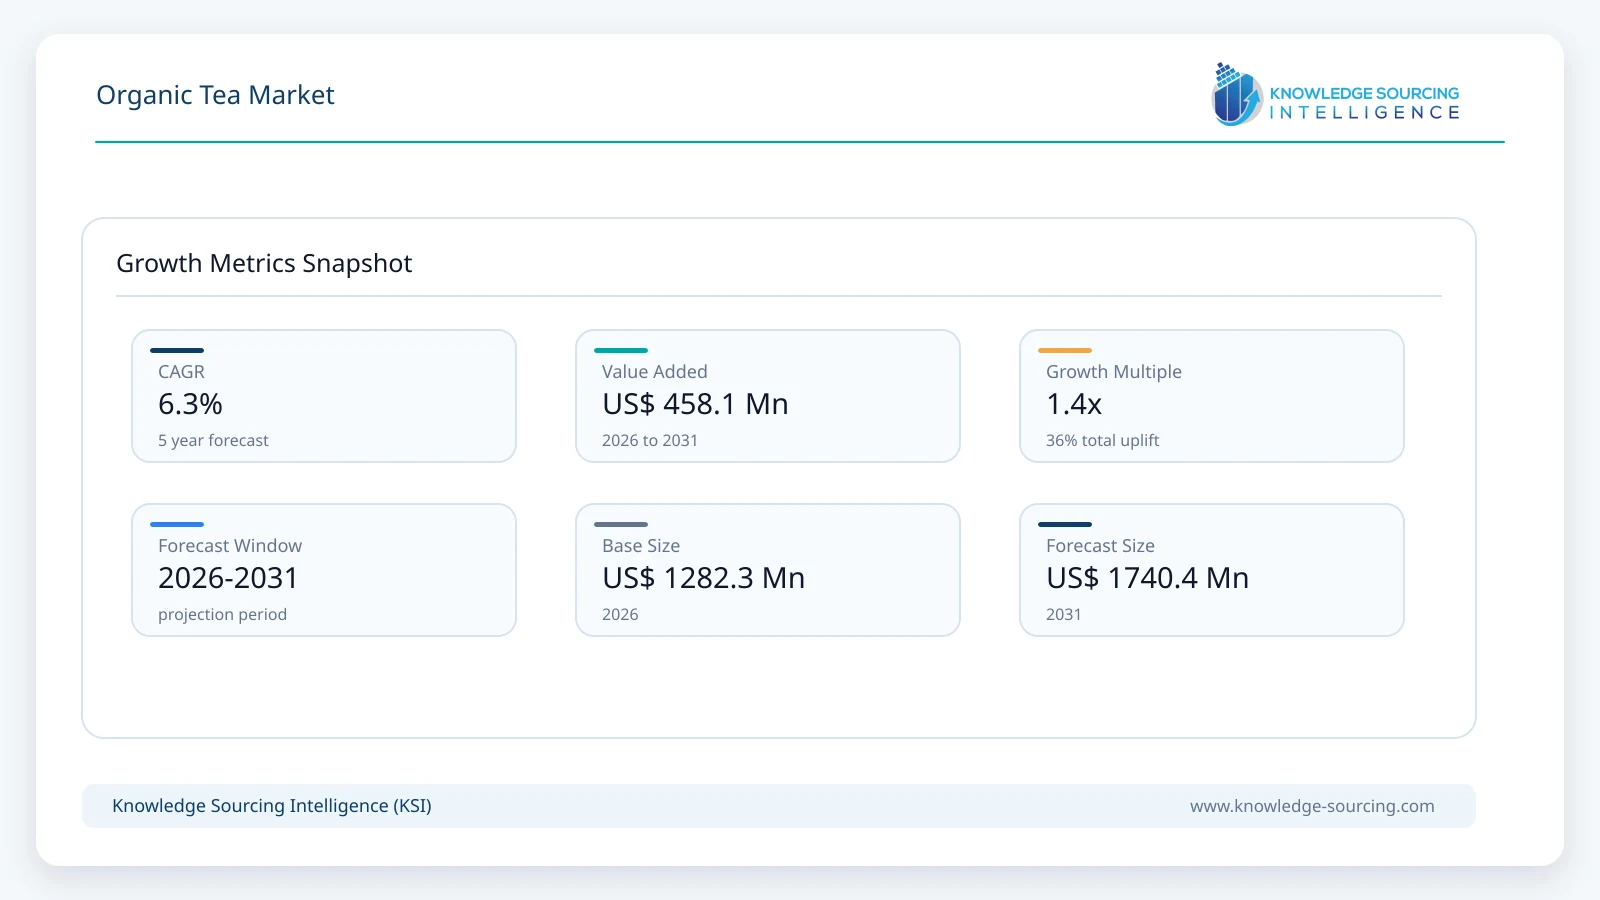
The organic tea market is forecast to grow at a CAGR of 6.3%, reaching USD 1,740.4 million in 2031 from USD 1,282.3 million in 2026.
Highlights:
- 1Certification is a central demand enablerOrganic claims require formal certification and documented compliance in major markets, increasing the importance of traceable sourcing and controlled processing.
- 2Tea bags remain commercially importantConvenience formats allow organic tea brands to reach mainstream grocery buyers while maintaining controlled portioning and standardized preparation.
- 3Loose-leaf products support premium positioningSpecialist brands use origin, tasting characteristics, organic certification, and Fair Trade credentials to differentiate products and support higher unit economics.
- 4Asia Pacific remains critical to supply and demandChina, India, Japan, Indonesia, South Korea, Thailand, and Australia combine major tea-producing capacity, established tea cultures, organic certification systems, and premium consumer segments.
- 5Regulatory scrutiny is increasingChina strengthened its organic certification framework from January 2026, while Japan has updated Organic JAS standards and the United Kingdom continues to require certification for organic food operators.
- 6Product innovation is broadening the premium assortmentRecent launches and portfolio extensions include pyramid tea bags, specialty herbal blends, single-origin products, and premium matcha, demonstrating competition beyond conventional black and green tea.
The Organic Tea Market covers tea and herbal infusions produced, processed, packaged, and sold under recognized organic production and certification requirements. The market includes certified organic black, green, white, oolong, herbal, and other tea products across loose-leaf, tea-bag, powder, liquid, and other formats. Commercial activity extends from certified tea estates and processors to importers, blenders, packers, retailers, and online sellers.
Organic tea differs from conventional tea primarily through the production system and certification requirements attached to the organic claim. In major consuming markets, organic status is not simply a branding statement. It requires documented production practices, certification, inspections, controlled handling, and compliant labeling. In the United States, USDA regulations govern organic claims, while the FDA continues to regulate applicable food safety and general labeling requirements.
The commercial importance of organic tea therefore extends beyond consumer preference. Certification creates a controlled value chain in which growers must maintain production records, processors must prevent contamination or mixing, and brand owners must maintain traceability between certified ingredients and finished products. These requirements influence procurement decisions, supplier qualification, inventory management, packaging, and international trade.
Demand is supported by consumers who associate organic certification with controlled agricultural practices, ingredient transparency, and differentiated product quality. However, purchasing decisions also depend on familiar tea varieties, taste, origin, convenience, package size, price, and availability. Organic certification can justify a price premium, but the premium remains constrained when shoppers compare certified products with conventional private-label alternatives.
The market has a broad buyer base. Retail consumers represent the largest demand pool, while specialty tea buyers, health-oriented consumers, hospitality businesses, foodservice operators, and premium grocery shoppers create additional demand. Online channels are particularly relevant for smaller brands because they allow extensive product assortments without requiring nationwide physical distribution.
Product differentiation occurs at several levels. Brands compete through tea origin, cultivar, flavor profile, certification status, leaf grade, blending expertise, packaging, ethical sourcing credentials, and preparation convenience. A specialist loose-leaf seller can therefore compete without matching the distribution footprint of a major packaged-tea company.
Supply conditions remain closely connected to agricultural output. Organic tea production requires suitable land management, certification, pest and disease control, segregation from non-organic production, and consistent post-harvest handling. Climate variability adds another procurement consideration because tea quality and harvest volumes depend on weather conditions in producing regions.
India illustrates the scale of the underlying organic agricultural infrastructure. APEDA reports that NPOP-certified organic and in-conversion cultivated area totaled approximately 3.96 million hectares in 2024–25, alongside 2.26 million hectares of certified wild collection area. Organic exports reached approximately US$666 million during the period.
The tea supply chain is also becoming more attentive to traceability and certification integrity. China introduced a revised organic-product certification implementation framework effective January 1, 2026, strengthening requirements around certification activities and post-certification management.
Japan provides another example of certification-led market structure. Under Organic JAS, certified operators can use the Organic JAS logo, while organic claims on covered agricultural and processed products require compliance with the relevant JAS framework. Revised standards for organic products of plant origin became effective January 1, 2025.
Consequently, the commercial opportunity in organic tea is determined by more than the volume of tea consumed. Suppliers must balance certified raw-material availability, certification costs, product quality, packaging requirements, retail margins, logistics, and consumer willingness to pay.
Market Drivers
Expansion of Health- and Ingredient-Conscious Purchasing
Organic tea benefits from consumers who increasingly examine agricultural practices, ingredient lists, certification marks, and sourcing information before purchasing packaged beverages. The mechanism is straightforward: organic certification provides a recognizable third-party signal that reduces uncertainty around how agricultural ingredients were produced.
For brands, certification can support differentiation when the underlying product category has limited physical differentiation. A conventional black tea and an organic black tea may use similar processing technology, but certification changes the product's positioning and procurement requirements.
Retail buyers also benefit from a clearer premium proposition. Certified organic products can occupy dedicated shelf sections or premium tea ranges, enabling retailers to increase assortment breadth without creating an entirely new beverage category.
The commercial implication is that organic certification increasingly functions as a product attribute rather than merely an agricultural production method. Suppliers able to combine certification with reliable taste, consistent supply, and competitive packaging are better positioned to secure repeat purchasing.
Growth of Premium and Specialty Tea Consumption
Premiumization supports organic tea because specialty buyers tend to place greater importance on origin, processing method, leaf quality, flavor, and production practices. This is especially relevant for loose-leaf tea, single-origin products, white tea, oolong, specialty green tea, and premium herbal blends.
Arbor Teas, for example, maintains a portfolio spanning black, green, white, oolong, herbal products, and specialty origins, while emphasizing organic and Fair Trade certification during product selection.
This purchasing model creates room for higher-value products. Buyers are not selecting tea solely on price per gram; they also assess origin, flavor complexity, preparation experience, certification, packaging, and ethical sourcing.
For suppliers, the implication is a shift toward portfolio segmentation. A single brand can serve mainstream demand through tea bags while using loose-leaf or single-origin products to target higher-value consumers.
Greater Availability of Convenient Organic Formats
Convenience is an important bridge between organic positioning and mainstream consumption. Tea bags, pyramid bags, individually wrapped servings, instant or powdered products, and ready-to-drink formats reduce the preparation effort associated with tea consumption.
This trend expands the addressable consumer base because organic tea does not need to remain a specialist loose-leaf purchase. Davidson's Organics' May 2025 introduction of 17 Pyramid Tea blends illustrates how an established organic tea company can extend an assortment into a convenient format while retaining black, green, herbal, and wellness-oriented products.
For retailers, convenient formats simplify merchandising and inventory management. For consumers, they reduce the preparation barrier. For manufacturers, standardized formats also allow more predictable portioning and packaging economics.
Retail and E-Commerce Assortment Expansion
Organic tea has benefited from the ability of online retailers and direct-to-consumer brands to maintain broader assortments than conventional supermarket shelves can accommodate.
Specialist companies can sell multiple origins, seasonal products, decaffeinated variants, herbal infusions, loose-leaf products, and gift formats without requiring each SKU to receive extensive physical shelf space.
This model is commercially important for smaller suppliers. Instead of competing directly for supermarket distribution from the beginning, brands can establish demand through direct online sales and specialty channels, collect customer feedback, and then use proven products to approach larger retailers.
The channel strategy also supports premium pricing because online product pages can provide detailed origin, certification, preparation, and sourcing information that is difficult to communicate on a small retail shelf.
Strengthening Traceability and Certification Infrastructure
Organic certification systems are becoming more structured, creating stronger incentives for suppliers to maintain documentation and traceability throughout the supply chain.
India's NPOP framework covers organic production standards, certification-body accreditation, operator inspection and certification, grower-group certification, and use of the India Organic logo. APEDA also operates TraceNet infrastructure for organic certification information.
China's revised rules similarly strengthen certification governance and post-certification oversight. In 2026, China's market regulator also reported the results of 2025 organic-product certification validity inspections covering tea and related products among other categories.
These systems increase compliance obligations, but they also reduce uncertainty for buyers. Importers and retailers can place greater value on suppliers capable of producing verifiable certification records and maintaining product integrity.
Market Restraints and Challenges
Higher Production and Certification Costs
Organic tea generally requires more intensive compliance management than conventional tea. Certification involves inspections, documentation, approved production inputs, segregation procedures, and ongoing monitoring.
The cost burden affects growers most directly, particularly smaller farms that lack economies of scale. Processors and exporters also incur costs related to separate handling, documentation, testing, storage, and certification maintenance.
These expenses can raise the final shelf price. If consumers are unwilling to sustain the premium, retailers may reduce shelf space or demand lower supplier margins.
Mitigation depends on grower-group certification, longer-term procurement relationships, efficient certification management, and greater production scale. India's NPOP framework specifically recognizes grower-group certification, providing a mechanism that can reduce administrative barriers for groups of producers.
Limited Availability of Consistent Organic Raw Material
Organic tea supply is geographically concentrated, while demand exists across multiple importing markets. This creates potential mismatches between required quality, origin, certification, and available volumes.
A brand may require a specific flavor profile or leaf grade but find that certified supply is unavailable in the necessary quantity. Substitution can affect taste consistency, product positioning, and customer expectations.
The problem is more pronounced for specialty teas where production volumes are naturally limited. Suppliers therefore need diversified sourcing networks rather than relying on a single estate or producing region.
Climate and Agricultural Supply Risks
Tea remains an agricultural commodity, making organic tea vulnerable to weather variability, pest pressure, rainfall changes, and temperature conditions.
Organic production can face additional constraints because producers must comply with permitted production inputs and organic-management requirements. A supply disruption can therefore affect both physical availability and procurement costs.
Brands with fixed retail prices may absorb part of the cost increase, reducing margins. Alternatively, they may reformulate blends, change origins, reduce package sizes, or adjust prices.
Long-term supplier relationships, diversified sourcing, agronomic support, and better production planning can reduce exposure, but they cannot eliminate agricultural risk.
Certification and Labeling Complexity Across Markets
Organic tea sold internationally may need to comply with different certification and labeling regimes. The United States, European Union, United Kingdom, Japan, India, and China maintain distinct regulatory structures.
The European Union requires certified organic products to meet defined production and processing conditions, while pre-packaged EU organic foods generally carry the EU organic logo and related control-body and agricultural-origin information.
The United Kingdom requires certification through approved organic control bodies for operators producing, preparing, storing, importing, exporting, marketing, or selling organic products.
For multinational suppliers, these differences increase regulatory administration. Packaging artwork, certification records, import documentation, and product claims may need market-specific management.
Major Segment Analysis
By Form: Tea Bags
Tea bags represent a commercially important form because they combine organic positioning with convenience and standardized preparation. Their relevance extends beyond traditional mass-market tea because premium brands increasingly use larger pyramid or full-leaf bags to deliver a more specialty-oriented experience.
The format addresses several buyer requirements simultaneously. Consumers receive controlled portions, consistent preparation, easy storage, and minimal cleanup. Retailers benefit from compact packaging and predictable unit sales. Manufacturers benefit from standardized filling, packaging, and distribution processes.
Bigelow's organic portfolio illustrates the breadth of this format. Its organic range includes black, green, oolong, and herbal products in conventional and full-leaf tea-bag formats, with products marketed as meeting USDA Organic standards.
Davidson's 2025 Pyramid Tea launch further demonstrates the role of upgraded tea-bag formats. The company introduced 17 blends following its acquisition of White Lion Tea formulations and packaging formats, offering products in both loose-leaf and pyramid tea-bag configurations.
The competitive advantage of premium tea bags lies in the combination of convenience and perceived product quality. Conventional small-cut tea bags compete primarily through price and familiarity, whereas premium organic pyramid formats can emphasize larger leaf particles, specialty ingredients, flavor complexity, and certification.
For procurement teams, tea bags also create more predictable SKU economics. Portioning is standardized, package counts are clear, and retail merchandising is straightforward. However, packaging costs are higher than bulk loose-leaf formats because every serving requires additional material and processing.
The form therefore remains commercially relevant as organic tea moves beyond specialist buyers. Its strongest opportunity lies in premium convenience, where certification, flavor, package design, and ingredient quality can support a higher selling price without requiring consumers to change their preparation habits.
Regional Analysis
North America
North America represents an important market for certified organic tea because organic labeling is supported by established regulatory infrastructure and extensive retail distribution.
In the United States, USDA's National Organic Program governs organic claims, while FDA requirements continue to apply to relevant food labeling and safety matters.
Consumer purchasing occurs across supermarkets, natural and specialty stores, direct-to-consumer websites, and major online marketplaces. The competitive structure includes established tea companies and specialist organic brands.
Product breadth is an important commercial factor. Bigelow offers organic black, green, oolong, and herbal products, while Arbor Teas maintains a broad organic loose-leaf portfolio across multiple origins.
The principal constraints are price sensitivity, certification costs, and competition from conventional premium tea. Canada and Mexico provide additional regional opportunities, although regulatory and distribution requirements differ.
Europe
Europe has a mature organic food regulatory framework and strong consumer familiarity with certification logos. The EU organic logo is compulsory for most pre-packaged organic products produced and sold as organic within the EU, provided the applicable conditions are satisfied.
This regulatory structure benefits transparent suppliers because certification becomes visible at the point of purchase. Retailers can organize organic tea assortments around recognizable certification credentials.
The United Kingdom operates under its own organic control framework following its departure from the EU regulatory system. Operators handling organic food must use approved control bodies, while imports require additional certification procedures.
European buyers generally place strong emphasis on certification, origin, environmental attributes, packaging, and product quality. Suppliers therefore face high compliance expectations but also access consumers familiar with organic products.
Asia Pacific
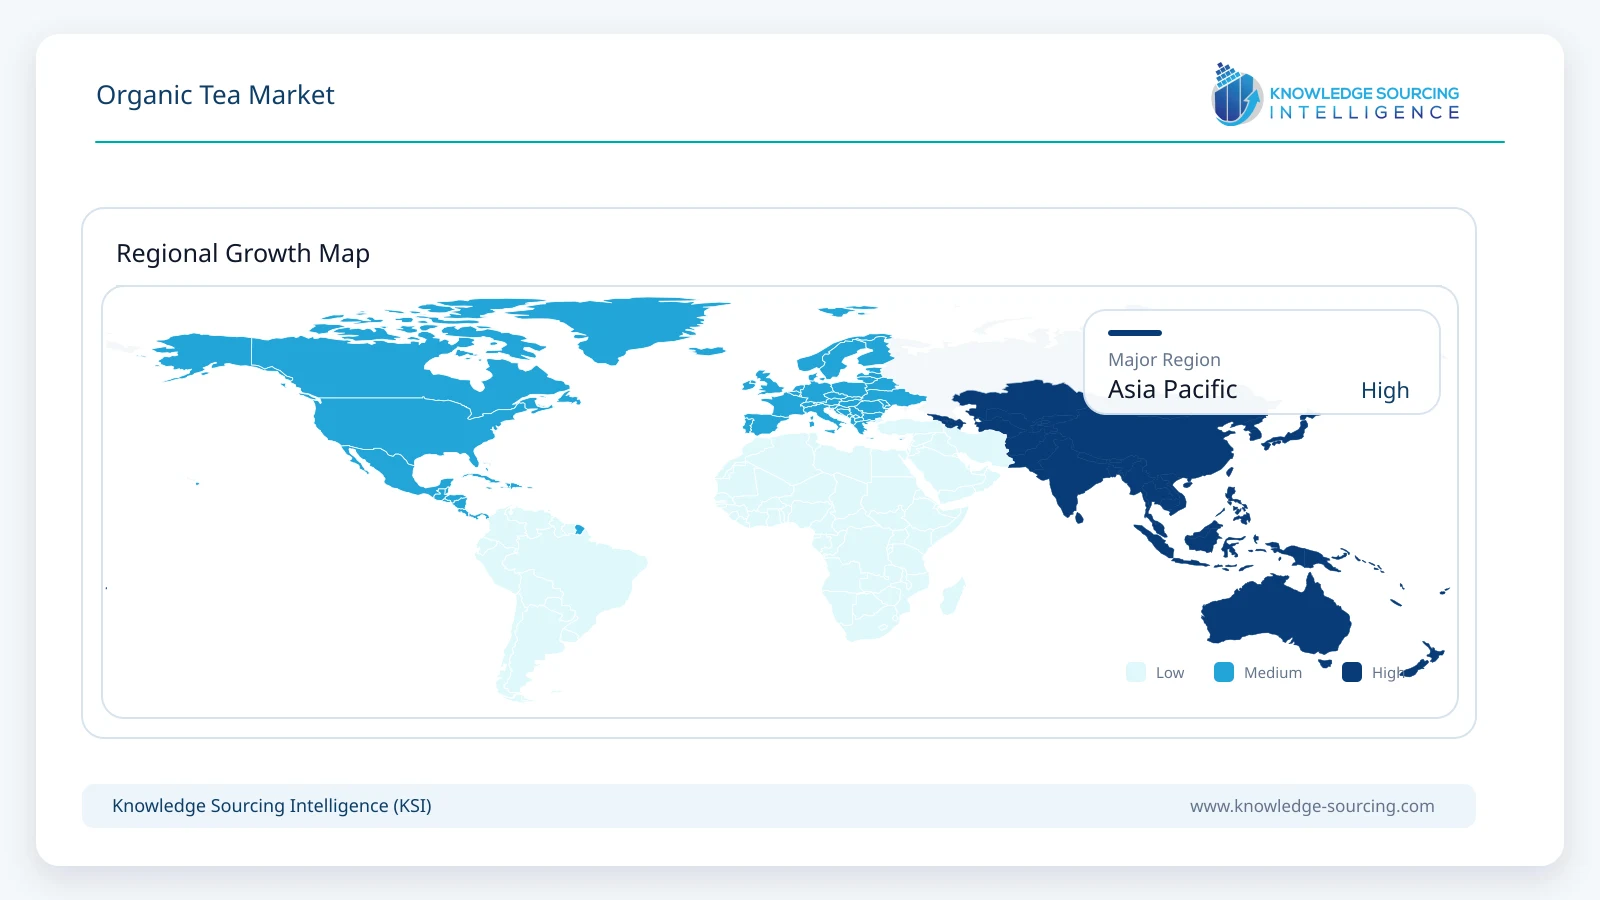
Asia Pacific combines some of the world's largest tea-producing economies with major domestic tea-consuming populations. China and India are particularly important to the supply base, while Japan, Australia, South Korea, and other markets provide premium consumption opportunities.
India's organic certification infrastructure supports domestic and export supply through NPOP. APEDA reports substantial certified production and export activity and identifies tea-producing states among the country's organic agricultural base.
China is particularly important because of both its tea production capacity and regulatory influence. The revised organic certification implementation rules effective from January 2026 strengthen certification and post-certification requirements.
Japan represents a highly structured premium market. Organic JAS certification controls the use of organic claims, while revised standards for organic plant products became effective in January 2025.
Australia provides another premium market where organic brands can compete through provenance, ethical sourcing, and specialty blends. Tielka's portfolio demonstrates the positioning of certified organic black, white, oolong, and herbal products in the Australian market.
Middle East and Africa
Middle East and Africa demand is supported by premium imported tea, established tea-drinking cultures, tourism and hospitality activity, and expanding modern retail.
South Africa has an established specialty beverage market and tea production base, while Gulf markets depend heavily on imported food and beverage products. Organic tea suppliers therefore compete on certification, international brand recognition, origin, packaging, and product assortment.
The principal challenge is price sensitivity outside premium consumer segments. Imported certified organic tea can carry additional certification, logistics, and distribution costs, making mainstream adoption more difficult.
South America
South America presents a mixed opportunity. Brazil and Argentina have established beverage markets, while several countries possess agricultural conditions suitable for specialty tea and herbal products.
The region's opportunity is stronger for differentiated products than for purely price-driven organic tea. Specialty retailers, premium supermarkets, online channels, and health-oriented consumers can support higher-value products.
Currency volatility, logistics, certification requirements, and uneven retail infrastructure can constrain expansion. Suppliers entering the region therefore benefit from local distribution partners and carefully selected premium SKUs rather than excessively broad portfolios.
Competitive Landscape
The Organic Tea Market includes multinational tea companies, specialist organic brands, regional processors, specialty retailers, and vertically integrated tea businesses. The competitive model is fragmented because companies can differentiate through sourcing and product specialization without requiring comparable production scale.
The companies covered in this market include Arbor Teas, Bigelow Tea, Davidson's Organics, Guangzhou Runming Tea Co., Ltd., The Hain Celestial Group, Inc., LIPTON Teas and Infusions, The Bombay Burmah Trading Corporation, Numi Organic Tea, Tielka, and Little Red Cup Tea Co.
Competition occurs across several dimensions. Large tea companies benefit from distribution reach, procurement scale, brand familiarity, and retail relationships. Specialist companies compete through organic credentials, origin transparency, loose-leaf expertise, limited-batch products, specialty blends, and direct customer relationships.
Arbor Teas illustrates a specialist model built around organic certification, loose-leaf products, Fair Trade sourcing, and sustainable packaging.
Bigelow demonstrates how organic products can be integrated into a broader tea portfolio while covering black, green, oolong, and herbal formats.
Davidson's has expanded its format strategy through pyramid tea bags while retaining loose-leaf products and a broad organic assortment.
Tielka emphasizes certified organic sourcing, specialty teas, single-origin products, and premium presentation. Its current portfolio includes 2025-harvest white tea and organic matcha products.
LIPTON Teas and Infusions represents a large-scale industry participant with a broad sustainability program. Its 2025 sustainability report, published in May 2026, describes work across health and well-being, social impact, environmental impact, climate-smart agriculture, research, and operational systems.
The competitive direction is therefore not based solely on organic certification. Certification increasingly acts as the entry requirement, while differentiation comes from taste, origin, format, packaging, sourcing transparency, retail access, and brand credibility.
Recent Developments
July 2026: Celestial Seasonings expanded its Anytime Wellness collection with Prebiotic Blend, Stomach Soother, and Throat Soother functional herbal teas, adding new wellness-focused formulations to its tea portfolio.
May 2026: LIPTON Teas and Infusions published its 2025 sustainability report, reporting progress in climate-smart agriculture, tea-specific agricultural research, environmental initiatives, and broader sustainability management.
April 2026: Evolution Fresh expanded its Organic Tea portfolio into select Whole Foods Market locations nationwide, offering four USDA-certified organic ready-to-drink tea and cold-pressed juice blends.
March 2026: Numi Organic Tea introduced its new organic Latte Powders, including Masala Chai and Turmeric Spice, using finely milled organic tea, spices, and plant-based ingredients.
January 2026: Traditional Medicinals launched Organic Stress Soother™ Tension Relief Tea in Canada, replacing its earlier cinnamon blend with skullcap, spearmint, lemon myrtle, and lemon verbena.
September 2025: China's National Certification and Accreditation Administration issued revised Organic Product Certification Implementation Rules, with the new framework taking effect January 1, 2026 and strengthening certification and post-certification management.
Regulatory and Policy Environment
Organic tea is regulated primarily through organic production and labeling frameworks rather than through a single global standard. This creates a multi-market compliance structure for companies that source tea internationally and sell finished products across multiple jurisdictions.
In the United States, the USDA National Organic Program establishes requirements for organic production and labeling. The FDA clarifies that it does not regulate the term “organic”; USDA oversees organic claims while FDA requirements remain applicable to food labeling and safety.
The USDA also establishes different organic labeling categories, including “100 Percent Organic,” “Organic,” and products containing specified proportions of organic ingredients.
In the European Union, Regulation (EU) 2018/848 provides the central legislative framework for organic production and labeling, supported by related implementing and delegated regulations. The EU organic logo provides a common identification mechanism for compliant products.
The United Kingdom requires certification by approved organic control bodies for businesses producing, preparing, storing, importing, exporting, marketing, or selling organic products. Organic food labeling generally requires at least 95% organic agricultural ingredients when the product is marketed as organic, alongside other regulatory conditions.
India's NPOP establishes production, accreditation, inspection, certification, grower-group, and labeling requirements. APEDA states that NPOP standards have recognition arrangements with several international markets, including the European Commission and Switzerland for relevant unprocessed plant products, and acceptance by Great Britain.
Japan's Organic JAS framework requires certification by accredited bodies for products carrying the Organic JAS logo. MAFF has also implemented revised organic plant-product standards effective from January 1, 2025.
China introduced a revised organic certification implementation framework effective January 1, 2026. The updated rules increase emphasis on certification procedures, inspection, traceability, and post-certification management. China's 2026 reporting on 2025 organic certification inspections also covered tea and related products, demonstrating regulatory attention to certification validity in the category.
For organic tea suppliers, regulatory compliance therefore affects sourcing, certification expenditure, packaging design, product claims, import procedures, recordkeeping, and market-entry timelines. Regulatory capability is becoming a commercial requirement rather than a back-office function.
Outlook and Strategic Implications
The outlook for the Organic Tea Market will be shaped by the interaction between organic certification, premium tea consumption, convenience, supply reliability, and regulatory scrutiny.
Procurement strategies are likely to place greater emphasis on multi-origin sourcing. Brands that depend on one certified estate or producing region remain exposed to weather, crop quality, certification interruptions, and logistics disruptions. Broader supplier networks can provide greater flexibility, particularly for blended products.
Certification management will also become more important. The expansion of digital records, traceability systems, certification databases, and post-certification inspections increases the value of suppliers with reliable documentation. India's TraceNet infrastructure and China's strengthened certification controls demonstrate the direction of regulatory administration.
Product development will increasingly connect organic certification with convenience and premiumization. Tea bags will remain important for mainstream consumption, while pyramid bags, full-leaf bags, loose-leaf products, specialty matcha, single-origin teas, and functional herbal blends can support higher-value positioning.
Packaging will remain a strategic consideration. Organic tea brands increasingly need to balance barrier performance, shelf life, product protection, regulatory labeling, sustainability expectations, and cost. Packaging changes must not compromise the physical integrity of tea during transportation or introduce unnecessary complexity into certification and supply-chain management.
Retail strategy will become more segmented. Supermarkets and hypermarkets provide scale but demand reliable supply and competitive pricing. Specialty stores allow greater storytelling around origin and production methods. Online retail supports wider assortments and direct communication around certification, preparation, sourcing, and product attributes.
Competitive positioning will increasingly depend on the ability to combine four elements: credible certification, dependable product quality, differentiated sourcing, and efficient distribution. Organic status alone provides limited protection when competing products carry similar certifications.
Companies with established agricultural relationships can strengthen supply security by working more closely with certified growers and supporting agronomic improvements. Brand owners without direct agricultural control may instead need longer-term contracts, diversified supplier portfolios, and stricter incoming-quality specifications.
The main risks through 2031 include agricultural volatility, certification costs, inconsistent organic raw-material availability, international trade friction, consumer price sensitivity, and regulatory divergence between markets. These risks will be particularly relevant for companies attempting to scale internationally.
Strategic opportunities are strongest where organic tea can command a clear reason for purchase. Premium origin, better flavor, convenient formats, transparent certification, sustainable packaging, and specialized blends can create stronger differentiation than an organic claim alone.
The next phase of competition will therefore center on supply-chain credibility and product economics. Companies that can maintain certified supply, control quality, manage regulatory requirements, and deliver convenient products at acceptable price points will have greater scope to expand distribution.
Organic Tea Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1,282.3 million |
| Total Market Size in 2031 | USD 1,740.4 million |
| Forecast Unit | Million |
| Growth Rate | 6.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Form, Packaging, Distribution Channel, Geography |
| Companies |
|
Market Segmentation
By Type
By Form
By Packaging
By Distribution Channel
By Geography
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies, Certifications, and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. ORGANIC TEA MARKET ANALYSIS, BY TYPE
5.1. Introduction
5.2. Black
5.3. Green
5.4. White
5.5. Oolong
5.6. Herbal
5.7. Others
6. ORGANIC TEA MARKET ANALYSIS, BY FORM
6.1. Introduction
6.2. Loose Leaf
6.3. Tea Bags
6.4. Powder
6.5. Liquid
6.6. Others
7. ORGANIC TEA MARKET ANALYSIS, BY PACKAGING
7.1. Introduction
7.2. Paper Pouches
7.3. Cartons
7.4. Cans and Tins
7.5. Paper-Based Packaging
7.6. Others
8. ORGANIC TEA MARKET ANALYSIS, BY DISTRIBUTION CHANNEL
8.1. Introduction
8.2. Supermarkets and Hypermarkets
8.3. Convenience and Grocery Stores
8.4. Specialty Stores
8.5. Online Retail
8.6. Others
9. ORGANIC TEA MARKET ANALYSIS, BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. United Kingdom
9.4.2. Germany
9.4.3. France
9.4.4. Spain
9.4.5. Italy
9.4.6. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. United Arab Emirates
9.5.3. Israel
9.5.4. South Africa
9.5.5. Others
9.6. Asia Pacific
9.6.1. Japan
9.6.2. China
9.6.3. India
9.6.4. Indonesia
9.6.5. South Korea
9.6.6. Thailand
9.6.7. Australia
9.6.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Emerging Players and Market Attractiveness
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Company Competitiveness Matrix
11. COMPANY PROFILES
11.1. Arbor Teas
11.2. Bigelow Tea
11.3. Davidson's Organics
11.4. Guangzhou Runming Tea Co., Ltd.
11.5. The Hain Celestial Group, Inc.
11.6. LIPTON Teas and Infusions
11.7. The Bombay Burmah Trading Corporation
11.8. Numi Organic Tea
11.9. Tielka
11.10. Little Red Cup Tea Co.
Navigate
Trusted by the world's leading organizations











