
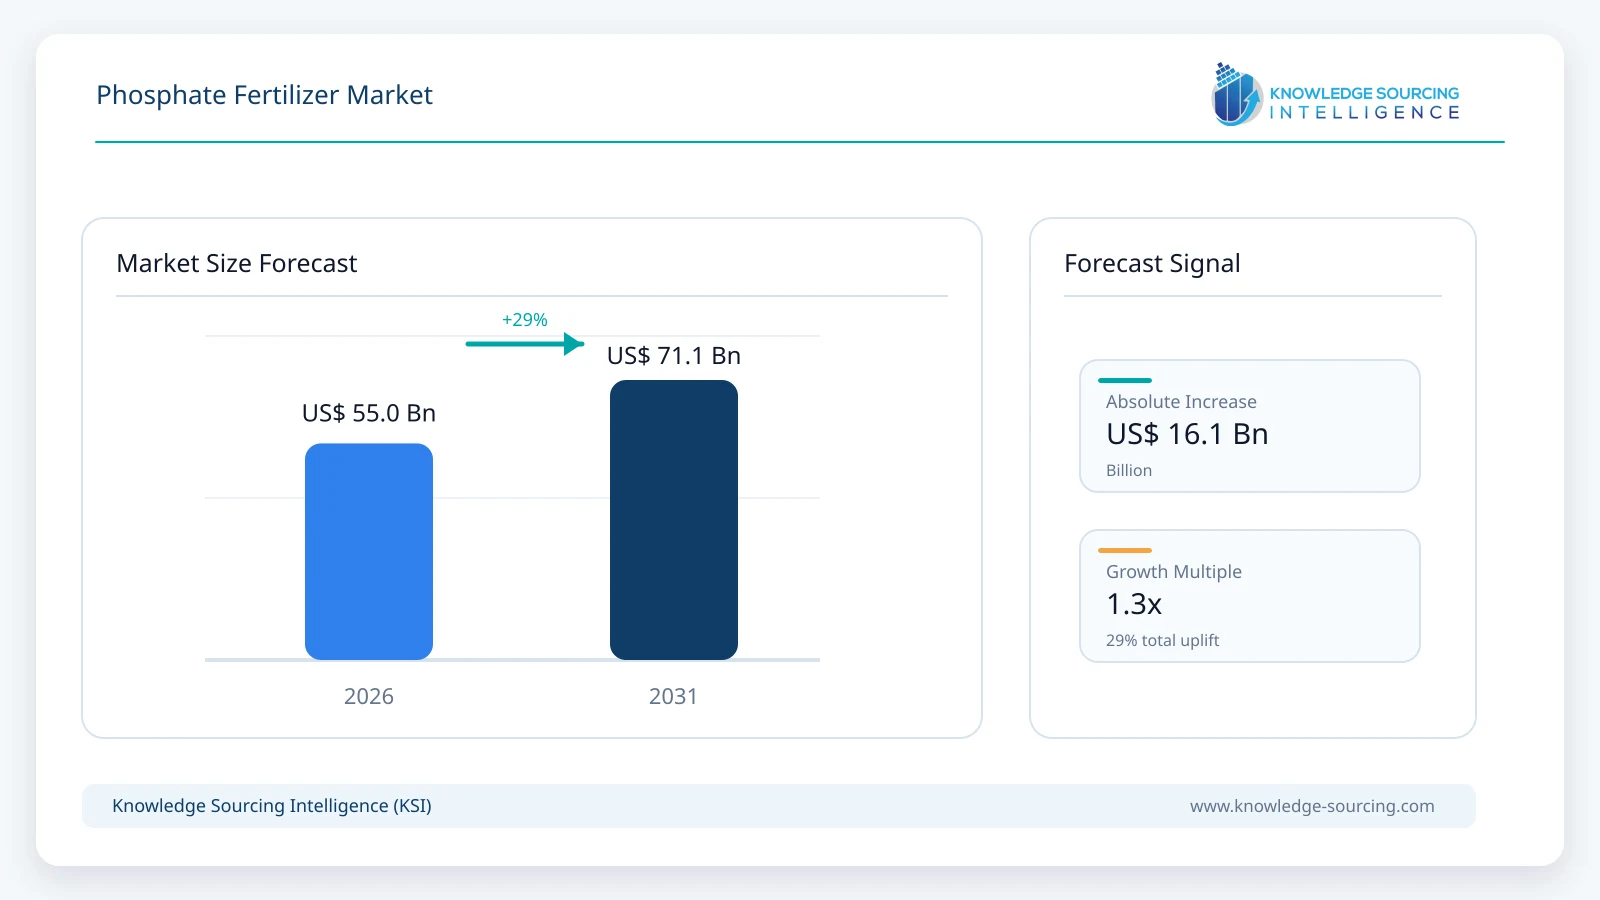
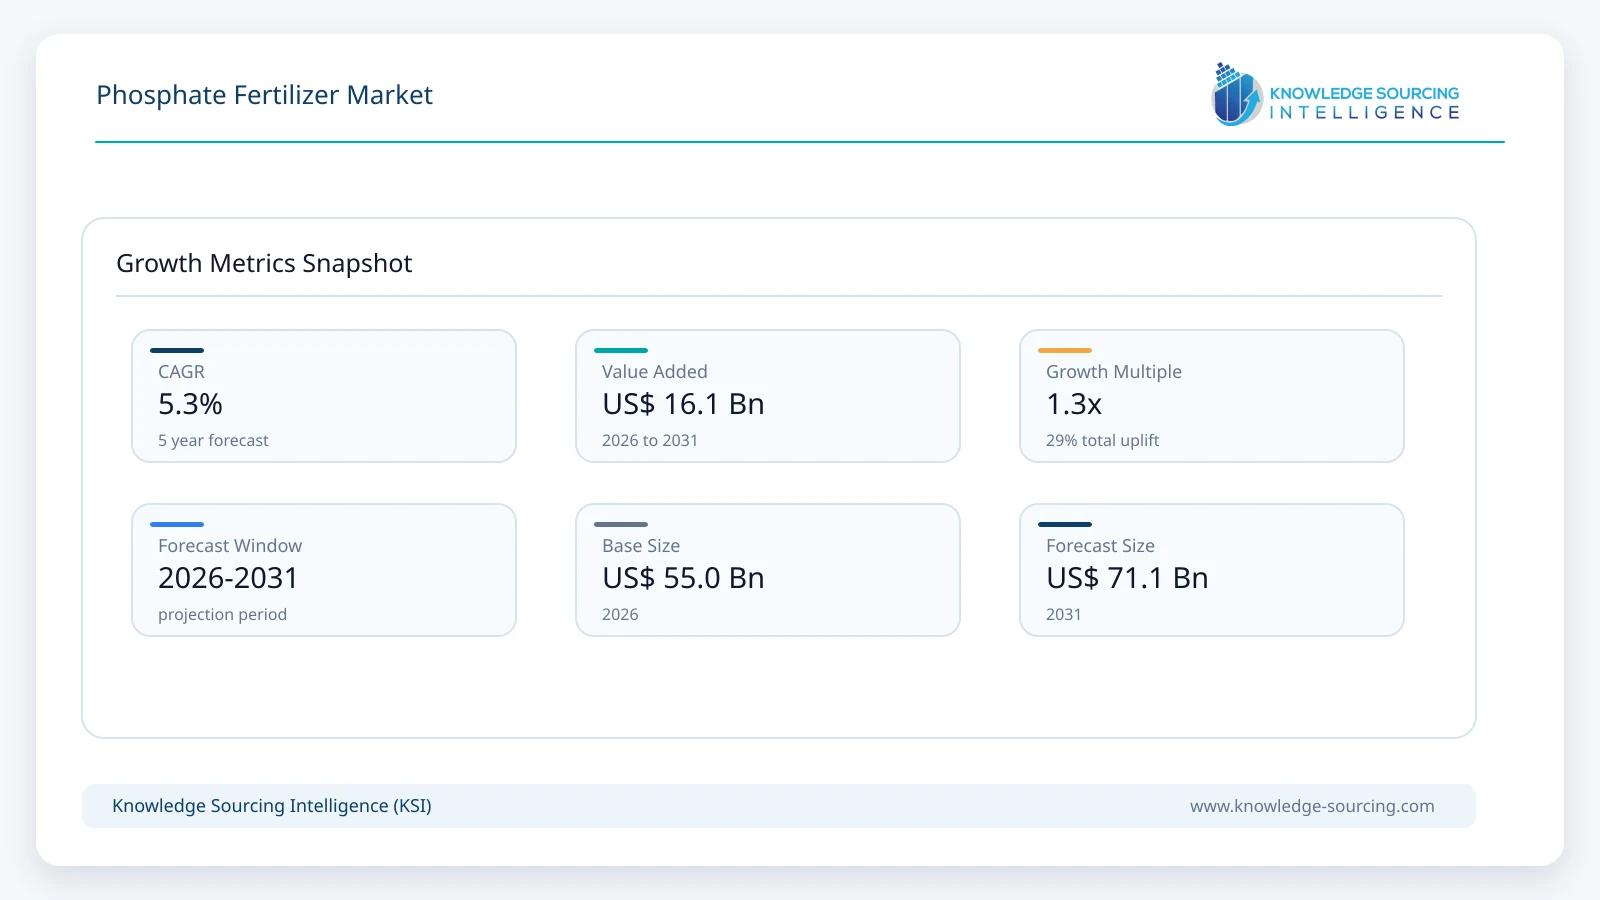
Phosphate Fertilizer Market, growing at a 5.3% CAGR, is projected to achieve USD 71.1 billion in 2031 from USD 55.0 billion in 2026.
Highlights:
- 1Diammonium phosphate accounts for approximately 38% of global phosphate fertilizer revenue in 2026.
- 2Dry formulations represent roughly 88% of global phosphate fertilizer value in 2026.
- 3Asia Pacific contributes approximately 46% of global phosphate fertilizer revenue in 2026.
- 4Phosphorus demand remains more sensitive to fertilizer affordability than nitrogen and potash demand.
- 5Integrated phosphate-rock and phosphoric-acid capacity is becoming a stronger source of supplier advantage.
- 6Export controls, sulfur costs and ammonia availability remain important determinants of phosphate pricing.
Market Overview
Phosphate fertilizers supply phosphorus, one of the three primary macronutrients required for plant development, root formation, energy transfer and reproductive growth. The market includes DAP, MAP, single superphosphate, triple superphosphate and liquid ammonium polyphosphate. Product choice depends on nutrient concentration, crop requirement, soil chemistry, local agronomic practice and delivered cost. DAP and MAP dominate international trade because of their high nutrient density and compatibility with large-scale commodity cropping, while SSP remains important in markets where sulfur and calcium content provide additional agronomic value.
The economics of phosphate fertilizer differ from those of nitrogen because production depends on mined phosphate rock and conversion through phosphoric acid, with sulfur and ammonia as critical inputs for many finished products. This makes integration across mining, acid and fertilizer production strategically important. OCP Group, The Mosaic Company, Ma'aden, PhosAgro, EuroChem and ICL operate significant upstream or integrated phosphate positions, while Coromandel International, IFFCO, Paradeep Phosphates and other regional producers serve large import-dependent agricultural markets.
Market Trends
Integrated phosphate supply chains are becoming more strategically valuable
Producers with control over phosphate rock, phosphoric acid and downstream fertilizer manufacturing are better positioned to manage input volatility and export disruptions. Morocco, Saudi Arabia, Russia and China remain important supply centers, while India continues to rely heavily on imported phosphate rock, phosphoric acid and finished DAP. Coromandel International's phosphoric-acid and sulfuric-acid investment at Kakinada reflects the strategic push toward greater upstream integration in import-dependent markets. The same logic supports large-scale capacity development by OCP and Ma'aden, where access to domestic mineral resources lowers exposure to imported rock and strengthens export competitiveness.
Phosphate demand is becoming more disciplined as affordability influences application rates
IFA's 2026 outlook indicates a more pressured phosphorus demand environment than for nitrogen or potash because farmers are more likely to defer or reduce phosphate application when nutrient affordability deteriorates. Phosphorus can be partially carried in soil reserves from previous applications, giving farmers some flexibility to delay purchases when prices rise sharply. This makes demand more cyclical and can produce slower volume recovery even when crop economics remain supportive. Suppliers are therefore focusing more heavily on efficiency, differentiated formulations and agronomic positioning rather than assuming that nutrient tonnes will expand at a constant rate.
Market Drivers
Crop-yield requirements sustain long-term phosphorus replacement demand
Phosphorus is removed from agricultural soils through harvested crops and must ultimately be replaced to maintain nutrient balance and yield potential. Cereals, oilseeds, pulses, fruits and vegetables all require phosphorus for root development and energy transfer, creating a recurring underlying demand base. Application rates vary according to soil test levels, crop economics and local practice, but sustained high-yield agriculture cannot indefinitely reduce phosphorus inputs without affecting productivity. This structural replacement requirement supports long-term demand even during periods when high prices cause temporary application deferral.
Capacity expansion in Morocco and the Middle East is reshaping global phosphate trade
Large integrated producers are expanding upstream and downstream capacity in resource-rich regions, increasing their influence over future supply growth. Morocco's OCP Group remains one of the world's most important phosphate exporters, while Ma'aden continues expanding Saudi Arabia's phosphate value chain. New integrated capacity can improve global product availability, but it also shifts trade flows toward a smaller group of highly competitive producers with access to low-cost rock resources. Import-dependent markets in South Asia, Latin America and parts of Africa are increasingly sensitive to these changes because domestic fertilizer economics depend heavily on seaborne DAP, MAP or intermediate inputs.
Market Restraint
Poor phosphate affordability can reduce application even when crop demand remains healthy
The principal restraint is the responsiveness of phosphorus use to farmer economics. IFA's 2026 scenarios show steeper potential declines in P2O5 use than in other nutrient categories when affordability worsens. High sulfur, ammonia, and rock costs can raise finished-product prices, while export restrictions or geopolitical disruptions tighten regional supply. Unlike nitrogen, which is frequently required each season, some farms can draw temporarily on residual soil phosphorus, allowing application to be reduced when prices are unfavorable. This creates more volatile purchasing behavior and can delay volume recovery even when global crop production remains strong.
Segment Analysis
By Type - Diammonium Phosphate (DAP)
DAP remains the largest phosphate fertilizer type and is projected to reach approximately USD 26.1 billion by 2031. Its high phosphorus concentration, inclusion of nitrogen and suitability for cereals and broad-acre crops support large-scale use and international trade. India is a major DAP import market, while China, Morocco, Saudi Arabia, Russia and the United States influence global supply. DAP pricing is highly sensitive to ammonia and phosphoric-acid economics, making it more exposed to upstream cost movements than SSP. MAP remains another large high-analysis product and is especially important in the Americas and blended fertilizer systems.
By Form - Dry
Dry phosphate fertilizers are projected to account for approximately 86% of market value by 2031. Granular DAP, MAP, TSP and SSP dominate because they are compatible with bulk handling, storage, blending and conventional field application equipment. Liquid ammonium polyphosphate has an established role in starter fertilizer and precision application, particularly in North America, but represents a much smaller global value pool. Dry products remain central to seaborne trade because their nutrient density and transport economics are better suited to long-distance movement than most liquid formulations.
By Geography - Asia Pacific
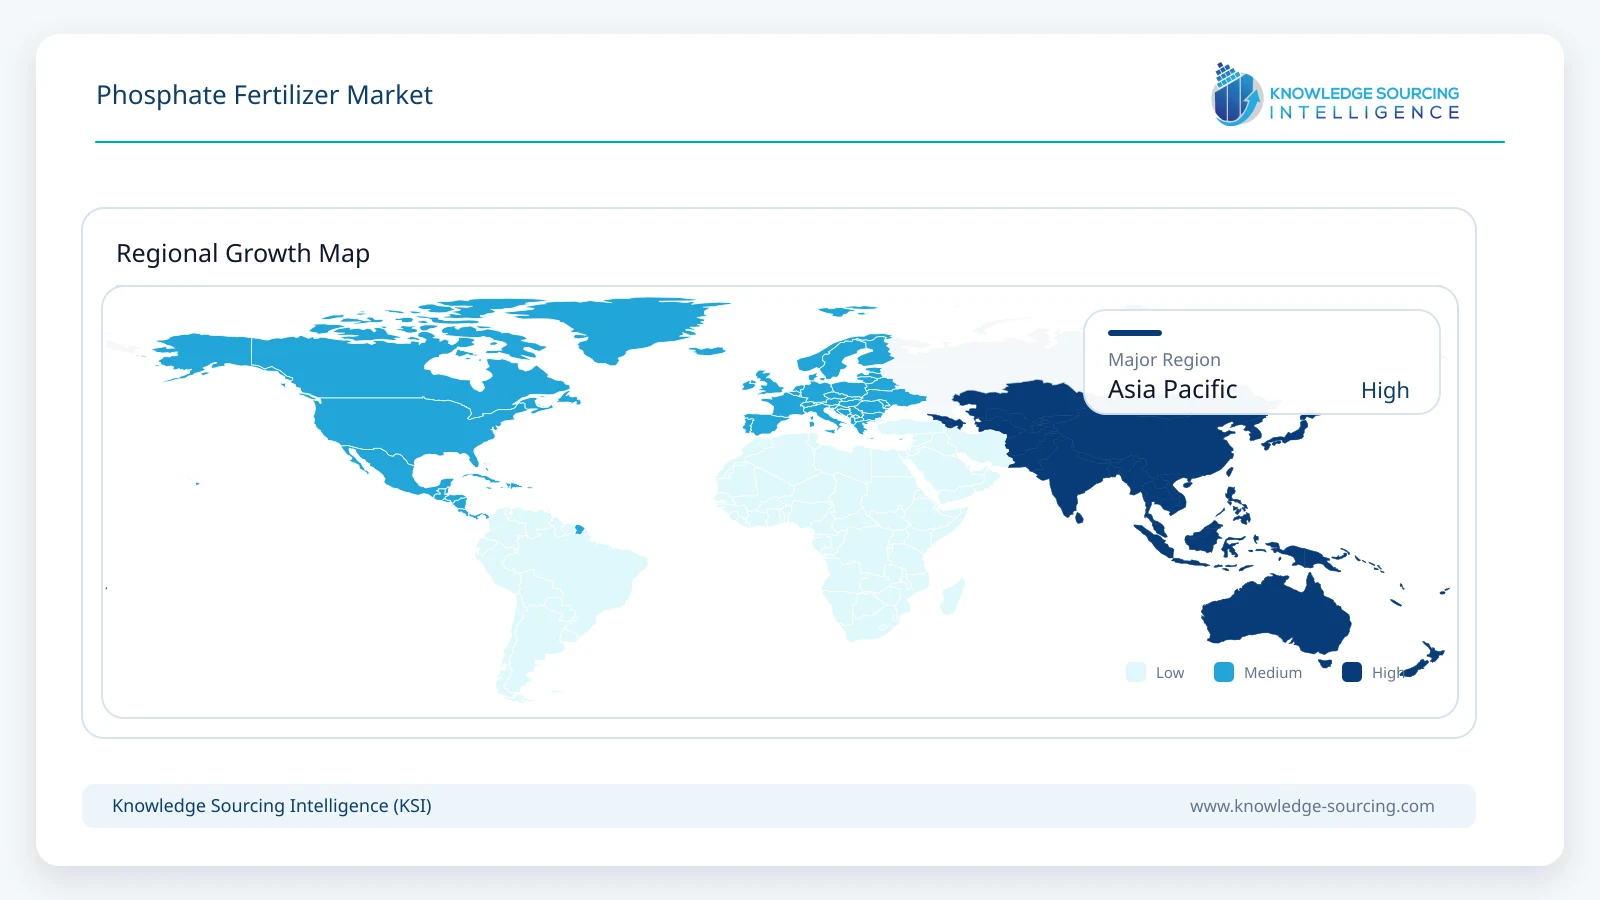
Asia Pacific is projected to reach approximately USD 31.9 billion in phosphate fertilizer revenue by 2031. China and India are the largest regional demand centers, though their supply positions differ sharply: China has a large domestic phosphate industry and periodically influences export availability through trade controls, while India remains substantially dependent on imported DAP, phosphoric acid and phosphate rock. Southeast Asia contributes additional demand from plantation crops, rice and horticulture. The region's large crop-production base keeps it the most important demand center even as phosphorus application growth remains relatively moderate.
Competitive Environment
The phosphate fertilizer industry is concentrated around companies with access to large phosphate-rock resources or integrated phosphoric-acid production. OCP Group, The Mosaic Company, Ma'aden, PhosAgro, EuroChem and ICL are among the most significant global or regional producers. India adds a large downstream market through Coromandel International, IFFCO, Paradeep Phosphates and Chambal Fertilisers, while Jordan Phosphate Mines and Groupe Chimique Tunisien remain relevant in rock, acid and fertilizer exports. Haifa Group and Yara participate more selectively through specialty or compound phosphate products.
Competitive advantage depends on rock quality, sulfur and ammonia sourcing, phosphoric-acid integration, logistics and access to end markets. Integrated exporters can manage conversion economics more effectively than companies dependent on imported intermediates, while downstream producers in large agricultural markets benefit from distribution reach and government-linked subsidy or procurement systems. The result is a market where upstream resource position and downstream market access are equally important.
Recent Developments
May 2026: The International Fertilizer Association published its 2026-2030 outlook, indicating a slower recovery path for global phosphorus use than for other major nutrients.
February 2026: Nutrien reported that phosphate markets strengthened in early 2026 after weaker late-2025 demand, supported by Chinese export restrictions and elevated input costs.
2026: Coromandel International continued development of its phosphoric-acid and sulfuric-acid complex at Kakinada to increase upstream integration for phosphatic fertilizer production.
2026: Major integrated producers continued expanding phosphate mining, phosphoric-acid and finished-fertilizer capacity across Morocco and the Middle East.
Phosphate Fertilizer Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 55.0 billion |
| Total Market Size in 2031 | USD 71.1 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Form, Geography |
| Companies |
|
Market Segmentation
By Type
Diammonium Phosphate (DAP)
Monoammonium Phosphate (MAP)
Single Superphosphate (SSP)
Triple Superphosphate (TSP)
Ammonium Polyphosphate Liquid
By Form
Dry
Liquid
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East And Africa
Saudi Arabia
UAE
Morocco
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Crop-Yield Requirements Sustain Long-Term Phosphorus Replacement Demand
3.1.2. Capacity Expansion in Morocco and the Middle East Is Reshaping Global Phosphate Trade
3.2. Market Restraint
3.2.1. Poor Phosphate Affordability Can Reduce Application Even When Crop Demand Remains Healthy
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. High-Efficiency Phosphate Fertilizers
4.2. Granulation and Coating Technologies
4.3. Phosphoric-Acid Process Improvements
5. PHOSPHATE FERTILIZER MARKET BY TYPE
5.1. Introduction
5.2. Diammonium Phosphate (DAP)
5.3. Monoammonium Phosphate (MAP)
5.4. Single Superphosphate (SSP)
5.5. Triple Superphosphate (TSP)
5.6. Ammonium Polyphosphate Liquid
6. PHOSPHATE FERTILIZER MARKET BY FORM
6.1. Introduction
6.2. Dry
6.3. Liquid
7. PHOSPHATE FERTILIZER MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. USA
7.2.2. Canada
7.2.3. Mexico
7.3. South America
7.3.1. Brazil
7.3.2. Argentina
7.3.3. Others
7.4. Europe
7.4.1. Germany
7.4.2. France
7.4.3. United Kingdom
7.4.4. Spain
7.4.5. Others
7.5. Middle East and Africa
7.5.1. Saudi Arabia
7.5.2. UAE
7.5.3. Morocco
7.5.4. Others
7.6. Asia Pacific
7.6.1. China
7.6.2. India
7.6.3. Japan
7.6.4. South Korea
7.6.5. Indonesia
7.6.6. Thailand
7.6.7. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. OCP Group
9.2. The Mosaic Company
9.3. Ma'aden
9.4. PhosAgro
9.5. EuroChem Group
9.6. ICL Group
9.7. Coromandel International Limited
9.8. Indian Farmers Fertiliser Co-operative Limited (IFFCO)
9.9. Paradeep Phosphates Limited
9.10. Chambal Fertilisers and Chemicals Limited
9.11. Jordan Phosphate Mines Company
9.12. Groupe Chimique Tunisien
9.13. Haifa Group
9.14. Yara International ASA
9.15. Acron Group
9.16. Fertiberia
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations
Navigate
Trusted by the world's leading organizations











