
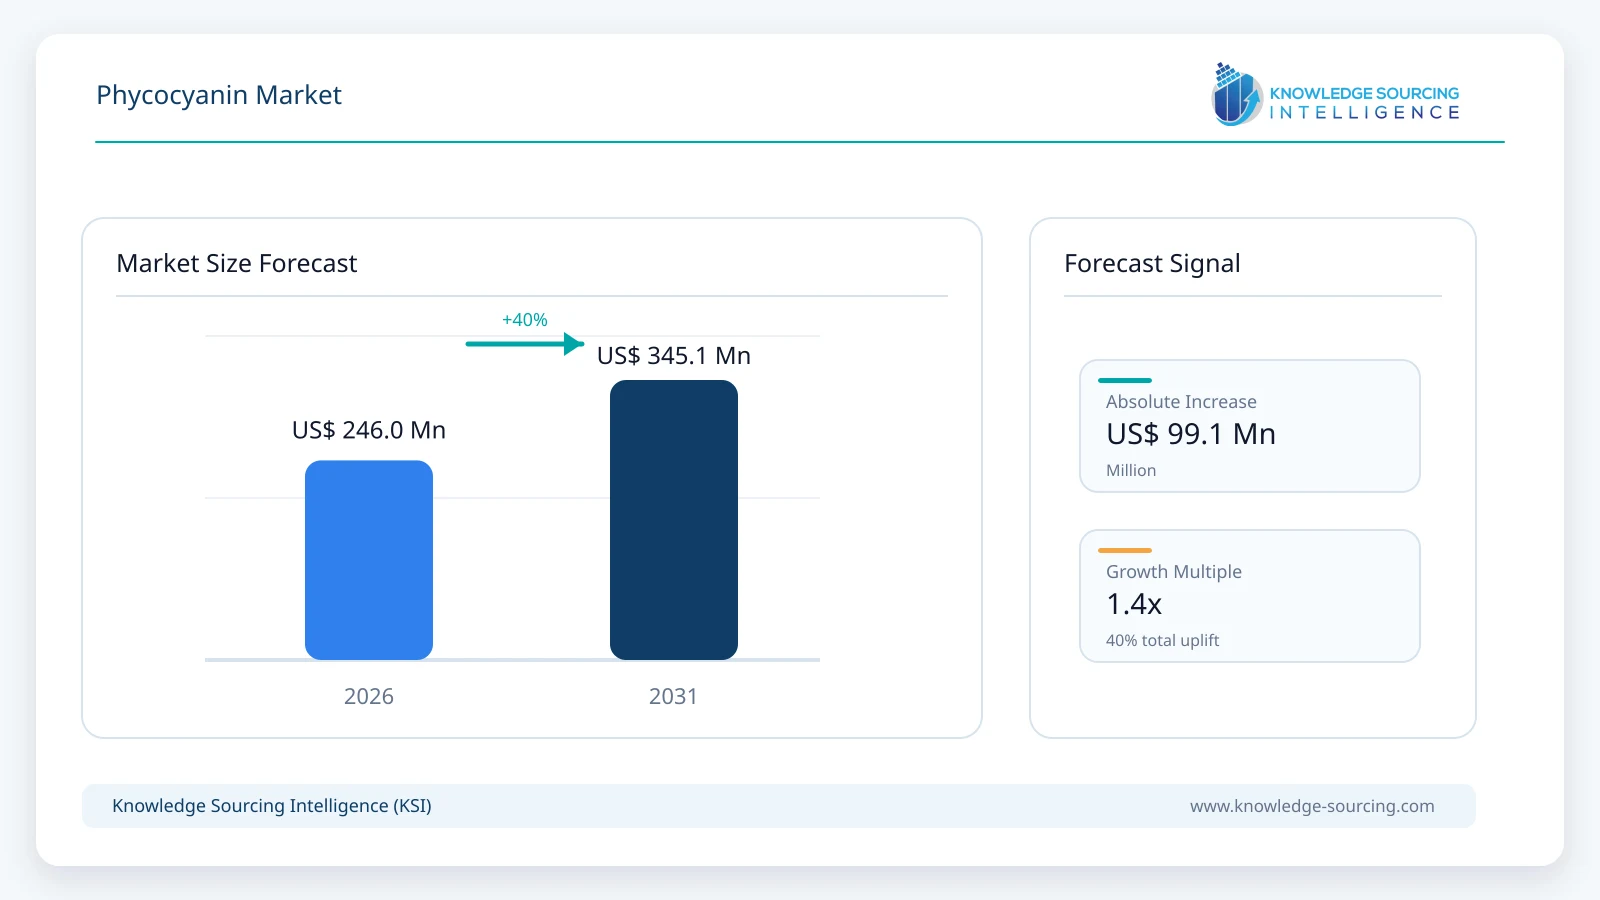
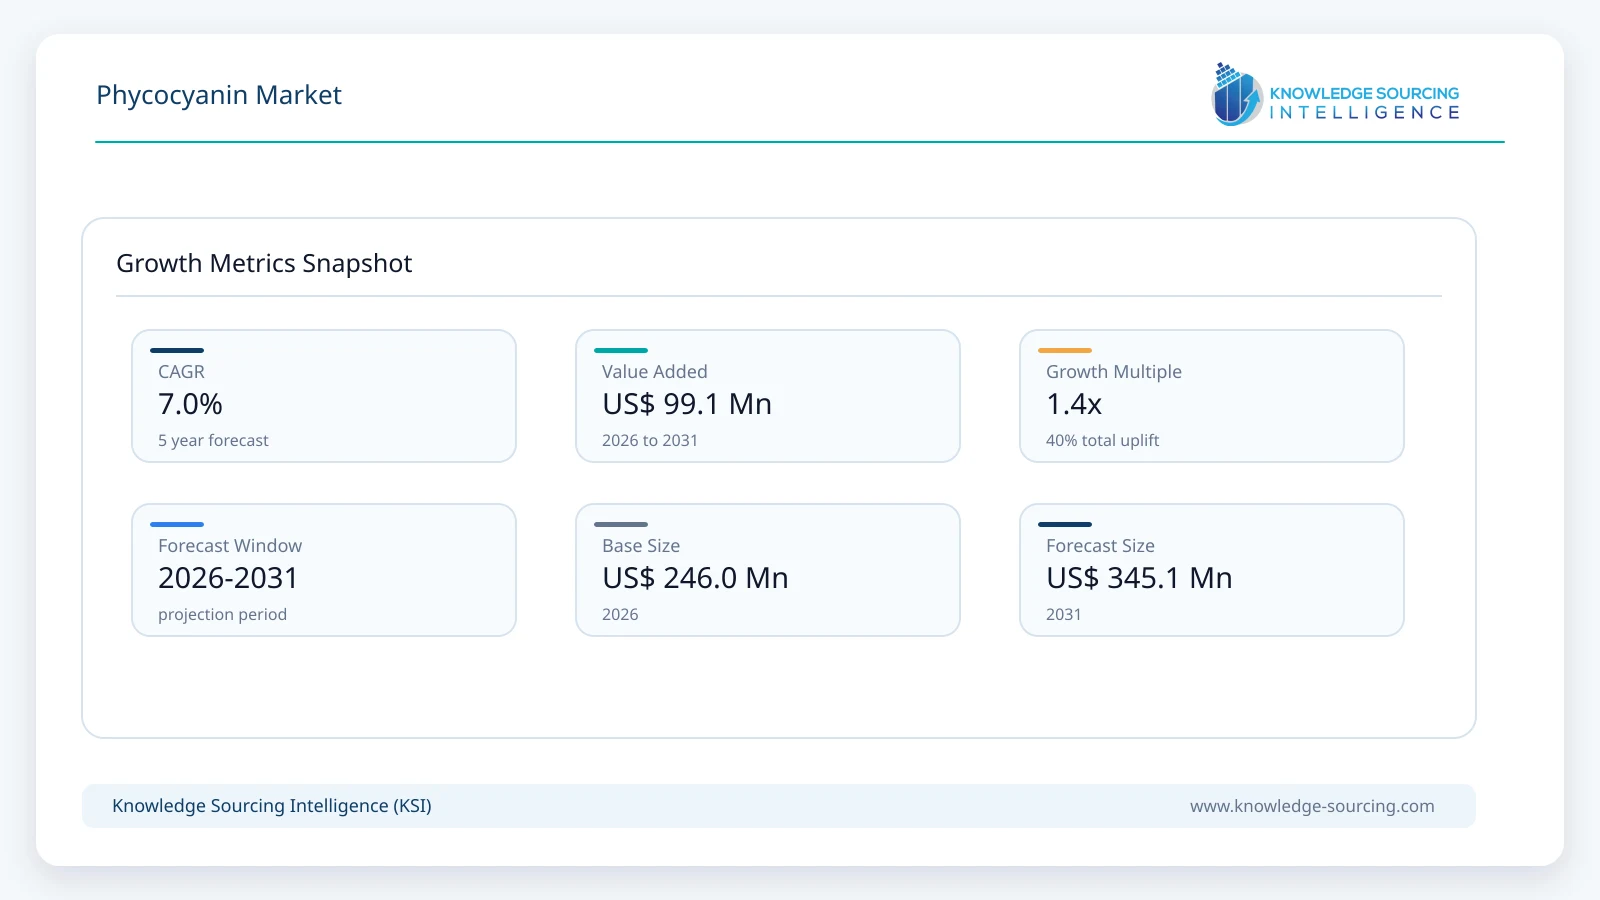
The phycocyanin market is forecast to grow at a CAGR of 7.0%, reaching USD 345.1 million in 2031 from USD 246.0 million in 2026.
Highlights:
- 1The Phycocyanin Market is projected to increase from USD 246.0 million in 2026 to USD 345.1 million by 2031, reflecting steady commercial adoption across food, nutraceutical, and personal care applications.
- 2Food and beverages represent a commercially important application segment, supported by continued replacement of synthetic blue colorants with spirulina-derived phycocyanin in processed foods and beverages.
- 3Dry phycocyanin remains a critical product format for ingredient manufacturers due to longer shelf life, easier transportation, and broader compatibility with industrial formulation processes.
- 4Asia-Pacific serves as a key supply center because of established spirulina cultivation, extraction infrastructure, and growing investments in algae-derived ingredient production capacity.
- 5Natural ingredient sourcing, clean-label product development, and expanding nutraceutical applications are increasing demand for higher-purity phycocyanin grades across multiple end-use sectors.
- 6Competitive activity increasingly focuses on cultivation efficiency, extraction yields, regulatory compliance, and supply-chain integration rather than commodity-scale volume expansion alone.
Market Overview
Phycocyanin is a blue pigment-protein complex extracted primarily from spirulina (Arthrospira species) and used as a natural colorant, nutritional ingredient, and functional bioactive compound. Commercial demand extends across food and beverages, nutraceuticals, personal care products, pharmaceuticals, and animal nutrition applications. Buyers increasingly evaluate phycocyanin not only as a coloring agent but also as an ingredient associated with natural positioning, traceable sourcing, and algae-derived nutrition.
The market growth is supported by the expanding use of natural color systems in food manufacturing, wider commercial acceptance of algae-derived ingredients, and increasing investment in spirulina cultivation and extraction technologies. Demand is distributed across ingredient producers, branded consumer-product manufacturers, contract formulators, distributors, and specialty nutrition companies.
Purchasing behavior differs substantially by application. Food manufacturers prioritize color stability, regulatory acceptance, and batch consistency. Nutraceutical companies place greater emphasis on purity, concentration, traceability, and documented functional characteristics. Personal care manufacturers evaluate ingredient compatibility, formulation stability, and clean-label positioning. These differing requirements have encouraged suppliers to offer multiple grades, concentrations, and delivery formats.
Commercial value is increasingly concentrated around vertically integrated suppliers capable of controlling spirulina cultivation, extraction, purification, quality testing, and downstream distribution. DIC Corporation, through its spirulina operations and LINABLUE® product portfolio, has invested heavily in integrated production capabilities, while other suppliers continue expanding extraction and cultivation capacity to secure supply and improve product consistency.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
|---|---|---|
FDA approval of spirulina-derived blue coloring | Approved since 2013 | Established regulatory acceptance accelerated commercial use in food and beverage formulations. |
Phycocyanin source | Derived primarily from Spirulina (Arthrospira) | Supports natural ingredient positioning and traceable sourcing strategies. |
DIC production investment | US extraction facility expansion and integrated cultivation operations | Reflects supplier commitment to long-term supply security. |
Spirulina food safety certification | FSSC 22000-certified production facilities | Improves supplier qualification among multinational food manufacturers. |
Indian commercialization support | Government-backed C-phycocyanin production initiative in 2026 | Expands future production capacity and regional supply diversification. |
Product applications | Food, nutraceuticals, cosmetics, feed, pharmaceuticals | Supports demand diversification across multiple industries. |
Market Drivers
Replacement of synthetic blue colorants in food manufacturing.
Food manufacturers continue shifting toward naturally sourced colors as product formulations move away from synthetic additives. Spirulina-derived phycocyanin became the first natural blue food color approved by the U.S. FDA in 2013, creating a commercially viable alternative for confectionery, beverages, frozen desserts, and related products. DIC reported substantial increases in demand following regulatory approval and expanded extraction capacity to address growing customer requirements.
Expansion of clean-label food and beverage portfolios.
Large consumer-goods companies increasingly require ingredient transparency and recognizable raw-material sources. Phycocyanin aligns with these objectives because it originates from edible microalgae and supports natural-label claims in many jurisdictions. The resulting demand extends beyond color replacement and increasingly influences product development strategies across beverage, confectionery, and nutritional food categories.
Growth of algae-derived nutraceutical ingredients.
Phycocyanin is gaining attention beyond coloration functions. DIC's healthcare initiatives and commercialization of PHYCONA products demonstrate growing interest in phycocyanin's functional properties, including applications linked to skin health and nutritional supplementation. These developments broaden the market beyond traditional food-color applications and increase opportunities for higher-value product categories.
Investment in spirulina cultivation and extraction capacity.
Supply expansion remains a critical industry theme. DIC has invested in large-scale spirulina cultivation and extraction infrastructure in both the United States and China, while governments and biotechnology companies are supporting new commercial production platforms. India's 2026 government-supported commercialization program for indigenous C-phycocyanin production illustrates growing interest in domestic supply development.
Broadening application base across multiple industries.
Commercial demand increasingly extends into cosmetics, personal care, animal nutrition, and pharmaceutical development. Suppliers continue exploring new uses for phycocyanin, including healthcare and biotechnology applications, reducing dependence on any single end-use sector. DIC's research activities highlight ongoing efforts to identify additional commercial uses for phycocyanin-derived compounds.
Market Restraints and Challenges
Cultivation and extraction costs remain comparatively high.
Commercial phycocyanin production requires controlled spirulina cultivation, harvesting, extraction, purification, and quality assurance processes. These requirements create higher production costs than many conventional food-color alternatives and can limit adoption in highly price-sensitive applications.
Sensitivity to heat, light, and processing conditions.
Phycocyanin stability remains a technical challenge. Scientific evaluations reviewed by EFSA indicate that color degradation can occur under elevated temperatures, prolonged light exposure, and certain pH conditions. These limitations restrict use in some processing environments and require manufacturers to optimize formulation conditions.
Dependence on biological production systems.
Unlike synthetic ingredients manufactured through conventional chemical processes, phycocyanin production depends on biological cultivation systems. Weather conditions, water quality, contamination risks, and cultivation yields can influence production economics and supply availability.
Qualification requirements among multinational buyers.
Food and nutraceutical companies increasingly require extensive quality documentation, certification, traceability records, and ingredient testing before approving suppliers. Smaller producers may face challenges meeting the documentation, auditing, and regulatory requirements imposed by global customers.
Competition from alternative natural blue technologies.
The broader natural-color market continues to evolve. EFSA's recent assessment of blue microalgae-derived extracts highlights ongoing innovation in naturally sourced blue ingredients. Alternative production technologies may increase competitive pressure and influence pricing across portions of the market.
Major Segment Analysis
Food and Beverages
Food and beverages represent the most commercially important application segment because they account for the largest concentration of current commercial demand drivers. Manufacturers increasingly seek naturally sourced blue ingredients for confectionery, beverages, frozen desserts, dairy products, and specialty food products. Regulatory acceptance and consumer preference for recognizable ingredients continue supporting adoption across these categories.
Purchasing decisions in this segment are driven by more than color performance. Buyers evaluate regulatory compliance, batch-to-batch consistency, microbial quality, color intensity, formulation stability, and long-term supply security. Suppliers capable of maintaining integrated cultivation and extraction operations are often better positioned to meet these requirements because they retain greater control over raw material quality and traceability.
Competition within the segment increasingly focuses on application performance. Food manufacturers require color systems that maintain appearance throughout processing, transportation, and shelf life. Suppliers therefore invest in extraction technologies, stabilization techniques, and application support services that improve performance in commercial formulations.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
|---|---|---|
North America | Natural food-color adoption and nutraceutical demand | Regulatory compliance and formulation performance |
Europe | Clean-label product development and food-color reformulation | Strict ingredient approval and specification requirements |
Asia-Pacific | Spirulina production, extraction investment, and ingredient manufacturing | Production-scale economics and quality consistency |
South America | Growing use of natural ingredients in food applications | Supply-chain dependence and limited domestic production |
Middle East & Africa | Emerging specialty food and nutrition demand | Import dependence and market scale limitations |
North America
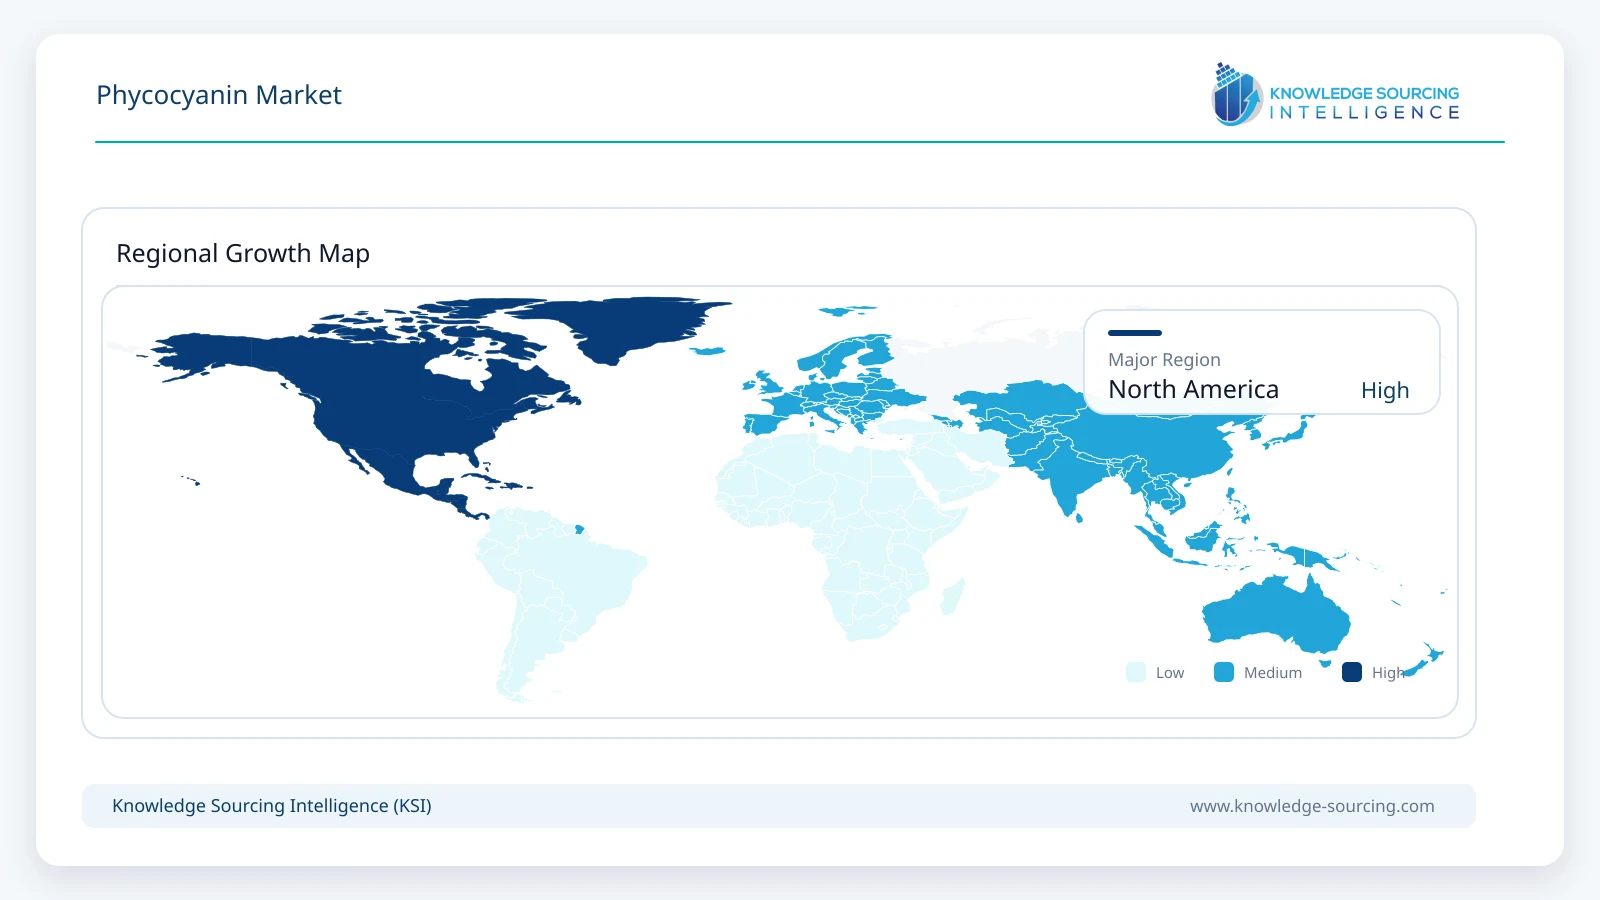
North America remains an important commercial market due to established regulatory acceptance of spirulina-derived blue coloring and widespread use of natural ingredients in food and beverages. The region also benefits from local cultivation and extraction infrastructure associated with DIC's Earthrise operations.
Europe
European demand is driven by stringent ingredient standards and strong interest in natural product formulations. Food manufacturers continue evaluating natural alternatives to synthetic additives, creating opportunities for certified phycocyanin suppliers capable of meeting quality and regulatory requirements.
Asia-Pacific
Asia-Pacific serves both demand and supply functions. China, Japan, India, Taiwan, and other regional markets support spirulina cultivation, extraction activities, and downstream ingredient manufacturing. Government-supported biotechnology initiatives and expanding food industries continue strengthening regional importance.
South America and Middle East & Africa
These regions currently represent smaller but expanding opportunities. Growth is linked to premium food products, dietary supplements, and imported specialty ingredients. Market development depends on distributor networks, regulatory approvals, and customer education regarding natural ingredient alternatives.
Competitive Landscape
The market combines characteristics of both specialty ingredients and biotechnology production. Competitive positioning depends on cultivation expertise, extraction technology, regulatory compliance, quality assurance systems, and distribution reach rather than commodity-scale manufacturing alone.
Companies such as DIC Corporation, Cyanotech Corporation, Far East Bio-Tec Co., Ltd., Bluetec Naturals Co., Ltd., Zhejiang Binmei Biotechnology Co., Ltd., and Tianjin Norland Biotech Co., Ltd. compete through cultivation scale, extraction capabilities, ingredient quality, and application support. DIC maintains a particularly strong position through vertically integrated spirulina cultivation and phycocyanin production operations.
The market also includes biotechnology-focused participants such as Pond Technologies Inc., ScotBio, Phyco-Biotech, and AlgoSource, which emphasize algae production technologies and specialized applications. Companies including Givaudan leverage broader ingredient portfolios and customer relationships to expand market access.
Barriers to entry remain meaningful. New suppliers must establish reliable cultivation systems, achieve regulatory compliance, secure food-safety certifications, demonstrate product consistency, and develop customer trust. These requirements favor companies with established production infrastructure and validated quality systems.
Recent Developments
July 2026: India's Technology Development Board supported commercialization of indigenous C-phycocyanin production technology developed from Spirulina. The initiative aims to reduce import dependence and expand domestic supply capacity.
February 2026: DIC highlighted expansion of sustainable spirulina cultivation capacity supporting LINABLUE® phycocyanin production. The investment reflects continued confidence in natural blue color demand.
2022–2026 Commercial Research Activities: DIC expanded research into additional phycocyanin applications beyond food coloring, including environmental and functional ingredient opportunities. Such diversification broadens future commercialization pathways.
Regulatory and Policy Environment
Regulation remains one of the most influential market factors. FDA approval of spirulina extract as a food color established an important commercial foundation for the industry. U.S. regulations define spirulina extract as a color additive whose principal coloring components are phycocyanins and specify quality requirements regarding impurities and composition.
European authorities continue reviewing algae-derived color technologies and related safety assessments. Regulatory scrutiny extends beyond safety to include purity specifications, manufacturing controls, contaminant limits, and product labeling requirements. Companies serving multinational customers therefore invest heavily in quality systems, analytical testing, and regulatory documentation.
Food-safety certifications also influence purchasing decisions. Certification frameworks such as FSSC 22000 increasingly serve as supplier qualification requirements for large food manufacturers and ingredient buyers.
Outlook and Strategic Implications
The market's growth trajectory is supported by expanding demand for natural blue colorants, increasing commercialization of algae-derived ingredients, and continuing investment in spirulina production infrastructure. Food and beverage applications will remain central to revenue generation, but nutraceutical and personal care opportunities are likely to account for an increasing share of value creation.
Strategic priorities across the industry include:
Expanding cultivation and extraction capacity while maintaining product consistency.
Improving phycocyanin stability across broader food-processing conditions.
Developing higher-purity grades for nutraceutical and pharmaceutical applications.
Strengthening regulatory compliance and food-safety certification programs.
Diversifying applications beyond food coloring into health, wellness, and specialty biotechnology sectors.
Commercial success through 2031 will depend less on volume expansion alone and more on a supplier's ability to combine reliable cultivation, efficient extraction, regulatory compliance, and differentiated application performance. Companies capable of controlling the full value chain from spirulina cultivation through finished ingredient delivery are likely to retain a competitive advantage as customer qualification requirements become more demanding.
Phycocyanin Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 246.0 million |
| Total Market Size in 2031 | USD 345.1 million |
| Forecast Unit | Million |
| Growth Rate | 7.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Nature, Form, Application, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Nature
Conventional
Organic
By Form
Dry
Liquid
By Application
Animal Feed
Food and Beverages
Nutraceuticals
Personal Care
Pharmaceuticals
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
United Arab Emirates
Others
Asia-Pacific
China
Japan
India
South Korea
Indonesia
Taiwan
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits for Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. CXO Perspective
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
4.5. Analyst View
5. PHYCOCYANIN MARKET BY NATURE
5.1. Introduction
5.2. Conventional
5.3. Organic
6. PHYCOCYANIN MARKET BY FORM
6.1. Introduction
6.2. Dry
6.3. Liquid
7. PHYCOCYANIN MARKET BY APPLICATION
7.1. Introduction
7.2. Animal Feed
7.3. Food and Beverages
7.4. Nutraceuticals
7.5. Personal Care
7.6. Pharmaceuticals
7.7. Others
8. PHYCOCYANIN MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. By Nature
8.2.2. By Form
8.2.3. By Application
8.2.4. By Country
8.2.4.1. United States
8.2.4.2. Canada
8.2.4.3. Mexico
8.3. South America
8.3.1. By Nature
8.3.2. By Form
8.3.3. By Application
8.3.4. By Country
8.3.4.1. Brazil
8.3.4.2. Argentina
8.3.4.3. Others
8.4. Europe
8.4.1. By Nature
8.4.2. By Form
8.4.3. By Application
8.4.4. By Country
8.4.4.1. United Kingdom
8.4.4.2. Germany
8.4.4.3. France
8.4.4.4. Italy
8.4.4.5. Spain
8.4.4.6. Others
8.5. Middle East and Africa
8.5.1. By Nature
8.5.2. By Form
8.5.3. By Application
8.5.4. By Country
8.5.4.1. Saudi Arabia
8.5.4.2. United Arab Emirates
8.5.4.3. Others
8.6. Asia-Pacific
8.6.1. By Nature
8.6.2. By Form
8.6.3. By Application
8.6.4. By Country
8.6.4.1. China
8.6.4.2. Japan
8.6.4.3. India
8.6.4.4. South Korea
8.6.4.5. Indonesia
8.6.4.6. Taiwan
8.6.4.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Bluetec Naturals Co., Ltd.
10.2. DIC CORPORATION
10.3. JAPAN ALGAE Co., Ltd.
10.4. Phyco-Biotech
10.5. Pond Technologies Inc.
10.6. ScotBio
10.7. Tianjin Norland Biotech Co., Ltd.
10.8. Zhejiang Binmei Biotechnology Co., Ltd.
10.9. Givaudan
10.10. Cyanotech Corporation
10.11. AlgoSource
10.12. Arthrise Nutritionals LLC
10.13. Nutra Bioactive
10.14. Naturalin Bio-Resources Co., Ltd.
10.15. Far East Bio-Tec Co., Ltd.
LIST OF TABLES
LIST OF FIGURES





Frequently asked questions
What is the projected Phycocyanin market size in 2031?
The Phycocyanin Market is projected to reach USD 345.1 million by 2031.
What is the forecasted CAGR for the Phycocyanin market?
The Phycocyanin market is forecast to grow at a CAGR of 7.0%.
Which application segment is commercially important for Phycocyanin?
Food and beverages represent a commercially important application segment.
Which region serves as a key supply center for Phycocyanin?
Asia-Pacific serves as a key Phycocyanin supply center.
What are key drivers for Phycocyanin market growth?
Natural ingredients, clean-label products, and nutraceutical applications drive growth.
What product format is critical for Phycocyanin ingredient manufacturers?
Dry phycocyanin remains critical for ingredient manufacturers.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Phycocyanin Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/phycocyanin-market