
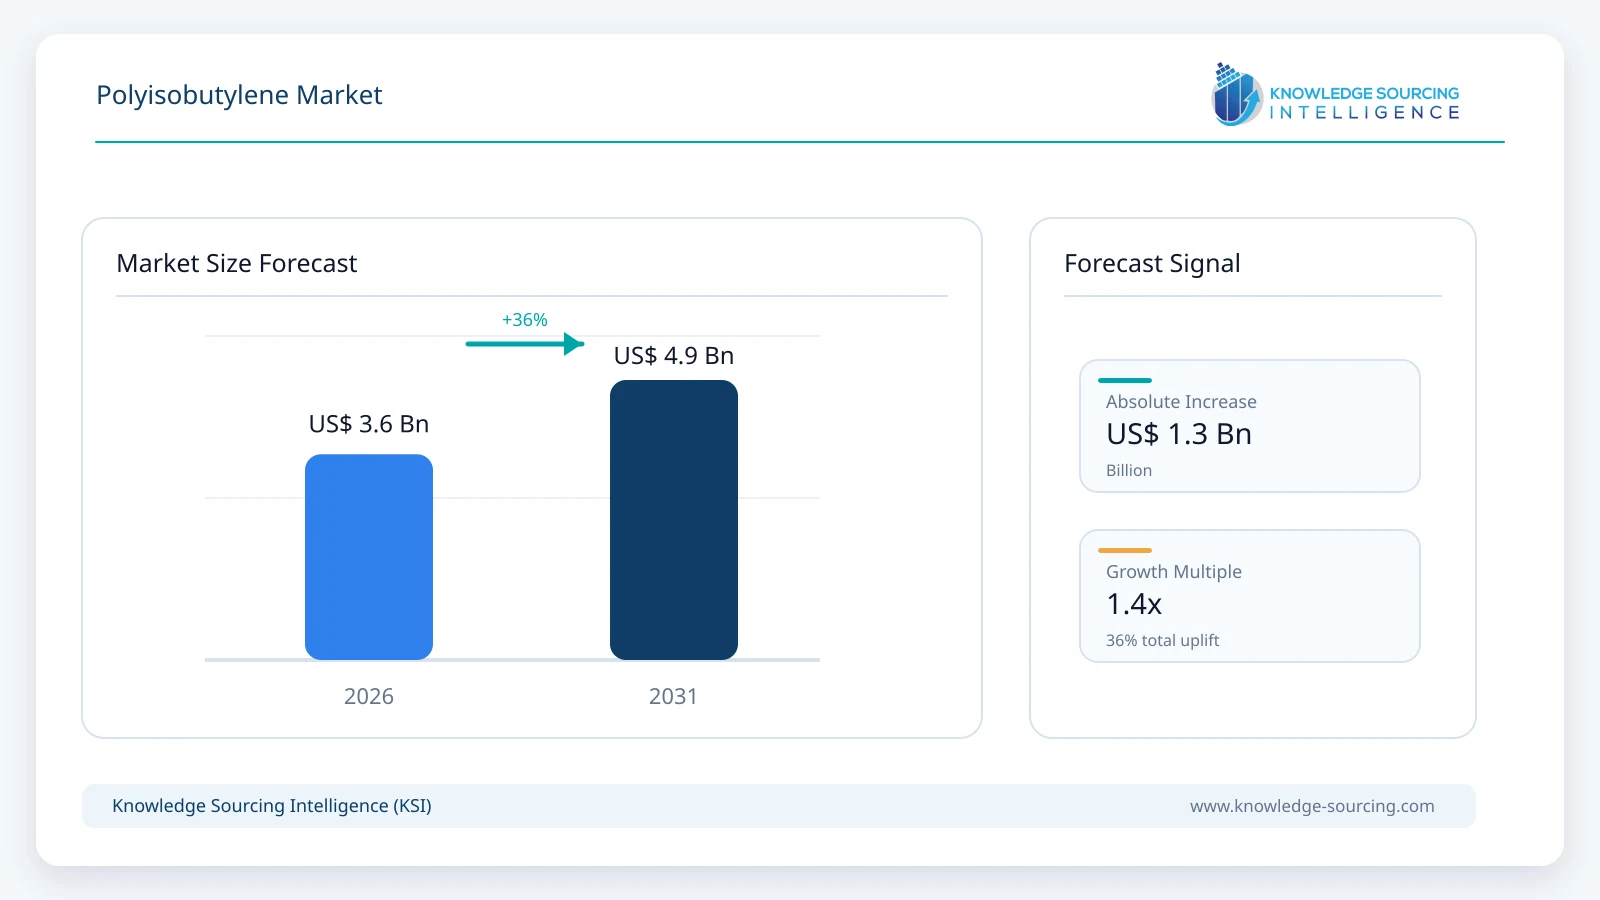
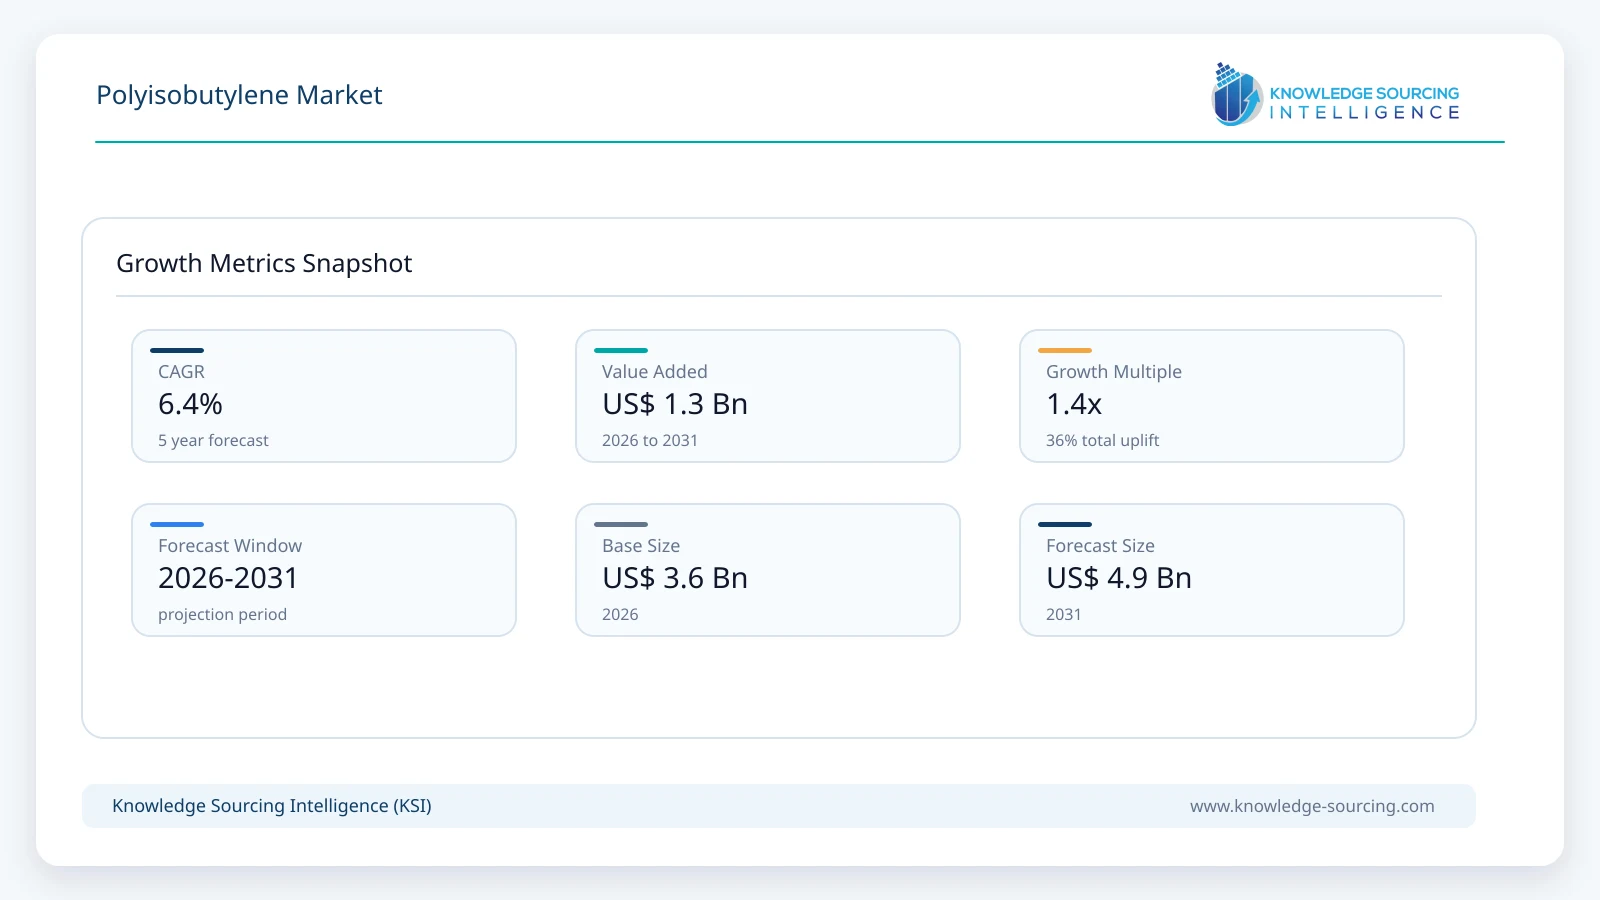
Polyisobutylene Market is expected to grow at a 6.4% CAGR, achieving USD 4.90 billion in 2031 from USD 3.60 billion in 2026.
Highlights:
- 1Low-molecular-weight grades account for approximately 71% of global polyisobutylene revenue in 2026.
- 2Highly reactive PIB is projected to grow at approximately 8.1% annually through 2031.
- 3Lubricant additives generate about USD 1.08 billion of global PIB market value in 2026.
- 4Asia Pacific accounts for approximately 44% of global polyisobutylene revenue in 2026.
- 5Battery binders and functionalized PIB are opening applications beyond traditional lubricant and sealant markets.
- 6C4 feedstock integration and regional production capacity remain important competitive advantages.
Market Overview
Polyisobutylene is produced by polymerizing isobutylene under controlled cationic conditions. Commercial grades differ by molecular weight, viscosity, and terminal unsaturation. Low-molecular-weight PIB is typically a clear viscous liquid and is used in lubricant additives, fuel detergents, adhesives, sealants, greases and process fluids. Medium- and high-molecular-weight products become progressively more tacky and elastic, making them useful in roofing membranes, insulating glass sealants, electrical insulation, rubber modification and other barrier applications. Highly reactive PIB contains a higher proportion of terminal vinylidene groups, which makes it especially useful as a chemical intermediate for detergent and dispersant additives.
Supply is concentrated among companies with access to C4 streams, polymerization know-how and specialized product portfolios. DL Chemical reports 220 KTA of polybutene capacity and describes itself as the leading supplier in the open market. BASF operates conventional, medium- and high-molecular-weight PIB under Oppanol and highly reactive grades under Glissopal, with 50,000-tonne-per-year HR-PIB plants in both Nanjing and Kuantan. TPC Group is a major North American producer, while INEOS markets a broad Indopol range and ENEOS Materials supplies Himol and Tetrax. India has a growing domestic base through Kothari Petrochemicals, which reached 48,000 tonnes per year of nameplate capacity.
Market Trends
Functionalized PIB is expanding the value of low-molecular-weight products
Low-molecular-weight PIB is no longer sold only as a viscosity modifier or tackifier. Suppliers are designing grades that act as reactive building blocks for more demanding chemistries. TPC Group's PIBplus is an epoxidized PIB platform intended to improve chemical functionality, including dispersant systems with stronger oxidation stability. BASF's Glissopal range is already used as a building block for fuel and lubricant additives, and KEMAT offers high-reactive grades from roughly 1,000 to 2,300 molecular weight. This matters commercially because functionalization raises the value per tonne and gives producers access to additive chemistries where consistency in terminal reactivity is more important than simple viscosity.
New applications are broadening beyond lubricants and traditional sealants
BASF's June 2026 launch of Oppanol N PLUS for next-generation batteries shows how high-purity PIB can move into applications that were not major demand centers a few years ago. The material is designed as a binder for battery electrodes or electrolyte systems, where elasticity, chemical inertness, and narrow product specifications are important. Existing high-molecular-weight grades already serve insulating glass, cable insulation, roofing and medical adhesive applications, while hydrogenated PIB is used in cosmetics. These markets will not displace fuel and lubricant additives as the core demand base by 2031, but they improve the mix and reduce dependence on one industrial cycle.
Market Drivers
Fuel and lubricant additive chemistry sustains the largest recurring demand pool
The largest volume of low-molecular-weight and highly reactive PIB is tied to lubricants and fuel-additive chemistry. HR-PIB is a preferred intermediate for PIBA and PIBSI detergent and dispersant molecules, while conventional grades work as viscosity modifiers, carriers, and tackifiers in lubricants and greases. Modern engines run at higher temperatures and tighter tolerances, increasing the importance of deposit control, oxidation stability, and lubricant performance. Refrigeration and industrial equipment add another demand layer as formulators adjust lubricant systems for newer refrigerants and efficiency requirements. The recurring nature of lubricant consumption makes this demand more stable than one-time construction or capital-equipment uses.
Adhesives, sealants and barrier applications benefit from PIB's low permeability and permanent tack
PIB is difficult to replace where formulators need a combination of water resistance, gas-barrier performance, flexibility and non-drying tack. It is widely used in insulating-glass sealants, roofing membranes, pressure-sensitive adhesives, automotive seam sealers and tire-related applications. ENEOS lists sealants, adhesives and electrical insulation among the main uses for Tetrax, while INEOS grades cover adhesives, sealants, cables and asphalt modification. Braskem also positions PIB around gas impermeability in automotive tire applications. Construction activity, renovation, energy-efficient glazing and packaging therefore provide a broad second demand base alongside lubricants.
Market Restraint
C4 feedstock availability and petrochemical price cycles can compress margins and disrupt supply
PIB production depends on isobutylene-rich C4 streams, making feedstock availability a practical constraint. Refinery and cracker operating rates, changes in C4 processing economics and competing uses for isobutylene can affect both cost and supply. TPC Group's 2026 debottlenecking program illustrates how strongly downstream specialty production depends on reliable C4 processing. Producers with integrated feedstock positions can manage this exposure better than smaller standalone suppliers, while customers may shift among PIB grades, PAO, hydrocarbon resins or other formulation components when relative prices move sharply. Qualification requirements slow substitution in higher-specification fuel, lubricant and electrical applications, but price-sensitive users can still reformulate.
Segment Analysis
By Molecular Weight - Low Molecular Weight
Low-molecular-weight PIB is projected to generate approximately USD 3.35 billion in market revenue by 2031. Its scale comes from fuel and lubricant additives, greases, adhesives, sealants, metalworking fluids and other industrial formulations. A published technical review notes that low-molecular-weight PIB holds the majority of the market, which is consistent with the large production platforms operated by DL Chemical, TPC Group, INEOS and BASF. Medium- and high-molecular-weight grades command higher prices in some specialty applications, but their physical form and narrower use base keep total volume lower.
By Product - Highly Reactive PIB
Highly reactive PIB is projected to reach approximately USD 1.49 billion by 2031. Growth is faster than conventional PIB because the material is used as a reactive intermediate rather than only as a formulation component. Higher terminal vinylidene content improves downstream functionalization for detergents, dispersants and other lubricant or fuel additives. BASF operates 50,000-tonne-per-year HR-PIB plants in Nanjing and Kuantan, and TPC Group markets a broad HR-PIB portfolio from its Houston operations. Conventional PIB remains larger in absolute value because it spans lubricants, adhesives, sealants, films and other non-reactive applications.
By Application - Lubricant Additives
Lubricant-additive applications are projected to grow at approximately 6.8% annually between 2026 and 2031. PIB functions as a viscosity modifier, carrier, tackifier, and chemical precursor in engine oils, industrial lubricants, and greases. Highly reactive grades are particularly important for PIB-derived dispersants used in combustion-engine lubricants and fuel systems. The demand profile is changing rather than disappearing as vehicle electrification progresses: internal-combustion applications remain large, while industrial lubricants, refrigeration, transmission fluids and specialty equipment continue to require high-performance additive systems. Battery applications create a separate opportunity for selected high-purity grades.
By Geography - Asia Pacific
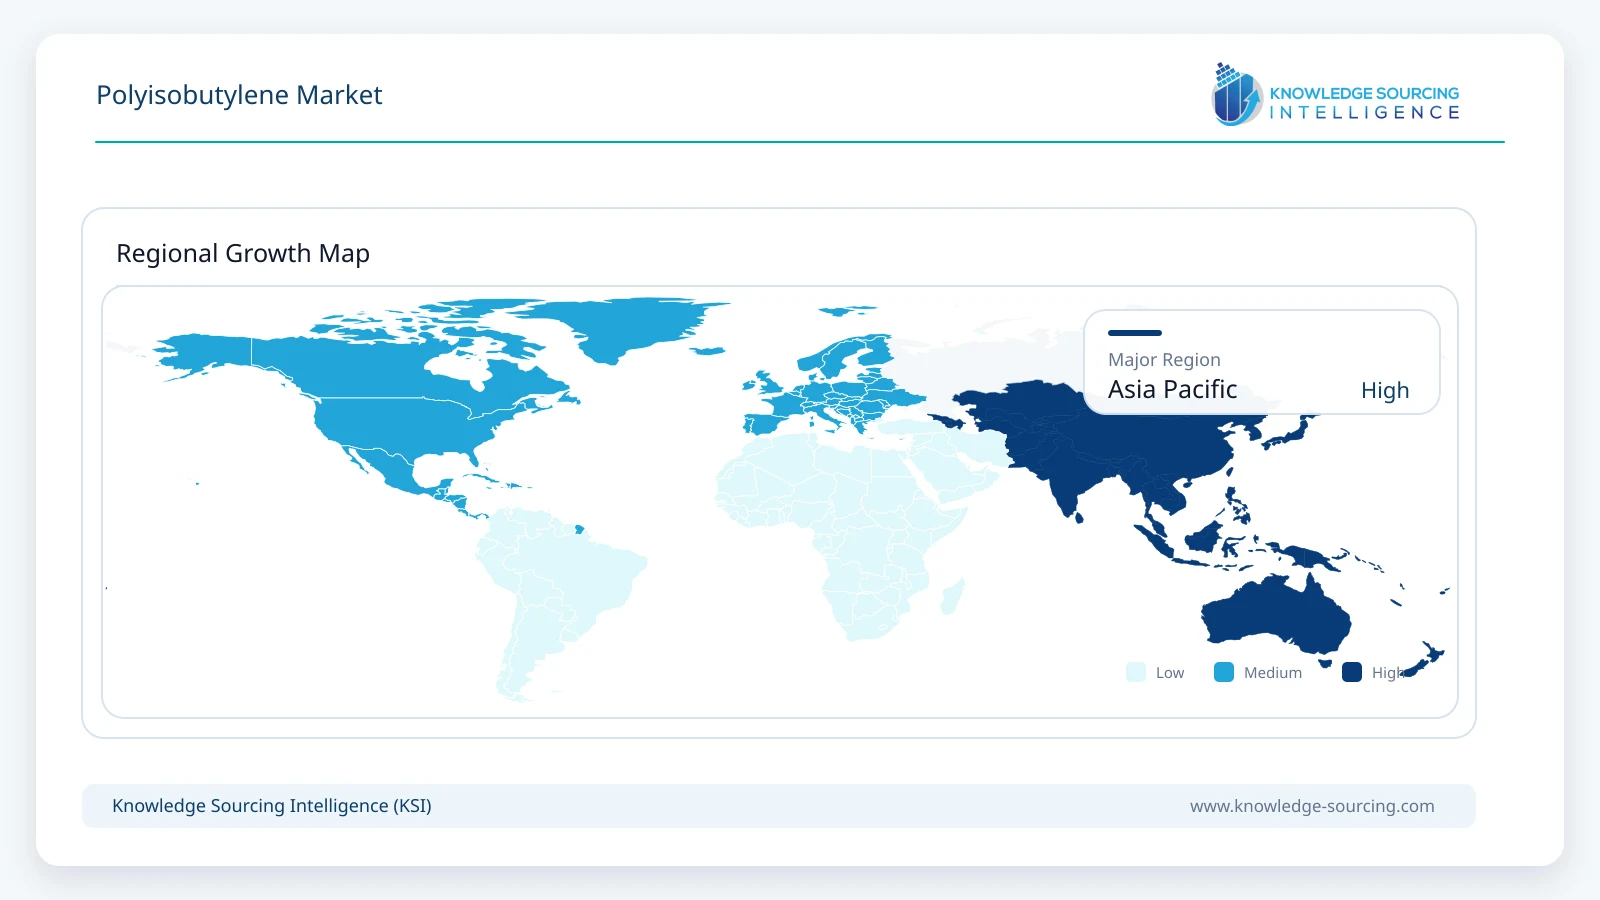
Asia Pacific is projected to reach approximately USD 2.27 billion in polyisobutylene revenue by 2031. The region combines large lubricant, automotive, tire, adhesive, and electronics industries with substantial local production. DL Chemical operates 220 KTA in South Korea, BASF has HR-PIB capacity in China and Malaysia, ENEOS Materials supplies the Japanese market, and Kothari Petrochemicals has expanded capacity in India. China also has a growing domestic producer base, including Zhejiang Cenway Materials and other regional manufacturers. North America remains important through TPC Group and INEOS, while Europe retains a strong specialty position through BASF and distribution networks such as KEMAT and TER Chemicals.
Competitive Environment
The market includes integrated petrochemical producers, specialist PIB manufacturers and regional distributors with proprietary grade portfolios. BASF has one of the broadest positions across conventional, medium-, high- and highly reactive PIB. DL Chemical has scale in conventional and HR polybutene, TPC Group is a major North American producer, and INEOS Oligomers covers a wide range of Indopol grades. ENEOS Materials competes in medium- and high-molecular-weight products, while Kothari Petrochemicals is the leading Indian producer. Braskem and several Chinese suppliers add regional competition.
Distribution and formulation support matter because customers often qualify a specific molecular-weight range, viscosity and terminal-reactivity profile rather than buying PIB as a simple commodity. KEMAT, RB Products, Connect Chemicals, TER Chemicals and Janex serve customers that require smaller lots, regional logistics or a wider product assortment. The pending acquisition of TPC Group by ENEOS Holdings could also reshape the competitive landscape if it closes as planned, combining a major North American C4 and PIB platform with ENEOS's existing materials business.
Recent Developments
August 2026: ENEOS Holdings agreed to acquire TPC Group, including its Houston petrochemical operations and downstream specialty-product platform; regulatory approvals were expected in October 2026.
June 2026: BASF introduced Oppanol N PLUS, a high-purity polyisobutene binder developed for next-generation and solid-state battery systems.
2026: BASF scheduled a polyisobutene production-capacity expansion as part of its Industrial Solutions investment program.
May 2026: ICRA reported that Kothari Petrochemicals had increased PIB nameplate capacity in India to 48,000 tonnes per year from 36,000 tonnes in 2023.
2026: TPC Group advanced C4 debottlenecking projects intended to increase feedstock-processing flexibility and support downstream specialty production.
Polyisobutylene Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 3.60 billion |
| Total Market Size in 2031 | USD 4.90 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 6.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Molecular Weight, Product, Application, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Molecular Weight
Low Molecular Weight
Medium Molecular Weight
High Molecular Weight
By Product
Conventional PIB
Highly Reactive PIB
By Application
Automotive and Tire Components
Fuel Additives
Lubricant Additives
Adhesives and Sealants
Electrical, Packaging and Other Applications
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Fuel and Lubricant Additive Chemistry Sustains the Largest Recurring Demand Pool
3.1.2. Adhesives, Sealants and Barrier Applications Benefit from PIB's Low Permeability and Permanent Tack
3.2. Market Restraint
3.2.1. C4 Feedstock Availability and Petrochemical Price Cycles Can Compress Margins and Disrupt Supply
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Highly Reactive PIB
4.2. Functionalized and Epoxidized PIB
4.3. High-Purity Battery-Grade PIB
4.4. Bio-Attributed and Lower-Carbon PIB
5. POLYISOBUTYLENE MARKET BY MOLECULAR WEIGHT
5.1. Introduction
5.2. Low Molecular Weight
5.3. Medium Molecular Weight
5.4. High Molecular Weight
6. POLYISOBUTYLENE MARKET BY PRODUCT
6.1. Introduction
6.2. Conventional PIB
6.3. Highly Reactive PIB
7. POLYISOBUTYLENE MARKET BY APPLICATION
7.1. Introduction
7.2. Automotive and Tire Components
7.3. Fuel Additives
7.4. Lubricant Additives
7.5. Adhesives and Sealants
7.6. Electrical, Packaging and Other Applications
8. POLYISOBUTYLENE MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Spain
8.4.5. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Indonesia
8.6.6. Thailand
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. BASF SE
10.2. DL Chemical Co., Ltd.
10.3. TPC Group
10.4. INEOS Oligomers
10.5. ENEOS Materials Corporation
10.6. Kothari Petrochemicals Limited
10.7. Braskem S.A.
10.8. Zhejiang Cenway Materials Co., Ltd.
10.9. KEMAT Polybutenes
10.10. RB Products, Inc.
10.11. Connect Chemicals GmbH
10.12. TER Chemicals
10.13. Zhejiang Shunda New Material Co., Ltd.
10.14. Shandong Hongrui New Material Technology Co., Ltd.
10.15. Janex S.A.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations





Frequently asked questions
What is the projected Polyisobutylene market size by 2031?
The Polyisobutylene Market is projected to reach USD 4.90 billion by 2031.
What is the Polyisobutylene market's Compound Annual Growth Rate?
The Polyisobutylene Market is expected to grow at a 6.4% CAGR.
Which polyisobutylene grade dominates revenue?
Low-molecular-weight grades account for 71% of revenue.
Which PIB type shows the highest growth rate?
Highly reactive PIB is projected to grow 8.1% annually.
What is the largest application segment for PIB?
Lubricant additives generate USD 1.08 billion market value.
Which region holds the largest Polyisobutylene market share?
Asia Pacific accounts for approximately 44% of global revenue.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Polyisobutylene Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/polyisobutylene-market