
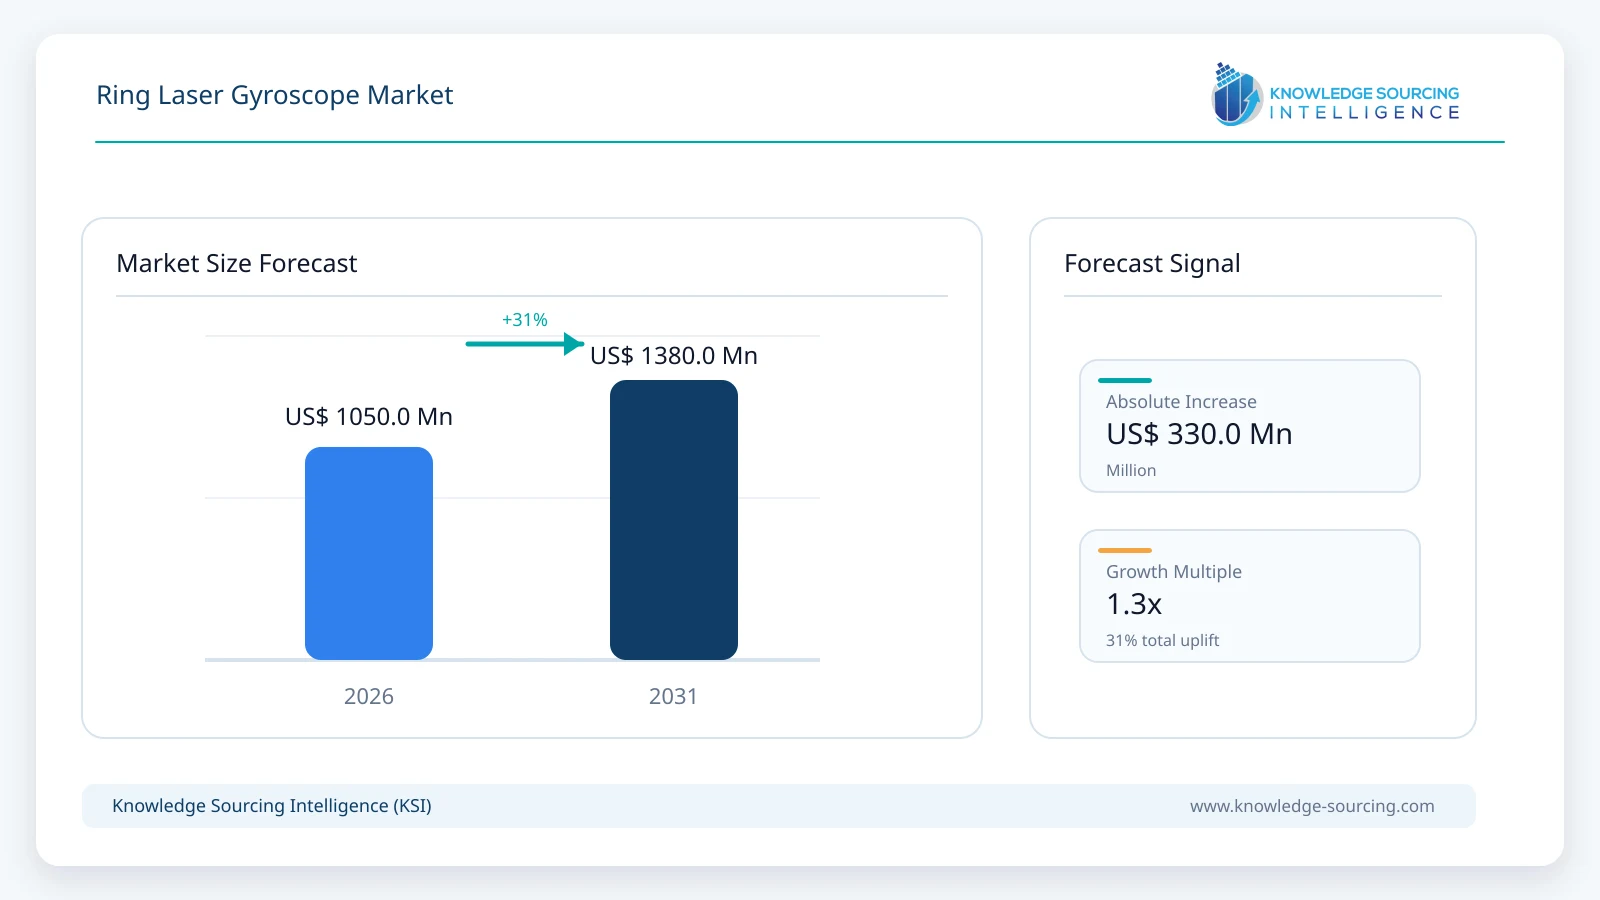
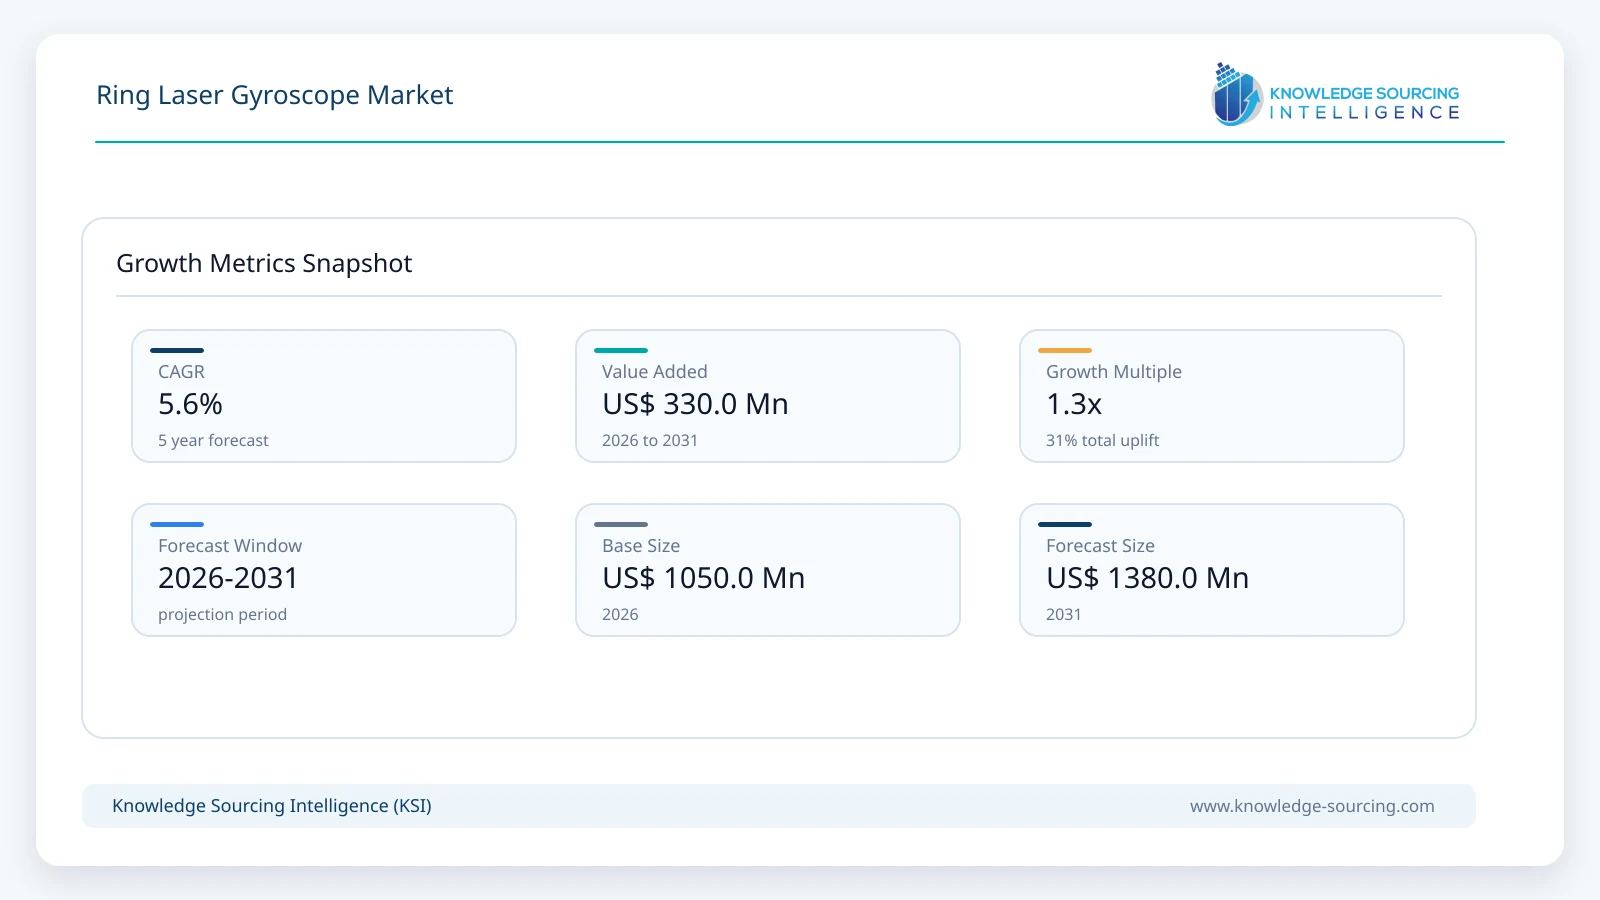
Ring Laser Gyroscope Market is forecast to grow at a CAGR of 5.60%, reaching USD 1,380 million in 2031 from USD 1,050 million in 2026.
Highlights:
- 1Leading configuration segmentMulti-Axis RLG IMUs / Assemblies dominates the Ring Laser Gyroscope Market, representing 65.0% of the 2026 market at USD 683 million.
- 2Application strongholdInertial Navigation is projected to reach USD 662 million by 2031, increasing its market share from 46.0% in 2026 to 48.0%.
- 3Fastest-growing end userDefense expands at a CAGR of 7.5% through 2031, driven by continued requirements for high-precision navigation and guidance systems.
- 4Regional market leaderNorth America holds the largest regional position in 2026, with a market value of USD 420 million, equivalent to a 40.0% share.
Ring laser gyroscopes (RLGs) are precision optical inertial sensors that measure angular rotation through the Sagnac effect. Unlike conventional mechanical gyroscopes, RLGs determine rotation by measuring the frequency difference between counter-propagating laser beams inside an optical cavity. Their high stability, repeatability, dynamic range, and established qualification record have supported adoption in demanding navigation and motion-control applications. Honeywell's current GG1320AN product documentation identifies RLGs as rotation-sensing elements for inertial navigation systems, attitude and heading reference systems, inertial measurement units, aircraft, spacecraft, marine vehicles, surface vehicles, and platform stabilization systems.
The Ring Laser Gyroscope Market is therefore closely associated with high-performance inertial navigation rather than the broader gyroscope market. The addressable market includes single-axis RLG sensors as well as multi-axis RLG-based inertial measurement units and assemblies used in navigation, guidance and control, attitude and heading reference, and platform stabilization and pointing applications. The market excludes lower-performance gyroscope categories when they are not incorporated into an RLG-based system, although competing technologies such as fiber optic gyroscopes (FOGs), MEMS gyroscopes, and hemispherical resonator gyroscopes (HRGs) remain important substitutes within procurement decisions.
Current demand is being shaped by the need for resilient positioning, navigation, and timing (PNT). Government aviation guidance confirms that GPS and GNSS signals can be affected by intentional and unintentional interference, including jamming and spoofing. The U.S. Federal Aviation Administration advises operators to be prepared to operate without GPS navigation when interference occurs. The FAA also identifies the continuing need to mitigate GPS interference and evaluate complementary navigation technologies.
This environment supports demand for inertial systems that can continue providing position, velocity, attitude, and heading information during temporary loss of satellite navigation. The commercial implication is not that every GNSS-denied application will use an RLG. FOG, MEMS, HRG, celestial navigation, radio navigation, and multi-sensor architectures compete for these requirements. Instead, RLGs retain their strongest position where customers prioritize navigation-grade accuracy, low drift, reliability, established qualification, and long operational life.
Honeywell's 2026 Aerospace Investor Day provides a current indication of the maturity of RLG technology. The company reported more than 8 billion flight hours for its digital RLG platform, more than 1.2 million IMUs produced at its Minneapolis site, and an installed base exceeding 900,000 units. Honeywell also continues to describe RLG manufacturing as part of its internal MEMS, FOG, and RLG manufacturing capabilities for aerospace and defense applications.
RLG purchasing is also increasingly shifting from individual sensor procurement toward integrated inertial architectures. Honeywell's current product portfolio includes RLG-based inertial reference systems and RLG-based IMUs, while Safran's Sigma 95 family combines ring laser gyrometers with embedded satellite navigation and filtering technologies. Thales similarly integrates three laser gyros and three accelerometers into its TopAxyz inertial measurement unit for navigation and stabilization functions.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Honeywell digital RLG flight experience | More than 8 billion flight hours | Demonstrates extensive operational validation of digital RLG technology across aerospace applications. |
Honeywell IMU production | More than 1.2 million IMUs produced at the Minneapolis site | Indicates established manufacturing capacity for inertial systems incorporating advanced gyro technologies. |
Honeywell installed base | More than 900,000 units | Supports the importance of installed-base support, replacement, qualification, and lifecycle services. |
Honeywell RLG performance | GG1320AN typical angular random walk of 0.0035°/?hour | Supports precision rotation sensing for navigation-grade applications. |
NASA small-spacecraft technology assessment | 2026 NASA guidance and navigation assessment lists Honeywell RLG-based MIMU and HG1700 IMU products. | Confirms continuing relevance of RLG-based inertial systems in space applications. |
Key indicator: Honeywell reported more than 8 billion flight hours for its digital RLG platform in its 2026 Aerospace Investor Day presentation.
Commercial meaning: Extensive operational experience can reduce qualification and adoption risk for customers evaluating high-performance inertial systems.
Market Drivers
Growing requirement for resilient navigation in GNSS-denied environments. Satellite navigation remains fundamental to aviation, defense, maritime transportation, and other positioning applications, but government authorities continue identifying jamming and spoofing as operational risks. The FAA's current navigation guidance specifically addresses GPS jamming and spoofing and states that aircraft operators should be prepared to operate without GPS navigation. The U.S. Department of Transportation's National PNT Architecture likewise identifies GPS limitations and increasing intentional and unintentional interference as reasons to develop complementary PNT capabilities.
RLG-based inertial systems can contribute to resilient navigation because they do not depend on continuous satellite signals to measure angular motion. The commercial opportunity is strongest when an RLG is integrated with accelerometers, GNSS receivers, navigation software, and other sensors to provide a hybrid architecture. Honeywell's RLG-based inertial reference systems and Safran's Sigma 95 systems illustrate this architecture, combining inertial sensing with satellite navigation and computational filtering.
Defense modernization and high-performance military navigation. Defense remains a core demand source because military aircraft, naval platforms, missiles, land systems, and other mission-critical platforms require reliable position, velocity, attitude, and heading information. U.S. Government Accountability Office assessments have identified GPS jamming, spoofing, cyber threats, and other vulnerabilities as reasons for developing alternative and complementary PNT capabilities for military operations.
RLGs benefit from this requirement where platform operators need navigation performance beyond the capability or environmental tolerance of lower-cost sensors. Northrop Grumman's current FLAG technology demonstrates continued development of laser-gyro-based inertial architectures, while its maritime navigation portfolio has historically incorporated RLG technology for ship navigation and fire-control stabilization.
Expansion of integrated inertial navigation systems. The market opportunity increasingly extends beyond individual RLG sensors. System integrators are combining multiple gyros and accelerometers with embedded GNSS, Kalman filtering, fault monitoring, software, and communications interfaces. Honeywell's RLG-based HG1700, HG5700, and HG9900 IMUs provide examples of multi-axis RLG assemblies for guidance, control, and navigation applications. Safran's Sigma 95 family similarly combines ring laser gyrometers with embedded GNSS and multimode filtering.
This trend supports the multi-axis RLG IMUs / assemblies segment because customers increasingly evaluate inertial performance at the system level. It also creates opportunities for suppliers with capabilities spanning sensors, electronics, embedded software, calibration, qualification, and lifecycle support.
Demand from aerospace and space programs. Aerospace platforms require high-integrity navigation and attitude information for flight control, aircraft guidance, pointing, and stabilization. Honeywell identifies aircraft and spacecraft among the applications of its GG1320AN RLG, while NASA's 2026 Guidance, Navigation, and Control state-of-the-art assessment lists RLG-based Honeywell MIMU and HG1700 products among available inertial systems for small spacecraft.
The space segment also values long-term stability, environmental reliability, and autonomous navigation capability. However, the market is not uniformly RLG-based because spacecraft manufacturers increasingly evaluate MEMS, FOG, HRG, and other technologies according to mass, power, radiation tolerance, cost, mission duration, and required navigation performance.
Market Restraints and Challenges
Competition from FOG, MEMS, and HRG technologies. RLGs compete against several established inertial sensing technologies. FOGs can provide high performance without the mechanical dithering mechanisms associated with many RLG designs, while MEMS technologies offer advantages in size, weight, power, and cost. HRGs provide another high-performance optical-mechanical alternative for demanding space and aerospace applications. Honeywell itself maintains internal capabilities across MEMS, FOG, and RLG manufacturing, illustrating the industry's multi-technology competitive structure.
Consequently, RLG suppliers cannot rely solely on historical accuracy advantages. Customers increasingly compare complete sensor architectures according to size, weight, power, reliability, lifecycle cost, environmental performance, software integration, and availability. This limits RLG penetration in platforms where lower-cost or smaller alternatives satisfy the required navigation performance.
High manufacturing precision and qualification requirements. RLG production requires precision optical components, controlled cavity characteristics, laser sources, specialized electronics, calibration, and stringent assembly processes. Suppliers must also maintain production consistency across long product lifecycles. These requirements raise capital and engineering barriers for new entrants and can make production localization difficult in countries attempting to develop indigenous high-performance inertial capabilities.
The qualification burden is similarly high. Aviation and defense customers require extensive reliability, environmental, electromagnetic compatibility, vibration, shock, thermal, and system-level testing. The long qualification cycle can delay commercialization and increase development expenditure. Once qualified, however, suppliers may benefit from long product lifecycles and significant switching costs.
High acquisition cost compared with lower-performance alternatives. RLGs generally target applications where performance requirements justify a higher cost than consumer, industrial, or tactical MEMS gyroscopes. This narrows the addressable market in cost-sensitive applications. FOGs also compete strongly in applications where customers seek high accuracy without the size, complexity, or cost profile associated with some RLG implementations.
Complex export controls and technology-transfer restrictions. High-performance inertial navigation equipment can be subject to export controls because of its relevance to aerospace, missile, naval, and military applications. Restrictions on technology transfer can affect supplier selection, local manufacturing agreements, after-sales support, and international sales. Governments promoting domestic production must balance technology localization objectives with security requirements and access to specialized components.
Major Segment Analysis
Multi-Axis RLG IMUs / Assemblies Segment
Multi-axis RLG IMUs / assemblies represent a leading value segment, accounting for 68.5% of the market in 2031 and reaching a segment value of USD 945 million, with the segment projected to expand at a CAGR of 6.7%. These systems combine multiple precision gyroscopes and accelerometers into an integrated inertial measurement architecture. Honeywell's RLG-based IMU portfolio includes HG1700, HG5700, and HG9900 products, with three-ring-laser-gyro configurations designed for guidance, control, and navigation applications. Honeywell also identifies RLG-based IMUs as part of its aerospace and defense inertial systems capabilities.
The commercial advantage of multi-axis assemblies is system integration. Instead of procuring and qualifying individual rotation sensors separately, platform manufacturers can integrate a calibrated multi-axis inertial unit with established interfaces, environmental specifications, diagnostics, and software. This approach reduces integration complexity and can simplify certification. It is particularly relevant to aircraft, missiles, spacecraft, naval systems, and high-end land platforms where navigation accuracy, reliability, and system availability are critical.
The segment also benefits from demand for redundant and resilient architectures. Modern inertial systems can combine RLG measurements with GNSS, air-data inputs, celestial or other navigation sources, and advanced filtering. During normal operation, these inputs can improve overall navigation accuracy. During GNSS interference or signal degradation, the inertial unit can continue providing navigation continuity while other sensors are unavailable or compromised. Honeywell's RLG-based inertial reference systems demonstrate the integration of RLG technology with GPS/IRS architectures, supporting continued demand for multi-axis inertial assemblies across aerospace, defense, and other precision-navigation applications.
Defense End-user Segment
Defense remains a major end-user segment because military navigation requirements place a premium on accuracy, reliability, environmental resilience, and independence from satellite navigation. The defense segment accounts for 33.0% of the Ring Laser Gyro Market in 2026 and is projected to increase its share to 36.0% by 2031, supported by continued demand for high-performance inertial systems. RLG-based systems are used or positioned for aircraft, ships, weapons, and other platforms requiring high-performance inertial reference. The U.S. Government Accountability Office has documented the Department of Defense's efforts to develop alternative PNT technologies that complement GPS because military operations can be disrupted by jamming, spoofing, cyber threats, and other attacks.
India provides a further example of domestic RLG-based navigation development. The Indian Ministry of Defence reported in December 2025 that India Optel Limited signed a collaboration agreement with Safran Electronics & Defense for local production of the SIGMA 30N Digital Ring Laser Gyro Inertial Navigation System. The government stated that the system is intended for artillery guns, air-defense systems, missiles, and radars. This development indicates that RLG-based inertial navigation is also becoming part of national defense-industrial localization strategies.
Defense demand also supports recurring revenue through upgrades, replacement, maintenance, and lifecycle support. Once an inertial system is qualified for a major military platform, replacing the technology can involve extensive testing and certification. This creates customer retention opportunities for established RLG suppliers while simultaneously making market entry difficult for new manufacturers.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
North America | Defense modernization, commercial aviation, resilient PNT, and space programs | Strict qualification, export controls, and strong competition from alternative inertial technologies |
Europe | Military aircraft, navigation systems, naval programs, and aerospace manufacturing | Complex procurement structures and technology-transfer requirements |
Asia-Pacific | Defense localization, aerospace development, naval modernization, and space programs | Limited domestic capability for some high-precision inertial technologies |
Middle East & Africa | Defense procurement, aircraft modernization, naval systems, and unmanned platforms | High dependence on imported systems and foreign technology suppliers |
South America | Naval modernization, aerospace applications, and defense fleet upgrades | Smaller procurement budgets and limited domestic RLG manufacturing infrastructure |
North America
North America is expected to remain a major RLG market, supported by large defense procurement programs, mature aerospace manufacturing, established inertial sensor suppliers, and advanced space activity. The region is projected to account for 38.0% of the global RLG market by 2031, while the segment is expected to expand at a CAGR of 4.5% during the forecast period. The United States holds a particularly strong position through companies such as Honeywell and Northrop Grumman, alongside continued government investment in resilient positioning, navigation, and timing (PNT) capabilities. Honeywell's 2026 Investor Day highlighted the scale of its digital RLG installed base and related manufacturing activities, while Northrop Grumman's 2026 FLAG documentation confirms continued commercial development of laser-gyro-based inertial architectures.
Government policy is also supporting the wider navigation ecosystem across North America. The FAA's April 2026 technical discipline update states that satellite navigation modernization must address spectrum-related challenges, including GPS interference, jamming, and spoofing. The FAA continues to evaluate technologies and operational measures that can support safe aviation operations when satellite-based PNT performance is degraded, strengthening demand for resilient inertial navigation technologies such as RLG-based systems.
Europe
Europe has a strong inertial-navigation industrial base supported by Safran Electronics & Defense, Thales, and other specialist suppliers. Safran's Sigma 95N uses high-accuracy ring laser gyros and integrates GNSS receivers and multimode Kalman filtering for advanced military aircraft operating in GNSS-denied environments. Thales' TopAxyz uses three laser gyros and three accelerometers to support navigation and stabilization functions across aerospace, land, and maritime applications.
Competition within Europe is increasingly technology-diverse. Safran's June 2026 investment in Montluçon was focused on scaling hemispherical resonator gyroscope production rather than RLG manufacturing. This is strategically relevant because it shows that established inertial suppliers are simultaneously investing in alternative high-performance gyro technologies. Safran announced a €120 million investment to modernize and expand the facility, with HRG production planned to increase from 10,000 units annually to 30,000 units by 2032.
Asia-Pacific
Asia-Pacific presents a growing opportunity, with the segment valued at USD 252 million in 2026 and projected to reach USD 373 million by 2031, expanding at a CAGR of 8.10%. Governments across the region are strengthening indigenous defense manufacturing, expanding aerospace capabilities, and developing naval and space platforms. China, Japan, India, South Korea, Indonesia, and Taiwan have varying levels of activity across military aviation, naval systems, missile programs, satellite development, and precision navigation. India provides a particularly clear example of RLG localization through the December 2025 India Optel-Safran production collaboration for the SIGMA 30N digital ring laser gyro inertial navigation system.
Domestic manufacturing initiatives can expand the addressable market by reducing dependence on imported inertial systems and improving local sustainment capability. However, establishing competitive RLG manufacturing requires specialized optical engineering, precision assembly, calibration, electronics, environmental testing, and long-term qualification. These requirements can slow localization even where government procurement strongly favors indigenous content.
Middle East & Africa
Middle East & Africa demand is primarily connected with defense procurement, aircraft modernization, naval platforms, air-defense systems, and unmanned technologies. Saudi Arabia, the United Arab Emirates, and Israel represent important technology and procurement centers, although much of the region's high-performance inertial equipment continues to be supplied by international aerospace and defense companies.
Demand is likely to remain focused on complete navigation systems rather than standalone RLG components. Customers typically require integrated inertial reference units, platform interfaces, maintenance support, and compatibility with existing aircraft or naval systems. This favors established suppliers with certified products and regional service capabilities.
South America
South America represents a smaller but relevant market, particularly for naval navigation, military aircraft, and aerospace applications. Brazil has an established defense and aerospace industrial base and has historically used high-performance navigation and maritime systems. Northrop Grumman has previously supplied RLG-based MK39 navigation systems to the Brazilian Navy, illustrating the role of RLG technology in regional naval navigation.
Market development is constrained by comparatively smaller defense procurement budgets, limited domestic production of high-end inertial sensors, and dependence on international suppliers. Opportunities are therefore more likely to emerge through fleet modernization, naval upgrades, aircraft replacement programs, and localized maintenance partnerships than through large-scale standalone RLG manufacturing.
Competitive Landscape
The Ring Laser Gyroscope Market has a technically concentrated competitive environment because high-performance RLG production requires specialized optical engineering, precision manufacturing, extensive qualification, and long-term product support. Honeywell, Northrop Grumman, Safran Electronics & Defense, Thales, and other established navigation suppliers compete through product accuracy, reliability, system integration, qualification history, manufacturing scale, and lifecycle support.
Honeywell has a particularly established RLG position through its GG1320AN digital RLG and RLG-based inertial reference systems. Its 2026 Investor Day presentation highlighted more than 8 billion flight hours associated with its digital RLG platform, while its current product information identifies applications spanning INS, AHRS, IMUs, aircraft, spacecraft, marine vehicles, surface vehicles, and platform stabilization.
Northrop Grumman continues to maintain laser-gyro capabilities through products such as the FLAG technology and its broader inertial navigation portfolio. Its June 2026 LTN-101 FLAGSHIP GNADIRU documentation describes a four-mode laser gyro architecture using three 18-centimeter Zero-lock laser gyroscopes in a single cavity, with reduced size relative to conventional ring laser gyro configurations.
Safran remains an important competitor through its Sigma 95 family, where ring laser gyrometers are integrated with GNSS receivers and navigation filters. Thales similarly combines RLG technology with multi-axis accelerometers in TopAxyz inertial measurement systems. These product strategies indicate that competition is moving toward integrated navigation performance rather than standalone gyro specifications.
Competitive pressure also comes from alternative technologies. Safran's 2026 investment in HRG manufacturing and Honeywell's simultaneous RLG, FOG, and MEMS capabilities illustrate how leading inertial suppliers are maintaining technology portfolios across multiple performance and cost levels. This makes technology selection increasingly application-specific rather than uniformly favoring one gyro architecture.
Recent Developments
April 2026: G&H detailed continued RLG technology development for next-generation missile and UAV platforms, including smaller form factors, precision optics, and reduced size, weight, and power requirements.
March 2026: G&H highlighted its defence-grade Ring Laser Gyroscope components for missiles and UAVs, emphasizing ultra-low drift, environmental stability, and vertically integrated U.S. manufacturing for GPS-denied navigation.
Regulatory and Policy Environment
Ring laser gyroscopes operate within a highly regulated aerospace, defense, and dual-use technology environment. Export controls can affect the international sale, transfer, manufacturing, and servicing of high-performance inertial navigation equipment. Suppliers serving defense customers must also comply with platform-specific technical specifications, cybersecurity requirements, environmental qualification standards, and national procurement rules.
In the United States, aviation navigation requirements are influenced by the Federal Aviation Administration, while defense navigation requirements are shaped by Department of Defense programs and associated procurement standards. The FAA's current technical guidance recognizes GPS interference, jamming, and spoofing as important navigation risks and continues evaluating satellite navigation capabilities and complementary technologies.
Government PNT policy is also becoming more focused on resilience. The U.S. Department of Transportation's National PNT Architecture identifies capability gaps associated with GPS limitations and calls for complementary PNT sources to improve resilience for safety-critical transportation. This policy direction supports broader development of inertial, terrestrial, alternative satellite, and sensor-fusion technologies.
Defense procurement adds another regulatory layer because RLG-based inertial systems can support missiles, artillery, naval navigation, aircraft, and other military platforms. India's December 2025 government announcement regarding local production of Safran's SIGMA 30N demonstrates how national industrial policy can directly influence the geography of RLG-based inertial system manufacturing.
Space applications also require stringent reliability and mission-specific qualification. NASA's 2026 Guidance, Navigation, and Control assessment continues to evaluate gyro technologies according to bias stability, angular random walk, size, mass, power, and axis configuration. Its inclusion of Honeywell RLG-based MIMU and HG1700 products demonstrates that RLG technology remains relevant within the broader spacecraft inertial technology landscape.
Outlook and Strategic Implications
The Ring Laser Gyroscope Market is expected to maintain a strong position in high-performance navigation applications during 2026-2031, although growth will remain highly dependent on defense modernization, aerospace production, space missions, naval programs, and the expansion of resilient PNT architectures. RLGs are unlikely to replace lower-cost MEMS or FOG technologies across the broader navigation market. Instead, the strongest opportunity lies in applications where accuracy, low drift, long-term stability, established qualification, and operational continuity justify the higher cost and engineering complexity of RLG-based systems.
The most important market shift is the movement from standalone gyro procurement toward integrated inertial solutions. Multi-axis RLG IMUs / assemblies can combine multiple gyroscopes and accelerometers with navigation software, GNSS receivers, filtering algorithms, diagnostics, and platform interfaces. This system-level approach increases the commercial value of established suppliers and creates opportunities for companies capable of supplying complete navigation architectures.
Defense will remain a central demand driver because military customers continue developing PNT capabilities that can operate when GPS or other satellite navigation signals are disrupted. Government assessments in the United States continue identifying jamming, spoofing, and cyber threats as reasons for complementary navigation capabilities, while aviation authorities are maintaining operational guidance for periods of GNSS degradation.
Technology competition will nevertheless intensify. FOGs offer strong performance with different architectural characteristics, MEMS technologies continue improving their accuracy and environmental performance, and HRGs are expanding in high-end aerospace and space applications. Safran's 2026 investment in HRG production illustrates how major inertial suppliers are scaling alternatives alongside established RLG capabilities.
Several strategic priorities are expected to shape the market through 2031:
Defense organizations will continue investing in resilient PNT and high-performance inertial systems that can maintain navigation during GNSS disruption.
Aerospace manufacturers will prioritize qualified inertial systems offering low drift, long service life, compact packaging, and integration with aircraft navigation architectures.
RLG manufacturers will focus on smaller, lighter, lower-power architectures and improved electronics to maintain competitiveness against FOG and advanced MEMS solutions.
System integrators will increase the use of sensor fusion, hybrid GNSS/inertial architectures, and software-based integrity monitoring to improve navigation continuity.
Governments will continue promoting domestic production and secure supply chains for strategic inertial technologies, particularly in countries seeking greater defense-industrial independence.
Suppliers will increasingly maintain multi-technology portfolios spanning RLG, FOG, MEMS, and HRG solutions to address different performance, size, power, and cost requirements.
Overall, the competitive outlook is expected to favor companies with established RLG manufacturing expertise, extensive qualification records, integrated inertial-system capabilities, and long-term customer support. The strongest commercial opportunities will remain concentrated in defense, aerospace, space, marine, navigation, guidance and control, and platform stabilization applications where navigation failure carries a high operational cost.
The market's long-term development will therefore depend not only on the technical performance of the ring laser gyroscope itself but also on how effectively manufacturers integrate RLG technology into resilient, secure, and platform-ready navigation systems. Continued government emphasis on PNT resilience, defense localization, aerospace modernization, and autonomous platform development should sustain the strategic relevance of RLG-based inertial technologies through the forecast period.
Ring Laser Gyroscope Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1,050 million |
| Total Market Size in 2031 | USD 1,380 million |
| Forecast Unit | Million |
| Growth Rate | 5.60% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Axis Configuration, Application, End-User, Geography |
| Companies |
|
Market Segmentation
By Axis Configuration
Single-Axis RLG Sensors
Multi-Axis RLG IMUs / Assemblies
By Application
Inertial Navigation
Guidance & Control
Attitude & Heading Reference
Platform Stabilization & Pointing
Others
By End-User
Aerospace & Aviation
Defense
Marine
Space
Industrial & Others
By Geography
North America
United States
Canada
Mexico
Europe
Germany
France
United Kingdom
Spain
Others
Asia-Pacific
China
Japan
India
South Korea
Indonesia
Taiwan
Others
Middle East & Africa
Saudi Arabia
United Arab Emirates
Israel
Others
South America
Brazil
Argentina
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key benefits to the stakeholder
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
4.5. Analyst View
5. RING LASER GYROSCOPE MARKET BY TECHNOLOGY
5.1. Introduction
5.2. Three-Axis Ring Laser Gyroscope
5.3. Single-Axis Ring Laser Gyroscope
6. RING LASER GYROSCOPE MARKET BY END-USER
6.1. Introduction
6.2. Aerospace
6.3. Defense
6.4. Marine and Underwater Systems
6.5. Space
6.6. Industrial
6.7. Others
7. RING LASER GYROSCOPE MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. By Technology
7.2.2. By End-user
7.2.3. By Country
7.2.3.1. United States
7.2.3.1.1. Market Trends and Opportunities
7.2.3.1.2. Growth Prospects
7.2.3.2. Canada
7.2.3.2.1. Market Trends and Opportunities
7.2.3.2.2. Growth Prospects
7.2.3.3. Mexico
7.2.3.3.1. Market Trends and Opportunities
7.2.3.3.2. Growth Prospects
7.3. South America
7.3.1. By Technology
7.3.2. By End-user
7.3.3. By Country
7.3.3.1. Brazil
7.3.3.1.1. Market Trends and Opportunities
7.3.3.1.2. Growth Prospects
7.3.3.2. Argentina
7.3.3.2.1. Market Trends and Opportunities
7.3.3.2.2. Growth Prospects
7.3.3.3. Others
7.3.3.3.1. Market Trends and Opportunities
7.3.3.3.2. Growth Prospects
7.4. Europe
7.4.1. By Technology
7.4.2. By End-user
7.4.3. By Country
7.4.3.1. Germany
7.4.3.1.1. Market Trends and Opportunities
7.4.3.1.2. Growth Prospects
7.4.3.2. France
7.4.3.2.1. Market Trends and Opportunities
7.4.3.2.2. Growth Prospects
7.4.3.3. United Kingdom
7.4.3.3.1. Market Trends and Opportunities
7.4.3.3.2. Growth Prospects
7.4.3.4. Spain
7.4.3.4.1. Market Trends and Opportunities
7.4.3.4.2. Growth Prospects
7.4.3.5. Others
7.4.3.5.1. Market Trends and Opportunities
7.4.3.5.2. Growth Prospects
7.5. Middle East and Africa
7.5.1. By Technology
7.5.2. By End-user
7.5.3. By Country
7.5.3.1. Saudi Arabia
7.5.3.1.1. Market Trends and Opportunities
7.5.3.1.2. Growth Prospects
7.5.3.2. UAE
7.5.3.2.1. Market Trends and Opportunities
7.5.3.2.2. Growth Prospects
7.5.3.3. Israel
7.5.3.3.1. Market Trends and Opportunities
7.5.3.3.2. Growth Prospects
7.5.3.4. Others
7.5.3.4.1. Market Trends and Opportunities
7.5.3.4.2. Growth Prospects
7.6. Asia Pacific
7.6.1. By Technology
7.6.2. By End-user
7.6.3. By Country
7.6.4. China
7.6.4.1. Market Trends and Opportunities
7.6.4.2. Growth Prospects
7.6.5. Japan
7.6.5.1. Market Trends and Opportunities
7.6.5.2. Growth Prospects
7.6.6. India
7.6.6.1.1. Market Trends and Opportunities
7.6.6.1.2. Growth Prospects
7.6.7. South Korea
7.6.7.1.1. Market Trends and Opportunities
7.6.7.1.2. Growth Prospects
7.6.8. Indonesia
7.6.8.1.1. Market Trends and Opportunities
7.6.8.1.2. Growth Prospects
7.6.9. Taiwan
7.6.9.1.1. Market Trends and Opportunities
7.6.9.1.2. Growth Prospects
7.6.10. Others
7.6.10.1. Market Trends and Opportunities
7.6.10.2. Growth Prospects
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisition, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Honeywell International Inc.
9.2. Northrop Grumman Corporation
9.3. Safran Electronics & Defense
9.4. Collins Aerospace
9.5. Thales Group
9.6. Exail
9.7. iMAR Navigation GmbH
9.8. ERICCO Inertial System
9.9. Litef GmbH
9.10. KVH Industries, Inc.
LIST OF FIGURES
LIST OF TABLES
Navigate
Trusted by the world's leading organizations











