
The self-supervised learning market is expected to show steady growth over the forecasted period.
Highlights:
- 1Growing enterprise demand for foundation models trained on proprietary datasets is strengthening adoption of self-supervised learning techniques.
- 2Natural Language Processing remains one of the most commercially valuable application segments due to widespread deployment of large language models.
- 3North America maintains strong demand supported by advanced AI infrastructure, cloud investment, and enterprise technology spending.
- 4Multimodal AI models combining text, image, audio, and sensor data are expanding the commercial scope of self-supervised learning.
- 5Government AI governance initiatives are encouraging greater emphasis on model transparency, security, and responsible deployment.
- 6Competition increasingly centers on computing efficiency, pretrained model quality, enterprise integration, and domain-specific AI capabilities.
The self-supervised learning market represents a specialized segment of artificial intelligence (AI) focused on developing machine learning models that learn meaningful representations from unlabeled or minimally labeled data. Instead of relying on extensive human annotation, self-supervised learning creates supervisory signals directly from the underlying data, enabling models to acquire generalized knowledge before being adapted to downstream tasks. This capability has become commercially important because organizations generate large volumes of structured and unstructured data that remain underutilized due to the high cost and time required for manual labeling.
Demand for self-supervised learning is closely linked to the expanding deployment of generative AI, foundation models, multimodal systems, autonomous technologies, and enterprise AI applications. Organizations across banking, healthcare, manufacturing, retail, telecommunications, and automotive sectors are seeking methods that reduce annotation costs while improving model accuracy and scalability. As enterprises increase investments in proprietary AI models trained on domain-specific datasets, self-supervised learning has become an attractive approach for extracting value from internal data repositories without creating extensive labeled datasets.
Commercial buyers evaluate self-supervised learning platforms based on model performance, scalability across cloud and on-premises environments, compatibility with existing machine learning operations (MLOps) pipelines, data privacy controls, inference efficiency, and support for multiple data modalities such as text, images, speech, sensor streams, and video. Procurement decisions increasingly involve collaboration between chief data officers, AI engineering teams, cybersecurity leaders, and business units responsible for digital initiatives.
Industry structure includes hyperscale cloud providers, semiconductor manufacturers, AI software vendors, open-source ecosystem contributors, enterprise platform providers, and specialist machine learning companies. Cloud infrastructure providers benefit from growing computational demand, while chip manufacturers support increasingly complex model training workloads. Software companies differentiate themselves through pretrained foundation models, developer frameworks, optimization tools, and enterprise deployment capabilities.
Revenue generation extends beyond software licensing. Organizations increasingly purchase managed AI services, cloud computing resources, consulting, model optimization services, infrastructure acceleration hardware, and industry-specific AI platforms incorporating self-supervised learning techniques. Long-term commercial value is also supported by continuous model retraining, maintenance contracts, and enterprise AI subscriptions.
Adoption patterns vary by industry maturity. Technology companies were among the earliest adopters because of access to large proprietary datasets and advanced computing resources. Financial institutions increasingly apply self-supervised learning to fraud detection, risk modeling, and document intelligence. Healthcare organizations are exploring medical imaging, clinical language models, and drug discovery applications, while automotive companies continue investing in autonomous driving perception systems. Manufacturing firms use self-supervised learning for visual inspection, predictive maintenance, and industrial automation where labeled operational datasets are often limited.
Market Drivers
Expansion of Foundation Models Across Enterprise AI
Large language models and multimodal foundation models require enormous volumes of unlabeled information during pretraining. Self-supervised learning enables developers to utilize publicly available and enterprise-specific datasets without manually creating annotations. Enterprises seeking proprietary AI assistants, document intelligence platforms, and domain-specific language models increasingly view self-supervised learning as an economically viable training methodology. Vendors are responding by offering optimized frameworks, pretrained models, and enterprise customization services that shorten deployment timelines.
Rising Cost of Data Annotation
Manual labeling remains one of the largest expenses in AI development, particularly for industries handling medical images, financial documents, industrial sensor data, and multilingual content. Organizations are therefore investing in learning approaches that minimize annotation requirements while preserving model accuracy. This purchasing behavior supports demand for software platforms integrating self-supervised pretraining with fine-tuning workflows, reducing overall development costs.
Growth in Multimodal AI Applications
Modern enterprise AI increasingly combines images, video, text, audio, and operational sensor data within a unified analytical framework. Self-supervised learning supports representation learning across these diverse data formats, making it valuable for autonomous vehicles, robotics, industrial inspection, intelligent surveillance, and digital assistants. Suppliers continue expanding multimodal model capabilities to address broader commercial use cases across multiple industries.
Increasing AI Infrastructure Investment
Cloud service providers and enterprise data centers continue investing heavily in accelerated computing infrastructure capable of supporting large-scale model training. High-performance GPUs, specialized AI accelerators, distributed computing platforms, and optimized software frameworks have reduced practical barriers associated with training self-supervised models. Infrastructure availability encourages organizations to expand internal AI development rather than relying solely on third-party models.
Market Restraints and Challenges
High Computational Requirements
Training advanced self-supervised models demands substantial computing resources, storage capacity, and electricity consumption. Small and medium-sized enterprises often encounter financial constraints when deploying large-scale training workloads. Although cloud services improve accessibility, infrastructure expenses remain an important consideration during procurement planning.
Data Governance and Privacy Constraints
Many industries possess valuable proprietary datasets but operate under strict privacy regulations governing financial records, healthcare information, and personal data. Organizations must establish secure data governance frameworks before using internal information for model training. Compliance requirements increase implementation complexity and lengthen deployment cycles.
Model Interpretability
Enterprise buyers increasingly require explainable AI, particularly in regulated industries where automated decisions affect lending, healthcare, insurance, and public services. Self-supervised learning models can produce highly effective representations while remaining difficult to interpret. Vendors therefore invest in explainability tools, model monitoring, and governance platforms that improve organizational confidence.
Shortage of Specialized AI Expertise
Successful implementation requires professionals with expertise in deep learning architectures, distributed computing, data engineering, and model optimization. Competition for experienced AI researchers and engineers continues to influence deployment schedules, project costs, and long-term operational scalability.
Major Segment Analysis
Natural Language Processing (NLP) represents the most commercially significant application segment because enterprise demand for language-based AI has accelerated across customer service, enterprise search, document processing, software development, legal analysis, and knowledge management.
Organizations increasingly possess extensive collections of emails, contracts, reports, technical documentation, customer conversations, and multilingual business records. Self-supervised learning enables language models to learn contextual relationships from these large document collections before fine-tuning for specialized enterprise applications. This approach substantially reduces dependence on manually labeled datasets while improving performance across industry-specific terminology.
Enterprise buyers prioritize accuracy, multilingual support, security, latency, deployment flexibility, and integration with existing business systems. Competitive differentiation increasingly depends on domain adaptation capabilities, inference efficiency, retrieval-augmented generation compatibility, and responsible AI governance features. As organizations continue building proprietary AI assistants and knowledge platforms, NLP remains a primary revenue contributor within the self-supervised learning ecosystem.
Regional Analysis
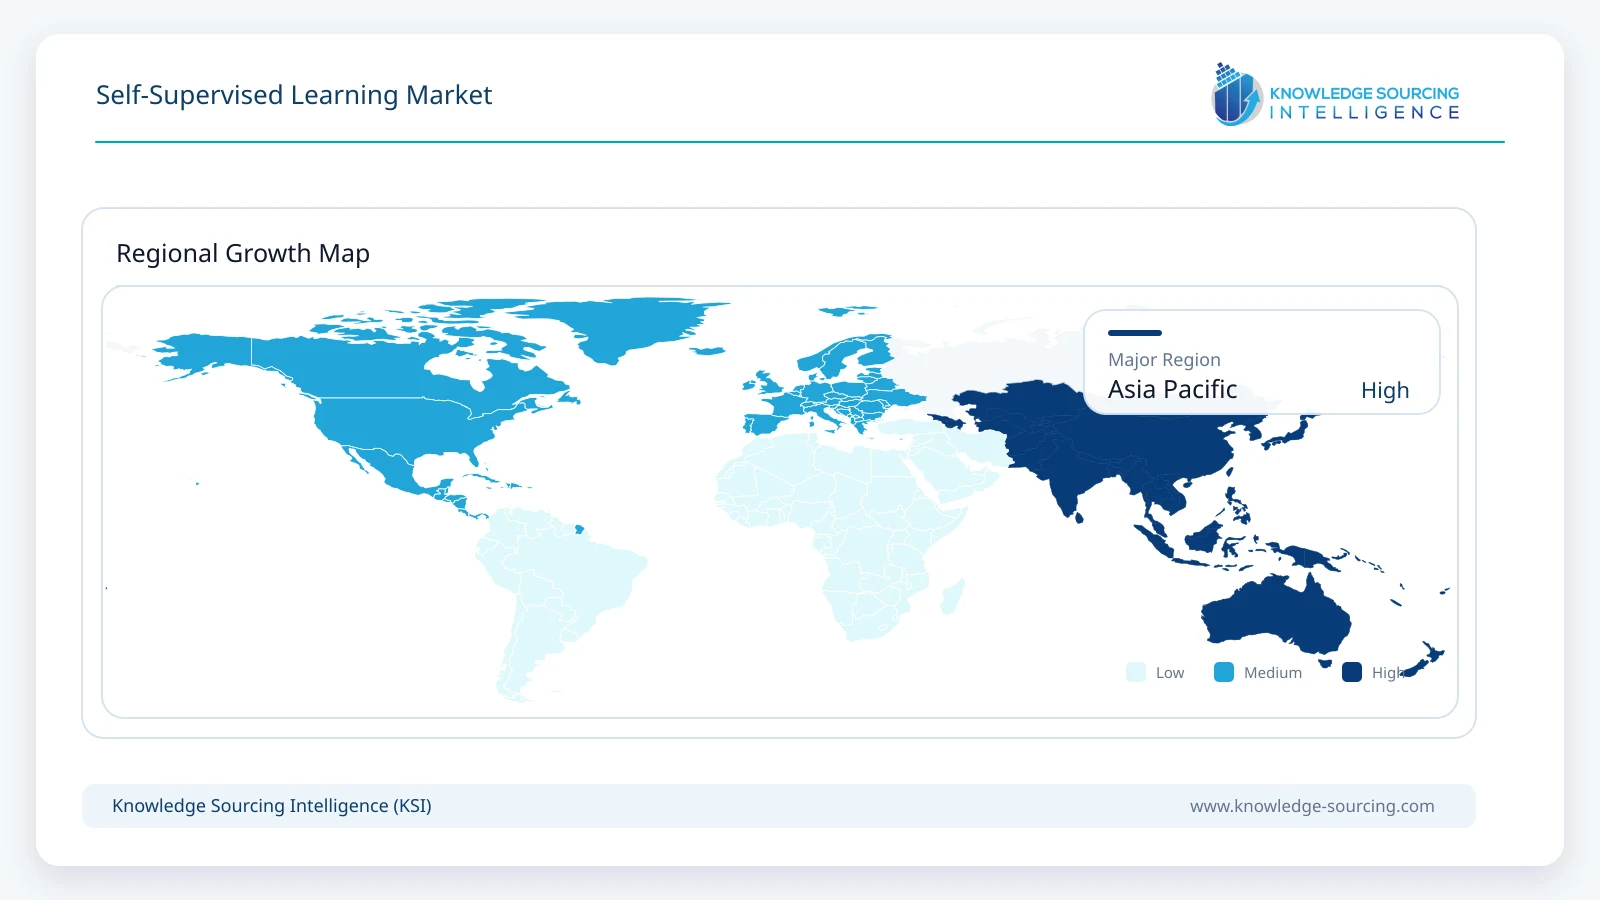
North America
North America represents the leading regional market due to substantial AI investment by cloud providers, technology companies, financial institutions, healthcare organizations, and government agencies. Strong venture capital activity, advanced semiconductor infrastructure, established research institutions, and enterprise software adoption support continued commercial demand. Buyers increasingly prioritize scalable cloud-native AI platforms with enterprise governance capabilities.
Europe
European adoption is influenced by industrial automation, automotive manufacturing, financial services, and public-sector digital initiatives. Organizations place considerable emphasis on trustworthy AI, regulatory compliance, and responsible data management. Investment focuses on industrial AI, language technologies supporting multiple European languages, and manufacturing automation. Regulatory requirements may lengthen deployment timelines but also encourage development of governance-focused AI solutions.
Asia Pacific
Asia Pacific continues experiencing strong adoption driven by expanding digital economies, semiconductor manufacturing, consumer internet platforms, and government-supported AI strategies. China, Japan, South Korea, and India continue investing in national AI capabilities, research infrastructure, and enterprise digitalization. Manufacturers increasingly deploy self-supervised learning for quality inspection, robotics, and predictive maintenance across industrial production environments.
Middle East & Africa
Governments across the Gulf region continue investing in AI research, digital government programs, smart cities, and cloud infrastructure. Financial services, energy, healthcare, and public administration represent important early adopters. Skills availability and infrastructure disparities remain important considerations across several regional markets.
South America
Adoption is steadily expanding as organizations modernize financial services, retail analytics, telecommunications, and industrial operations. Budget limitations and limited AI talent remain practical constraints, although cloud-based deployment models improve accessibility for enterprises seeking advanced machine learning capabilities without major infrastructure investments.
Competitive Landscape
Competition within the self-supervised learning market combines large technology companies, AI platform providers, semiconductor manufacturers, and specialized machine learning software vendors. Google LLC, Microsoft Corporation, Meta Platforms, Inc., Amazon.com, Inc., IBM Corporation, NVIDIA Corporation, Intel Corporation, Baidu, Inc., DataRobot, Inc., Databricks, Inc., and The MathWorks, Inc. compete through integrated software ecosystems, AI infrastructure, pretrained foundation models, developer platforms, and enterprise deployment services.
Competitive positioning increasingly depends on computational efficiency, developer productivity, cloud integration, proprietary model architectures, optimized hardware acceleration, and support for enterprise governance. Strategic partnerships between cloud providers, semiconductor companies, and enterprise software vendors continue strengthening integrated AI deployment capabilities across multiple industries.
Recent Developments
May 2026: NVIDIA expanded enterprise AI software capabilities supporting optimized training and deployment of foundation models across accelerated computing platforms. The development strengthens enterprise scalability for self-supervised learning workloads.
April 2026: Meta introduced Muse Spark, its first model from Meta Superintelligence Labs, featuring native multimodal reasoning and large-scale pretraining that advances foundation model capabilities built on extensive self-supervised learning across text, images, audio, and video.
March 2026: Databricks introduced expanded AI platform capabilities supporting enterprise development, fine-tuning, and governance of foundation models using proprietary organizational data. The enhancement simplifies commercial AI deployment.
January 2026: NVIDIA released the Earth-2 family of open AI weather models, libraries, and frameworks, allowing researchers to train advanced climate forecasting systems using large-scale satellite and radar data through self-supervised and foundation-model learning approaches.
Regulatory and Policy Environment
The regulatory environment increasingly emphasizes responsible AI development rather than specific regulation of self-supervised learning algorithms. Organizations operating in regulated sectors must comply with data protection requirements, cybersecurity standards, intellectual property obligations, and sector-specific governance rules during model development and deployment.
In Europe, the AI Act establishes a risk-based governance framework affecting providers and users of AI systems. Data protection requirements under the General Data Protection Regulation (GDPR) influence model training practices involving personal information. In the United States, agencies continue issuing AI guidance covering procurement, cybersecurity, and responsible deployment across federal programs. Several Asia-Pacific governments have introduced national AI strategies supporting research investment while encouraging responsible innovation.
Industry standards addressing AI risk management, cybersecurity, model governance, documentation, and lifecycle management are becoming increasingly important during enterprise procurement. Buyers increasingly request evidence of security controls, bias monitoring, explainability mechanisms, and ongoing model governance before approving commercial deployments.
Outlook and Strategic Implications
Commercial investment over the forecast period is expected to concentrate on enterprise foundation models, multimodal AI systems, industry-specific language models, efficient training architectures, and optimized inference technologies. Organizations will increasingly prioritize solutions capable of utilizing proprietary datasets while maintaining compliance with evolving regulatory requirements.
Procurement strategies are shifting toward integrated AI ecosystems combining accelerated hardware, cloud infrastructure, MLOps platforms, governance tools, and pretrained models. Buyers increasingly prefer vendors offering end-to-end deployment capabilities rather than isolated machine learning components.
Technology development is expected to emphasize computational efficiency, smaller domain-adapted models, synthetic data generation, retrieval-enhanced architectures, and privacy-preserving learning techniques. Competitive differentiation will increasingly depend on measurable enterprise productivity gains, lower operating costs, and secure deployment across hybrid computing environments.
Despite challenges associated with computational expenses, governance requirements, and talent availability, self-supervised learning is expected to remain a foundational technology supporting enterprise AI adoption. Organizations capable of integrating efficient infrastructure, responsible AI governance, and domain-specific expertise will be better positioned to capture commercial opportunities as enterprises expand investments in advanced machine learning applications.
Self-Supervised Learning Market Scope
| Report Metric | Details |
|---|---|
| Forecast Unit | Billion |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Learning Method, Application, End-User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Learning Method
By Application
By End-user
By Geography
Geographical Segmentation
- Middle East and Africa
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. SELF-SUPERVISED LEARNING MARKET BY LEARNING METHOD
5.1. Introduction
5.2. Contrastive Learning
5.3. Predictive (Self-Predictive) Learning
5.4. Generative Self-Supervised Learning
5.5. Masked Modeling
5.6. Clustering-Based Learning
6. SELF-SUPERVISED LEARNING MARKET BY APPLICATION
6.1. Introduction
6.2. Natural Language Processing (NLP)
6.3. Computer Vision
6.4. Speech Recognition
6.5. Robotics and Autonomous Systems
6.6. Recommendation Systems
6.7. Others
7. SELF-SUPERVISED LEARNING MARKET BY END-USER
7.1. Introduction
7.2. BFSI
7.3. Healthcare
7.4. Retail & E-commerce
7.5. Automotive & Transportation
7.6. Manufacturing
7.7. IT & Telecommunications
7.8. Media & Entertainment
7.9. Government & Public Sector
7.10. Others
8. SELF-SUPERVISED LEARNING MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. United Kingdom
8.4.2. Germany
8.4.3. France
8.4.4. Italy
8.4.5. Spain
8.4.6. Others
8.5. Middle East & Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Australia
8.6.6. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Google LLC
10.2. Microsoft Corporation
10.3. Meta Platforms, Inc.
10.4. Amazon.com, Inc.
10.5. IBM Corporation
10.6. NVIDIA Corporation
10.7. Intel Corporation
10.8. Baidu, Inc.
10.9. DataRobot, Inc.
10.10. Databricks, Inc.
10.11. The MathWorks, Inc.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations





Frequently asked questions
What is the projected growth trajectory for the Self-Supervised Learning Market between 2026 and 2031?
The Self-Supervised Learning Market is expected to show steady growth over the forecasted period of 2026 to 2031. This growth is primarily driven by organizations seeking to leverage large volumes of unlabeled data more efficiently. The market's expansion is closely linked to the increasing deployment of advanced AI applications across various sectors.
Which major industries are adopting Self-Supervised Learning techniques, and what are their primary motivations?
Key industries adopting self-supervised learning include banking, healthcare, manufacturing, retail, telecommunications, and automotive sectors. Their primary motivation is to reduce the high cost and time associated with manual data labeling while simultaneously improving model accuracy and scalability. This allows them to extract value from proprietary, domain-specific datasets.
Who are the main types of players contributing to the industry structure of the Self-Supervised Learning market?
The industry structure comprises hyperscale cloud providers, semiconductor manufacturers supporting complex model training, and AI software vendors offering pretrained foundation models and developer frameworks. Additionally, open-source ecosystem contributors, enterprise platform providers, and specialist machine learning companies play significant roles in this evolving market.
What key technological and commercial drivers are fueling demand for Self-Supervised Learning solutions?
Demand for self-supervised learning is primarily driven by the expanding deployment of generative AI, foundation models, multimodal systems, and autonomous technologies. The increasing investment in enterprise AI applications and proprietary AI models trained on internal domain-specific datasets also acts as a significant commercial driver. These factors emphasize the need for cost-effective data utilization without extensive labeling.
What are the critical evaluation criteria for commercial buyers when considering Self-Supervised Learning platforms?
Commercial buyers prioritize model performance, scalability across cloud and on-premises environments, and compatibility with existing MLOps pipelines. Other critical factors include robust data privacy controls, inference efficiency, and comprehensive support for multiple data modalities such as text, images, speech, sensor streams, and video. Procurement decisions often involve collaboration among various C-suite and engineering teams.
Beyond traditional software licensing, what diverse revenue generation models exist within the Self-Supervised Learning market?
Revenue generation extends beyond software licensing to include managed AI services, cloud computing resources, and specialized consulting and model optimization services. Organizations also purchase infrastructure acceleration hardware and industry-specific AI platforms. Long-term commercial value is further supported by continuous model retraining, maintenance contracts, and enterprise AI subscriptions.
Cite this report
Knowledge Sourcing Intelligence. (Jul 2026). Self-Supervised Learning Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/self-supervised-learning-market