
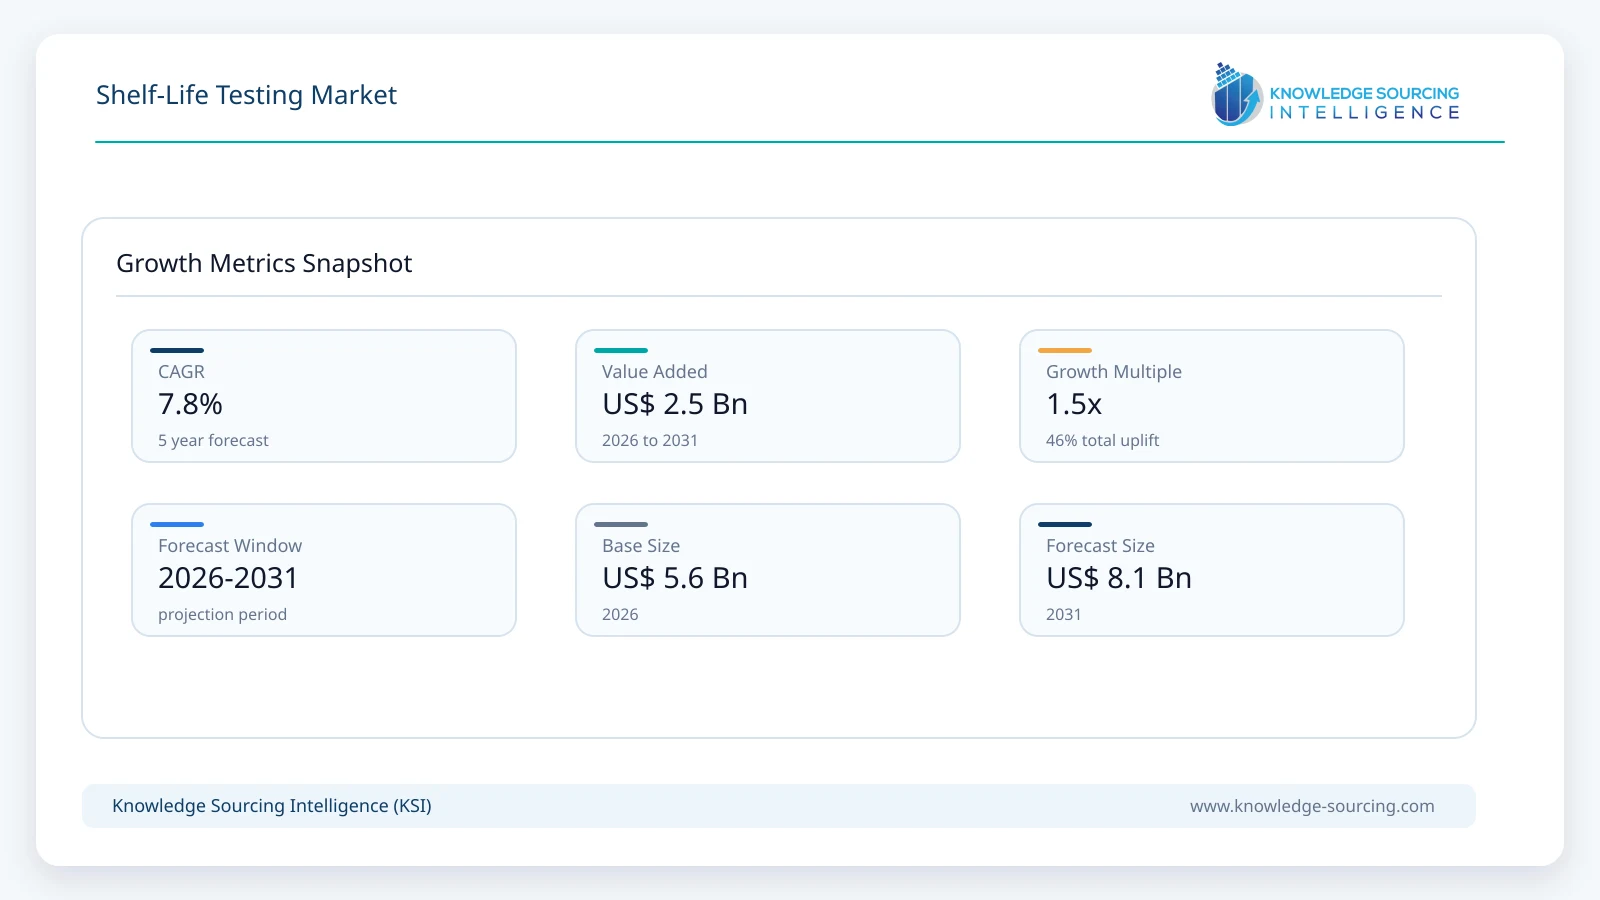
The shelf-life testing market is forecast to grow at a CAGR of 7.8%, increasing from approximately USD 5.56 billion in 2026 to USD 8.09 billion in 2031.
Highlights:
- 1Microbial contamination testing accounts for approximately 37% of global shelf-life testing market value in 2026 as pathogen and spoilage-organism behaviour remains central to safety-based shelf-life determination.
- 2Packaged food represents approximately 31% of market value in 2026, reflecting the diversity of storage conditions, formulations and packaging systems requiring product-specific shelf-life validation.
- 3Real-time testing accounts for approximately 61% of market value in 2026 because storage under intended commercial conditions remains the principal method for confirming actual product durability.
- 4Equipment- and kit-based testing represents approximately 58% of market value in 2026 as laboratories increase the use of PCR, automated microbiology and analytical instrumentation.
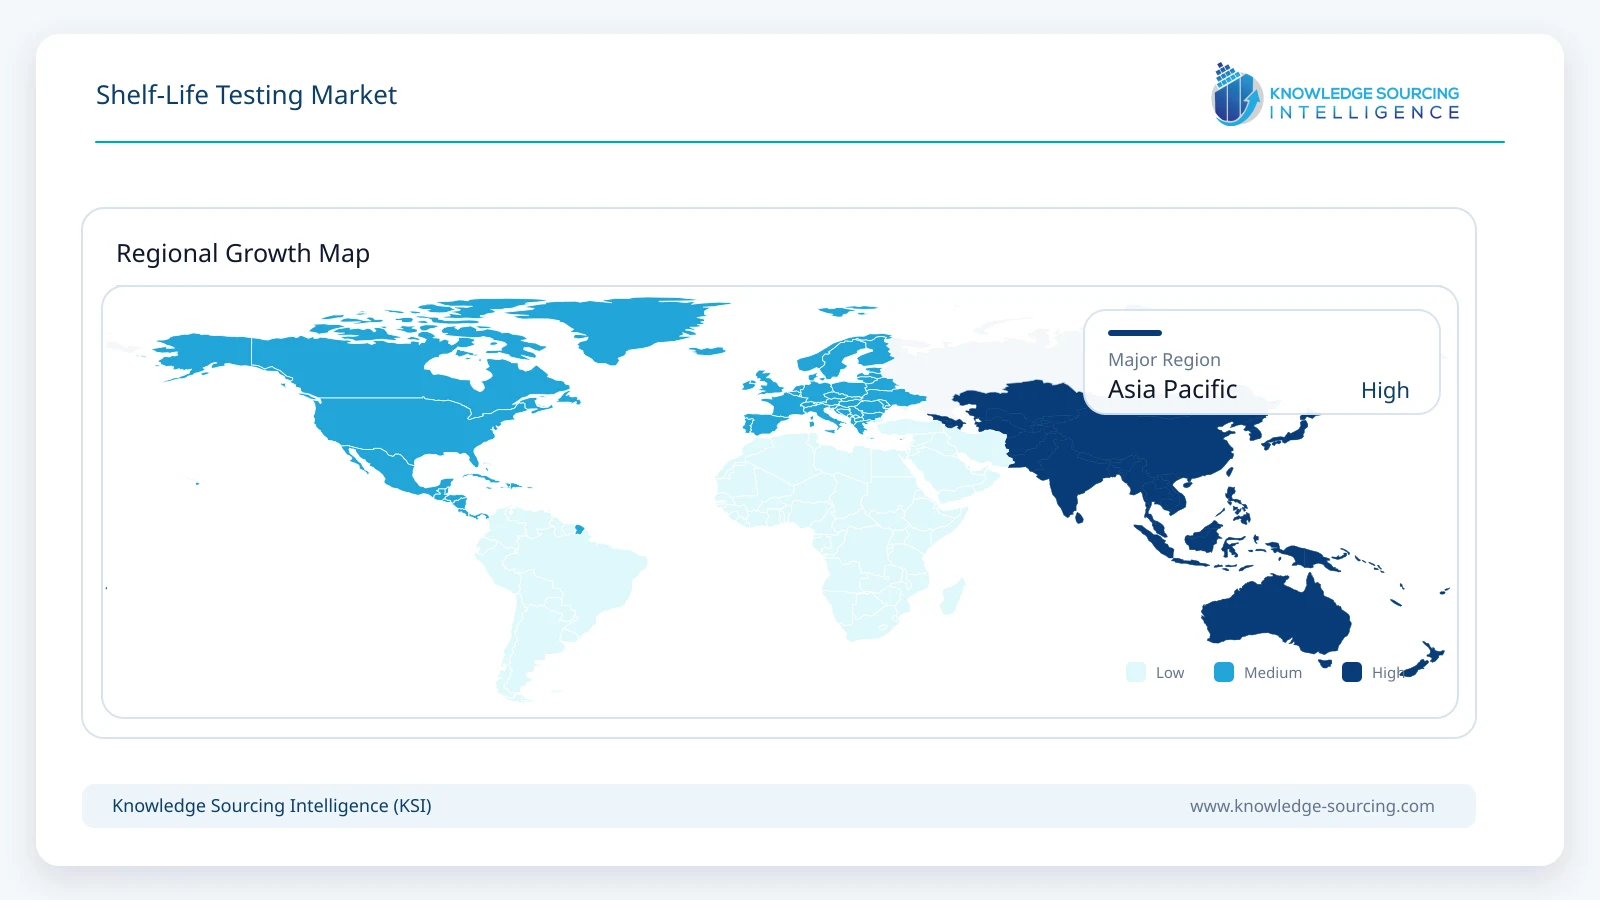
- 5Asia Pacific accounts for approximately 34% of global market value in 2026 and is also expected to record the strongest regional growth through 2031.
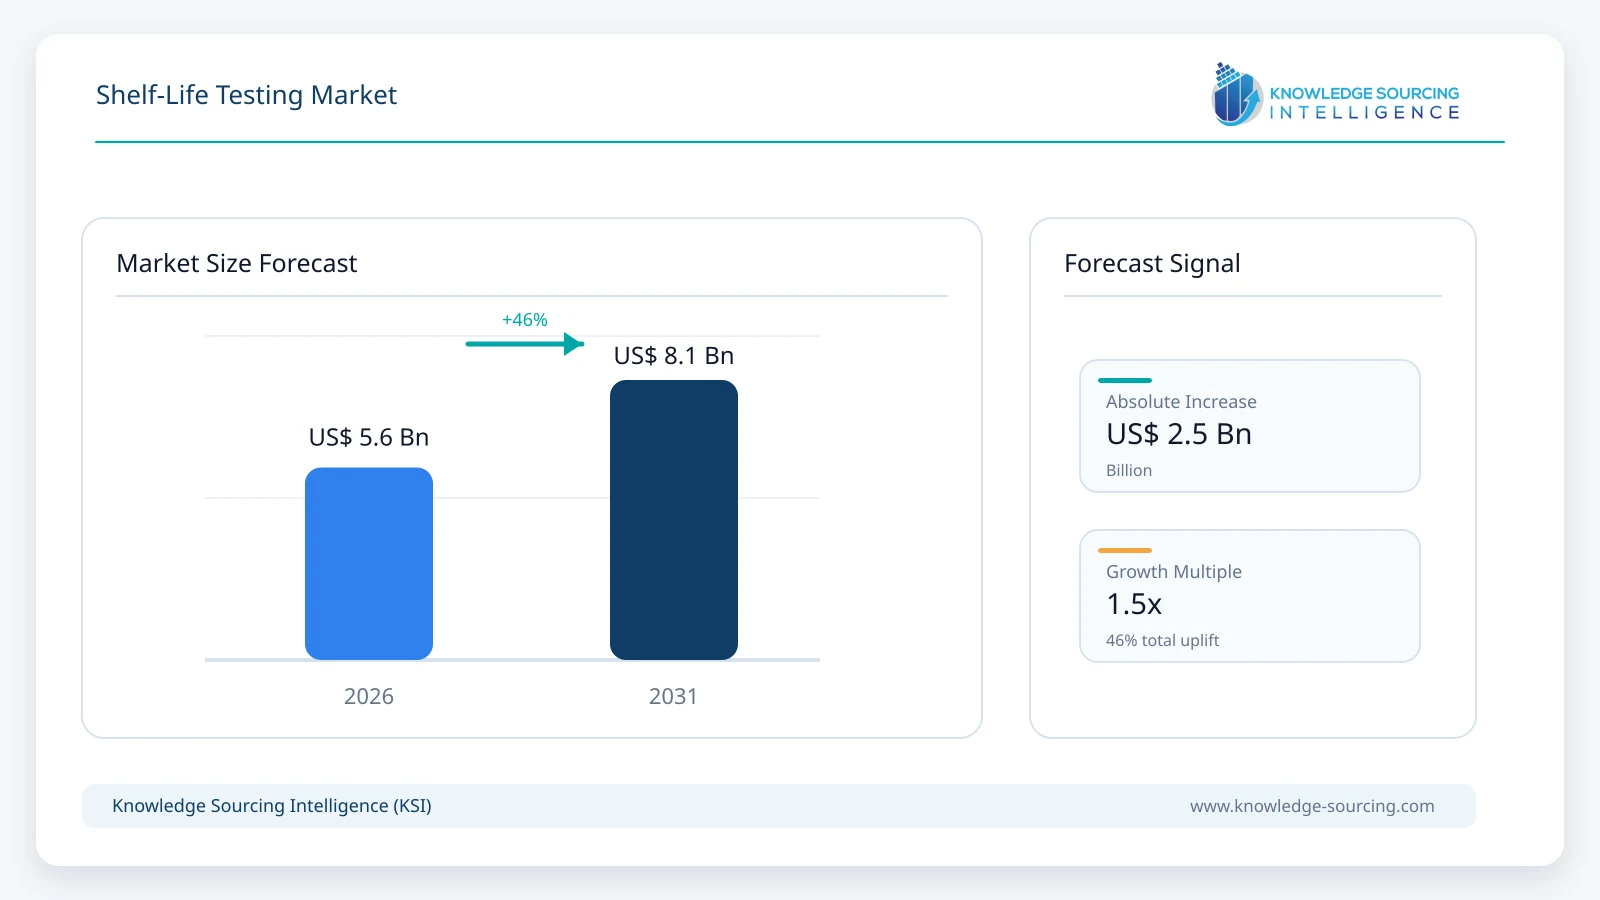
The market covers laboratory testing and related analytical services used to determine the period during which food and beverage products remain safe, microbiologically stable and acceptable in terms of sensory, chemical, physical and nutritional characteristics.
Shelf-life determination normally combines several analytical parameters rather than relying on a single test. Intertek identifies microbiological organisms, moisture content, acidity, pH, water activity and fat rancidity among the variables evaluated during food shelf-life studies. Mérieux NutriSciences similarly uses microbiological, physicochemical, sensory and nutrient-stability measurements, while SGS offers both real-time and accelerated shelf-life studies under controlled storage conditions.
Microbiological safety is becoming particularly important for refrigerated and ready-to-eat foods. ISO 20976-1 establishes requirements for food and feed challenge tests used to determine microbial growth potential, lag time and maximum growth rate, and the standard was reviewed and reconfirmed in 2025.
Market Overview
Shelf-life testing determines how safety and quality characteristics change between production and the end of a product’s commercial life. Product formulation, water activity, acidity, processing method, packaging permeability, storage temperature, oxygen exposure and microbial ecology can all influence the final shelf-life decision. Testing protocols therefore differ substantially between chilled ready meals, dairy products, meat, bakery products, beverages and ambient packaged foods.
The commercial importance of accurate testing extends beyond compliance. Shelf lives that are too long can expose manufacturers to microbiological or quality failures, while unnecessarily short dates can increase product write-offs and food waste. The European Commission estimates that up to 10% of annual food waste in the European Union is linked to date marking and states that product-life information should be consistent with safety and quality testing rather than shortened unnecessarily for other reasons.
This creates a dual role for shelf-life laboratories. They must demonstrate that products remain safe throughout the labelled period while also helping manufacturers identify whether formulations, preservation processes or packaging changes can safely extend commercial life.
Market Trends
Microbiological Challenge Testing Is Becoming More Important
Challenge testing is becoming increasingly important for foods where pathogen growth during storage presents a meaningful risk. Laboratories deliberately inoculate products with specified microorganisms and observe growth, survival or inactivation under controlled conditions. Eurofins identifies Listeria monocytogenes, Bacillus cereus and Staphylococcus aureus among common pathogens evaluated through challenge studies, alongside spoilage organisms such as moulds, yeasts and lactic acid bacteria.
The regulatory relevance increased materially in Europe from July 2026. Commission Regulation (EU) 2024/2895 requires ready-to-eat foods capable of supporting Listeria monocytogenes growth to meet the applicable criterion throughout shelf life. Where a producer cannot demonstrate that contamination will remain at or below 100 cfu/g, Listeria must not be detected in 25 grams during the product’s commercial life.
This creates direct demand for durability studies, challenge tests, predictive microbiology and expert interpretation rather than routine end-product testing alone.
Accelerated Shelf-Life Testing Is Expanding but Requires Validation
Food manufacturers increasingly use accelerated shelf-life testing when real-time studies would delay product development for months or years. Accelerated studies typically increase temperature, humidity, oxygen exposure or other deterioration factors and then model behaviour under intended commercial conditions.
A 2025 peer-reviewed study on high-pressure-processed meat products described conventional real-time shelf-life determination as labor-intensive and time-consuming, often requiring several months, and evaluated accelerated testing as a way to produce usable predictions earlier.
The method is most useful when the deterioration mechanism remains consistent between accelerated and normal conditions. Complex foods can behave differently when exposed to excessive temperature or other stress, which means real-time validation remains important even as predictive techniques improve.
Shelf-Life Testing Is Becoming Part of Food-Waste Reduction Strategies
Shelf-life optimization is moving beyond a purely safety-oriented function. Food companies are increasingly evaluating whether formulations, packaging materials, preservation technologies or distribution conditions can extend acceptable product life and reduce losses.
The European Commission links up to 10% of EU food waste with date marking and specifically states that use-by and best-before periods should correspond to safety and quality test results. SGS also positions shelf-life studies as a means of identifying how ingredients, packaging and storage conditions can lengthen usable life and reduce food waste.
This expands commercial demand from regulatory validation toward product reformulation, packaging optimization, sensory studies and comparative storage trials.
Market Drivers
Tighter Listeria Requirements for Ready-to-Eat Foods
The July 2026 implementation of Commission Regulation (EU) 2024/2895 materially strengthens the commercial requirement for scientifically validated shelf life in Europe. Ready-to-eat foods capable of supporting Listeria growth must meet the applicable microbiological criterion throughout their commercial life, and producers unable to demonstrate that concentrations remain below 100 cfu/g face a not-detected-in-25-g criterion.
The requirement increases demand for challenge tests, durability studies and predictive microbiology because manufacturers must demonstrate microorganism behaviour across the complete labelled shelf life rather than rely only on testing before products leave their immediate control.
Persistent Foodborne Disease and Ready-to-Eat Food Risk
Foodborne illness remains a substantial global public-health problem. WHO estimates that almost one in ten people worldwide become ill from contaminated food each year and more than 420,000 die.
Listeria presents a particularly important shelf-life risk because it can continue growing under refrigeration in suitable ready-to-eat products. EFSA reported in December 2025 that Listeria produced the highest proportion of hospitalisations and deaths among foodborne infections reported in the EU during 2024.
These risks create recurring testing requirements for product reformulation, process changes and shelf-life extensions, particularly in chilled foods, meat, dairy and ready-to-eat categories.
Pressure to Reduce Waste Without Shortening Safe Product Life
Food manufacturers and retailers are seeking longer usable product lives to reduce write-offs while maintaining microbiological and sensory integrity. The European Commission estimates that up to 10% of annual EU food waste is associated with date marking and stresses that labelled product life should reflect safety and quality evidence.
This creates demand for comparative formulation studies, packaging trials, sensory testing and accelerated studies aimed at establishing whether a product can remain commercially acceptable for longer without increasing risk.
Market Restraints
Real-Time Testing Can Delay Product Launches
Real-time studies are scientifically robust but can require the full expected storage period before manufacturers obtain final results. A product designed for a one-year commercial life can therefore generate a long testing programme involving repeated sampling, laboratory storage and multiple analytical measurements.
Microbac notes that shelf-life programmes extending beyond one year may require preliminary reporting before the final study is complete, illustrating the long lead times associated with conventional programmes.
Accelerated techniques reduce this delay but do not eliminate the need for validation, particularly where microbial or sensory deterioration cannot be reliably extrapolated from elevated-temperature conditions.
Accelerated Models Do Not Transfer Reliably Across Every Food Matrix
Food deterioration may involve multiple chemical, microbiological and physical mechanisms that respond differently to temperature, humidity and oxygen. Accelerated conditions can therefore change the principal deterioration mechanism instead of simply increasing its rate.
Research on accelerated shelf-life testing notes that real-time simulation is expensive and time-consuming, while accelerated methods require appropriate kinetic assumptions and validation for the specific product. Complex food systems can generate greater prediction uncertainty than simple shelf-stable formulations.
This prevents laboratories from applying a single predictive model across all food categories and maintains the requirement for product-specific protocol design and expert interpretation.
Segment Analysis
By Parameter: Microbial Contamination
Microbial contamination testing represents the leading parameter because microbiological growth can determine whether a product presents a safety risk before sensory deterioration becomes apparent. Shelf-life studies commonly evaluate pathogens together with spoilage microorganisms and general quality indicators, while higher-risk foods may require dedicated challenge tests.
The microbial-contamination segment is projected to reach approximately USD 3.18 billion by 2031, representing growth of around 9.1% annually from 2026. Ready-to-eat foods, chilled meals, dairy, meat products and minimally processed foods provide particularly strong demand because temperature and product characteristics can allow microbial populations to change materially during distribution.
WHO continues to estimate that contaminated food causes approximately 600 million illnesses and more than 420,000 deaths globally each year, maintaining regulatory and commercial pressure for stronger microbiological risk management throughout food supply chains.
By Food Tested: Packaged Food
Packaged foods form the largest product category because the segment covers a wide range of ready meals, sauces, snacks, shelf-stable foods and refrigerated products with substantially different deterioration mechanisms. Packaging changes can also alter oxygen transmission, moisture migration, microbial behaviour and sensory performance, requiring shelf-life validation whenever formulations or packaging systems are materially modified.
The packaged-food testing segment is projected to reach approximately USD 2.45 billion by 2031, with growth of around 7.3% annually during the forecast period. Demand is increasingly associated with reformulation, clean-label preservation, reduced preservative levels and packaging changes rather than only the initial launch of a product.
Intertek notes that ingredient consistency, moisture, acidity, storage conditions and packaging materials all contribute to product shelf life, reinforcing the need for food-specific protocols instead of standardized testing intervals across packaged-food categories.
By Method: Real-Time Testing
Real-time testing remains the principal method because it evaluates food under the actual or closely simulated storage and distribution conditions expected during commercial sale. Samples are removed at scheduled intervals and evaluated for microbiological, chemical, physical or sensory changes until the relevant safety or quality limit is reached.
Real-time testing revenue is projected to reach approximately USD 4.66 billion by 2031. Mérieux NutriSciences describes real-life storage for a period longer than the expected shelf life as the most reliable approach for shelf-life determination, particularly when manufacturers need defensible evidence for labelled dates.
The method’s principal limitation is time. Products expected to remain stable for many months can require equally long studies before final validation, encouraging manufacturers to use accelerated testing during development while maintaining real-time programmes for confirmation.
By Technology: Equipment- and Kit-Based Testing
Equipment- and kit-based testing is increasing as laboratories automate microbiology, chemical analysis and environmental measurements. PCR, rapid pathogen assays, water-activity measurement, chromatographic systems, automated microbial enumeration and digital data acquisition reduce turnaround time and allow more parameters to be incorporated into individual shelf-life programmes.
The segment is projected to grow at approximately 8.5% annually through 2031 and reach about USD 4.84 billion. Rapid methods are especially valuable where laboratories conduct repeated measurements across multiple storage intervals and product batches.
Eurofins currently combines standardized microbiological methods with validated rapid alternatives including PCR and chromogenic media, while Hill Labs uses both traditional and molecular platforms for pathogens and spoilage indicators.
Regional Outlook
Asia Pacific
Asia Pacific represents the largest regional shelf-life testing market and is also expected to record the fastest growth through 2031. Regional demand is supported by large food-processing industries in China, India, Japan, South Korea and Southeast Asia, growing packaged-food distribution and increasing requirements for testing products intended for international export.
The regional market is projected to reach approximately USD 2.90 billion by 2031, representing growth of around 8.9% annually from 2026. Laboratory networks are expanding accordingly. ALS acquired Mumbai-based Audentes Laboratories in July 2026, adding food and consumer-product analytical testing capacity supported by NABL, FSSAI, APEDA, AGMARK and EIC certifications.
Mérieux NutriSciences has also expanded substantially across Asia Pacific through its acquisition of Bureau Veritas food-testing activities in Japan and Southeast Asia and through the Mérieux NutriSciences AQ joint venture covering Australia and Southeast Asia.
Competitive Landscape
The shelf-life testing market combines large international testing networks with regional food laboratories and specialist food-science organizations. Eurofins, SGS, Intertek, ALS and Mérieux NutriSciences maintain broad laboratory networks and provide shelf-life services alongside microbiology, chemistry, nutritional analysis and food-safety testing. Specialist organizations compete through sensory expertise, challenge testing, customized product studies and closer proximity to regional food manufacturers.
Industry consolidation is increasing the geographic scale of the major providers. Mérieux NutriSciences completed the worldwide acquisition of Bureau Veritas’ food-testing business in September 2025. The transaction spanned 15 countries and added nearly 2,000 employees to its laboratory network.
SGS expanded its U.S. food-testing capabilities in March 2026 through the acquisition of Murray-Brown Laboratories, an ISO 17025-accredited laboratory specializing in microbiology and analytical chemistry. ALS followed with the acquisition of Audentes Laboratories in India in July 2026.
The market nevertheless remains fragmented because shelf-life programmes often require local sample storage, product-specific expertise and frequent interaction between laboratories and food manufacturers. Competition therefore depends on geographic coverage, accreditation, storage infrastructure, microbial challenge capability, sensory testing, turnaround time and the ability to interpret results rather than laboratory analysis alone.
Recent Developments
July 2026: ALS completed the acquisition of Audentes Laboratories in Mumbai, expanding food, consumer-product and claim-validation testing capacity in western India.
July 2026: Commission Regulation (EU) 2024/2895 became applicable, strengthening Listeria monocytogenes requirements for ready-to-eat foods throughout their shelf life.
March 2026: SGS acquired Murray-Brown Laboratories in Colorado, expanding its North American food microbiology and analytical chemistry capabilities.
February 2026: Mérieux NutriSciences acquired Zínia Ensaios Laboratoriais in Brazil, adding a food laboratory in Joinville to a Brazilian network that had grown to 18 laboratories and more than 1,000 employees.
June 2025: Mérieux NutriSciences and AsureQuality formally launched Mérieux NutriSciences AQ, combining food-testing and assurance capabilities across Australia and Southeast Asia.
Market Outlook
The shelf-life testing market is forecast to increase. The strongest structural demand comes from microbiological risk management, scientifically defensible date marking and the need to extend usable food life without increasing product-safety risk.
Microbial contamination remains the largest testing parameter as ready-to-eat foods, dairy products, meat and other refrigerated categories require increasing evidence that pathogenic organisms will remain within acceptable limits throughout commercial life. Regulatory developments such as the EU’s revised Listeria requirements strengthen this trend.
Real-time testing remains the largest method through 2031 because direct observation under expected storage conditions provides the strongest evidence for shelf-life validation. Accelerated testing grows faster as food manufacturers attempt to shorten product-development cycles, but its use continues to require product-specific validation.
Asia Pacific maintains the largest regional market and records the strongest growth as packaged-food production, export activity and independent laboratory capacity expand. The region is also attracting investment from major global testing companies seeking to increase local laboratory coverage.
Competition will increasingly depend on the combination of microbiological challenge testing, analytical chemistry, sensory science, predictive modelling and rapid methods. Laboratories able to integrate these capabilities into a single shelf-life programme are better positioned as manufacturers move away from simple expiry-date confirmation toward continuous optimization of formulation, packaging and storage conditions.
Shelf-Life Testing Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 5.56 billion |
| Total Market Size in 2031 | USD 8.09 billion |
| Forecast Unit | Billion |
| Growth Rate | 7.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Parameter, Food Tested, Method, Technology, Geography |
| Companies |
|
Market Segmentation
By Parameter
Microbial Contamination
Rancidity
Nutrient Stability
Organoleptic Properties
Others
By Food Tested
Packaged Food
Beverages
Bakery
Meat & Meat Products
Dairy & Dairy Products
Processed Fruits & Vegetables
Others
By Method
Real-Time
Accelerated
By Technology
Equipment & Kit Based
Manual Tests
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
China
Japan
India
South Korea
Taiwan
Thailand
Indonesia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Research
2.4. Market Estimation
2.5. Segment Modelling
2.6. Data Triangulation and Validation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Shelf-Life Testing Market Size, 2026-2031
3.3. Parameter Outlook
3.4. Food Tested Outlook
3.5. Method Outlook
3.6. Technology Outlook
3.7. Regional Opportunity Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Tighter Listeria Requirements for Ready-to-Eat Foods
4.1.2. Persistent Foodborne Disease and Ready-to-Eat Food Risk
4.1.3. Pressure to Reduce Food Waste Without Shortening Safe Product Life
4.2. Market Restraints
4.2.1. Long Lead Times for Real-Time Shelf-Life Studies
4.2.2. Limited Transferability of Accelerated Models Across Food Matrices
4.3. Porter’s Five Forces Analysis
4.4. Industry Value Chain Analysis
4.5. Regulatory Environment
4.6. Shelf-Life Study Design and Validation
5. SHELF-LIFE TESTING MARKET BY PARAMETER
5.1. Introduction
5.2. Microbial Contamination
5.3. Rancidity
5.4. Nutrient Stability
5.5. Organoleptic Properties
5.6. Others
6. SHELF-LIFE TESTING MARKET BY FOOD TESTED
6.1. Introduction
6.2. Packaged Food
6.3. Beverages
6.4. Bakery
6.5. Meat & Meat Products
6.6. Dairy & Dairy Products
6.7. Processed Fruits & Vegetables
6.8. Others
7. SHELF-LIFE TESTING MARKET BY METHOD
7.1. Introduction
7.2. Real-Time
7.3. Accelerated
8. SHELF-LIFE TESTING MARKET BY TECHNOLOGY
8.1. Introduction
8.2. Equipment & Kit Based
8.3. Manual Tests
9. SHELF-LIFE TESTING MARKET BY GEOGRAPHY
9.1. North America
9.1.1. USA
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. United Kingdom
9.3.2. Germany
9.3.3. France
9.3.4. Spain
9.3.5. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. Israel
9.4.4. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. Japan
9.5.3. India
9.5.4. South Korea
9.5.5. Taiwan
9.5.6. Thailand
9.5.7. Indonesia
9.5.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Eurofins Scientific SE
11.2. Mérieux NutriSciences
11.3. SGS SA
11.4. Intertek Group plc
11.5. ALS Limited
11.6. Tentamus Group
11.7. Microbac Laboratories, Inc.
11.8. QIMA
11.9. Hill Labs
11.10. Microchem Lab Services (Pty) Ltd.
11.11. Campden BRI
11.12. RSSL
11.13. Normec Foodcare
11.14. NSF
11.15. Agrifood Technology
Navigate
Trusted by the world's leading organizations











