
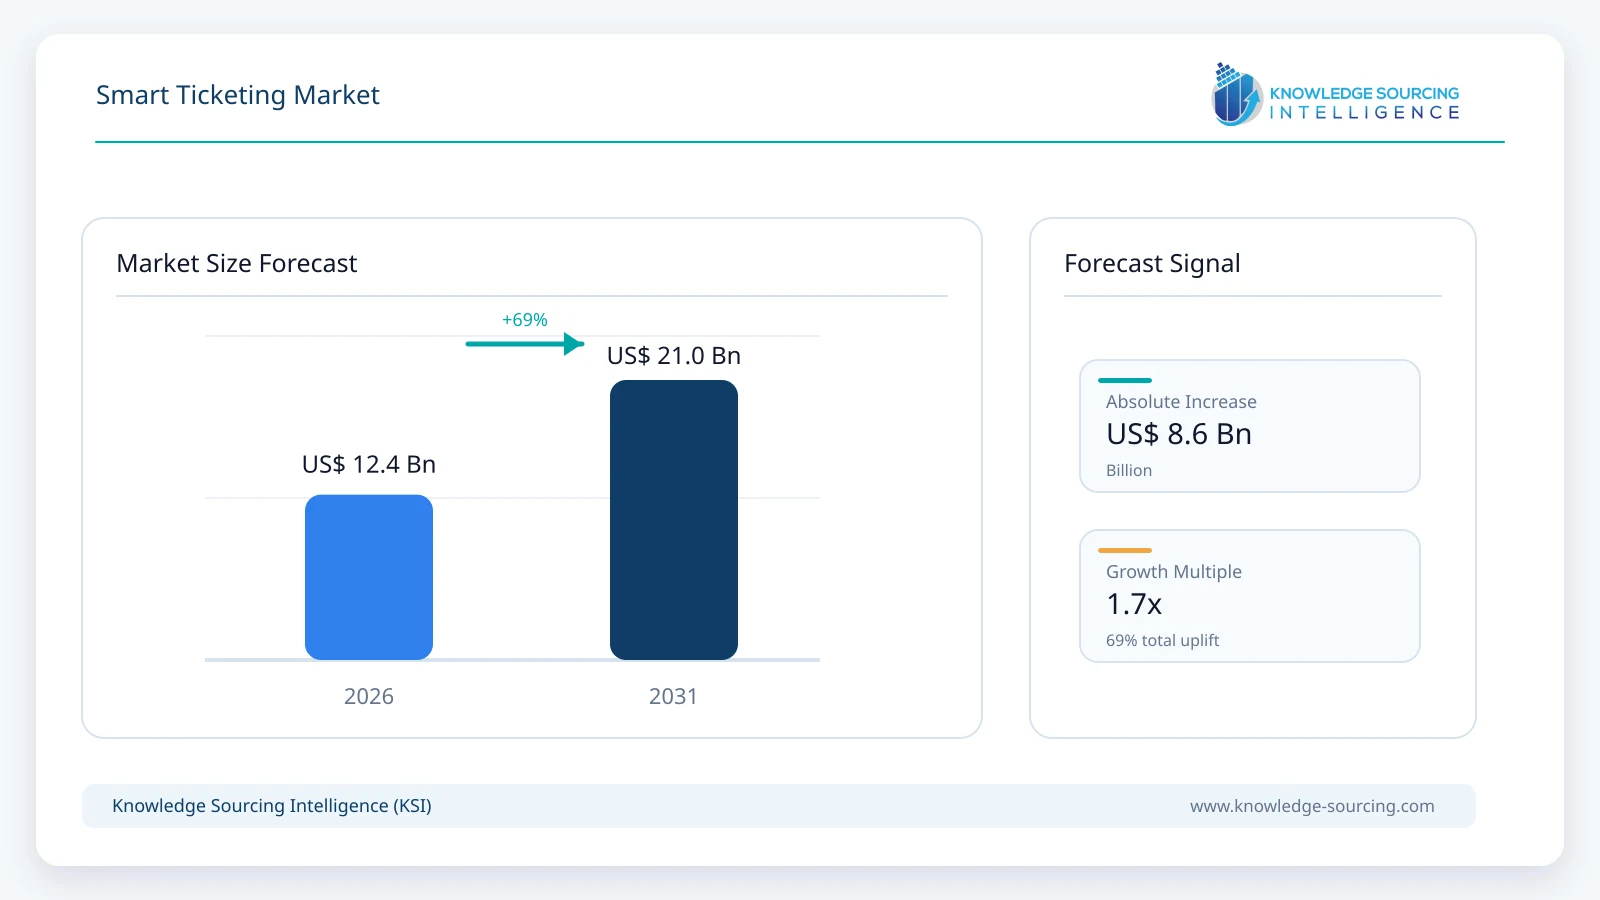
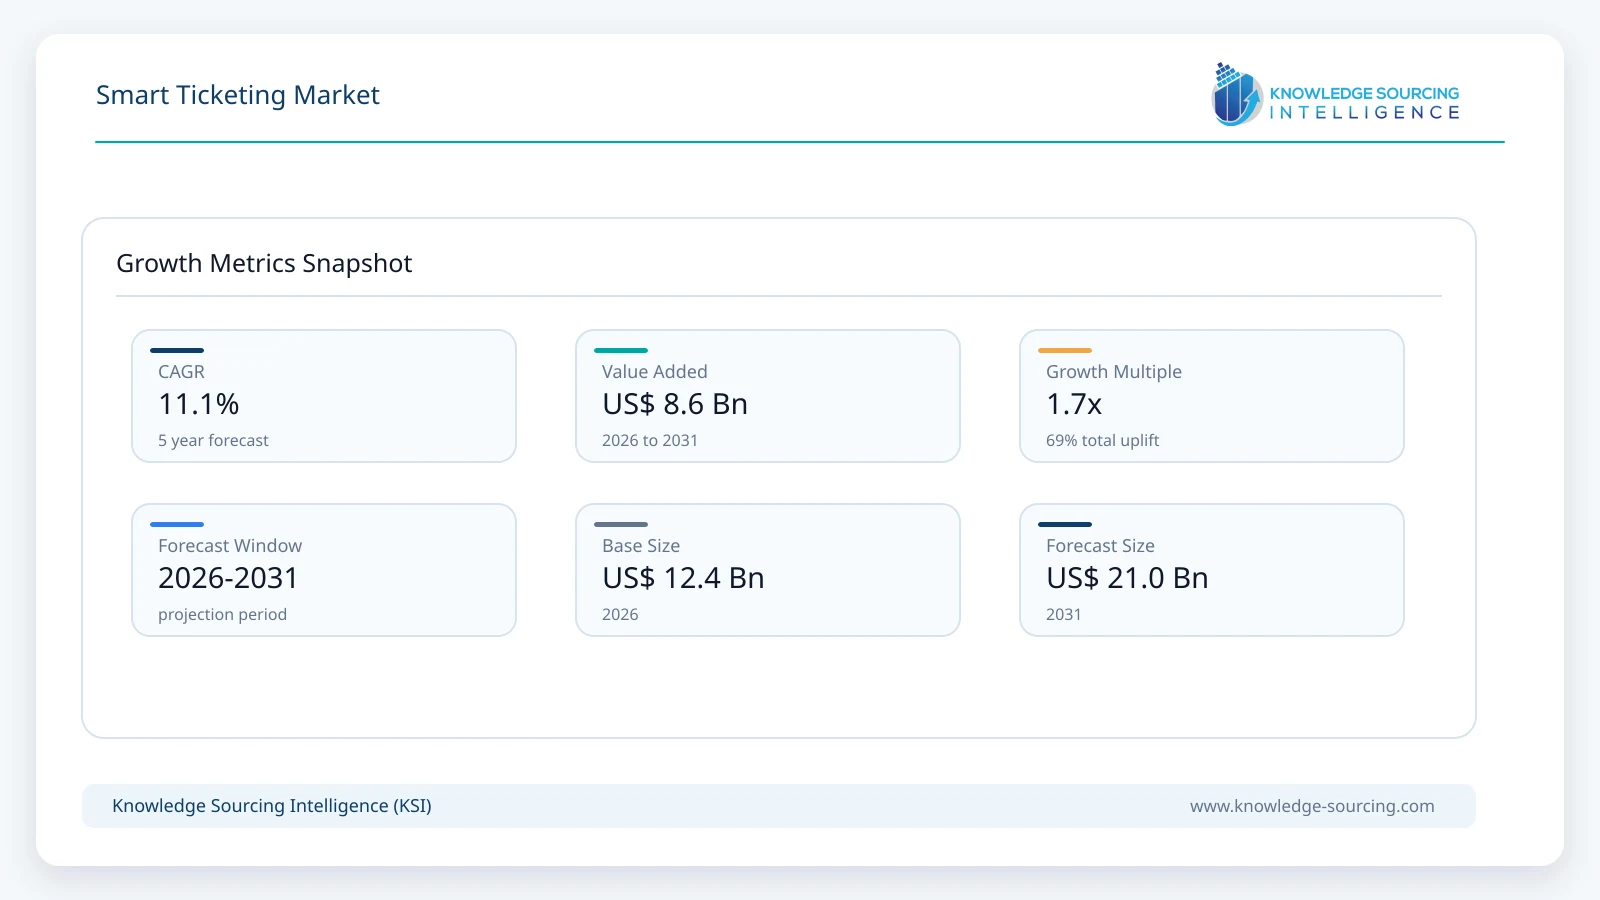
The Smart Ticketing Market is growing at a CAGR of 11.1%, from USD 12.40 billion in 2026 to USD 21.00 billion by 2031.
Highlights:
- 1Software accounts for approximately 38% of global smart ticketing revenue in 2026.
- 2Open-loop bank-card and mobile-wallet ticketing is projected to grow at approximately 14.5% annually through 2031.
- 3Transportation applications generate about USD 8.4 billion of global smart ticketing market value in 2026.
- 4Europe accounts for approximately 32% of global smart ticketing revenue in 2026.
- 5Account-based ticketing is shifting fare rules and customer accounts from physical media into centralized back offices.
- 6QR, NFC and EMV contactless technologies are increasingly deployed together rather than as mutually exclusive ticketing formats.
Smart ticketing has evolved from electronic replacement of paper tickets into a wider revenue-management architecture. In a traditional closed-loop system, the fare product and stored value may reside on an operator-issued smart card. In an account-based ticketing system, the travel entitlement and fare calculation move to a central back office, while the passenger presents a token such as a transit card, QR code, mobile device or payment card. Open-loop systems extend this model by accepting EMV contactless bank cards and mobile wallets directly at the validator or gate. This allows agencies to support tap-and-go travel without requiring every occasional rider to purchase or reload dedicated fare media.
The market therefore spans more than gates and validators. A modern deployment can include account management, fare engines, payment gateways, clearing and settlement, fraud controls, inspection tools, mobile applications, card management, analytics, device management and customer-service portals. UITP notes that public-transport ticketing now encompasses closed-loop cards, open-loop payment, mobile ticketing, QR codes and account-based architectures. Suppliers increasingly differentiate on how easily these layers can be integrated with legacy systems and with third-party payment, journey-planning and mobility services rather than on a single hardware component.
Market Trends
Account-based and open-loop architectures are replacing media-centric fare systems
The most important structural change is the migration of fare intelligence from the ticket or card into the back office. This gives operators more flexibility to apply daily or monthly fare caps, concessions and multimodal rules while allowing passengers to use several credentials against the same account. Visa reported that it had supported more than 750 contactless public-transit projects worldwide, and UITP continues to promote open-loop implementation through its Urban Mobility Open Payments Forum. In the United States, open payments are spreading beyond the largest systems: San Joaquin Regional Transit District launched contactless bank-card and mobile-wallet acceptance with fare capping in July 2026, while several other medium-sized agencies introduced account-based or open-payment systems during the first half of the year.
Cloud-native fare collection and software-as-a-service are reducing deployment barriers
Ticketing procurement historically involved multi-year bespoke implementations with large on-premise back offices and tightly coupled hardware. Cloud-native fare platforms are changing this model by separating the core fare engine from local equipment and providing continuous software updates. Masabi positions its Justride platform around fare payments as a service, while Cubic has extended open payments to its Umo platform for smaller and mid-sized agencies. This model does not eliminate integration work, but it lowers the need for every agency to build and maintain a proprietary back office. QR and mobile-first deployments complement this trend because they allow agencies to digitize parts of the fare system before replacing all onboard validators or station equipment.
Market Drivers
Public transport modernization and interoperability programs sustain the largest investment pool
Public transport remains the core driver because fare systems are mission-critical infrastructure and are replaced or upgraded over long operating cycles. New York is completing the move from MetroCard toward OMNY, with tap-and-go required across subway and bus services as the legacy payment medium is phased out during 2026. India is expanding interoperable fare collection through the National Common Mobility Card, which the Ministry of Housing and Urban Affairs reported as functional in 13 metro projects and 11 bus corporations by July 2026. The PM-eBus Sewa guidelines also include NCMC-based automatic fare collection. These programs create demand for validators, gates, ticketing software, payment processing and long-term operations rather than a single one-time ticketing device purchase.
Contactless payment behavior is raising passenger expectations for frictionless ticketing
The second demand driver comes from consumer payment behavior. Riders increasingly expect to use the same bank card, mobile wallet or smartphone they use in retail, which raises the cost of maintaining cash-heavy or proprietary ticketing systems. Open-loop acceptance is especially attractive for visitors and occasional passengers because it removes ticket purchase and reload steps. Transport operators also gain from lower cash handling, less physical media management and better transaction data. This does not mean closed-loop media disappears: concessionary passengers, unbanked users, children and frequent travelers still require dedicated products in many systems. The commercial opportunity is therefore strongest in hybrid platforms that can support open-loop, closed-loop, mobile and QR payment methods through one back office.
Market Restraint
Legacy integration, payment security and inclusion requirements make fare-system replacement complex
Smart ticketing projects remain difficult to standardize because fare rules, concessions, operator contracts and legacy equipment vary significantly by city and country. An open-payment deployment must coordinate validators, payment schemes, acquiring banks, risk controls, PCI requirements, fare calculation and customer support while maintaining high gate throughput. Agencies also need to preserve access for passengers who do not hold bank cards or smartphones, which prevents a simple transition to fully cashless systems in many markets. Large installed bases of existing gates, smart cards and ticket-vending machines further slow replacement. As a result, procurement can extend over several years and vendors must often integrate modern account-based platforms with legacy front-end devices rather than replace the entire system at once.
Segment Analysis
By Component - Software
Software is the largest component because fare calculation, account management, payments, clearing, device management, fraud controls and analytics increasingly sit in centralized or cloud-hosted platforms. The segment is projected to approach USD 8.1 billion by 2031 as agencies move from device-centric systems toward account-based back offices. Hardware remains essential because validators, gates, kiosks and readers must process passenger interactions at high speed, but software captures a growing share of lifecycle value through hosting, upgrades and integration. Services are expected to grow faster than the market as operators use managed-service contracts for implementation, monitoring, customer support and payment operations.
By Ticketing Medium - Open-Loop Bank Cards and Mobile Wallets
Open-loop bank cards and mobile wallets are the fastest-growing ticketing medium. The model allows a rider to tap an existing contactless payment credential rather than obtain an operator-specific card, making it particularly useful for occasional riders and tourists. Visa, Mastercard and other payment networks have invested in transit acceptance standards, while operators are increasingly combining open-loop payment with fare capping so passengers receive the best available fare without pre-selecting a product. Closed-loop cards remain important for concessions and local fare products, while mobile QR tickets retain a cost advantage for operators that want digital ticketing without replacing every validator with full EMV-certified hardware.
By Technology - NFC and RFID
NFC and RFID remain the largest technology family because both closed-loop smart cards and many mobile-wallet interactions depend on short-range contactless communication. The segment is projected to exceed USD 9.8 billion by 2031 when contactless cards, NFC-enabled devices and associated readers are considered together. QR and barcode ticketing is expanding more quickly in selected bus, rail and event markets because smartphones can generate and display tickets without requiring secure chip issuance. Modern deployments increasingly support both approaches, using NFC for rapid tap transactions and QR codes for digital retail, event access, remote ticket issuance or lower-cost deployments.
By End User - Transportation
Transportation will remain the dominant end-user segment and is projected to exceed USD 14 billion by 2031. Bus, metro, rail, ferry and multimodal operators require fare systems that can process large transaction volumes while enforcing complex fare rules and transferring revenue among agencies. The segment also generates recurring software and services demand because payment certifications, fare policies and back-office integrations continue to evolve after the initial system launch. Media and entertainment uses many of the same mobile and QR technologies, but ticketing platforms in that sector are generally more focused on admission, inventory and resale control than on high-frequency fare calculation.
By Geography - Europe
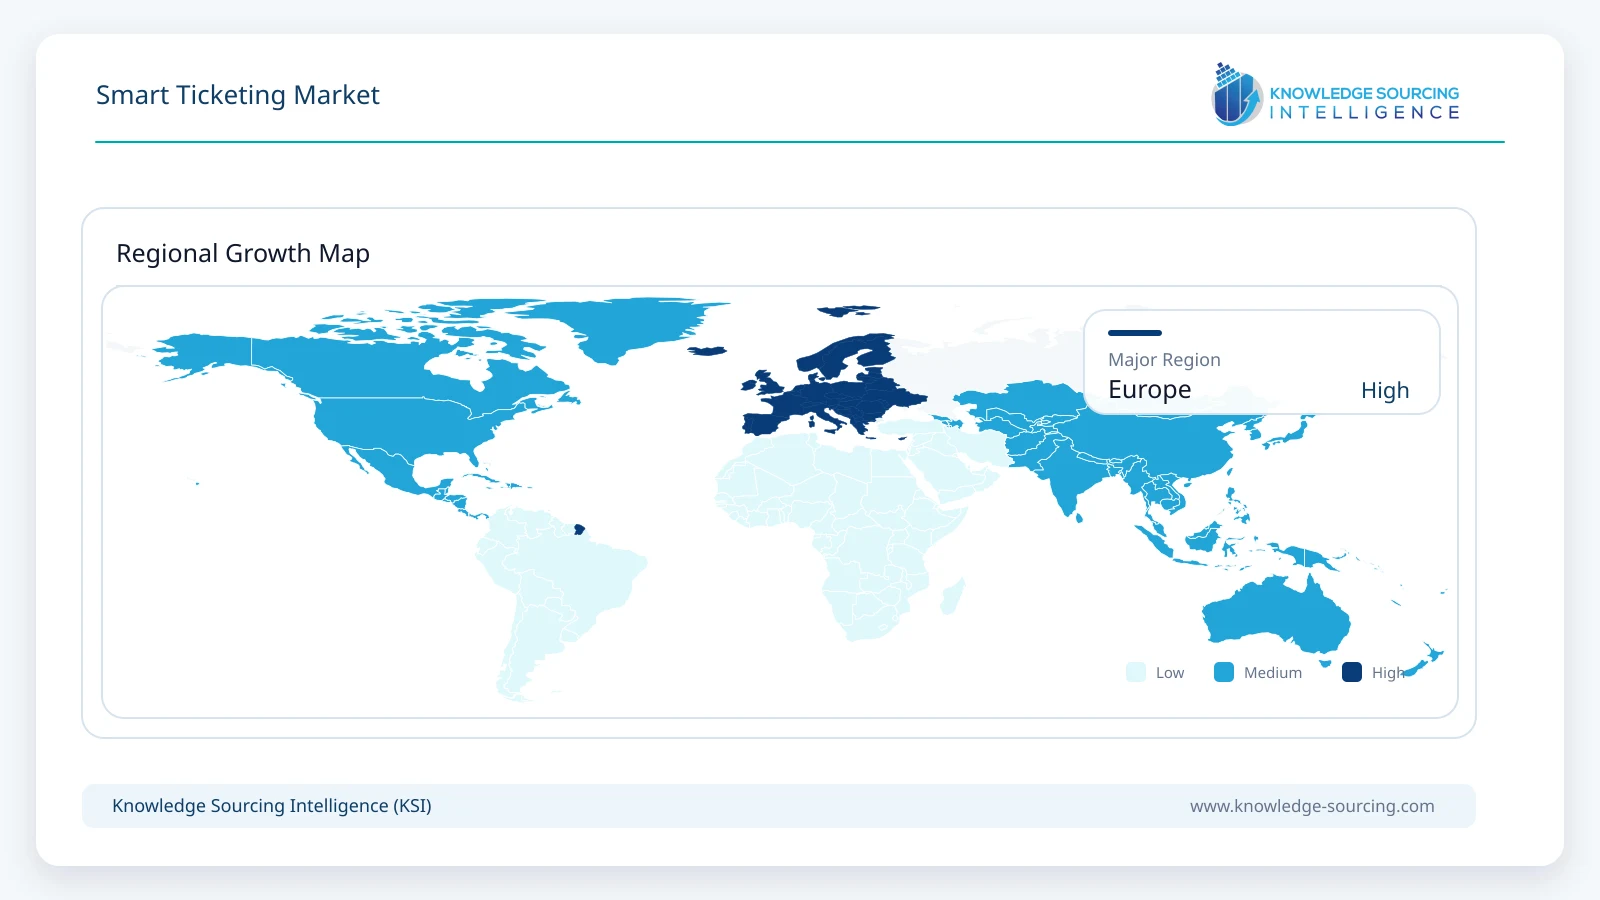
Europe remains the largest regional market and is projected to reach roughly USD 6.5 billion by 2031. The region combines mature contactless payment infrastructure with extensive urban transit networks, national and regional ticketing initiatives and a strong supplier base. The Netherlands demonstrates the scale of open-loop integration through OVpay, while Spain is expanding regional account-based systems such as the Galician Mobility Platform. Asia Pacific is expected to grow faster as metro and bus networks expand and governments pursue interoperable digital payment, particularly in India. North America is also accelerating adoption as agencies outside the largest metropolitan areas add open payments and account-based fare capping.
Competitive Environment
Competition is shifting from closed proprietary systems toward modular platforms that can support multiple fare media and payment methods. Cubic Transportation Systems, Scheidt & Bachmann, Vix Technology, Conduent, Thales, Indra and INIT compete on large integrated fare-collection programs, combining field equipment, back-office software and long-term support. Masabi, Ridango, Littlepay, Kuba and other software-led providers emphasize cloud-native account-based ticketing, open payments and faster deployments. Flowbird remains active in transport ticketing under EasyPark Group ownership, while payment and secure-element suppliers such as NXP and Giesecke+Devrient support the underlying contactless ecosystem.
Competitive advantage increasingly depends on integration rather than exclusive ownership of every layer. Agencies want systems that can accept operator-issued cards, EMV bank cards, mobile wallets and QR products while connecting to journey planning, concessions, inspection and customer-service systems. This favors vendors with open APIs, established payment certifications, strong device-management capabilities and proven high-volume operations. At the same time, procurement models are broadening from large capital projects toward managed-service and subscription structures, allowing smaller agencies to access account-based ticketing capabilities that were historically concentrated in major cities.
Recent Developments
July 2026: San Joaquin Regional Transit District launched open payments with Masabi, allowing riders to tap contactless bank cards or mobile wallets while applying daily and monthly fare caps.
May 2026: Spain’s Galician Mobility Platform reached more than 50% of interurban transport services, advancing a regional account-based ticketing rollout intended to cover more than 120 operators.
February 2026: Masabi acquired Passenger Technology Group, combining fare collection and payments with passenger information, mobile applications and customer-facing digital services.
January 2026: Central Ohio Transit Authority launched open payments across its network using Masabi, expanding tap-and-go bank-card and mobile-wallet acceptance in the Columbus region.
2026: New York continued the final MetroCard-to-OMNY transition, with MetroCard sales ending and contactless tap-and-go becoming the required fare-payment method for subway and bus travel later in the year.
July 2026: India’s Ministry of Housing and Urban Affairs reported National Common Mobility Card functionality across 13 metro projects and 11 bus transport corporations, reinforcing the move toward interoperable fare collection.
Smart Ticketing Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 12.40 billion |
| Total Market Size in 2031 | USD 21.00 billion |
| Forecast Unit | Billion |
| Growth Rate | 11.1% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Ticketing Medium, Technology, End User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Component
Hardware
Software
Services
By Ticketing Medium
Contactless Smart Cards
Open-Loop Bank Cards and Mobile Wallets
Mobile and QR Tickets
Kiosks and Other Ticketing Media
By Technology
NFC and RFID
QR Codes and Barcodes
EMV Contactless and Secure Payment Technologies
Others
By End User
Transportation
Media and Entertainment
Travel and Tourism
Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Italy
Netherlands
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Australia
Singapore
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Public Transport Modernization and Interoperability Programs Sustain the Largest Investment Pool
3.1.2. Contactless Payment Behavior Is Raising Passenger Expectations for Frictionless Ticketing
3.2. Market Restraint
3.2.1. Legacy Integration, Payment Security and Inclusion Requirements Make Fare-System Replacement Complex
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Account-Based Ticketing
4.2. Open-Loop EMV Contactless Payments
4.3. Mobile and QR Ticketing
4.4. Fare Capping, Analytics and AI-Enabled Revenue Protection
5. SMART TICKETING MARKET BY COMPONENT
5.1. Introduction
5.2. Hardware
5.3. Software
5.4. Services
6. SMART TICKETING MARKET BY TICKETING MEDIUM
6.1. Introduction
6.2. Contactless Smart Cards
6.3. Open-Loop Bank Cards and Mobile Wallets
6.4. Mobile and QR Tickets
6.5. Kiosks and Other Ticketing Media
7. SMART TICKETING MARKET BY TECHNOLOGY
7.1. Introduction
7.2. NFC and RFID
7.3. QR Codes and Barcodes
7.4. EMV Contactless and Secure Payment Technologies
7.5. Others
8. SMART TICKETING MARKET BY END USER
8.1. Introduction
8.2. Transportation
8.3. Media and Entertainment
8.4. Travel and Tourism
8.5. Others
9. SMART TICKETING MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. USA
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. France
9.4.3. United Kingdom
9.4.4. Spain
9.4.5. Italy
9.4.6. Netherlands
9.4.7. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. South Africa
9.5.4. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. India
9.6.3. Japan
9.6.4. South Korea
9.6.5. Australia
9.6.6. Singapore
9.6.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Cubic Transportation Systems
11.2. Masabi Ltd.
11.3. Scheidt & Bachmann Fare Collection Systems GmbH
11.4. Vix Technology
11.5. Conduent Transportation
11.6. Thales Group
11.7. Indra Sistemas, S.A.
11.8. INIT Innovation in Traffic Systems SE
11.9. Flowbird Group / EasyPark Group
11.10. Ridango AS
11.11. Kuba
11.12. Littlepay
11.13. Ticketer Group
11.14. NXP Semiconductors N.V.
11.15. Giesecke+Devrient GmbH
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations





Frequently asked questions
What is the projected size and growth rate of the Smart Ticketing Market?
The Smart Ticketing Market will reach USD 21.00 billion by 2031, growing at 11.1% CAGR.
Which component accounts for the largest revenue share in smart ticketing?
Software accounts for approximately 38% of global smart ticketing revenue in 2026.
Which smart ticketing technology is projected for the fastest growth?
Open-loop bank-card and mobile-wallet ticketing will grow at 14.5% annually.
Which application segment generates the most Smart Ticketing Market value?
Transportation applications generated about USD 8.4 billion in 2026.
Which region holds the largest share of global smart ticketing revenue?
Europe accounts for approximately 32% of global smart ticketing revenue in 2026.
What are the primary architectural shifts in smart ticketing?
Account-based and open-loop systems are replacing media-centric fare systems.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Smart Ticketing Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/smart-ticketing-market