Sterilization Pouches Market - Strategic Insights and Forecasts (2026-2031)
Sterilization Pouches Market Size, Share & Trends By Format (Heat-Seal Pouches, Self-Seal Pouches, Reels and Roll Stock), Material (Paper-Film, Tyvek-Film, Specialty Film and Foil), Sterilization Method (Steam, Ethylene Oxide, Hydrogen Peroxide / Low Temperature, Radiation and Other), End User (Hospitals and ASCs, Dental and Physician Practices, Medical Device Manufacturers, Veterinary and Other Healthcare), and Geography
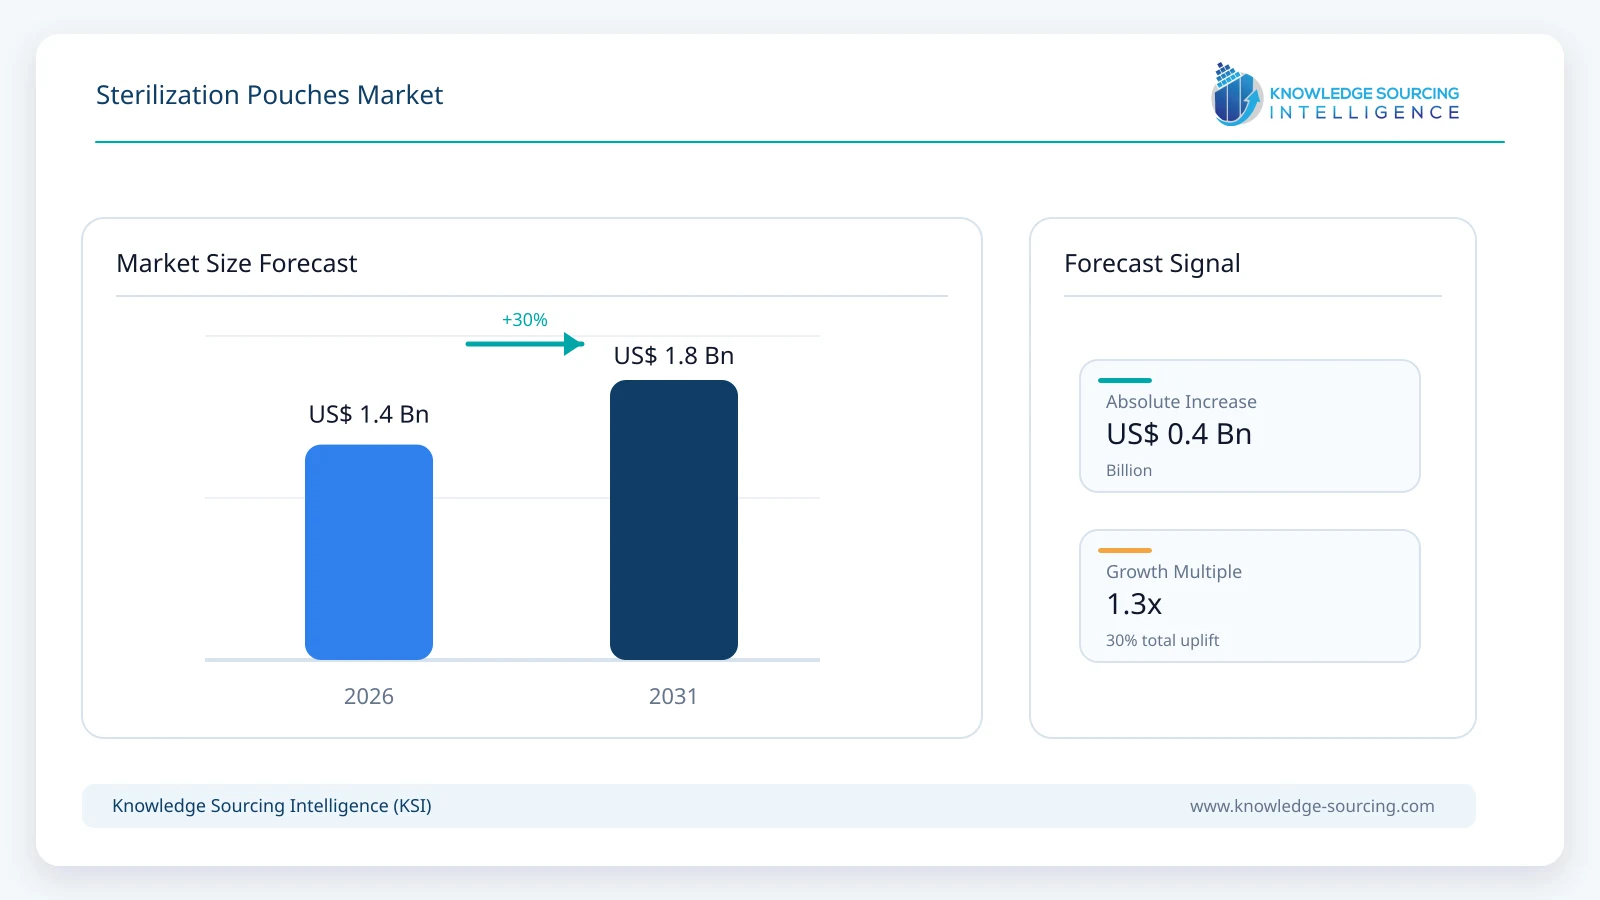
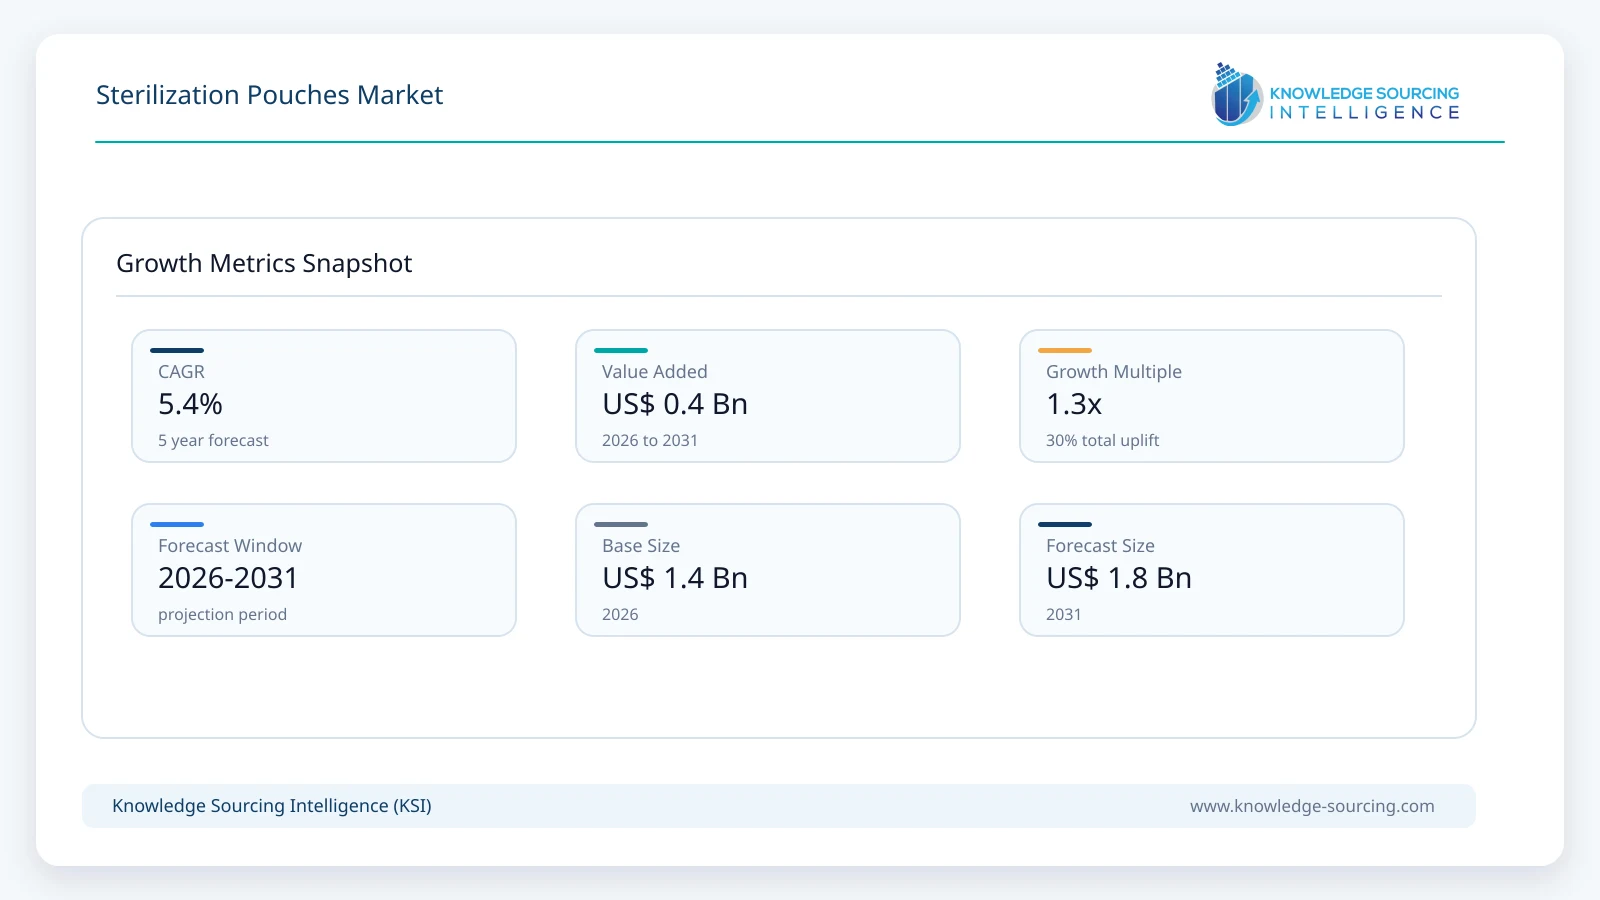
The global sterilization pouches market is estimated at USD 1.40 billion in 2026 and is projected to reach USD 1.82 billion by 2031, growing at a CAGR of 5.4% during the forecast period.
Highlights:
1
Paper-film pouches and reels account for an estimated 68% of 2026 market revenue because steam and ethylene-oxide workflows use them extensively in hospitals, dental practices, and outpatient facilities.
2
CDC guidance explicitly treats peel-open pouches and roll stock/reels as separate packaging options from sterilization wraps and rigid containers.
3
Shanghai Jianzhong received FDA 510(k) clearance in February 2025 for sterilization pouches and reels, confirming current regulatory activity in the category.
4
Anqing Kangmingna reports three production bases, eight workshops, service to more than 80 countries, and a major sterilization-pouch position in China.
5
Tyvek-based pouches are smaller in volume but carry higher average value in low-temperature and medical-device sterile-barrier applications.
Key Highlights
Market Overview
Demand is fundamentally consumables-driven. Hospitals, ambulatory surgical centers, dental clinics, veterinary facilities, and medical-device manufacturers use pouches and reels as single-use sterile-barrier systems. The recurring nature of consumption supports stable growth even when capital spending on sterilizers fluctuates.
Manufacturer evidence confirms a large and geographically distributed supply base. Shanghai Jianzhong obtained a new FDA clearance for sterilization pouches and reels in February 2025. PMS Healthcare Technologies sells paper-film, Tyvek, and EtO pouches/reels; Getinge markets flat sterilization pouches; STERIS sells low-temperature pouches; Oliver, ProAmpac, Amcor, Wipak/SteriKing, VP Group/SteriCLIN, Medicom, Dynarex, and multiple Asian manufacturers participate in finished pouch systems.
Market Drivers and Trends
Procedure and instrument-reprocessing volumes create recurring consumption
Reusable surgical and dental instruments must be packaged after cleaning and before sterilization, and sterile integrity must be maintained through storage and handling. Because pouches are single-use, procedure growth translates more directly into consumable demand than into capital equipment demand.
Outpatient and dental care favor simple self-seal formats
Ambulatory surgery centers, dental practices, veterinary clinics, and smaller facilities often favor self-seal or heat-seal pouches because they are simple to standardize and require less complex wrapping workflows for individual instruments and small sets.
Heat-sensitive devices increasingly use hydrogen-peroxide, ethylene oxide, and other low-temperature processes. Tyvek-based pouches and validated specialty films are important in these applications and carry higher value per unit than basic paper-film steam pouches.
Regulatory and quality requirements support premium suppliers
Seal integrity, microbial barrier performance, puncture resistance, clean peel, sterilization compatibility, and indicator accuracy are critical. FDA clearance, ISO 11607 validation, and EN 868 compatibility create barriers to low-quality substitution.
Market Restraints
Mixed-material sustainability challenges
Paper-film and Tyvek-film structures are difficult to recycle in many healthcare waste streams. Sustainability initiatives therefore pressure manufacturers to reduce material use and develop mono-material or recycle-ready structures without compromising sterile-barrier performance.
Risk of seal failure and handling damage
Wet packs, channel leaks, punctures, tears, improper sealing, and incorrect sterilization compatibility can compromise sterility. These risks increase quality-control requirements and can limit adoption of low-cost unvalidated products.
Alternative sterile-barrier formats
Large or heavy instrument sets are better suited to wraps or rigid containers, placing a natural limit on the pouch addressable market.
Segment Analysis
By Pouch Format
Heat-seal pouches and reels form the largest segment because they are used across hospital central sterile departments and medical-device manufacturing. Self-seal pouches are particularly important in dental, physician-office, veterinary, and lower-throughput settings.
Reels provide flexibility where facilities cut custom pouch lengths, while preformed pouches reduce setup time and support standardized instrument sizes.
By Material Structure
Paper-film structures account for approximately 68% of 2026 revenue. Tyvek-film pouches represent a smaller but faster-growing premium segment because of strong microbial barrier properties and compatibility with selected low-temperature sterilization methods. Foil and specialty barrier pouches occupy niche device-manufacturing applications.
By Sterilization Method
Steam is the largest use case by unit volume. Ethylene oxide remains important for heat-sensitive devices, while hydrogen-peroxide and other low-temperature systems support demand for Tyvek and compatible film structures.
By End User
Hospitals and ambulatory surgical facilities form the largest value segment. Dental practices create very high unit volumes of smaller self-seal pouches. Medical-device manufacturers use more customized, validated pouches and therefore represent a higher-value subsegment despite lower transaction frequency.
Geographic Analysis
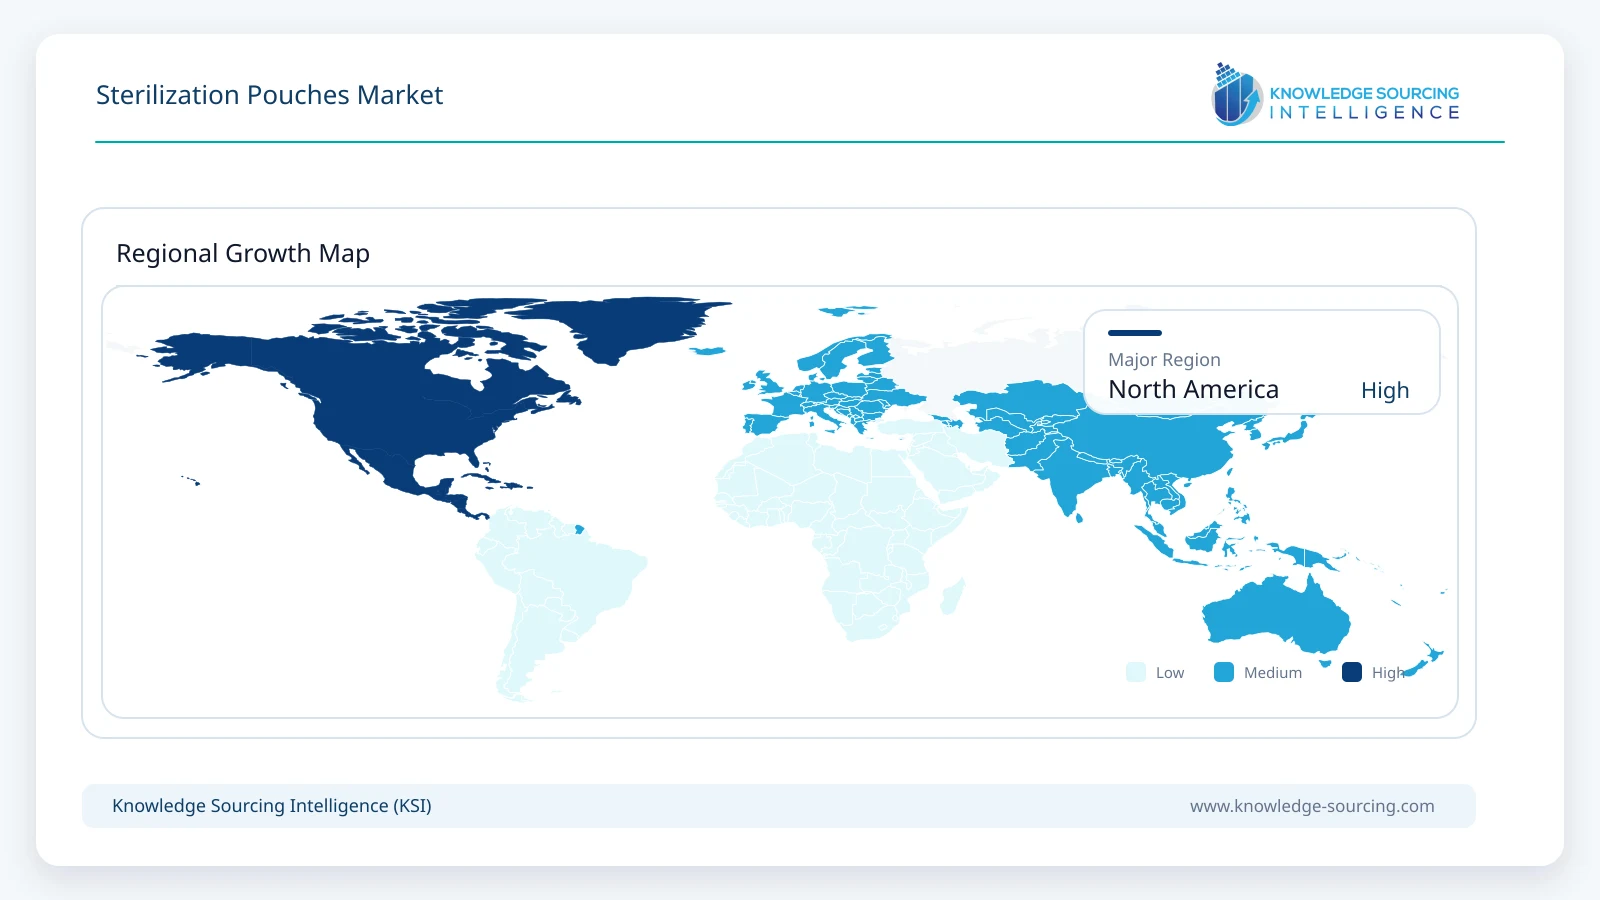
North America
North America is a mature high-value market with large surgical and dental procedure volumes, extensive central-sterile processing, and strong regulatory requirements. Oliver, ProAmpac, Amcor, STERIS, Cardinal Health, Medicom and Dynarex have significant commercial presence.
Europe
Europe is a major market for hospital reprocessing and medical-device sterile-barrier packaging. Wipak/SteriKing, VP Group/SteriCLIN, Getinge and other regional suppliers compete alongside global converters.
Asia Pacific
Asia Pacific is the fastest-growing manufacturing and consumption region. Shanghai Jianzhong, Anqing Kangmingna, PMS Healthcare Technologies, and other regional suppliers have expanded export reach while hospital and medical-device production capacity grows.
South America and Middle East & Africa
Demand is driven by hospital expansion, dental care, and adoption of standardized sterilization workflows, with a higher share of price-sensitive paper-film products.
Competitive Environment
The market includes healthcare-packaging converters, sterilization-system companies with proprietary pouch portfolios, and high-volume Asian manufacturers. Competition is based on seal consistency, sterilization compatibility, barrier performance, clean peel, printing/indicators, regulatory documentation, and delivery reliability.
Material suppliers such as DuPont are not counted as finished-pouch market participants unless they sell the pouch itself.
Recent Developments
• April 2026: Oliver Healthcare Packaging published updated sterile-barrier pouch development guidance and continues to expand its medical pouch material platform.
• February 2026: ProAmpac highlighted Tyvek pouches, header bags, and bags-on-roll for medical sterile-barrier applications at MD&M West.
• January 2026: FDA granted 510(k) clearance K251347 to Sterivic Medical for a sterilization pouch/roll system, confirming continued new-product activity.
• February 2025: FDA granted 510(k) clearance K242898 to Shanghai Jianzhong Medical Packaging for sterilization pouches and reels.
Market Outlook
Sterilization pouches should remain a stable recurring-consumables market through 2031. Growth will be linked to procedures, instrument reprocessing, dental care, outpatient surgery, and medical-device manufacturing rather than dramatic changes in basic pouch geometry.
Premium growth is expected in low-temperature-compatible Tyvek structures, validated high-volume medical-device pouches, stronger traceability/printing, and sustainability improvements.
Sterilization Pouches Market Scope:
Report Metric
Details
Total Market Size in 2026
USD 1.40 billion
Total Market Size in 2031
USD 1.82 billion
Forecast Unit
USD Billion
Growth Rate
5.4%
Study Period
2021 to 2031
Historical Data
2021 to 2024
Base Year
2025
Forecast Period
2026 – 2031
Segmentation
Format, Material, Sterilization Method, End User, Geography
Companies
Amcor plc
Wipak Group / SteriKing
VP Group / SteriCLIN
Getinge AB
STERIS plc
Market Segmentation
By Format
Heat-Seal Pouches
Self-Seal Pouches
Reels and Roll Stock
By Material
Paper-Film
Tyvek-Film
Specialty Film and Foil
By Sterilization Method
Steam
Ethylene Oxide
Hydrogen Peroxide / Low Temperature
Radiation and Other
By End User
Hospitals and ASCs
Dental and Physician Practices
Medical Device Manufacturers
Veterinary and Other Healthcare
By Geography
North America
South America
Europe
Middle East and Africa
Asia Pacific
Table of Contents
1. INTRODUCTION
1.1 Market Definition and Scope
1.2 Sterile Barrier System Boundary
1.3 Exclusions
2. RESEARCH METHODOLOGY
2.1 Procedure and Consumable Demand Framework
2.2 Manufacturer and Regulatory Validation
3. EXECUTIVE SUMMARY
3.1 Market Size and Growth
3.2 Key Findings
4. MARKET DYNAMICS
4.1 Drivers
4.2 Restraints
4.3 Material and Regulatory Trends
5. STERILIZATION POUCHES MARKET BY FORMAT
5.1 Heat-Seal Pouches
5.2 Self-Seal Pouches
5.3 Reels and Roll Stock
6. MARKET BY MATERIAL
6.1 Paper-Film
6.2 Tyvek-Film
6.3 Specialty Film and Foil
7. MARKET BY STERILIZATION METHOD
7.1 Steam
7.2 Ethylene Oxide
7.3 Hydrogen Peroxide / Low Temperature
7.4 Radiation and Other
8. MARKET BY END USER
8.1 Hospitals and ASCs
8.2 Dental and Physician Practices
8.3 Medical Device Manufacturers
8.4 Veterinary and Other Healthcare
9. MARKET BY GEOGRAPHY
9.1 North America
9.2 South America
9.3 Europe
9.4 Middle East and Africa
9.5 Asia Pacific
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1 Supplier Positioning
10.2 Material and Validation Capabilities
10.3 Recent Developments
11. COMPANY PROFILES
11.1 Amcor plc
11.2 Wipak Group / SteriKing
11.3 VP Group / SteriCLIN
11.4 Getinge AB
11.5 STERIS plc
11.6 Oliver Healthcare Packaging
11.7 ProAmpac
11.8 PMS Healthcare Technologies
11.9 Shanghai Jianzhong Medical Packaging Co., Ltd.