
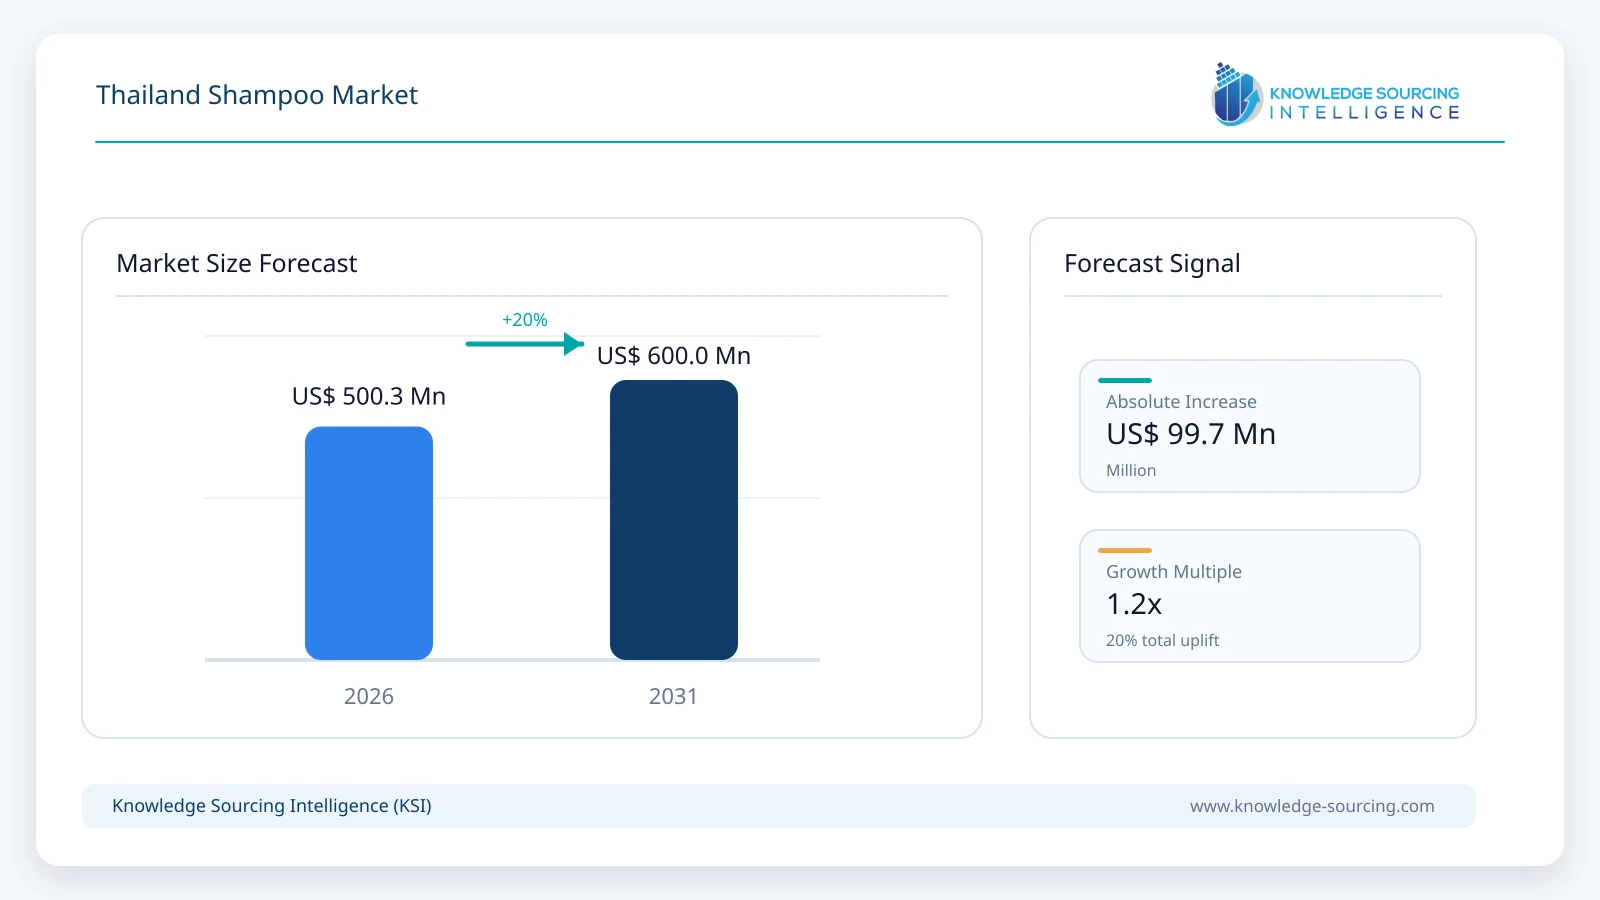
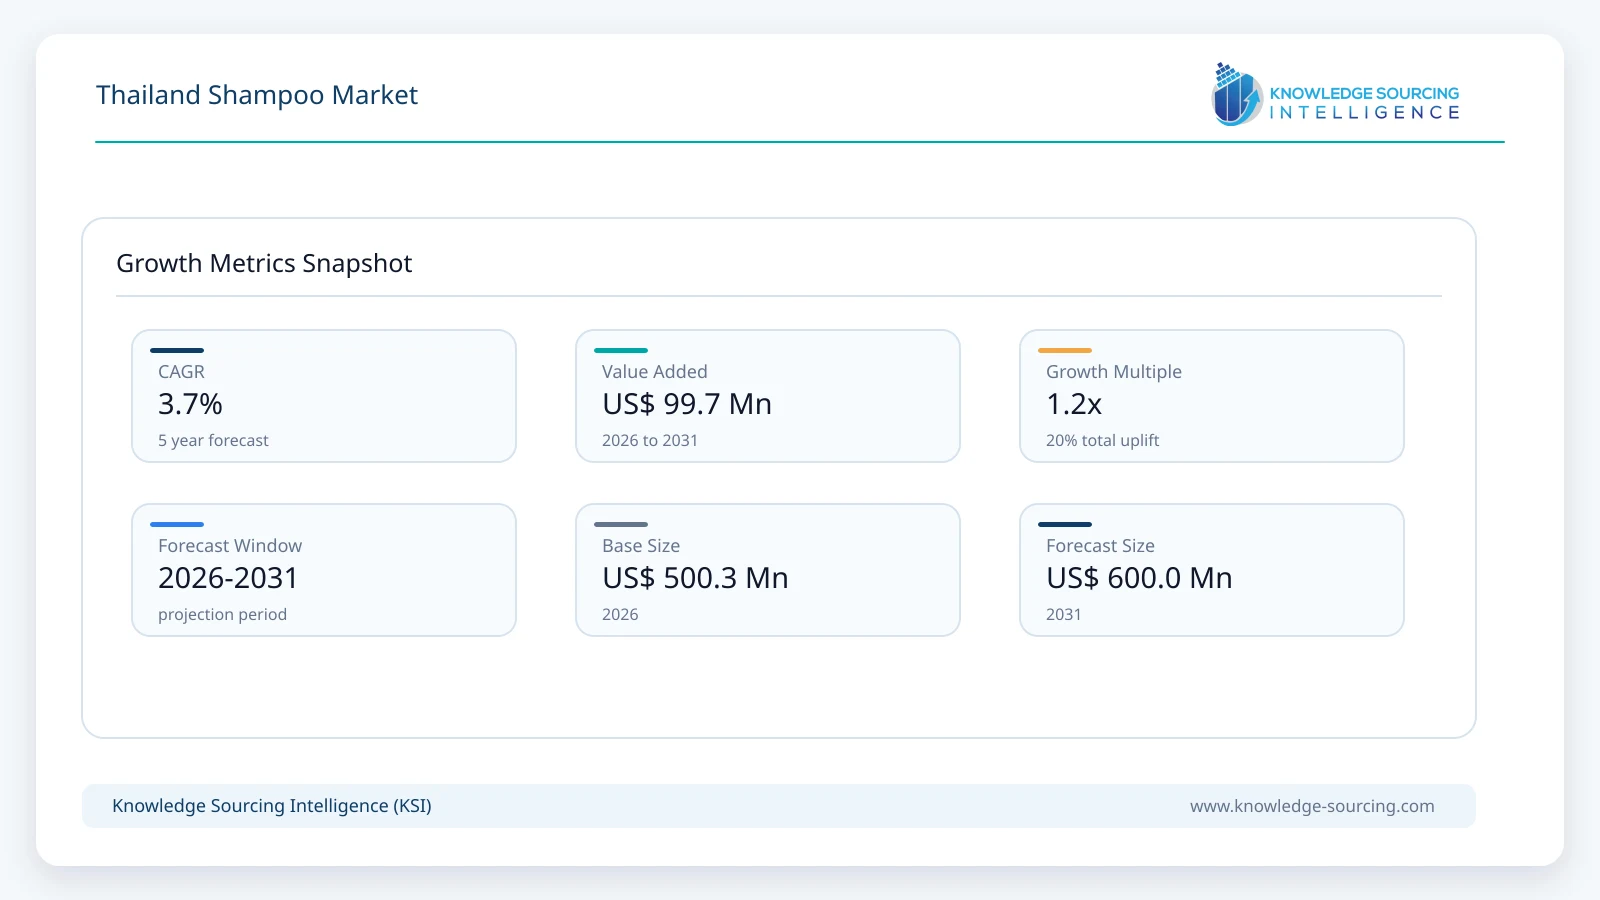
Thailand shampoo market is forecast to grow at a CAGR of 3.7%, reaching USD 600.0 million in 2031 from USD 500.3 million in 2026.
Highlights:
- 178% of market value in 2026Non-Medicated/Regular Shampoo remains the largest product segment, accounting for approximately .
- 26.3% annually through 2031Medicated/Special-Purpose Shampoo is projected to grow at approximately , materially faster than the overall market.
- 388% of market value in 2026Household consumption represents approximately , reflecting shampoo’s status as a routine personal-care product.
- 4Commercial demand from salons, hotels and other professional users grows faster than household demand from a smaller base.
- 5Hypermarkets and Supermarkets remain the largest individual distribution channel, while Online Stores are projected to record the strongest growth.
- 6Bangkok Metropolitan Region is the largest geographic market because of population concentration, purchasing power and dense premium retail.
- 7Southern Thailand records one of the strongest regional growth rates, supported by tourism-intensive urban centres, hospitality demand and modern retail expansion.
- 8Scalp care, anti-hair-fall products, damage repair and specialized formulations are increasingly important areas of product differentiation.
Shampoo demand is supported by an established personal-care culture, extensive modern retail, strong multinational and domestic brand participation and growing consumer interest in products addressing scalp health, dandruff, hair fall, chemical damage and colour maintenance. Market growth is moderate at the total level, but the product mix is changing as consumers increasingly distinguish between basic cleansing and hair-care products positioned around specific scalp or hair conditions.
Thailand has a highly developed health-and-beauty retail environment. Watsons alone operates more than 800 online-to-offline stores in the country and currently lists mass-market, dermatologist-oriented, Korean, Japanese, herbal and private-label shampoo ranges. Specialized retail is complemented by supermarkets, convenience stores, pharmacies, salons and rapidly developing online marketplaces, giving consumers broad access across price points and product types.
Functional hair care is becoming more important within this distribution base. Current Thai assortments include anti-dandruff, hair-fall, sensitive-scalp, colour-care, keratin-repair, micellar, herbal and scalp-balancing shampoos from brands such as Clear, Pantene, Head & Shoulders, L’Oréal Paris, Vichy, Ryo, Lolane, Kokliang and Watsons’ own ranges. The development reflects a broader shift from shampoo being treated primarily as a hygiene product toward a category that increasingly overlaps with scalp care, dermatology-inspired beauty and professional hair maintenance.
The demographic environment reinforces part of this transition. Thailand’s population aged 60 and above represented 20.8% of the population in 2024, compared with 17.8% in 2020, while the working-age share continued to decline. An ageing consumer base does not automatically translate into shampoo growth, but it increases the addressable audience for products positioned around hair thinning, scalp sensitivity and hair-strengthening concerns while younger consumers continue to support colour care, repair and trend-driven products.
Growth Drivers and Trends
Scalp Care Is Moving Shampoo Beyond Basic Cleansing
The most important change in the Thai shampoo market is the increasing separation between basic cleansing products and solutions addressing specific hair and scalp concerns. Anti-dandruff shampoo has long been established, but current assortments also include hair-fall control, sensitive-scalp products, detoxifying formulas, anti-pollution positioning, colour maintenance and products incorporating ingredients traditionally associated with hair strengthening.
This shift is visible across both global and domestic portfolios. Clear’s Scalpceuticals Pro range sold in Thailand includes products positioned around hair-fall resistance, dandruff control and sensitive-scalp care. P&G continues to develop Pantene around hair-loss and damage-related solutions, while L’Oréal’s Thai retail presence spans mainstream Elseve products and more dermatology-oriented Vichy Dercos shampoos. Lolane, one of Thailand’s established domestic hair-care companies, maintains dedicated anti-dandruff, scalp-balancing, colour-care and herbal shampoo ranges.
The commercial effect is a gradual increase in value per purchase because specialized products commonly sell at a premium to large-volume general-purpose shampoos. Consumers can remain within a familiar brand while moving into a product designed around a particular concern, allowing functional growth without requiring a complete change in retail channel or purchasing behaviour.
Professional and At-Home Hair Treatments Increase Damage-Repair Demand
Hair colouring, straightening, bleaching, heat styling and chemical treatment create another important shampoo use case. Thai consumers have access to extensive salon services and home-use colour products, while social media and fashion trends continue to increase experimentation with hair colour and styling.
P&G has specifically identified Southeast Asian consumer demand for stronger damage-repair products, while Kao is expanding its strategic Asian hair-care portfolio around post-colour damage. In July 2026, Kao announced that products incorporating its new H-Linx technology would begin rolling out across seven Asian countries and regions, with the Thailand launch scheduled from September 2026.
Domestic suppliers are following the same functional direction. Lolane offers keratin-serum, colour-care, anti-yellow, anti-red and detoxifying shampoos across its consumer and professional portfolios. This gives specialized shampoo demand a broader base than medical-style scalp care alone and helps explain why special-purpose products are expected to grow faster than routine cleansing shampoos.
E-Commerce Expands the Market for Niche and Premium Products
Thailand’s digital retail ecosystem makes it easier for small brands, imported products and narrowly positioned formulations to reach consumers without first building national supermarket distribution. Shopee, Lazada, TikTok Shop and other platforms are increasingly important discovery and purchasing channels for beauty and personal-care products, particularly among younger consumers.
The Thai FDA has responded by strengthening cooperation with major e-commerce platforms. In October 2025, it announced work with six platforms including Lazada, Shopee and TikTok Shop to use API connectivity and AI screening against illegal health products. In November 2025, the agency signed additional agreements with leading marketplaces under its FDA Connect Marketplace programme to expand legitimate product access while improving consumer protection.
This regulatory participation is important because shampoo and other cosmetics sold online still require appropriate Thai cosmetic notification and compliance. More reliable marketplace screening can support legitimate brands by making product authenticity and regulatory status more visible, while consumers benefit from wider assortment and home delivery.
Thailand’s Retail Infrastructure Supports Broad Market Access
Shampoo benefits from one of the broadest retail footprints within personal care. Products are sold through hypermarkets, supermarkets, convenience stores, pharmacies, health-and-beauty chains, salons and digital platforms, allowing manufacturers to build distinct channel strategies for mass and premium products.
The Bank of Thailand’s Retail Sales Index for specialized stores selling pharmaceutical, medical, cosmetic and toilet articles reached 136.15 in June 2026, with 2019 equal to 100. The measure covers a broader category than shampoo, but it demonstrates that specialized health-and-beauty retail activity remains materially above the pre-2020 base.
Watsons’ more than 800 Thai stores provide a useful example of assortment breadth. The retailer currently carries mass products such as Clear and TRESemmé alongside Vichy Dercos, Ryo, herbal products, salon-style brands and several of its own shampoo ranges. This shelf diversity allows new product concepts to enter the market without displacing basic shampoos immediately, supporting gradual segmentation of demand by hair concern and willingness to pay.
Tourism and Professional Beauty Support Commercial Shampoo Demand
Household use dominates shampoo consumption, but Thailand’s large tourism and hospitality sector supports a meaningful commercial market across hotels, resorts, spas, salons and other professional users. The Bank of Thailand expected approximately 33 million foreign visitors in 2026, while official Ministry of Tourism and Sports data continue to track substantial visitor flows across Bangkok, Phuket, Chonburi, Chiang Mai and southern tourism destinations.
Commercial shampoo demand differs from household consumption because salons and hospitality operators buy according to professional performance, package size, guest positioning and service economics. Premium hotels may use branded amenities, while salons require products matched to colour, chemical treatment and scalp services.
This provides a comparatively faster growth route for professional and commercial products even though household demand remains much larger in absolute value. Tourism-intensive southern markets also benefit disproportionately from this demand alongside normal resident consumption.
Market Restraints
Price Competition Remains Intense
Thailand has a broad assortment of shampoo products at relatively low entry prices. Mass-market brands regularly compete through promotions, larger bottles, multi-buy discounts and bundled conditioner packs, making it difficult for manufacturers to raise prices without providing a clearly differentiated benefit.
Current supermarket and health-and-beauty promotions show substantial discounting across Pantene, Head & Shoulders, Watsons private label and other mainstream brands. This price transparency keeps routine shampoo highly competitive and limits value growth in the largest Non-Medicated/Regular segment.
Functional brands can sustain higher prices when consumers perceive a specific benefit, but even specialized products compete with frequent promotional activity, particularly on digital marketplaces.
Population Growth Is No Longer a Volume Driver
Thailand’s demographic profile creates a structural constraint for mass-market personal-care volume. Registered population declined modestly in 2024, the total fertility rate was approximately 1.0 and the share of children aged 0–14 fell to 15.2%.
A stable or declining population means shampoo manufacturers cannot rely heavily on an expanding consumer base. Growth increasingly needs to come from premiumization, more specialized formulations, higher usage value or share shifts between brands.
This makes product innovation more important but also limits the potential for very high total-market growth despite strong category participation.
Functional Claims Require Careful Regulatory Positioning
Cosmetics sold in Thailand must be notified to the Thai FDA before manufacture or import for sale. Notification covers the business operator, product type, ingredients and conditions of use, and notification receipts remain valid for three years.
The ASEAN Harmonized Cosmetic Regulatory Scheme also governs safety evaluation, product information, cosmetic claims, restricted substances and labelling. This becomes particularly relevant when shampoo brands move toward stronger scalp-care or anti-hair-loss positioning because claims cannot cross casually into therapeutic territory without appropriate substantiation and classification.
Established companies generally have the regulatory and technical resources to manage these requirements, while smaller brands can face higher relative compliance costs.
Counterfeit and Unregistered Online Products Create Trust Issues
Digital commerce expands access but also increases the number of sellers participating in personal care. Unauthorized imports, counterfeit products and improperly notified cosmetics can undermine consumer confidence and create unfair competition for compliant companies.
The Thai FDA’s recent partnerships with e-commerce companies specifically target this issue through database connectivity and automated screening. Continued enforcement can improve the environment, but marketplaces remain more fragmented than established offline retail.
Brands therefore need to invest in authorized-store identification, packaging verification and consumer communication alongside normal digital marketing.
Sustainability Improvements Remain Cost Sensitive
Shampoo packaging relies heavily on plastic bottles, pumps, caps and flexible refill pouches. Global beauty companies are introducing refill formats and lower-plastic packaging, but consumer adoption depends on convenience and price as well as environmental considerations.
L’Oréal’s current refill portfolio demonstrates that shampoo refills can materially reduce plastic use compared with equivalent bottles, but refill adoption is not yet universal. Thailand’s mass-market shampoo segment remains price competitive, making packaging changes difficult when they increase the shelf price.
The sustainability opportunity therefore develops gradually through refill pouches, lighter packaging and recycled-content initiatives rather than through a rapid move away from conventional packaged shampoo.
Segment Analysis:
By Product
Non-Medicated/Regular Shampoo Remains the Largest Segment
Non-Medicated/Regular Shampoo accounts for approximately 78% of market value in 2026 because basic cleansing, moisture, smoothness, damage repair and general hair maintenance represent the majority of routine household purchases. The category benefits from broad supermarket and convenience-store availability and a substantial portfolio of mass-market brands.
Competition is intense, with Sunsilk, Pantene, Dove, TRESemmé, L’Oréal Paris, Herbal Essences, Kao, Lion and domestic products occupying multiple price tiers. Large bottle sizes and promotional pricing make the category highly accessible, while manufacturers increasingly add keratin, hyaluronic acid, botanical extracts and other ingredients to mainstream products to prevent regular shampoo from becoming completely commoditized.
Medicated/Special-Purpose Shampoo is projected to grow at approximately 6.3% annually through 2031, supported by anti-dandruff, anti-hair-fall, sensitive-scalp, colour-care and related functional formulations. Stronger growth does not make specialized shampoo the dominant category during the forecast period, but it gradually shifts value toward products where consumers are willing to pay for a clearly defined hair or scalp benefit.
By Application
Household Consumption Dominates the Market
Household use accounts for approximately 88% of market value in 2026, reflecting the routine and high-frequency nature of shampoo consumption. Products purchased through supermarkets, convenience stores, health-and-beauty retailers and e-commerce primarily serve individual and family use, with price, scent, hair type and brand familiarity remaining important purchasing considerations.
The segment remains the central volume base, but growth is moderate because household penetration is already very high and Thailand’s population is no longer expanding materially. Most incremental value therefore comes from consumers moving into specialized or premium products rather than from first-time shampoo adoption.
Commercial applications are projected to grow at approximately 6.5% annually through 2031, faster than household demand from a much smaller base. Salons, hotels, resorts, spas and professional beauty businesses support this growth, particularly in Bangkok and Thailand’s major tourism destinations where hair services and hospitality remain economically important.
By Distribution Channel
Hypermarkets and Supermarkets Remain the Largest Channel
Hypermarkets and Supermarkets account for approximately 43% of market value in 2026. The channel benefits from large assortments, high household shopping frequency and strong promotional activity across mainstream brands, making it particularly important for family-sized bottles and routine shampoo purchases.
Modern grocery chains also provide brands with national visibility and allow consumers to compare bottle sizes, formulations and prices directly. This reinforces the channel’s position in mass-market shampoo even as health-and-beauty specialists and digital platforms become more important for premium and functional products.
Online Stores are projected to grow at approximately 8.8% annually through 2031, significantly above total market growth. Wider assortment, promotions, social-commerce discovery and easier access to imported and niche products make online retail particularly well suited to specialized shampoo categories. The channel gains share steadily but does not displace supermarkets as Thailand’s largest shampoo distribution route within the forecast period.
Geographical Outlook
Bangkok Metropolitan Region Represents the Largest Market
Bangkok Metropolitan Region accounts for approximately 36% of Thailand shampoo market value in 2026. The region combines Thailand’s largest concentration of higher-income urban consumers with dense supermarket, pharmacy, health-and-beauty, salon and e-commerce activity.
Household spending data also show stronger personal-care expenditure in Greater Bangkok than in many other regions. The area therefore supports both the high-volume mass market and a disproportionate share of premium, professional and dermatologist-oriented hair care.
Southern Thailand is projected to record approximately 5.2% annual growth through 2031, making it one of the fastest-growing regional markets in the model. Phuket, Surat Thani and other tourism-intensive provinces combine local household consumption with hotels, resorts, spas and professional salons, while personal-care expenditure in the South is also relatively high compared with several other Thai regions.
Recent Developments
In August 2026, Kao Corporation began the sequential rollout of its expanded Liese strategic hair-care range incorporating H-Linx TECH across seven Asian markets including Thailand. The wider Asian launch is intended to combine hair-colour products with post-colour damage care and forms part of Kao Corporation's effort to accelerate its hair-care business across Asia.
In July 2026, Kao Corporation announced that its redefined Liese hair-color series, featuring the newly developed H-Linx TECH, would be sequentially rolled out across seven Asian countries and regions (Hong Kong, Thailand, Taiwan, Malaysia, China, Japan, and Singapore) beginning in August 2026.
In March 2026, P&G highlighted Southeast Asian consumer research behind its Pantene damage-repair innovation programme, showing how regional hair-treatment behaviour is increasingly influencing product development rather than Southeast Asia being treated only as a distribution market.
During 2026, Watsons Thailand continued to expand its scalp-care assortment, including Clear Scalpceuticals Pro, Ryo Hair Loss Expert Care, Vichy Dercos and multiple Watsons-owned anti-hair-fall and anti-dandruff ranges. The retailer’s current footprint of more than 800 online-to-offline stores gives specialized products broad national distribution.
In November 2025, Procter & Gamble (P&G) introduced Pantene Abundant & Strong, a three-product hair-loss system including shampoo, conditioner, and daily scalp serum.
Competitive Environment
Thailand’s shampoo market combines multinational FMCG companies, international professional hair-care brands, domestic specialists and retailer-owned labels. Unilever remains particularly important through Sunsilk, Clear, Dove and TRESemmé, while P&G competes through Pantene, Head & Shoulders and Herbal Essences. L’Oréal participates at several price and positioning levels through L’Oréal Paris Elseve, Garnier, Kérastase and Vichy Dercos.
Kao and Lion provide a strong Japanese presence, while Amorepacific and other Korean suppliers participate in premium and scalp-oriented hair care. Henkel and Wella are important in professional products, and FineToday/Shiseido-linked brands broaden Japanese competition in the premium consumer channel.
Domestic manufacturers remain strategically important because they can respond more directly to Thai preferences and price points. S.C. Sereechai Beauty’s Lolane brand has operated for decades, exports to more than 30 countries and maintains consumer and professional shampoo ranges covering herbs, scalp care, keratin repair and colour maintenance. Other local brands including Bergamot, Kokliang, Berina and Caring contribute to a fragmented domestic competitive base.
Retailer-owned products add another layer of competition. Watsons sells multiple proprietary shampoo ranges spanning low-priced general cleansing, botanical positioning, keratin repair and scalp care, demonstrating that private-label participation is no longer limited to basic formulations.
Competition through 2031 is expected to move increasingly around scalp health, damage repair, ingredient positioning, digital discovery and channel-specific pricing. Large multinationals retain advantages in advertising, R&D and national distribution, while local and Asian specialist brands can compete effectively where they provide a distinct functional proposition at an accessible price.
Analyst View
The Thailand Shampoo Market is a mature yet steadily evolving consumer-care category, supported by widespread product usage and changing consumer preferences. Growth is unlikely to be driven by population expansion because Thailand’s demographic structure is becoming less supportive. Instead, the market is moving toward greater value differentiation within an already widely used product.
Regular shampoo remains the largest category because routine cleansing and mainstream damage care dominate consumption, but specialized products capture a growing share of incremental value. Anti-dandruff has an established base, while hair-fall, sensitive-scalp, colour-care and treatment-oriented products broaden the functional market. The distinction between beauty and scalp care is therefore becoming less rigid.
Distribution is changing at the same time. Supermarkets remain the largest channel because shampoo is a routine household purchase, while e-commerce gives niche, imported and functional products wider reach and allows brands to use social media more directly in product discovery. Physical health-and-beauty chains occupy an important position between these models by combining product breadth with trusted retail and online ordering.
The competitive advantage through 2031 should therefore come from delivering a specific, credible hair-care benefit without losing price accessibility. Products that combine clinically oriented scalp positioning, locally relevant ingredients, strong digital visibility and broad offline distribution are better positioned than brands relying principally on basic cleansing claims.
Thailand Shampoo Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 500.3 million |
| Total Market Size in 2031 | USD 600.0 million |
| Forecast Unit | Million |
| Growth Rate | 3.7% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product, Application, Distribution Channel, Region |
| Companies |
|
Market Segmentation
By Product
· Medicated/Special-Purpose
· Non-Medicated/Regular
By Application
· Household
· Commercial
By Distribution Channel
· Hypermarkets/Supermarkets
· Health & Beauty Stores/Pharmacies
· Convenience Stores
· Online Stores
· Salons & Others
By Geography
· Bangkok Metropolitan Region
· Central Thailand
· Northern Thailand
· Northeastern Thailand
Southern Thailand
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL AND PRODUCT OUTLOOK
4.1. Scalp-Care Formulations
4.2. Anti-Hair-Fall and Hair-Retention Products
4.3. Colour and Damage-Repair Technology
4.4. Herbal and Botanical Ingredients
4.5. Refill and Lower-Plastic Packaging
5. THAILAND SHAMPOO MARKET BY PRODUCT
5.1. Introduction
5.2. Medicated/Special-Purpose
5.3. Non-Medicated/Regular
6. THAILAND SHAMPOO MARKET BY APPLICATION
6.1. Introduction
6.2. Household
6.3. Commercial
7. THAILAND SHAMPOO MARKET BY DISTRIBUTION CHANNEL
7.1. Introduction
7.2. Hypermarkets/Supermarkets
7.3. Health & Beauty Stores/Pharmacies
7.4. Convenience Stores
7.5. Online Stores
7.6. Salons & Others
8. THAILAND SHAMPOO MARKET BY GEOGRAPHY
8.1. Introduction
8.2. Bangkok Metropolitan Region
8.3. Central Thailand
8.4. Northern Thailand
8.5. Northeastern Thailand
8.6. Southern Thailand
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Brand Positioning Analysis
9.3. Product Launches and Portfolio Development
9.4. Distribution and Digital Strategy
9.5. Competitive Dashboard
10. COMPANY PROFILES
10.1. Unilever Thai Holdings Limited
10.2. Procter & Gamble Manufacturing (Thailand) Ltd.
10.3. L’Oréal (Thailand) Ltd.
10.4. Kao Industrial (Thailand) Co., Ltd.
10.5. Lion Corporation (Thailand) Ltd.
10.6. Johnson & Johnson (Thailand) Ltd.
10.7. Henkel (Thailand) Ltd.
10.8. Wella Company
10.9. Amorepacific Corporation
10.10. FineToday Holdings Co., Ltd.
10.11. A.S. Watson Group / Watsons Thailand
10.12. S.C. Sereechai Beauty Co., Ltd. / Lolane
10.13. Better Way (Thailand) Co., Ltd. / Mistine
10.14. Berina Cosmetics Co., Ltd.
10.15. Caring Hair Cosmetic Co., Ltd.
10.16. Bergamot Hair Care
10.17. Kokliang
10.18. New Moon Cosmetics Pvt. Ltd.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











