
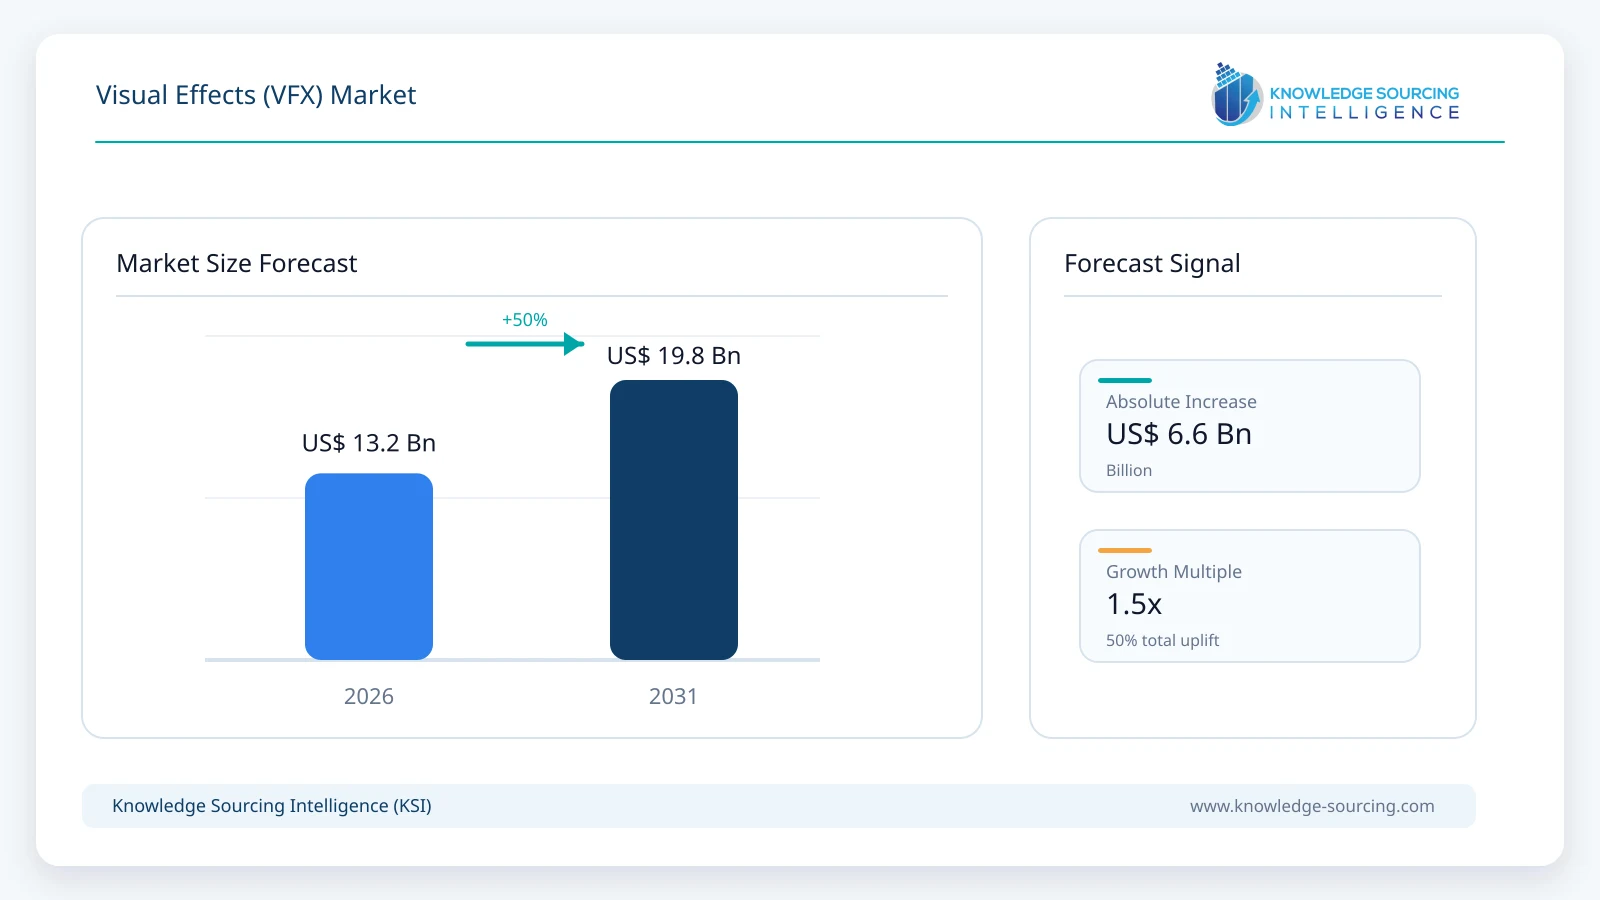
The Global Visual Effects (VFX) market is forecast to grow at a CAGR of 8.4%, reaching USD 19.8 billion in 2031 from USD 13.2 billion in 2026.
Highlights:
- 1CGI and digital asset services account for approximately 43% of global VFX revenue in 2026.
- 2Film applications generate about USD 4.6 billion of global VFX revenue in 2026.
- 3Production companies and studios are projected to grow at approximately 8.7% annually through 2031.
- 4North America represents approximately 36% of global VFX revenue in 2026.
- 5AI is automating selected production tasks while increasing demand for pipeline redesign and artist supervision.
- 6India is gaining importance as global studios expand high-end VFX and production-technology capacity.
Visual effects are now embedded across the production lifecycle rather than confined to final post-production. Previsualization teams build digital versions of sets, action and camera movement before shooting. On-set teams capture camera, lighting and performance data that can be reused downstream. Virtual production combines real-time rendering with LED stages and tracked cameras. Post-production artists then complete digital environments, characters, simulations, cleanup, compositing and final image integration. This broader workflow increases the number of departments that interact with VFX providers.
The market remains project-driven, but high-end episodic content has reduced the distinction between feature-film and television pipelines. Large series now require complex creatures, simulations, environments and digital doubles across multiple episodes. Industrial Light & Magic, Framestore, DNEG, Weta FX, Eyeline, Sony Pictures Imageworks and other major studios operate across global production hubs to balance client proximity, talent access, tax incentives and time-zone coverage. Smaller studios compete by specializing in compositing, environments, creatures, simulation, advertising or real-time work.
Market Trends
AI is moving from isolated tools into studio production pipelines
The most important technology shift is the integration of AI into existing artist workflows rather than the replacement of complete VFX pipelines. Autodesk added AI-assisted motion and production tools across Maya, Flow Studio and its media portfolio during 2026. Framestore created a dedicated Creative Director, AI role in May 2026 and is rolling out its Futon platform to connect machine learning and generative AI with established production processes. Digital Domain has also expanded AI-integrated production infrastructure. The commercial benefit comes from reducing repetitive work and shortening iteration cycles while preserving supervision and final creative control.
Virtual production is shifting visual development and environment work earlier
LED volumes, real-time engines and camera tracking allow directors to see digital environments during principal photography. This changes the timing of VFX spending because assets that once could be created late in post-production may now need to be production-ready before a shoot begins. Industrial Light & Magic continues to use and extend StageCraft workflows across film, television and live-event applications. Eyeline combines traditional VFX with virtual production and production-technology research. The result is a more integrated service model in which previs, virtual art departments, on-set teams and post-production share assets and data.
Global delivery capacity is expanding in India and other production hubs
India is moving beyond labor-intensive roto and paint work toward higher-value shot production, supervision, pipeline engineering and production technology. Netflix opened Eyeline Studios in Hyderabad in March 2026 as a global production and innovation facility. DNEG continues to operate major Indian studios, including its expanded Bengaluru facility, while Rodeo FX has also established a Bangalore presence. Canada, the United Kingdom, Australia and New Zealand remain important because they combine deep creative talent with film-production incentives and established studio ecosystems.
Market Drivers
High-end film and episodic production continues to require complex digital imagery
Large productions increasingly depend on visual effects for world-building, creatures, environments, crowds, action sequences and digital doubles. The requirement is not limited to fantasy and science fiction. Period dramas, sports films, thrillers and even grounded productions use invisible effects for cleanup, set extensions and environment control. Industrial Light & Magic reported work across all five Best Visual Effects nominees at the 98th Academy Awards in 2026, illustrating how broadly large productions rely on multiple VFX vendors and specialist teams.
Streaming and premium episodic content create a more continuous production pipeline
Streaming platforms and broadcasters now commission episodic projects with feature-film visual standards. This supports multi-month and multi-season VFX engagements rather than one-off feature contracts alone. High-end episodic work can include hundreds or thousands of shots across a season and requires coordinated asset reuse between episodes. The model favors studios with scalable production management, secure global data infrastructure and the ability to distribute work across several locations without compromising consistency.
Real-time workflows increase the number of VFX services used before and during filming
Virtual production expands the commercial scope of VFX beyond post-production. Digital environments, real-time assets, camera tracking and previs can be commissioned before principal photography. The same assets may then move into final post-production, reducing duplication while raising the value of early creative and technical planning. Studios that combine art departments, virtual production, on-set supervision and final VFX are therefore able to capture a larger share of project spending.
Market Restraint
Project volatility and labor-intensive production models continue to pressure margins
VFX studios operate under fixed delivery schedules while creative changes can continue late into production. Shot counts, complexity and revision cycles can expand after contracts are awarded, creating margin risk when pricing does not fully reflect additional work. The market also requires highly specialized artists, supervisors and pipeline engineers whose skills are mobile across global hubs. AI and cloud collaboration can improve productivity, but they do not remove the need for experienced creative review and production management. Studios therefore remain exposed to project timing, capacity utilization and client concentration.
Segment Analysis
By Service Type - CGI and Digital Asset Services
CGI and digital asset services form the largest service category because modern productions require digital characters, environments, props and extensions that can be reused across many shots. The segment is projected to reach approximately USD 8.4 billion by 2031. Demand is supported by creature work, digital doubles, environment creation and full-CG sequences. The segment also benefits from virtual production because production-ready assets increasingly need to be created before filming and then refined for final delivery.
By Application - Film
Film remains the largest single application because effects-heavy theatrical releases combine high shot complexity with large production budgets. The segment is projected to grow at approximately 7.8% annually through 2031. Blockbuster productions often distribute work among several VFX vendors to manage scale, specialist requirements and delivery risk. Episodic and streaming content is growing faster, but feature films continue to anchor high-end creature, environment, simulation and digital-double work.
By Client Type - Production Companies and Studios
Production companies and studios form the largest client group because they commission VFX directly for films, television series and streaming content. The segment is projected to reach approximately USD 10.6 billion by 2031. Large clients increasingly expect secure global pipelines, consistent asset management and multi-location delivery. Advertising agencies and game developers remain important specialist buyers, but their project structures and production cycles differ from film and episodic work.
By Geography - North America
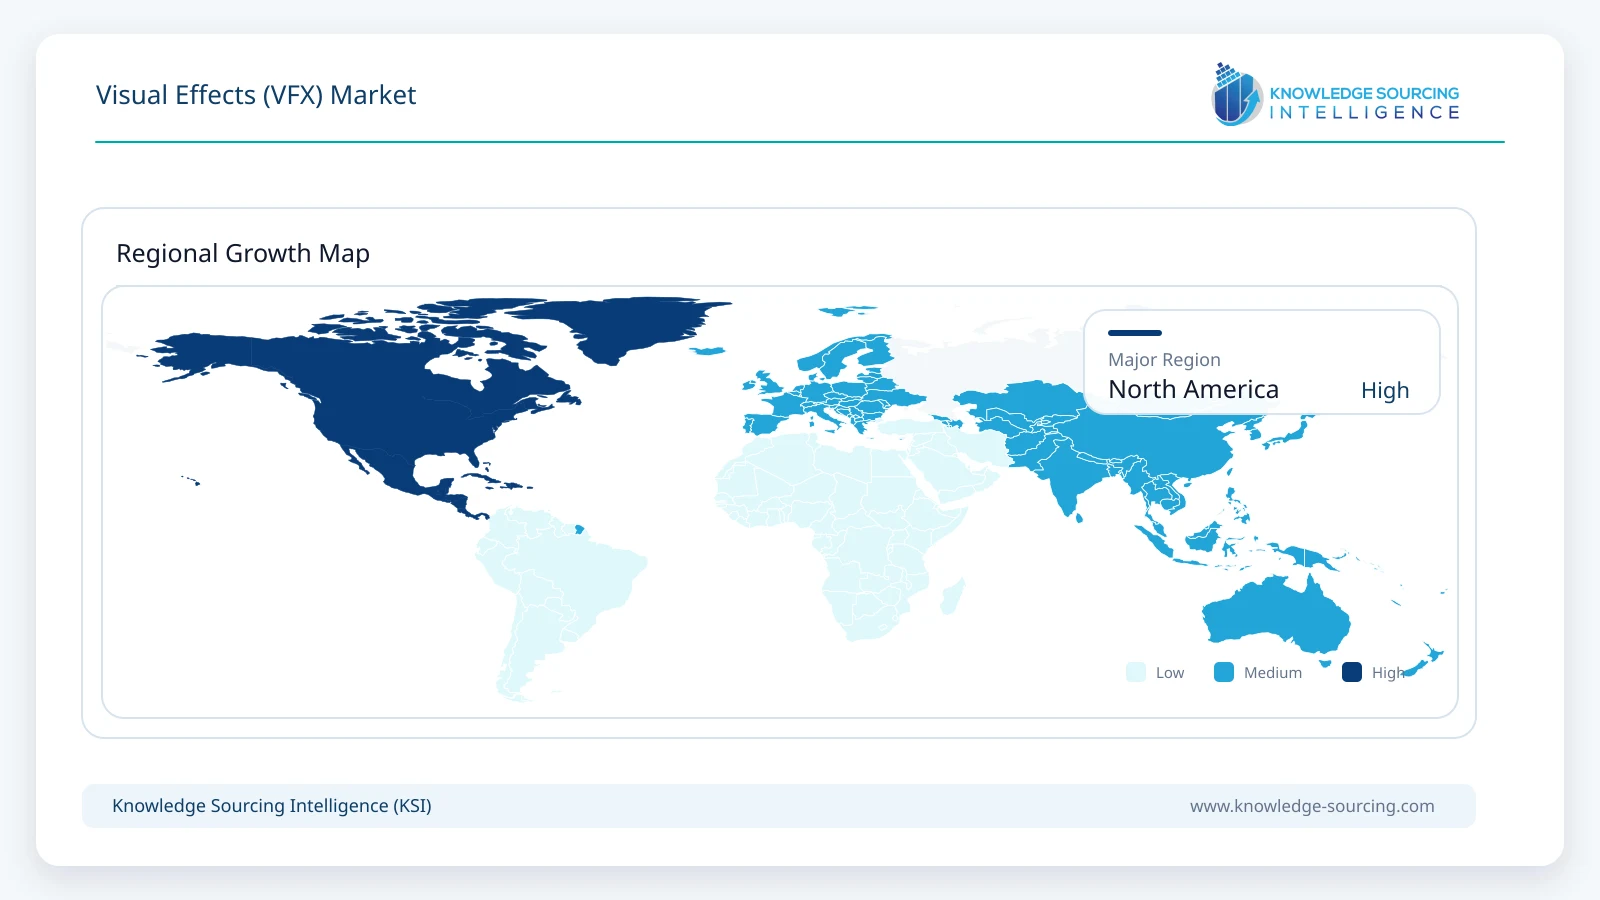
North America is the largest regional market because the United States and Canada combine major content owners, production infrastructure, established VFX studios and strong demand for high-end film and episodic work. Regional market value is projected to reach approximately USD 7.0 billion by 2031. Los Angeles remains central to client decision-making, while Vancouver and Montreal are major delivery hubs. Europe and Asia Pacific are also important, with London, Mumbai, Bengaluru, Hyderabad, Seoul, Sydney and Wellington supporting increasingly global production networks.
Competitive Environment
Industrial Light & Magic, Weta FX, DNEG and Framestore occupy strong positions in high-end feature and episodic work. ILM combines decades of effects development with proprietary technologies such as StageCraft and deep integration with Lucasfilm and Disney productions. Weta FX is known for complex characters, environments and large-scale simulation. DNEG operates a broad international footprint, while Framestore combines film, episodic, advertising and immersive work.
Sony Pictures Imageworks, Eyeline and Digital Domain add significant technical depth. Sony Pictures Imageworks combines visual effects and feature-animation capability with proprietary production technology. Eyeline now brings together the former Scanline VFX operation with Netflix's virtual production and production-innovation capabilities. Digital Domain remains active in photoreal VFX, virtual humans and performance-capture technology.
Cinesite, The Mill, Rodeo FX, Pixomondo, FuseFX, Important Looking Pirates, Goodbye Kansas, Tippett Studio and Zoic Studios compete across film, episodic and advertising work. The competitive landscape continues to change through consolidation. In June 2026, MPC and The Mill were combined under The Mill brand following TransPerfect's ownership of the businesses. Differentiation increasingly depends on creative reputation, pipeline technology, global capacity, security, client relationships and the ability to integrate AI without compromising final quality.
Recent Developments
September 2026: Industrial Light & Magic won Primetime Emmy awards for Spider-Noir and Stranger Things Season Five.
August 2026: Autodesk launched new directable 3D Editor and Canvas capabilities within Flow Studio for generative filmmaking workflows.
July 2026: Autodesk introduced new Maya, 3ds Max, Flow Production Tracking and Arnold tools at SIGGRAPH 2026.
June 2026: MPC and The Mill were unified under The Mill brand, creating one global creative studio under TransPerfect.
May 2026: Framestore created a Creative Director, AI role to lead the global rollout of its Futon AI production platform.
March 2026: Netflix opened Eyeline Studios in Hyderabad to expand advanced VFX and production-technology capacity in India.
February 2026: Foundry released Nuke 17.0 with a new USD-based 3D system, Gaussian Splat support and expanded machine learning capabilities.
Visual Effects (VFX) Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 13.2 billion |
| Total Market Size in 2031 | USD 19.8 billion |
| Forecast Unit | Billion |
| Growth Rate | 8.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Service Type, Application, Client Type, Geography |
| Companies |
|
Market Segmentation
By Service Type
CGI and Digital Asset Services
Compositing and Finishing
Simulation and FX
Motion Capture and Virtual Production Support
Others
By Application
Film
Television and Streaming
Advertising
Gaming and Interactive Media
Others
By Client Type
Production Companies and Studios
Advertising Agencies
Game Development Studios
Other Content Producers
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
France
Germany
Spain
Italy
Others
Middle East and Africa
UAE
Saudi Arabia
South Africa
Others
Asia Pacific
India
China
Japan
South Korea
Australia
New Zealand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. High-End Film and Episodic Production Continues to Require Complex Digital Imagery
3.1.2. Streaming and Premium Episodic Content Create a More Continuous Production Pipeline
3.1.3. Real-Time Workflows Increase the Number of VFX Services Used Before and During Filming
3.2. Market Restraint
3.2.1. Project Volatility and Labor-Intensive Production Models Continue to Pressure Margins
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. AI-Assisted Production Workflows
4.2. Virtual Production and LED Volumes
4.3. Real-Time Rendering
4.4. Motion and Performance Capture
4.5. OpenUSD and Connected Production Pipelines
5. VISUAL EFFECTS MARKET BY SERVICE TYPE
5.1. Introduction
5.2. CGI and Digital Asset Services
5.3. Compositing and Finishing
5.4. Simulation and FX
5.5. Motion Capture and Virtual Production Support
5.6. Others
6. VISUAL EFFECTS MARKET BY APPLICATION
6.1. Introduction
6.2. Film
6.3. Television and Streaming
6.4. Advertising
6.5. Gaming and Interactive Media
6.6. Others
7. VISUAL EFFECTS MARKET BY CLIENT TYPE
7.1. Introduction
7.2. Production Companies and Studios
7.3. Advertising Agencies
7.4. Game Development Studios
7.5. Other Content Producers
8. VISUAL EFFECTS MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. United Kingdom
8.4.2. France
8.4.3. Germany
8.4.4. Spain
8.4.5. Italy
8.4.6. Others
8.5. Middle East and Africa
8.5.1. UAE
8.5.2. Saudi Arabia
8.5.3. South Africa
8.5.4. Others
8.6. Asia Pacific
8.6.1. India
8.6.2. China
8.6.3. Japan
8.6.4. South Korea
8.6.5. Australia
8.6.6. New Zealand
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Technology and Delivery Positioning
9.4. Mergers, Acquisitions, Agreements and Collaborations
9.5. Competitive Dashboard
10. COMPANY PROFILES
10.1. Industrial Light & Magic
10.2. Weta FX
10.3. DNEG
10.4. Framestore
10.5. Sony Pictures Imageworks
10.6. Eyeline
10.7. Digital Domain
10.8. Cinesite
10.9. The Mill
10.10. Rodeo FX
10.11. Pixomondo
10.12. FuseFX
10.13. Important Looking Pirates
10.14. Goodbye Kansas Studios
10.15. Tippett Studio
10.16. Zoic Studios
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











