
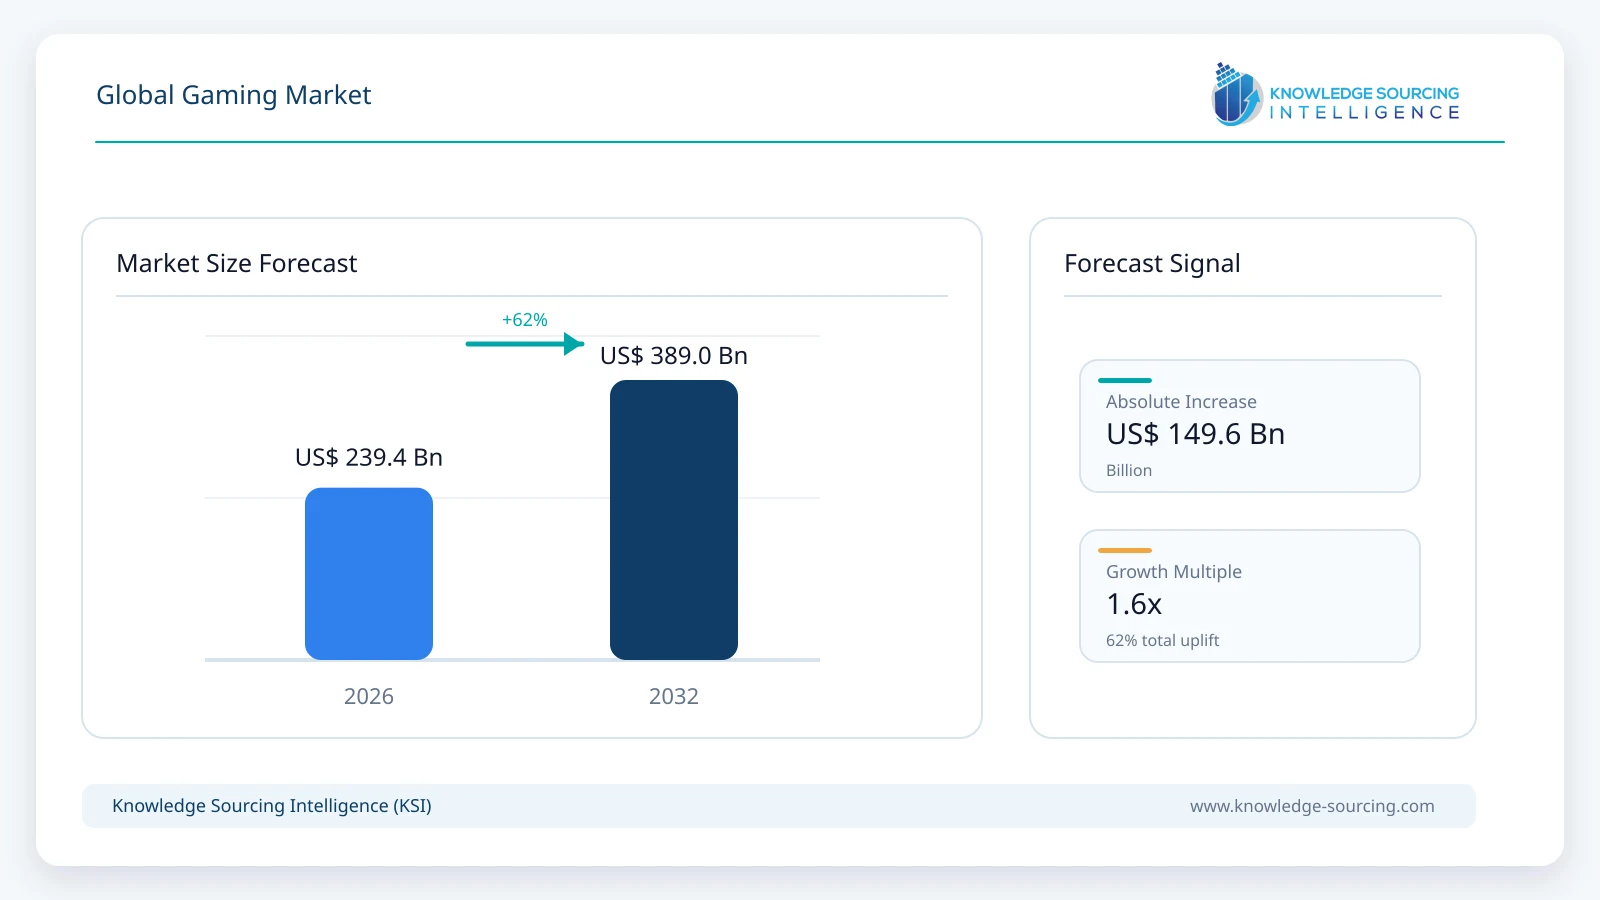
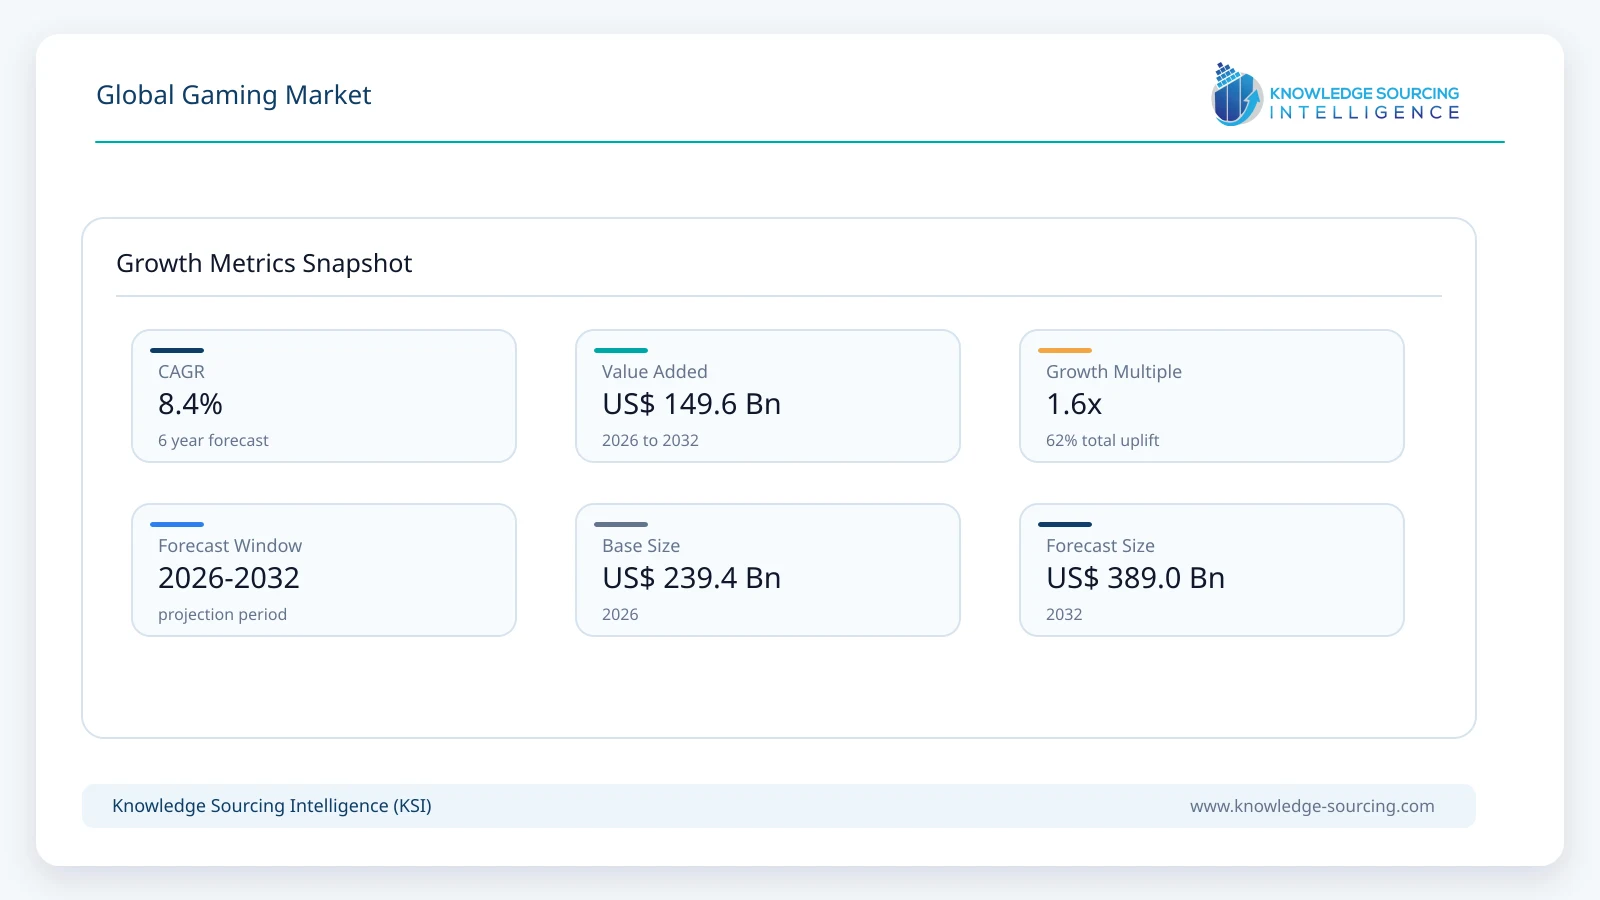
The Global Gaming Market is estimated at USD 239.4 billion in 2026 and is projected to reach USD 389.0 billion by 2032, representing a CAGR of 8.4% during 2026-2032.
Highlights:
- 1Smartphones lead device spending, accounting for 43.0% of global gaming revenue in 2026.
- 2Handheld gaming is the fastest-growing device segment, expanding at a 15.1% CAGR through 2032.
- 3Software and digital content remain the largest component, representing 72.5% of 2026 revenue.
- 4Gaming services are the fastest-growing component, recording a 14.7% CAGR through 2032.
- 5Action and adventure lead game types, accounting for 28.0% of global gaming revenue in 2026.
- 6Cloud gaming is the fastest-growing revenue model, expanding at a 19.5% CAGR through 2032.
Market Overview
Gaming revenue is becoming less dependent on a single device or transaction. A player may purchase a premium title on a console, access the same account on a PC, subscribe to a service library, buy downloadable content, participate in a live event and continue engagement through a mobile companion experience. This multi-channel structure increases the lifetime value of successful intellectual property and makes account ecosystems, digital storefronts and player communities strategically important alongside the underlying game itself.
Hardware remains relevant because major platform transitions create bursts of spending and expand the addressable base for premium software. Nintendo Switch 2 demonstrates the effect of a successful new-device cycle, while the PlayStation 5 installed base continues to support software, add-on content and network-service revenue. At the same time, PC gaming is becoming easier to access through unified launchers, handheld PCs and cloud delivery. Microsoft is positioning Windows and Xbox services around downloaded titles, Game Pass libraries and Xbox Cloud Gaming, reducing the importance of a single fixed gaming device.
The software layer has become more durable. Large publishers increasingly build live-service roadmaps around seasonal content, in-game events, competitive modes and recurring digital purchases. Advertising is also becoming a more structured revenue stream. In June 2026, Electronic Arts launched EA Advertising with dynamic in-game placements and brand integrations across selected sports titles, showing how large player communities can support commercial models beyond direct consumer payments.
Market Drivers
Large player populations sustain a broad recurring revenue base
Gaming participation is now distributed across age groups and device types rather than concentrated among younger console users. The Entertainment Software Association reported that 212.3 million Americans play video games weekly in 2026, with 67% of people aged 5 to 90 playing at least one hour per week. This breadth supports a wide spectrum of monetization, from mobile free-to-play titles and family games to premium console releases, competitive multiplayer, subscriptions and creator-led experiences.
Digital distribution and live services increase lifetime monetization
Digital storefronts reduce dependence on physical retail and make it easier to sell expansions, virtual items, battle passes, subscriptions and recurring content. Publishers can refresh successful titles for several years rather than rely entirely on new launches. This improves the commercial importance of engagement, retention and community scale. EA reported more than 120 million monthly players across its portfolio during fiscal 2026, illustrating the audience reach available to publishers that operate persistent game ecosystems.
New hardware cycles support premium gaming expenditure
Console and handheld launches create a synchronized replacement cycle for devices, accessories and software. Nintendo Switch 2 reached 23.68 million cumulative hardware units by June 30, 2026, while its software sales reached 58.17 million units. Sony reported more than 93 million cumulative PlayStation 5 units by March 2026. Large installed bases encourage publishers to commit development budgets to premium games and raise the potential return from downloadable content and platform services.
Cloud and cross-device access widen the addressable market
Cloud gaming does not replace local hardware across all use cases, but it reduces installation and device barriers for selected games and subscription libraries. Cross-save, cross-play and shared accounts also allow players to move between PC, console and mobile environments. Microsoft continues to expand Xbox Cloud Gaming and Windows-based access to multiple game libraries, while publishers increasingly design communities and progression systems around persistent player accounts rather than one physical device.
Restraints and Adoption Challenges
The market faces rising development cost, long production cycles and difficult content discovery. Large premium titles can require several years of development and substantial marketing expenditure, increasing financial exposure when release schedules slip or user reception is weak. Live-service games face a different challenge: players have limited time, making retention increasingly competitive across a crowded set of established titles. Platform fees, user-acquisition costs and regulatory scrutiny of monetization practices can also pressure margins. Hardware businesses remain exposed to component pricing, inventory risk and console-cycle timing, while cloud gaming must balance streaming quality, latency and infrastructure cost against subscription economics.
Segment Analysis
By Device Type
Smartphones represent the largest device segment, estimated at USD 102.9 billion in 2026. The category combines the world's broadest installed device base with mature app-store distribution, free-to-play monetization, social discovery and increasingly capable mobile processors. Revenue extends beyond game downloads into in-app purchases, battle passes, advertising and recurring live-service content. Growth is supported by deeper 5G availability, higher device performance and continued expansion of mobile-first gaming markets across Asia, Latin America, the Middle East and Africa.
Handheld gaming is expected to record the fastest device growth, with the segment projected to reach approximately USD 38.9 billion by 2032. Growth is being supported by Nintendo Switch 2, the expansion of portable PC gaming systems and stronger consumer preference for hybrid play across home and mobile settings. New handheld devices increasingly support premium libraries, cloud access and cross-save functionality, allowing players to move between television, desktop and portable screens. This improves software attach rates and makes handheld systems a larger revenue channel than the previous generation of dedicated portable consoles.
By Component
Software and digital content represent the largest component segment, estimated at USD 173.6 billion in 2026. The segment includes premium game purchases, digital downloads, in-game transactions, downloadable content and other paid game content. Its scale reflects the transition from one-time physical purchases toward persistent digital spending across console, PC and mobile ecosystems. Major franchise releases, recurring content, broader digital storefront penetration and longer monetization cycles continue to support the category.
Gaming services are expected to grow fastest within the component segmentation, reaching approximately USD 60.0 billion by 2032. Subscriptions, cloud gaming, online multiplayer services, account ecosystems, advertising tools and other recurring platform services benefit as publishers and platform owners seek revenue beyond individual game purchases. The category also gains from expanding subscription libraries and cloud delivery, which allow services to monetize users across multiple devices.
By Game Type
Action and adventure games constitute the largest game-type segment, estimated at USD 67.0 billion in 2026. The category captures a large share of premium console and PC expenditure and also extends into mobile through action, open-world and multiplayer formats. Its commercial strength is reinforced by established franchises, high-priced premium releases, downloadable expansions and live-service extensions. Major publishers continue to concentrate development and marketing budgets on globally scalable intellectual property in this category.
Role-playing games are expected to record the fastest growth among the major game-type categories, reaching approximately USD 76.0 billion by 2032. The segment benefits from long engagement cycles, character progression, downloadable expansions and strong overlap with open-world and live-service design. Role-playing mechanics are also being incorporated into action, mobile and online multiplayer titles, broadening the addressable audience beyond traditional RPG players. Large franchises increasingly support multi-year monetization through expansions, cosmetics and recurring digital content after the original release.
By Revenue Model
Free-to-play and in-game purchases form the largest revenue-model segment, estimated at USD 105.3 billion in 2026. The model is deeply established in mobile gaming and is increasingly used across PC and console titles through cosmetic items, season passes, virtual currency and recurring content. Its broad player funnel lowers the initial access barrier while allowing successful games to monetize highly engaged users over longer periods.
Cloud gaming is expected to be the fastest-growing revenue model, reaching approximately USD 28.0 billion by 2032. Growth is supported by platform investment, improving broadband and 5G connectivity, cross-device account ecosystems and the inclusion of cloud access within broader subscription offerings. Cloud gaming remains smaller than premium sales or in-game spending, but it can extend high-end game access to lower-specification PCs, televisions, handhelds and mobile devices. Its commercial importance therefore rises as publishers and platform owners pursue device-agnostic distribution.
Market and Industry Indicators
Indicator | Latest Development | Market Impact |
U.S. consumer spending | ESA reports USD 60.7 billion of U.S. video-game consumer spending in 2025, including USD 52.3 billion on content. | Shows digital content remains the core high-value revenue pool in a mature market. |
PlayStation engagement | Sony reported more than 93 million PS5 units and 125 million monthly active accounts as of March 2026. | Large installed bases support recurring software and network-service monetization. |
Nintendo hardware cycle | Nintendo Switch 2 reached 23.68 million cumulative hardware units by June 30, 2026. | Confirms strong spending around a new console and handheld hardware cycle. |
Publisher audience scale | EA reported more than 120 million monthly players across its games and services during fiscal 2026. | Supports advertising, live services and cross-franchise recurring monetization. |
Premium release economics | Grand Theft Auto VI is scheduled for November 19, 2026 at USD 79.99 for the standard edition. | Major franchises can support higher premium price points alongside ongoing online services. |
Regional Opportunity
North America
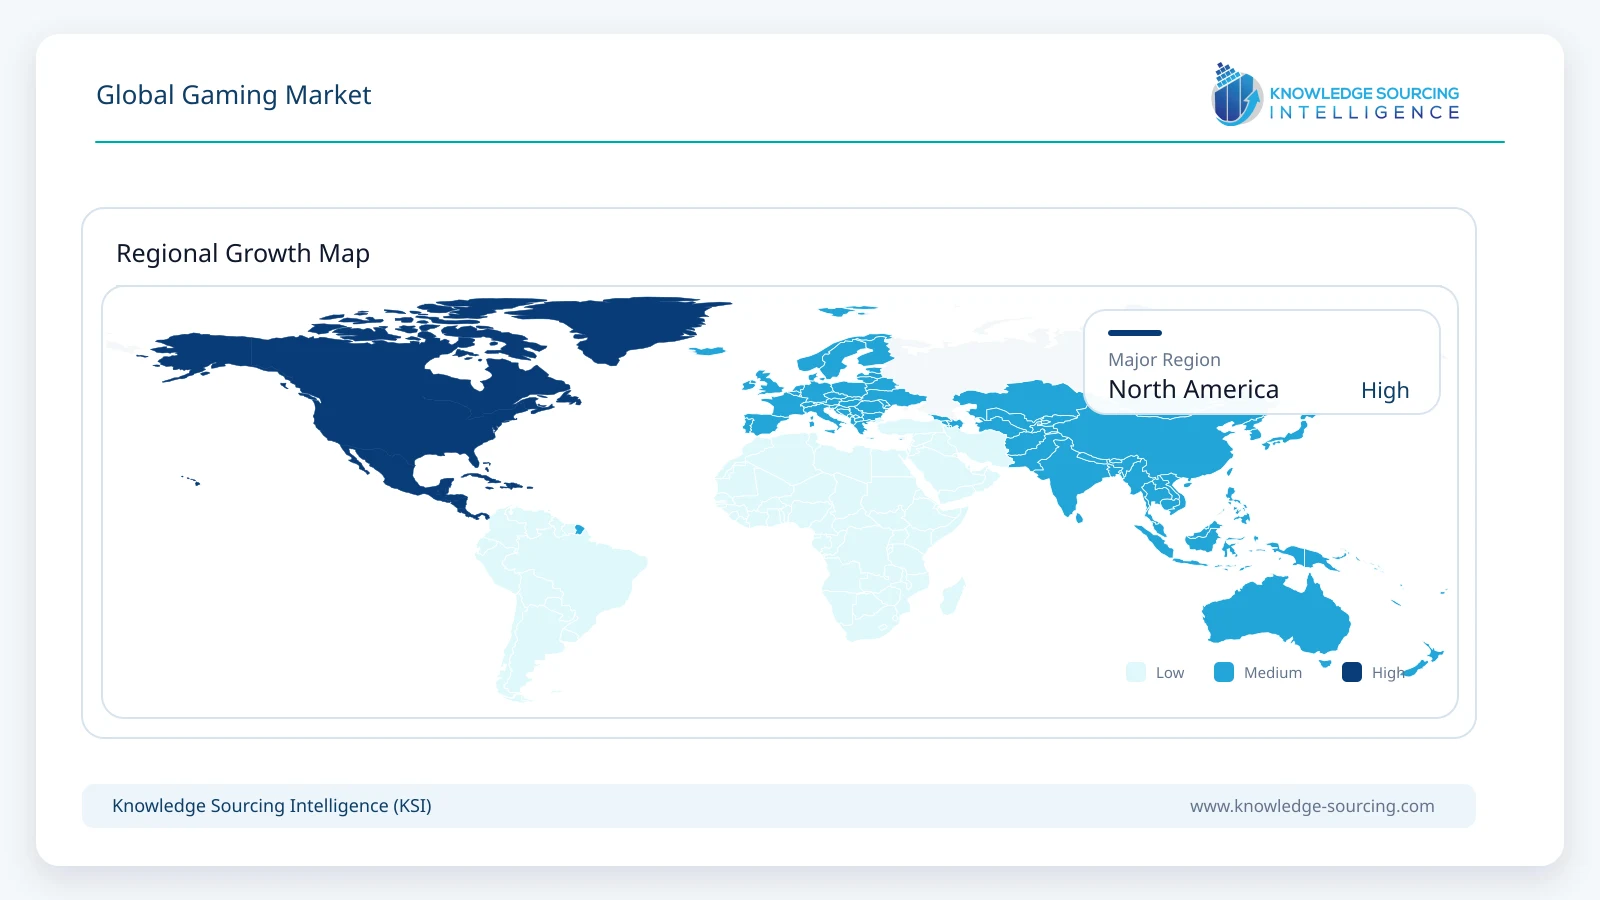
North America remains one of the highest-value gaming markets because the region combines a large paying player base, leading console and PC ecosystems, major publishers and strong digital-payment penetration. The United States alone recorded USD 60.7 billion in consumer video-game spending during 2025 according to the Entertainment Software Association, with content representing USD 52.3 billion. The same organization reported 212.3 million weekly players in 2026, demonstrating that gaming participation extends far beyond a narrow enthusiast audience.
The region is also a major center for gaming platforms and intellectual property. Microsoft operates Xbox hardware, Game Pass, PC distribution and cloud gaming; Sony Interactive Entertainment manages the PlayStation ecosystem from a large North American operating base; and publishers including Electronic Arts, Take-Two Interactive, Epic Games, Roblox and Activision Blizzard maintain substantial development, publishing or platform operations in the region. This concentration supports spending across premium releases, live services, subscriptions, advertising and creator-driven gaming environments.
Commercial models are broadening. Electronic Arts launched EA Advertising in June 2026, adding dynamic and integrated brand placements across selected game experiences. Take-Two is preparing Grand Theft Auto VI for a November 2026 release, while major sports franchises continue to combine annual releases with Ultimate Team-style recurring engagement. These developments reinforce North America as an important testing ground for premium pricing, brand integrations and long-duration franchise monetization.
Asia Pacific contributes the deepest global player base and remains critical through China, Japan, South Korea, India and Southeast Asia. Japan is central to console platforms and major intellectual property, China has large mobile and PC ecosystems, and India and Southeast Asia continue to add mobile-first players. Europe is a mature multi-platform market with strong PC and console participation, while Latin America and the Middle East offer faster player growth from smaller revenue bases.
Competitive Landscape
Competition is distributed across platform owners, publishers, mobile and PC ecosystem operators, storefronts and creator-led platforms. Microsoft, Sony and Nintendo compete through hardware, digital stores, subscriptions, first-party studios and account ecosystems. Tencent and NetEase have substantial exposure to mobile and PC publishing, while Electronic Arts, Take-Two, Ubisoft, Sega Sammy, Bandai Namco, Capcom and Square Enix compete through franchise portfolios and recurring digital content. Epic Games, Valve and Roblox occupy strategically important positions through storefronts, engines, multiplayer ecosystems, user-generated content and creator economies.
Competitive advantage increasingly depends on the ability to sustain engagement after launch. Publishers with durable franchises can monetize through downloadable content, seasonal events, subscriptions, esports, advertising and cross-media licensing. Platform owners benefit when hardware, storefronts and subscriptions reinforce each other. The August 2026 completion of Electronic Arts’ acquisition by PIF, Silver Lake and Affinity Partners also illustrates the strategic value investors place on large game communities, sports intellectual property and recurring digital revenue.
Major companies and ecosystem participants covered: Microsoft Gaming, Sony Interactive Entertainment, Nintendo, Tencent, NetEase, Electronic Arts, Take-Two Interactive, Epic Games, Roblox, Valve, Ubisoft Entertainment, Sega Sammy Holdings, Bandai Namco Entertainment, Capcom, Square Enix, Krafton, CD Projekt and Embracer Group.
Recent Developments
August 2026: Electronic Arts completed its acquisition by PIF, Silver Lake and Affinity Partners, beginning operations as a private company.
June 2026: Rockstar Games opened pre-orders for Grand Theft Auto VI ahead of its November 19, 2026 console launch.
June 2026: Electronic Arts launched EA Advertising, adding dynamic in-game advertising and brand-integration capabilities across selected franchises.
June 2026: Sony highlighted more than 93 million PlayStation 5 units and 125 million monthly active PlayStation accounts as of March 2026.
June 2026: Nintendo reported Nintendo Switch 2 cumulative sales of 23.68 million hardware units and 58.17 million software units.
Gaming Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 239.4 billion |
| Total Market Size in 2032 | USD 389.0 billion |
| Forecast Unit | Billion |
| Growth Rate | 8.4% |
| Study Period | 2021 to 2032 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2032 |
| Segmentation | Device Type, Component, Game Type, Revenue Model, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Device Type
PCs
Smartphones
Tablets
TV Gaming Consoles
Handheld Gaming Consoles and Portable Gaming PCs
By Component
Hardware
Software and Digital Content
Services
By Game Type
Action and Adventure
Strategy
Sports and Racing
Role-Playing Games
Puzzle and Casual Games
Simulation and Other Genres
By Revenue Model
Premium Game Sales
Free-to-Play and In-Game Purchases
Subscriptions and Game Libraries
Cloud Gaming Services
Advertising, Sponsorship and Brand Integrations
Downloadable Content and Expansion Packs
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Europe
United Kingdom
Germany
France
Italy
Spain
Middle East and Africa
Saudi Arabia
United Arab Emirates
South Africa
Asia Pacific
China
Japan
India
South Korea
Australia
Southeast Asia
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Market Opportunity and Key Findings
1.2. Global Player and Engagement Outlook
1.3. Principal Revenue Pools
2. MARKET OVERVIEW
2.1. Multi-Platform Gaming Ecosystem
2.2. Digital Distribution and Live-Service Economics
2.3. Console, PC, Mobile and Handheld Convergence
2.4. Cloud Gaming and Cross-Device Access
2.5. Creator Economies and User-Generated Content
3. MARKET SIZE AND FORECAST, 2021-2032
3.1. Historical Market Revenue, 2021-2025
3.2. Global Market Revenue, 2026-2032
3.3. Annual Growth Analysis
4. MARKET BY DEVICE TYPE
4.1. PCs
4.2. Smartphones
4.3. Tablets
4.4. TV Gaming Consoles
4.5. Handheld Gaming Consoles and Portable Gaming PCs
5. MARKET BY COMPONENT
5.1. Hardware
5.2. Software and Digital Content
5.3. Services
6. MARKET BY GAME TYPE
6.1. Action and Adventure
6.2. Strategy
6.3. Sports and Racing
6.4. Role-Playing Games
6.5. Puzzle and Casual Games
6.6. Simulation and Other Genres
7. MARKET BY REVENUE MODEL
7.1. Premium Game Sales
7.2. Free-to-Play and In-Game Purchases
7.3. Subscriptions and Game Libraries
7.4. Cloud Gaming Services
7.5. Advertising, Sponsorship and Brand Integrations
7.6. Downloadable Content and Expansion Packs
8. REGIONAL MARKET
8.1. North America
8.1.1. United States
8.1.2. Canada
8.1.3. Mexico
8.2. South America
8.2.1. Brazil
8.2.2. Argentina
8.3. Europe
8.3.1. United Kingdom
8.3.2. Germany
8.3.3. France
8.3.4. Italy
8.3.5. Spain
8.4. Middle East and Africa
8.4.1. Saudi Arabia
8.4.2. United Arab Emirates
8.4.3. South Africa
8.5. Asia Pacific
8.5.1. China
8.5.2. Japan
8.5.3. India
8.5.4. South Korea
8.5.5. Australia
8.5.6. Southeast Asia
9. MARKET DYNAMICS
9.1. Drivers
9.1.1. Expansion of the Global Player Base
9.1.2. Digital Distribution and Live-Service Monetization
9.1.3. Console and Handheld Hardware Refresh Cycles
9.1.4. Cloud and Cross-Platform Gaming Access
9.2. Restraints
9.2.1. Rising AAA Development Costs and Release Risk
9.2.2. User-Acquisition and Discoverability Pressure
9.2.3. Regulation of In-Game Monetization and Youth Protection
9.2.4. Platform Fees and Infrastructure Economics
10. COMPETITIVE LANDSCAPE
10.1. Market Share Analysis
10.2. Console and Platform Ecosystems
10.3. Publisher and Franchise Strategies
10.4. Mobile, PC and Creator-Led Gaming Platforms
10.5. Mergers, Acquisitions and Strategic Partnerships
11. COMPANY PROFILES
11.1. Microsoft Gaming
11.2. Sony Interactive Entertainment
11.3. Nintendo
11.4. Tencent
11.5. NetEase
11.6. Electronic Arts
11.7. Take-Two Interactive
11.8. Epic Games
11.9. Roblox
11.10. Valve
11.11. Ubisoft Entertainment
11.12. Sega Sammy Holdings
11.13. Bandai Namco Entertainment
11.14. Capcom
11.15. Square Enix
11.16. Krafton
11.17. CD Projekt
11.18. Embracer Group
12. RECENT DEVELOPMENTS
13. APPENDIX





Frequently asked questions
What is the projected size of the Global Gaming Market by 2032?
The Global Gaming Market is projected to reach USD 389.0 billion by 2032.
What is the forecasted CAGR for the Global Gaming Market?
The Global Gaming Market is projected to grow at an 8.4% CAGR through 2032.
Which device segment leads global gaming revenue in 2026?
Smartphones account for 43.0% of global gaming revenue in 2026.
What is the fastest-growing revenue model in the gaming market?
Cloud gaming is the fastest-growing model, expanding at 19.5% CAGR.
What is the largest revenue component in the gaming market?
Software and digital content represent 72.5% of 2026 gaming revenue.
What are the key drivers for Global Gaming Market growth?
Large player populations and multi-channel engagement drive market growth.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Global Gaming Market - Strategic Insights and Forecasts (2026-2032). https://www.knowledge-sourcing.com/report/global-gaming-market