
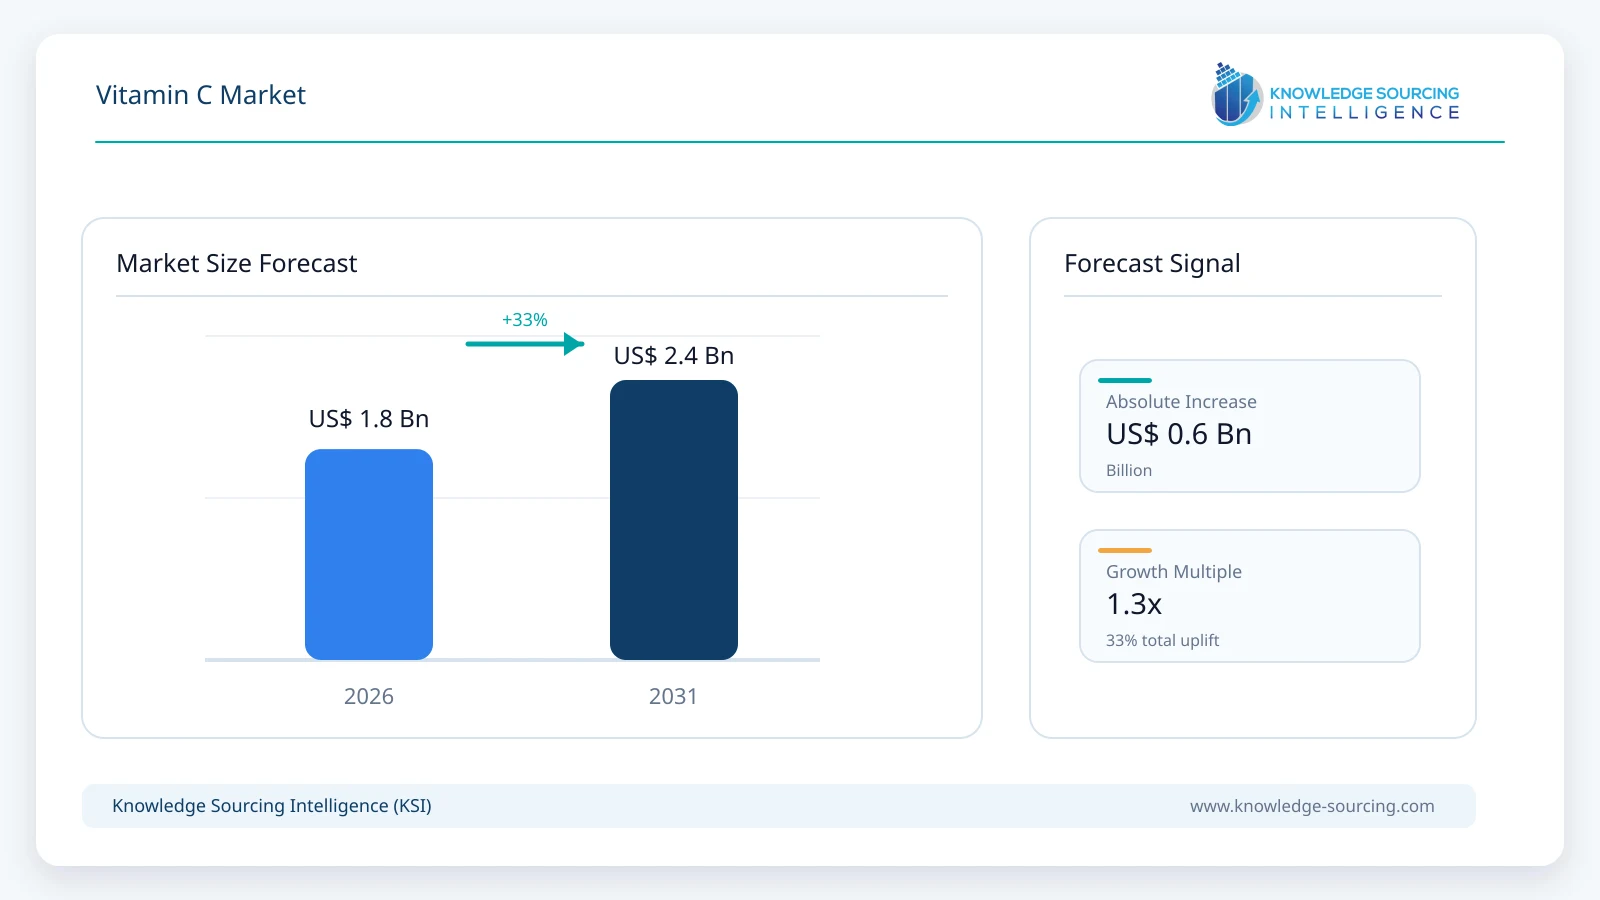
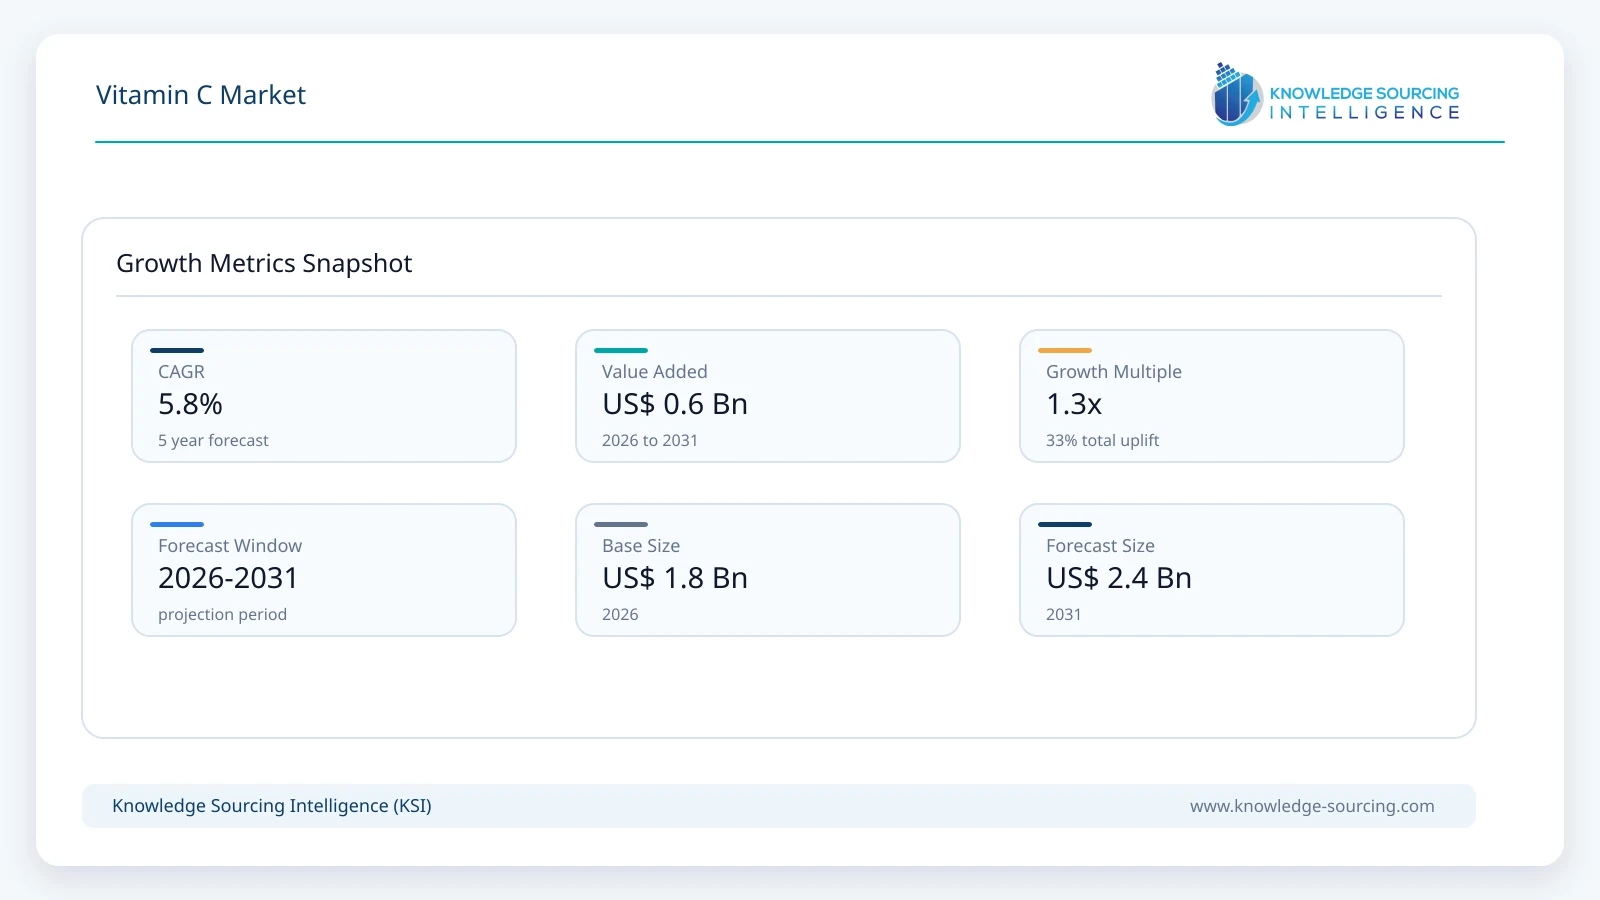
The Vitamin C market is projected to increase from USD 1.80 billion in 2026 to USD 2.39 billion in 2031, representing a compound annual growth rate of 5.8% during the forecast period.
Highlights:
- 1Vitamin C ingredient demand expands across fortified foods, supplements, pharmaceuticals, cosmetics, and animal nutrition.
- 2Ascorbic acid retains about 84% of 2026 revenue due to broad industrial applicability.
- 3Stabilized and derivative grades gain adoption where processing heat, pH, or oxidation constrain performance.
- 4Asia Pacific leads demand while China remains the dominant global manufacturing and export base.
Vitamin C Market Overview
Demand is supported by vitamin C's dual role as an essential nutrient and a functional formulation ingredient. Beyond supplementation, ascorbic acid is used as an antioxidant, reducing agent, color stabilizer, dough improver, preservation aid, and processing ingredient. Sodium and calcium ascorbate provide buffered alternatives, while coated and directly compressible grades improve handling or stability in feed, tablets, premixes, and processing environments.
The supply structure remains unusually concentrated. China exported approximately 190.6 thousand tonnes of vitamin C and its derivatives under HS 293627 in 2024, with an export value of about USD 617.6 million. China's 2025 export value for the same six-digit category was reported at approximately USD 627.9 million. dsm-firmenich states that its Dalry, Scotland facility is the only Western production site for vitamin C, with the rest of primary global capacity concentrated in China. This makes supply resilience, energy costs, maintenance schedules, regulatory compliance, and manufacturer qualification important considerations for industrial buyers.
The market is also shifting in product mix. Conventional crystalline ascorbic acid remains the largest revenue pool, but premium growth is increasingly associated with coated, granulated, buffered, natural-source, and application-specific grades. These products address stability, taste, direct compression, processing, clean-label positioning, and formulation constraints. The result is a market in which unit-volume growth is moderate, while value growth is supported by formulation complexity and specialty grade penetration.
Vitamin C Market Growth Drivers
Expansion of fortified food, beverage, and nutrition applications
Food and beverage manufacturers use vitamin C both for fortification and for its technological functionality. Ascorbic acid is commercially offered for beverages, infant and early-life nutrition, food processing, sports nutrition, and related applications, while major ingredient distributors continue to carry food-grade material at industrial scale. Demand is supported by the continued development of functional beverages, nutritional powders, premixes, bakery products, processed foods, and products positioned around immunity or antioxidant content. Unlike finished supplement demand, which can fluctuate with consumer cycles, industrial use spans multiple formulation categories. This broad end-use base supports recurring ingredient consumption and gives large suppliers opportunities to sell differentiated mesh sizes, granules, coated grades, and customer-specific specifications.
Higher-value stabilized and formulation-specific vitamin C grades
Vitamin C is sensitive to oxygen, heat, light, and formulation conditions, which creates commercial demand for grades that improve stability and manufacturing performance. Current supplier portfolios include coated ascorbic acid, directly compressible granules, fine powders, sodium ascorbate, calcium ascorbate, magnesium ascorbyl phosphate, sodium ascorbyl phosphate, and other stabilized forms. These grades expand the addressable value pool beyond commodity crystalline ascorbic acid. Coated products are particularly relevant in animal nutrition and premixes, while direct-compression grades support tablet manufacturing. In personal care, more stable derivatives can address the oxidation limitations of L-ascorbic acid in topical formulations. Product differentiation therefore supports faster value growth in specialty forms than in standard bulk material.
Supply-chain diversification and lower-carbon sourcing
The concentration of primary production in China creates a structural procurement issue for global customers. In 2025 and 2026, dsm-firmenich highlighted its Dalry facility as the only Western vitamin C production source and expanded its positioning around lower-carbon and resilient supply. In May 2026, the company reported a 49% reduction in the carbon footprint of its vitamin C production through renewable energy, process improvements, and related measures developed with Bayer. For pharmaceutical, nutrition, and consumer-health manufacturers with Scope 3 targets, verified manufacturing footprint and regional supply diversification can increasingly influence supplier selection alongside assay, price, and regulatory documentation. This supports premium opportunities for suppliers able to demonstrate traceability, compliance, and lower-carbon production.
Broad pharmaceutical and personal-care functionality
Vitamin C retains a stable pharmaceutical base as an active and formulation ingredient, while personal-care applications provide a higher-growth avenue. Ingredient suppliers market ascorbic acid and stabilized derivatives for antioxidant protection and skin-care formulations, and the commercial range has expanded toward derivatives designed to improve stability and formulation compatibility. Growth in topical antioxidant products, skin-brightening formulations, and premium dermocosmetics supports demand for high-purity and specialty grades. This application does not dominate volume, but it contributes disproportionately to value growth because purity, particle characteristics, stability, and documentation can command higher prices than standard food or feed grades.
Market Restraints
Persistent global oversupply limits pricing power for standard crystalline ascorbic acid grades.
Production concentration increases exposure to Chinese energy, raw-material, maintenance, and logistics conditions.
Oxidation and thermal sensitivity can restrict direct use in demanding formulations without stabilization.
High qualification requirements in pharmaceutical and regulated nutrition applications lengthen supplier-switching cycles.
The principal market restraint is the tension between strong application breadth and structural oversupply in standard vitamin C. dsm-firmenich's 2026 market updates described the vitamin C market as having significant or structural excess production capacity even as higher raw-material costs and producer discipline supported firmer pricing. This limits sustained price expansion for commodity grades. At the same time, concentration of manufacturing capacity creates the opposite risk for buyers: individual plant outages, logistics disruptions, or changes in Chinese operating economics can quickly alter availability. Suppliers therefore compete on cost in standard grades while differentiating through quality systems, regional supply, technical form, and documentation in higher-value applications.
Vitamin C Market Segment Analysis
Major segment: Ascorbic acid
Ascorbic acid is estimated to account for approximately USD 1.52 billion of market revenue in 2026, making it the dominant vitamin C ingredient type. Its lead reflects the breadth of direct use across food, beverages, dietary supplements, pharmaceuticals, personal care, and animal nutrition. It also serves as the base material for several downstream vitamin C derivatives and stabilized products. Large-scale fermentation-based manufacturing, established pharmacopeial and food-grade specifications, and widespread global distribution further reinforce its commercial position. Standard crystalline and powder grades continue to account for most tonnage, while finer mesh, direct-compression, coated, and application-specific grades create additional value within the ascorbic-acid segment.
Fastest-growing application: Personal care and cosmetics
Personal care and cosmetics are expected to record the fastest value growth among the principal application groups, supported by continued use of vitamin C in antioxidant, brightening, and collagen-support positioning. The segment is projected to approach USD 0.24 billion by 2031. Growth is not limited to L-ascorbic acid: formulators increasingly use stabilized derivatives when oxidation, pH, solubility, or skin-delivery requirements make pure ascorbic acid difficult to formulate. This mix shift raises the average value of vitamin C inputs used in topical applications and supports opportunities for suppliers of specialty grades, high-purity materials, and derivatives with documented stability characteristics.
Vitamin C Market Geographical Outlook
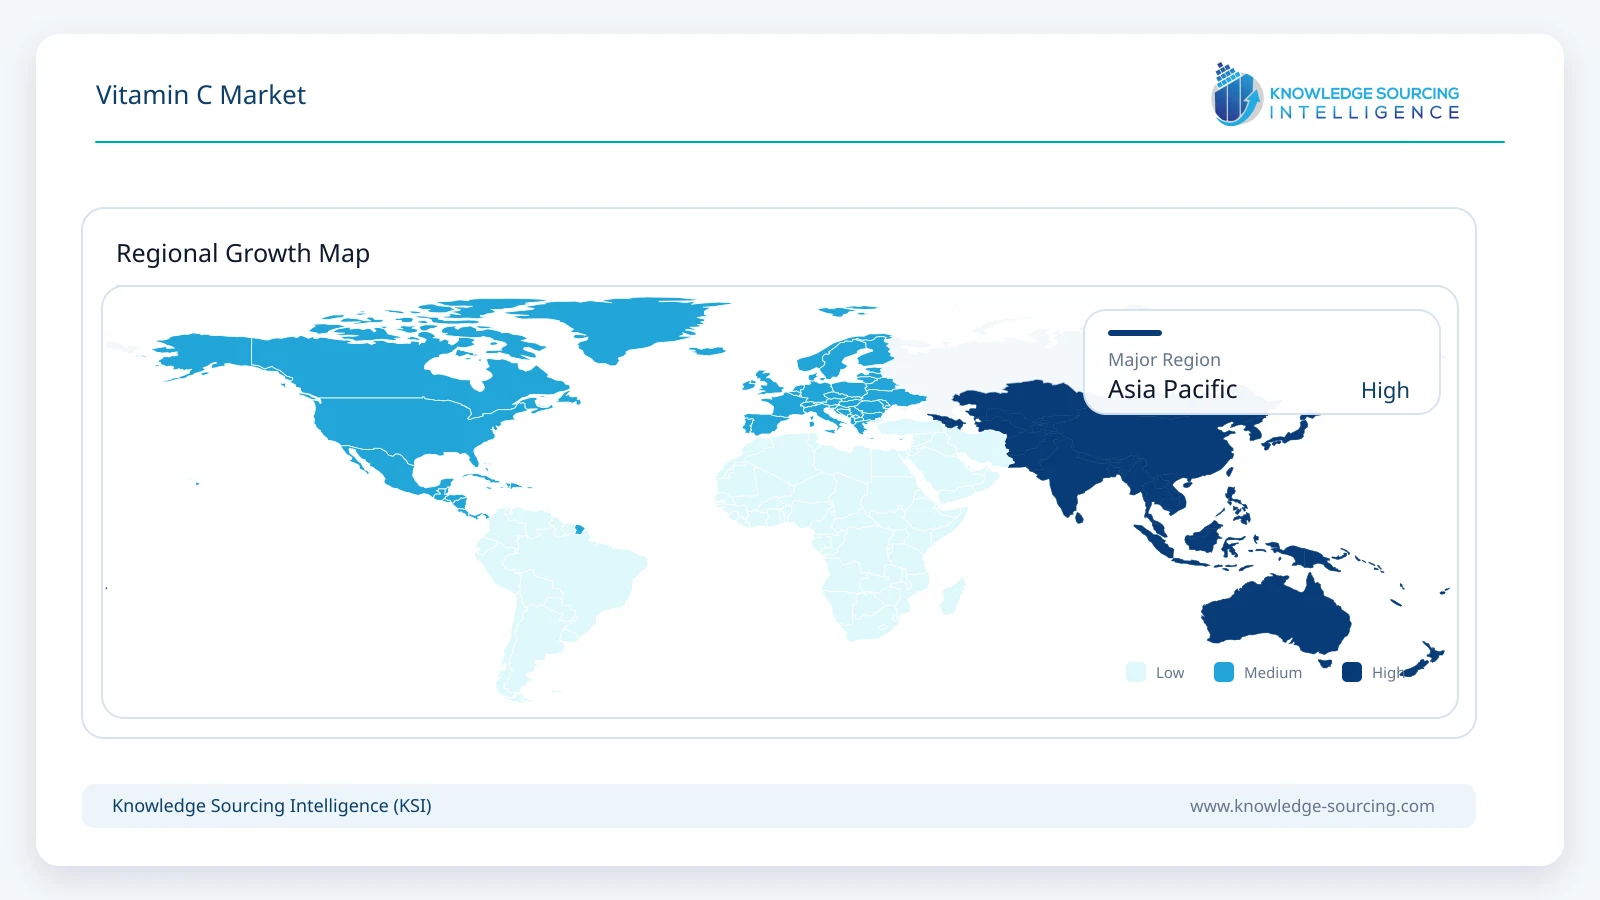
Asia Pacific is estimated to represent about 44% of global Vitamin C market revenue in 2026 and remains central to both supply and demand. China is the world's dominant manufacturing and export base, while China, India, Japan, South Korea, and Southeast Asian markets provide substantial demand from food processing, supplements, pharmaceuticals, personal care, and animal nutrition. By 2031, Asia Pacific market revenue is projected to exceed USD 1.05 billion. North America and Europe remain important value markets because of high supplement penetration, regulated food and pharmaceutical demand, and the use of premium or traceable grades. Europe also has strategic importance on the supply side through dsm-firmenich's Dalry facility. Latin America and the Middle East and Africa represent smaller but expanding markets, driven by food fortification, dietary supplements, pharmaceutical production, and imported ingredient demand.
Competitive Environment
The Vitamin C ingredient market combines a concentrated primary-manufacturing base with a broader global network of specialty manufacturers, formulators, and direct distributors. Chinese producers remain central to bulk ascorbic acid supply, including CSPC Weisheng Pharmaceutical, Northeast Pharmaceutical, Jiangsu Jiangshan Pharmaceutical, Luwei Pharmaceutical Group, Shandong Tianli Pharmaceutical, and Ningxia Qiyuan Pharmaceutical. dsm-firmenich differentiates through Western production, pharmaceutical and nutrition positioning, and lower-carbon manufacturing at Dalry. Global Calcium participates in ascorbic acid and calcium ascorbate, while Foodchem, Prinova, Univar Solutions, Brenntag, Merck KGaA/Sigma-Aldrich, Spectrum Chemical, and Thermo Fisher Scientific provide direct commercial access to food, pharmaceutical, laboratory, nutrition, and industrial grades. Competitive priorities include price, assay and impurity control, certification, regulatory documentation, physical form, direct-compression or coating performance, supply reliability, and regional inventory availability.
Recent Market Developments
September 2026: dsm-firmenich reported modest Vitamin C price increases from firmer raw-material costs and producer sentiment, while noting that significant global capacity could cap further gains.
May 2026: dsm-firmenich reported a 49% reduction in the carbon footprint of Vitamin C production at Dalry through renewable energy and process improvements linked to its Bayer collaboration.
May 2026: Ningxia Qiyuan Pharmaceutical disclosed Vitamin C production capacity of approximately 20,000 tonnes per year in its clean-production information.
2025 trade data: China exported about USD 627.9 million of HS 293627 Vitamin C and derivatives, reinforcing its central position in global supply.
Market Outlook
The Vitamin C market is expected to remain a two-speed ingredient market through 2031. Standard ascorbic acid will continue to represent most volume and revenue, with pricing constrained by installed capacity and producer competition. Faster value creation will come from coated, granulated, buffered, natural-source, low-carbon, high-purity, and application-specific materials. Food and beverage use will remain the largest demand base, while personal care and other specialty applications increase their contribution to value. Supply concentration will keep qualification of alternative sources and inventory strategy important for large buyers. Producers that combine scale with differentiated physical forms, regulatory support, sustainability credentials, and regional availability are positioned to capture a larger share of incremental value than suppliers competing only in commodity powder.
Vitamin C Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.80 billion |
| Total Market Size in 2031 | USD 2.39 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Source, Form, Application, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Ascorbic Acid
Sodium Ascorbate
Calcium Ascorbate
Other Vitamin C Derivatives
By Source
Synthetic
Natural
By Form
Powder and Crystal
Granules and Coated Forms
Liquid and Other Formulations
By Application
Food and Beverage
Dietary Supplements and Nutraceuticals
Pharmaceuticals
Personal Care and Cosmetics
Animal Nutrition
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Taiwan
Thailand
Indonesia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Definition
1.2. Scope of the Study
1.3. Market Segmentation
1.4. Currency
1.5. Assumptions
1.6. Base and Forecast Years Timeline
2. RESEARCH METHODOLOGY
2.1. Research Process
2.2. Research Data
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Market Size and Forecast
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Expansion of Fortified Food, Beverage, and Nutrition Applications
4.1.2. Growth of Stabilized and Formulation-Specific Vitamin C Grades
4.1.3. Supply-Chain Diversification and Lower-Carbon Sourcing
4.1.4. Broad Pharmaceutical and Personal-Care Functionality
4.2. Market Restraints
4.2.1. Structural Oversupply in Standard Ascorbic Acid
4.2.2. Geographic Concentration of Primary Production
4.2.3. Stability and Formulation Limitations
4.3. Porter’s Five Forces Analysis
4.4. Industry Value Chain Analysis
5. VITAMIN C MARKET, BY TYPE
5.1. Introduction
5.2. Ascorbic Acid
5.3. Sodium Ascorbate
5.4. Calcium Ascorbate
5.5. Other Vitamin C Derivatives
6. VITAMIN C MARKET, BY SOURCE
6.1. Introduction
6.2. Synthetic
6.3. Natural
7. VITAMIN C MARKET, BY FORM
7.1. Introduction
7.2. Powder and Crystal
7.3. Granules and Coated Forms
7.4. Liquid and Other Formulations
8. VITAMIN C MARKET, BY APPLICATION
8.1. Introduction
8.2. Food and Beverage
8.3. Dietary Supplements and Nutraceuticals
8.4. Pharmaceuticals
8.5. Personal Care and Cosmetics
8.6. Animal Nutrition
8.7. Others
9. VITAMIN C MARKET, BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. United Kingdom
9.4.2. Germany
9.4.3. France
9.4.4. Italy
9.4.5. Spain
9.4.6. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. South Africa
9.5.4. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. Japan
9.6.3. India
9.6.4. South Korea
9.6.5. Taiwan
9.6.6. Thailand
9.6.7. Indonesia
9.6.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Competitive Positioning
10.3. Product and Grade Differentiation
10.4. Mergers, Acquisitions, Agreements, and Collaborations
11. COMPANY PROFILES
11.1. dsm-firmenich
11.2. CSPC Weisheng Pharmaceutical (Shijiazhuang) Co., Ltd.
11.3. Northeast Pharmaceutical Group Co., Ltd.
11.4. Jiangsu Jiangshan Pharmaceutical Co., Ltd.
11.5. Luwei Pharmaceutical Group Co., Ltd.
11.6. Shandong Tianli Pharmaceutical Co., Ltd.
11.7. Ningxia Qiyuan Pharmaceutical Co., Ltd.
11.8. Global Calcium Private Limited
11.9. Foodchem International Corporation
11.10. Prinova Group LLC
11.11. Merck KGaA (Sigma-Aldrich)
11.12. Univar Solutions Inc.
11.13. Brenntag SE
11.14. Spectrum Chemical Mfg. Corp.
11.15. Thermo Fisher Scientific Inc.
12. APPENDIX
12.1. Abbreviations
12.2. Additional Sources and Data Notes





Frequently asked questions
What is the projected growth of the Vitamin C market?
The Vitamin C Market will grow at 5.8% CAGR, reaching USD 2.39 billion by 2031.
What does this report's Vitamin C market definition include?
The Vitamin C Market covers ingredient-level sales, excluding finished consumer products.
Which industries drive Vitamin C ingredient demand?
Food, supplements, pharma, personal care, and animal nutrition.
Which region leads Vitamin C ingredient demand and supply?
Asia Pacific leads demand, China dominates global manufacturing.
How is the Vitamin C product mix evolving?
Specialty and application-specific grades are driving premium value growth.
What Vitamin C ingredient type holds the largest revenue share?
Conventional crystalline ascorbic acid remains the largest revenue pool.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Vitamin C Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/vitamin-c-market