
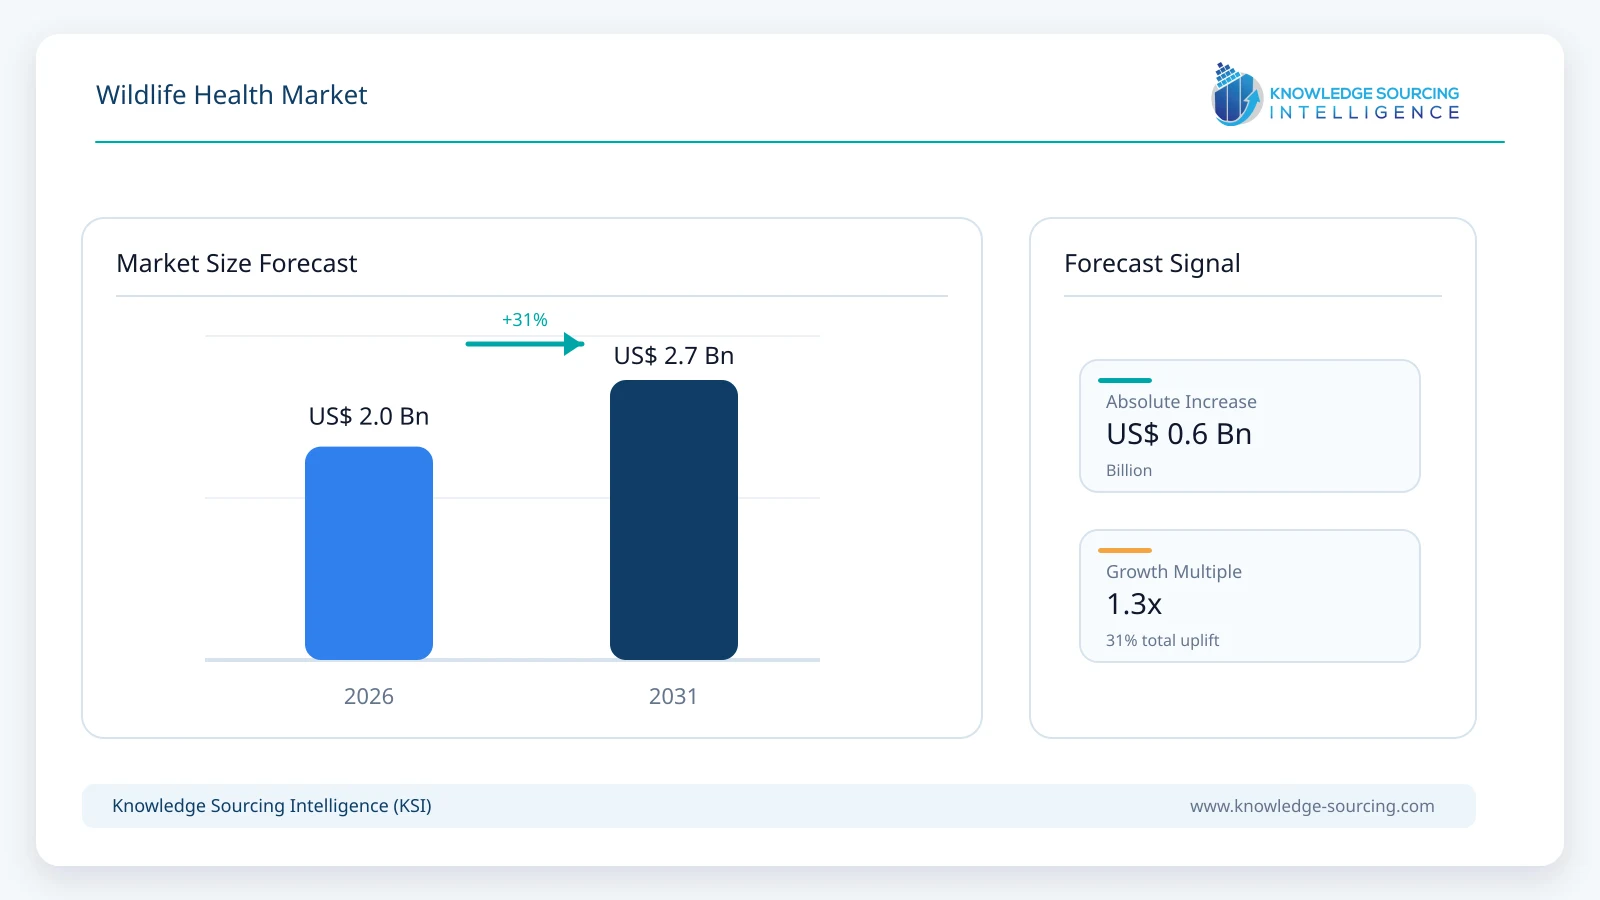
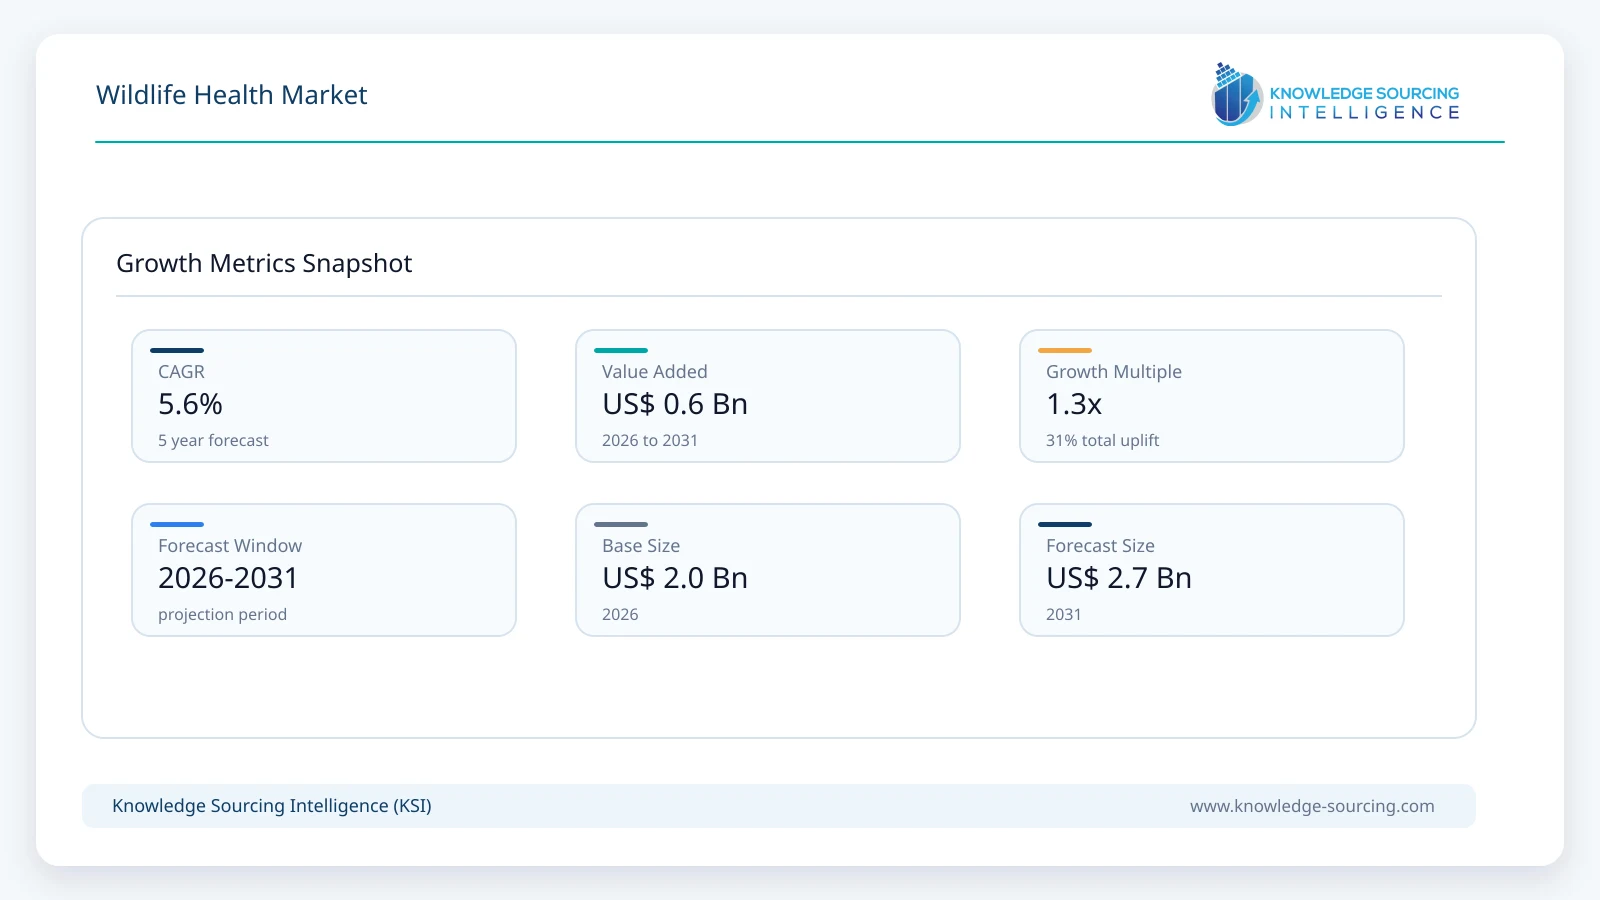
Wildlife Health Market is estimated at USD 2.05 billion in 2026 and is forecast to reach approximately USD 2.69 billion in 2031, representing a CAGR of 5.6% throughout the forecast period.
Highlights:
- 1Wildlife disease surveillance is becoming more integrated with national One Health systems.
- 2Diagnostic capacity is gaining importance as wildlife disease events cross species boundaries.
- 3Vaccination programs are expanding for selected high-conservation-value and zoonotic-risk wildlife species.
- 4Zoos and protected areas require specialized treatment, monitoring, biosecurity, and disease-control services.
- 5Regulatory agencies increasingly require earlier detection and reporting of wildlife disease events.
- 6Suppliers are combining pharmaceuticals, diagnostics, field support, and veterinary expertise for wildlife applications.
Market Overview
Disease surveillance is becoming a central purchasing requirement because wildlife can act as a reservoir, bridge, or early warning signal for pathogens. The World Organisation for Animal Health (WOAH) has incorporated wildlife health into its One Health approach and is promoting stronger surveillance, early detection, notification, and disease management systems. Its 2025 surveillance guidelines also address infectious and non-infectious diseases, pathogens, and toxic agents in free-ranging wildlife.
Purchasing decisions differ from those in conventional livestock or companion-animal markets. Wildlife managers must consider species sensitivity, conservation status, field conditions, animal restraint, dosing limitations, withdrawal concerns, biosecurity, and the feasibility of repeated intervention. Diagnostic speed is also important when animals are dispersed across remote habitats or when a disease event affects an endangered population. The USGS National Wildlife Health Center, for example, combines veterinary medicine, epidemiology, molecular biology, toxicology, and field investigation to support wildlife disease detection and management.
Commercial value is distributed across pharmaceuticals, vaccines, diagnostics, medical equipment, consumables, monitoring devices, and specialist services. Demand is therefore less dependent on routine treatment volume and more dependent on disease surveillance programs, conservation priorities, outbreak response, captive-animal management, and government-funded health interventions.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Wildlife disease surveillance | WOAH published global surveillance guidelines in 2025 | Supports standardized testing and creates demand for diagnostic and field-surveillance capabilities. |
U.S. chronic wasting disease | Detected in 37 U.S. states and 5 Canadian provinces by June 2026 | Sustained disease spread supports testing, surveillance, field diagnostics, and management programs. |
U.S. oral rabies vaccination | About 6.5 million baits distributed annually | Demonstrates recurring public-sector demand for wildlife vaccines and field delivery systems. |
European HPAI surveillance | 763 wild-bird detections, February 28-June 4, 2026 | Continued wildlife disease activity sustains demand for surveillance, diagnostics, biosecurity, and vaccination research. |
Australian H5 surveillance | 17 confirmed detections in wild seabirds by July 21, 2026 | Shows how new wildlife disease incursions can quickly create national monitoring and response requirements. |
India wildlife health program | National interdisciplinary wildlife health program maintained by WII | Supports demand for veterinary diagnostics, field medicine, mortality investigation, and specialist training. |
Market Drivers
Disease surveillance is moving toward earlier detection. Wildlife health agencies increasingly need information before mortality becomes widespread. USGS surveillance programs cover high-consequence pathogens such as highly pathogenic avian influenza and emerging diseases such as Batrachochytrium salamandrivorans. Its WHISPers platform also provides a shared system for wildlife mortality and morbidity events. These programs create recurring demand for laboratory diagnostics, sample collection equipment, field testing, epidemiological analysis, and monitoring systems. The commercial opportunity is strongest where agencies shift from reactive investigation toward structured, risk-based surveillance.
Zoonotic disease risk is increasing the value of wildlife health programs. Disease transmission at the wildlife-livestock-human interface gives government agencies a reason to fund wildlife testing even when conservation budgets are constrained. WOAH identifies wildlife surveillance as an important component of One Health because disease spillovers can remain undetected when animal and human surveillance systems operate separately. Suppliers that can connect diagnostics, reporting, field response, and veterinary expertise are better positioned for government and institutional contracts.
Captive conservation programs require more specialized veterinary care. Zoos and wildlife parks manage species with different physiology, drug responses, diets, and disease risks within the same facility. Preventive medicine therefore requires species-specific diagnostics, anesthesia, surgery, monitoring, vaccines, and consumables. Zoetis also identifies zoo and wildlife veterinarians as a specialist group requiring dedicated education and clinical support. Its foundation has funded wildlife veterinary residency support at Wildlife Conservation Society facilities since 2022, reflecting the need for specialist capacity alongside products.
Targeted vaccination is expanding into wildlife applications. Vaccination is particularly valuable where disease control can protect threatened populations or reduce transmission between wildlife and other animal populations. USDA's Wildlife Services distributes oral rabies vaccine baits in targeted U.S. areas, while Boehringer Ingelheim supplies RABORAL V-RG for wildlife rabies control programs. Such programs create demand for vaccines that can be delivered without capturing individual animals.
Wildlife disease events are creating demand for rapid field response. Mortality investigations often require sample collection, temporary restraint, anesthesia, transport, diagnostic testing, treatment, and subsequent population monitoring. The USGS National Wildlife Health Center provides field assistance, diagnostic services, epidemiological support, and disease-management guidance, illustrating the multi-stage nature of wildlife health intervention. Suppliers can therefore compete beyond individual products by combining equipment, diagnostics, pharmaceuticals, training, and technical support.
Market Restraints and Challenges
Species-specific evidence limits product development. Wildlife products cannot always rely on dosing and safety data generated in domestic animals. Species vary widely in metabolism, physiology, behavior, and sensitivity to drugs or vaccines. Small populations also limit the ability to conduct conventional clinical studies. This raises development and validation costs while reducing the commercial case for products intended for only a few species. Suppliers therefore tend to adapt established veterinary products where regulatory and clinical conditions permit, while conservation agencies and research institutions provide much of the species-specific evidence.
Field conditions raise treatment and monitoring costs. Free-ranging animals may be difficult to capture, restrain, transport, or revisit. Remote locations can also increase the cost of sample handling and cold-chain logistics. USGS disease investigations rely on coordinated field collection, preservation, shipment, laboratory examination, and epidemiological analysis. These requirements can make a technically suitable product commercially impractical if it needs frequent administration, specialist equipment, or controlled storage.
Regulatory pathways can limit rapid use of vaccines and medicines. Wildlife interventions may require consideration of animal welfare, environmental exposure, species status, food-chain risks, and unintended effects on non-target animals. The regulatory position can also differ between captive wildlife and free-ranging populations. This creates uncertainty for suppliers developing products specifically for wildlife. The recent expansion of avian influenza vaccination options in French zoos shows how regulatory changes can directly affect access to products for conservation collections.
Specialist veterinary capacity remains limited. Wildlife medicine requires skills that combine veterinary practice with ecology, epidemiology, animal restraint, anesthesia, pathology, and conservation management. The Wildlife Institute of India operates an interdisciplinary program involving health professionals, wildlife managers, ecologists, conservation specialists, veterinary institutions, and state agencies. The need for this broad skill base can constrain service availability, particularly in regions with large protected areas but fewer specialist veterinary facilities.
Demand can remain project-based and dependent on public funding. A large share of wildlife health activity is linked to government surveillance, conservation programs, research grants, emergency responses, or institutional budgets. This creates uneven purchasing patterns. An outbreak can sharply increase demand for diagnostics, vaccines, and field equipment, while spending can fall after the immediate response period. Suppliers therefore face a different demand cycle from companion-animal markets, where recurring clinical visits provide a more predictable revenue base.
Major Segment Analysis
Diagnostics
Diagnostics represent a commercially important product category because disease control depends on early and accurate identification of pathogens. Wildlife samples often require laboratory confirmation before managers can determine whether mortality is caused by infection, toxins, environmental stress, or another condition. USGS surveillance programs cover molecular testing, epidemiological investigation, and disease-specific monitoring, while WOAH's surveillance framework promotes structured national programs.
Buyers value diagnostic products that reduce sample handling time, work with limited specimen volumes, and support rapid decisions in field or laboratory settings. The requirement is especially strong for avian influenza, rabies, chronic wasting disease, amphibian fungal diseases, and other pathogens that can affect conservation or public health. Zoetis has continued expanding its veterinary diagnostics network, including its 2025 acquisition of Veterinary Pathology Group in the UK and Ireland.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
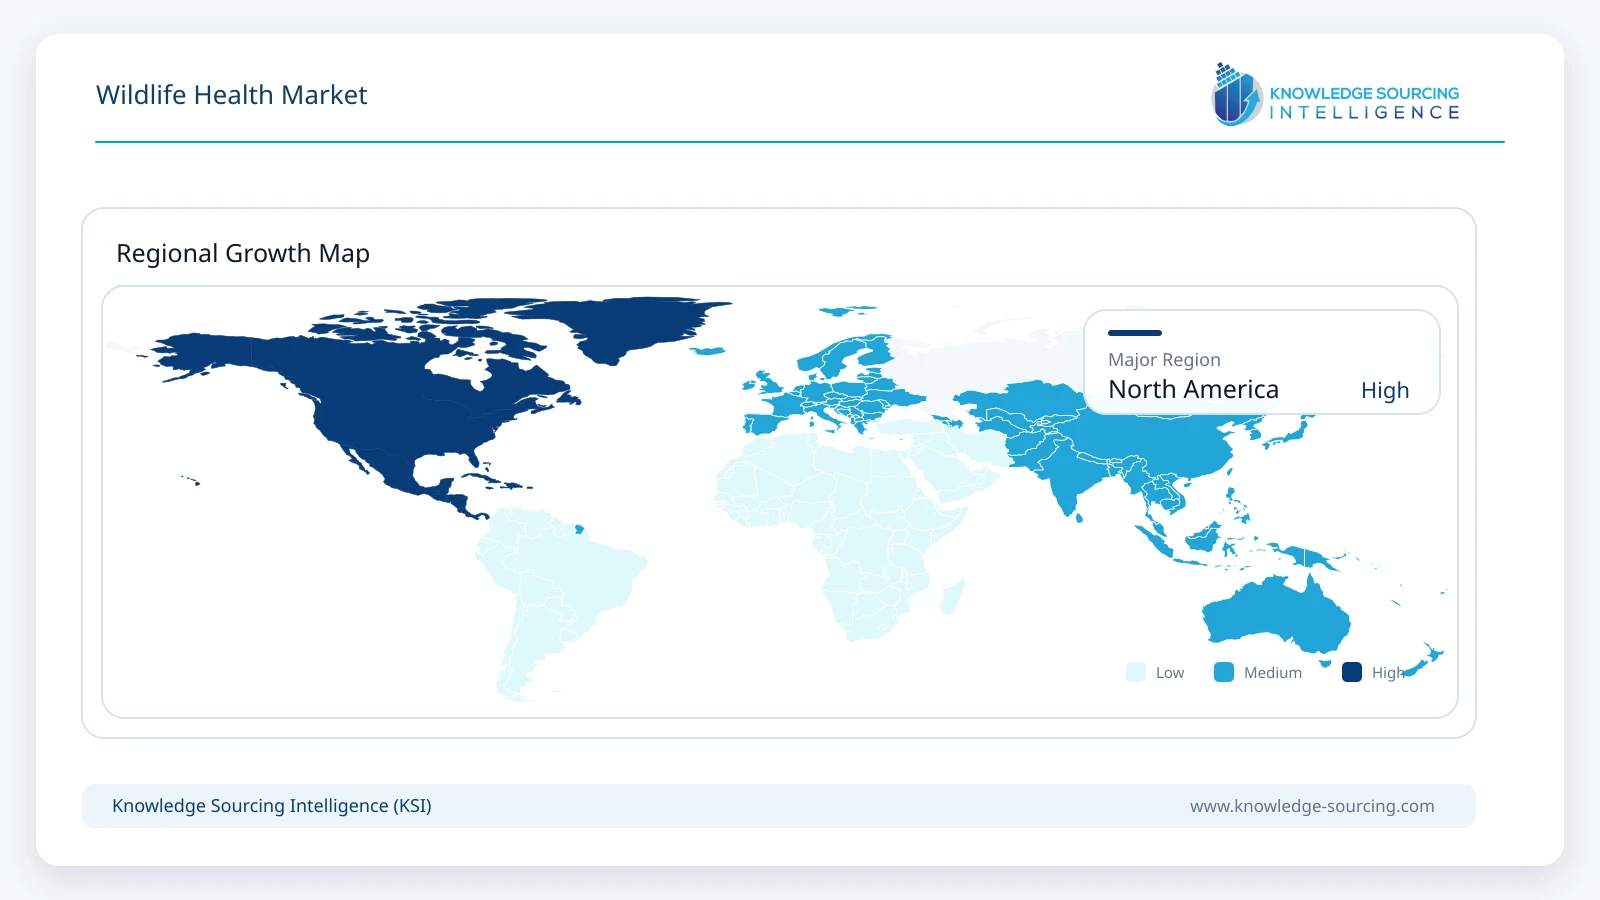
North America | Federal and state wildlife disease surveillance, chronic wasting disease testing, rabies vaccination, and avian influenza monitoring support recurring demand for diagnostics, vaccines, field equipment, and veterinary services. | Large geographic coverage increases field-surveillance and sample-transport costs, while wildlife populations remain difficult to capture and monitor consistently. |
Europe | Strong animal-health regulation, zoo networks, protected-area programs, and continued monitoring of highly pathogenic avian influenza support demand for diagnostics, vaccines, biosecurity products, and specialist veterinary services. | Regulatory requirements, species-specific vaccination considerations, and differences in national implementation can lengthen product qualification and deployment. |
Asia Pacific | Wildlife conservation programs, zoological collections, protected areas, emerging disease surveillance, and government-supported wildlife health initiatives are expanding the need for diagnostics and veterinary capabilities. | Specialist wildlife veterinary capacity and laboratory access remain uneven across countries, while remote habitats increase treatment and sample-collection costs. |
Middle East and Africa | Protected-area management, wildlife conservation, zoonotic disease control, and veterinary surveillance create demand for field diagnostics, pharmaceuticals, monitoring equipment, and specialist services. | Limited laboratory networks, specialist staffing, field logistics, and uneven public funding can restrict the scale and frequency of wildlife health programs. |
North America has the most established combination of federal surveillance, specialist laboratories, wildlife agencies, and conservation programs. The U.S. National Wildlife Health Center supports disease surveillance, field investigations, diagnostic testing, and epidemiological analysis, while USDA Wildlife Services operates large-scale oral rabies vaccination programs. Chronic wasting disease and avian influenza continue to require sustained monitoring across wide geographic areas.
Europe benefits from a structured animal-health framework under the EU Animal Health Law, which covers surveillance, notification, biosecurity, disease control, and measures involving wild animals. Continued detection of highly pathogenic avian influenza in wild birds also supports demand for laboratory testing and wildlife monitoring. The region's dense network of zoos, wildlife parks, research institutions, and veterinary laboratories provides additional institutional demand.
Asia Pacific has a more varied market structure. India's Wildlife Institute of India operates an interdisciplinary wildlife health program involving veterinary institutions, wildlife managers, ecologists, and government agencies. Similar needs exist across countries with large protected areas and substantial zoological collections, although diagnostic infrastructure and specialist veterinary expertise vary considerably between markets.
The Middle East and Africa market is more dependent on conservation programs, protected-area management, government veterinary services, and externally supported research or disease-control initiatives. Demand can be concentrated around specific wildlife populations, disease events, or conservation projects. Suppliers with local technical support, laboratory partnerships, field-service capability, and adaptable logistics are better positioned to address these operating conditions.
Competitive Landscape
The competitive structure combines diversified animal-health companies, diagnostic suppliers, specialist laboratories, veterinary distributors, and public-sector research organizations. Companies such as Zoetis, MSD Animal Health, Boehringer Ingelheim, Elanco Animal Health, Virbac, Ceva Santé Animale, IDEXX Laboratories, Dechra Pharmaceuticals, Heska, and Jorgensen Laboratories participate through broader veterinary product, diagnostic, equipment, or distribution capabilities.
Competition is not based only on wildlife-specific product portfolios. Diagnostics, vaccine access, technical support, regulatory capability, field delivery, and relationships with veterinary institutions can influence supplier selection. Zoetis has expanded laboratory capacity and diagnostics through acquisitions, while Ceva has developed wildlife-focused research activity around avian influenza vaccination. Boehringer Ingelheim has an established wildlife rabies program.
Recent Developments
June 2026: Australia confirmed H5 high pathogenicity avian influenza in wild seabirds and expanded national surveillance and response measures. By July 21, authorities had recorded 17 confirmed detections in wild seabirds, creating a new wildlife biosecurity requirement for the country.
May 2026: HORIBA launched Yumivet and the VH2500 hematology analyzer, bringing rapid, multispecies veterinary diagnostics into a dedicated platform that can support zoological and wildlife clinical applications at scale.
January 2026: Ceva Wildlife Research Fund and the Association Française des Vétérinaires de Parcs Zoologiques launched a pilot avian influenza vaccination project across six French zoos. The project is assessing vaccine protection in exotic birds with conservation value.
November 2025: Zoetis acquired Veterinary Pathology Group in the UK and Ireland to expand its veterinary diagnostics network. The transaction strengthens laboratory capacity and access to multi-specialty diagnostic services for veterinary customers.
Regulatory and Policy Environment
Wildlife health regulation is increasingly connected to One Health, biodiversity protection, animal disease control, and biosecurity. WOAH's Wildlife Health Framework calls for stronger national capacity to manage pathogen emergence and zoonotic transmission while improving wildlife surveillance, early detection, notification, and disease management. Its 2025 guidance provides a practical basis for national surveillance programs covering infectious and non-infectious threats.
The EU Animal Health Law provides one of the clearest regulatory structures for integrating wildlife into animal disease control. Regulation (EU) 2016/429 includes surveillance, notification, biosecurity, traceability, emergency measures, and specific provisions concerning wild animals. It also allows measures for emerging and listed diseases affecting wildlife.
National systems differ in how they regulate vaccination, drug use, sample collection, animal movement, quarantine, and disease reporting. Australia illustrates the importance of preparedness planning: its government has developed specific guidance for H5 avian influenza response in wildlife and has supported preparedness funding for native species.
For suppliers, regulatory capability is therefore part of market access. Products intended for free-ranging wildlife may require evidence beyond standard veterinary use, particularly where vaccination, environmental exposure, endangered species, or cross-species transmission is involved.
Outlook and Strategic Implications
Demand during 2026-2031 is likely to remain closely linked to disease surveillance, conservation priorities, zoonotic-risk management, and the health requirements of captive wildlife collections. The commercial opportunity will not be distributed evenly across all products. Diagnostics, vaccines, field monitoring equipment, pharmaceuticals, anesthesia supplies, and specialist veterinary services should benefit where governments and conservation organizations move toward earlier disease detection and structured response programs.
The expansion of wildlife surveillance also changes supplier requirements. Buyers increasingly need products that function within multidisciplinary programs rather than isolated clinical settings. Suppliers that combine reliable diagnostics, field usability, regulatory support, technical training, and data interpretation can address more of the operational problem faced by wildlife managers. Zoetis' combination of diagnostics, scientific support, and wildlife-focused veterinary education illustrates this broader model.
The next three to five years will be shaped by the frequency of wildlife disease events, public funding for surveillance, regulatory acceptance of wildlife vaccination, laboratory capacity, and the availability of specialist veterinary expertise. For investors and manufacturers, scalable diagnostics and products with applications across multiple animal-health settings can reduce dependence on small wildlife-only markets. For government agencies and conservation organizations, stronger surveillance networks and regional diagnostic capacity can reduce the cost and delay associated with outbreak response. The market's commercial performance will therefore depend as much on institutional health infrastructure as on individual product innovation.
Wildlife Health Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.05 billion |
| Total Market Size in 2031 | USD 2.69 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 5.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Animal Type, Product, Route of Administration, End-User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Animal Type
Mammals
Birds
Fish
Reptiles
Amphibians
Invertebrates
By Product
Pharmaceuticals
Vaccines
Diagnostics
Medical Equipment
Anesthesia Equipment and Supplies
Surgical Instruments
Consumables
Monitoring and Tracking Devices
Other Products
By Route of Administration
Oral
Injectable
Topical
Ophthalmic
Inhalation
Other Routes
By End-User
Zoos
Wildlife Sanctuaries
Wildlife Rescue and Rehabilitation Centers
Wildlife Hospitals
National Parks and Protected Areas
Government Wildlife and Conservation Agencies
Research and Academic Institutions
Veterinary Clinics and Hospitals
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Spain
Others
The Middle East and Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
Japan
China
India
South Korea
Indonesia
Thailand
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
2. RESEARCH METHODOLOGY
2.1. Research Data
2.2. Assumptions
3. EXECUTIVE SUMMARY
3.1. Research Highlights
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Force Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
5. WILDLIFE HEALTH MARKET BY ANIMAL TYPE
5.1. Introduction
5.2. Mammals
5.3. Birds
5.4. Fish
5.5. Reptiles
5.6. Amphibians
5.7. Invertebrates
6. WILDLIFE HEALTH MARKET BY PRODUCT
6.1. Introduction
6.2. Pharmaceuticals
6.3. Vaccines
6.4. Diagnostics
6.5. Medical Equipment
6.6. Anesthesia Equipment and Supplies
6.7. Surgical Instruments
6.8. Consumables
6.9. Monitoring and Tracking Devices
6.10. Other Products
7. WILDLIFE HEALTH MARKET BY ROUTE OF ADMINISTRATION
7.1. Introduction
7.2. Oral
7.3. Injectable
7.4. Topical
7.5. Ophthalmic
7.6. Inhalation
7.7. Other Routes
8. WILDLIFE HEALTH MARKET BY END-USER
8.1. Introduction
8.2. Zoos
8.3. Wildlife Sanctuaries
8.4. Wildlife Rescue and Rehabilitation Centers
8.5. Wildlife Hospitals
8.6. National Parks and Protected Areas
8.7. Government Wildlife and Conservation Agencies
8.8. Research and Academic Institutions
8.9. Veterinary Clinics and Hospitals
8.10. Others
9. WILDLIFE HEALTH MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. United Kingdom
9.4.2. Germany
9.4.3. France
9.4.4. Spain
9.4.5. Others
9.5. The Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. Israel
9.5.4. Others
9.6. Asia Pacific
9.6.1. Japan
9.6.2. China
9.6.3. India
9.6.4. South Korea
9.6.5. Indonesia
9.6.6. Thailand
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
11. COMPANY PROFILES
11.1. Zoetis
11.2. MSD Animal Health
11.3. Boehringer Ingelheim
11.4. Elanco Animal Health
11.5. Virbac
11.6. Ceva Santé Animale
11.7. IDEXX Laboratories
11.8. Dechra Pharmaceuticals
11.9. Heska
11.10. Jorgensen Laboratories
LIST OF FIGURES
LIST OF TABLES





Frequently asked questions
What is the projected market size for wildlife health by 2031?
The Wildlife Health Market is forecast to reach USD 2.69 billion in 2031 at 5.6% CAGR.
What is the estimated market value for wildlife health in 2026?
The Wildlife Health Market is estimated at USD 2.05 billion in 2026.
What are the primary growth drivers for the Wildlife Health Market?
Integrated surveillance, advanced diagnostics, and expanded vaccination programs drive growth.
Why is disease surveillance a central requirement in wildlife health?
Wildlife acts as a disease reservoir, bridge, or early warning signal.
Which commercial areas comprise the Wildlife Health Market's value?
Pharmaceuticals, vaccines, diagnostics, equipment, and specialist services are key areas.
How do regulatory bodies impact the Wildlife Health Market?
Regulatory agencies increasingly require earlier detection and reporting of disease events.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Wildlife Health Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/wildlife-health-market