
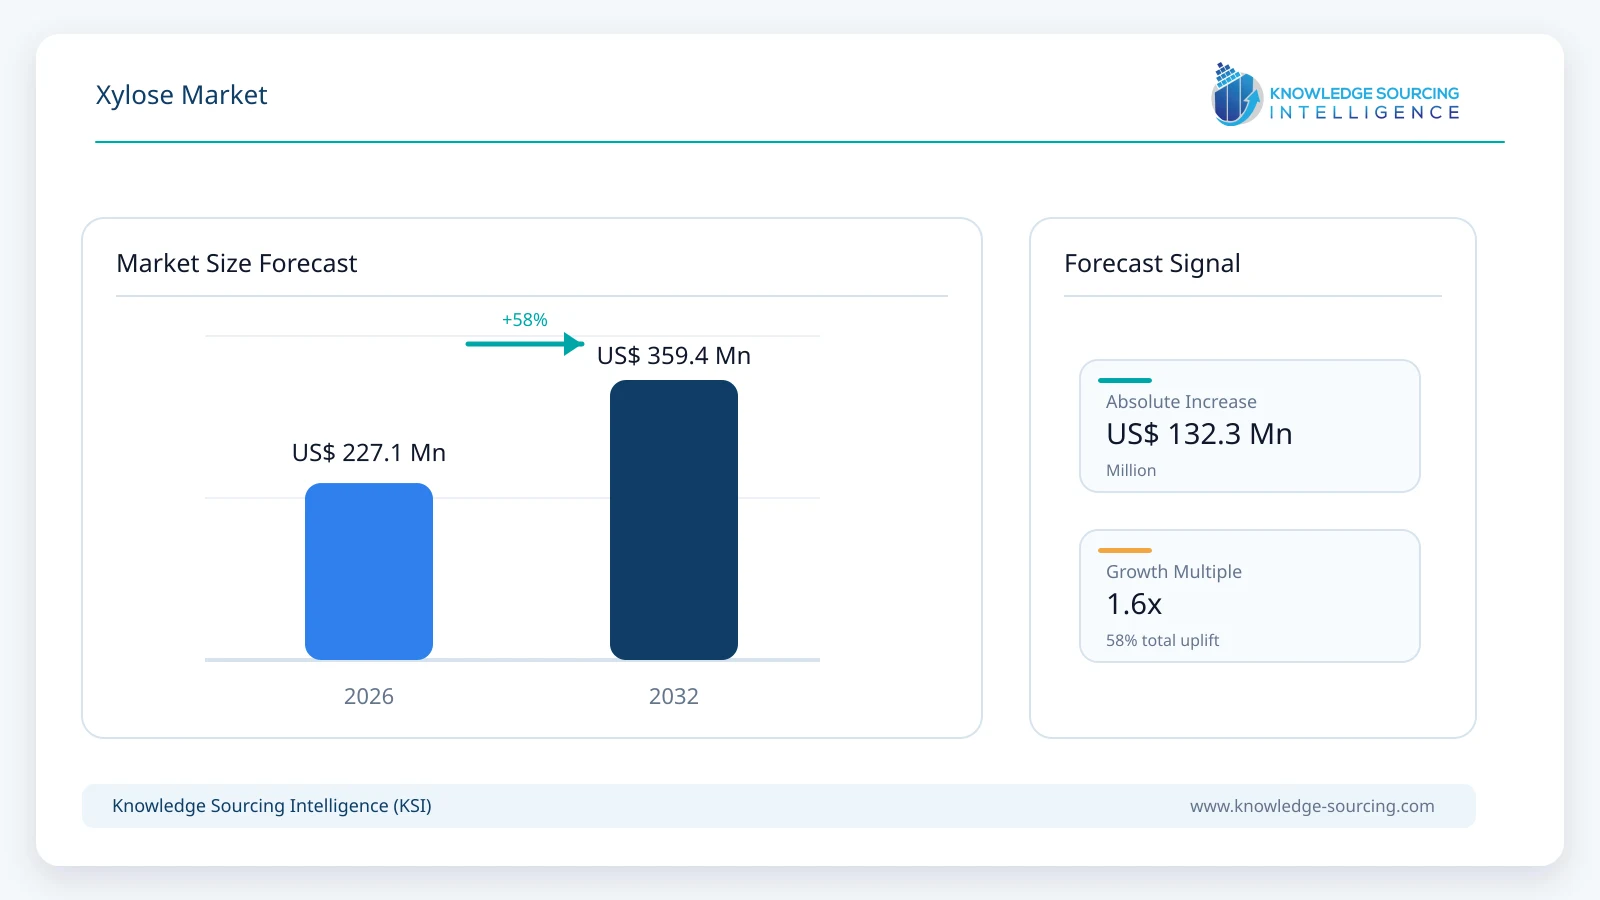
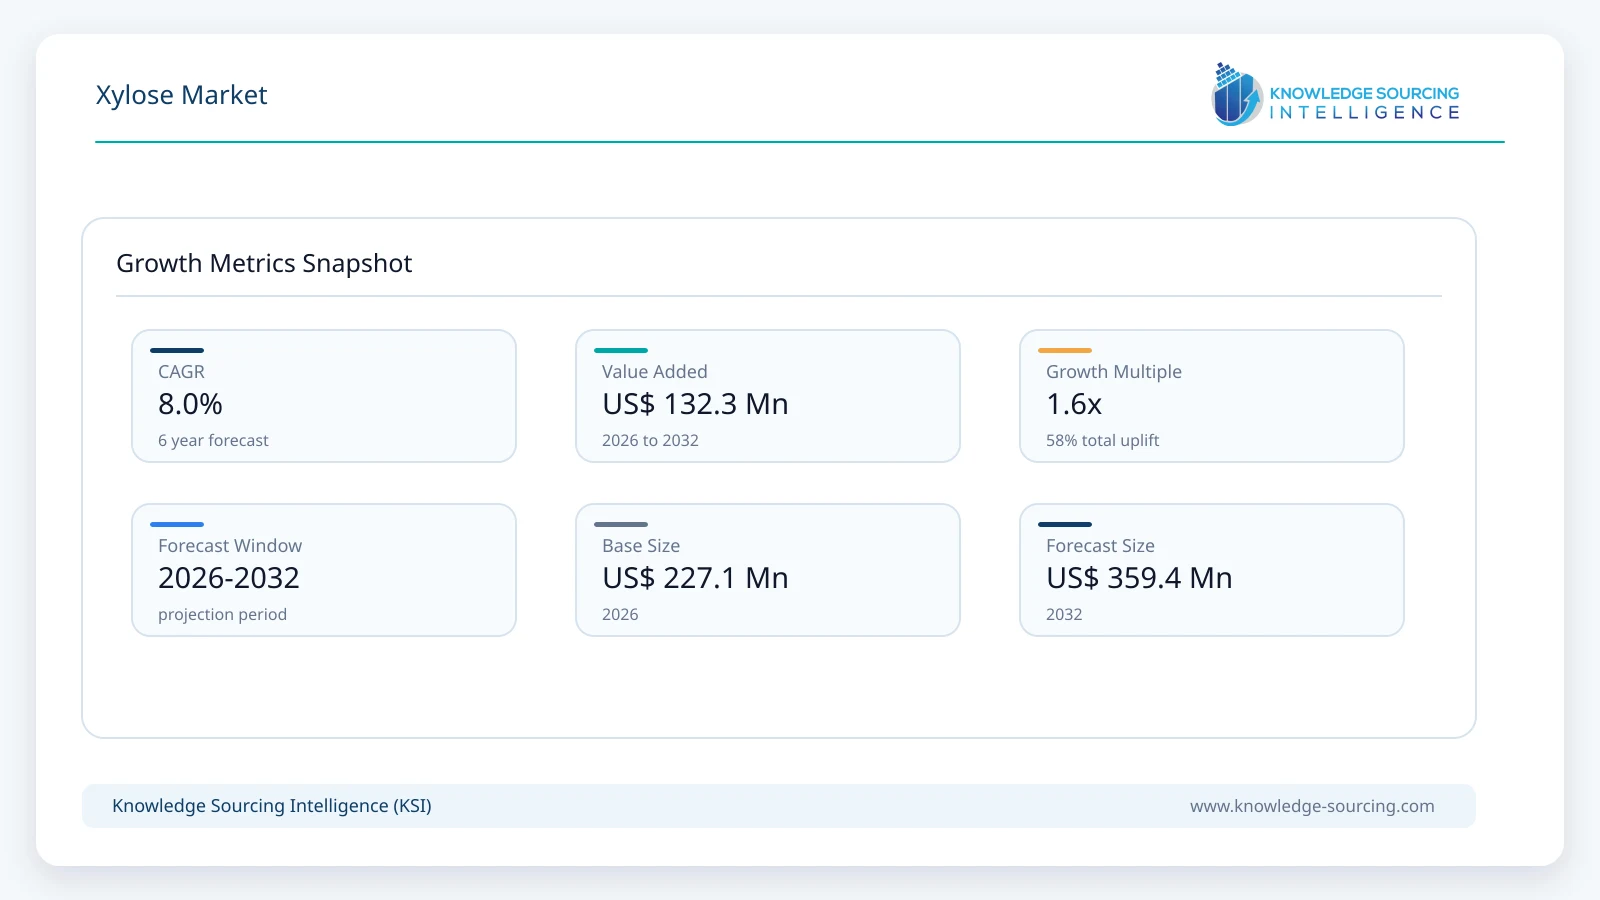
The global xylose market is estimated at US$227.14 million in 2026 and projected to reach US$359.39 million by 2032, representing a 7.95% CAGR over the forecast period.
Highlights:
- 1Merchant xylose supplied to independent xylitol producers accounts for an estimated 36.4% of market revenue in 2026. Its revenue is sensitive to the share of downstream xylitol output that relies on externally purchased xylose rather than integrated processing.
- 2Asia Pacific remains the largest producing and consuming region, supported by corncob processing, xylose purification and downstream functional-ingredient manufacturing in China.
- 3Supplier economics depend on throughput and recovery from feedstock, acid or enzyme use, decolorization, ion exchange, evaporation and crystallization. Feedstock availability alone does not determine the competitive selling price.
- 4Specialized food-flavor and bioprocess uses command different specifications from bulk xylitol feedstock, including tighter contaminant controls and repeatable soluble-solids profiles.
- 5The scarcity and specialty use of L-xylose mean its high catalog price should not be projected across industrial D-xylose volumes.
Xylose Market Trends
Captive integration is changing the economics of merchant xylose
The decisive structural variable is not simply xylitol demand, but the proportion of xylose feedstock purchased by companies manufacturing xylitol. A producer using corncob hemicellulose can produce intermediate xylose and hydrogenate it on the same site. That arrangement eliminates some third-party ingredient transactions and can reduce freight, repeated drying, packaging and exposure to spot prices. An independent xylitol producer, by contrast, has to secure qualified xylose, control inbound impurity variability and maintain working capital sufficient for imported or domestically purchased stocks.
Huakang's July 2025 exchange documentation offers rare company-level evidence. Its target producer reported 5,917.90 tonnes of commercial xylose sales in 2024 at RMB 14,106.05 per tonne, while a related xylose operation manufactured approximately 25,983 tonnes and had 40,000 tonnes of rated capacity. A large share of the raw material output was directed internally toward xylitol. Treating the entire 25,983 tonnes as sold at external prices would therefore overstate merchant revenue. The gap between output and commercial xylose sales is a direct illustration of the boundary this market must maintain.
For buyers, integration creates a different competitive landscape from the broad sweeteners industry. Non-integrated manufacturers may be more vulnerable to shifts in corncob availability and supplier production allocation. Integrated suppliers, meanwhile, have an incentive to route high-purity material either to external food and specialty customers or to their own xylitol line depending on net realizations. Merchant market growth can consequently diverge from physical xylose production even when biomass processing capacity expands.
Specifications rather than sweetness determine procurement
A basic description of xylose as a diabetic sweetener obscures its actual buying criteria. A food flavor house buying crystalline D-xylose often seeks a reliable reducing sugar for Maillard reactions, where thermal treatment with amino compounds produces specific roasted, caramelized or savory notes. Product qualification then depends on purity, moisture, color, particle characteristics and the stability of flavor formation under standardized cooking conditions. The buyer values consistent reaction performance rather than sweetness intensity alone.
In fermentation, a comparable quantity of xylose may be judged by assimilability, fermentation inhibitors and trace impurities. Sugars derived from lignocellulosic hydrolysates can carry compounds that inhibit microbial processes, requiring purification or strains tolerant of the feedstock. Those considerations create a cost boundary: refining a low-value substrate beyond the needed specification may destroy the economic advantage offered by agricultural residues. Buyers need qualified material at an acceptable total fermentation cost, not necessarily the highest available analytical purity.
For pharmaceutical and laboratory applications, traceability, batch documentation and assay specifications can justify smaller-pack premiums. Such prices should not be extrapolated to bulk industrial market volume. Merck's catalog differentiates xylose for biochemistry from flavor applications; specialty listings for L-xylose demonstrate the different scale of supply. These markets overlap chemically but not commercially.
Xylose Market Growth Drivers and Restraints
Feedstock availability and recovery economics
Corncobs are a commercially important source because their hemicellulose fraction can yield a xylose-rich liquor without requiring the complete conversion of cellulose into glucose. That does not make extraction inexpensive. Biomass is geographically dispersed; moisture, ash, xylan content and storage losses vary. Processors face transport and drying costs before hydrolysis, followed by neutralization, decolorization, membrane or ion-exchange separation, energy-intensive concentration and quality testing.
In an industrial processing chain, an apparent improvement in raw material cost can be overwhelmed by a lower recoverable sugar yield or higher purification duty. For example, a facility increasing annual throughput while using a more contaminated feedstock may see revenue volume rise without an equivalent improvement in gross margin. Projects aiming to expand xylose output therefore need to demonstrate saleable kilograms per tonne of dry biomass and cost per tonne of qualified product, rather than relying on headline feedstock tonnage.
The pressure encourages co-product approaches and integrated biorefineries. Processors may monetize arabinose, lignin-related streams or downstream sugar alcohols, but only actual xylose sales are recognized here. Revenue from those other products belongs in separate market calculations.
Xylitol dependence creates both demand and substitution risk
Xylitol production remains the central industrial demand channel for purified xylose. Hydrogenation converts the aldehyde functionality of D-xylose into the corresponding sugar alcohol. The practical purchased requirement depends on feed purity, conversion, recovery yield and whether the processor sources liquid intermediates or refined crystals. The molecular conversion relationship is not equivalent to a fixed merchant purchase ratio: integrated producers can make much of their own xylose, while some alternative fermentation routes produce xylitol directly from hydrolysates.
Research published in June 2026 demonstrated xylitol fermentation from nondetoxified corncob hydrolysate at an optimized yield of 0.67 grams of xylitol per gram of xylose. That experimental result is not a commercial plant-average yield, but it demonstrates why direct hydrolysate conversion is relevant to future xylose procurement. In October 2026, researchers affiliated with Zhejiang Huakang published a pathway converting L-arabinose and glucose into xylitol, showing a further prospective route that could reduce dependence on merchant D-xylose for specific applications.
These technological options create a restraint on raw xylose sales even as downstream specialty sweetener demand expands. Commercial purchasing decisions depend on purity, conversion performance, capital intensity, feedstock economics and qualification risk. A model extrapolating xylose merchant volumes directly from sugar-free confectionery trends would miss these changes.
Food formulation and industrial biotechnology diversify demand
Food processors use D-xylose in controlled flavor reactions, not just as a sweetening ingredient. August 2026 research on a xylose-based Maillard treatment for plant-protein patties shows how reducing sugars may influence solubility, taste and texture. Industrial adoption requires repeatable performance at manufacturing scale, alongside cost and regulatory review. This creates a differentiated application opportunity without making every flavor-reaction experiment an immediate market sale.
Bioprocessing expands the number of potential outlets for pentose sugars. September 2026 work on xylose utilization for 3-hydroxypropionic acid illustrates the need to engineer microorganisms to consume pentose-rich streams efficiently. However, integrated fermentation plants may use crude hydrolysates rather than purchased refined xylose. Commercial revenue arises only when an external buyer procures qualifying purified material; development-stage applications must be discounted until that purchasing pathway is established.
Xylose Market Segment Analysis
By Application
Xylitol Feedstock
The xylitol feedstock application is the largest merchant xylose demand segment because hydrogenation processes require a consistent carbohydrate input and sugar-alcohol manufacturers purchase qualified material when captive production is insufficient or unavailable. Its estimated 2026 market value is US$82.62 million. The central commercial tension is the choice between buying crystals and integrating hemicellulose extraction, a decision that reshapes revenues without necessarily changing the amount of xylose processed physically.
The trade-off begins at the xylose purification stage. Buying purified powder simplifies part of the upstream process but introduces a per-tonne ingredient price, packaging, inventory and, for cross-border supply, freight and duty costs. Internal extraction requires upfront capital, acid handling or enzyme management, membrane or ion-exchange systems, energy input and specialist process operation. A producer purchasing feedstock may therefore prefer external xylose when utilization is uncertain, while a high-throughput site with secure biomass supply can justify an integrated line.
Huakang's filing provides an unusually transparent example of that decision. Its related Shengjiu operation moved from a 6,000-tonne annual xylose line toward 40,000 tonnes of design capacity, and its xylose output was used primarily as an input to a downstream xylitol plant. Although approximately 25,983 tonnes were produced in 2024, external commercial sales of xylose by the target business were only about 5,918 tonnes. Those figures are not directly interchangeable measures, because they refer to related operations and different transaction boundaries. Nevertheless, the evidence shows that treating capacity as external sales can dramatically exaggerate addressable merchant revenue.
The output of xylitol cannot be counted as xylose revenue. Neither should one tonne of captive xylose be assumed to produce one tonne of finished xylitol without process losses. In determining purchasing demand, the relevant calculation is production output divided by a realistic net conversion yield, multiplied by the externally sourced share. The merchant market then depends on contract prices and the proportion of input bought from independent providers.
Supplier differentiation is built around impurity control and continuity of supply. Excess color, mineral residue or fermentation-derived inhibitors can increase purification requirements and reduce downstream throughput. Consistent crystal properties simplify handling and dissolution; reliable documentation reduces requalification risk. For purchasers operating continuous hydrogenation facilities, interruptions or deviations can cost more than a modest ingredient price premium.
Asia Pacific is central to this segment because Chinese manufacturers combine agricultural feedstocks, ingredient purification and xylitol production. Their geographic advantage is reinforced by integrated sites, although tariffs, freight and destination-country rules can influence delivered economics. In Europe and North America, buyers may place greater weight on product traceability, reliable regional inventories and acceptable manufacturing documentation. Those characteristics support differentiated pricing even when the underlying molecule is chemically identical.
By Application
Food Flavors, Bioprocessing and Specialty Uses
Food-flavor applications are estimated to reach US$98.28 million by 2032. Purchasing is governed by flavor formation, quality consistency and formula economics rather than consumer sweetener demand. The bioprocessing segment expands more rapidly from a smaller base, but commercial penetration depends on external procurement rather than captive lignocellulosic hydrolysates. Pharmaceutical, diagnostic and laboratory uses represent smaller volumes at higher specifications, with catalog prices unsuitable for establishing bulk-market averages.
By Type and Form
D-xylose accounts for nearly all industrial-scale quantities. L-xylose is retained as a specialty research category but is not assigned a large food or chemical-production share. Powder and crystalline forms support stable storage and transport, while liquid standardized grades are relevant where customers prioritize dissolution and are close enough to production sites to avoid excessive water transport. For either form, revenue comparisons require concentration-adjusted volume and transparent delivered-price assumptions.
Xylose Market Geographical Outlook
Asia Pacific: Integrated processing determines competitive advantage
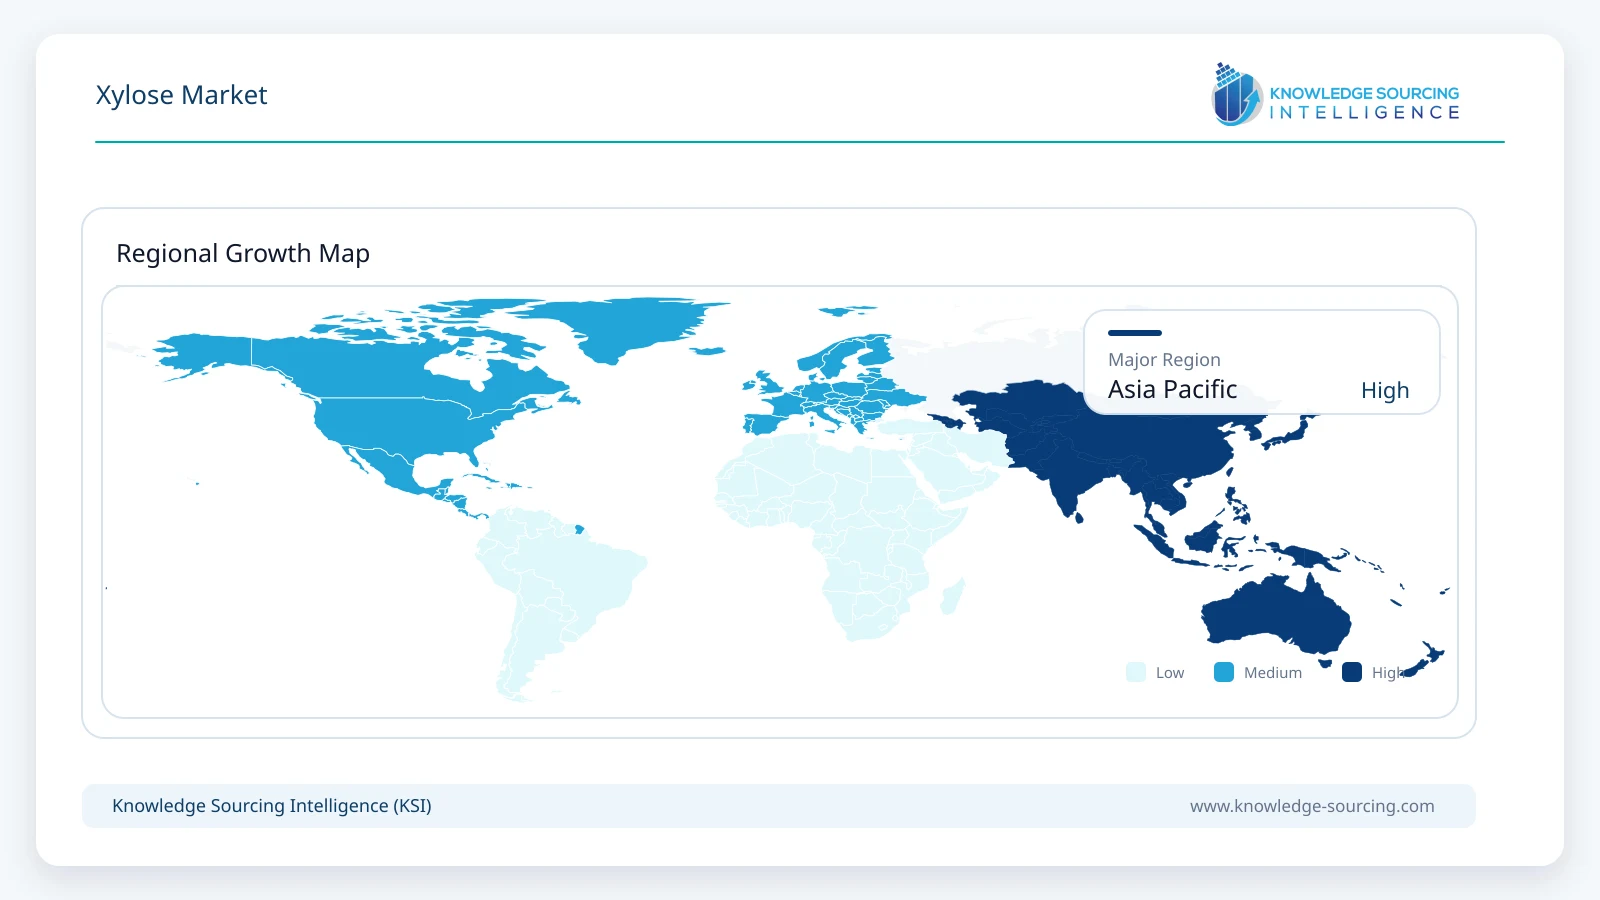
Asia Pacific accounts for the majority of refined xylose supply, particularly through Chinese producers that process corncobs and other biomass streams into sugar intermediates. The modeled region contributes US$112.79 million in 2026. The concentration of processing facilities does not mean every producer's output is available to merchant buyers. Captive demand from xylitol manufacturing can account for a substantial portion of physical xylose flow.
The regional economics depend on biomass collection density, utility expenses, process-water management, product grade and destination-country logistics. Companies investing in integrated extraction and hydrogenation can improve raw-material security, but their investments can also reduce independent purchases. Merchant suppliers therefore compete in a market shaped by both new downstream customers and ongoing vertical integration.
Europe and North America: Qualification-sensitive specialty demand
Europe and North America contain buyers in food flavoring, specialty ingredients, research and bioprocessing. Their procurement economics can differ from Chinese ex-works transaction benchmarks because transport, distributor stocking, documentation and small-lot purchasing increase delivered costs. For specialty grades, maintaining a repeatable impurity profile can matter more than nominal sugar purity alone. Buyers also evaluate alternative formulations and substrates when import availability or qualification costs become too high.
South America and Middle East and Africa
South America has biomass potential, including bagasse-derived streams, yet a biomass resource does not automatically create an economically viable refined xylose industry. Conversion to saleable product requires investment in hydrolysis, purification, drying and commercial customer qualification. In the Middle East and Africa, specialized distribution and imported ingredient sourcing remain more relevant than large-scale regional refining in the central scenario. Both regions have potential for selective demand growth without justifying a blanket assumption of local manufacturing expansion.
Competitive Environment and Analysis
The competitive landscape includes distinct types of participants. Zhejiang Huakang, through its xylose-associated operations and wider xylitol business, and Chinese producers such as Futaste and Shengquan Healtang are relevant to integrated industrial supply. Yuxin Sugar Alcohol and its related Shengjiu operation provide transaction-level evidence for the distinction between saleable xylose and internal feedstock. Specialist suppliers including Merck/Sigma-Aldrich, Thermo Fisher Scientific, HiMedia Laboratories, Carl Roth and CATO address laboratory, pharmaceutical, analytical or selected niche ingredient channels. These distributors should not be portrayed as having the same manufacturing scale as primary bulk producers.
Competition is therefore driven by secured biomass feedstock, usable extraction yields, quality qualification, captive conversion options, inventory and distribution reliability. A producer with a large downstream xylitol operation may report far greater corporate revenue than a merchant xylose specialist, but that total revenue cannot be used to calculate xylose market share. The report distinguishes manufacturer and specialty-channel participation and evaluates the supply chain using product-level evidence.
Recent Developments
August 2026: Zhejiang Huakang-affiliated researchers published an alternative xylitol biosynthesis pathway using L-arabinose with glucose co-utilization, potentially diversifying feedstock options.
September 2026: Researchers published a sugarcane-bagasse hydrolysis study using recombinant E. coli to optimize xylose and total-sugar recovery.
August 2026: Food scientists reported a xylose-based Maillard reaction approach to improve sensory and functional performance of plant-protein patties.
June 2026: An ACS Omega study demonstrated xylitol fermentation from nondetoxified corncob hydrolysate using Pichia fermentans.
April 2026: Zhejiang Huakang released its 2025 annual-report summary, detailing its integrated functional-sweetener business and production strategy.
Xylose Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | US$227.14 million |
| Total Market Size in 2032 | US$359.39 million |
| Forecast Unit | Million |
| Growth Rate | 7.95% |
| Study Period | 2021 to 2032 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2032 |
| Segmentation | Application, Type, Form, Feedstock Source, Geography |
| Companies |
|
Market Segmentation
By Application
Xylitol Feedstock (Merchant)
Food Flavors and Maillard Systems
Bioprocessing and Chemical Conversion
Pharmaceutical, Diagnostics and Laboratory
Feed and Other Industrial Uses
By Type
D-Xylose
L-Xylose (Specialty)
By Form
Crystalline and Powder
Standardized Liquid and Syrup
By Feedstock Source
Corncobs and Other Corn Residues
Hardwood and Pulp Side Streams
Bagasse, Straw and Other Residues
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Finland
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Others
Table of Contents
1. INTRODUCTION
1.1. Market Definition and Boundaries
1.2. Scope of the Study
1.3. Market Segmentation
1.4. Currency, Base and Forecast Years
1.5. Assumptions and Exclusions
2. RESEARCH METHODOLOGY
2.1. Primary and Secondary Research
2.2. Bottom-Up Volume and Realized-Price Estimation
2.3. Captive Versus Merchant Supply Reconciliation
2.4. Regional and Product Segment Reconciliation
2.5. Sensitivity and Forecast Validation
3. EXECUTIVE SUMMARY
3.1. Market Size and Growth, 2026–2032
3.2. Key Demand and Supply Findings
3.3. Strategic Commercial Implications
4. MARKET DYNAMICS
4.1. Drivers
4.1.1. Xylitol Feedstock Procurement
4.1.2. Flavor and Maillard-Reaction Applications
4.1.3. Bioprocessing and Industrial Biotechnology
4.1.4. Biomass Refining and By-Product Economics
4.2. Restraints
4.2.1. Captive Xylose Integration
4.2.2. Recovery and Purification Costs
4.2.3. Qualifying Specialty Grades
4.2.4. Competing Substrates and Downstream Pathways
4.3. Porter's Five Forces Analysis
4.4. Industry Value Chain Analysis
5. XYLOSE MARKET BY APPLICATION
5.1. Introduction
5.2. Xylitol Feedstock (Merchant)
5.3. Food Flavors and Maillard Systems
5.4. Bioprocessing and Chemical Conversion
5.5. Pharmaceutical, Diagnostics and Laboratory
5.6. Feed and Other Industrial Uses
6. XYLOSE MARKET BY TYPE
6.1. Introduction
6.2. D-Xylose
6.3. L-Xylose (Specialty)
7. XYLOSE MARKET BY FORM
7.1. Introduction
7.2. Crystalline and Powder
7.3. Standardized Liquid and Syrup
8. XYLOSE MARKET BY FEEDSTOCK SOURCE
8.1. Introduction
8.2. Corncobs and Other Corn Residues
8.3. Hardwood and Pulp Side Streams
8.4. Bagasse, Straw and Other Residues
9. XYLOSE MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. Germany
9.3.2. France
9.3.3. United Kingdom
9.3.4. Finland
9.3.5. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. South Africa
9.4.4. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. Japan
9.5.3. India
9.5.4. South Korea
9.5.5. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Manufacturer and Distributor Landscape
10.2. Merchant Versus Captive Production
10.3. Strategic Supply and Qualification Considerations
10.4. Mergers, Acquisitions and Partnerships
11. COMPANY PROFILES
11.1. Zhejiang Huakang Pharmaceutical Co., Ltd.
11.2. Yuxin Sugar Alcohol Co., Ltd.
11.3. Shengjiu Sugar Alcohol Co., Ltd.
11.4. Futaste Pharmaceutical Co., Ltd.
11.5. Shengquan Healtang
11.6. Merck KGaA / Sigma-Aldrich
11.7. Thermo Fisher Scientific
11.8. HiMedia Laboratories
11.9. Carl Roth GmbH
11.10. CATO Research Chemicals
12. APPENDIX
12.1. Definitions and Conversion Factors
12.2. Sources and Assumptions
12.3. Research Limitations
12.4. Abbreviations
Navigate
Trusted by the world's leading organizations











