
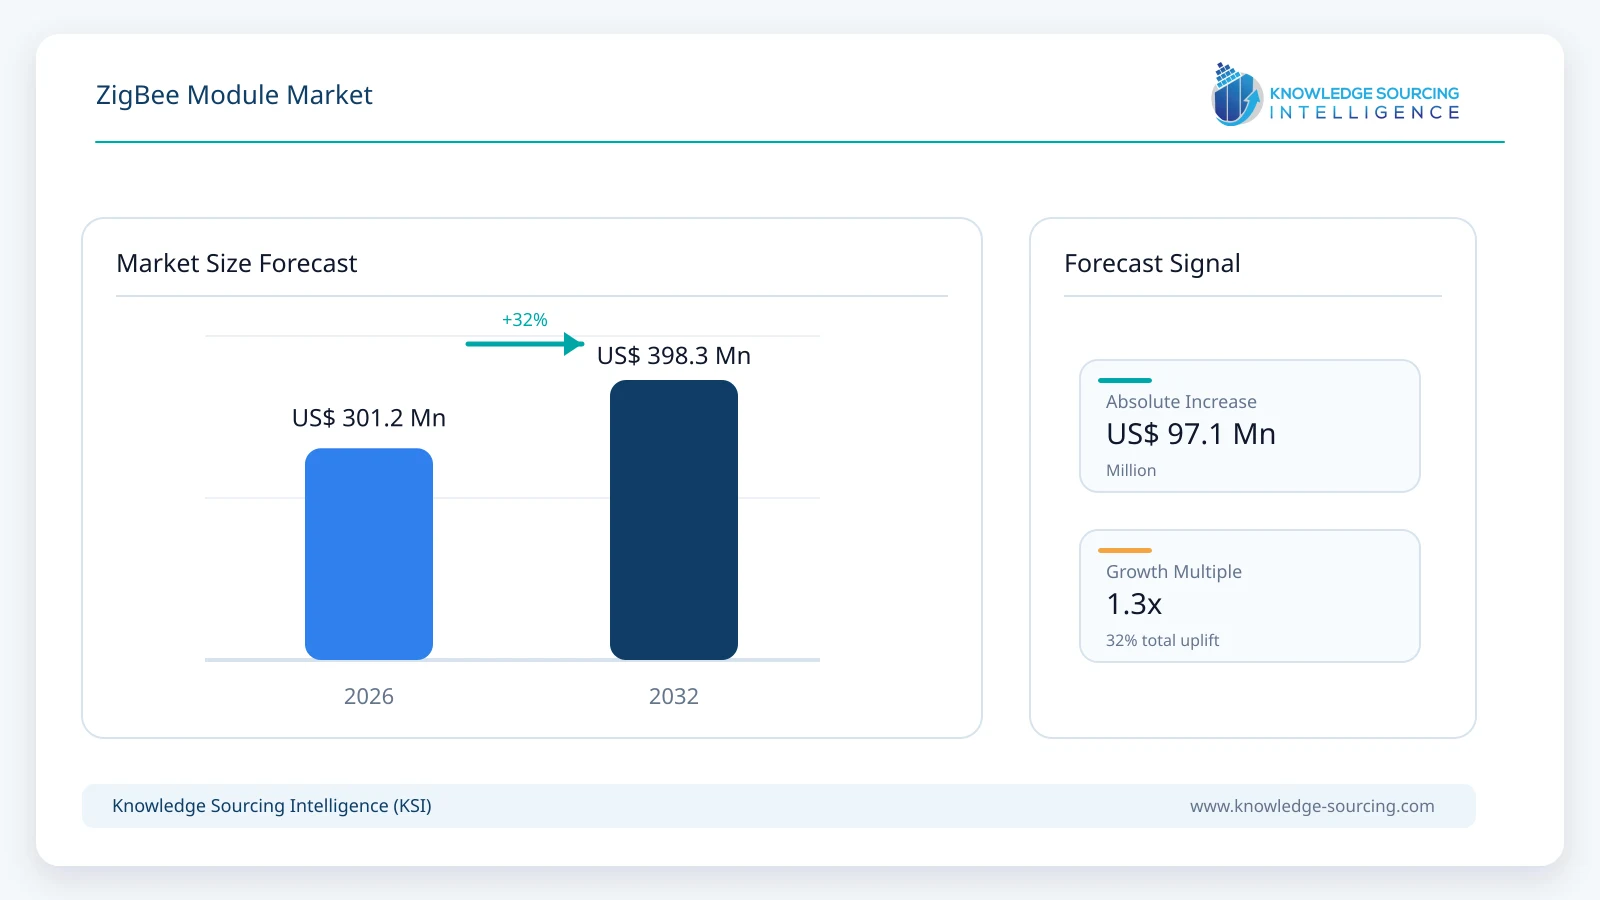
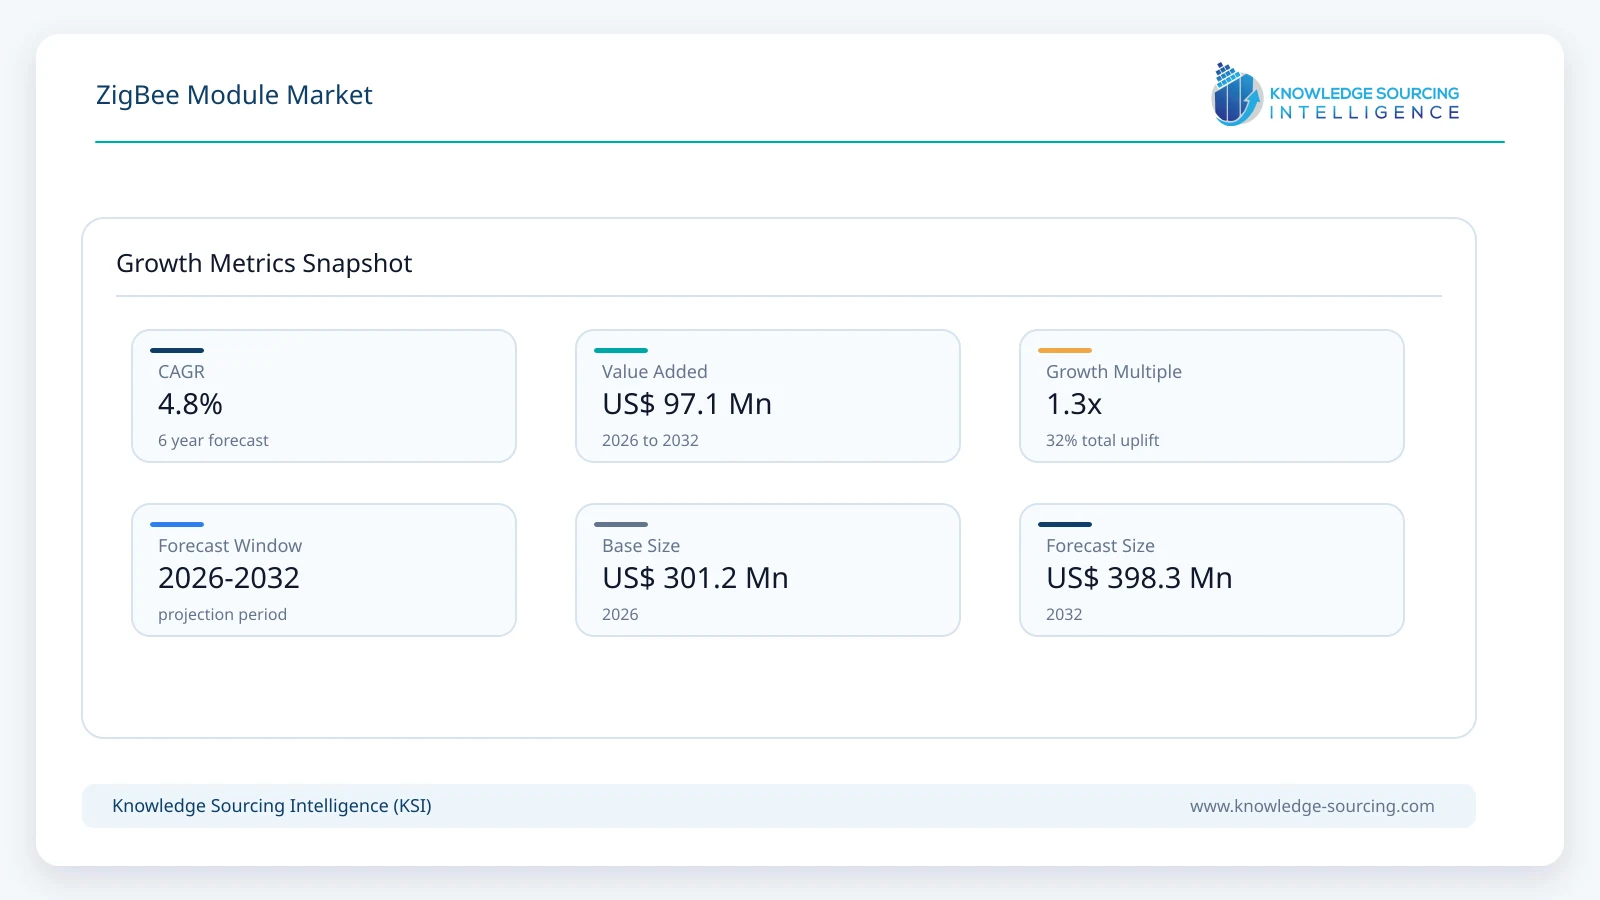
The Zigbee module market is estimated at USD 301.2 million in 2026 and is projected to reach USD 398.3 million by 2032, registering a CAGR of 4.8% over the forecast period.
Highlights:
- 1Residential controls and sensors represent 27.8% of modeled 2026 module revenue, supported by retrofit smart-home equipment and integrated sensors.
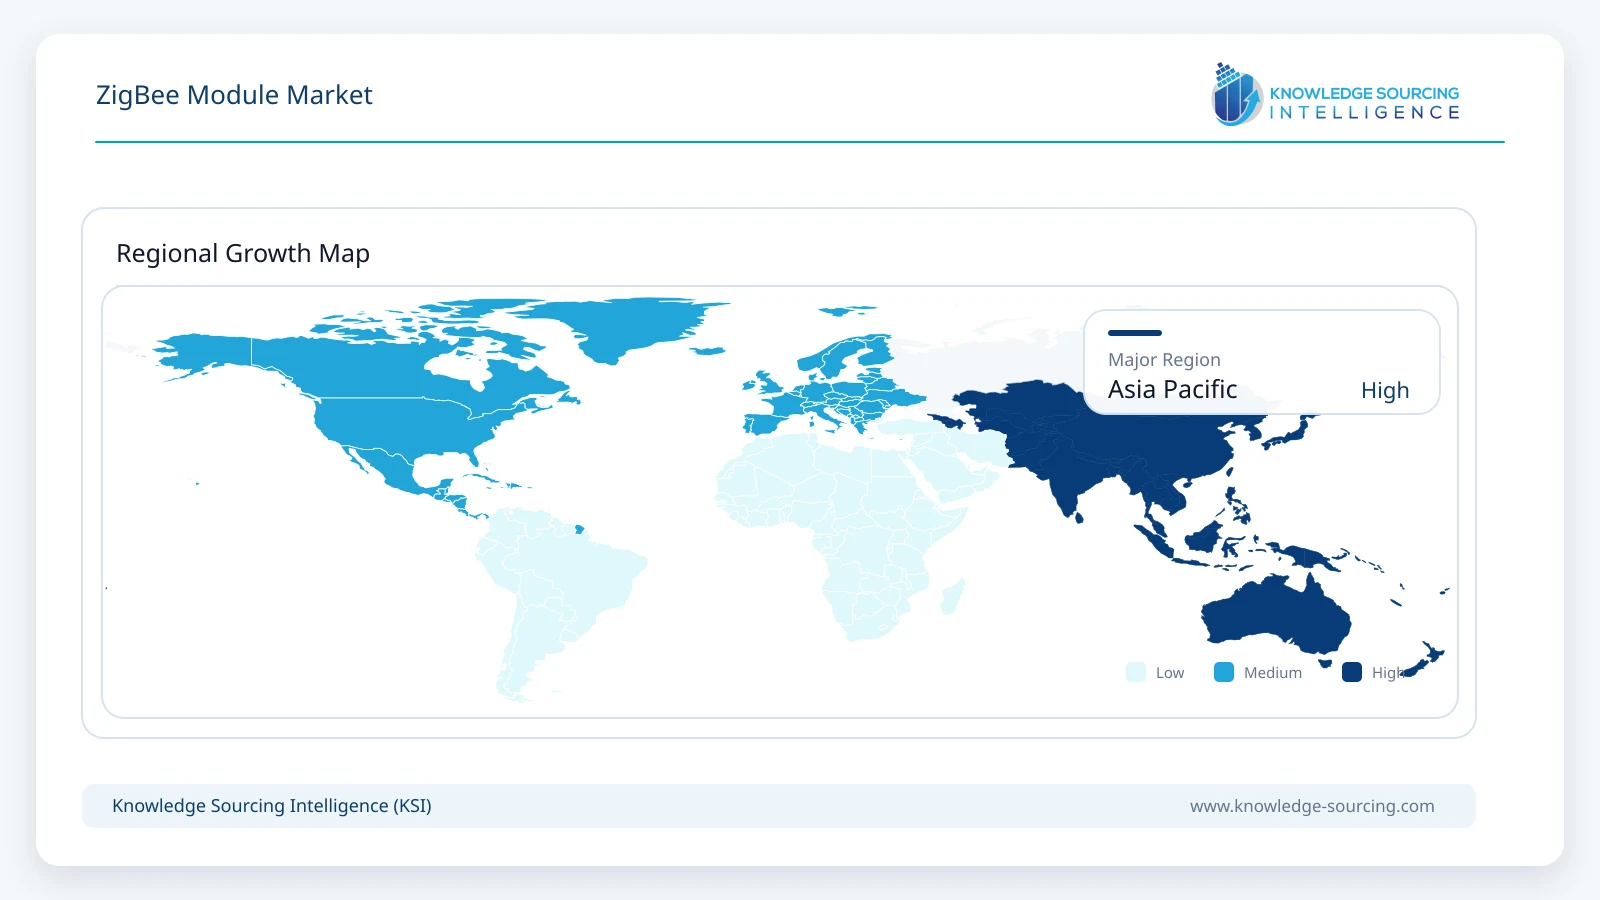
- 2Asia Pacific accounts for approximately 39.1% of 2026 module revenue, reflecting the region’s position in connected-device manufacturing and component integration.
- 3Zigbee 4.0 and the Suzi sub-GHz certification pathway expand the technology roadmap, but they do not establish immediate volume sales of compatible modules.
- 4Concurrent Zigbee and Matter/Thread operation is reshaping OEM architecture decisions; multi-protocol capability does not automatically mean that every qualifying module is deployed for Zigbee.
Market revenue is generated by embedded radio modules designed and supplied for equipment using Zigbee networking, including dedicated Zigbee modules and multiprotocol modules deployed with Zigbee functionality. The analysis values the RF module rather than the price of an entire connected lamp, smart meter, environmental sensor, gateway or building automation system.
Module demand depends on two separate decisions. Device manufacturers first select Zigbee as a connectivity option, then determine whether to purchase an integrated, prequalified radio module or place an RF system-on-chip directly on their circuit board. The second decision is increasingly sensitive to production scale, certification expenditure, engineering resources, antenna performance and supplier lifecycle commitments. A growing population of connected devices therefore does not translate automatically into equivalent growth in standalone module revenue.
Zigbee Module Market Trends and Growth Drivers
RF-module procurement shifts toward development risk and certification economics
The first constraint in module procurement is rarely the raw Zigbee link budget alone. Original equipment manufacturers must qualify antenna performance, manage coexistence with 2.4 GHz Wi-Fi and Bluetooth traffic, implement network security, and obtain applicable radio approvals across destination markets. These tasks introduce engineering expense and product-launch risk that are disproportionately important for small and mid-volume equipment manufacturers. A radio module with matched RF components and existing compliance documentation can reduce the redesign burden even when its unit price exceeds that of a bare chip.
For large, standardized consumer-electronics programs, the calculation is different. An OEM shipping millions of identical devices can amortize antenna design, RF certification and firmware integration over a far larger production run. Direct system-on-chip integration may therefore reduce the per-device bill of materials. This is why the revenue outlook must incorporate an explicit module-attachment rate instead of multiplying all Zigbee-capable device shipments by the price of an RF module. The commercial competition is partly between module suppliers and chip-level integration, not simply among module brands.
The distribution channel illustrates the price distinction. Tuya’s ZTU module is publicly listed at a little above three dollars per unit for a thousand-unit order, while a Silicon Labs MGM240P module is listed near five dollars at the same order quantity. These are published distributor quotations, not proof of realized multi-million-unit OEM contract prices. They nevertheless indicate why an estimate involving billions of dollars in standalone modules needs a credible bridge to annual unit shipments, mix and realized selling prices.
Multiprotocol integration changes competition and revenue attribution
Zigbee and Thread use related IEEE 802.15.4 radio foundations, while Matter specifies an application-layer interoperability approach that can operate over Thread or Wi-Fi. A module may support Zigbee, Thread and Bluetooth Low Energy through the same silicon architecture, but that capability does not establish which network stack the finished product uses. The appropriate revenue attribution must follow the deployed use case rather than count every multiprotocol module as Zigbee revenue.
The June 2026 collaboration between Signify and Silicon Labs illustrates how this distinction affects hardware planning. Their announced concurrent multiprotocol approach allows selected Philips Hue smart bulbs to support Zigbee and Matter over Thread with compatible wireless silicon. For existing Zigbee installations, continuity reduces the incentive to replace the full device fleet. For module suppliers, the opportunity shifts toward secure software stacks, adequate memory, concurrent radio scheduling and stable long-term support. The disadvantage is that protocol convergence can also make the RF hardware increasingly interchangeable across product ecosystems.
Silicon Labs’ MGM260P and xGM270S families further demonstrate the move toward preintegrated and certified multiprotocol solutions. Form factor, low-power operation and security resources matter because module selection is embedded in the customer’s mechanical design and battery-life commitments. Suppliers that preserve firmware and footprint continuity can win repeat business when manufacturers revise products over several generations. A protocol-only comparison would miss these commercial switching costs.
Zigbee 4.0 expands opportunities but raises transition costs
The Connectivity Standards Alliance released Zigbee 4.0 in November 2025, introducing network-management and security updates alongside support for a sub-GHz extension branded Suzi. Product certification for Suzi opened in September 2026. These milestones address deployment constraints in larger buildings, utility assets and industrial sites, where radio penetration through walls and long distances can undermine conventional short-range configurations.
The value proposition is operational: greater range can reduce the number of repeaters, provisioning work and maintenance visits required to cover a property. However, certification availability does not prove that a broad commercial module portfolio is already shipping. Module vendors still require suitable silicon, country-specific frequency planning, interoperability testing and customer design wins. The new specification should therefore be treated as a medium-term product-development opportunity, not as evidence of immediate double-digit growth across all existing Zigbee module categories.
Smart-energy use cases require stricter product qualification
Zigbee Smart Energy provides a mature reference architecture for connecting meters and home-area-network equipment. Utility-grade equipment is purchased through long qualification cycles and may remain in the field for more than a decade. Module selection consequently depends on secure commissioning, firmware maintenance, stable component availability and conformance with the operating environment. Procurement value can be higher than in commodity lighting, but deployment volumes vary by geography and utility technology choice.
It is also important not to treat every smart meter as a Zigbee module sale. Meter communications may use cellular, RF mesh, Wi-SUN, PLC or other technologies, and some meters use Zigbee only for the in-home interface. The economic unit in this market is the radio module purchased for a verified Zigbee function. Applying total electricity-meter installation figures without a Zigbee technology and module-attachment adjustment would systematically inflate the addressable market.
Zigbee Module Market Restraints
Price pressure is amplified by the availability of integrated wireless chips, particularly in cost-sensitive, high-volume lighting and accessory products. End-device OEMs can substitute custom RF layouts for certified modules when unit scale justifies the engineering burden. At the same time, multiprotocol chipsets create technology substitution within the same hardware footprint: a product redesigned for Thread may no longer contribute Zigbee module demand even if the RF component itself is technically capable of operating Zigbee.
Other restrictions are application-specific. Battery-powered sensors must meet operating and standby current targets without sacrificing link reliability; commercial buildings require dependable mesh behavior through high-density radio environments; utility applications impose cybersecurity and component-lifecycle requirements. The deployment economics also include gateway compatibility and the cost of replacing installed nodes. These constraints reward mature ecosystems, but can lengthen supplier qualification and restrain near-term volume conversion.
Zigbee Module Market Segment Analysis
By Application: Residential Controls and Sensors
Residential controls and sensors constitute the largest modeled application segment, reaching US$109.45 million in 2032. Demand encompasses smart plugs, switches, occupancy and contact sensors, thermostatic controls, motorized-shade controllers and related low-data-rate automation nodes. The purchasing problem is not simply whether a device can transmit a packet: manufacturers must balance RF reliability across varied housing layouts against battery life, installation simplicity, local operation and connectivity to existing hubs.
Low-duty-cycle sensors can operate for extended periods on small batteries, but antenna placement and network-join behavior impose product engineering costs. Sensors installed inside metal-backed housings, behind walls or near dense wireless traffic require careful validation. A certified embedded module can accelerate design qualification because its RF components and antenna arrangement have already been characterized. That advantage is greatest when a supplier is producing several closely related models at moderate volumes and cannot justify custom radio engineering for each variant.
Module suppliers also compete on the degree of application integration they provide. Designs that combine the Zigbee radio and programmable processing resources can reduce the number of chips needed for simple end nodes. Tuya’s Zigbee module portfolio, for example, provides documented UART interfaces and embedded firmware options that support standardized host integration. This shifts the OEM decision from component procurement toward selecting a repeatable software and hardware architecture across several device lines.
The commercial constraints are especially visible in devices that consumers expect to work for years without maintenance. A reduced module price is of little value if firmware incompatibility increases customer-support contacts or causes field failures after a gateway update. Security maintenance, over-the-air update reliability and compatibility testing therefore influence supplier qualification and long-term economics. Vendors with maintained software stacks and consistent certifications may sustain value even as radio hardware itself commoditizes.
Matter’s expansion introduces a more complex demand pattern. Some existing Zigbee products remain commercially attractive because established hubs, lighting systems and accessories depend on a mature installed base. New models may adopt Thread-based connectivity, while others implement both protocols through common multiprotocol silicon. Suppliers win by making these transitions straightforward, but the specific Zigbee revenue recorded in the module market depends on which protocol the product actually uses. Revenue growth cannot be inferred merely from the number of modules that list Zigbee among supported features.
This segment also carries a pronounced regional manufacturing effect. Many consumer connected-device makers procure radios through Asian electronics suppliers even when finished products are sold in North America and Europe. The geographic revenue model should therefore clearly describe whether it measures module consumption by OEM manufacturing location or final end-device demand. The present model allocates value by OEM integration or manufacturing demand and avoids treating the retailer’s location as the supplier’s module revenue destination.
Other Application Segments
Connected lighting accounts for US$49.29 million in 2026. Smart lighting provides a substantial Zigbee installed base, but direct radio integration and competing connectivity technologies constrain the proportion of finished-device revenue attributable to purchased modules. Modules serving commercial building automation reach a modeled US$75.10 million in 2032, reflecting access-control, building-control and monitoring requirements where certifications and maintenance continuity can justify a higher average module selling price.
Industrial and infrastructure applications generate a modeled US$47.40 million in 2026. These modules can command higher realized prices because temperature tolerance, antenna options, product-life support and commissioning reliability matter more than minimum upfront component cost. Smart metering and home-area-network applications are measured separately from general residential controls to prevent counting the same meter-linked module twice.
By Module Architecture
The market is segmented into dedicated Zigbee RF modules and multiprotocol Zigbee-capable modules deployed for Zigbee applications. Dedicated modules often suit stable, cost-sensitive products where firmware scope is limited. Multiprotocol modules are more important when device manufacturers must preserve options across Zigbee, Thread and Bluetooth LE, or support concurrent operation. Multi-protocol revenue is attributed to Zigbee only when Zigbee is the selected or concurrent deployed function, excluding otherwise identical modules used solely for Thread or Bluetooth.
Zigbee Module Market Geographical Outlook
Asia Pacific: Manufacturing concentration and value-chain competition
Asia Pacific contributes an estimated US$117.72 million in 2026. The region benefits from electronics contract-manufacturing capacity, proximity to component supply chains and the concentration of embedded-device production. Its importance should not be confused with the share of Zigbee end devices ultimately installed within the region. North America and Europe can purchase substantial quantities of completed Zigbee products assembled in Asian factories; those radio modules are attributed to the place where equipment manufacturers integrate them.
Asian module suppliers compete across tightly differentiated prices and production volumes. Standardized modules can be purchased by manufacturers that want rapid integration, while large production programs increasingly evaluate chip-level integration to remove module premiums. The result is growing physical demand for low-power wireless connectivity but more limited growth in module revenue per finished device. Producers with well-documented RF modules, consistent firmware and reliable component availability can defend business across multiple customer product cycles.
Europe generates approximately US$87.84 million in 2026, supported by building controls and smart energy applications where qualification and product longevity matter. North America accounts for about 23.0% of modeled 2026 revenue. Regional adoption depends on certification requirements, manufacturing locations, product mix and competition from alternative wireless architectures. These differences make a universal regional growth assumption unsuitable for this market.
Competitive Landscape
The competitive landscape combines specialist RF-module manufacturers, wireless-software platform providers and semiconductor companies. Digi International competes through XBee family modules with embedded configuration and security capabilities. Silicon Labs supplies multiprotocol certified modules and chipsets, with software support that shortens OEM integration. Tuya provides standardized Zigbee modules and device-development tools targeting connected-device makers, while EBYTE and other RF-module suppliers serve applications demanding serial interfaces, antenna options and industrial connectivity.
Chip suppliers including NXP Semiconductors, Texas Instruments, Telink Semiconductor and Microchip influence architecture selection through radio performance, reference designs and ecosystem support. However, chip revenue should not be automatically included in standalone module sales. Likewise, a vendor selling finished hubs or smart sensors is not necessarily a supplier of third-party embedded modules. Competitive ranking should therefore distinguish direct module revenue, chipset participation, licensing and downstream connected-product sales.
Recent Developments
October 14, 2026: Mouser announced availability of Silicon Labs’ BGM270S and MGM270S wireless SiP modules, including Zigbee Green Power support in MGM270S.
September 2, 2026: The Connectivity Standards Alliance opened Suzi product certification for sub-GHz Zigbee devices.
June 23, 2026: Signify and Silicon Labs announced concurrent Zigbee and Matter-over-Thread support for selected Philips Hue smart bulbs.
February 4, 2026: Silicon Labs introduced its xGM270S wireless SiP module family for compact low-power IoT equipment.
November 18, 2025: The Connectivity Standards Alliance released Zigbee 4.0 and the Suzi sub-GHz extension.
ZigBee Module Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 301.2 million |
| Total Market Size in 2032 | 398.3 million |
| Forecast Unit | Million |
| Growth Rate | 4.8% |
| Study Period | 2021 to 2032 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2032 |
| Segmentation | Application, Module Architecture, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Application
Connected Lighting
Residential Controls and Sensors
Smart Metering and Home-Area Networks
Commercial Building Automation
Industrial and Infrastructure Monitoring
Gateways and Coordinators
By Module Architecture
Dedicated Zigbee RF Modules
Multiprotocol Zigbee-Capable RF Modules
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Taiwan
Indonesia
Others
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Market Size and Forecast, 2026–2032
1.2. Key Commercial Findings
1.3. Supplier and OEM Implications
2. MARKET DEFINITION AND RESEARCH METHODOLOGY
2.1. Zigbee-Capable Embedded Module Definition
2.2. RF Module versus Bare IC and Finished Device
2.3. Module Revenue and Manufacturing-Location Attribution
2.4. Bottom-Up Volume × Module ASP Methodology
2.5. Research Assumptions, Validation and Limitations
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Opportunities and Technology Substitution
3.4. Porter's Five Forces Analysis
3.5. Value Chain and OEM Sourcing Economics
3.6. Certifications and Regulatory Requirements
4. TECHNOLOGY OUTLOOK
4.1. IEEE 802.15.4 and Zigbee Networking
4.2. Zigbee 3.0, Zigbee 4.0, and Smart Energy
4.3. Suzi Sub-GHz Extension
4.4. Dedicated and Multiprotocol Module Architectures
4.5. Matter, Thread, and Bluetooth Coexistence
4.6. Embedded Modules versus Direct-SoC Integration
5. ZIGBEE MODULE MARKET BY APPLICATION
5.1. Connected Lighting
5.2. Residential Controls and Sensors
5.3. Smart Metering and Home-Area Networks
5.4. Commercial Building Automation
5.5. Industrial and Infrastructure Monitoring
5.6. Gateways and Coordinators
6. ZIGBEE MODULE MARKET BY MODULE ARCHITECTURE
6.1. Dedicated Zigbee RF Modules
6.2. Multiprotocol Zigbee-Capable RF Modules
7. ZIGBEE MODULE MARKET BY GEOGRAPHY
7.1. North America
7.1.1. United States
7.1.2. Canada
7.1.3. Mexico
7.2. South America
7.2.1. Brazil
7.2.2. Argentina
7.2.3. Others
7.3. Europe
7.3.1. Germany
7.3.2. United Kingdom
7.3.3. France
7.3.4. Italy
7.3.5. Spain
7.3.6. Others
7.4. Middle East and Africa
7.4.1. Saudi Arabia
7.4.2. UAE
7.4.3. South Africa
7.4.4. Others
7.5. Asia Pacific
7.5.1. China
7.5.2. Japan
7.5.3. India
7.5.4. South Korea
7.5.5. Taiwan
7.5.6. Indonesia
7.5.7. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Direct RF Module Suppliers
8.2. Semiconductor and Wireless Stack Ecosystem
8.3. OEM Integration and Pricing Competition
8.4. Partnerships and Recent Developments
9. COMPANY PROFILES
9.1. Silicon Laboratories Inc.
9.2. Digi International Inc.
9.3. Tuya Inc.
9.4. EBYTE Electronic Technology Co., Ltd.
9.5. Microchip Technology Incorporated
9.6. Ezurio (formerly Laird Connectivity)
9.7. Telink Semiconductor Co., Ltd.
9.8. RF-star Technology Co., Ltd.
9.9. NXP Semiconductors N.V.
9.10. Texas Instruments Incorporated
9.11. Renesas Electronics Corporation
9.12. STMicroelectronics N.V.
10. APPENDIX
10.1. Currency and Forecast Period
10.2. Market Estimation Assumptions
10.3. Source Register and Evidence Hierarchy
10.4. Methodology and Definitions
10.5. Abbreviations





Frequently asked questions
What is the projected Zigbee module market size by 2032?
The ZigBee Module Market is projected to reach $398.3 million by 2032, growing at 4.8% CAGR.
What is the estimated Zigbee module market value in 2026?
The ZigBee Module Market is estimated at $301.2 million in 2026.
Which application segment leads Zigbee module revenue?
Residential controls and sensors account for 27.8% of 2026 revenue.
Which region dominates the Zigbee module market revenue?
Asia Pacific accounts for 39.1% of 2026 module revenue.
What are key growth drivers for Zigbee module demand?
Procurement shifts towards development risk, certification economics, and module attachment rate.
How is Zigbee's technology roadmap evolving?
Zigbee 4.0, Suzi sub-GHz, and multi-protocol Matter/Thread operation are expanding.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). ZigBee Module Market - Strategic Insights and Forecasts (2026-2032). https://www.knowledge-sourcing.com/report/zigbee-module-market