
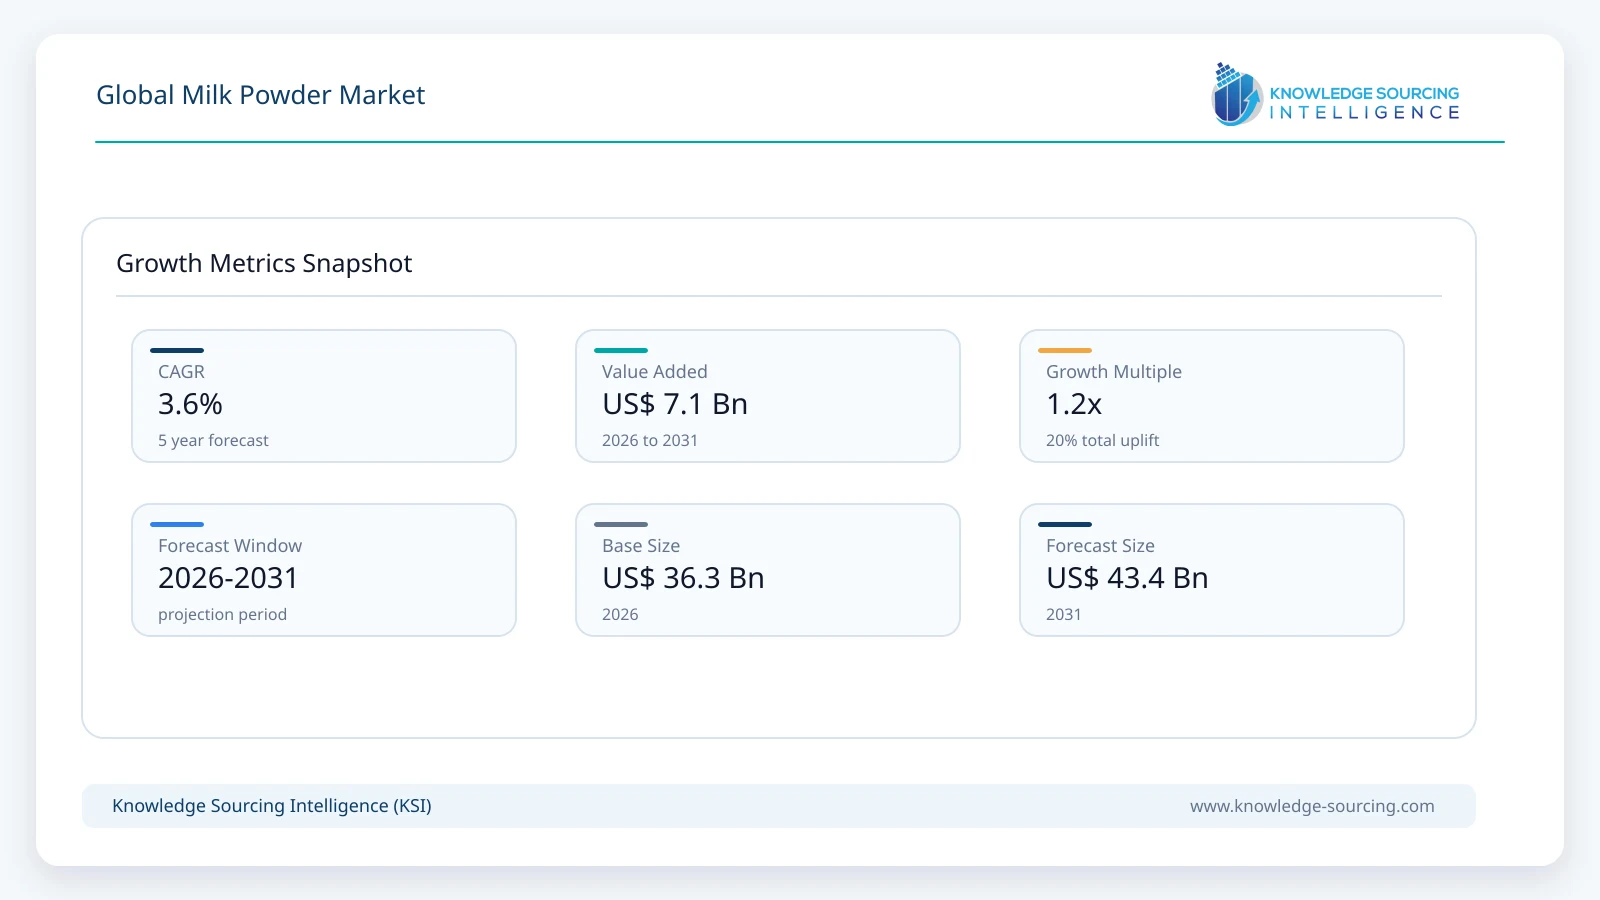
The global milk powder market is forecast to grow at a CAGR of 3.6%, reaching USD 43.4 billion in 2031 from USD 36.3 billion in 2026.
Highlights:
- 1Whole milk powder serves buyers seeking milk fat and solids, while skimmed milk powder supplies protein-rich dairy solids for food processing and industrial formulations.
- 2Commercial and industrial buyers value consistent composition, solubility, shelf life, reliable supply, and competitive ingredient costs when selecting milk powder suppliers.
- 3Asia Pacific combines large domestic dairy markets with import demand, while China remains an important destination for internationally traded whole milk powder.
- 4European dairy processors are investing in production efficiency, energy savings, and scale, creating opportunities for suppliers that meet strict quality and sustainability requirements.
- 5Regional and product-level market shares remain unconfirmed in the supplied inputs; the analysis therefore avoids assigning unsupported percentages to segments or geographies.
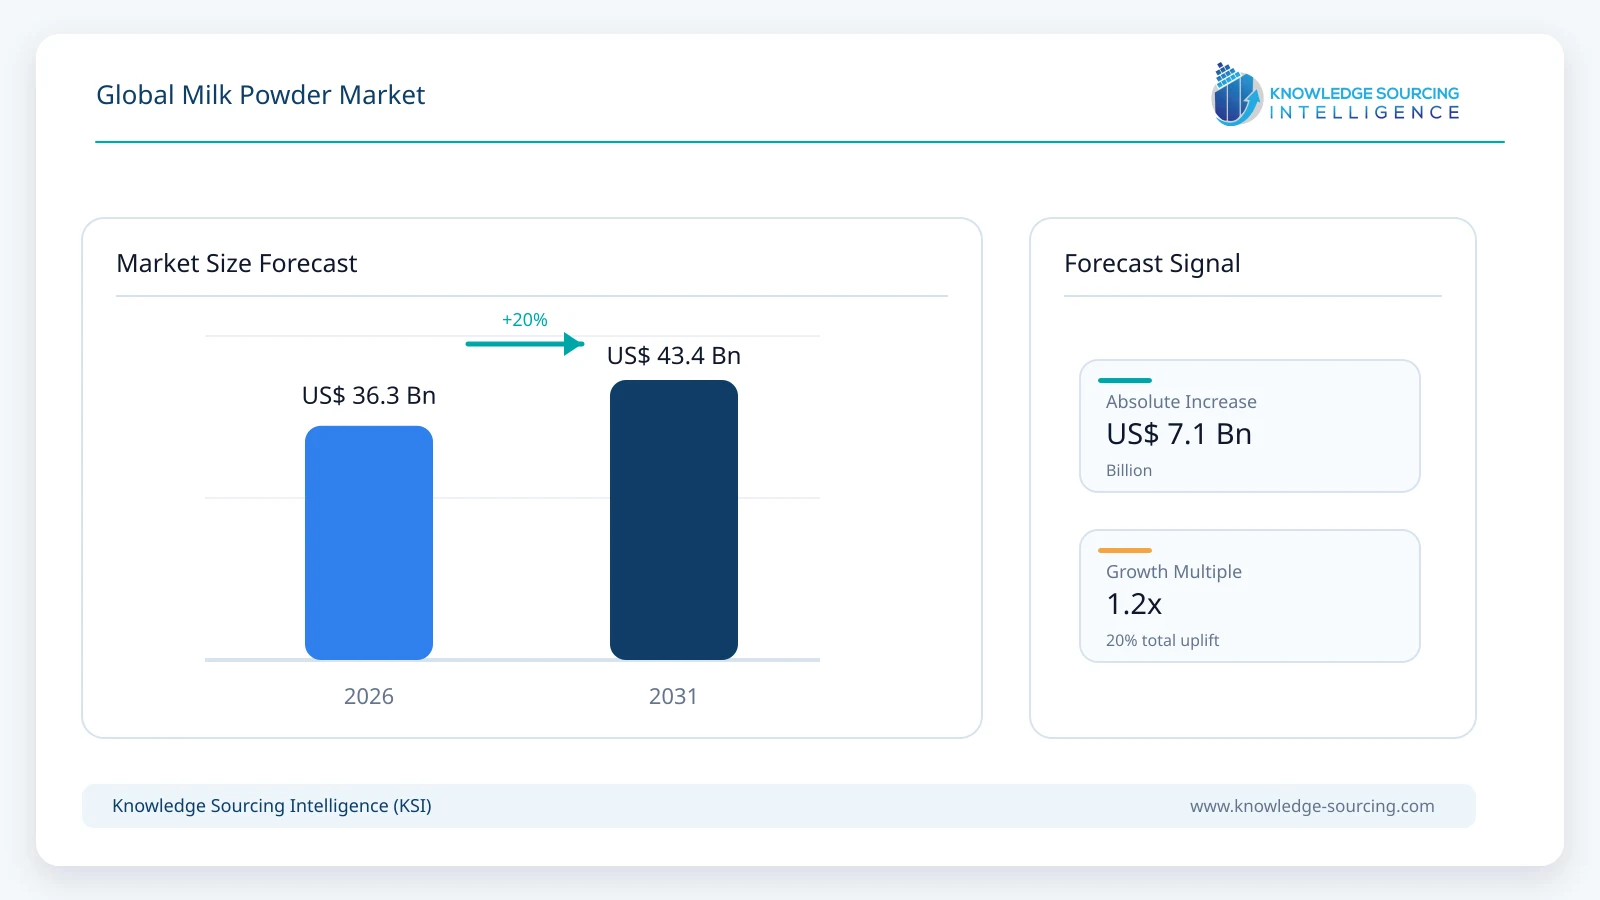
The global milk powder market serves households, food manufacturers, bakeries, confectionery producers, beverage companies, and food-service operators that need dairy ingredients with a longer shelf life and easier storage than liquid milk. Demand depends on milk availability, dairy processing capacity, food formulation needs, and the cost of transporting and storing fresh dairy products. From 2026 to 2031, market performance will depend on the balance between milk production, international trade, industrial ingredient demand, and consumer purchasing power.
Milk powder also gives dairy processors a way to preserve milk solids and manage seasonal differences between milk supply and demand. However, the economics vary by product type, fat content, application, and destination market. Manufacturers must manage raw milk prices, energy-intensive drying processes, food safety rules, and changing import requirements. Buyers, in turn, assess product composition, price stability, supplier reliability, traceability, and consistency across production batches.
The dairy market is shaped by production efficiency, customer retention, and product mix rather than volume expansion alone. Suppliers serving industrial customers with consistent product specifications and reliable delivery can strengthen their competitive position beyond spot pricing for dairy commodities. Operational improvements, dependable supply chains, and long-term customer relationships remain important for maintaining market stability and meeting diverse buyer requirements. Companies that align product quality with changing industrial demand can improve customer loyalty, support operational consistency, and reinforce their position across the dairy value chain.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
|---|---|---|
Arla milk intake | 14.3 billion kg in 2025 | Large milk pools support the supply of dairy ingredients and improve processing flexibility. |
China whole milk powder imports | 425,000 metric tonnes in 2025 | Import demand creates opportunities for exporters, although purchasing volumes remain sensitive to local production and inventories. |
Arla milk powder site emissions reduction | More than 1,500 tonnes of CO? annually | Energy-saving technology can reduce the environmental burden of spray drying. |
Arla and DMK combined milk pool | 19.4 billion kg annually | Cooperative scale can strengthen sourcing, production planning, and supply reliability across European dairy markets. |
Fonterra South Island investment commitment | NZD 1 billion over three years | Investment in protein manufacturing may shift some milk away from commodity powders toward higher-value dairy ingredients. |
Market Drivers
Demand from food manufacturers for stable dairy ingredients
Milk powder helps food manufacturers maintain consistent formulations without relying entirely on daily deliveries of fresh milk. Bakery mixes, confectionery, chocolate, instant beverages, soups, sauces, and prepared foods use milk solids to control taste, texture, colour, and nutritional content. Powder also reduces the need for refrigerated storage before use, which can simplify distribution to factories and markets with limited cold-chain capacity.
The commercial value depends on the formulation. Whole milk powder supplies both milk fat and non-fat solids, while skimmed milk powder provides dairy proteins and lactose with little residual fat. Buyers often specify protein content, moisture, microbiological quality, heat classification, and solubility. Suppliers that meet these requirements consistently can secure repeat business, while manufacturers that rely mainly on commodity pricing remain exposed to changes in international dairy prices.
Growth in international dairy trade and supply balancing
Dairy production and consumption do not always occur in the same countries or seasons. Milk powder lets exporters convert surplus milk into a product that can be stored and shipped over longer distances. The Food and Agriculture Organization's review of 2024 dairy markets reported increased milk production, supported by output growth in Asia, Oceania, and parts of Europe.
International trade provides buyers with an alternative when local milk supply is insufficient or when domestic processors cannot produce the required grade. However, importers must weigh product prices against freight, tariffs, currency movements, customs procedures, and inventory costs. Exporters also face differences in demand for whole and skimmed milk powder. Changes in Chinese buying patterns, for example, can affect suppliers that direct a large share of their output toward that market.
Expansion of value-added dairy and protein applications
Dairy processors are seeking better returns from milk by supplying ingredients with defined functional or nutritional properties. Some applications require standard milk powder, while others use more specialised dairy ingredients with tighter specifications. Fonterra's September 2026 results identified global protein demand and product mix as factors supporting its ingredients business. The company also announced further investment in South Island protein manufacturing, with the aim of moving more milk away from whole milk powder and commodity products.
This shift creates a two-part competitive environment. Commodity powder suppliers must control processing costs and maintain reliable volumes. Higher-value ingredient suppliers must also meet customer requirements for composition, functionality, traceability, and application support. Investment in specialised products can improve returns, but it requires suitable equipment, technical expertise, customer qualification, and a reliable supply of milk with the required properties.
Growth in convenience-oriented food production and retail availability
Milk powder suits consumers and food businesses that need dairy products with flexible storage and preparation. Households may use it where fresh milk is costly, less accessible, or purchased less frequently. Food-service businesses and small manufacturers can also use powder to manage inventory and reduce losses associated with chilled products. Demand varies by income, local dairy habits, product availability, and the relative price of powder compared with liquid milk.
Retail channels influence how products reach these buyers. Supermarkets and convenience stores support packaged household sales, while online platforms provide access to specialised brands and larger pack sizes. Industrial buyers usually purchase through direct contracts, ingredient distributors, or business-to-business channels. Suppliers need to match pack sizes, product grades, delivery schedules, and pricing structures to each channel rather than apply one distribution model across all customer groups.
Market Restraints and Challenges
Volatile raw milk and dairy commodity prices
Milk powder production costs depend heavily on raw milk prices, milk composition, energy, labour, packaging, and plant utilisation. Seasonal supply changes can alter the volume of milk available for drying. When milk production rises faster than demand, processors may face lower powder prices and weaker returns. When supply tightens, higher input costs can squeeze margins if customer contracts prevent prompt price adjustments.
The effect differs across the value chain. Cooperatives and integrated processors may have more control over milk sourcing, but they remain exposed to feed costs, weather, farm productivity, and the cost of collecting milk. Independent manufacturers and distributors may have less room to absorb price swings. Buyers can limit exposure through fixed-price contracts, diversified sourcing, and inventory planning, although these measures may carry additional costs or reduce flexibility.
Energy use and the cost of spray drying
Removing water from milk requires energy-intensive processing. Spray drying, the process of turning concentrated liquid milk into powder, uses controlled heat and airflow to achieve the required moisture level and product quality. Energy prices therefore affect production costs, while equipment performance and plant utilisation influence the cost per unit of output. Manufacturers operating older plants may face a greater burden when energy costs rise or emissions rules tighten.
Arla Foods reported in October 2025 that a high-temperature electric heat pump at its AKAFA milk powder site in Denmark reduced annual emissions by more than 1,500 tonnes of CO?. The system was designed to meet the high-temperature needs of spray drying.
This demonstrates a practical route to lower process emissions, but the investment also requires suitable equipment, technical integration, and capital. Smaller processors may find it harder to fund comparable upgrades.
Trade barriers and changing import requirements
Milk powder exporters must comply with food safety rules, product labelling, customs procedures, and country-specific import conditions. Tariffs and trade restrictions can change the delivered cost of imported powder and alter the relative position of domestic processors. Importers also need to verify that products meet the rules of the destination market, including requirements for dairy origin, permitted ingredients, contaminants, and microbiological safety.
These conditions make market access a commercial issue as well as a regulatory one. Exporters with established certification systems and local distribution partners may be better placed to serve several markets. Suppliers that depend on one destination face greater exposure to policy changes or sudden shifts in import demand. Buyers can reduce risk by qualifying alternative suppliers, but switching requires checks on product performance, documentation, and production consistency.
Competition from fresh milk and alternative ingredients
Milk powder competes with liquid milk, concentrated dairy products, plant-based ingredients, and other protein sources, depending on the application. Powder offers storage and transport advantages, but it may not match the taste, texture, processing behaviour, or consumer expectations of every fresh dairy product. Manufacturers must also account for reconstitution costs, water quality, mixing equipment, and the labour needed to prepare the ingredient for use.
Price differences can alter purchasing decisions quickly, particularly for food manufacturers with narrow margins. When fresh milk is readily available at competitive prices, some buyers may prefer local liquid supply. Conversely, buyers with long distribution routes or limited refrigeration may place greater value on powder. Suppliers need to compete on delivered cost and application performance, not simply on the price per tonne.
Major Segment Analysis
Whole Milk Powder
Whole milk powder is commercially important because it retains both milk fat and non-fat milk solids. It is used in confectionery, bakery products, dairy beverages, ice cream, chocolate, and other processed foods where manufacturers need dairy flavour, body, and consistent solids content. Its value to buyers depends on fat content, moisture, microbiological quality, heat treatment, and performance in the final formulation. Storage stability and lower transport weight can also make it practical for export markets and food businesses with limited chilled storage.
Industrial buyers tend to evaluate whole milk powder through technical specifications and total delivered cost. Chocolate and confectionery manufacturers may require precise fat levels and consistent flavour, while beverage producers place greater emphasis on dispersibility and solubility. Product qualification can take time because a change in milk powder may affect the finished product's texture, processing behaviour, or shelf life. Suppliers that maintain stable quality and dependable delivery can build longer customer relationships, but they must still compete with other dairy ingredients and locally available milk.
International trade remains an important influence on the segment. USDA Foreign Agricultural Service data lists China as the largest destination among the countries shown for whole milk powder imports, with imports of 425,000 metric tonnes in 2025.
Import demand can change with domestic milk output, consumer demand, inventory levels, and purchasing policies. Exporters therefore need to balance long-term customer contracts with the risk of relying too heavily on one destination. Whole milk powder's performance also depends on milk-fat prices, which can influence the returns available from alternative dairy products.
Regional Analysis
North America
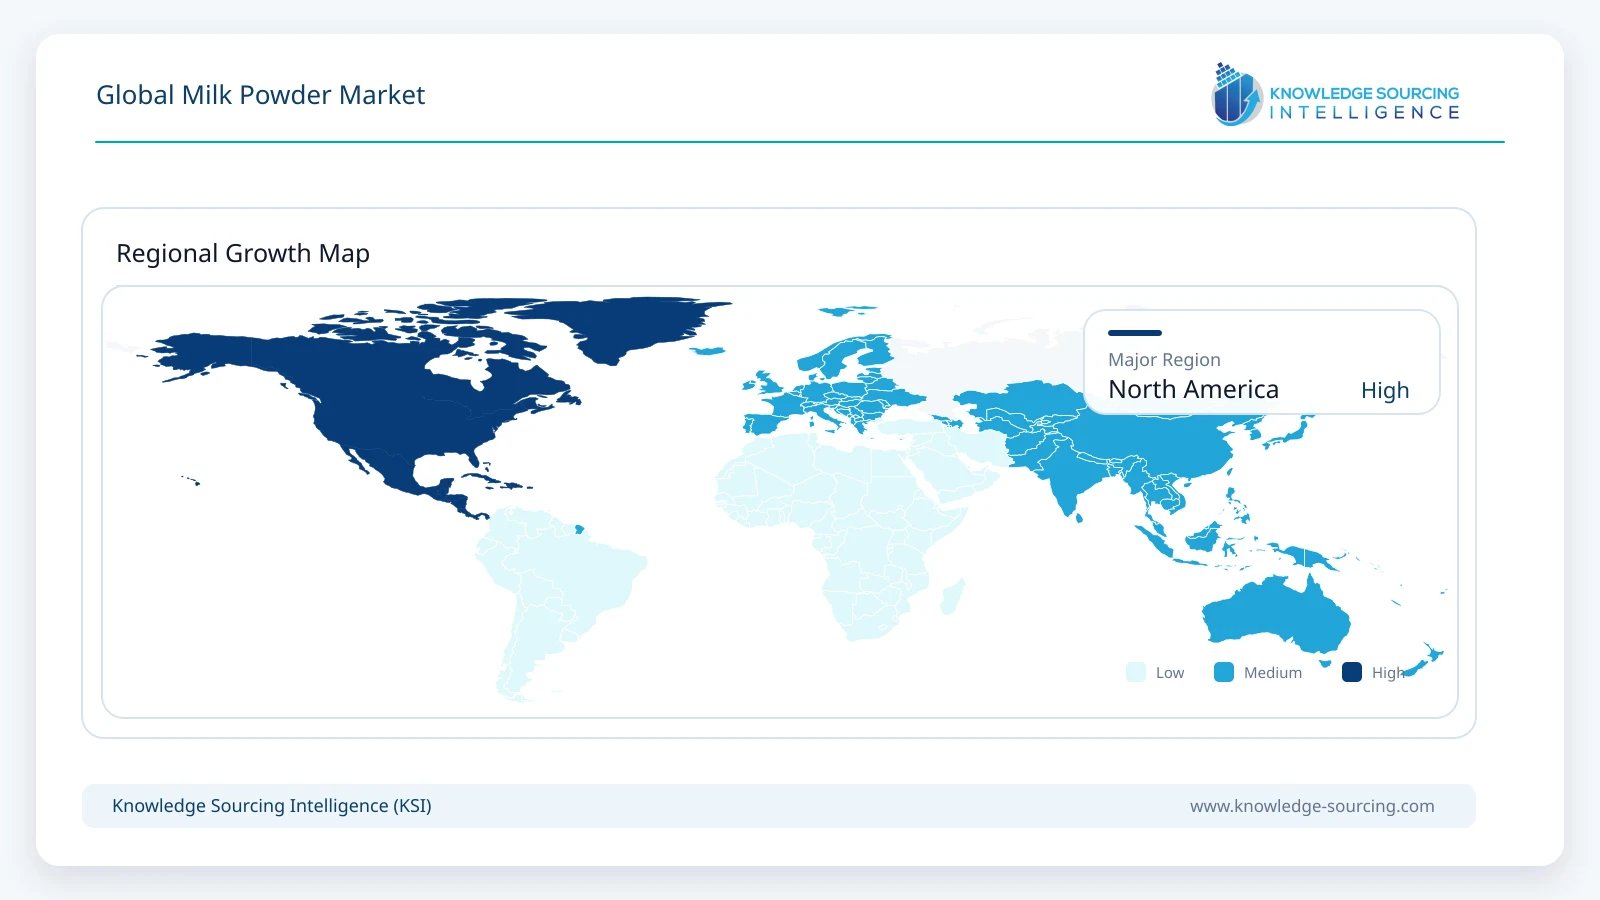
North American demand reflects a large food-processing base, established dairy supply chains, and the use of milk powder in bakery products, confectionery, beverages, and prepared foods. The United States combines domestic milk production with international dairy trade, while Canada and Mexico have their own production, import, and food-processing requirements. Buyers assess powder against the cost of locally sourced dairy ingredients, transport, and the technical needs of each application.
The United States is also an important participant in international dairy trade. The USDA Economic Research Service reported that U.S. dairy exports in 2025 declined on a skim-solids milk-equivalent basis compared with 2024, while exports increased on a milk-fat basis. Imports showed the reverse pattern across those two measures.
These differences illustrate why aggregate dairy trade figures should not be treated as a direct measure of milk powder demand. Product composition and the mix of dairy categories affect trade performance.
Europe
Europe has an established dairy processing and export base, with cooperative and privately owned processors supplying retail, food-service, and industrial customers. Milk powder forms part of a wider portfolio that includes cheese, butter, whey, and specialised dairy ingredients. Processors can direct milk toward different products according to market prices, customer demand, plant capacity, and the returns available from each use.
Scale and energy efficiency influence the region's competitive position. Arla's 2025 investment programme included capacity projects across its markets, while its milk powder site in Denmark adopted high-temperature heat pump technology to cut emissions from spray drying.
European suppliers must also meet applicable food safety, labelling, environmental, and traceability rules. These requirements add operating obligations, but they can help buyers assess quality and supply-chain controls when selecting suppliers.
Asia Pacific
Asia Pacific combines large domestic dairy markets, food-processing demand, and import requirements that vary by country. China is important to international whole milk powder trade, while India has a large domestic milk production base. Japan, South Korea, Indonesia, and Thailand have different balances of local dairy production, imported ingredients, food manufacturing, and consumer demand. These differences make a uniform regional sales strategy less effective than country-specific sourcing and distribution plans.
India illustrates how local milk supply can shape the role of imported powder. A USDA Foreign Agricultural Service report published in 2025 forecast India's skimmed milk powder production at 0.79 million metric tonnes for calendar year 2026, compared with 0.77 million metric tonnes in 2025. It also described India's dairy sector as largely self-sufficient in fluid milk, with domestic supply limiting the need for imports in several product categories.
Such conditions can support domestic processors while restricting the market for imported standard milk powder. Specialised dairy ingredients may face different supply conditions.
South America
South America combines domestic dairy consumption with cross-border trade, particularly among producers and buyers in the Southern Cone. Brazil is a key market because of its large food industry and consumer base. Argentina also has a developed dairy sector, while other markets depend on their own production capacity, import costs, and distribution networks. Whole milk powder demand can reflect local milk availability, food manufacturing needs, and the relative cost of imported ingredients.
Price competition and currency changes can influence purchasing decisions. Importers must assess foreign exchange exposure, freight, customs requirements, and local supply before committing to large orders. Domestic processors may have an advantage when they can source milk locally and deliver quickly. Export-oriented suppliers, by contrast, need to match product specifications and maintain dependable delivery to win industrial contracts.
Middle East and Africa
Milk powder serves markets where local dairy production, climate, water availability, and cold-chain infrastructure differ widely. In parts of the Middle East, importers use powder for food processing and distribution where local milk supply does not meet all needs. Saudi Arabia, the United Arab Emirates, and Israel have distinct production systems and regulatory requirements, while several African markets rely on imported dairy products to supplement local supply.
Import dependence exposes buyers to freight costs, currency movements, and changes in international commodity prices. Product registration, food safety controls, and labelling rules also shape market access. Suppliers that maintain local distributor relationships and provide clear product documentation may find it easier to serve multiple customers. However, purchasing power, storage conditions, and the cost of imported goods can restrict demand in price-sensitive markets.
Competitive Landscape
The milk powder market includes dairy cooperatives, multinational food companies, specialised ingredient suppliers, and regional processors. Competition depends on access to raw milk, processing scale, product quality, production efficiency, and established customer relationships. The market is not defined by one uniform product: suppliers compete across commodity powders, branded household products, and ingredients designed for industrial use.
Fonterra Co-operative Group Limited and Royal FrieslandCampina N.V. have business models that connect farmer milk supply with processing and international sales. Arla Foods amba, following its 2026 merger with DMK Group, has expanded its cooperative scale and combined milk pool.
Nestlé S.A. competes across consumer foods and dairy-based products, while Gujarat Cooperative Milk Marketing Federation Ltd. (Amul) has a strong domestic distribution model in India. These differences affect how companies source milk, allocate production, and reach customers.
Other companies in the report's scope include Dairy Farmers of America, Inc., Darigold, Inc., Lactalis Group, Saputo Inc., and Glanbia plc. Their commercial positions depend on their product portfolios, access to milk, customer mix, manufacturing assets, and geographic reach. Company size alone does not determine competitiveness in every powder category. Industrial customers may prefer a specialist supplier with the right functional grade, while retail buyers may value brand recognition, pack sizes, and distribution availability.
Suppliers also face a choice between competing on commodity cost and investing in products with higher functional value. Commodity suppliers need efficient plants, reliable milk sourcing, and strong logistics. Specialised ingredient suppliers need technical sales teams, product testing, and close links with food manufacturers. Across both models, energy efficiency and consistent product quality influence margins. The ability to meet destination-market rules also affects which customers a supplier can serve.
Recent Developments
September 2026: Fonterra announced an additional NZD 1 billion investment in South Island protein manufacturing over three years. The company said the investment would expand its protein network and help shift more milk from whole milk powder and commodity products toward higher-value ingredients.
June 2026: Darigold announced a strategic partnership with Actus Nutrition to transfer operation of its Jerome, Idaho, milk protein plant and supply high-value whey products from Sunnyside, Washington, under a long-term commercial agreement.
May 2026: Arla Foods and DMK Group received regulatory approval for their merger. The combined cooperative reported an annual milk pool of 19.4 billion kg and planned to integrate their operations from June 2026. Greater scale may strengthen sourcing, production planning, and customer coverage across European dairy markets.
April 2026: Royal FrieslandCampina published its 2025 Nutrition Impact Report, outlining progress in dairy product nutrition, affordable dairy access, responsible communication, and its roadmap toward 2030.
March 2026: FrieslandCampina Ingredients completed its Borculo production expansion, doubling capacity for whey protein isolate and milk fat globule membrane used in specialised nutrition and dairy ingredient applications.
Regulatory and Policy Environment
Food safety, composition, and labelling
Milk powder manufacturers must comply with food safety rules in the countries where they produce and sell products. Requirements may cover permitted ingredients, moisture levels, microbiological limits, contaminants, packaging, traceability, and storage conditions. Product labels must accurately describe the contents and provide information required by the destination market. Infant and specialised nutritional products may face additional rules that do not apply to standard milk powder.
The Codex Alimentarius Commission provides international food standards and guidance, including standards for milk powders and cream powder. These standards support common expectations for product identity, composition, and quality in international trade. National regulators apply their own legal requirements, which may differ from Codex provisions. Exporters must confirm the rules for each destination rather than assume that compliance in one market ensures access to another.
International trade and import controls
Tariffs, customs procedures, sanitary requirements, and trade agreements affect the cost of imported milk powder. Governments may use import controls to protect domestic dairy producers or manage food supply conditions. Such policies can change the relative cost of imported and locally produced ingredients, affecting both manufacturers and distributors.
Exporters need to monitor changes in customs classification, tariff rates, and required documentation. Importers must verify product origin, health certification, and applicable food safety conditions before shipment. Long-term supply contracts can reduce uncertainty, but they cannot remove all exposure to policy changes. A supplier's ability to redirect product to alternative markets depends on whether its products meet those markets' standards and whether the delivered price remains competitive.
Environmental policy and energy use
Environmental rules are becoming more relevant to dairy processing because milk concentration and spray drying consume energy. Requirements for industrial emissions, energy use, wastewater treatment, and climate reporting can influence plant operating costs and investment choices. The exact obligations depend on the location, plant size, fuel source, and applicable regulatory framework.
Arla's investment in high-temperature heat pump technology illustrates how processors can respond through process changes rather than relying only on purchased energy or emissions offsets.
Similar investments require an assessment of energy prices, equipment performance, plant layout, and the cost of financing. Larger processors may be better able to spread these costs across multiple facilities, while smaller plants may need to prioritise upgrades with shorter payback periods.
Outlook and Strategic Implications
The milk powder market is forecast to expand at a measured pace through 2031. Demand will depend on industrial food production, household purchasing, international dairy trade, and the balance between local milk supply and imported ingredients. The supplied forecast implies continued market expansion, but it does not remove the risk of price cycles. Milk output, energy costs, trade policy, and customer inventories can still alter revenue and margins over shorter periods.
Suppliers will need to align capacity and product mix with the needs of their target customers. Commodity manufacturers should focus on plant utilisation, energy efficiency, milk sourcing, and logistics. Suppliers of specialised dairy ingredients should prioritise product consistency, technical support, and customer qualification. Distributors can reduce exposure by diversifying sources and monitoring demand across product grades and destination markets.
The most relevant strategic priorities are:
For manufacturers: Improve drying efficiency, manage raw milk exposure, and match production plans to customer orders and seasonal supply.
For industrial buyers: Qualify alternative suppliers, specify clear quality standards, and compare total delivered cost rather than purchase price alone.
For exporters and distributors: Monitor tariffs, destination-market rules, freight costs, and changes in major import markets.
For investors: Assess access to milk supply, plant utilisation, energy costs, product mix, and the ability to serve higher-value applications.
For regulators and policymakers: Maintain clear food safety rules while supporting reliable dairy supply, efficient processing, and responsible resource use.
Over the forecast period, commercial performance will depend less on volume alone than on how well suppliers manage input costs, match product specifications to buyer needs, and maintain access to target markets. Companies that combine reliable milk sourcing with efficient processing and disciplined customer selection should be better placed to manage commodity cycles and protect returns.
Milk Powder Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 36.3 billion |
| Total Market Size in 2031 | USD 43.4 billion |
| Forecast Unit | Billion |
| Growth Rate | 3.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, End-user, Distribution Channel, Geography |
| Companies |
|
Market Segmentation
By Type
Whole Milk Powder
Skimmed Milk Powder/Non-Fat Dry Milk
Buttermilk Powder
Dairy Whitener
Fat-Filled Milk Powder
Other Types
By End-user
Household
Commercial
Industrial
By Distribution Channel
Online
Supermarkets/Hypermarkets
Convenience Stores
Other Distribution Channels
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Spain
Others
Middle East & Africa
Saudi Arabia
United Arab Emirates
Israel
Others
Asia Pacific
China
Japan
India
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Market Trends
3.5. Porter’s Five Forces Analysis
3.6. Industry Value Chain Analysis
3.7. Policies and Regulations
3.8. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Milk Powder Processing Technologies
4.2. Spray Drying and Evaporation Technologies
4.3. Instantization and Agglomeration Technologies
4.4. Quality Control and Food Safety Technologies
5. GLOBAL MILK POWDER MARKET BY TYPE
5.1. Introduction
5.2. Whole Milk Powder
5.3. Skimmed Milk Powder/Non-Fat Dry Milk
5.4. Buttermilk Powder
5.5. Dairy Whitener
5.6. Fat-Filled Milk Powder
5.7. Other Types
6. GLOBAL MILK POWDER MARKET BY END-USER
6.1. Introduction
6.2. Household
6.3. Commercial
6.4. Industrial
7. GLOBAL MILK POWDER MARKET BY DISTRIBUTION CHANNEL
7.1. Introduction
7.2. Online
7.3. Supermarkets/Hypermarkets
7.4. Convenience Stores
7.5. Other Distribution Channels
8. GLOBAL MILK POWDER MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. By Type
8.2.2. By End-User
8.2.3. By Distribution Channel
8.2.4. By Country
8.2.4.1. United States
8.2.4.2. Canada
8.2.4.3. Mexico
8.3. South America
8.3.1. By Type
8.3.2. By End-User
8.3.3. By Distribution Channel
8.3.4. By Country
8.3.4.1. Brazil
8.3.4.2. Argentina
8.3.4.3. Others
8.4. Europe
8.4.1. By Type
8.4.2. By End-User
8.4.3. By Distribution Channel
8.4.4. By Country
8.4.4.1. United Kingdom
8.4.4.2. Germany
8.4.4.3. France
8.4.4.4. Spain
8.4.4.5. Others
8.5. Middle East & Africa
8.5.1. By Type
8.5.2. By End-User
8.5.3. By Distribution Channel
8.5.4. By Country
8.5.4.1. Saudi Arabia
8.5.4.2. United Arab Emirates
8.5.4.3. Israel
8.5.4.4. Others
8.6. Asia Pacific
8.6.1. By Type
8.6.2. By End-User
8.6.3. By Distribution Channel
8.6.4. By Country
8.6.4.1. China
8.6.4.2. Japan
8.6.4.3. India
8.6.4.4. South Korea
8.6.4.5. Indonesia
8.6.4.6. Thailand
8.6.4.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Benchmarking
9.5. Competitive Dashboard
9.6. SWOT Analysis of Major Companies
10. COMPANY PROFILES
10.1. Arla Foods amba
10.2. Dairy Farmers of America, Inc.
10.3. Fonterra Co-operative Group Limited
10.4. Darigold, Inc.
10.5. Lactalis Group
10.6. Nestlé S.A.
10.7. Royal FrieslandCampina N.V.
10.8. Gujarat Cooperative Milk Marketing Federation Ltd. (Amul)
10.9. Saputo Inc.
10.10. Glanbia plc
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
12. LIST OF TABLES
13. LIST OF FIGURES
Navigate
Trusted by the world's leading organizations











