
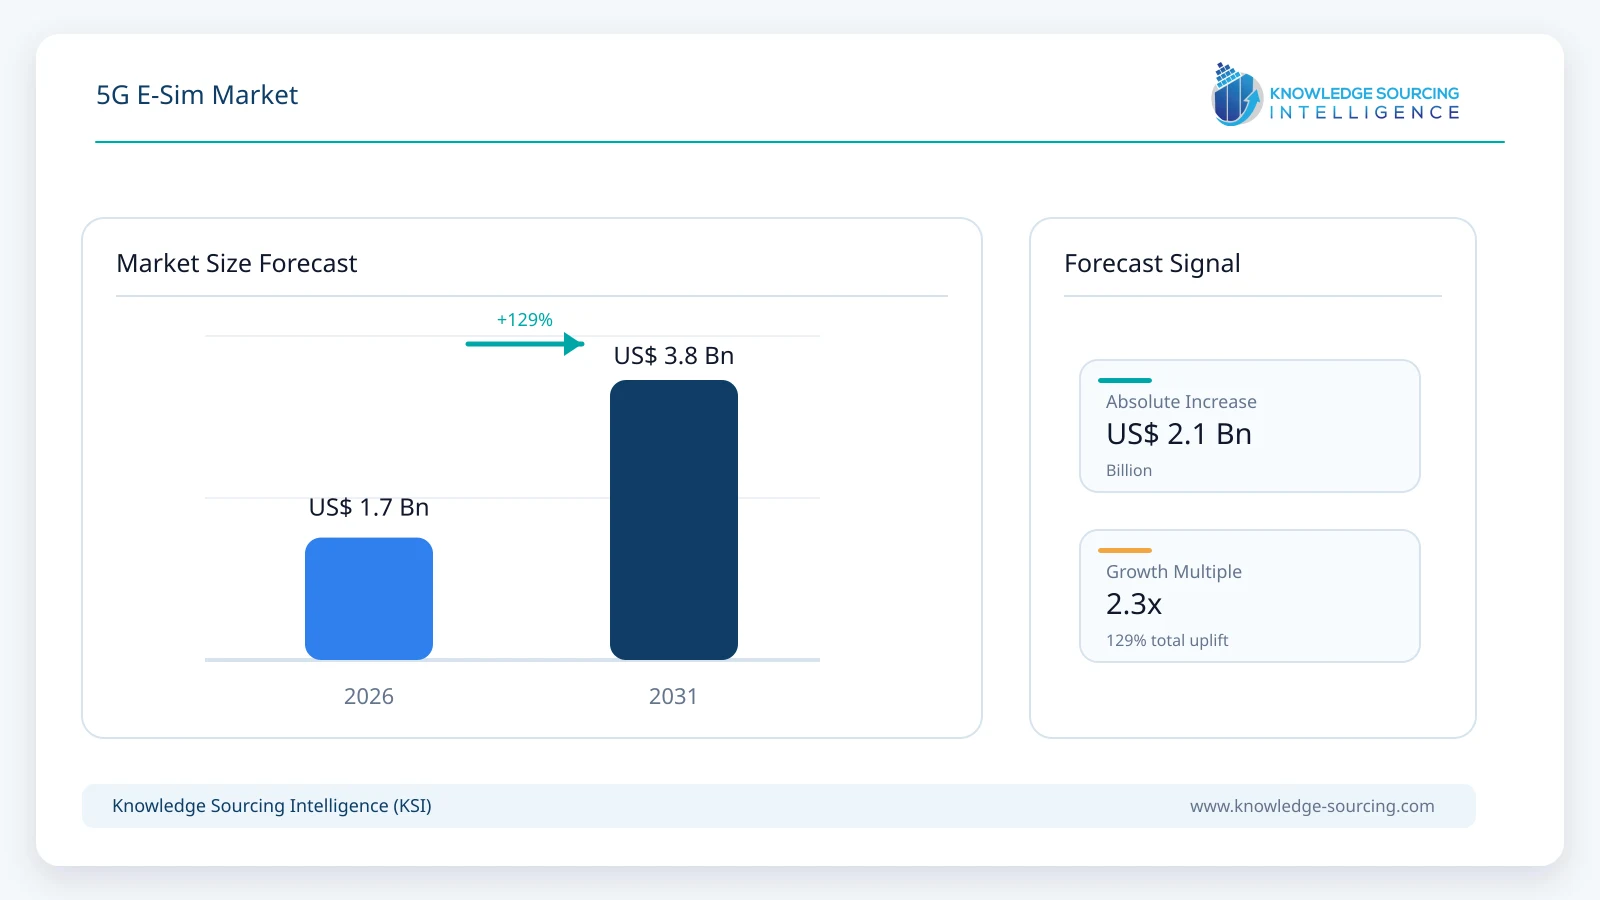
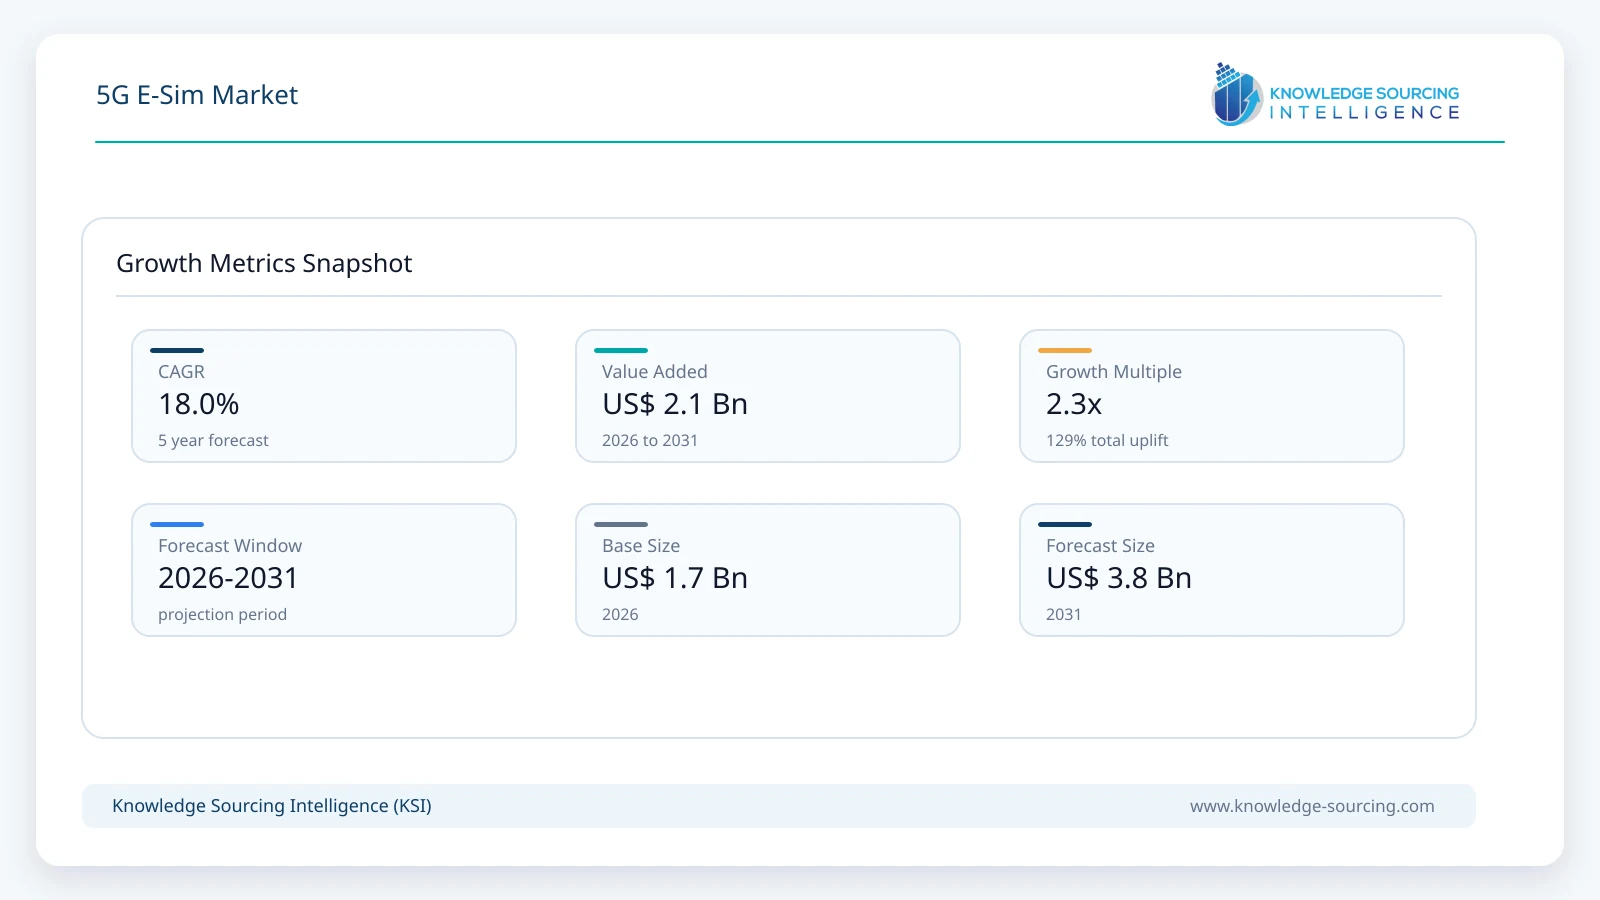
The global 5G E-SIM Market is expected to grow at a CAGR of approximately 18.0%, reaching USD 3.82 billion in 2031 from USD 1.67 billion in 2026 over the forecast period.
Highlights:
- 1Trusted Connectivity Alliance reported a 43% increase in consumer profile downloads during 2025 and noted further acceleration during the first half of 2026, underscoring the importance of dependable digital activation.
- 2Connectivity services account for approximately 63% of market revenue in 2026 as remote activation and digital service delivery expand alongside hardware sales.
- 3Consumer electronics represents approximately 69% of 2026 market revenue, led by smartphones and cellular wearables.
- 4Machine-to-machine applications increase their share toward 2031, supported by connected vehicles, utility assets and remotely managed industrial devices.
- 5The Americas has an established base of commercially active eSIM-enabled 5G devices, while Asia Pacific is positioned for faster growth as Chinese consumer activation and connected-device deployment expand.
- 6The shift to GSMA SGP.32 changes how vehicle and IoT fleets can manage operator profiles after installation, increasing demand for interoperable provisioning services.
Market Overview
Embedded SIM adoption is being shaped by handset design decisions as much as by network rollout. Apple extended its eSIM-only iPhone 17 configurations beyond the United States to multiple other markets in 2025, while operator support and digital onboarding determine whether those devices activate smoothly. eSIM reduces the need for a removable SIM tray and enables remote activation, although actual 5G data speed remains a function of the modem, radio spectrum, and network rather than of the eSIM itself.
Trusted Connectivity Alliance estimated 605 million eSIM shipments worldwide in 2025, an 18% annual increase, and recorded 43% growth in consumer profile downloads. Its October 2026 mid-year update then reported that consumer profile downloads in just the first half of 2026 nearly matched the entire 2025 volume, helped by a strong acceleration in China. These observations indicate growth in the wider secure-identity and provisioning ecosystem, although individual shipments and activations can be associated with non-5G devices. Ericsson separately recorded 3.1 billion global 5G subscriptions in the first quarter of 2026 and forecasts 6.4 billion by 2031, indicating the scale of the broader compatible-device opportunity.
Supplier offerings cover different stages of the activation stack. Infineon's OPTIGA Connect and STMicroelectronics' ST4SIM devices provide secure hardware, while Giesecke+Devrient, Thales, Kigen and Valid focus on varying combinations of eUICC technology, provisioning platforms and managed services. Telecom operators and digital distributors compete on the ease of activation, network availability and customer support required to turn those technical capabilities into recurring commercial use.
Market Trends
eSIM-Only Handsets Are Broadening Beyond the First Wave of Markets
Smartphone manufacturers are increasingly treating remote SIM activation as a normal device capability rather than an optional feature for premium models. Apple's 2025 iPhone 17 launch specified eSIM-only configurations in markets including Japan, Canada and selected Middle Eastern countries, expanding operator onboarding requirements across substantially different retail ecosystems. Wider deployment rewards providers able to manage activation reliably at device setup and when customers change carriers.
Growth in the active eSIM installed base is also changing operator economics. Remote activation can reduce card production, shipping and retail handling, but an unsuccessful profile download or identity check may transfer cost into customer service and fraud prevention. In the first half of 2026, Trusted Connectivity Alliance reported consumer profile downloads nearly matching the total for all of 2025; this places more commercial weight on activation completion, supported-device testing and recovery paths. Operators therefore need resilient self-service provisioning and reliable account verification before reducing physical distribution options.
SGP.32 Is Moving IoT Profile Management Toward Fleet Operations
Vehicle manufacturers and industrial device operators need connectivity credentials that remain manageable when equipment is inaccessible. The GSMA SGP.32 IoT architecture introduces remotely coordinated profile management suited to constrained devices, creating an alternative to older M2M provisioning arrangements. Giesecke+Devrient's announced Rivian R2 program combines automotive-grade eSIM hardware with its eSIM IoT Remote Manager and an initial U.S. network relationship with AT&T.
Connected-device manufacturers gain flexibility when they can configure one product for multiple markets and alter an operator relationship after installation. These benefits require more than a secure eUICC: device software, eSIM IoT Remote Managers, provisioning servers and network operators must interoperate. Trusted Connectivity Alliance reported a fivefold increase in SGP.32-compatible subscription-manager platforms in the first half of 2026 compared with full-year 2025, pointing to an expanding deployment ecosystem. Kigen's 2026 starter kit illustrates why qualification and multi-operator profile testing remain necessary before manufacturers move from evaluation to scaled fleet management.
Secure-Element Design Is Moving Toward Smaller, Integrated Packages
Hardware vendors are reducing the footprint and power requirements of secure eSIM components while expanding standards support. Infineon's OPTIGA Connect family addresses consumer and IoT devices, and STMicroelectronics lists its ST4SIM-300M IoT product in volume production with SGP.32 v1.2 compliance. Integration enables eSIM functionality in wearables, metering modules and telematics units where additional board area or service access is costly.
Smaller components do not eliminate qualification needs. OEMs still require certified security implementations, reliable storage of operator credentials and manufacturing processes that preserve identity integrity. Silicon suppliers differentiate through package size, security assurance, supported provisioning standards, and the operational simplicity of deploying the component within established device platforms.
Digital Connectivity Distribution Is Becoming More Modular
Consumer eSIM services are increasingly distributed through operator apps, device onboarding interfaces and specialized travel connectivity platforms. Remote profile delivery is the identity-management mechanism, while the retail carrier or reseller remains responsible for network access, permitted roaming and customer care. GSMA Intelligence estimated that only 5% of smartphone connections used eSIM at the end of 2025, leaving substantial room for future digital onboarding despite widespread device capability. The customer proposition therefore depends on supported carrier profiles, transparent service terms and reliable activation rather than on an assumed radio-performance benefit from the SIM technology itself.
For suppliers, this model favors reusable provisioning interfaces and agreements that permit profiles to be delivered across different storefronts. Margins can be pressured by multiple intermediaries, while support and refund disputes remain important operating expenses. The market therefore rewards distribution efficiency and provisioning reliability rather than treating every mobile-data transaction as a separate technology breakthrough.
Segment Analysis
By Solution
Connectivity Services
Connectivity services form the larger solution category, with a projected 63% of market value in 2026. This group encompasses 5G-relevant digital activation, remote SIM profile management and identifiable eSIM-based connectivity offerings. The business benefits from repeat activations, fleet changes and customer renewals, whereas a secure element usually enters the value chain when a device is manufactured.
Thales, Giesecke+Devrient and other provisioning providers compete on standards compliance, platform availability and integration with operator systems. IoT customers additionally require remote lifecycle controls and the ability to modify carrier relationships after installation. Services gain share toward 2031 as platform utilization increases, but suppliers still need strong interoperability and favorable operator economics to convert technical adoption into revenue.
By Application
Consumer Electronics
Consumer electronics represents approximately 69% of the 2026 market, with smartphones accounting for most of its value. Large device-replacement cycles and the expansion of eSIM-capable handsets make consumer activation the broadest commercial channel. Wearables contribute a smaller but more specialized requirement because connectivity must be delivered within compact, power-constrained products.
The competitive focus is shifting from availability of the eSIM chip alone to activation completion rates, dual-line convenience and efficient digital distribution. Operators that simplify transfer between devices can improve customer experience and reduce support workload. Smartphones remain the leading application in 2031, although their share moderates as connected machines create more demand for managed profile lifecycles.
By Application
M2M, Including Automotive
Machine-to-machine applications grow faster than the market average as automakers, energy utilities and industrial operators install devices intended to work for many years. A remote or mobile asset cannot rely on a user replacing a SIM when its coverage or service provider changes. The ability to manage profiles remotely therefore affects product design, manufacturing complexity and future operating flexibility.
Giesecke+Devrient's collaboration with Rivian and AT&T shows the progression from general IoT specification work toward vehicle-specific sourcing programs. Automotive remains the largest M2M subcategory in the working outlook, while meters, gateways and industrial systems provide additional opportunities. Qualification, connectivity agreements and long lead times mean adoption is likely to advance through specific production programs rather than an immediate universal transition.
Market Drivers
5G Device Growth Expands the Eligible Connectivity Base
Ericsson reported 3.1 billion 5G subscriptions worldwide in the first quarter of 2026 and projects 6.4 billion by 2031. That growth expands the pool of endpoints capable of using embedded profiles, particularly as midrange smartphones and connected equipment adopt modern cellular modems. More compatible devices support larger volumes of secure-element integration, operator downloads and digital activation.
Network growth alone does not guarantee an eSIM transaction; device design and carrier support remain essential. The strongest revenue effect occurs where both conditions are met and customers can move from physical provisioning to a supported remote activation journey.
OEM Adoption Reduces Dependence on Physical SIM Logistics
Phone manufacturers increasingly ship products designed around embedded digital identity, and Apple's iPhone 17 rollout expanded eSIM-only availability across several countries in 2025. Eliminating or reducing physical SIM handling simplifies selected packaging, channel and customer onboarding processes. It also encourages operators to invest in compatible activation systems because customers expect setup directly on a new device.
As device availability broadens, activation infrastructure becomes a recurring procurement consideration rather than a limited pilot investment. Providers with stable download performance, broad handset compatibility and responsive customer support are better positioned to retain business.
Long-Life Industrial Devices Need Remote Operator Flexibility
Automotive telematics units, industrial gateways and smart meters may remain in the field far longer than a typical mobile handset. Operators can change commercial terms or network footprints during that period, making a fixed, factory-installed connectivity arrangement less attractive. SGP.32 gives enterprise users a technical path to remotely manage profiles on constrained equipment.
The Rivian R2 project announced by Giesecke+Devrient illustrates how a single hardware configuration can support wider geographic deployment and subsequent network changes. The financial incentive comes from reducing service visits, inventory variations and redesign costs rather than merely raising data speeds.
Digital Distribution Creates Additional Activation Demand
Operator apps and specialist digital connectivity distributors enable customers to purchase and load profiles without visiting a shop. Travel connectivity, secondary lines and temporary subscriptions create activation events beyond the original handset sale. Successful delivery relies on coordination among mobile operators, provisioning servers, identity checks and customer-facing software.
Growth in these channels supports eSIM-specific services revenue as the number of usable devices expands. However, platform providers must offer reliable activation and transparent device eligibility, because failed downloads erode both customer trust and the economics of low-value transactions.
Standards Maturity Improves Enterprise Deployment Confidence
The GSMA's SGP.32 IoT architecture and its 2026 specification updates give equipment makers a more consistent basis for interoperability testing and provisioning integration. Standardization matters because many IoT buyers manage fleets across multiple carrier networks and national markets. Common interfaces reduce the requirement for proprietary connection-management work on every device program.
Kigen's July 2026 evaluation offering brings together certified eSIMs, a management environment and participating connectivity providers to test these workflows. This lowers the practical barrier between technical readiness and deployment decisions, especially for smaller equipment suppliers without established telecom integration teams.
Market Restraints
Operator Provisioning Systems Remain Unevenly Integrated
Remote profile download requires coordination between the device operating system, eUICC, provisioning servers and operator back-office systems. An operator may support eSIM in one device category or country but not offer equivalent activation capability elsewhere. Product qualification and customer-care workflows therefore remain fragmented despite common standards.
This creates measurable operating friction for handset distributors and cross-border IoT programs. Providers must spend on carrier onboarding, device testing and exception handling before the service can scale reliably across markets.
Security and Identity Controls Increase Operating Requirements
Mobile credentials require controlled issuance, secure storage and protection against unauthorized profile transfers. Digital activation also introduces risks around identity theft, SIM-swap fraud and compromised customer accounts. Secure-element certification and strong authentication help address these issues, but they add testing, audit and system-maintenance obligations.
The security burden is especially high in connected vehicles and enterprise equipment because a failed identity process can interrupt essential telemetry or service availability. Buyers often favor established, audited suppliers even when less expensive alternatives offer similar features.
Low-Cost Devices Face Integration and Unit-Economics Constraints
Entry-level modules and mass-market IoT equipment are built to tight hardware budgets. An eUICC, secure operating environment and associated provisioning services must fit within the device's bill of materials and expected lifetime. When a product requires only one network and minimal profile changes, traditional SIM solutions can remain economically competitive.
Supplier differentiation therefore depends on demonstrating a lower total cost of ownership through fewer variants, reduced field visits or easier international deployment. Benefits are less compelling in simple applications with stable domestic connectivity and easy physical access.
M2M Migration Requires Testing Across Long Product Lifecycles
Vehicle and utility equipment manufacturers often support products for a decade or longer. Moving an installed fleet from legacy M2M provisioning toward SGP.32 can require changes to device software, remote management systems and operator contracts. Older eUICCs may not support every workflow available in newer products, requiring parallel platforms during a migration period.
Enterprise buyers consequently validate the complete activation and recovery sequence before committing to large deployments. This lengthens design cycles and concentrates early adoption among programs where the operational benefit justifies integration effort.
Roaming Rules and Country-Specific Connectivity Policies Limit Uniform Rollouts
Global equipment makers must contend with differing permanent-roaming restrictions, operator agreements and local subscription requirements. A remotely changeable eSIM makes the commercial response more flexible, but it does not remove the need for legally permitted local network access. Device makers may still need separate provisioning arrangements in countries with restrictive policies.
These variations complicate pricing and global service commitments. Suppliers with established operator relationships and regional implementation experience are better equipped to support multi-country deployments without creating an unsupported promise of universal coverage.
Regional Outlook
Americas
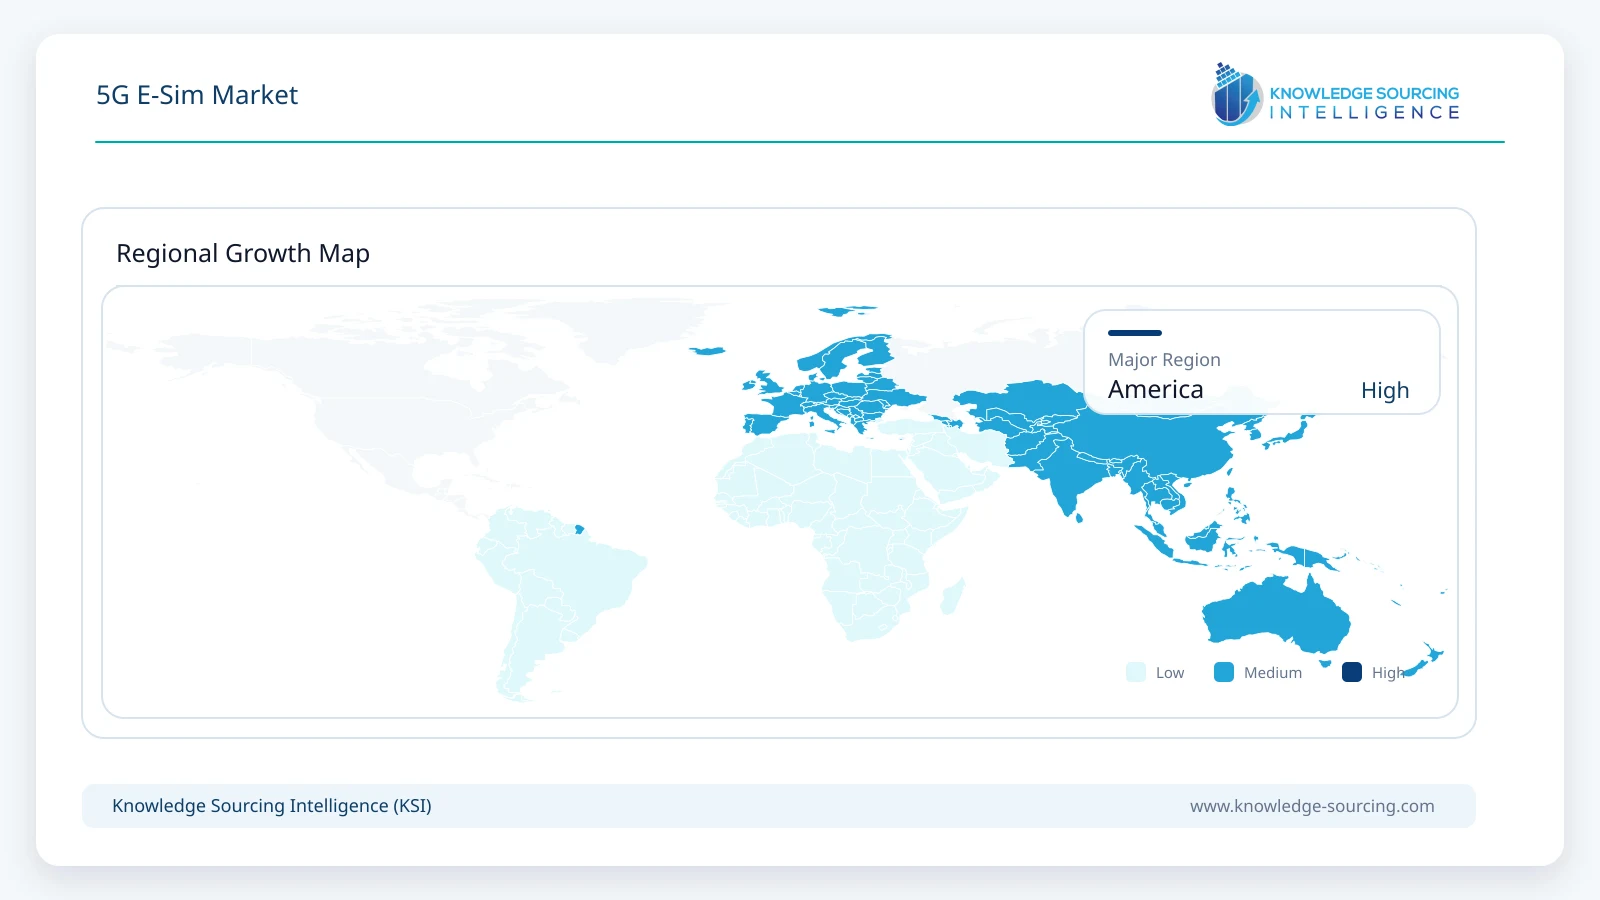
The Americas leads the 5G eSIM market in 2026, supported by high 5G penetration, broad operator eSIM support and the established use of eSIM-only smartphones in the United States. North America anchors the region through premium handset replacement, mobile-network investment and digitally managed connections. Consumer activations remain commercially important, while enterprise and automotive systems create additional demand for remotely managed credentials.
Apple's expansion of eSIM-only handset configurations and operator participation in vehicle connectivity show how adoption is spreading across use cases. South America offers a smaller but growing opportunity as carriers introduce more digital onboarding and connected-device services. Regional suppliers compete increasingly on activation quality, compatible device coverage and specialist enterprise connectivity rather than simply hardware availability.
Asia Pacific
Asia Pacific is expected to post the strongest regional growth through 2031 as the installed base of eSIM-capable smartphones and remotely managed connected equipment expands. The Trusted Connectivity Alliance's October 2026 report identified a substantial jump in eSIM profile downloads in China following approvals for consumer eSIM services in October 2025. Ericsson expects India to exceed 1.1 billion 5G subscriptions by 2031, illustrating the scale of future compatible mobile demand without suggesting that every connection already uses eSIM. Japan, South Korea and regional electronics supply chains also contribute design and production capabilities for secure identity hardware.
Operator readiness, identity requirements and pricing differ substantially across Asia Pacific. China has become a more important source of consumer activation, Japan has adopted additional eSIM-only smartphone configurations, and India presents considerable long-term device potential alongside different channel economics. Telecom operators, OEMs and provisioning suppliers will need to align onboarding, local service availability and enterprise fleet-management agreements to realize this opportunity. Regional growth should therefore be linked to supported profiles and actual device programs, not interpreted as a direct percentage of 5G subscriptions.
Competitive Landscape
The competitive landscape separates secure hardware specialists from remote provisioning platforms and connectivity distributors. Infineon and STMicroelectronics compete through certified chips, form factors, and embedded security capabilities; Giesecke+Devrient, Thales, IDEMIA Secure Transactions, Kigen and Valid supply different parts of the profile management and lifecycle ecosystem. Operator relationships, software integration and certification are central to winning multi-year deployments.
Specialist connectivity companies and travel eSIM distributors operate closer to the end customer. Their competitive position depends on accessible network inventory, service pricing, activation completion and customer support rather than silicon design. These models also differ in revenue quality: a hardware sale occurs at production, while provisioning and specialized digital connectivity can recur over a device's lifetime.
Scale is not the only competitive advantage. Vehicle and utility customers may prioritize long-term security support and a proven global partner network, whereas consumer platforms need simple mobile onboarding and low support costs. SGP.32 is making service interoperability and remote fleet management more visible differentiators, but successful deployments require cooperation between multiple suppliers instead of one company controlling the full chain.
Recent Developments
July 2026: Kigen opened access to its IoT eSIM Starter Kit, combining certified eSIMs, remote management tools and profiles from more than 13 connectivity partners to support evaluation before large deployments.
July 2026: Telefónica and Thales announced an SGP.32-based IoT connectivity initiative aimed at simplifying profile management across international deployments.
May 2026: GSMA published SGP.32 version 1.3, updating the technical foundation for remote provisioning and management of constrained IoT devices.
March 2026: Giesecke+Devrient announced collaboration with Rivian and AT&T for SGP.32-enabled eSIM and 5G connectivity in the upcoming Rivian R2 vehicle.
October 2026: Trusted Connectivity Alliance reported that global consumer eSIM profile downloads in the first half of 2026 nearly matched the volume for all of 2025; SGP.32 subscription-manager platforms increased fivefold compared with full-year 2025, indicating faster activation and infrastructure adoption.
September 2025: Apple introduced iPhone 17 with eSIM-only configurations in a wider set of countries, expanding the need for carrier-supported digital onboarding.
Market Outlook
5G eSIM demand is increasingly moving from the initial delivery of secure hardware toward ongoing identity and connectivity lifecycle management. Smartphones should continue to account for substantial activation volumes, while automotive and industrial equipment create longer service horizons and repeated profile-management events. The expansion of SGP.32-compatible management platforms in 2026 improves the ecosystem for cross-border fleet operations, but suppliers still need dependable certification, operator access and documented recovery procedures to secure production programs.
Asia Pacific's expanding device base and automotive supply chains are expected to increase regional revenue participation, while the Americas remains a substantial source of consumer and enterprise spending. Standards-based IoT management may reduce the cost of expanding into new countries, although operator interoperability, local regulation and security requirements will continue to affect the speed of deployment.
Competition increasingly centers on making profile delivery operationally dependable. Chip miniaturization, multi-operator support, automated fleet provisioning and measurable activation success will matter more than broad claims that an eSIM itself improves radio speed. The businesses that link those capabilities to lower onboarding and lifecycle costs should capture a growing share of the market.
5G E-SIM Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.67 billion |
| Total Market Size in 2031 | USD 3.82 billion |
| Forecast Unit | Billion |
| Growth Rate | 18.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Solution, Application, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Solution
Hardware
Connectivity Services
By Application
Consumer Electronics
Smartphones
Wearables
Other Consumer Electronics
M2M
Automotive
Energy and Utilities
Other M2M
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
United Arab Emirates
Israel
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Australia
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. 5G E-SIM Market Size, 2026–2031
1.3. Solution, Application and Regional Outlook
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. 5G Device Growth Expands the Eligible Connectivity Base
3.1.2. OEM Adoption Reduces Dependence on Physical SIM Logistics
3.1.3. Long-Life Industrial Devices Need Remote Operator Flexibility
3.1.4. Digital Distribution Creates Additional Activation Demand
3.1.5. Standards Maturity Improves Enterprise Deployment Confidence
3.2. Market Restraints
3.2.1. Operator Provisioning Systems Remain Unevenly Integrated
3.2.2. Security and Identity Controls Increase Operating Requirements
3.2.3. Low-Cost Devices Face Integration and Unit-Economics Constraints
3.2.4. M2M Migration Requires Testing Across Long Product Lifecycles
3.2.5. Roaming Rules and Country-Specific Connectivity Policies Limit Uniform Rollouts
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Consumer eSIM Provisioning (SGP.21/SGP.22)
4.2. IoT Remote SIM Provisioning (SGP.31/SGP.32)
4.3. eUICC Hardware and Embedded Security
4.4. eSIM IoT Remote Manager (eIM) and SM-DP+
4.5. 5G Standalone Authentication and Device Interoperability
4.6. eSIM Activation, Lifecycle Management and API Integration
5. 5G E-SIM MARKET BY SOLUTION
5.1. Introduction
5.2. Hardware
5.3. Connectivity Services
6. 5G E-SIM MARKET BY APPLICATION
6.1. Introduction
6.2. Consumer Electronics
6.2.1. Smartphones
6.2.2. Wearables
6.2.3. Other Consumer Electronics
6.3. M2M
6.3.1. Automotive
6.3.2. Energy and Utilities
6.3.3. Other M2M
7. 5G E-SIM MARKET BY GEOGRAPHY
7.1. North America
7.1.1. United States
7.1.2. Canada
7.1.3. Mexico
7.2. South America
7.2.1. Brazil
7.2.2. Argentina
7.2.3. Others
7.3. Europe
7.3.1. Germany
7.3.2. United Kingdom
7.3.3. France
7.3.4. Italy
7.3.5. Spain
7.3.6. Others
7.4. Middle East and Africa
7.4.1. Saudi Arabia
7.4.2. United Arab Emirates
7.4.3. Israel
7.4.4. South Africa
7.4.5. Others
7.5. Asia Pacific
7.5.1. China
7.5.2. India
7.5.3. Japan
7.5.4. South Korea
7.5.5. Indonesia
7.5.6. Thailand
7.5.7. Australia
7.5.8. Taiwan
7.5.9. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Giesecke+Devrient GmbH
9.2. Thales S.A.
9.3. IDEMIA Secure Transactions
9.4. Kigen
9.5. Valid S.A.
9.6. Infineon Technologies AG
9.7. STMicroelectronics N.V.
9.8. Airalo
9.9. 1GLOBAL
9.10. Eseye Ltd.
9.11. Circles.Life
9.12. Telna Inc.
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations





Frequently asked questions
What is the projected market size and growth rate for 5G E-Sim?
The 5G E-Sim Market will reach USD 3.82 billion by 2031, growing at an 18.0% CAGR.
Which market segment contributes the most revenue to 5G E-Sim?
Consumer electronics represents approximately 69% of 2026 market revenue.
Which applications will see increased share in the 5G E-Sim market?
Machine-to-machine applications, like connected vehicles, will increase their share.
What are the key regional dynamics for 5G E-Sim market growth?
Asia Pacific is positioned for faster growth; Americas has an established base.
What key trends are driving the adoption of 5G E-Sim technology?
Increased consumer profile downloads and the GSMA SGP.32 shift are key drivers.
What is the forecasted global scale of 5G subscriptions by 2031?
Ericsson forecasts 6.4 billion global 5G subscriptions by 2031.
Cite this report
Knowledge Sourcing Intelligence. (Nov 2026). 5G E-Sim Market - Strategic Insights and Forecasts (2026–2031). https://www.knowledge-sourcing.com/report/5g-e-sim-market