
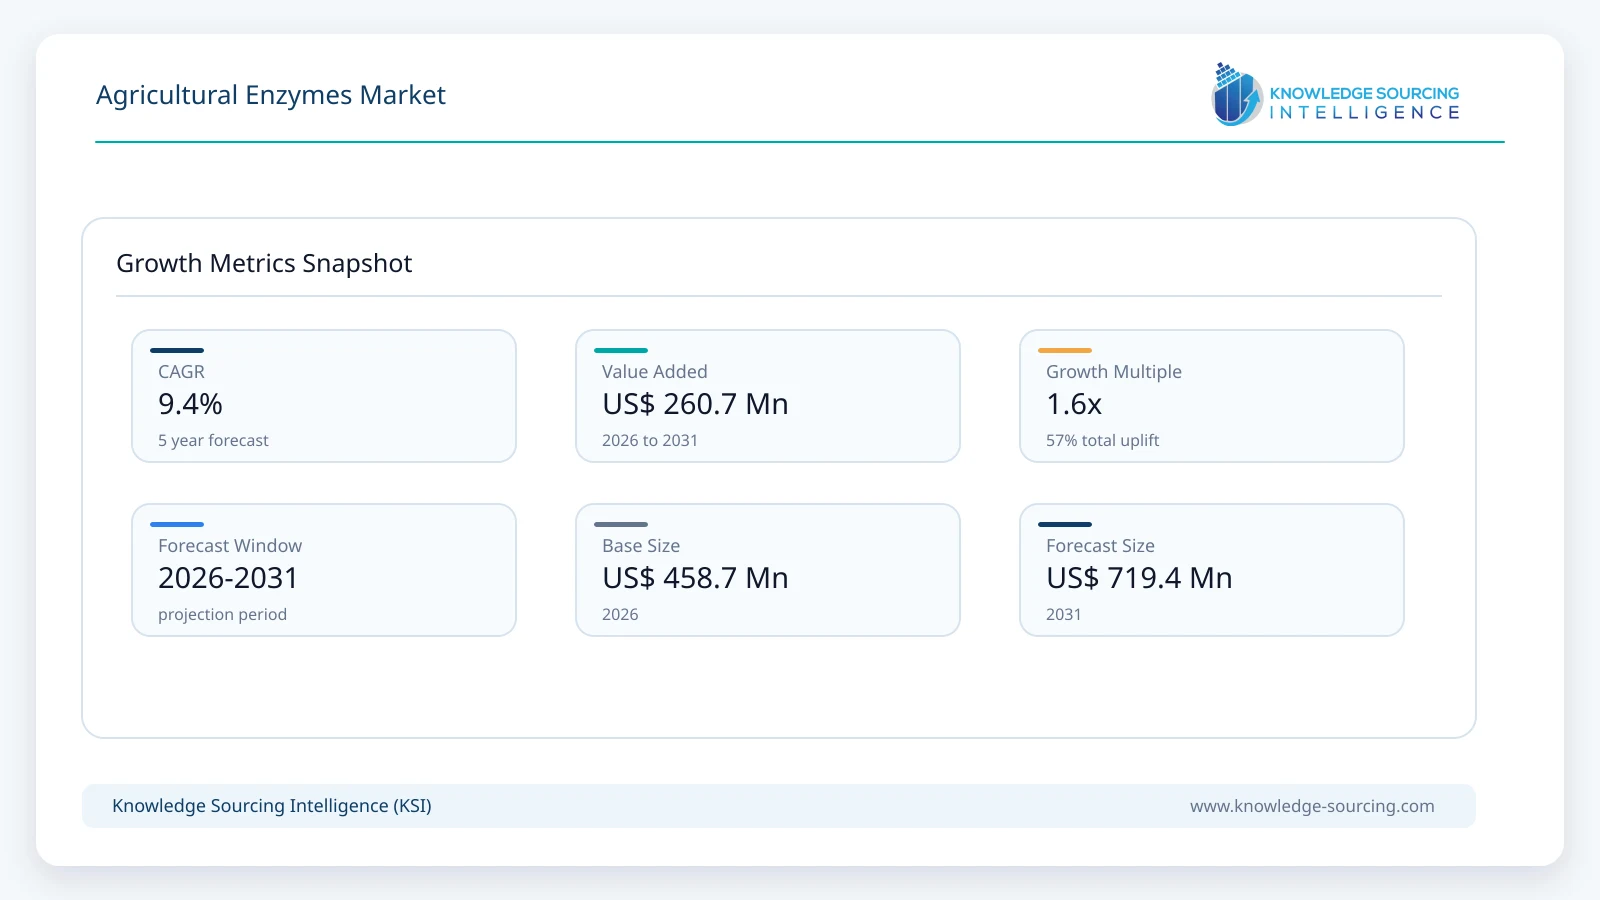
The agricultural enzymes market is anticipated to grow at a CAGR of 9.4%, from USD 458.7 million in 2026 to USD 719.4 million by 2031.
Highlights:
- 1Soil fertility and nutrient mobilization account for an estimated 54.0% of market revenue in 2026, making nutrient-use efficiency the largest commercial application.
- 2Microbial-derived enzymes represent approximately 66.0% of 2026 revenue, reflecting the scalability and flexibility of microbial fermentation for commercial enzyme production.
- 3Liquid formulations account for approximately 59.0% of the market in 2026, supported by in-furrow, seed-treatment, fertilizer-additive and side-dress applications.
- 4Cereals and grains represent approximately 39.0% of 2026 demand, reflecting large planted acreage and the commercial importance of improving nutrient efficiency in corn, wheat, rice and other broadacre crops.
- 5North America accounts for an estimated 30.0% of global revenue in 2026, while Asia Pacific is projected to record the strongest growth among the major regions.
- 6Elemental Enzymes states that its technologies expanded from approximately 17 million treated acres in 2024 to 27 million acres in 2025, providing evidence that enzyme-based crop inputs are moving beyond small-scale trials into materially larger commercial acreage.
- 7Commercial product development is increasingly focused on phosphorus mobilization, fertilizer-use efficiency, residue decomposition and integration of enzyme technology directly with fertilizer and crop-nutrition programs.
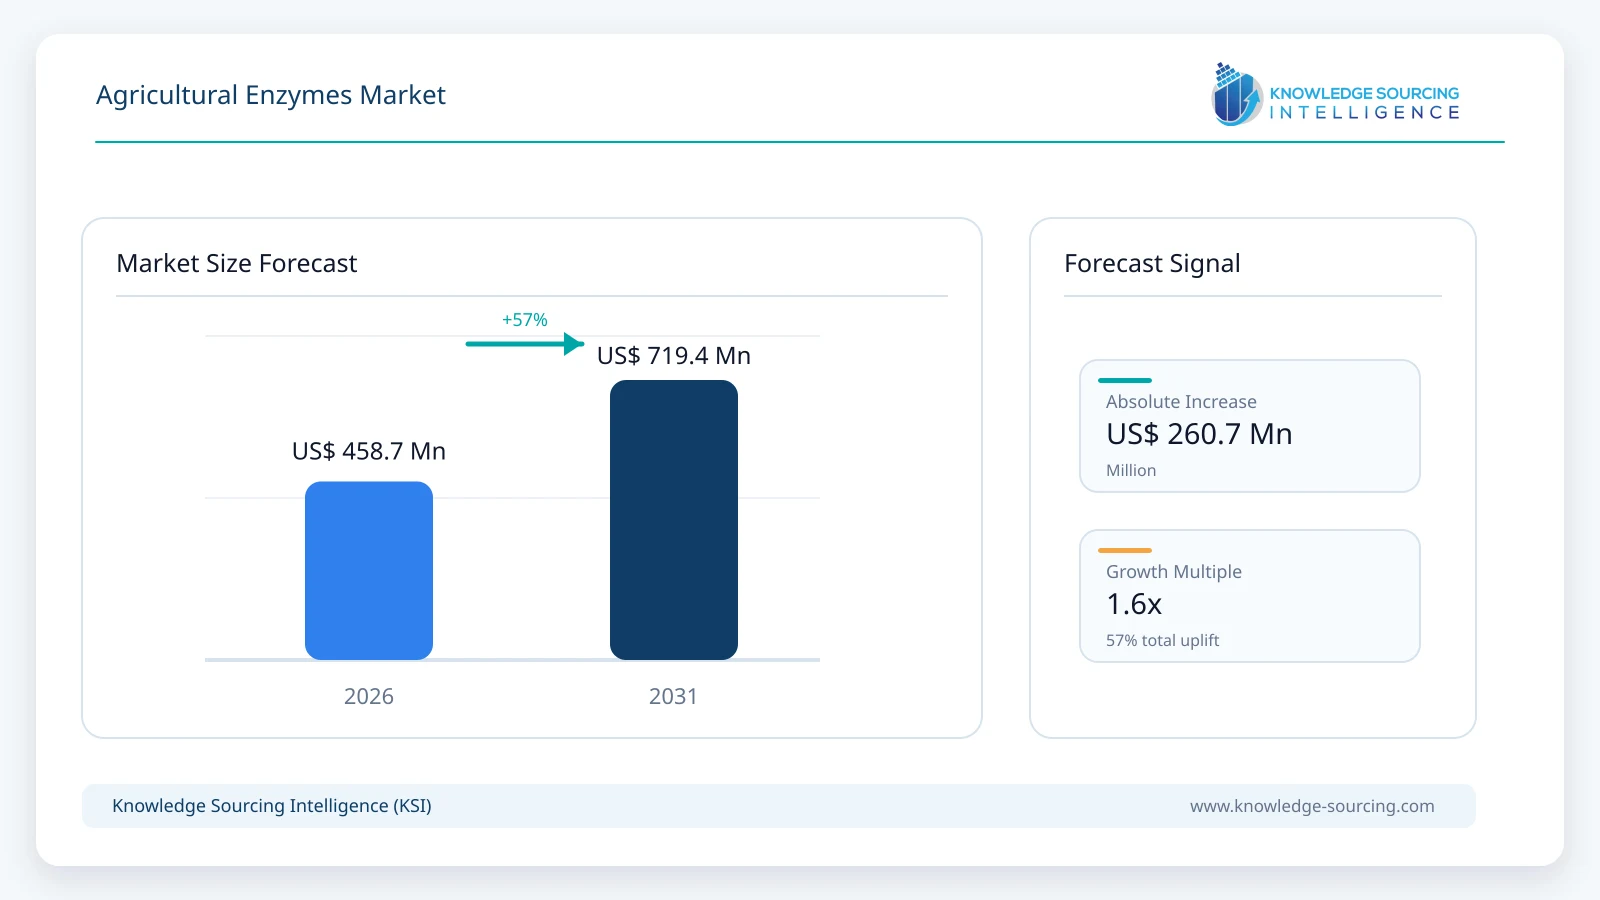
Growth is supported by increasing commercial use of enzymes for nutrient mobilization, fertilizer-use efficiency, crop-residue decomposition, soil-health improvement and selected crop-protection applications. Enzyme technologies are increasingly being incorporated into seed treatments, in-furrow products, liquid fertilizer additives and residue-management programs, allowing growers to introduce biological functionality without substantially altering established crop-production practices.
Agricultural enzymes are biological catalysts applied to crops, soil, seeds, fertilizer or crop residues to accelerate specific biochemical reactions that improve nutrient availability, residue decomposition, plant establishment or crop health. Unlike living microbial inoculants, enzymes do not need to establish or reproduce after application. Their activity is determined by the enzyme itself, its formulation, placement and environmental conditions. This distinction is commercially important because enzyme products can be combined with fertilizers and other agricultural inputs while offering more predictable biochemical activity than products that depend entirely on successful microbial colonization.
The scope covers enzymes used in crop production, soil management, nutrient-use efficiency, crop establishment, residue management and biological crop protection. Animal-feed enzymes, food-processing enzymes, industrial enzymes and enzymes used principally in livestock nutrition are excluded.
Agricultural enzymes occupy a relatively specialized but increasingly relevant position within the broader agricultural biologicals industry. Their value proposition differs from conventional fertilizers, pesticides and microbial inoculants. Enzymes catalyze defined biochemical reactions without being consumed by the reaction itself and can therefore be used to accelerate processes already occurring within soil, crop residues or the rhizosphere.
One of the clearest commercial applications is nutrient mobilization. Significant quantities of phosphorus and other nutrients can be present in soil but remain chemically or biologically unavailable to plant roots. Phosphatases and related enzyme systems can accelerate the conversion of organic or bound phosphorus compounds into more available forms, improving the productivity of both native soil nutrients and applied fertilizer. Corteva’s Utrisha P provides an example of this mechanism through a microbial biological whose root-zone activity includes production of enzymes that support phosphorus mobilization.
Elemental Enzymes has taken a more direct enzyme-application approach. Its agricultural technology places selected enzymes into the root zone through seed treatments, liquid in-furrow applications, fertilizer impregnation and side-dress programs. The company states that agricultural enzymes can unlock soil-bound nutrients, improve fertilizer-use efficiency and accelerate crop-residue breakdown. Its products are already incorporated into commercially available inputs distributed across the United States and Australia.
Residue management represents another commercially distinct application. Cellulases and related carbohydrases can begin breaking down structural carbohydrates in harvested plant material, improving microbial access to retained stubble and accelerating nutrient recycling. ADAMA Australia’s RES+ product, developed by Elemental Enzymes, contains cellulase as its principal enzyme and is used to accelerate the degradation of retained crop residue in minimum- and zero-tillage systems.
The market remains substantially smaller than the overall agricultural biologicals industry because many biological products use microorganisms, metabolites, peptides or plant extracts without adding purified enzymes directly. However, enzyme technology is gaining commercial relevance where a defined reaction can be linked to a specific grower problem, particularly nutrient availability, residue breakdown and fertilizer efficiency.
Market Drivers
Fertilizer-use efficiency is creating a direct commercial case for soil enzymes
The strongest market driver is the need to improve the amount of applied fertilizer that ultimately becomes available to the crop. Fertilizer expenditure represents a substantial operating cost for broadacre growers, while phosphorus and other nutrients can become chemically bound or remain trapped within organic matter after application.
Enzyme products can improve this economics without requiring a grower to abandon conventional fertilizers. Instead, the enzyme is placed close to the seed or root system and catalyzes reactions that release nutrients already present in soil, organic matter or fertilizer.
Elemental Enzymes specifically positions its nutrient-efficiency technology around extraction of soil nutrients and improved return on fertilizer expenditure. In February 2026, the company highlighted field results showing different enzyme formulations and application methods increasing nutrient draw in corn, while a commercial Australian example using patented liquid enzyme fertilizer additives in phosphorus-restricted soil reported yield improvement of up to 30%.
This integration with conventional crop nutrition is important commercially. Enzyme technology does not necessarily need to compete with fertilizer expenditure; it can be sold as a method of increasing fertilizer productivity. This supports adoption across both high-input agriculture and regions where growers are attempting to lower nutrient cost per unit of crop output.
Enzyme products fit established fertilizer and seed-treatment workflows
A new agricultural input has a considerably stronger adoption case when it can be integrated into practices growers already use. Agricultural enzymes can be delivered through in-furrow applications, seed treatment, liquid fertilizer, coated dry fertilizer and side-dress programs.
Elemental Enzymes’ commercial application guidance specifically includes direct soil application, impregnation onto solid fertilizer, liquid planting applications and seed treatment. The company’s March 2026 Australian partnership with Tanuki extends this approach by combining Lumen enzyme technology with zinc in the Lumen Z formulation and developing products that can be integrated with established fertilizer programs.
This reduces the practical barrier to adoption. Growers do not need separate specialist application machinery or entirely new operating procedures. Distribution through fertilizer and crop-nutrition companies can also place enzyme technology within channels that already have agronomic relationships with farmers.
The KSI model consequently expects fertilizer-integrated and liquid formulations to remain important growth areas throughout the forecast period.
Residue-management enzymes are gaining relevance in reduced-tillage systems
Conservation tillage and residue retention can improve soil structure, moisture retention and erosion control, but heavy stubble can create operational problems during planting and can immobilize nutrients while decomposition occurs.
Cellulase-based products accelerate the first stages of residue decomposition by weakening cellulose-rich structural material and increasing access for naturally occurring decomposer microorganisms. RES+ is a commercial example. ADAMA identifies cellulase as the active enzyme and recommends the product for post-harvest crop residues across field-grown grain and fibre crops.
Long-duration field evidence is strengthening the commercial case. Elemental Enzymes reported in March 2026 that a six-season trial in Western Australia’s wheatbelt produced an additional 2.56 tonnes per hectare of cumulative grain production and a 9.2% total yield improvement in the RES+ treatment program compared with the untreated system.
Residue management remains smaller than nutrient mobilization but is projected to grow at approximately 11.5% annually through 2031, above the overall market rate.
Biological crop-input companies are incorporating enzymes into broader portfolios
Agricultural biologicals are increasingly sold as integrated programs rather than isolated microbial or biochemical products. Corteva defines biological agricultural inputs as naturally derived materials including beneficial bacteria and enzymes and is expanding biological solutions aimed at yield, stress management and nutrient efficiency.
Novonesis similarly states that naturally occurring microbes and enzymes are part of its plant biosolutions platform and identifies enzymes as tools for improving crop fertility, soil phosphorus efficiency and plant nutrition.
This broader industry structure matters because specialized enzyme developers can reach substantially larger acreage through licensing, distribution and formulation partnerships rather than building their own agricultural sales organizations. Elemental Enzymes, for example, describes commercial partnerships as a core route for integrating proprietary enzyme technology into agricultural products already sold through established distribution systems.
The resulting market is therefore likely to include both standalone enzyme products and enzymes embedded within branded fertilizers, biologicals and seed-treatment systems.
More stable formulations are reducing practical limitations
Enzymes historically faced challenges related to storage stability, temperature, formulation compatibility and environmental activity. Improvements in protein engineering and formulation technology are making it possible to deliver enzymes through commercially practical agricultural products.
RES+, for example, is formulated as a soluble liquid and ADAMA states that the product remains viable for at least 24 months when stored appropriately. Its cellulase enzyme does not require refrigerated storage under normal recommended conditions because the product does not contain living microorganisms.
This is an important difference from some microbial biologicals. An enzyme does not need to remain alive, reproduce or successfully colonize the rhizosphere. Its performance can still be affected by temperature, moisture, pH and placement, but manufacturers can engineer activity and formulation around a narrower biochemical task.
Improved formulation consequently broadens commercial use across fertilizer additives, seed treatments and residue-management products.
Market Restraints and Challenges
Enzyme performance remains highly dependent on placement and agronomic conditions
Enzymes act on specific substrates and normally have limited mobility in soil. An effective enzyme applied too far from the target substrate may therefore provide little agronomic value.
Elemental Enzymes recommends placing soil enzymes close to the seed and root zone through in-furrow, 2×2 or seed-associated applications rather than broadcasting them indiscriminately. Moisture, soil pH and temperature can also influence activity.
This creates a more knowledge-intensive sales process than commodity fertilizers. Manufacturers and distributors need to specify appropriate crop, timing, rate and placement rather than marketing enzymes as universal soil enhancers.
Farmers need measurable returns rather than broad biological claims
The agricultural biologicals market contains products with widely different levels of technical validation. Growers increasingly demand replicated field evidence demonstrating that a product improves yield, nutrient-use efficiency or operating economics under relevant local conditions.
This creates a barrier for smaller enzyme suppliers without multi-year trial programs. Elemental Enzymes states that it conducts replicated, multi-site field programs and reported that its 2024 research program covered more than 20 countries, more than 50 crops and over 1,000 site-years of data.
The market therefore favors suppliers capable of supporting product claims with multi-location data rather than relying primarily on laboratory enzyme activity.
Enzymes compete with microbial nutrient solutions and conventional agronomy
Direct enzyme products are only one route to improving nutrient availability. Microbial inoculants can produce enzymes within the rhizosphere, while fertilizer chemistry, chelation, acidification and other agronomic interventions can address similar nutrient limitations.
Corteva’s Utrisha P, for example, uses a root-colonizing bacterium that produces enzymes which mobilize phosphorus. This means the direct agricultural-enzyme market competes not only against conventional chemicals but also against other biological technologies that deliver an enzymatic effect indirectly.
The commercial case for a direct enzyme product therefore needs to rest on consistency, storage, compatibility, precise mode of action or ease of use rather than simply claiming biological nutrient mobilization.
Production and formulation remain specialized
Commercial enzyme production typically requires strain selection, fermentation, purification, stabilization and formulation capabilities. The enzyme must remain active through storage, transport, tank mixing and field application while still functioning under variable agronomic conditions.
Large biosolutions companies have substantial fermentation and protein-development capabilities, while smaller agricultural-enzyme developers often depend on specialized manufacturing or licensing partnerships.
This contributes to a relatively concentrated technology base even though final products may be sold through numerous agricultural distributors.
Major Segment Analysis
By Enzyme Type
Phosphatases and other phosphorus-mobilizing enzymes account for an estimated 31.0% of market revenue in 2026, reflecting the economic importance of improving phosphorus availability and fertilizer efficiency. The segment is projected to reach approximately USD 237.4 million by 2031, representing growth of about 10.8% annually.
Carbohydrases, including cellulases, amylases and related enzymes, represent the second-largest category. Their applications include residue decomposition, organic-matter transformation and nutrient cycling. Cellulases have an especially clear commercial role in crop-residue management, illustrated by ADAMA’s RES+ product.
Carbohydrase revenue is projected to reach approximately USD 208.6 million by 2031, supported by increasing residue-retention practices and greater interest in nutrient recovery from crop biomass.
Proteases and chitinases remain smaller categories. Proteases participate in organic nitrogen cycling and selected plant-health applications, while chitinases have potential in biological crop protection through degradation of chitin-containing pathogen or pest structures. Commercial penetration remains lower than nutrient- and residue-management enzymes.
By Function
Soil fertility and nutrient mobilization remain the largest application, accounting for 54.0% of 2026 market revenue. The segment is projected to reach approximately USD 402.9 million by 2031, supported by phosphorus mobilization, improved nutrient extraction from organic matter and enzyme integration with fertilizers.
Crop establishment and growth applications use enzyme technology to improve root-zone conditions and nutrient availability during early crop development. They represent a smaller but established market across seed treatment and in-furrow systems.
Residue management is projected to record the strongest growth among the principal functions. Cellulase and other degradative enzymes fit increasingly well with reduced-tillage systems where growers want to retain crop residues without allowing heavy stubble to interfere with planting or nutrient cycling.
Crop-protection applications remain technically promising but comparatively less commercialized. Enzymatic biocontrol competes with microbial pesticides, peptides and other biological crop-protection mechanisms and therefore remains a smaller portion of near-term revenue.
By Source
Microbial-derived enzymes account for approximately 66.0% of market revenue in 2026 and are projected to reach around USD 496.4 million by 2031. Microbial fermentation provides a scalable route to producing enzymes with specified biochemical properties and allows manufacturers to optimize strains for commercial production.
Plant-derived enzymes represent the second-largest source category and remain relevant where naturally occurring plant proteins or biochemical extracts provide useful agricultural functionality.
Animal-derived and other enzyme sources account for a smaller proportion of crop and soil applications and gradually lose market share through the forecast period as microbial production becomes more versatile.
By Formulation
Liquid formulations account for approximately 59.0% of the market in 2026. Their advantages include compatibility with in-furrow programs, seed-treatment systems, liquid fertilizer and side-dress applications.
The segment is projected to reach approximately USD 438.8 million by 2031 as suppliers increasingly design enzyme technology to fit existing liquid crop-nutrition programs.
Solid formulations remain significant through coated fertilizer, seed-applied products, powders and granular delivery. Growth is slower than liquid formulations but the category retains value where storage, handling and compatibility with dry fertilizer are important.
By Crop Type
Cereals and grains account for approximately 39.0% of global demand in 2026, supported by the enormous planted acreage of corn, wheat, rice and related crops and the value of improving fertilizer efficiency across high-input farming systems.
The segment is projected to reach approximately USD 287.8 million in 2031.
Oilseeds and pulses represent the second major broadacre group. Enzyme technology can complement inoculants and fertilizer programs in soybeans, canola and pulses where phosphorus and residue management are relevant.
Fruits and vegetables are projected to grow slightly faster than the overall market because higher crop value per hectare can support greater expenditure on biological inputs and nutrient-efficiency products.
Regional Analysis
North America remains the largest regional market in 2026, accounting for approximately 30.0% of global revenue. The United States has a developed biological-input distribution network and large corn, soybean and specialty-crop markets where nutrient-use efficiency can produce measurable economic returns.
Elemental Enzymes is headquartered in the United States and states that its enzyme technologies are already incorporated into commercial products used on millions of acres. The presence of Corteva, Novonesis, FMC and other major biological-input companies further supports the regional innovation ecosystem.
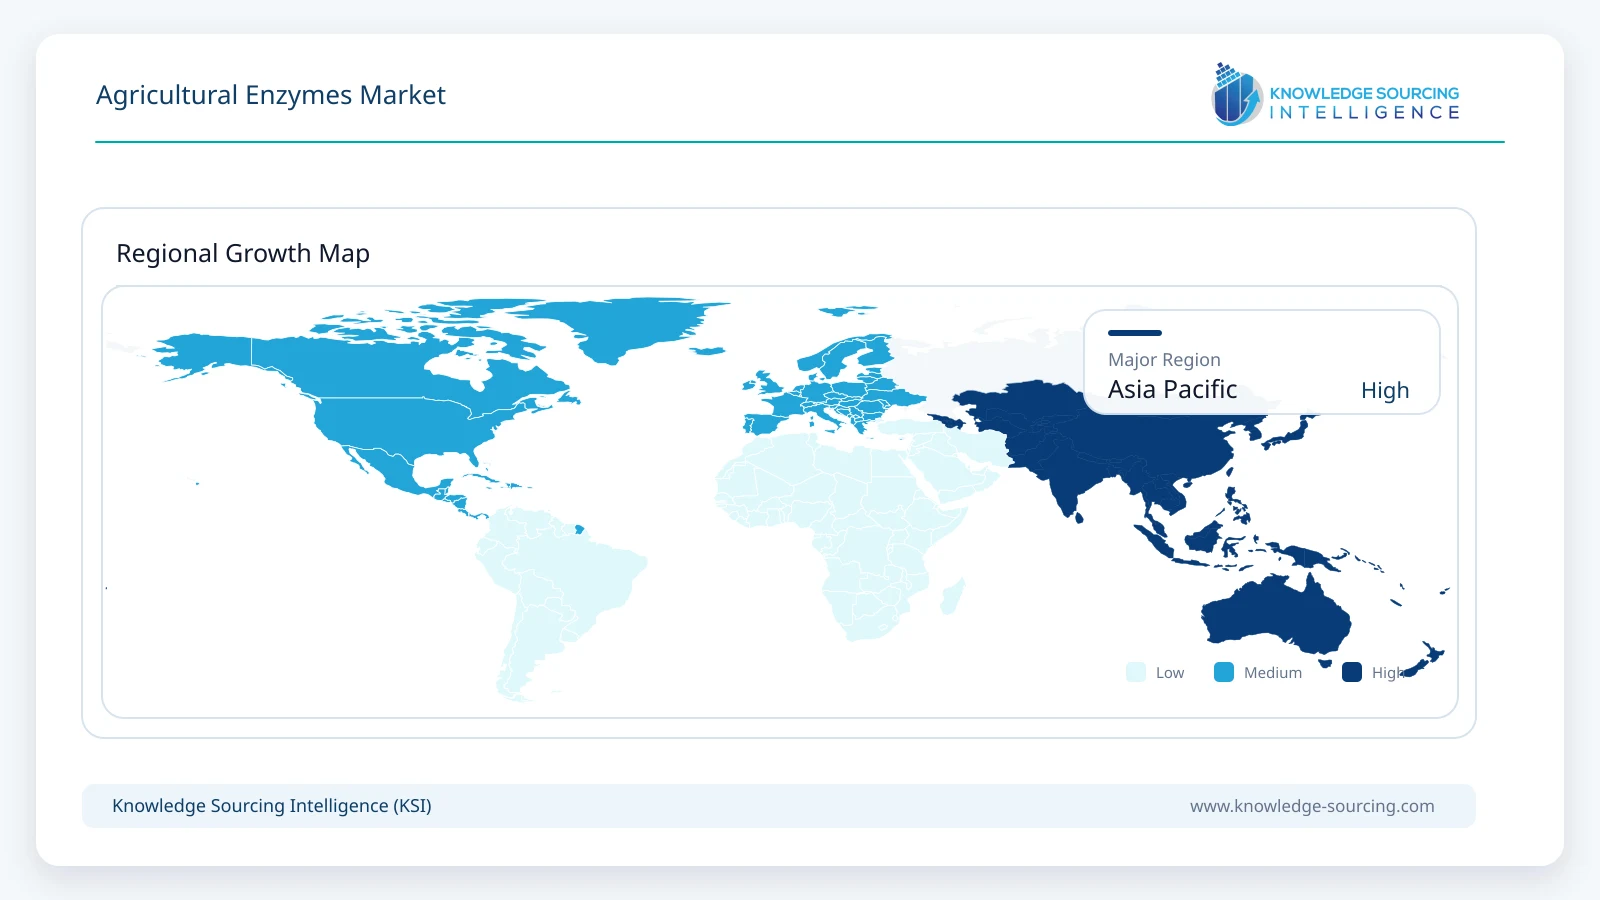
Asia Pacific follows closely and is projected to become the largest region by 2031, reaching approximately USD 230.2 million. Growth is supported by fertilizer-efficiency requirements, intensive crop production and expanding biological-input adoption across China, India, Australia and Southeast Asia.
Australia provides one of the clearest current examples of direct agricultural-enzyme commercialization. Elemental Enzymes has expanded Lumen and Magno through Tanuki, while ADAMA distributes the cellulase-based RES+ residue-management product.
Europe remains an important agricultural biologicals market but direct enzyme commercialization is developing more gradually than the broader biostimulant and microbial sectors. South America provides meaningful longer-term opportunity through Brazil and Argentina, particularly in broadacre crops and reduced-tillage systems.
Technology Outlook
Precision Enzymes for Nutrient Mobilization
Agricultural enzyme development is moving toward more specific biochemical targets rather than broad formulations promoted as general soil enhancers. Phosphorus mobilization is particularly attractive because soil can contain substantial phosphorus reserves that remain inaccessible to crops.
The technology opportunity is therefore to identify enzymes that remain active under field conditions and release targeted nutrient pools at commercially relevant rates.
Fertilizer-Integrated Enzyme Formulations
The second important transition is integration directly into crop-nutrition products. Enzymes can be coated onto solid fertilizer, supplied as liquid additives or combined with micronutrients.
Elemental Enzymes and Tanuki’s Lumen Z formulation, which combines enzyme technology with zinc for in-furrow use, illustrates this direction.
This approach reduces the number of separate applications required and allows distributors to sell enzyme technology through existing fertilizer programs.
Enzyme-Based Residue Management
Cellulase and related degrading enzymes provide a more targeted alternative to relying only on naturally occurring microbial decomposition. Enzyme formulations can begin weakening plant cell-wall structures immediately after application, increasing microbial access to retained biomass.
The strongest commercial opportunities are likely to remain in zero- and minimum-tillage systems where retained residue has agronomic value but can interfere with planting or slow nutrient recycling.
Recent Developments
August 25, 2026: ADAMA Australia reported continued commercial adoption of RES+, an Elemental Enzymes residue-management product containing cellulase. ADAMA stated that the product was being used to accelerate stubble decomposition and nutrient cycling in high-residue farming systems, with long-term Australian field work showing repeated yield benefits.
March 27, 2026: Elemental Enzymes Australia published results from a six-season RES+ field program in Katanning, Western Australia. Across five wheat seasons and one canola season, the treated program produced an additional 2.56 tonnes per hectare of cumulative grain and a 9.2% total yield improvement, providing multi-year field evidence for enzyme-assisted residue management.
March 3, 2026: Elemental Enzymes announced a partnership with Tanuki to expand enzyme technologies in Australia. The agreement increases availability of Lumen and Magno for broadacre and horticultural growers and includes integrated products such as Lumen Z, combining enzyme technology with zinc for in-furrow application.
Competitive Landscape
The agricultural-enzyme supplier base is more specialized than the broader agricultural biologicals market. Elemental Enzymes is one of the most directly exposed companies, with proprietary enzyme technologies targeting nutrient-use efficiency, soil health and residue management. Its commercial strategy combines internal R&D with licensing and distribution through larger agricultural companies.
Novonesis combines extensive enzyme-production expertise with a global agricultural biosolutions portfolio. The company states directly that naturally occurring microbes and enzymes are used within its plant-health platform to improve crop health and yield and identifies soil phosphorus efficiency and crop nutrition as target areas.
Corteva participates through a wider biologicals portfolio incorporating microbial and enzyme-mediated nutrient-mobilization mechanisms. Its partnership history with Elemental Enzymes also demonstrates how large crop-input companies can commercialize technologies developed by specialist biological innovators.
ADAMA has become directly relevant through commercialization of RES+ in Australia, while Tanuki participates through distribution, formulation and integration of Elemental Enzymes technology into crop-nutrition programs.
FMC has participated in enzyme-based agricultural biocontrol development through collaboration with the former Novozymes organization, now part of Novonesis. UPL maintains a broad biosolutions platform and collaborates with specialist biological technology companies across crop-protection applications.
A second tier of specialist companies includes ZymeCO, which develops enzyme-based products for residue management, nutrient availability and soil function, and several regional enzyme manufacturers offering agricultural and soil-treatment formulations.
Competition is therefore occurring at two levels: specialist enzyme developers compete on enzyme discovery, stabilization and agronomic evidence, while larger agricultural companies compete on distribution, formulation, registration and integration of enzyme technology into broader crop-management programs.
Analyst View
Agricultural enzymes should be treated as a specialized component of agricultural biologicals rather than as a substitute for the entire fertilizer or crop-protection market. The technology is commercially strongest where one defined biochemical reaction solves an identifiable agronomic problem and produces an outcome growers can measure.
Nutrient mobilization currently provides the clearest route to scale. Fertilizer is already part of the grower’s budget, so an enzyme that improves nutrient availability can be evaluated against fertilizer efficiency and yield rather than requiring an entirely new expenditure category. This also explains why fertilizer-integrated formulations and root-zone placement are commercially more attractive than generic broadcast biological products.
Residue management is developing into a second defensible niche. Cellulase-based products have a clear substrate, a defined application window and increasingly useful multi-year field data. Their value proposition is particularly strong in reduced-tillage systems where residue retention is desirable but heavy stubble creates planting and nutrient-cycling problems.
The competitive environment is likely to remain partnership-driven. Specialist companies possess enzyme-discovery and formulation knowledge, while large crop-input companies control registration, distribution and agronomic sales networks. Licensing, co-development and formulation partnerships can therefore commercialize enzyme technology more efficiently than specialists attempting to build global agricultural distribution independently.
Asia Pacific is likely to capture an increasing proportion of incremental demand as biological crop inputs expand and fertilizer-efficiency requirements become more important across high-intensity agricultural systems. Australia’s current enzyme commercialization provides evidence that direct enzyme products can move beyond North American applications when formulations and distribution are adapted to local farming practices.
The strongest opportunities through 2031 are consequently concentrated in phosphorus and nutrient mobilization, fertilizer-integrated formulations, cellulase-based residue management and enzyme technologies supported by repeatable multi-location field evidence.
Agricultural Enzymes Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 458.7 million |
| Total Market Size in 2031 | USD 719.4 million |
| Forecast Unit | Million |
| Growth Rate | 9.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Enzyme Type, Functional, Source, Formulation, Crop Type, Geography |
| Companies |
|
Market Segmentation
By Enzyme Type
Phosphatases & Other Phosphorus-Mobilizing Enzymes
Carbohydrases
Cellulases
Amylases
Xylanases & Other Carbohydrases
Proteases
Chitinases
Other Agricultural Enzymes
By Function
Soil Fertility & Nutrient Mobilization
Crop Establishment & Growth
Crop Protection
Crop Residue Management
Others
By Source
Microbial
Plant-Derived
Animal & Other Sources
By Formulation
Liquid
Solid
By Crop Type
Cereals & Grains
Oilseeds & Pulses
Fruits & Vegetables
Turf & Ornamentals
Other Crops
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
South Africa
Others
Asia Pacific
China
India
Japan
Australia
Indonesia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition and Scope
2.3. Scope Exclusions
2.4. Market Segmentation
2.5. Key Market Indicators
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints and Challenges
3.3. Market Opportunities
3.4. Fertilizer-Use Efficiency and Nutrient Mobilization
3.5. Soil Health and Crop-Residue Management
3.6. Agricultural Biologicals Adoption
3.7. Product Formulation and Commercialization
3.8. Regulatory and Registration Environment
3.9. Porter’s Five Forces Analysis
3.10. Strategic Recommendations
4. TECHNOLOGY OUTLOOK
4.1. Precision Enzymes for Nutrient Mobilization
4.2. Fertilizer-Integrated Enzyme Formulations
4.3. Enzyme-Based Residue Management
5. AGRICULTURAL ENZYMES MARKET BY ENZYME TYPE
5.1. Introduction
5.2. Phosphatases & Other Phosphorus-Mobilizing Enzymes
5.3. Carbohydrases
5.3.1. Cellulases
5.3.2. Amylases
5.3.3. Xylanases & Other Carbohydrases
5.4. Proteases
5.5. Chitinases
5.6. Other Agricultural Enzymes
6. AGRICULTURAL ENZYMES MARKET BY FUNCTION
6.1. Introduction
6.2. Soil Fertility & Nutrient Mobilization
6.3. Crop Establishment & Growth
6.4. Crop Protection
6.5. Crop Residue Management
6.6. Others
7. AGRICULTURAL ENZYMES MARKET BY SOURCE
7.1. Introduction
7.2. Microbial
7.3. Plant-Derived
7.4. Animal & Other Sources
8. AGRICULTURAL ENZYMES MARKET BY FORMULATION
8.1. Introduction
8.2. Liquid
8.3. Solid
9. AGRICULTURAL ENZYMES MARKET BY CROP TYPE
9.1. Introduction
9.2. Cereals & Grains
9.3. Oilseeds & Pulses
9.4. Fruits & Vegetables
9.5. Turf & Ornamentals
9.6. Other Crops
10. AGRICULTURAL ENZYMES MARKET BY GEOGRAPHY
10.1. North America
10.1.1. United States
10.1.2. Canada
10.1.3. Mexico
10.2. South America
10.2.1. Brazil
10.2.2. Argentina
10.2.3. Others
10.3. Europe
10.3.1. United Kingdom
10.3.2. Germany
10.3.3. France
10.3.4. Italy
10.3.5. Spain
10.3.6. Others
10.4. Middle East and Africa
10.4.1. Saudi Arabia
10.4.2. South Africa
10.4.3. Others
10.5. Asia Pacific
10.5.1. China
10.5.2. India
10.5.3. Japan
10.5.4. Australia
10.5.5. Indonesia
10.5.6. Others
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Competitive Positioning
11.2. Enzyme Technology and Mode-of-Action Analysis
11.3. Nutrient-Efficiency Product Benchmarking
11.4. Residue-Management Product Benchmarking
11.5. Formulation and Application Analysis
11.6. Partnership and Distribution Strategies
11.7. Strategic Developments
11.8. Competitive Dashboard
12. COMPANY PROFILES
12.1. Elemental Enzymes
12.2. Novonesis
12.3. Corteva Agriscience
12.4. ADAMA Ltd.
12.5. FMC Corporation
12.6. UPL Limited
12.7. BASF Agricultural Solutions
12.8. Syngenta Biologicals
12.9. Rovensa Next
12.10. ZymeCO
12.11. Infinita Biotech Pvt. Ltd.
12.12. Capri Enzymes
12.13. Praxon Industries LLP
12.14. Phyllozyme
13. ANALYST VIEW
14. APPENDIX
14.1. Research Methodology
14.2. Market Estimation and Assumptions
14.3. Scope and Double-Counting Controls
14.4. Definitions and Abbreviations
Navigate
Trusted by the world's leading organizations











