
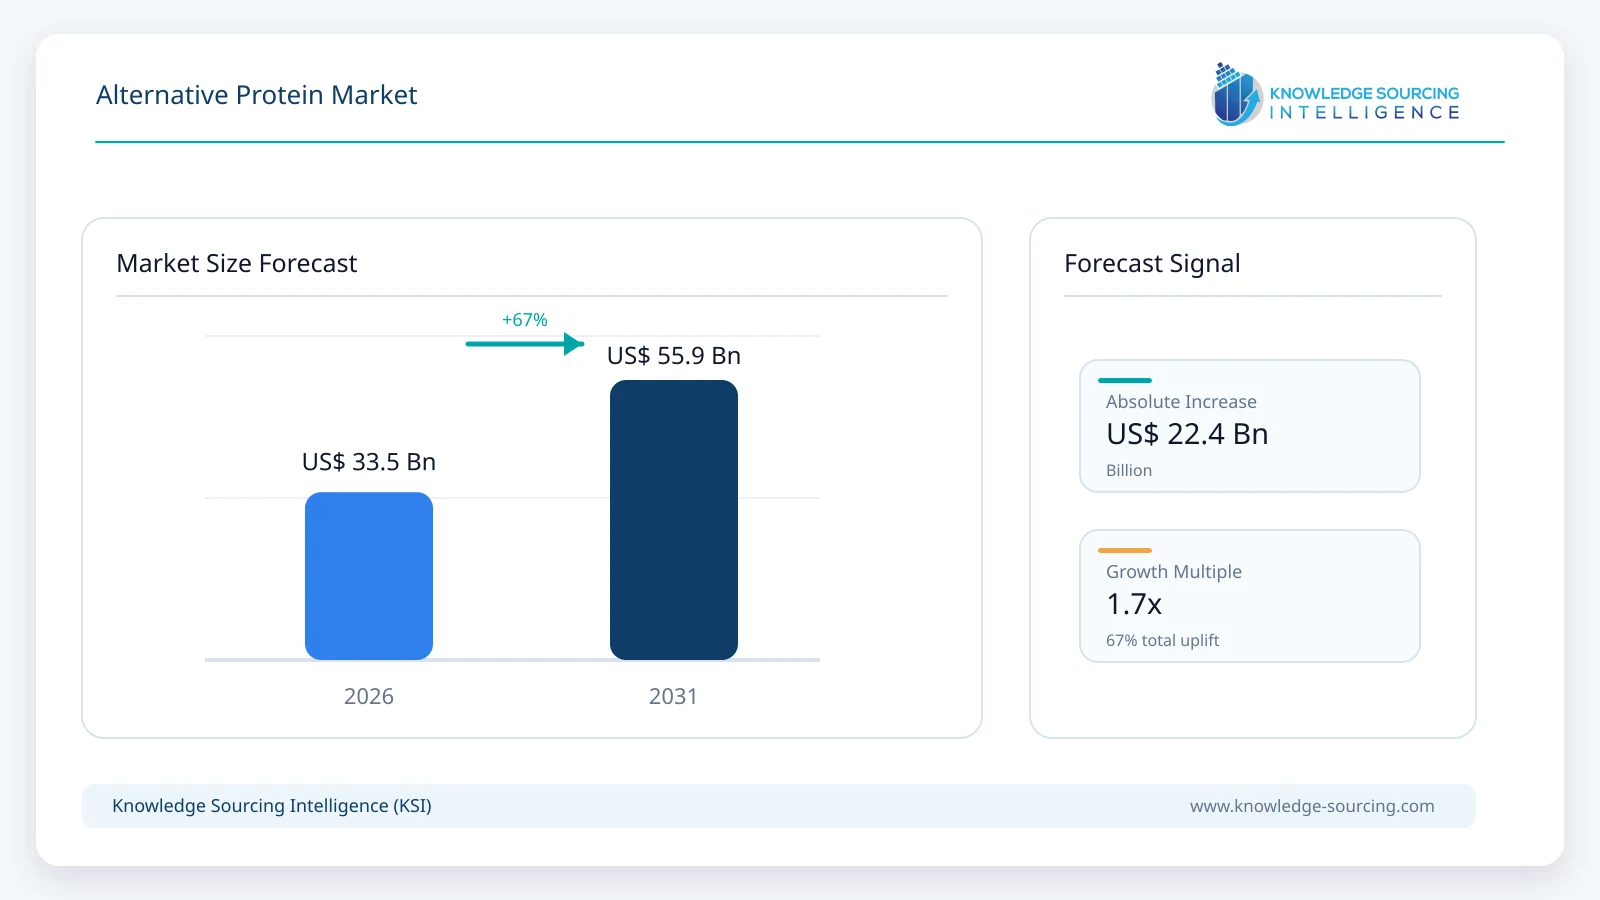
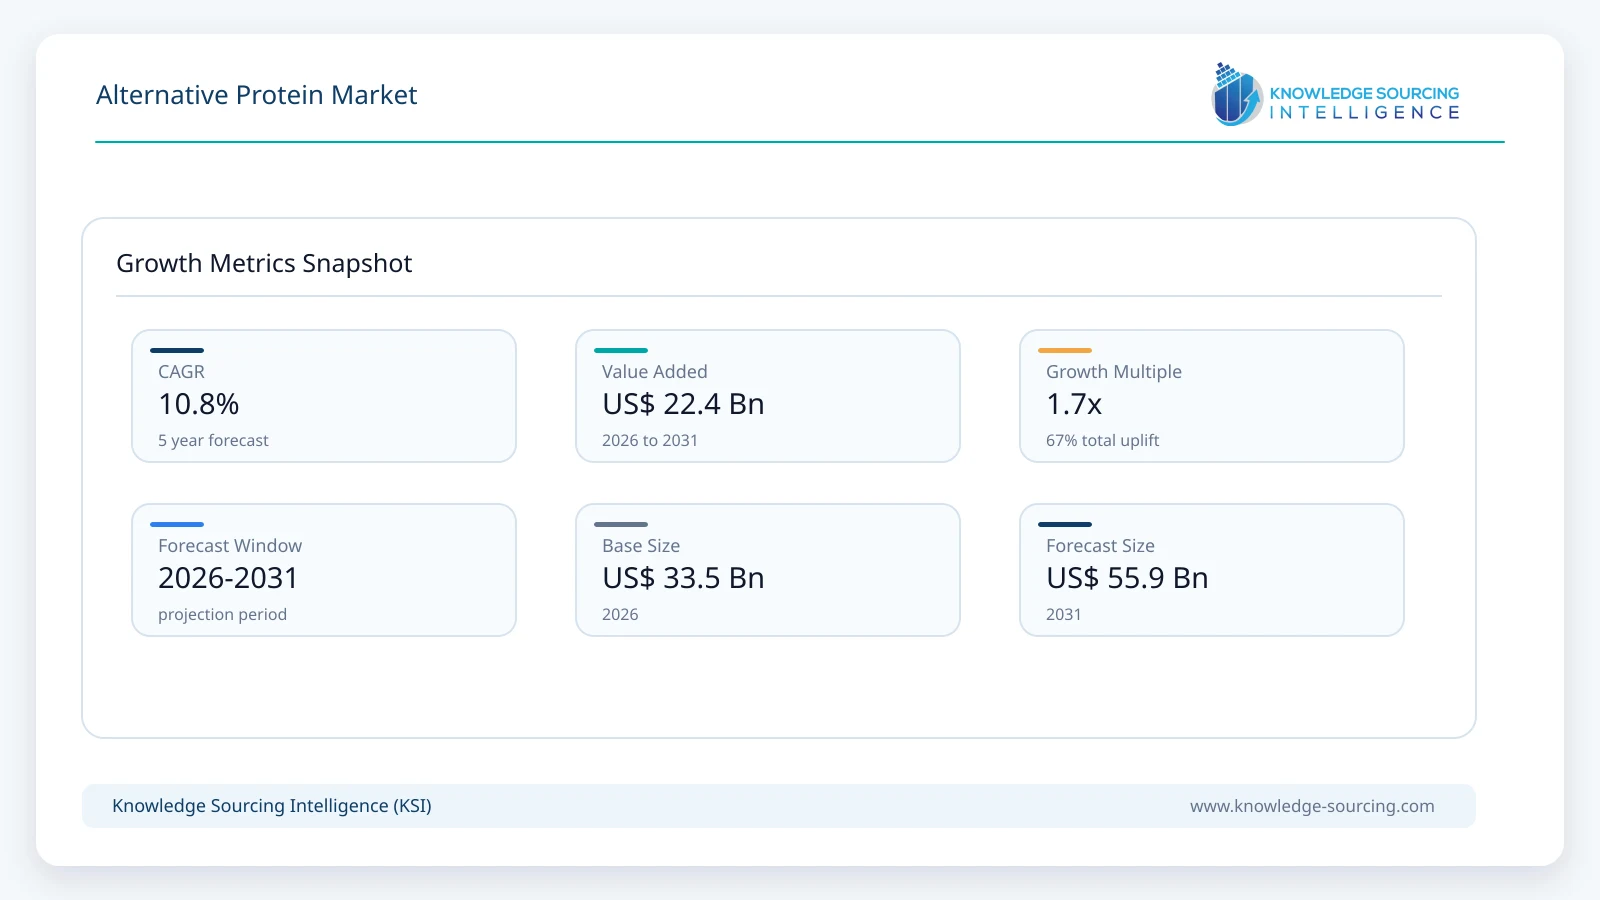
The global alternative protein market is forecast to grow at a CAGR of 10.8%, reaching USD 55.9 billion in 2031 from USD 33.5 billion in 2026.
Highlights:
- 1Plant-based products account for approximately 89% of global alternative protein revenue in 2026.
- 2Fermentation-derived proteins are projected to grow at approximately 29% annually through 2031.
- 3Dairy alternatives generate about USD 22.6 billion of global alternative protein market value in 2026.
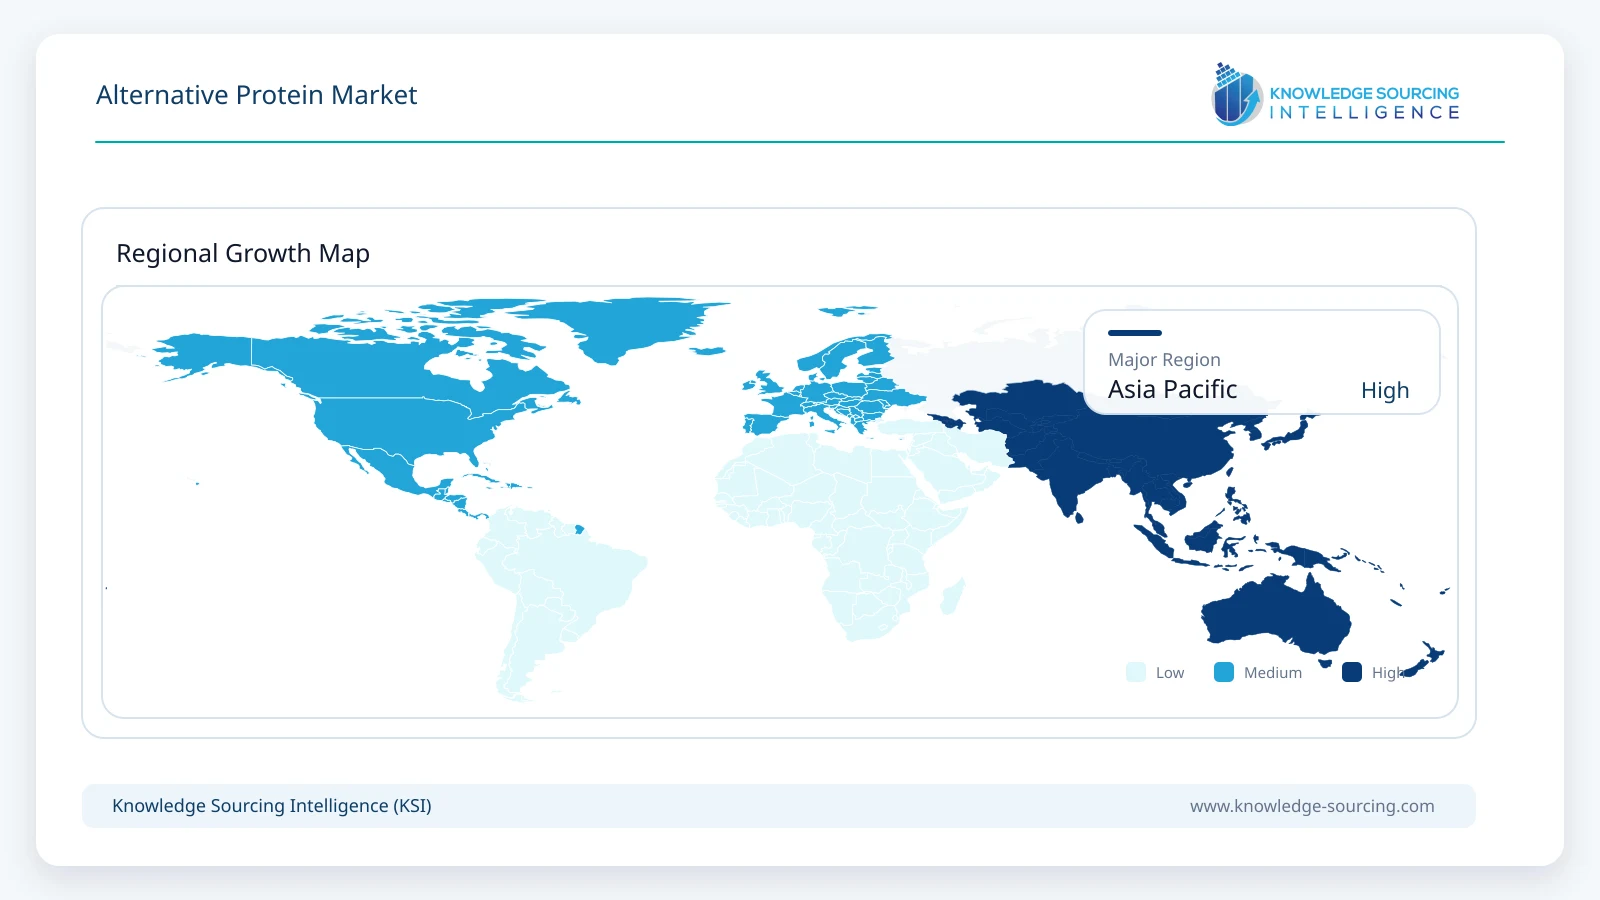
- 4Asia Pacific accounts for approximately 35% of global alternative protein revenue in 2026.
- 5Taste, texture and protein quality are replacing novelty as the main drivers of repeat purchase.
- 6Precision fermentation capacity and cultivated-protein approvals are expanding the technology mix beyond plants.
Market Overview
Alternative proteins are produced through several distinct technology platforms. Plant-based systems isolate or concentrate proteins from soy, pea, wheat, fava bean, chickpea, and other crops before texturizing or formulating them into meat, dairy, beverage, and nutrition products. Biomass fermentation grows protein-rich microorganisms such as fungi or yeast as the primary food material, while precision fermentation programs microorganisms to produce specific proteins such as egg or dairy proteins. Cultivated meat and seafood grow animal cells in controlled environments and remain at an earlier stage of commercialization.
The commercial base is still heavily plant-based. The Good Food Institute reported global retail sales of plant-based meat, seafood, milk, yogurt, ice cream and cheese of approximately USD 28.9 billion in 2025, including USD 22.7 billion in plant-based dairy and USD 6.6 billion in plant-based meat and seafood. The mix explains why market growth cannot be modeled by applying the high growth rates of cultivated or fermentation technologies to the entire category. Mature plant-based dairy and meat categories grow more slowly, while fermentation and cultivated technologies contribute progressively more value from a much smaller base.
Market Trends
Taste and protein quality are becoming more important than category novelty
Alternative protein companies are shifting product development toward sensory quality, recognizable nutrition claims and functionality rather than relying primarily on sustainability positioning. This is particularly visible in plant proteins, where beany or bitter notes, dryness and textural limitations can reduce repeat purchase. Roquette launched NUTRALYS Pea 850F in February 2026 to provide a cleaner, more neutral taste, while ADM introduced eight new soy and pea protein solutions in May 2026 across North America and Europe. These launches indicate that established ingredient suppliers see growth increasingly coming from better-performing protein systems that can be used in beverages, nutrition products and mainstream foods as well as direct meat analogues.
Fermentation is moving from technical validation toward manufacturing scale
Fermentation-derived protein is becoming a more important part of the commercial mix as producers secure larger manufacturing runs and customers become more comfortable with microbial production. GFI identified more than 160 specialized fermentation companies operating globally in 2025, with products ranging from mycoprotein and microbial biomass to precision-fermented dairy and egg proteins. In June 2026, The EVERY Company and Huvepharma announced a fourfold expansion in production capacity for OvoPro precision-fermented egg protein after annual orders secured in the first four months of 2026 exceeded the company's total 2025 order volume several times over. The development is important because capacity utilization and unit economics, rather than scientific feasibility alone, now determine which fermentation proteins can scale into recurring food manufacturing demand.
Market Drivers
Consumers continue to diversify protein intake across animal and non-animal sources
Alternative protein demand is increasingly linked to protein diversification rather than a complete replacement of animal products. Consumers use plant-based milk, high-protein beverages, meat alternatives, tofu, protein powders and hybrid products for different eating occasions. This broadens the addressable market beyond strict vegan populations. GFI's 2026 industry review found that the number of U.S. households purchasing plant-based foods and the percentage purchasing more than once remained broadly stable in 2025 even as total U.S. plant-based retail value declined modestly. Globally, plant-based retail sales still increased, showing that regional performance differs and that the category retains a large recurring consumer base.
Food manufacturers are investing in proteins that improve supply diversification and product functionality
Food and ingredient companies are expanding alternative protein portfolios because soy, pea, wheat, fungi and fermentation-derived proteins offer different nutritional, functional and sourcing characteristics. Large suppliers can combine proteins with flavors, texturizers, fats and processing expertise, allowing customers to design products around a target cost and sensory profile. ADM's 2026 launch of eight new regionally sourced soy and pea protein products illustrates this shift toward broader protein choice. Roquette is similarly expanding pea-protein formats, while ingredient companies such as Ingredion, Kerry, IFF and Glanbia integrate proteins into larger formulation systems. This supports growth in sports nutrition, meal replacement, bakery, beverages and hybrid foods even when standalone plant-based meat demand is uneven.
Market Restraint
Price premiums and inconsistent sensory performance continue to limit repeat purchasing
Alternative protein adoption remains constrained where products are materially more expensive than conventional meat or dairy and where taste or texture does not meet consumer expectations. GFI's 2026 plant-based industry report identifies price and taste gaps as persistent barriers in the United States, while several plant-based categories continued to sell at significant premiums to conventional products. The challenge is more severe for cultivated and precision-fermented products because smaller manufacturing runs, specialized equipment, media inputs and downstream processing raise production costs. Funding pressure has also increased scrutiny on commercialization timelines. Fermentation-focused companies raised USD 357 million in 2025, down from USD 632 million in 2024 according to GFI, encouraging companies to prioritize products that can reach competitive economics and reliable utilization rather than building capacity ahead of demand.
Segment Analysis
By Type - Plant-Based Proteins
Plant-based proteins are projected to generate approximately USD 42.5 billion in market revenue by 2031. The segment remains the largest because soy, pea, wheat and other plant proteins already serve meat alternatives, dairy alternatives, beverages, sports nutrition, snacks and conventional food fortification. Retail availability is also far broader than for cultivated or precision-fermented products. However, its share of total alternative protein revenue is expected to decline gradually as fermentation-derived products scale. Fermentation-derived proteins represent the fastest-growing commercially meaningful technology segment, supported by mycoprotein, microbial biomass, dairy proteins and egg proteins produced through fermentation. Cultivated meat and seafood are expected to record very high percentage growth from a minimal base, but regulatory availability and manufacturing scale keep their absolute contribution relatively small through 2031.
By Distribution Channel - Offline
Offline channels are estimated to account for approximately USD 27.5 billion of alternative protein revenue in 2026. Supermarkets, hypermarkets, specialty grocers and foodservice remain central because consumers frequently discover and compare alternative products alongside conventional meat, dairy and nutrition products. Refrigerated and frozen categories also favor established physical retail distribution. Online sales are expanding faster as direct-to-consumer brands, grocery platforms and subscription channels make niche products easier to access. Beyond Meat's retail rollout of Beyond Steak Filet in June 2026 followed an earlier direct-to-consumer launch, illustrating how online channels can be used to validate demand before wider physical distribution.
By Application - Dairy Alternatives
Dairy alternatives are projected to reach approximately USD 35.4 billion in market value by 2031 and remain the largest application. Plant-based milk has established repeat usage across coffee, cereal, cooking and direct consumption, while creamers, yogurt and protein beverages extend category breadth. Global plant-based dairy retail sales were estimated at USD 22.7 billion in 2025, substantially larger than plant-based meat and seafood. Meat alternatives are expected to grow faster over the forecast period as whole-cut formats, improved texturization, fermentation-derived proteins and hybrid cultivated products expand the range of products available. The application mix is therefore expected to become more balanced even though dairy alternatives remain the larger revenue pool.
By Geography - Asia Pacific
Asia Pacific is projected to reach approximately USD 21.3 billion in alternative protein revenue by 2031. The region combines a large existing market for soy foods and plant-based beverages with rising investment in fermentation, cultivated meat and modern plant-based products. GFI estimates that Asia Pacific accounted for more than one-third of global plant-based dairy sales in 2025. Singapore, Australia and several other markets have also become important regulatory or commercialization centers for cultivated products, while China, India, Japan and South Korea provide large food-manufacturing and protein-consumption bases. Europe and North America remain especially important for plant-based meat and seafood, together accounting for more than 80% of global retail sales in that category in 2025.
Competitive Environment
The market combines global ingredient suppliers, branded consumer-food companies and technology-focused startups. ADM, Cargill, Ingredion, Kerry, Roquette, IFF and Glanbia compete through plant protein ingredients, formulation systems and food-manufacturing relationships. Consumer-facing companies such as Beyond Meat, Impossible Foods, Oatly and Danone compete through branded products and retail distribution, while Marlow Foods has a long-established position in fermentation-derived mycoprotein through Quorn. Precision-fermentation specialists including The EVERY Company and Perfect Day, along with cultivated-meat developers such as UPSIDE Foods, GOOD Meat and Wildtype, broaden the technology base.
Competition is increasingly determined by economics and application performance rather than by the novelty of the production technology. Large ingredient companies have advantages in procurement, protein fractionation, flavor systems, application laboratories and customer distribution, while specialist companies can differentiate through proprietary strains, cell lines, bioprocesses or product formats. Partnerships between technology developers and established manufacturers are becoming more important because fermentation and cultivated-protein companies need existing production expertise, regulatory support and route-to-market capabilities to reduce the cost and time required for commercial scale-up.
Recent Developments
June 2026: Beyond Meat launched Beyond Steak Filet into Wegmans and H-E-B retail stores after an earlier direct-to-consumer introduction, expanding its whole-cut plant-protein offering.
June 2026: The EVERY Company and Huvepharma announced a fourfold expansion of production capacity for OvoPro precision-fermented egg protein.
May 2026: ADM introduced eight new soy and pea protein products across North America and Europe to expand its plant-protein ingredient portfolio.
February 2026: Roquette launched NUTRALYS Pea 850F, a pea protein isolate designed to improve neutral taste and sensory performance in plant-based formulations.
2025: U.S. regulatory clearances expanded for cultivated products including Wildtype cultivated salmon, Mission Barns cultivated pork fat and Believer Meats cultivated chicken, broadening the commercial pathway for cell-cultivated proteins.
Alternative Protein Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 33.5 billion |
| Total Market Size in 2031 | USD 55.9 billion |
| Forecast Unit | Billion |
| Growth Rate | 10.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Distribution Channel, Application, Geography |
| Companies |
|
Market Segmentation
By Type
Plant-Based Proteins
Cultivated
Fermentation Derived
Others
By Distribution Channel
Online
Offline
Supermarket/Hypermarket
Specialty Stores
Others
By Application
Meat Alternative
Dairy Alternative
Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Taiwan
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Consumers Continue to Diversify Protein Intake Across Animal and Non-Animal Sources
3.1.2. Food Manufacturers Invest in Proteins That Improve Supply Diversification and Product Functionality
3.2. Market Restraint
3.2.1. Price Premiums and Inconsistent Sensory Performance Continue to Limit Repeat Purchasing
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Protein Fractionation and Texturization
4.2. Biomass Fermentation
4.3. Precision Fermentation
4.4. Cultivated Protein and Cell-Culture Systems
5. ALTERNATIVE PROTEIN MARKET BY TYPE
5.1. Introduction
5.2. Plant-Based Proteins
5.3. Cultivated
5.4. Fermentation Derived
5.5. Others
6. ALTERNATIVE PROTEIN MARKET BY DISTRIBUTION CHANNEL
6.1. Introduction
6.2. Online
6.3. Offline
6.3.1. Supermarket/Hypermarket
6.3.2. Specialty Stores
6.3.3. Others
7. ALTERNATIVE PROTEIN MARKET BY APPLICATION
7.1. Introduction
7.2. Meat Alternative
7.3. Dairy Alternative
7.4. Others
8. ALTERNATIVE PROTEIN MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. United Kingdom
8.4.2. Germany
8.4.3. France
8.4.4. Italy
8.4.5. Spain
8.4.6. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Taiwan
8.6.6. Thailand
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Archer-Daniels-Midland Company (ADM)
10.2. Cargill Incorporated
10.3. Ingredion Incorporated
10.4. Kerry Group plc
10.5. Roquette Freres
10.6. International Flavors & Fragrances Inc. (IFF)
10.7. Glanbia plc
10.8. dsm-firmenich
10.9. Novonesis A/S
10.10. Beyond Meat, Inc.
10.11. Impossible Foods Inc.
10.12. Oatly Group AB
10.13. Danone S.A.
10.14. Marlow Foods Limited (Quorn)
10.15. The EVERY Company
10.16. Perfect Day, Inc.
10.17. MycoTechnology, Inc.
10.18. UPSIDE Foods, Inc.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











